
 France Metaverse Market | 2026-2036
France Metaverse Market Size, Share, and Industry Trends Forecast 2026-2036
France Metaverse Market Insights
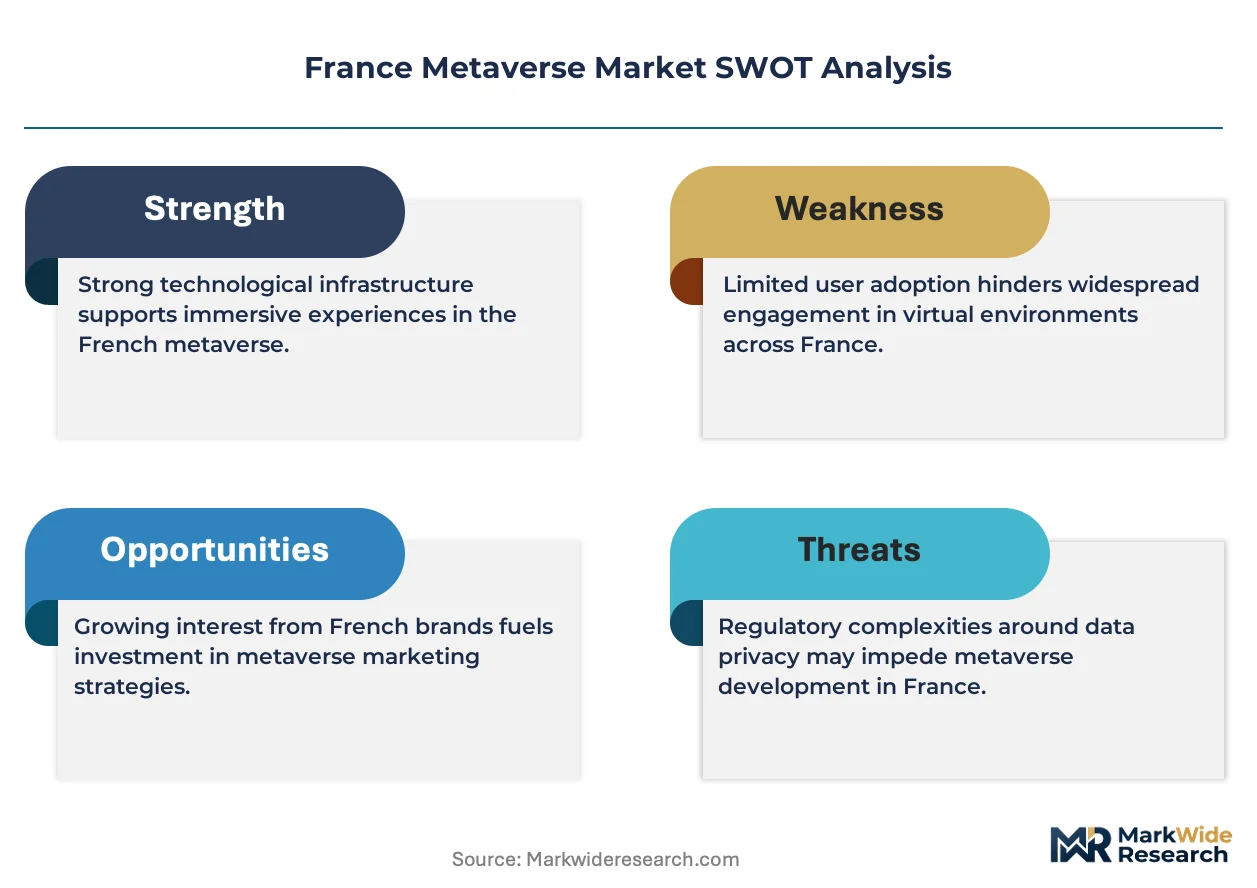
Enterprise buyers are rotating toward immersive training and digital-twin deployments as consumer gaming spend moderates. Meta anchors its European metaverse engineering hub in Paris, leveraging local AI talent for Horizon Workrooms development. NVIDIA sustains R&D intensity through its French research collaborations in neural rendering and real-time simulation. The Sandbox competes on brand-controlled virtual real estate, specializing in cultural partnerships with French museums and fashion houses.
The France Metaverse comprises persistent, shared virtual environments rendered through real-time 3D engines, spatial computing interfaces, and distributed ledger authentication protocols, with latency thresholds below 20 milliseconds for synchronous multi-user presence. Its primary commercial purpose spans remote collaboration, experiential marketing, and synthetic environment training. Gaming applications dominate current revenue pools, though enterprise virtual reality experiences capture expanding margin as French manufacturers adopt digital-twin workflows. Blockchain technology underpins ownership verification for virtual assets, while cloud computing infrastructure determines scalability for multi-tenant deployments.
CNIL enforces GDPR-mandated biometric data protections for VR headset deployments, constraining facial-geometry capture and gaze-tracking monetization. The EU AI Act classifies certain metaverse content-moderation algorithms as high-risk, imposing conformity assessments on French platform operators. ANSM monitors extended-reality medical applications, shaping clinical-validation requirements for therapeutic metaverse programs. Stakeholders must weigh sovereign-cloud mandates against latency penalties when architecting cross-border virtual infrastructure.
Market Dynamics
Enterprise digital-twin deployments are compressing hardware refresh cycles while CNIL biometric enforcement constrains headset data monetization, creating a split market between sovereign-cloud enterprise stacks and latency-optimized consumer platforms.
Growth Catalysts
- EU AI Act compliance mandates:High-risk algorithm classifications are forcing French platform operators into conformity assessments, creating captive demand for certified infrastructure providers.
- Aerospace manufacturing training:Digital-twin workflows for assembly simulation are pulling extended-reality hardware into Toulouse and Bordeaux production facilities.
- Neural rendering advances:Real-time light-field synthesis is collapsing photogrammetry timelines for Paris-Saclay immersive content studios.
Market Restraints
- GDPR biometric friction:CNIL facial-geometry capture restrictions are blocking gaze-tracking revenue models that fund consumer headset subsidies elsewhere.
- Cloud concentration risk:Three hyperscalers dominate French sovereign-cloud certification, limiting infrastructure negotiation leverage for mid-scale metaverse operators.
- Display supply bottleneck:Micro-OLED fab capacity in East Asia is constraining high-resolution headset rollout timelines for French enterprise buyers.
Strategic Opportunities
- ANSM therapeutic pathways:Extended-reality clinical validation frameworks are opening reimbursement routes for anxiety and pain-management metaverse applications.
- Occitanie underpenetration:Montpellier and Perpignan enterprise density lags Île-de-France by a factor of five, offering first-mover positioning for regional immersive training providers.
- 5G edge convergence:Low-latency slicing partnerships with Orange and Bouygues Telecom are enabling synchronous multi-user presence without hyperscaler dependency.
Industry Challenges
- Spatial-computing talent scarcity:Unity and Unreal Engine specialists command premiums that exhaust Series B metaverse startup runway before product-market fit.
- Legacy ERP integration:SAP and Dassault Systèmes digital-twin pipelines require custom middleware development that extends enterprise sales cycles by 8-14 months.
- Cross-border latency arbitration:Sovereign-cloud mandates for patient data in therapeutic applications conflict with sub-20ms synchronization requirements for multi-user clinical environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Metaverse Market |
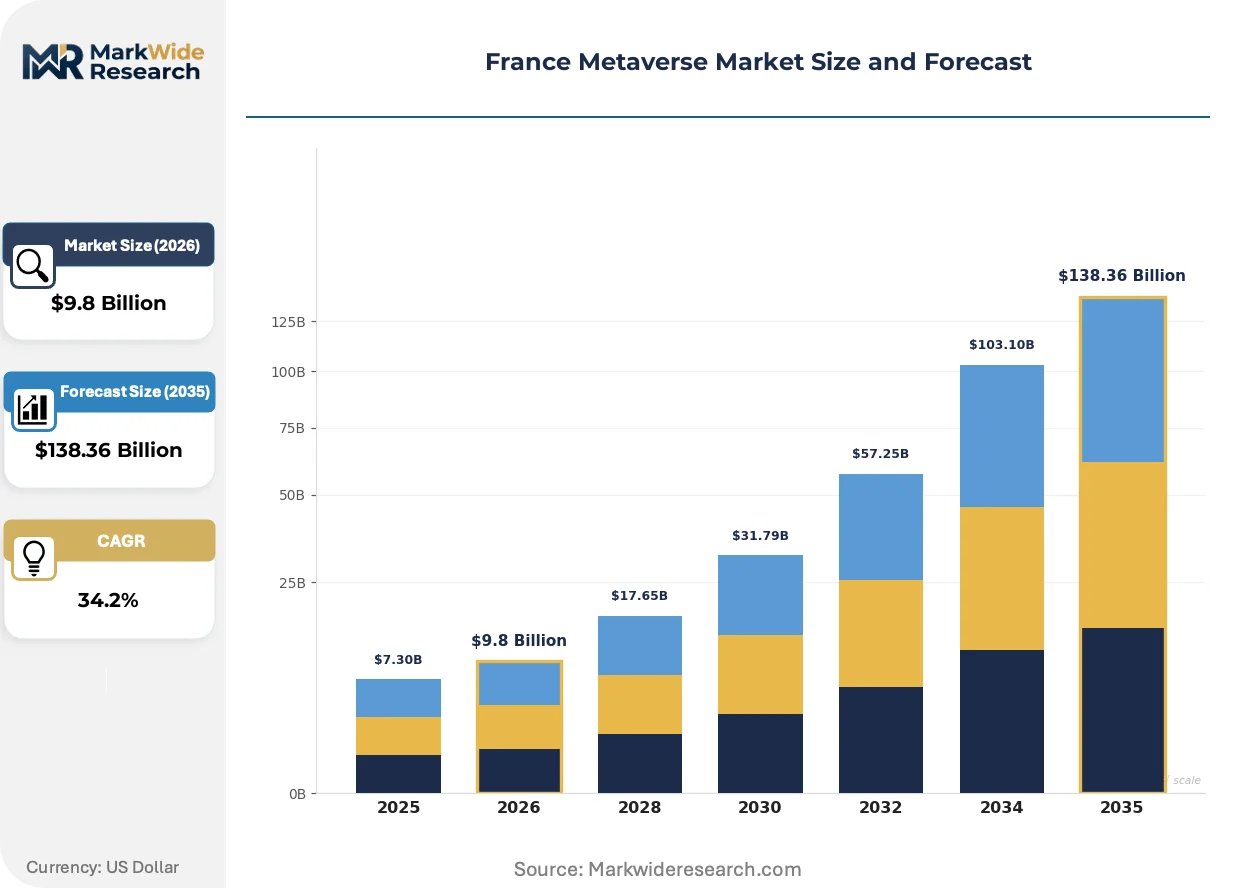
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $138.36 Billion |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Gaming, Social Networking, Virtual Reality Experiences, E-commerce End User: Consumers, Enterprises, Educational Institutes, Artists Technology: Blockchain, Augmented Reality, 3D Modeling, Cloud Computing Device Type: VR Headsets, Smartphones, PCs, Consoles |
| Companies Covered | Roblox Corporation, ByteDance Ltd., Meta, Antier Solutions, NetEase, Inc., The Sandbox, Decentraland, Kinetix, NVIDIA Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Metaverse Market Trends and Innovations
Real-time 3D engines are fragmenting into specialized stacks for photorealistic simulation versus lightweight mobile rendering, while regulatory pressure on biometric data is accelerating privacy-preserving gaze-estimation research.
Neural radiance fields are bifurcating the content-production pipeline. French automotive designers at Renault and Stellantis are adopting instant NeRF capture for showroom configurators, bypassing traditional photogrammetry studios. The technology is compressing asset-creation costs for mid-fidelity experiences while pushing high-end productions toward proprietary light-field capture arrays.
The EU AI Act's high-risk system classification is reshaping content-moderation architecture. French social-VR platforms must now maintain algorithmic audit trails and human-in-the-loop override systems for avatar-behavior analysis. Gaming-oriented operators with lean moderation stacks are facing retrofit costs that favor enterprise-focused competitors with existing compliance infrastructure.
Enterprise procurement of immersive training is consolidating through systems integrators rather than direct hardware purchases. Capgemini and Accenture France are bundling headset fleets with change-management services, displacing standalone device vendors in manufacturing and healthcare verticals. This shift is most visible in Grand Est, where regional hospital groups prefer single-contract immersive therapy deployments over fragmented vendor management.
France Metaverse Market Segmentation
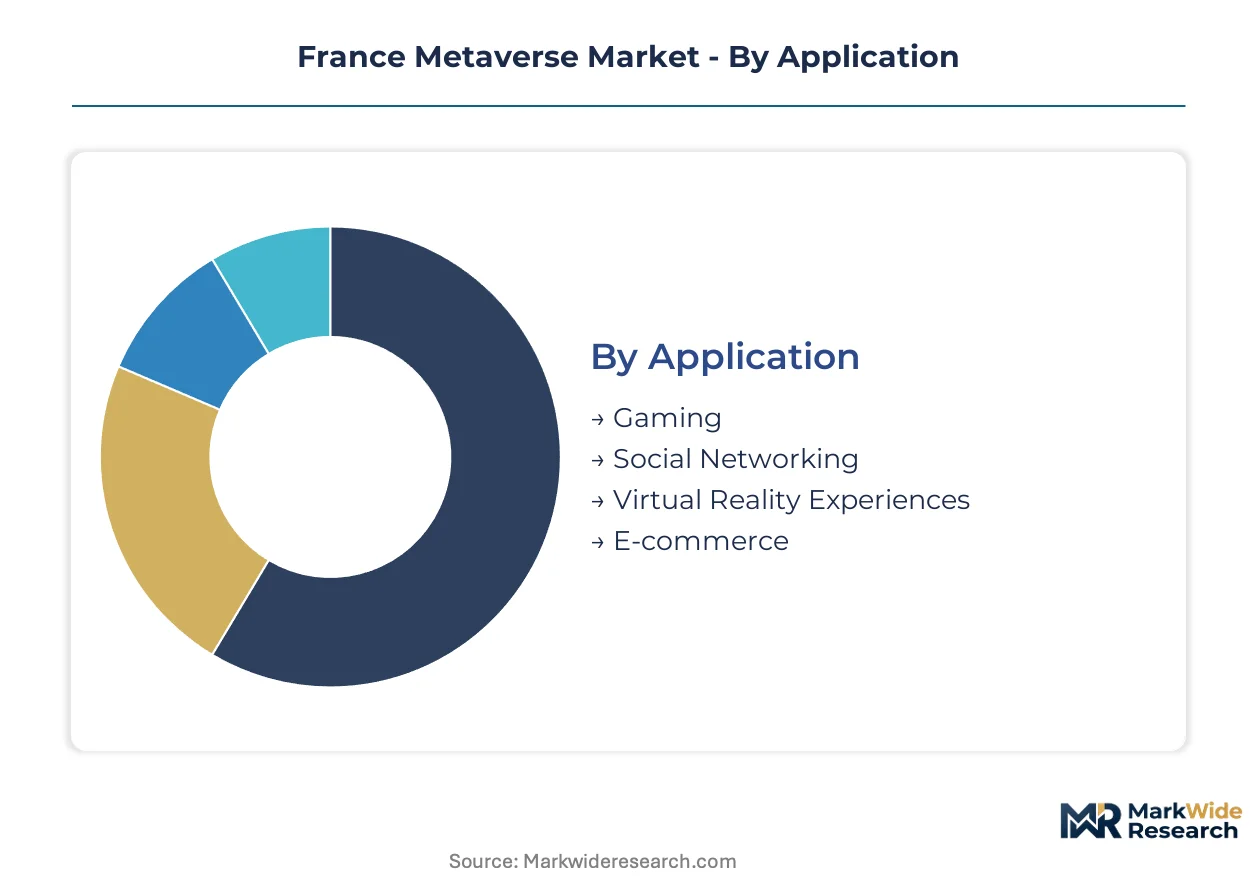
France's metaverse market fragments along four dimensions that reveal divergent growth physics. Application and end-user splits expose the enterprise-consumer tension driving hardware procurement cycles, while technology and device categories illuminate infrastructure dependencies that determine scalability for Paris-Saclay studios versus Toulouse aerospace deployments.
Application:
Gaming anchors domestic revenue concentration through Sophia Antipolis studios, while enterprise applications pull specialized infrastructure toward export-competitive manufacturing clusters.
- Gaming:Real-time 3D engines power persistent multiplayer worlds with sub-20ms latency requirements. Demand clusters in Paris and Lyon where independent studios serve both domestic players and export markets to French-speaking Africa and Belgium.
- Social Networking:Avatar-based persistent spaces rely on distributed ledger authentication for virtual asset ownership. French platforms face CNIL biometric constraints on facial-geometry capture that block gaze-tracking monetization models viable in less regulated jurisdictions.
- Virtual Reality Experiences:Location-based entertainment venues in Marseille and Bordeaux deploy room-scale tracking for tourism and cultural heritage applications.
- E-commerce:Virtual showroom configurators for automotive and luxury goods leverage neural rendering to compress photogrammetry timelines.
Gaming commands the established base. The steepest expansion runs through Virtual Reality Experiences.
End User:
Procurement patterns diverge sharply between volume-driven consumer segments and margin-rich enterprise deployments with sovereign-cloud compliance requirements.
- Enterprises:Digital-twin workflows for automotive and aerospace manufacturing require SAP and Dassault Systèmes integration that extends sales cycles. Capgemini and Accenture France bundle headset fleets with change-management services, consolidating procurement through systems integrators rather than direct hardware purchases.
- Consumers:Gaming and social VR adoption faces GDPR biometric friction that blocks subsidy-funded headset distribution models operating elsewhere.
- Educational Institutes:Grand Est hospital groups pilot ANSM-validated immersive therapy programs with single-contract deployment preferences.
- Artists:The Sandbox partnerships with French museums and fashion houses create brand-controlled virtual real estate revenue streams.
Enterprises capture expanding margin as manufacturing digital-twin adoption accelerates. Artists gain share fastest through cultural institution partnerships.
Technology:
Stack selection determines latency-versus-sovereignty tradeoffs that shape competitive positioning for French platform operators under EU AI Act compliance mandates.
- Cloud Computing:Three hyperscalers dominate French sovereign-cloud certification, limiting infrastructure negotiation leverage for mid-scale operators. 5G edge slicing partnerships with Orange and Bouygues Telecom enable synchronous multi-user presence without hyperscaler dependency.
- Blockchain:Distributed ledger protocols underpin virtual asset ownership verification for museum and fashion house partnerships, though energy consumption scrutiny constrains public-chain deployments.
- Augmented Reality:Mobile-first spatial computing overlays face display supply bottlenecks as micro-OLED fab capacity concentrates in East Asia.
- 3D Modeling:Neural radiance fields compress asset-creation costs for Renault and Stellantis showroom configurators, bypassing traditional photogrammetry studios.
Cloud Computing anchors current infrastructure investment. 3D Modeling climbs fastest as neural rendering collapses production timelines.
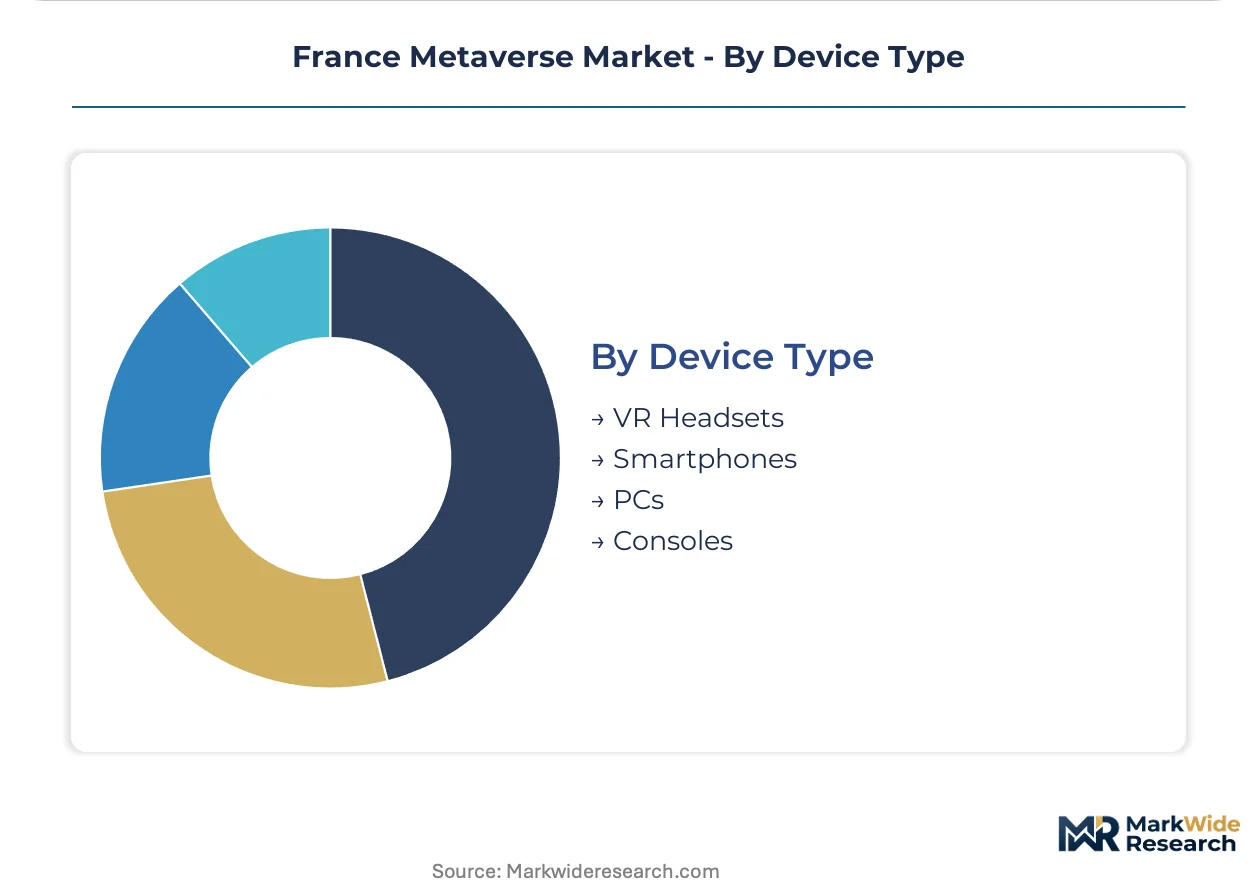
Device Type:
Hardware procurement splits between enterprise refresh cycles driven by digital-twin deployment and consumer adoption constrained by biometric regulation and supply concentration.
- VR Headsets:Micro-OLED fab capacity constraints in East Asia limit high-resolution rollout timelines for French enterprise buyers. CNIL facial-geometry capture restrictions block gaze-tracking revenue models that fund consumer subsidies elsewhere.
- Smartphones:AR-enabled mobile devices serve as the primary entry point for consumer metaverse access, with 5G edge slicing reducing latency for synchronous experiences.
- PCs:Workstation-class deployments anchor professional content creation pipelines for Paris-Saclay immersive studios.
- Consoles:Gaming-optimized hardware maintains installed-base concentration among domestic consumers despite enterprise rotation toward specialized VR headsets.
VR Headsets absorb the majority of enterprise capital expenditure. Smartphones maintain the broadest consumer reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Paris-Lyon-Marseille high-speed rail corridor and Orange's 5G backbone infrastructure underwrite France's metaverse distribution topology, compressing latency windows for synchronous multi-user deployments across the hexagon's industrial spine.
Île-de-France
Paris-Saclay's deep-tech ecosystem anchors neural rendering R&D for automotive configurators, while Meta's European engineering hub concentrates Horizon Workrooms development talent. CNIL biometric enforcement operates most stringently here, constraining facial-geometry capture for consumer platforms. La Défense hosts systems integrators bundling enterprise headset fleets with change-management services.
Provence-Alpes-Côte d'Azur
Sophia Antipolis gaming studios drive persistent multiplayer world development for export to French-speaking African markets. The EU AI Act's high-risk algorithm classifications impose conformity assessment costs on social-VR operators headquartered in Nice and Cannes. Marseille location-based entertainment venues deploy room-scale tracking for cultural heritage tourism applications.
Occitanie
Montpellier and Perpignan enterprise density lags the national average by a factor of five, creating first-mover positioning for immersive training providers targeting aerospace subcontractors. ANSM therapeutic validation frameworks are piloting extended-reality anxiety treatments at regional hospital groups. Toulouse aerospace manufacturers pull digital-twin workflows into assembly simulation deployments.
Nouvelle-Aquitaine
Bordeaux production facilities integrate extended-reality hardware for Stellantis manufacturing training programs. The region's wine and tourism sectors experiment with virtual showroom configurators leveraging neural radiance field compression. Micro-OLED supply bottlenecks from East Asian fabs delay high-resolution headset rollouts for enterprise buyers here.
Hauts-de-France
Lille's proximity to Belgian and Dutch markets positions cross-border virtual collaboration platforms serving EU-wide distributed teams. Regional hospital groups prefer single-contract immersive therapy deployments over fragmented vendor management. 5G edge slicing partnerships with Bouygues Telecom enable synchronous multi-user presence without hyperscaler dependency for manufacturing clusters.
France Metaverse Market Competitive Landscape
Concentration sits with hyperscale platform operators and specialized systems integrators rather than fragmented hardware vendors. The vendor base splits between cloud-native social platforms with compliance infrastructure and automotive-industry digital-twin specialists. Three archetypes dominate: sovereign-cloud enterprise stack providers, neural rendering content studios, and brand-controlled virtual real estate operators. Competitive moves center on M&A for spatial-computing talent and 5G edge partnerships to bypass latency penalties.
Among platform operators, Meta anchors the social-VR archetype with its Paris engineering hub, while NVIDIA Corporation exemplifies the R&D-intensive infrastructure tier through French research collaborations. The Sandbox occupies a position within brand-controlled virtual real estate, specializing in cultural partnerships that distinguish its offering from open-world competitors.
| Leading Market Players |
|---|
| Roblox Corporation |
| ByteDance Ltd. |
| Meta |
| Antier Solutions |
| NetEase, Inc. |
| The Sandbox |
| Decentraland |
| Kinetix |
| NVIDIA Corporation |
| Others |
Pricing and Supply Chain Analysis
CNIL biometric certification gates headset qualification and price differentiation simultaneously, forcing French platform operators into compliance-premium tiers while East Asian display fabs extract scarcity rents from unqualified supply channels.
Pricing Analysis
Volume-discount tiering structures dominate enterprise procurement through Capgemini and Accenture France bundling arrangements, with three-tier pricing separating sovereign-cloud certified stacks from latency-optimized consumer platforms. Price differentiation rests on GDPR compliance grade and integration depth with SAP or Dassault Systèmes pipelines. Cost compression in consumer VR hardware intensifies because CNIL facial-geometry restrictions block gaze-tracking subsidy models that fund headsets elsewhere. Educational institutes in Grand Est exhibit highest price sensitivity, while aerospace manufacturers in Toulouse prioritize compliance over unit cost.
Supply Chain Analysis
China and South Korea anchor micro-OLED wafer and display module production, with Taiwan feeding precision optics and sensor assemblies into French headset assembly. Component dependencies center on gallium-based micro-LED backplanes, rare-earth magnet arrays for haptic actuators, and photopolymer resin stocks for light-field optics. Single-source vulnerability concentrates in East Asian fab capacity for sub-10-micron pixel pitches. Distribution runs through Orange and Bouygues Telecom 5G edge nodes for synchronous multi-user deployments, bypassing hyperscaler concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward systems integrators as Capgemini and Accenture France consolidate enterprise immersive training procurement, fragmenting direct hardware vendor relationships.
For Market Incumbents: Secure spatial-computing talent pipelines through Paris-Saclay research partnerships before Unity and Unreal Engine specialist premiums exhaust competitor runway. Defend against neural rendering commoditization by deepening proprietary light-field capture array investments. Prioritize sovereign-cloud certification maintenance as EU AI Act high-risk algorithm classifications raise compliance barriers for lean-moderation competitors. For New Entrants and Emerging Players: ANSM fast-track therapeutic validation pathways offer lowest competitive density for anxiety and pain-management metaverse applications in Occitanie hospital groups. White-space positioning concentrates in Montpellier and Perpignan enterprise immersive training, where aerospace subcontractor density lags national averages. Go-to-market execution should anchor on single-contract deployment preferences visible in Grand Est regional health procurement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across neural rendering content studios as real-time light-field synthesis R&D demands specialized compute infrastructure. Long-term viability favors acquisition targets with established CNIL compliance architecture and existing Capgemini or Accenture France channel relationships. Watch 5G edge slicing partnership announcements with Orange or Bouygues Telecom as inflection indicators for synchronous multi-user capability scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign-Cloud Certification Investment | EU AI Act high-risk system classifications create captive demand for compliant infrastructure providers in France. |
| Neural Rendering R&D Partnership | Paris-Saclay collaborations accelerate photorealistic asset pipelines for Renault and Stellantis showroom configurators. |
| 5G Edge Slicing Alliance | Orange and Bouygues Telecom partnerships enable sub-20ms synchronous presence without hyperscaler dependency. |
| ANSM Therapeutic Validation Pathway | Extended-reality clinical frameworks open reimbursement routes for regional hospital anxiety treatment programs. |
| Spatial-Computing Talent Acquisition | Unity and Unreal Engine specialist scarcity commands premiums that determine Series B runway exhaustion timing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of CNIL enforcement actions, EU AI Act implementation guidance, and hyperscaler sovereign-cloud certification disclosures. Primary interviews engaged CTOs at Paris-Saclay immersive studios, procurement leads at Toulouse aerospace manufacturers, regulatory affairs directors at social-VR platforms, and biomedical engineers piloting ANSM-validated therapeutic programs. Secondary sources encompassed ANSM clinical validation frameworks, Orange 5G infrastructure deployment data, and customs records for VR headset component imports. Bottom-up triangulation across application segments and end-user verticals validated top-down macroeconomic scenario weightings.
Segmentation dimensions modeled span application type, end-user archetype, technology stack, and device category, with regional adoption patterns and compliance tier cross-cutting all segments. CAGRs derive from regression analysis against hardware refresh cycle compression, digital-twin deployment velocity, and biometric regulation enforcement intensity. Neural rendering adoption curves and 5G edge node rollout timelines feed industry-specific forecast inputs throughout the projection horizon.
Underlying assumptions cover sustained CNIL biometric enforcement stringency, continued micro-OLED supply concentration in East Asia, and stable EU AI Act high-risk classification scope, with deviation risk concentrated in sovereign-cloud mandate timing and therapeutic reimbursement policy shifts. Recalibration cycles align with material shifts in ANSM validation framework expansions or Orange 5G infrastructure deployment accelerations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Middle East and Africa Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Collaboration Platform Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) in Healthcare Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Automotive Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Head Show Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) and Augmented Reality (AR) Microdisplay Market
Virtual Reality (VR) and Augmented Reality (AR)
VR All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
US Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Mirror Market
Virtual Reality (VR) and Augmented Reality (AR)
India Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
Mobile Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Collaboration Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
China Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Software Market