
 Virtual Reality Box Glasses Market | 2026-2036
Virtual Reality Box Glasses Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Reality Box Glasses Market Insights
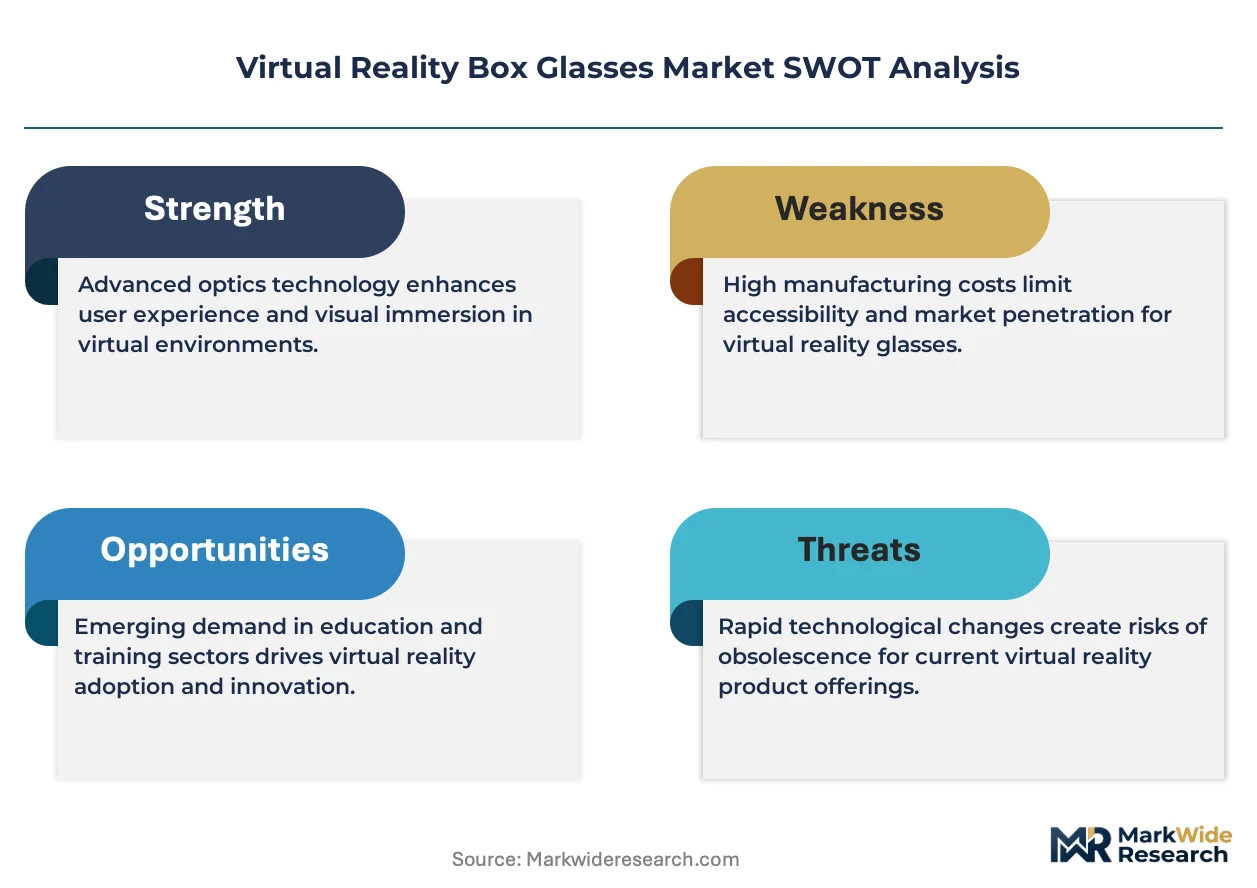
The EU Green Deal is hardening material compliance requirements for consumer electronics, forcing VR hardware makers to redesign housing plastics and display assemblies. Meta Platforms, Inc. leverages its captive content ecosystem to sustain hardware attach rates across Quest devices. Sony Group Corporation anchors its position through optical component specialization drawn from camera sensor expertise. HTC Corporation competes in enterprise training verticals where device durability commands premium positioning.
Virtual reality box glasses are head-mounted display enclosures that integrate Fresnel or pancake lenses with stereoscopic panel arrays to create immersive visual fields for users. These devices typically employ LCD or OLED substrates with refresh rates exceeding 90 Hz to minimize motion sickness during extended sessions. Standalone headsets now lead unit shipments as system-on-chip efficiency eliminates tethered PC dependency, while smartphone-compatible variants retain share in price-sensitive Asian markets. Haptic Feedback technology captures expanding margin pools as force-feedback gloves and bodysuits integrate with base headsets for industrial training simulations.
FCC certification mandates govern wireless transmission protocols for VR devices sold in the United States, while REACH compliance in Europe restricts hazardous substances in lens coatings and circuit assemblies. China's SAMR enforces GB standards for battery safety in standalone units, creating divergent testing burdens for multi-region launches. ISO 9241 ergonomic guidelines increasingly influence headset weight distribution and interpupillary adjustment ranges. Stakeholders must monitor how fragmented regulatory timelines for eye-tracking biometric data reshape hardware feature roadmaps and regional go-to-market sequencing.
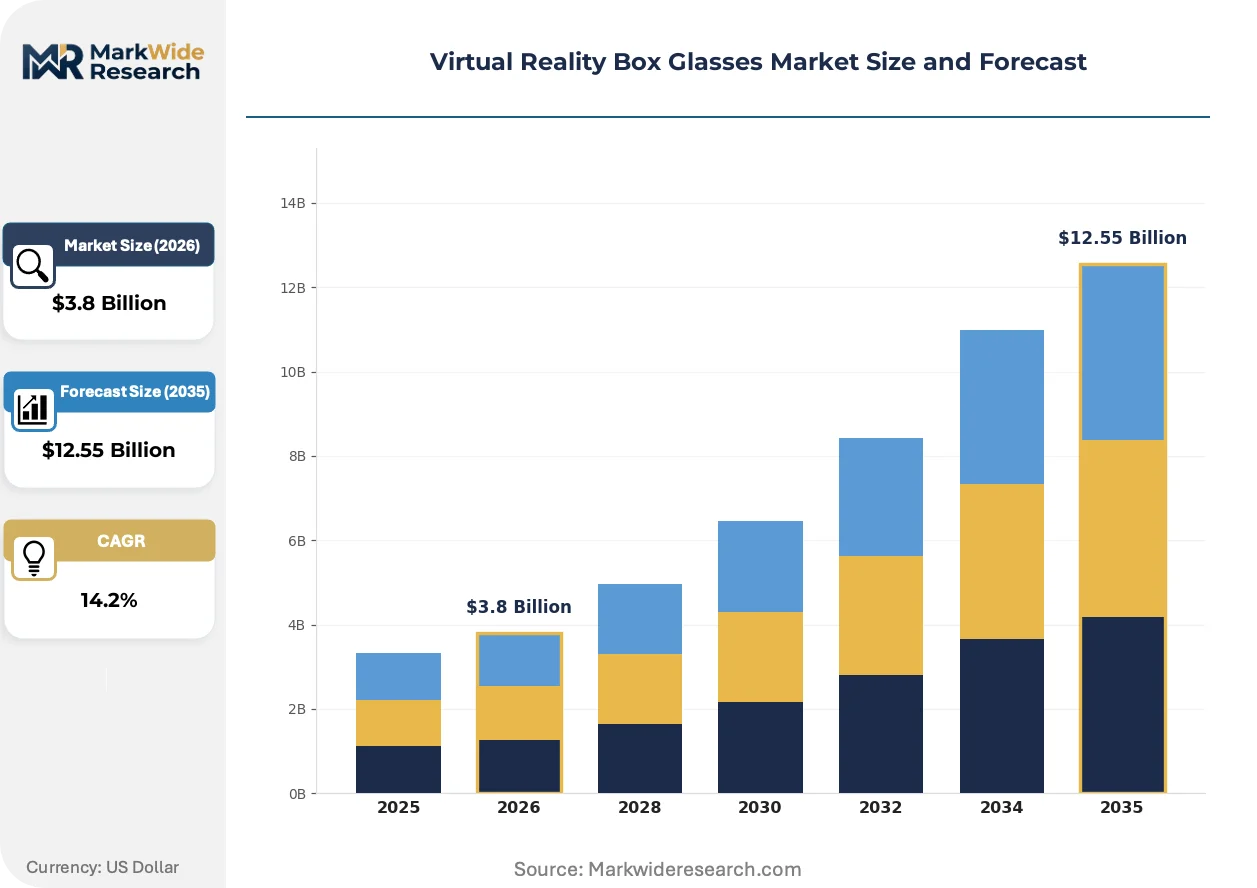
Market Dynamics
Standalone headset architectures are eliminating tethered PC dependency, compressing the addressable market for smartphone-compatible enclosures while redistributing margin pools toward system-on-chip suppliers and thermal management specialists.
Growth Catalysts
- Surgical Training Adoption:Healthcare providers across the United States are deploying VR box glasses for resident education and preoperative planning, creating institutional procurement pipelines that bypass consumer retail volatility.
- EU Green Deal Compliance:Extended producer responsibility mandates are accelerating housing redesigns using recycled polycarbonate and bio-based lens substrates, opening premium positioning for certified sustainable SKUs.
- Pancake Lens Migration:Optical stack thinning enabled by pancake lens architectures is reducing headset weight below 300 grams, extending session duration tolerance for enterprise training deployments.
Market Restraints
- OLED Panel Concentration:Samsung Display and BOE Technology control over 80 percent of micro-OLED wafer supply, creating allocation risk for premium headset launches during semiconductor cycle upturns.
- REACH Substance Restrictions:ECHA classification of certain flame retardants as substances of very high concern is forcing housing material reformulations with 18-24 month requalification timelines.
- Smartphone Tethering Decline:Low-cost cardboard-style enclosures face demand erosion as entry-level standalone units from Shenzhen assemblers hit sub-$150 price points.
Strategic Opportunities
- Industrial Haptic Integration:Force-feedback glove convergence with base headsets is expanding addressable spend per seat in manufacturing training verticals beyond hardware-only economics.
- India PLI Scheme:Production-linked incentive structures for electronics manufacturing are attracting component assembly investments that could serve Middle East and African distribution channels.
- ISO 9241 Ergonomic Certification:Third-party validation of interpupillary adjustment ranges and weight distribution is becoming a procurement filter for enterprise buyers, creating differentiation headroom for compliant vendors.
Industry Challenges
- Optical Engineer Scarcity:Pancake lens design and waveguide simulation expertise concentrates in Taiwan and South Korea, constraining in-house R&D scaling for Western OEMs.
- Multi-Region Certification Burden:Simultaneous FCC Part 15, CE RED, and China SRRC radio approvals add 8-14 months to product launch timelines for wireless standalone units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Reality Box Glasses Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Smartphone-Compatible, PC-Compatible, Console-Compatible End User: Gaming, Education, Healthcare, Training Technology: Optical Tracking, Motion Sensing, Haptic Feedback, 3D Audio Distribution Channel: Online Retail, Electronics Stores, Specialty Stores, Wholesale |
| Companies Covered | Meta Platforms, Inc., Sony Group Corporation, Microsoft Corporation, Samsung Group, HTC Corporation, Seiko Epson Corporation, Google LLC, Apple Inc., Lenovo Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Reality Box Glasses Market Trends and Innovations
Pancake optics and AI-driven foveated rendering are compressing hardware refresh cycles while regulatory fragmentation around biometric data collection is reshaping feature roadmaps across all price tiers.
Pancake lens stacks using polarization-based optical folding are expanding into enterprise training headsets where weight reduction directly correlates with session completion rates. Boeing and Siemens training divisions have standardized on sub-250-gram configurations for maintenance simulation programs. This optical architecture is expanding into mid-tier consumer SKUs previously served by bulkier Fresnel alternatives, compressing the premium-mid price gap.
REACH Annex XIV authorization requirements for certain phthalate plasticizers are forcing housing manufacturers toward bio-based TPU alternatives with equivalent impact resistance. German automotive suppliers with materials science divisions are licensing polymer formulations originally developed for interior trim applications. Medical-grade headset assemblers face the steepest compliance burden, as patient-contact surfaces trigger additional biocompatibility testing under MDR Class I rules.
Enterprise procurement committees are consolidating vendor relationships around full-stack training platform providers rather than hardware-only transactions. Siemens Energy and Deutsche Bahn have shifted from unit purchases to multi-year fleet management contracts bundling headsets, content licensing, and biometric analytics. This behavioral shift is most visible in German-speaking markets where works council consultation requirements favor single-source accountability over best-of-breed assembly.
Virtual Reality Box Glasses Market Segmentation
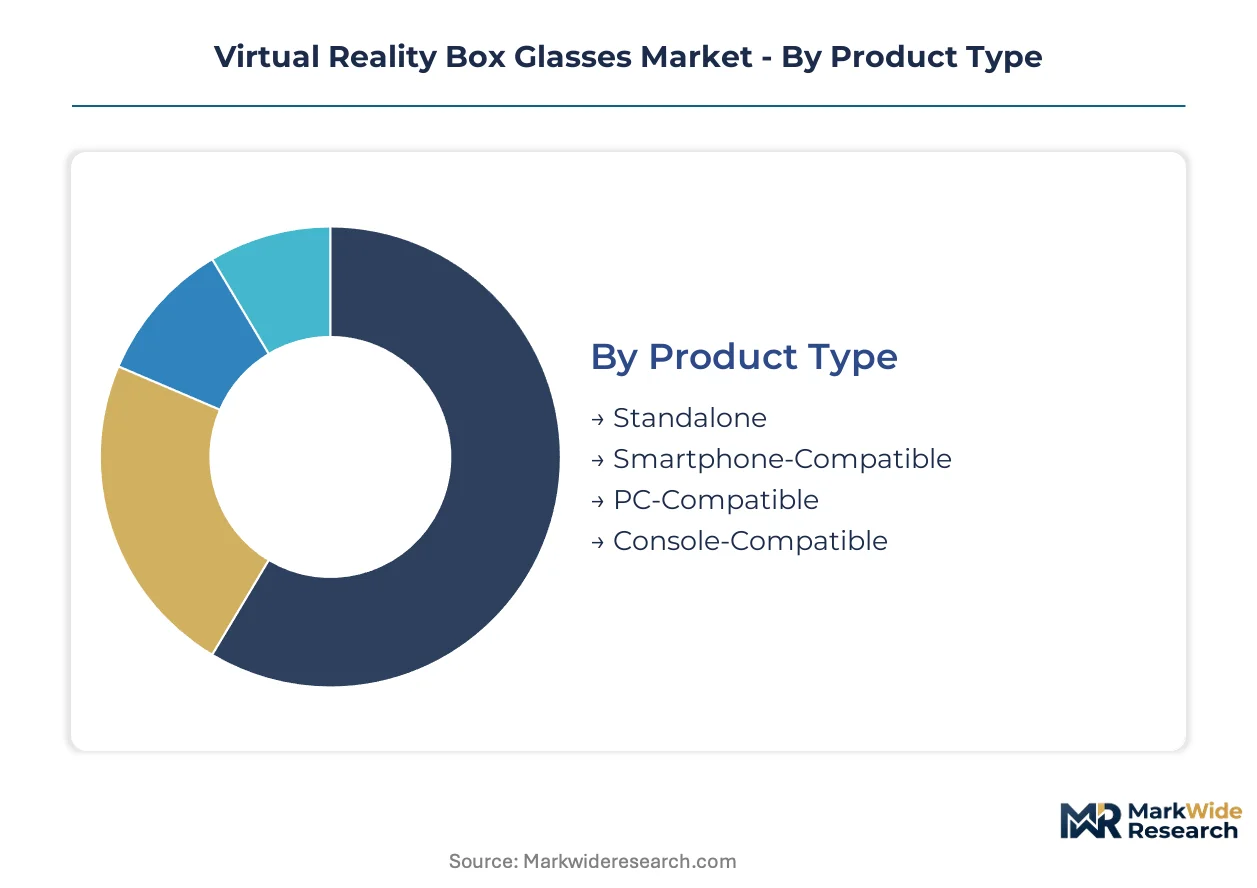
VR box glasses segmentation reveals how hardware architecture, use case intensity, and procurement channel shape margin structures differently. Product type determines silicon and thermal cost bases, while end user concentration governs software attach rates and replacement cycles.
Product Type:
System architecture dictates power budget, lens complexity, and supply chain dependencies across form factors.
- Standalone:Integrated SoC designs with onboard battery and compute eliminate tethering constraints. Demand concentrates in enterprise training deployments across the United States and Germany, where untethered mobility justifies unit premiums for maintenance simulation programs.
- Smartphone-Compatible:Enclosures leveraging handset displays and processors through USB-C or wireless mirroring. Cardboard-derived variants retain volume in Indian and Indonesian education tenders where per-seat cost caps dominate procurement criteria.
- PC-Compatible:Tethered headsets relying on external GPU rendering for high-fidelity applications. Niche persistence in flight simulation and architectural visualization studios where pixel density requirements exceed mobile SoC capability.
- Console-Compatible:Licensed accessories for PlayStation and Xbox ecosystems. Sony's captive content pipeline anchors attach rates for first-party titles.
Standalone leads on scale; smartphone-compatible leads on momentum in price-sensitive institutional tenders.
End User:
Application intensity varies from episodic entertainment to continuous clinical use, reshaping durability specifications and service contract structures.
- Gaming:Consumer entertainment drives refresh rate optimization and low-latency controller integration. Meta's Quest Store and SteamVR platform economics concentrate software revenue in North American and Western European households.
- Healthcare:Surgical training and patient therapy applications demand ISO 13485 quality systems and biocompatible surface materials. Cleveland Clinic and Johns Hopkins residency programs have standardized on medical-grade enclosures with single-patient-use face interfaces.
- Education:K-12 and higher education deployments prioritize content library breadth over hardware specification. Shenzhen OEMs supply bulk orders to Chinese provincial education bureaus under centralized procurement frameworks.
- Training:Corporate and military simulation requires MIL-STD-810G durability certification and integration with force-feedback peripherals. Boeing and Lockheed Martin maintenance programs specify sub-250-gram pancake lens configurations for extended session tolerance.
Training commands the steepest unit economics; healthcare shows the steepest expansion trajectory as FDA 510(k) pathways clarify for therapeutic indications.
Technology:
Sensor fusion depth determines immersion quality and corresponding bill-of-materials escalation.
- Optical Tracking:Inside-out camera arrays for spatial mapping and controller localization. Base functionality for all standalone architectures, with camera module costs declining through smartphone supply chain spillover.
- Motion Sensing:IMU arrays for head orientation and gesture recognition. Six-axis fusion algorithms from Bosch Sensortec and TDK InvenSense dominate component sourcing.
- Haptic Feedback:Force-feedback gloves and bodysuits extending immersion beyond visual channels. Industrial training verticals in Germany and Japan show fastest adoption where tactile fidelity reduces skill transfer time.
- 3D Audio:Spatial audio rendering through head-related transfer function modeling. Sony's audio engineering heritage informs PlayStation VR2 differentiation.
Optical tracking leads on scale; haptic feedback climbs the fastest as manufacturing training budgets expand per-seat spend beyond hardware-only economics.
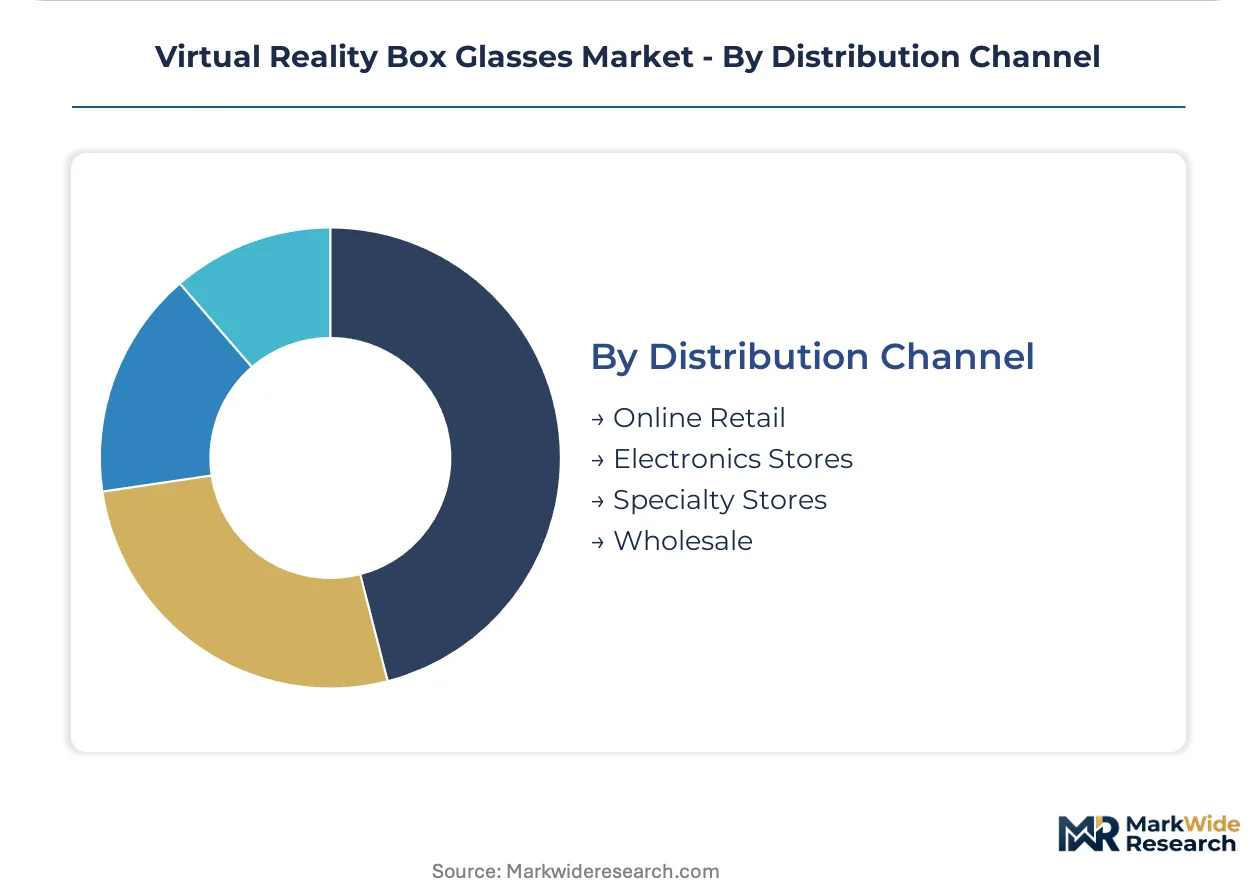
Distribution Channel:
Channel selection reflects buyer sophistication, support requirements, and volume scale.
- Online Retail:Direct-to-consumer and marketplace sales dominating consumer and prosumer segments. Amazon and manufacturer storefronts capture hardware margins while platform stores monetize software attach.
- Electronics Stores:Best Buy and MediaMarkt providing hands-on demonstration and immediate fulfillment. Critical for first-time VR adopters requiring fit verification.
- Specialty Stores:Enterprise AV integrators and medical device distributors offering configuration and training services. Necessary for healthcare and corporate training deployments with compliance documentation requirements.
- Wholesale:B2B volume procurement for education and government tenders. Chinese provincial bulk purchasing and Indian central government schemes flow through distributor networks.
Online retail leads on scale; specialty stores gain share fastest as enterprise procurement consolidates around full-stack platform providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The virtual reality box glasses industry traces its commercial roots to 1990s Japanese consumer electronics laboratories, where early head-mounted display prototypes established the optical engineering foundations that later migrated to Silicon Valley and Shenzhen manufacturing corridors.
United States
Healthcare residency programs at Cleveland Clinic and Johns Hopkins drive institutional procurement of medical-grade headsets for surgical simulation. FDA 510(k) clearance pathways for therapeutic VR devices are clarifying regulatory requirements for patient-contact hardware. Boston and Seattle host specialized optical engineering consultancies serving defense and enterprise training contractors.
China
Shenzhen and Guangzhou manufacturing clusters supply Fresnel lens assemblies and pancake optical stacks to global headset assemblers under concentrated OEM arrangements. SAMR enforcement of GB standards for lithium-polymer battery safety creates testing bottlenecks for standalone unit launches. Dongguan mold-makers are retooling for recycled polycarbonate housing production to meet EU import specifications.
Germany
Siemens Energy and Deutsche Bahn maintenance divisions specify sub-250-gram pancake lens configurations for extended industrial training sessions. ECHA REACH Annex XIV restrictions on phthalate plasticizers are forcing 18-24 month housing material requalification cycles. Bavarian automotive suppliers with polymer science divisions license bio-based TPU formulations originally developed for interior trim applications.
Japan
Sony Group Corporation leverages camera sensor optical expertise to anchor premium headset positioning through specialized display component supply. METI funding for immersive technology R&D supports enterprise training pilot programs in manufacturing and logistics. Tokyo and Osaka maintain concentrated talent pools for waveguide simulation and polarization optics engineering.
South Korea
Samsung Display and local competitors control micro-OLED wafer supply allocation for premium headset launches. MFDS medical device regulations are shaping biocompatibility testing requirements for patient-contact VR hardware. Seoul Capital Area fabrication facilities supply system-on-chip thermal management components to standalone headset manufacturers.
Virtual Reality Box Glasses Market Competitive Landscape
Premium-margin players sit above commodity-margin players across optical stack complexity and content ecosystem depth. The vendor base stratifies into three tiers: integrated platform operators with captive software stores, specialized optical component suppliers with display manufacturing heritage, and Shenzhen-based OEM assemblers serving price-sensitive institutional tenders. Dominant competitive moves include backward integration into lens fabrication capacity and strategic partnerships with enterprise training content platforms.
Within the integrated platform tier, Meta Platforms, Inc. and Sony Group Corporation exemplify divergent positioning strategies. Meta leverages its captive content ecosystem to sustain hardware attach rates, while Sony anchors its market presence through optical component specialization drawn from camera sensor manufacturing heritage. HTC Corporation occupies a distinct position in enterprise training verticals where device durability commands premium positioning. Microsoft Corporation and Google LLC represent technology conglomerates with cloud and productivity software assets that inform mixed-reality hardware roadmaps.
| Leading Market Players |
|---|
| Meta Platforms, Inc. |
| Sony Group Corporation |
| Microsoft Corporation |
| Samsung Group |
| HTC Corporation |
| Seiko Epson Corporation |
| Google LLC |
| Apple Inc. |
| Lenovo Group Ltd. |
| Others |
Pricing and Supply Chain Analysis
Micro-OLED wafer costs from Samsung Display and BOE Technology flow downstream through premium headset bill-of-materials, compressing margins for mid-tier assemblers while concentrating pricing power with optical stack integrators serving enterprise training contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates medical-grade enclosures with FDA 510(k) pathways from cardboard-derived education tenders and sub-$150 Shenzhen standalone units. Price differentiation hinges on ISO 9241 ergonomic certification and pancake lens optical complexity. Cost compression in smartphone-compatible tiers intensifies because entry-level standalone units from Guangzhou assemblers displace tethered enclosures. Education procurement committees in India and Indonesia exhibit highest price sensitivity; Boeing and Siemens maintenance divisions show lowest sensitivity where session completion rates justify weight-reduction premiums.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore handle hub-and-spoke patterns for EU and Asia-Pacific enterprise deployments. Manufacturing concentrates in China, Taiwan, and South Korea. Optical component sourcing draws from specialized lens fabricators in Dongguan and Taichung. Single-source vulnerability sits with micro-OLED wafer allocation controlled by two dominant suppliers. Distribution runs through electronics integrators for consumer channels and specialty AV distributors for healthcare and training verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Virtual reality box glasses function as a stable compounder anchored by institutional healthcare procurement pipelines that bypass consumer retail volatility.
For Market Incumbents: Cement platform stickiness through backward integration into pancake lens fabrication capacity in Taiwan and South Korea. Deepen enterprise training content partnerships to defend against full-stack platform providers bundling hardware, software, and biometric analytics. ISO 9241 certification investment creates procurement filters that emerging Shenzhen assemblers cannot easily replicate.
For New Entrants and Emerging Players: Direct-to-enterprise digital channels offer lower customer acquisition costs than retail shelf competition against Meta and Sony. White-space targets include Indian PLI scheme manufacturing for Middle East and African distribution, and force-feedback glove integration for German industrial training verticals. Specialty medical device distributors provide the most penetrable go-to-market angle for patient-contact therapeutic hardware.
For Investors and Strategic Acquirers: Roll-up economics work for optical component specialists because pancake lens design expertise concentrates in constrained geographic talent pools. Long-term viability rests on enterprise training budget expansion and FDA pathway clarity for therapeutic indications. Acquisition targets should show captive lens fabrication or haptic peripheral integration. Watch for ECHA REACH Annex XIV authorization timelines as inflection indicators for housing material reformulation costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Pancake Lens Fabrication Investment | Weight reduction below 250 grams extends session tolerance for Boeing and Siemens training programs. |
| Enterprise Training Platform Partnership | Full-stack bundling with content licensing and biometric analytics captures multi-year fleet management contracts. |
| ISO 9241 Ergonomic Certification | Third-party validation of interpupillary adjustment ranges filters procurement for healthcare and corporate buyers. |
| EU Green Deal Compliance Repositioning | Recycled polycarbonate and bio-based TPU housings open premium positioning for certified sustainable SKUs. |
| Haptic Feedback Peripheral Integration | Force-feedback glove convergence expands per-seat spend beyond hardware-only economics in manufacturing training. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged optical engineering directors at lens fabricators, procurement leads at enterprise training divisions, regulatory affairs specialists navigating FDA 510(k) pathways, and biomedical engineers at hospital systems. Secondary validation drew from FCC equipment authorization databases, ECHA REACH substance registrations, SAMR GB standard filings, and customs records for optical component trade flows. Bottom-up bill-of-materials modeling and top-down addressable market sizing were cross-referenced for triangulation.
Segment-weighting across product architecture, end-use intensity, and geographic regulatory clusters shaped the analytical framework. Standalone, smartphone-compatible, PC-compatible, and console-compatible form factors were modeled separately. Healthcare, training, gaming, and education end-use segments carried distinct replacement cycle assumptions. CAGRs were derived from installed base growth and average selling price trajectory analysis across the projection horizon. Forecast inputs included semiconductor cycle timing for micro-OLED wafer allocation and ECHA authorization timelines for housing material transitions.
The model assumes a particular technology adoption path; alternative pathways for waveguide optics or holographic displays would alter the outlook. Forecasts reflect assumptions around enterprise training budget continuity, REACH compliance cost pass-through, and healthcare reimbursement clarity for therapeutic VR. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Global Enterprise Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality and Virtual Reality (AR/VR) in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
India Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
China Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
5G and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Industrial Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Telepresence Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive AR and VR Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Learning Market
Virtual Reality (VR) and Augmented Reality (AR)
VR All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Somatosensory Virtual Fitting Market