
 Global Augmented Reality (AR) in Healthcare Market | 2026-2036
Global Augmented Reality (AR) in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Global Augmented Reality (AR) in Healthcare Market Foresight
Hospital procurement channels for AR surgical systems is fragmenting as regional purchasing consortia gain leverage over single-vendor contracts. Microsoft Corporation leverages its HoloLens enterprise footprint to anchor mixed-reality deployments across academic medical centers. Siemens Healthineers AG sustains deep imaging integration that differentiates its AR navigation from standalone hardware competitors. Google LLC competes through cloud-native architecture that reduces on-premise infrastructure burdens for mid-size hospitals.
Augmented Reality in Healthcare overlays digital anatomical models, real-time patient data, and navigational guidance onto the clinician's field of view through head-mounted displays or projection systems, typically operating at sub-20-millisecond latency to prevent motion sickness during prolonged procedures. Its primary purpose is to reduce surgical error rates and compress training curves for complex interventions. AR software commands disproportionate margin pools relative to hardware because recurring licensing and update revenue outpace one-time headset sales. Surgical navigation applications lead clinical adoption, while medical training represents the fastest-expanding use case as residency programs replace cadaver-based instruction with repeatable virtual scenarios. Cloud-based deployment is displacing on-premise installations among clinics seeking lower capital expenditure entry points.
The FDA's software-as-a-medical-device pathway shapes clearance timelines and clinical evidence requirements for AR platforms entering the US market. EMA's Medical Device Regulation and Japan's PMDA software review standards create parallel compliance obligations that fragment go-to-market strategies across major jurisdictions. Stakeholders must monitor how reimbursement codes for AR-assisted procedures evolve, as coding recognition determines whether hospital capital committees approve purchasing requests regardless of clinical efficacy demonstrations.
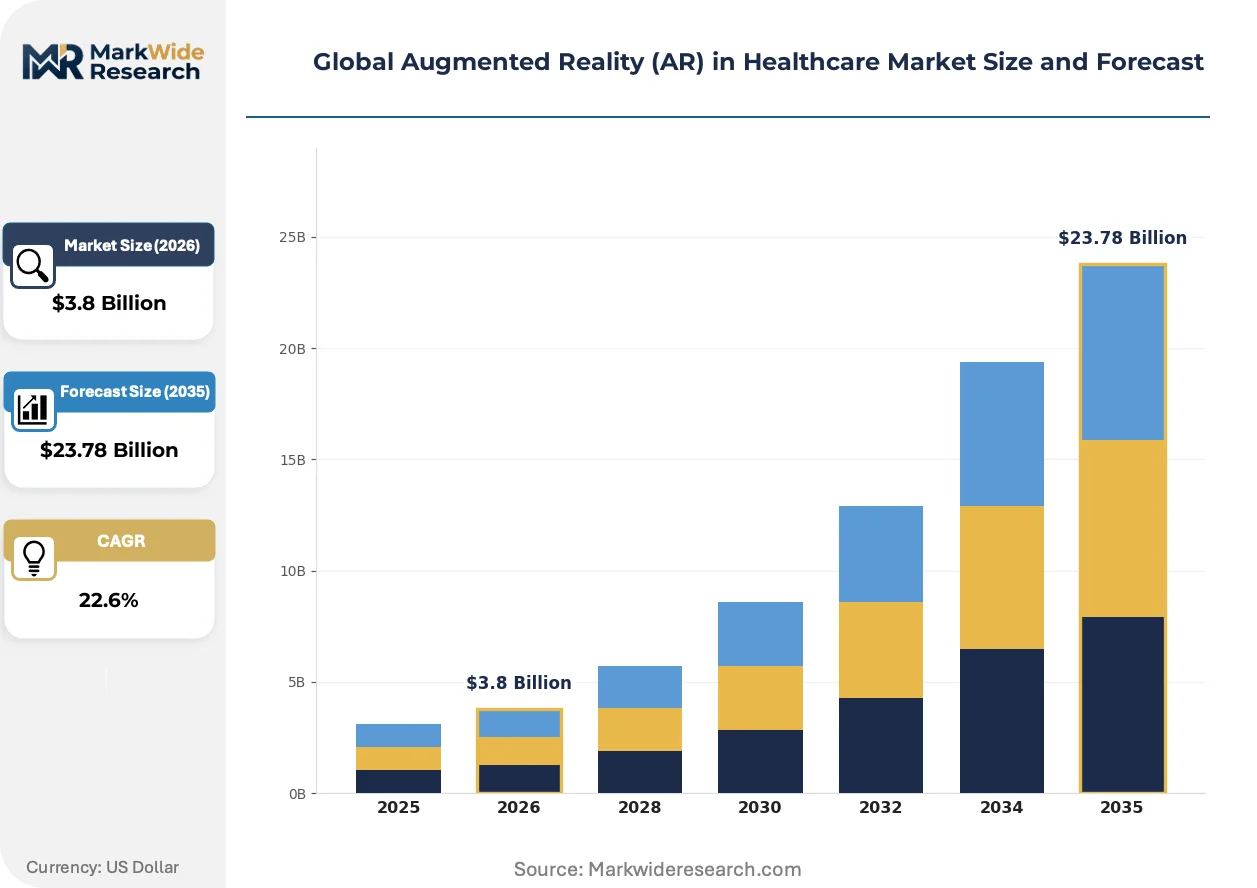
Market Dynamics
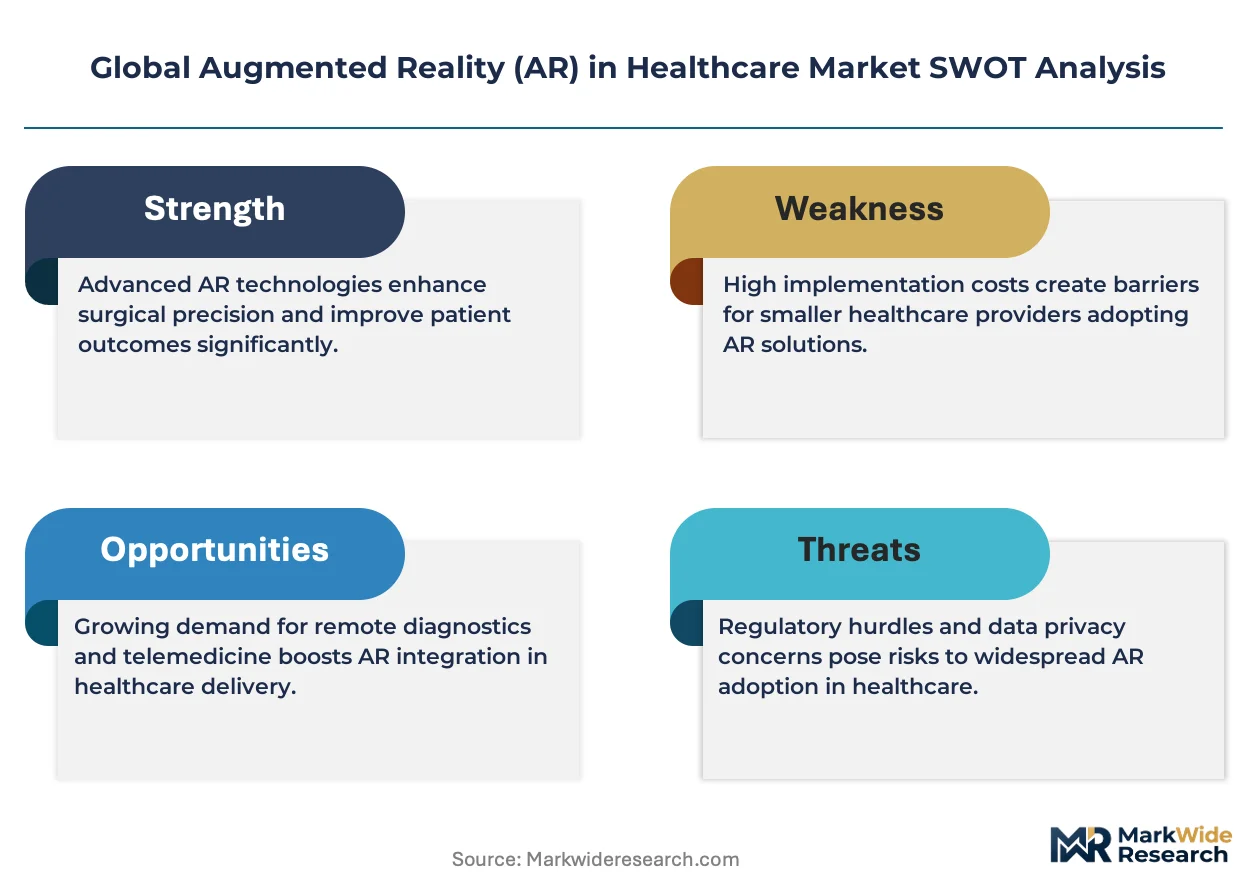
Hospital procurement committees now prioritize AR platforms with established FDA software-as-a-medical-device clearances over experimental hardware, compressing vendor selection timelines and favoring incumbent enterprise software ecosystems.
Growth Catalysts
- FDA Software-as-a-Medical-Device Pathway:The framework accelerates market entry for AR surgical navigation tools by clarifying clinical evidence requirements and reducing regulatory uncertainty for developers.
- Residency Program Modernization:Medical training institutions are replacing cadaver-based instruction with repeatable AR scenarios, creating institutional demand for simulation platforms.
- German Health Technology Assessment Programs:Dedicated evaluation frameworks for immersive surgical tools are creating reimbursement precedents that validate capital expenditure requests at university hospitals.
Market Restraints
- Optical Component Supply Concentration:High-resolution waveguide displays depend on specialized manufacturing concentrated in East Asian precision optics suppliers, creating single-source vulnerability.
- EMA Medical Device Regulation Compliance Costs:Parallel clinical evidence requirements for AR platforms seeking European market access inflate development budgets and extend timelines.
- Latency Threshold Technical Ceiling:Sub-20-millisecond motion-to-photon latency requirements demand specialized edge computing infrastructure that mid-size facilities cannot deploy.
Strategic Opportunities
- Japan PMDA Software Review Standards:Streamlined digital health device pathways create favorable entry conditions for AR training platforms targeting surgical residency programs.
- Cloud-Native Deployment Architectures:Converging 5G low-latency networks with containerized AR software eliminates on-premise server requirements for regional hospital networks.
- India Medical Education Infrastructure:Underpenetrated simulation training capacity at emerging medical colleges creates demand for scalable AR anatomy instruction without cadaver logistics.
Industry Challenges
- Interoperability with Legacy PACS Infrastructure:AR navigation systems require bidirectional integration with existing imaging archives that use incompatible data formats and security protocols.
- Clinical Evidence Generation Timelines:Randomized controlled trials for surgical outcome improvements demand multi-year study periods that outpace hardware refresh cycles.
- Biomedical Engineering Talent Scarcity:The specialized workforce combining surgical workflow knowledge with spatial computing software development concentrates at academic medical centers and major technology firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Augmented Reality (AR) in Healthcare Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.78 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AR Glasses, AR Headsets, AR Software, AR Displays, AR Controllers Application: Surgical Navigation, Medical Training, Patient Care, Rehabilitation, Therapy, Medical Imaging End User: Hospitals, Clinics, Medical Schools, Diagnostic Centers, Research Institutes Deployment: On-Premise, Cloud-Based, Hybrid, Mobile, Enterprise Solutions |
| Companies Covered | Microsoft Corporation, Siemens Healthineers AG, Google LLC, Magic Leap, Inc., Koninklijke Philips N.V., Augmedix, Inc., Osso VR, Inc., AccuVein Inc., CAE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Augmented Reality (AR) in Healthcare Market Shifts & Advancements
Spatial computing architectures are restructuring how surgical teams access patient-specific anatomical data, shifting competitive advantage from hardware specifications toward software integration depth and regulatory clearance velocity.
Edge-rendered holographic visualization is migrating from tethered operating room installations toward wireless headset deployments. Ambulatory surgical centers are adopting untethered AR systems at twice the pace of academic hospitals. This migration is compressing infrastructure requirements and enabling point-of-care deployment in facilities lacking dedicated biomedical engineering staff.
Japan's PMDA has issued guidance documents distinguishing standalone AR software from accessory hardware, clarifying which components require independent clinical validation. This policy shift reduces regulatory duplication for developers pursuing simultaneous US and Japanese market entry. Surgical navigation platforms with existing FDA clearances are prioritizing PMDA submissions to capture procurement cycles at Tokyo and Osaka university hospital networks.
Hospital capital committees now unbundle hardware acquisition from software licensing negotiations, treating AR headsets as commodity peripherals while negotiating multi-year SaaS contracts for procedural guidance content. Original equipment manufacturers are responding by decoupling device sales from platform subscriptions. This pattern is most visible in United States metropolitan health systems where procurement consortia aggregate purchasing power across multiple facilities.
Global Augmented Reality (AR) in Healthcare Market Segmentation
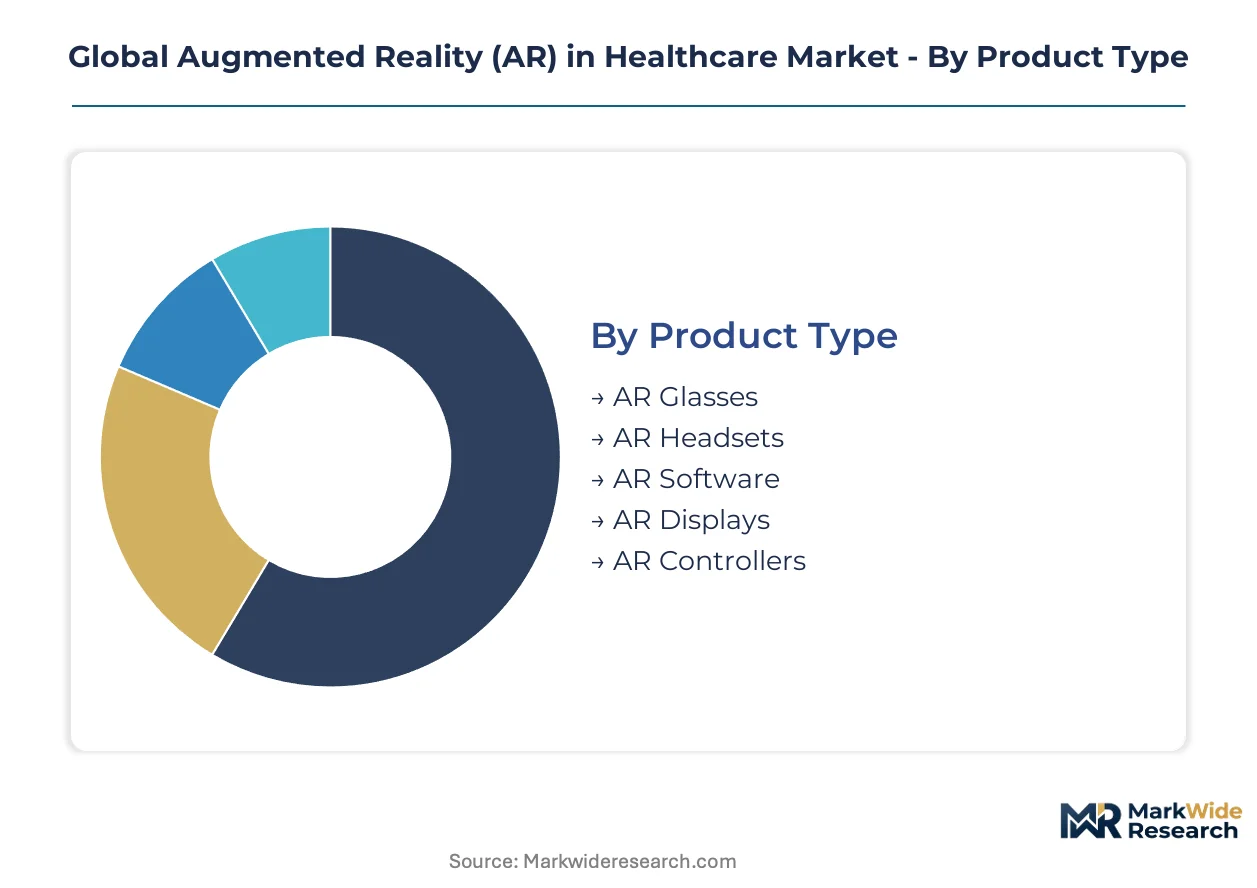
Segmentation reveals how AR healthcare value pools concentrate across hardware-software boundaries and deployment architectures. Procurement committees evaluate segments through distinct lenses: capital expenditure tolerance, regulatory clearance status, and interoperability with legacy infrastructure.
Product Type:
AR healthcare spans wearable hardware, visualization infrastructure, and algorithmic platforms, each commanding different margin structures and replacement cycles.
- AR Glasses:Lightweight waveguide displays projecting anatomical overlays at sub-20-millisecond latency, favored by ambulatory surgical centers in Germany seeking untethered workflows. Procurement concentrates in metropolitan hospital networks with established biomedical engineering staff.
- AR Headsets:Fully immersive mixed-reality devices with depth-sensing cameras and spatial mapping, anchoring academic medical center deployments across the United States. Demand clusters where FDA software-as-a-medical-device clearances already exist.
- AR Software:Procedural guidance engines and anatomical visualization platforms generating recurring licensing revenue. Cloud-native architectures reduce on-premise infrastructure burdens for mid-size hospitals.
- AR Displays:Projection-based systems rendering holographic patient data onto surgical fields without head-mounted equipment. Adoption lags in facilities lacking dedicated installation space.
- AR Controllers:Haptic and gesture interfaces enabling sterile manipulation of digital models during procedures. Integration challenges with existing surgical instrument sterilization protocols constrain deployment.
The dominant share belongs to AR Software, while AR Glasses is closing the gap fastest.
Application:
Clinical use cases range from real-time operative guidance to repeatable training scenarios, with reimbursement recognition determining capital committee priorities.
- Surgical Navigation:Real-time anatomical tracking and instrument guidance overlaying patient-specific imaging onto the operative field. University hospitals in Japan prioritize platforms with PMDA clearance for Tokyo and Osaka procurement cycles.
- Medical Training:Repeatable virtual scenarios replacing cadaver-based instruction in residency programs. German health technology assessment programs validate simulation platform expenditures.
- Patient Care:AR-enhanced patient education and preoperative planning tools. Deployment concentrates where HIPAA-compliant cloud infrastructure already exists.
- Rehabilitation:Movement tracking and biofeedback systems for post-surgical recovery. Reimbursement code ambiguity limits hospital capital allocation.
- Therapy:Mental health and pain management applications using immersive distraction techniques. Clinical evidence generation timelines outpace hardware refresh cycles.
- Medical Imaging:Three-dimensional reconstruction and collaborative review of radiological data. Bidirectional PACS integration requirements fragment vendor selection.
Surgical Navigation captures institutional procurement budgets, though Medical Training is expanding most quickly as residency programs modernize.
End User:
Facility type dictates infrastructure sophistication, regulatory compliance burden, and purchasing consortium leverage.
- Hospitals:Integrated delivery networks with dedicated capital committees evaluating AR platforms through clinical outcome and total cost-of-ownership lenses. United States metropolitan health systems unbundle hardware from SaaS negotiations.
- Clinics:Smaller facilities prioritizing cloud-based deployment to eliminate on-premise server requirements. 5G low-latency networks enable wireless headset adoption at twice the pace of academic hospitals.
- Medical Schools:Institutions replacing cadaver laboratories with scalable anatomy instruction. India emerging medical colleges drive demand for simulation infrastructure without cadaver logistics.
- Diagnostic Centers:Imaging-focused facilities requiring bidirectional integration with legacy PACS archives. Data format incompatibilities constrain platform selection.
- Research Institutes:Early-stage validation sites generating clinical evidence for regulatory submissions. Talent scarcity in biomedical engineering limits internal development capacity.
Hospitals command the largest procurement volumes, while Clinics are adopting cloud-native architectures fastest.
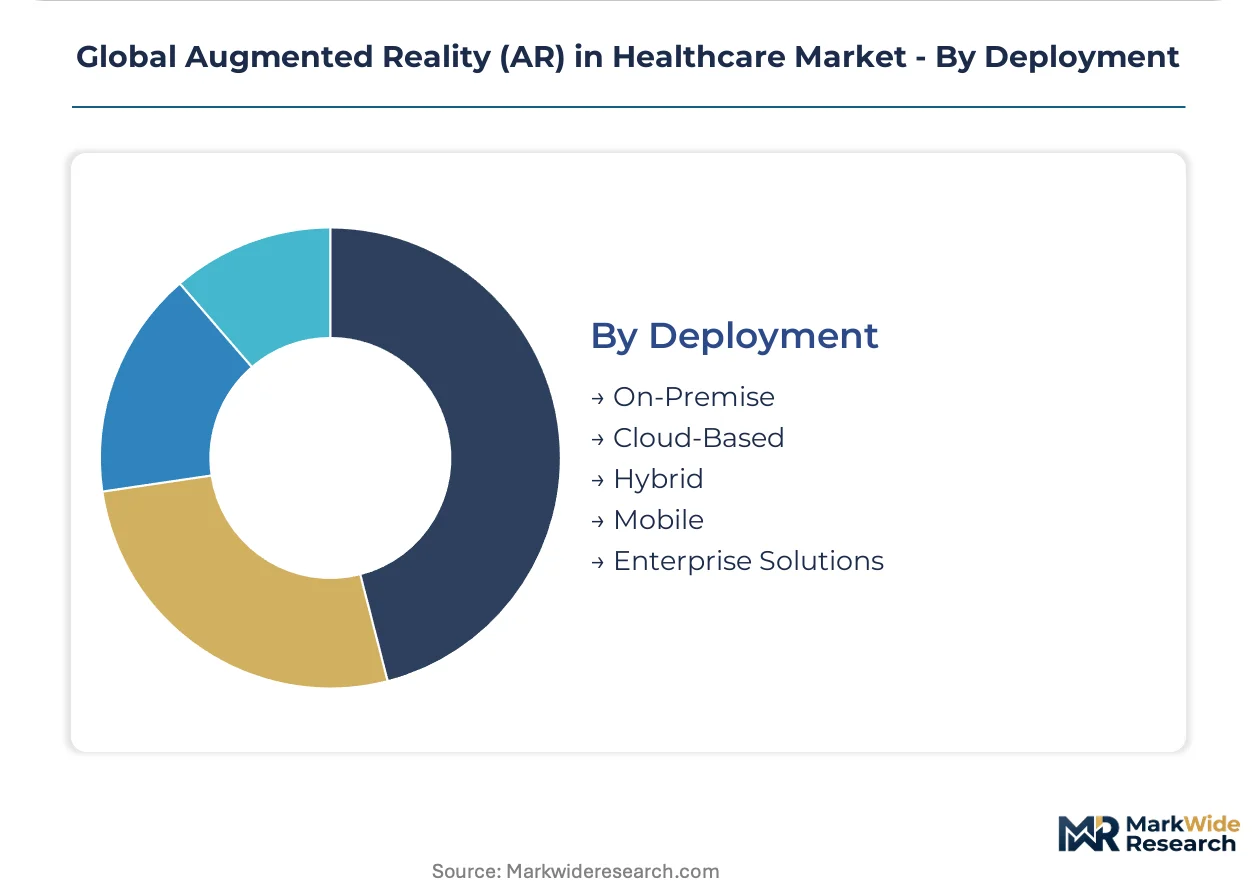
Deployment:
Infrastructure architecture choices determine latency performance, capital intensity, and IT staffing requirements.
- On-Premise:Local server installations delivering sub-20-millisecond motion-to-photon latency through dedicated edge computing. Mid-size facilities face deployment barriers due to specialized infrastructure demands.
- Cloud-Based:Containerized software eliminating capital expenditure entry points for regional hospital networks. Converging 5G networks enable wireless surgical deployments.
- Hybrid:Split architectures processing sensitive patient data locally while leveraging cloud resources for non-critical functions. Addresses HIPAA compliance concerns in United States deployments.
- Mobile:Tablet and smartphone-based AR without dedicated headsets. Limited clinical utility in sterile surgical environments constrains adoption.
- Enterprise Solutions:Multi-facility licensing agreements aggregating purchasing power across hospital networks. Procurement consortia in United States metropolitan systems favor this structure.
Cloud-Based deployment is gaining share fastest, though On-Premise retains dominance where latency thresholds are non-negotiable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA software-as-a-medical-device clearances anchor procurement decisions in the United States, while parallel regulatory pathways in Germany and Japan shape competitive entry strategies. Hospital capital committees in these markets prioritize platforms with established regulatory validation over experimental hardware.
United States
Metropolitan health systems unbundle hardware from SaaS negotiations, treating AR headsets as commodity peripherals while locking in multi-year platform subscriptions. FDA's evolving framework for software-as-a-medical-device compresses vendor selection timelines for surgical navigation tools. Procurement consortia in Chicago, Houston, and Los Angeles aggregate purchasing power across integrated delivery networks.
Germany
Dedicated health technology assessment programs for immersive surgical tools validate capital expenditure requests at university hospitals in Berlin and Munich. EMA Medical Device Regulation compliance creates parallel evidence requirements that inflate development budgets for European market entry. Siemens Healthineers anchors mixed-reality deployments through deep imaging integration at academic medical centers in Bavaria and North Rhine-Westphalia.
Japan
PMDA guidance distinguishing standalone AR software from accessory hardware reduces regulatory duplication for developers pursuing simultaneous US and Japanese market entry. Tokyo and Osaka university hospital networks prioritize platforms with existing PMDA clearances for surgical navigation procurement cycles. METI standards for digital health devices streamline validation pathways for residency training platforms.
India
Emerging medical colleges drive demand for scalable AR anatomy instruction without cadaver logistics, creating infrastructure gaps that cloud-native architectures address. CDSCO medical device regulations for software-based diagnostic tools shape clearance timelines for training platforms entering the domestic market. Karnataka and Maharashtra state medical universities modernize simulation capacity through centralized procurement of wireless headset systems.
United Kingdom
NHS capital committees evaluate AR platforms through clinical outcome and total cost-of-ownership lenses, favoring cloud-based deployments that eliminate on-premise server requirements. MHRA software medical device guidance aligns with FDA pathways to accelerate dual-clearance strategies for surgical navigation vendors. London and Manchester academic hospital networks pilot untethered AR systems for ambulatory surgical workflows.
Global Augmented Reality (AR) in Healthcare Market Competitive Landscape
Enterprise technology conglomerates and specialized health technology vendors split the market through divergent integration strategies. Consolidation pressure favors incumbents with established regulatory clearances and enterprise software ecosystems. Three archetypes dominate: imaging-integrated hardware manufacturers, cloud-native platform providers, and simulation-focused training specialists. Competitive moves center on strategic partnerships with academic medical centers and portfolio diversification into adjacent surgical workflow tools.
Within the enterprise technology tier, Microsoft Corporation and Google LLC exemplify divergent architectural approaches to hospital infrastructure. Microsoft leverages its HoloLens enterprise footprint to anchor mixed-reality deployments, while Google competes through cloud-native architecture that reduces on-premise burdens. Siemens Healthineers AG occupies a position bridging imaging hardware with AR navigation software, representing the imaging-integrated manufacturer archetype that sustains competitive differentiation through deep PACS connectivity.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Siemens Healthineers AG |
| Google LLC |
| Magic Leap, Inc. |
| Koninklijke Philips N.V. |
| Augmedix, Inc. |
| Osso VR, Inc. |
| AccuVein Inc. |
| CAE Healthcare |
| Others |
Supply & Pricing Matrix
Taoyuan's precision optics cluster anchors waveguide display manufacturing, concentrating capacity for high-resolution AR surgical headsets among three dominant suppliers. This geographic concentration grants upstream vendors substantial pricing leverage over hardware OEMs, while downstream hospital procurement consortia compress margins through aggregated SaaS negotiations.
Pricing Analysis
US-German-Japanese price spreads of 15-25 percent reflect divergent reimbursement code maturity and regulatory validation costs. Three-tier pricing structure across FDA-cleared platforms, CE-marked systems, and pre-certification hardware segments the market. Pricing pressure stems from cloud-native entrants offering subscription models that undercut perpetual licenses. Mid-size clinics exhibit highest price sensitivity, while academic medical centers prioritize clearance status over cost.
Supply Chain Analysis
Foxconn and Jabil hold contract manufacturing capacity for AR headset assembly, with Luxshare supplying critical waveguide components. Taiwan, South Korea, and Japan concentrate precision optics and microdisplay fabrication. Supply chains draw from specialized gallium nitride substrates, rare-earth phosphors, and high-index glass substrates. Single-source vulnerability in diffractive waveguide etching creates bottlenecks. Distribution runs through regional medical device distributors with FDA 510(k) clearance documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from flat-panel 3D visualization systems that bypass head-mounted hardware entirely, preserving surgical navigation revenue pools.
For Market Incumbents: Build regulatory clearance velocity as the primary moat by accelerating FDA software-as-a-medical-device submissions ahead of hardware refresh cycles. Deepen imaging integration through bidirectional PACS connectivity that standalone hardware competitors cannot replicate. Counter emerging cloud-native entrants by bundling on-premise latency guarantees with enterprise SaaS contracts.
For New Entrants and Emerging Players: Build out India medical college simulation infrastructure as the most penetrable white-space target, where cadaver logistics constraints create immediate demand for scalable AR anatomy instruction. Target German health technology assessment programs for reimbursement precedent validation. Pursue channel partnerships with established GPOs rather than direct hospital sales.
For Investors and Strategic Acquirers: Long-term, this sits as a software-margin compounding play because recurring platform licensing outpaces hardware depreciation cycles and generates predictable cash flows. Target acquisition candidates with existing FDA clearances and embedded clinical workflow integration. Monitor PMDA submission timelines for Tokyo-Osaka university hospital procurement cycles as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | Accelerates market entry by clarifying clinical evidence requirements for AR surgical navigation platforms. |
| Hospital System Partnership | Locks in multi-year SaaS revenue through integrated delivery network procurement consortia in metropolitan United States markets. |
| Imaging Integration Development | Differentiates from standalone hardware competitors through deep PACS connectivity at Siemens Healthineers scale. |
| Cloud-Native Architecture Deployment | Reduces capital expenditure barriers for mid-size clinics via 5G-enabled wireless headset systems. |
| Reimbursement Strategy | Secures health technology assessment validation in Germany and coding recognition in United States Medicare. |
Research Methodology
A standing panel of hospital purchasing committee directors, biomedical engineering leads, GPO contracts managers, and surgical navigation specialists provided ongoing calibration across the study period. Primary interviews combined with secondary validation against FDA 510(k) databases, EMA Medical Device Regulation guidance documents, hospital procurement records, and CMS reimbursement coding updates. Bottom-up segment sizing triangulated with top-down market boundary checks.
Scenario-bracketing framed optimistic, baseline, and constrained projections across the analysis window. Segmentation dimensions modeled include product type, application, end-user facility category, and deployment architecture. CAGRs derived from weighted average of historical trajectory and technology diffusion curve analysis. Forecast inputs incorporated 5G network rollout timelines and health technology assessment program expansion schedules.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by cloud hyperscalers would shift outcomes through subsidized hardware deployment. Regulatory pathway acceleration or delay at FDA, EMA, and PMDA represents primary revision risk. Quarterly review of hospital capital committee approval rates and reimbursement code updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
3D Telepresence Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
India Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Mobile Infrastructure Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented and Virtual Reality (AR VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Canada Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
AR in Healthcare Market
Virtual Reality (VR) and Augmented Reality (AR)
Social VR Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Enterprise AR Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Connected Service Market
Virtual Reality (VR) and Augmented Reality (AR)
AR-VR Head Display Equipment Market