
 VR Head Show Market | 2026-2036
VR Head Show Market Size, Share, and Industry Trends Forecast 2026-2036
VR Head Show Market Insights
China is reconfiguring regional supply dynamics through expanded optoelectronics manufacturing clusters in Shenzhen and Chengdu. Meta Platforms leverages its Quest ecosystem to sustain software-hardware integration across consumer and enterprise tiers. Sony Interactive Entertainment anchors premium tethered headset production through disciplined semiconductor sourcing from domestic Japanese fabs. HTC Corporation competes in enterprise simulation with specialized lighthousing tracking systems for medical and military training contracts.
A VR head show is a wearable display system combining near-eye microdisplays, Fresnel or pancake optics, and inertial measurement units to render stereoscopic 3D environments with sub-20ms motion-to-photon latency. The device serves industrial design review, surgical planning, and interactive entertainment by replacing flat screens with spatial computing interfaces. Standalone headsets capture the largest volume pool as wireless Snapdragon XR platforms eliminate PC dependency for mainstream gaming and social applications. Tethered headsets retain margin concentration in flight simulation and automotive styling studios where pixel density and refresh rate thresholds exceed untethered capabilities. Healthcare applications represent the fastest-expanding demand segment as surgical training programs at Cleveland Clinic and Johns Hopkins adopt haptic-integrated immersive modules.
The FCC in the United States enforces SAR limits and RF exposure standards that constrain transmit power in wireless VR headsets, while the EU AI Act and CE marking framework under ECHA jurisdiction impose algorithmic transparency requirements for eye-tracking and biometric data collection. China's MIIT and GB standards mandate cybersecurity review for devices processing spatial mapping data, creating divergent certification pathways for multinational vendors. Stakeholders must monitor whether regulatory fragmentation around biometric data governance forces region-specific hardware SKUs or unified platform architectures.
Market Dynamics
Enterprise procurement of VR head shows is concentrating around Qualcomm Snapdragon XR platforms and pancake optics, compressing hardware margins while expanding software attach rates across industrial training programs.
Growth Catalysts
- EU AI Act biometric transparency mandates:Algorithmic disclosure requirements for eye-tracking data are accelerating enterprise adoption of certified immersive training modules at regulated facilities.
- Optoelectronics clustering in Shenzhen:Domestic Chinese supply chains for microdisplays and Fresnel lenses are reducing component lead times for both consumer and industrial headset assembly.
- Surgical simulation demand:Haptic-integrated VR modules for preoperative planning are penetrating residency programs at major academic medical centers.
Market Restraints
- Semiconductor supply concentration:Advanced XR SoC fabrication depends on TSMC capacity allocation, creating procurement bottlenecks for standalone headset vendors.
- FCC SAR exposure limits:RF power caps on wireless transmitters constrain untethered device performance in high-density enterprise deployments.
- Display panel cost volatility:Micro-OLED wafer yields fluctuate with semiconductor substrate availability, pressuring bill-of-materials predictability.
Strategic Opportunities
- MIIT cybersecurity review pathways:GB standards compliance for spatial mapping data processing opens procurement channels to Chinese state-owned enterprise training programs.
- Convergence of eye-tracking with biometric authentication:Foveated rendering combined with iris recognition enables secure access control in defense and healthcare settings.
- Direct-to-enterprise channel expansion:Bypassing consumer retail distribution reduces channel margin extraction for specialized simulation hardware vendors.
Industry Challenges
- Optical engineer talent scarcity:Pancake lens design and waveguide fabrication expertise concentrates among former camera module and semiconductor lithography specialists.
- CE marking timeline compression:ECHA algorithmic transparency documentation for eye-tracking systems extends product launch cycles by four to six months.
- Legacy CAD integration complexity:Industrial design review workflows require custom API development to bridge immersive headsets with existing product lifecycle management databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VR Head Show Market |
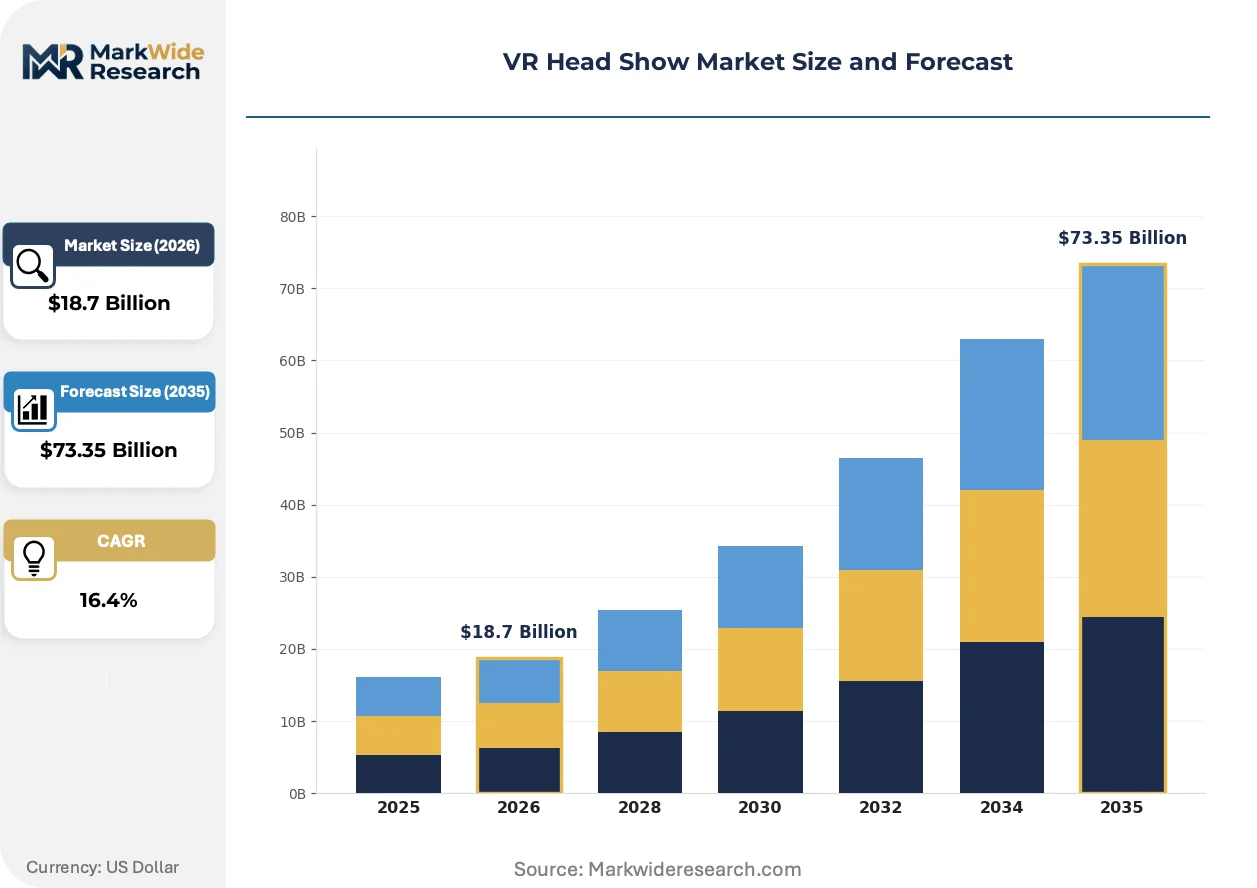
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Headsets, Tethered Headsets, Mobile Headsets, Smartphone-Integrated Application: Gaming, Education, Training, Healthcare End User: Individual Consumers, Educational Institutions, Corporates, Healthcare Providers Technology: Augmented Reality, Mixed Reality, 3D Visuals, Gesture Recognition |
| Companies Covered | Meta Platforms, Sony Interactive Entertainment, HTC Corporation, Samsung Electronics, Microsoft Corporation, Valve Corporation, Pico Interactive, Apple, Varjo Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VR Head Show Market Trends and Innovations
Optical architectures and biometric data governance are the primary vectors reshaping competitive differentiation, with hardware vendors racing to reduce form factor weight while navigating divergent regulatory frameworks for spatial computing.
Pancake optics is migrating from premium tethered headsets toward mid-tier standalone devices, compressing the thickness and weight of near-eye display assemblies. Automotive styling studios and flight simulation centers in Germany and Japan are adopting these folded optical paths to enable multi-hour continuous use. The technology is migrating from niche professional equipment toward mass-market hardware, collapsing the historical segmentation between enterprise-grade and consumer-grade optical performance.
The EU AI Act's algorithmic transparency requirements for biometric data processing are forcing hardware vendors to document eye-tracking inference models before CE marking approval. Medical device manufacturers must now submit technical documentation to notified bodies describing how gaze vectors are computed and stored. Surgical training programs at European university hospitals are delaying procurement decisions until full regulatory clarity emerges on class IIa medical device classification for diagnostic VR applications.
Enterprise buyers are consolidating vendor relationships around integrated hardware-software platforms rather than sourcing displays, tracking systems, and content engines separately. Defense contractors and aviation maintenance trainers in the United States are negotiating multi-year enterprise licensing agreements that bundle device refresh cycles with content library access. This purchasing consolidation is most visible in North American federal procurement channels, where single-vendor accountability reduces integration risk for classified training environments.
VR Head Show Market Segmentation
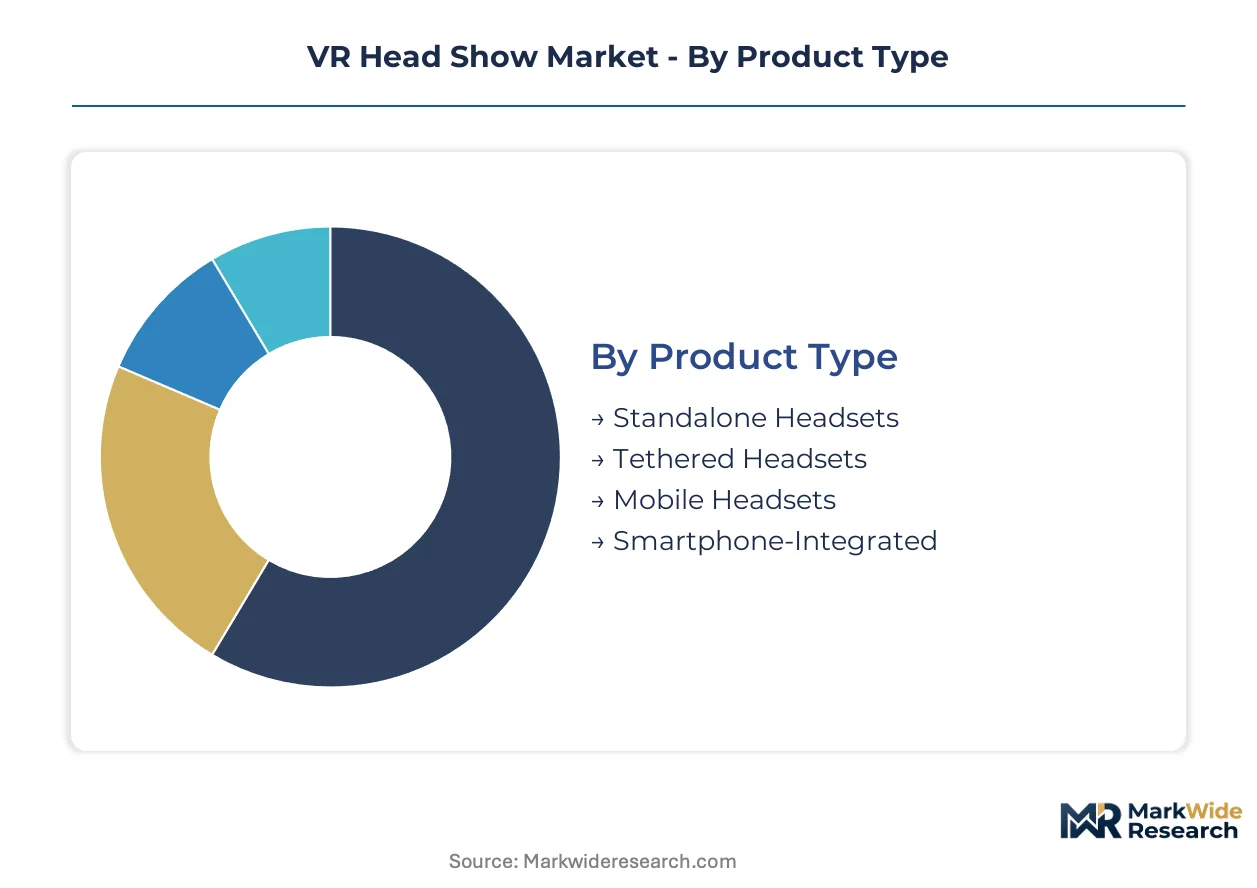
Segmentation in the VR head show market exposes divergent margin structures across hardware architectures and end-use economics. Procurement patterns for Qualcomm Snapdragon XR platforms versus tethered GPU-dependent systems create fundamentally different vendor relationships and replacement cycles.
Product Type:
Mature wireless platforms dominate volume procurement while emerging optical architectures reshape premium tiers.
- Standalone Headsets:Wireless Snapdragon XR platforms integrate compute, display, and battery into a single housing, eliminating PC dependency. Walmart and Boeing deploy these for warehouse logistics and assembly training where cable management disrupts mobility. Qualcomm's chip supply allocation constrains vendor scaling during demand surges.
- Tethered Headsets:DisplayPort or USB-C tethering to discrete GPUs enables 4K-per-eye resolution and sub-20ms latency thresholds. Flight simulation centers at Lufthansa Aviation Training and automotive styling studios in Stuttgart specify these for pixel-critical applications where wireless compression artifacts degrade immersion.
- Mobile Headsets:Shell designs leveraging smartphone compute and displays occupy entry price tiers. Samsung Gear VR legacy users and Google Cardboard educational deployments sustain residual demand despite standalone displacement.
- Smartphone-Integrated:Direct handset docking architectures with integrated optics and sensors bridge casual and dedicated VR use. Chinese OEMs including Xiaomi and OPPO have explored this form factor for domestic consumer markets where standalone penetration remains cost-prohibitive.
Standalone headsets handle the majority of throughput; tethered configurations are expanding most quickly in enterprise simulation contracts.
Application:
Cost tier separation distinguishes consumer entertainment from regulated professional training budgets.
- Gaming:Beat Saber and Half-Life: Alyx drive hardware attach rates through SteamVR and Meta Quest Store distribution. Consumer price elasticity constrains ASPs below enterprise tiers despite comparable bill-of-materials.
- Education:K-12 STEM modules and university laboratory simulations adopt wireless headsets for safety and hygiene. San Diego Unified School District and similar US public systems issue RFPs with 500+ unit volumes and multi-year refresh cycles.
- Training:Industrial maintenance and hazardous environment preparation command premium pricing with haptic integration. Shell's offshore rig safety programs and Siemens factory automation training represent multi-site deployment templates.
- Healthcare:Surgical planning and phobia therapy applications face FDA and CE marking pathways that extend procurement timelines. Cleveland Clinic and Johns Hopkins residency programs pilot haptic-integrated modules for preoperative rehearsal.
Gaming absorbs the largest unit volumes; healthcare is gaining share fastest as regulatory clarity emerges for diagnostic VR classification.
End User:
Customer type determines purchasing authority structures and integration complexity.
- Individual Consumers:Direct-to-consumer retail through Amazon and Best Buy dominates, with Meta Quest capturing mainstream gaming and social VR demand.
- Educational Institutions:District-level IT procurement with E-rate funding eligibility shapes US public school purchasing patterns.
- Corporates:Centralized procurement through learning and development departments favors enterprise licensing over per-device sales.
- Healthcare Providers:Hospital system value analysis committees evaluate clinical outcomes evidence before capital equipment approval.
Individual consumers represent the installed base anchor; healthcare providers are climbing the fastest as reimbursement frameworks adapt.
Technology:
Supply concentration in microdisplay and sensor fabrication creates vendor lock-in dynamics.
- Augmented Reality:Optical see-through waveguides from WaveOptics and Digilens enable contextual information overlay. Microsoft HoloLens 2 and Magic Leap 2 target industrial maintenance with hands-free operation.
- Mixed Reality:Passthrough camera arrays blend physical and virtual environments, enabling spatial anchoring for collaborative design review.
- 3D Visuals:Stereoscopic rendering pipelines and foveated display techniques reduce GPU load while maintaining perceived resolution.
- Gesture Recognition:Computer vision hand tracking eliminates controller dependency for casual interactions.
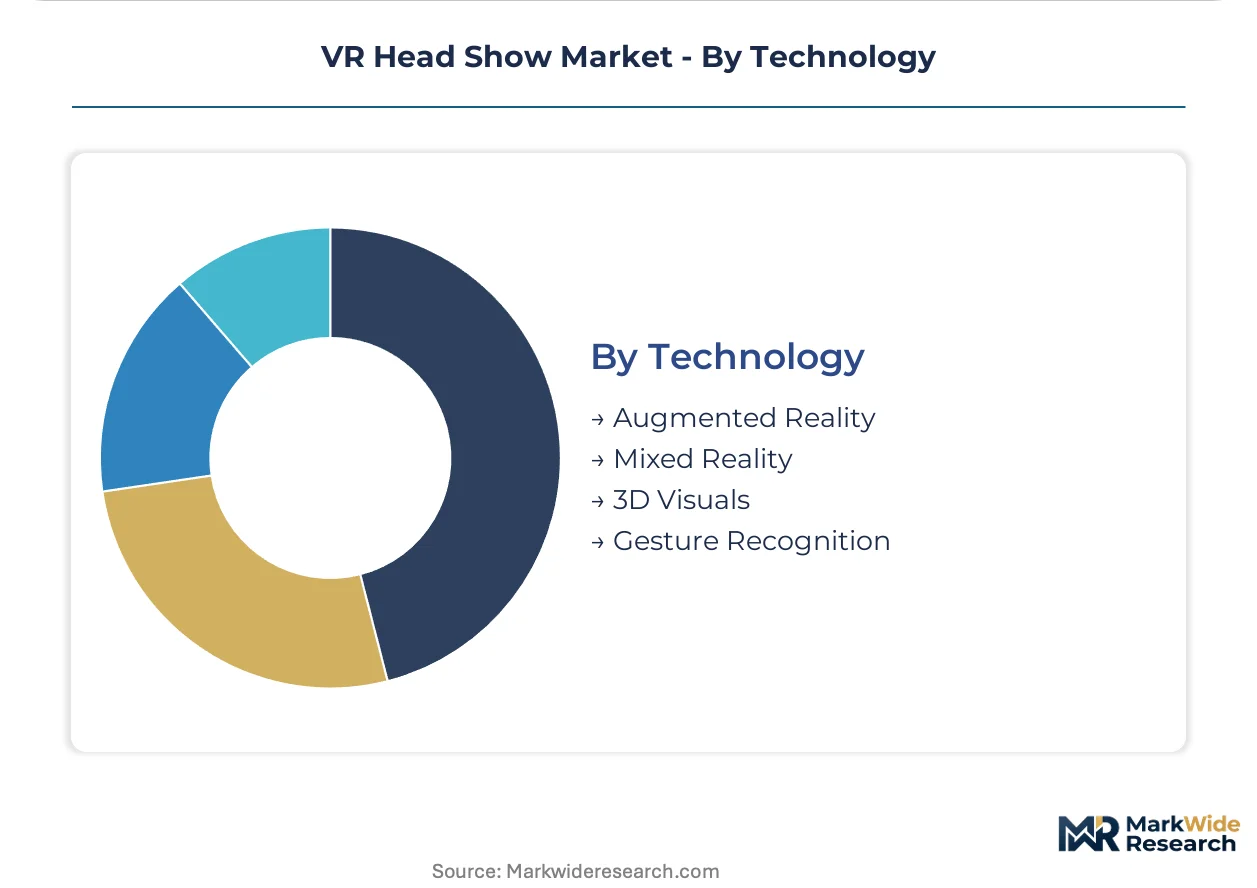
Mixed Reality handles the majority of new enterprise evaluations; Augmented Reality is expanding most quickly in defense and industrial maintenance segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optoelectronics manufacturing clusters in Shenzhen and Chengdu anchor component supply for global headset assembly. The EU AI Act and CE marking requirements under ECHA jurisdiction reshape certification timelines for immersive devices entering European markets. Procurement patterns diverge across regulatory environments as biometric data governance creates region-specific compliance burdens.
United States
Boeing and Walmart drive enterprise hardware procurement for training programs. The FCC enforces SAR limits and RF exposure standards that constrain transmit power in wireless headsets. Flight simulation centers in Florida and Texas specify tethered configurations for pixel-critical applications.
China
Domestic brands scale manufacturing for both consumer and industrial buyers through expanded optoelectronics clusters. MIIT and GB standards mandate cybersecurity review for devices processing spatial mapping data. Shenzhen and Chengdu production hubs reduce component lead times for microdisplays and Fresnel lenses.
Germany
Automotive styling studios in Stuttgart adopt pancake optics for multi-hour continuous use in design review. The EU AI Act imposes algorithmic transparency requirements for eye-tracking data before CE marking approval. ECHA jurisdiction extends product launch cycles for biometric-integrated devices.
Japan
Sony Interactive Entertainment anchors premium tethered headset production through disciplined semiconductor sourcing from domestic fabs. METI oversight shapes industrial technology adoption timelines for enterprise simulation contracts. Nagoya and Osaka manufacturing corridors concentrate precision optics fabrication expertise.
United Kingdom
University hospitals pilot haptic-integrated surgical training modules pending regulatory clarity on class IIa medical device classification. GDPR compliance requirements intersect with EU AI Act mandates for biometric data processing. London-based defense contractors negotiate multi-year enterprise licensing for classified training environments.
VR Head Show Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in microdisplay and sensor fabrication. The vendor base stratifies between consolidated platform ecosystems and fragmented optical component suppliers. Three archetypes dominate: Snapdragon XR platform licensees, pancake optics specialists, and enterprise simulation integrators. Competitive moves concentrate on strategic partnerships for content library access and capacity expansion in Chinese optoelectronics clusters.
Among platform-scale integrators, Meta Platforms and Sony Interactive Entertainment occupy positions spanning consumer and enterprise tiers. HTC Corporation sits within the specialized simulation segment. These three exemplify divergent strategic postures: ecosystem lock-in through software-hardware integration, disciplined domestic semiconductor sourcing, and targeted lighthouse tracking contracts for regulated training environments.
| Leading Market Players |
|---|
| Meta Platforms |
| Sony Interactive Entertainment |
| HTC Corporation |
| Samsung Electronics |
| Microsoft Corporation |
| Valve Corporation |
| Pico Interactive |
| Apple |
| Varjo Technologies |
| Others |
Pricing and Supply Chain Analysis
TSMC fab undercapacity in advanced XR SoC nodes compresses procurement timelines for standalone headset vendors while simultaneously elevating component premiums passed through to enterprise buyers. This utilization squeeze tightens margin pools across mid-tier hardware tiers and accelerates consolidation around vertically integrated platform licensors.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across biometric-integrated VR head shows, separating CE-marked medical-grade systems from consumer entertainment hardware. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with FDA-cleared surgical training modules commanding substantial premiums over industrial safety applications. Cost compression in standalone Snapdragon XR platforms stems from Qualcomm's chip allocation constraints, while tethered configurations for flight simulation show reduced price sensitivity due to pixel-density requirements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for lens assembly and microdisplay sourcing. Component fabrication draws from Taiwan for XR SoCs, Japan for precision optics, and China for Fresnel lens molding and final assembly. Single-source vulnerability concentrates in TSMC's N4/N5 node capacity for Qualcomm Snapdragon XR2+ Gen 2 chipsets. Distribution runs through direct enterprise licensing channels for defense and aviation contracts, bypassing retail margin extraction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The VR head show market is accelerating through regulatory inflection as the EU AI Act's biometric transparency mandates force hardware redesign cycles and certification investments ahead of CE marking deadlines.
For Market Incumbents: Pre-empt margin erosion in standalone consumer tiers by securing captive supply agreements for pancake optics modules from Shenzhen-based fabricators. Anchor enterprise relationships through multi-year platform licensing that bundles device refresh cycles with surgical training content libraries, insulating against emerging entrants with pure hardware plays.
For New Entrants and Emerging Players: Pursue white-space opportunity in haptic-integrated healthcare modules for European university hospitals awaiting class IIa medical device classification clarity. Target direct-to-institution sales bypassing GPO channels, with initial beachhead through pilot contracts at Cleveland Clinic-scale academic medical centers seeking preoperative rehearsal tools.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among enterprise simulation integrators bundling hardware-software-platform access. Long-term viability hinges on regulatory certification moats rather than component cost advantages. Monitor FDA breakthrough device designations for diagnostic VR applications as the definitive inflection signal for healthcare segment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | ECHA algorithmic transparency documentation compresses launch timelines for eye-tracking systems entering European markets. |
| Pancake Optics Manufacturing Scale-Up | Shenzhen and Chengdu cluster expansion reduces lens assembly lead times for mid-tier standalone headset production. |
| Enterprise Licensing Agreement Expansion | Multi-year platform contracts with Boeing and Walmart anchor recurring revenue and reduce customer acquisition costs. |
| Biometric Data Governance Investment | GDPR and EU AI Act compliance infrastructure enables procurement access to regulated healthcare and defense channels. |
| Qualcomm Snapdragon XR Platform Integration | Chip-level integration secures supply allocation priority and reduces bill-of-materials volatility for volume production. |
Research Methodology
Desk research of SEC filings, ECHA regulatory databases, and hospital procurement records preceded structured interviews with VR hardware product managers, surgical training directors at academic medical centers, aviation maintenance training officers, and semiconductor procurement leads at Tier 1 OEMs. Primary fieldwork validated component cost structures and certification timeline assumptions, while secondary sources anchored market sizing through customs data and enterprise licensing disclosures. Bottom-up unit economics triangulated against top-down sector spending estimates.
Assumptions held fixed include regulatory enforcement intensity across the analysis window, Qualcomm's foundry allocation priorities, and enterprise training budget elasticity. Segmentation modeling incorporated product architecture, application vertical, end-user purchasing authority, and regional regulatory cluster. CAGRs derived from weighted scenario analysis across standalone versus tethered adoption curves, with surgical simulation penetration and defense procurement cycles as primary demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic brands or Apple-scale ecosystem entrants would shift outcomes substantially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
India Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Prototype Market
Virtual Reality (VR) and Augmented Reality (AR)
Neuro-Gaming Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
Wireless AR Glass Market
Virtual Reality (VR) and Augmented Reality (AR)
US Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Social VR Market
Virtual Reality (VR) and Augmented Reality (AR)
Florida Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Collaboration Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality (AR) Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) in Healthcare Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR Solutions Market
Virtual Reality (VR) and Augmented Reality (AR)
Internet of Senses Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Visor Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Enterprise Augmented Reality Market