
 Virtual Reality (VR) and Augmented Reality (AR) Microdisplay Market | 2026-2036
Virtual Reality (VR) and Augmented Reality (AR) Microdisplay Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Reality (VR) and Augmented Reality (AR) Microdisplay Market Insights
Resolution-grade upgrades toward 4K-per-eye and beyond is unwinding legacy supply commitments as OEMs retool for immersive fidelity. Sony Group Corporation leverages its CMOS image sensor fabrication infrastructure to produce OLED microdisplays with integrated driver logic. Kopin Corporation anchors the defense and industrial training segments with its Lightning silicon backplane architecture. JBD, Inc. specializes in gallium nitride MicroLED emitters for waveguide-coupled AR glasses.
Virtual Reality and Augmented Reality microdisplays are compact, high-pixel-density panels—typically under one inch diagonal with pixel pitches below 10 micrometers—manufactured on silicon wafers using semiconductor lithography to achieve luminance exceeding 5,000 nits for see-through AR applications. These devices convert electronic signals into photonic output for near-to-eye optical systems, enabling immersive visualization without conventional display form factors. OLED microdisplays currently occupy the premium tier for VR headsets due to their self-emissive architecture and sub-millisecond response times, while MicroLED technology leads growth trajectory as epitaxial lift-off yields improve and red-emitting chip efficiency advances. Near-to-Eye technology dominates shipment volumes, though Transparent display architectures command margin concentration in enterprise AR where optical see-through fidelity determines procurement decisions.
FCC equipment authorization rules in the United States govern radio-frequency emissions from wireless-tethered headsets, while CE marking under the EU Radio Equipment Directive mandates SAR testing and interoperability standards for European market access. China's GB standards for electronic displays, administered by SAMR, specify luminance limits and blue-light hazard thresholds that directly influence panel design specifications. Stakeholders must monitor evolving ophthalmic safety regulations across jurisdictions, as exposure-duration limits for near-eye displays remain under active scientific review and will shape certification requirements for next-generation products.
Market Dynamics
Resolution-grade upgrades toward 4K-per-eye and beyond are unwinding legacy supply commitments as OEMs retool for immersive fidelity. The EU AI Act and CE marking requirements for wearable electronics are tightening optical safety and electromagnetic compatibility standards.
Growth Catalysts
- GB Standards Luminance Mandates:China's SAMR-administered electronic display regulations specify blue-light hazard thresholds that directly accelerate panel design iterations for domestic AR device makers.
- Gaming Headset Procurement:Headset manufacturers serving the gaming sector are expanding procurement of high-resolution microdisplays as immersive fidelity becomes a primary competitive differentiator.
- Shenzhen Display Cluster:Shenzhen's concentrated panel component supply base feeds both domestic Chinese AR device production and export-bound manufacturing for international OEMs.
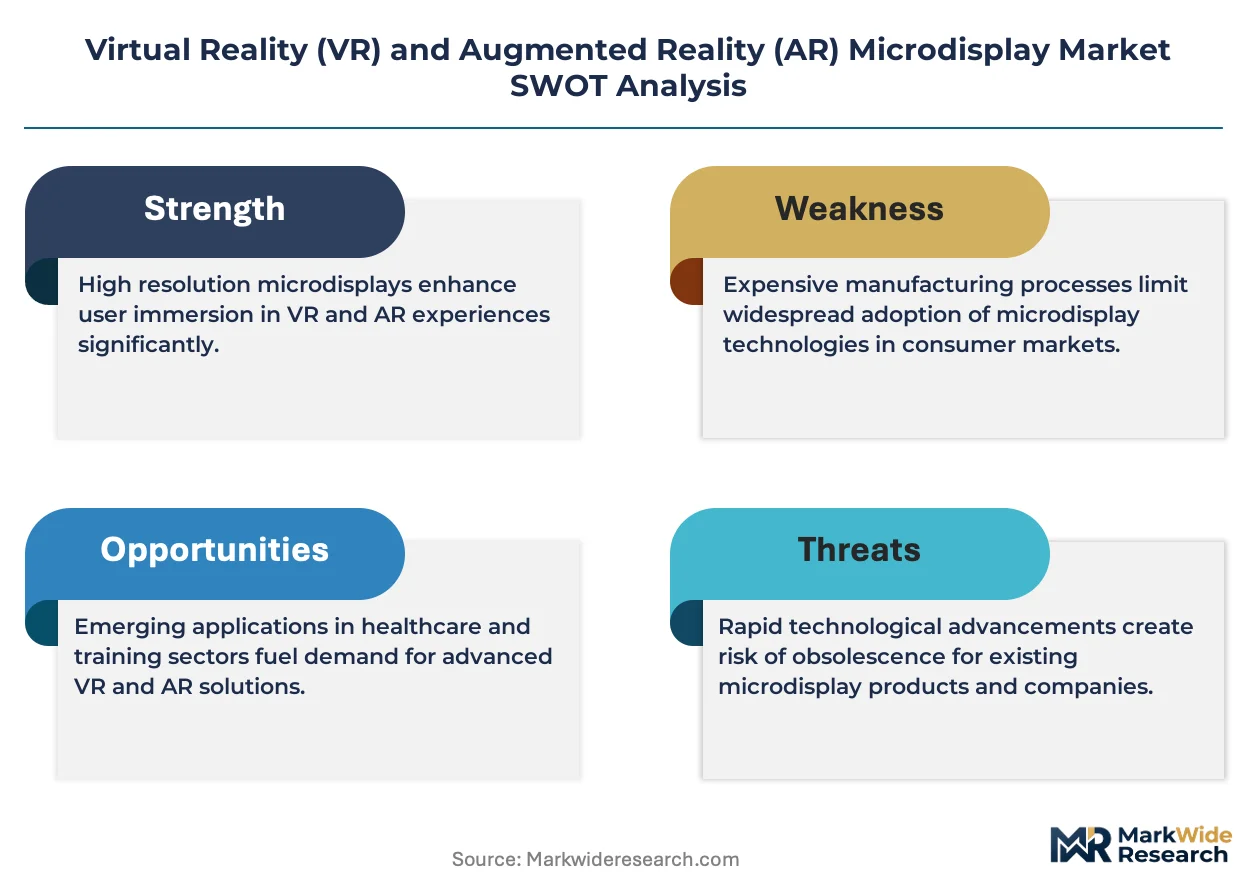
Market Restraints
- Red-Emitting Chip Efficiency Gap:MicroLED technology faces persistent technical limitations in red-emitting chip efficiency that constrain full-color microdisplay yields.
- Epitaxial Lift-Off Yield Volatility:Manufacturing process yields for MicroLED epitaxial lift-off remain unstable, creating input cost volatility and supply uncertainty.
- Shenzhen Supply Concentration:Heavy reliance on Shenzhen's display cluster for panel components creates geographic supply concentration risk for global AR device supply chains.
Strategic Opportunities
- Enterprise AR Optical See-Through:Transparent display architectures command margin concentration in enterprise AR where optical fidelity determines procurement decisions.
- Defense and Industrial Training:Lightning silicon backplane architectures anchor specialized applications in defense simulation and industrial skills training environments.
- Gallium Nitride MicroLED Convergence:Waveguide-coupled AR glasses are driving convergence between gallium nitride emitter technology and near-to-eye optical system design.
Industry Challenges
- Ophthalmic Safety Certification Timeline:Exposure-duration limits for near-eye displays remain under active scientific review, creating uncertainty in certification timelines for next-generation products.
- Multi-Jurisdiction Compliance Complexity:Stakeholders must simultaneously navigate FCC equipment authorization, EU Radio Equipment Directive SAR testing, and China's GB standards luminance limits.
- Semiconductor Lithography Capex Intensity:Manufacturing microdisplays on silicon wafers using sub-10 micrometer pixel pitch lithography requires substantial capital investment in fabrication infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Reality (VR) and Augmented Reality (AR) Microdisplay Market |
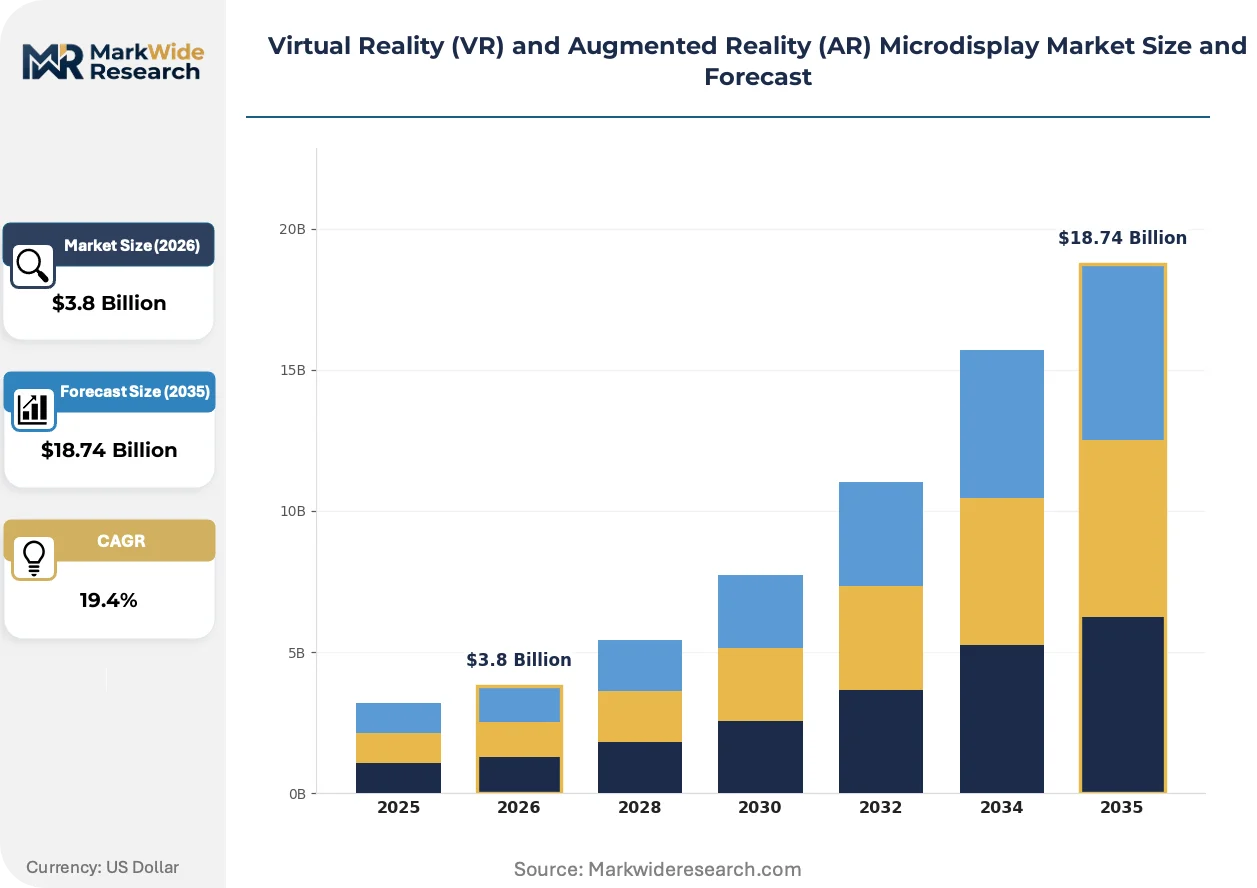
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $18.74 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, OLED, MicroLED, LCoS Technology: Near-to-Eye, Transparent, Reflective, Retinal Display Application: Gaming, Training, Simulation, Healthcare End User: Consumers, Enterprises, Medical Professionals, Researchers |
| Companies Covered | Kopin Corporation, eMagin, LG Display Co., Ltd., Sony Group Corporation, Seiko Epson Corporation, SeeYA Technology, JBD, Inc., Himax Technologies, Inc., MicroOLED, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Reality (VR) and Augmented Reality (AR) Microdisplay Market Trends and Innovations
Active reshaping of this market centers on three converging forces: semiconductor fabrication techniques borrowed from CMOS image sensor production, tightening multi-jurisdiction safety mandates for near-eye radiation exposure, and procurement pattern shifts among headset OEMs prioritizing immersive fidelity specifications.
MicroLED technology is miniaturizing pixel architectures through improved epitaxial lift-off processes and advancing red-emitting chip efficiency. Gaming headset OEMs are accelerating adoption timelines as 4K-per-eye specifications become baseline requirements. This compression is miniaturizing optical engine form factors while maintaining luminance thresholds exceeding 5,000 nits for see-through AR applications.
The EU AI Act classification requirements for biometric identification systems are extending to AR headsets with eye-tracking capabilities. Industrial consequence includes mandatory conformity assessment procedures before CE marking authorization. Enterprise AR deployments across German automotive and French aerospace manufacturing facilities face the most pronounced compliance timeline pressures.
Resolution-grade specification escalation is compressing legacy supply commitments as OEMs unwind contracts tied to lower-fidelity panels. Direct procurement relationships with silicon foundries are displacing traditional display distributor channels. This pattern is most visible in Shenzhen's domestic AR device ecosystem and among US-based gaming peripheral manufacturers.
Virtual Reality (VR) and Augmented Reality (AR) Microdisplay Market Segmentation
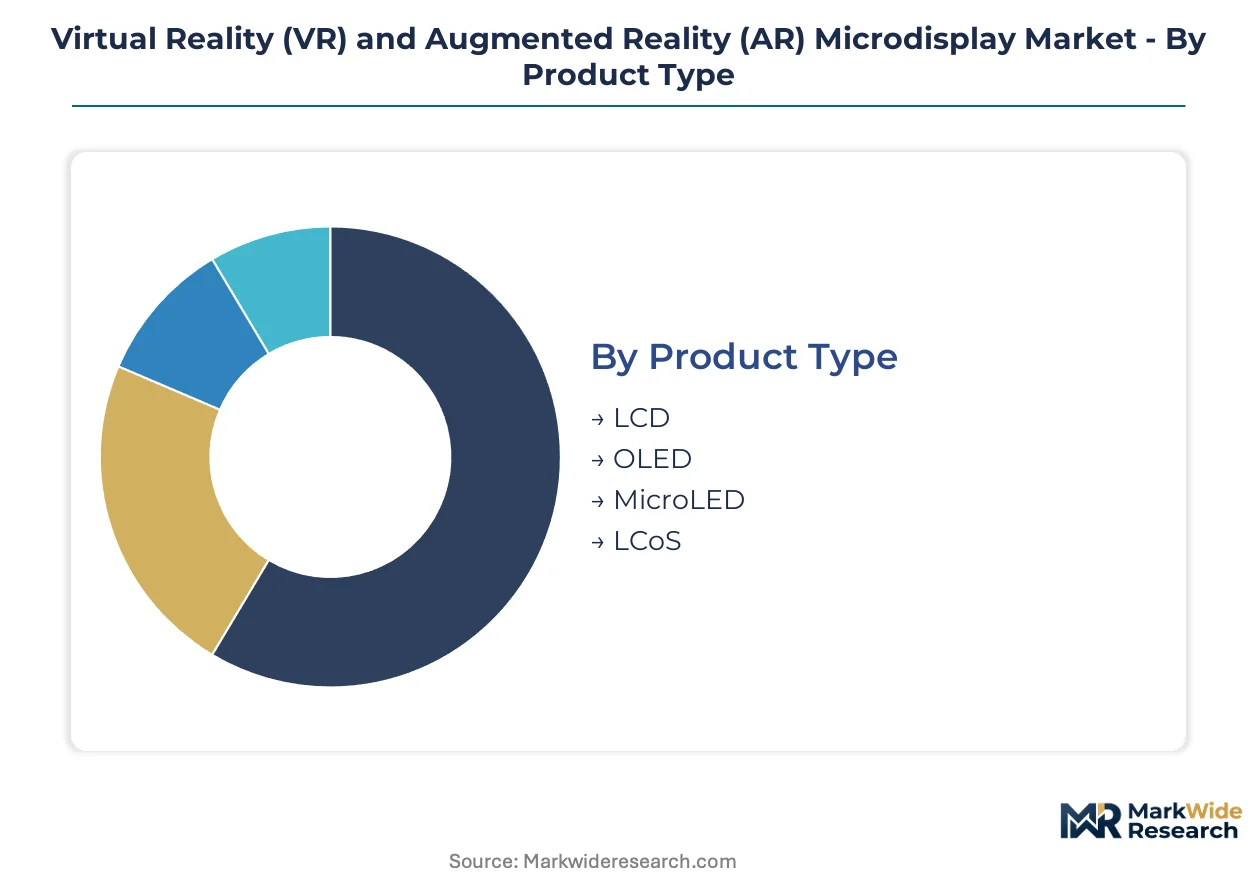
Microdisplay procurement decisions pivot on resolution-luminance tradeoffs, optical system integration requirements, and end-use safety certification pathways. Segmentation reveals where technology substitution pressures are highest and which specifications command procurement premiums across VR and AR device categories.
Product Type:
OLED and MicroLED segments face the most intense substitution pressure as MicroLED epitaxial lift-off yields improve and red-emitting chip efficiency advances.
- LCD:Transmissive liquid crystal architectures with external backlighting deliver cost-efficient panels for entry-tier VR headsets. Demand concentrates in Chinese domestic gaming peripheral manufacturing where GB standards luminance mandates accelerate panel design iterations.
- OLED:Self-emissive organic diode structures with sub-millisecond response times and deep black levels dominate premium VR headset specifications. Procurement from Sony Group Corporation's CMOS-integrated fabrication lines anchors supply for immersive fidelity-focused OEMs retooling toward 4K-per-eye baselines.
- MicroLED:Gallium nitride emitter arrays with luminance exceeding 5,000 nits enable waveguide-coupled AR glasses. Shenzhen's display cluster feeds both domestic production and export-bound manufacturing for international OEMs targeting see-through optical fidelity.
- LCoS:Reflective liquid crystal on silicon backplanes leverage mature semiconductor lithography for cost-sensitive near-to-eye applications. Demand clusters in industrial training simulators where Lightning silicon architectures anchor specialized procurement.
OLED retains volume leadership; MicroLED holds the steepest expansion curve.
Technology:
Cost tier stratification separates near-to-eye volume shipments from transparent display margin concentration in enterprise AR deployments.
- Near-to-Eye:Direct-view microdisplays mounted within centimeters of the pupil dominate shipment volumes across consumer VR headsets. FCC equipment authorization requirements for wireless-tethered headsets govern radio-frequency emissions from these architectures.
- Transparent:Optical see-through waveguide-coupled systems command procurement premiums where fidelity determines enterprise AR adoption decisions. EU AI Act classification for biometric eye-tracking extends conformity assessment pressures to German automotive and French aerospace manufacturing deployments.
- Reflective:LCoS-based illumination systems with polarized light management serve cost-optimized training and simulation environments. CE marking under the EU Radio Equipment Directive mandates SAR testing for European market access.
- Retinal Display:Laser-scanning direct-to-retina projection eliminates physical panel constraints for ultra-compact AR form factors. China's SAMR-administered blue-light hazard thresholds directly influence design specifications for domestic device makers.
Near-to-Eye dominates shipment volumes; Transparent commands the highest procurement premiums.
Application:
Customer type differentiation separates consumer gaming volume from enterprise and medical procurement cycles governed by distinct certification timelines.
- Gaming:Headset manufacturers serving this sector are expanding procurement of high-resolution microdisplays as immersive fidelity becomes a primary competitive differentiator. 4K-per-eye specifications are compressing legacy supply commitments as OEMs unwind lower-fidelity contracts.
- Training:Defense and industrial skills environments anchor demand for Lightning silicon backplane architectures with specialized durability requirements. Procurement runs through direct silicon foundry relationships displacing traditional display distributor channels.
- Simulation:High-fidelity visual reproduction for pilot and surgical training demands sub-10 micrometer pixel pitch lithography with substantial capital investment in fabrication infrastructure. Multi-jurisdiction compliance complexity shapes vendor selection across FCC, EU Radio Equipment Directive, and GB standards.
- Healthcare:Ophthalmic safety certification timelines remain uncertain as exposure-duration limits for near-eye displays undergo active scientific review. CE marking authorization faces the most pronounced compliance pressures for next-generation products with biometric identification capabilities.
Gaming anchors volume demand; Healthcare faces the most protracted certification pathways.
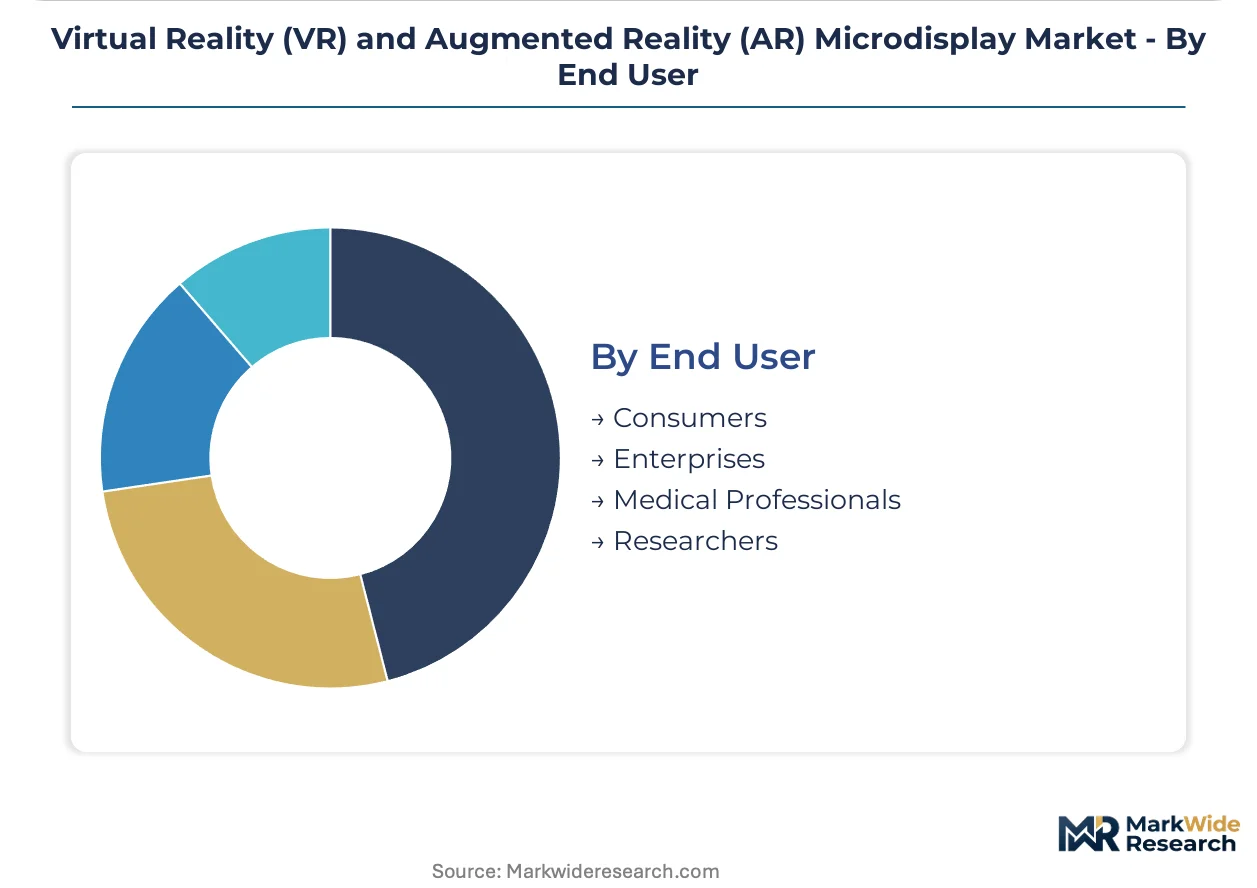
End User:
Supply concentration geography determines procurement channel structure, with Shenzhen's cluster feeding consumer and enterprise segments through distinct distribution pathways.
- Consumers:Gaming-focused headset purchasers drive resolution-grade specification escalation toward 4K-per-eye baselines. Shenzhen's concentrated panel component supply base feeds export-bound manufacturing for international OEMs.
- Enterprises:German automotive and French aerospace manufacturing facilities face pronounced EU AI Act compliance timeline pressures for AR deployments with eye-tracking capabilities. Transparent display architectures command margin concentration where optical fidelity determines procurement decisions.
- Medical Professionals:Surgical visualization and diagnostic applications demand luminance thresholds and blue-light hazard compliance under China's GB standards. Exposure-duration limits remain under active scientific review across jurisdictions.
- Researchers:Laboratory and development environments require specialized retinal display and reflective technologies for experimental optical systems. Procurement concentrates through direct relationships with gallium nitride MicroLED specialists.
Consumers drive volume scale; Enterprises concentrate margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's display cluster concentrates panel component supply for both domestic Chinese AR device production and export-bound manufacturing for international OEMs. This geographic concentration shapes procurement channel structures across consumer and enterprise segments. Regulatory fragmentation across the United States, European Union, and China creates multi-jurisdiction compliance complexity for microdisplay vendors.
United States
Gaming headset OEMs headquartered in California and Washington states drive resolution-grade specification escalation toward 4K-per-eye baselines. FCC equipment authorization rules govern radio-frequency emissions from wireless-tethered headsets, mandating pre-market testing for market access. The Pacific Northwest technology corridor anchors defense and industrial training procurement for Lightning silicon backplane architectures.
China
Shenzhen's concentrated panel component supply base feeds both domestic AR device production and export-bound manufacturing for international OEMs. SAMR-administered GB standards specify luminance limits and blue-light hazard thresholds that directly influence panel design specifications. The Pearl River Delta display cluster supplies gallium nitride MicroLED emitters to waveguide-coupled AR glasses manufacturers.
Germany
Automotive manufacturing facilities in Bavaria and Baden-Württemberg face pronounced EU AI Act compliance timeline pressures for AR deployments with eye-tracking capabilities. CE marking under the EU Radio Equipment Directive mandates SAR testing and interoperability standards for European market access. The Stuttgart-Munich industrial corridor concentrates enterprise AR procurement where optical see-through fidelity determines vendor selection.
Japan
CMOS image sensor fabrication infrastructure in the Kanto region enables OLED microdisplay production with integrated driver logic. METI industrial policy supports semiconductor lithography capital investment for sub-10 micrometer pixel pitch manufacturing. The Tokyo-Osaka technology corridor anchors supply relationships with immersive fidelity-focused VR headset OEMs retooling for premium specifications.
South Korea
Display panel manufacturing clusters in Gyeonggi Province supply high-resolution microdisplays for gaming and enterprise VR applications. MFDS ophthalmic safety guidelines influence exposure-duration limit specifications for near-eye display certification. The Seoul Capital Area concentrates OLED microdisplay procurement relationships with international headset manufacturers.
Virtual Reality (VR) and Augmented Reality (AR) Microdisplay Market Competitive Landscape
Concentration sits with diversified electronics conglomerates possessing captive semiconductor fabrication infrastructure. The vendor base spans three tiers: integrated conglomerates with CMOS sensor-to-display pipelines, specialized microdisplay foundries serving defense and industrial verticals, and emerging gallium nitride emitter specialists. Competitive dynamics center on backward integration into silicon wafer supply and direct procurement relationships displacing traditional display distributor channels.
Within the integrated conglomerate tier, Sony Group Corporation and LG Display Co., Ltd. exemplify players leveraging existing semiconductor lithography infrastructure for OLED microdisplay production. Kopin Corporation anchors the specialized foundry segment with its Lightning silicon backplane architecture for defense and industrial training applications. JBD, Inc. occupies a position among gallium nitride MicroLED specialists targeting waveguide-coupled AR glasses. Seiko Epson Corporation and Himax Technologies, Inc. represent diversified component suppliers with reflective and near-to-eye technology portfolios. eMagin, SeeYA Technology, and MicroOLED sit within the emerging specialist tier focused on high-resolution military and medical applications.
| Leading Market Players |
|---|
| Kopin Corporation |
| eMagin |
| LG Display Co., Ltd. |
| Sony Group Corporation |
| Seiko Epson Corporation |
| SeeYA Technology |
| JBD, Inc. |
| Himax Technologies, Inc. |
| MicroOLED |
| Others |
Pricing and Supply Chain Analysis
CE marking under the EU Radio Equipment Directive gates both supply qualification and price differentiation simultaneously, as SAR testing mandates and interoperability standards force panel vendors into tiered certification investments that stratify procurement premiums across European-bound and non-certified product streams.
Pricing Analysis
CE marking dictates the pricing tier structure across the European market access pathway, with SAR testing and interoperability standards separating premium-certified panels from standard-grade alternatives. Price differentiation rests on certification grade and volume scale, with gaming headset OEMs absorbing higher per-unit costs for 4K-per-eye baselines while industrial training buyers negotiate long-term offtake contracts. Cost compression in entry-tier LCD segments is intensifying because Shenzhen cluster competition drives yield optimization pressures. Gaming peripheral manufacturers exhibit highest price sensitivity; defense procurement committees demonstrate lowest sensitivity due to durability specifications.
Supply Chain Analysis
Japan and South Korea anchor wafer fabrication for CMOS-integrated OLED microdisplays, while China's Pearl River Delta concentrates gallium nitride MicroLED emitter production. Raw material dependencies draw from silicon ingot supply, rare-earth dopants for phosphor conversion, and specialized photoresist chemistries. Single-source vulnerability concentrates in epitaxial lift-off equipment providers. Distribution runs through direct silicon foundry relationships displacing traditional display distributor channels, with Shenzhen's cluster feeding both domestic production and export-bound manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gaming headset OEM consolidation into three dominant platform ecosystems has shifted procurement leverage toward buyers, compressing supplier margins as direct foundry relationships displace intermediary channels.
For Market Incumbents: Fortify captive semiconductor lithography infrastructure against MicroLED substitution threats by accelerating red-emitting chip efficiency R&D and securing exclusive epitaxial lift-off equipment allocations. Deepen backward integration into silicon wafer supply through long-term offtake agreements with Kanto-region fabrication partners. Channel control through direct OEM procurement relationships anchors margin defense against distributor displacement. For New Entrants and Emerging Players: Enterprise AR optical see-through service layers present incumbent underservice gaps, with German automotive and French aerospace manufacturing facilities facing acute EU AI Act compliance timeline pressures. Waveguide-coupled AR glasses for industrial training applications represent the most penetrable segment. Go-to-market execution should leverage gallium nitride MicroLED specialization through direct silicon foundry partnerships bypassing traditional distribution. For Investors and Strategic Acquirers: EU AI Act classification requirements for biometric eye-tracking systems reshape the acquisition landscape, elevating conformity assessment capability as a differentiation anchor. Long-term viability favors vertically integrated specialists with captive CMOS sensor-to-display pipelines and multi-jurisdiction certification infrastructure. The signal to monitor is ophthalmic safety standard finalization timelines across FDA, EMA, and SAMR jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Wafer Supply | Captive wafer supply from Japan and South Korea secures sub-10 micrometer pixel pitch fabrication capacity against epitaxial lift-off yield volatility. |
| Multi-Jurisdiction Certification Investment | Simultaneous FCC, CE marking, and GB standards compliance opens procurement channels across US gaming, European automotive, and Chinese domestic markets. |
| Direct Foundry Relationship Establishment | Bypassing Shenzhen distributor channels captures margin compression from gaming OEM procurement consolidation into platform ecosystems. |
| Red-Emitting Chip Efficiency R&D Scale-Up | Closing the MicroLED efficiency gap unlocks full-color microdisplay yields for waveguide-coupled AR glasses targeting enterprise optical see-through applications. |
| Defense and Industrial Training Vertical Specialization | Lightning silicon backplane architectures anchor durable procurement relationships with simulation and skills training facilities requiring specialized durability specifications. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with display technology executives, procurement leads at gaming headset OEMs, regulatory affairs specialists, and silicon foundry operations directors; and secondary validation through SEC filings, SAMR GB standards documentation, EU Radio Equipment Directive compliance databases, and hyperscaler VR hardware capex disclosures. Bottom-up panel shipment aggregation and top-down OEM procurement budget triangulation anchored volume estimates.
Across the projection horizon, the analytical framework modeled technology substitution dynamics between OLED and MicroLED architectures, resolution-grade specification escalation pathways, and end-use segmentation across gaming, training, simulation, and healthcare applications. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs incorporated epitaxial lift-off yield improvement curves and ophthalmic safety standard evolution timelines.
Underlying assumptions cover MicroLED red-emitting chip efficiency advancement, Shenzhen cluster supply stability, and multi-jurisdiction regulatory harmonization, with deviation risk concentrated in ophthalmic safety certification timeline delays and semiconductor lithography capital expenditure cycles. Recalibration cycles align with material shifts in SAMR luminance mandate revisions, EU AI Act implementation guidance, and FCC equipment authorization rule updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Learning Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Collaboration Platform Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Mirror Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented and Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Location-Based Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality for Consumer Market
Virtual Reality (VR) and Augmented Reality (AR)
Global AR and VR Smart Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Mobile Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Industrial AR Platforms Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
AR-VR Head Display Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
South Korea Metaverse Market