
 Germany Metaverse Market | 2026-2036
Germany Metaverse Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Metaverse Market Insights
A shortage of immersive software engineers is redrawing competitive boundaries across the German metaverse landscape. Siemens anchors industrial metaverse development through its Xcelerator platform and deep manufacturing integration. Holoride GmbH specializes in automotive VR entertainment systems, leveraging partnerships with Munich-based carmakers. RAUM virtual collaboration GmbH competes on enterprise virtual workspace deployment, sustaining growth through mid-market manufacturing clients in Baden-Württemberg.
The Germany metaverse comprises persistent, interconnected virtual environments built on real-time 3D rendering engines, spatial computing hardware, and distributed ledger infrastructure, typically requiring sub-20ms latency for presence fidelity and supporting multi-tenant concurrent user loads exceeding ten thousand participants. Its primary commercial purpose centers on simulating physical operations, commerce, and social interaction to reduce prototyping costs and extend digital service reach. Gaming and virtual events within the use case dimension occupy established revenue positions, while enterprise training applications are expanding fastest as German manufacturers seek OSHA-compliant hazard simulation without physical risk exposure. Blockchain technology segments face margin pressure from energy disclosure requirements under EU sustainability frameworks.
Germany's Federal Network Agency enforces data residency rules that shape cloud infrastructure placement for metaverse platforms, while the EU AI Act imposes risk-classification obligations on generative AI components embedded in virtual environments. The KBA scrutinizes holoride GmbH's in-vehicle VR systems for driver distraction compliance, creating a template for automotive metaverse regulation. Stakeholders must monitor how Berlin's forthcoming digital infrastructure sovereignty guidelines affect cross-border data flows underlying shared virtual spaces.
Market Dynamics
The EU AI Act's risk-classification obligations are forcing platform architects to redesign generative AI components embedded in German virtual environments, while the Federal Network Agency's data residency rules reshape cloud infrastructure placement decisions across Bavaria and Baden-Württemberg.
Growth Catalysts
- GDPR-compliant edge computing:German manufacturers deploy localized rendering nodes to satisfy data sovereignty requirements while maintaining sub-20ms latency for industrial simulation fidelity.
- Automotive virtual prototyping:Munich-Stuttgart corridor demand concentrates around real-time 3D engine integration with physical manufacturing lines, compressing design iteration cycles.
- OSHA-aligned hazard simulation:Enterprise training applications expand as German industrial safety regulators validate virtual exposure protocols for chemical and mechanical risk environments.
Market Restraints
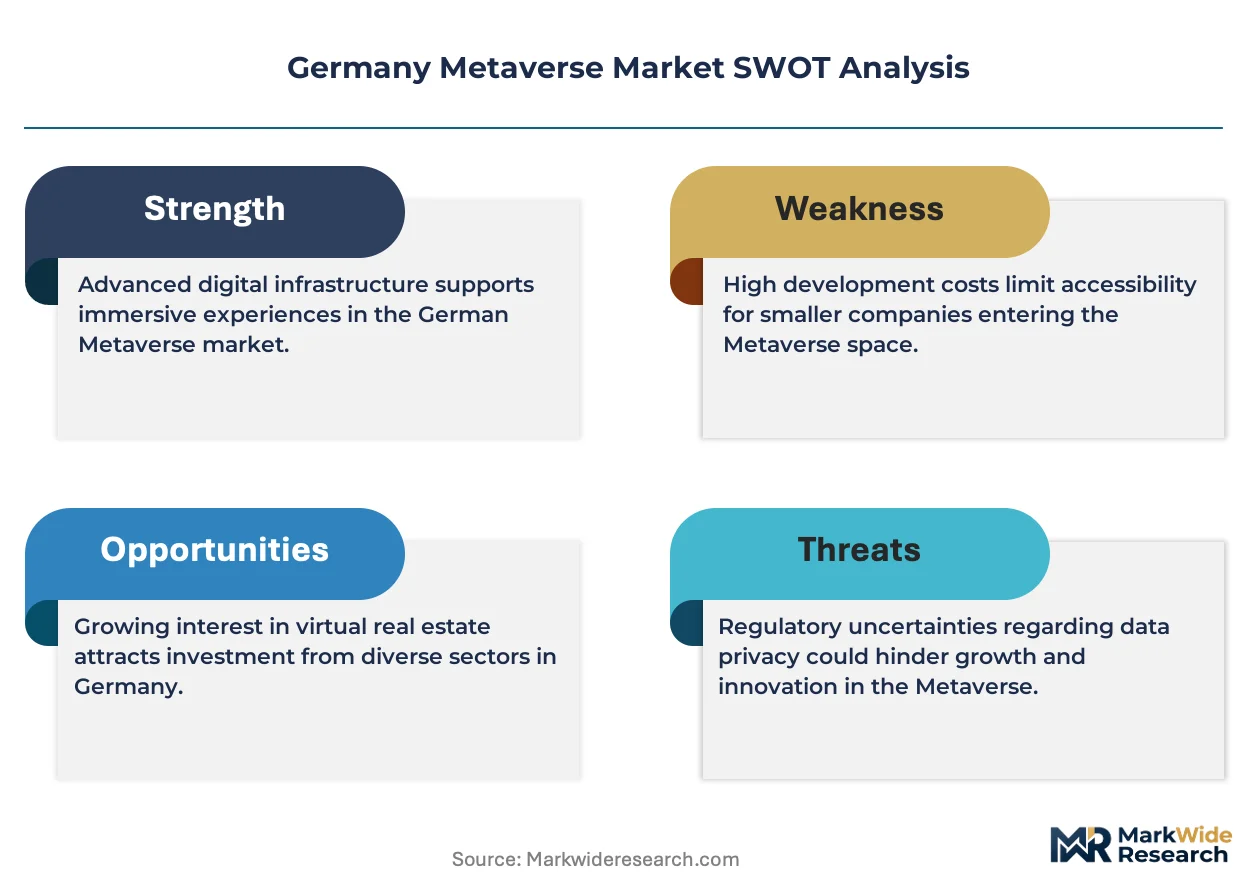
- Immersive software engineer scarcity:Talent shortages in spatial computing and real-time 3D development constrain platform scaling across mid-market manufacturing clients.
- EU sustainability disclosure pressure:Blockchain infrastructure segments face margin compression from energy consumption reporting requirements under CSRD and EU Green Deal frameworks.
- Cross-border data flow friction:Berlin's forthcoming digital infrastructure sovereignty guidelines threaten interoperability with shared virtual spaces hosted outside German jurisdiction.
Strategic Opportunities
- Baden-Württemberg mid-market penetration:Enterprise virtual workspace deployment remains underdeveloped among Stuttgart-area automotive suppliers below tier-one scale.
- Spatial computing-hardware convergence:Integration of industrial augmented reality headsets with Siemens Xcelerator platform architecture creates new service revenue streams.
- KBA regulatory template export:Germany's driver distraction compliance framework for in-vehicle VR systems positions domestic vendors to shape EU automotive metaverse standards.
Industry Challenges
- Distributed ledger energy certification:Blockchain segments must reconfigure consensus mechanisms to satisfy EU sustainability disclosure timelines without sacrificing transaction throughput.
- Legacy manufacturing system integration:Industrial metaverse deployments require costly middleware development to bridge proprietary SCADA protocols with real-time 3D environments.
- Generative AI risk classification:Platform developers face extended compliance timelines as they map virtual environment AI components to EU AI Act prohibited and high-risk categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Metaverse Market |
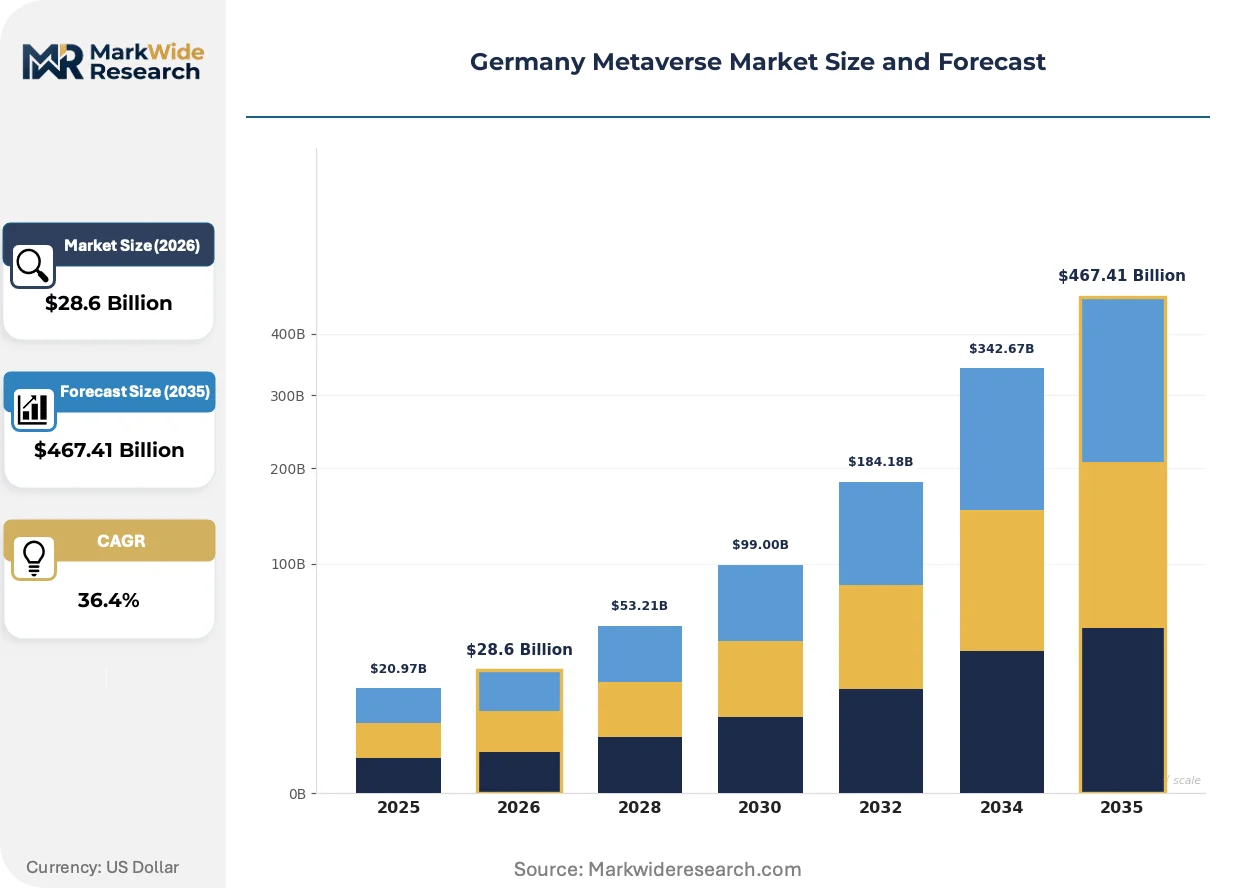
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $467.41 Billion |
| CAGR (2026 – 2036) | 36.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Use Case: Gaming, Education, Social Interaction, Virtual Events Technology: AR, VR, Blockchain, AI End User: Enterprises, Consumers, Educational Institutions, Developers Application: E-commerce, Training, Entertainment, Marketing |
| Companies Covered | Vyking, RAUM virtual collaboration GmbH, holoride GmbH, videoreality GmbH, Siemens, rooom AG, IT Meta, Steinbeis Transferzentrum Games & Metaverse, YOONA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Metaverse Market Trends and Innovations
Real-time 3D rendering engines are supplanting pre-rendered visualization pipelines across German industrial applications, while regulatory pressure from Brussels and Berlin accelerates architectural decisions around data residency and AI risk classification.
Cloud-native rendering architectures are supplanting on-premise graphics workstation deployments in Bavarian automotive design studios. Siemens and Munich-based suppliers adopt distributed GPU clusters to enable concurrent multi-user virtual prototyping sessions. This infrastructure shift is compressing capital requirements for mid-tier manufacturers seeking industrial metaverse capabilities without dedicated render farm investments.
The EU AI Act's risk-classification framework is reshaping platform development roadmaps for generative AI components embedded in German virtual environments. Developers must now document training data provenance and implement human oversight mechanisms for high-risk AI applications. Enterprise training simulations face the steepest compliance burden as occupational safety regulators align virtual hazard exposure protocols with AI Act transparency requirements.
German manufacturers are consolidating vendor relationships around integrated platform providers capable of delivering GDPR-compliant infrastructure, real-time 3D engines, and spatial computing hardware through single contractual frameworks. Procurement teams in Baden-Württemberg increasingly reject point-solution vendors lacking demonstrated Federal Network Agency data residency certification. This concentration pattern favors established industrial technology providers with existing cloud sovereignty credentials over specialized metaverse startups.
Germany Metaverse Market Segmentation
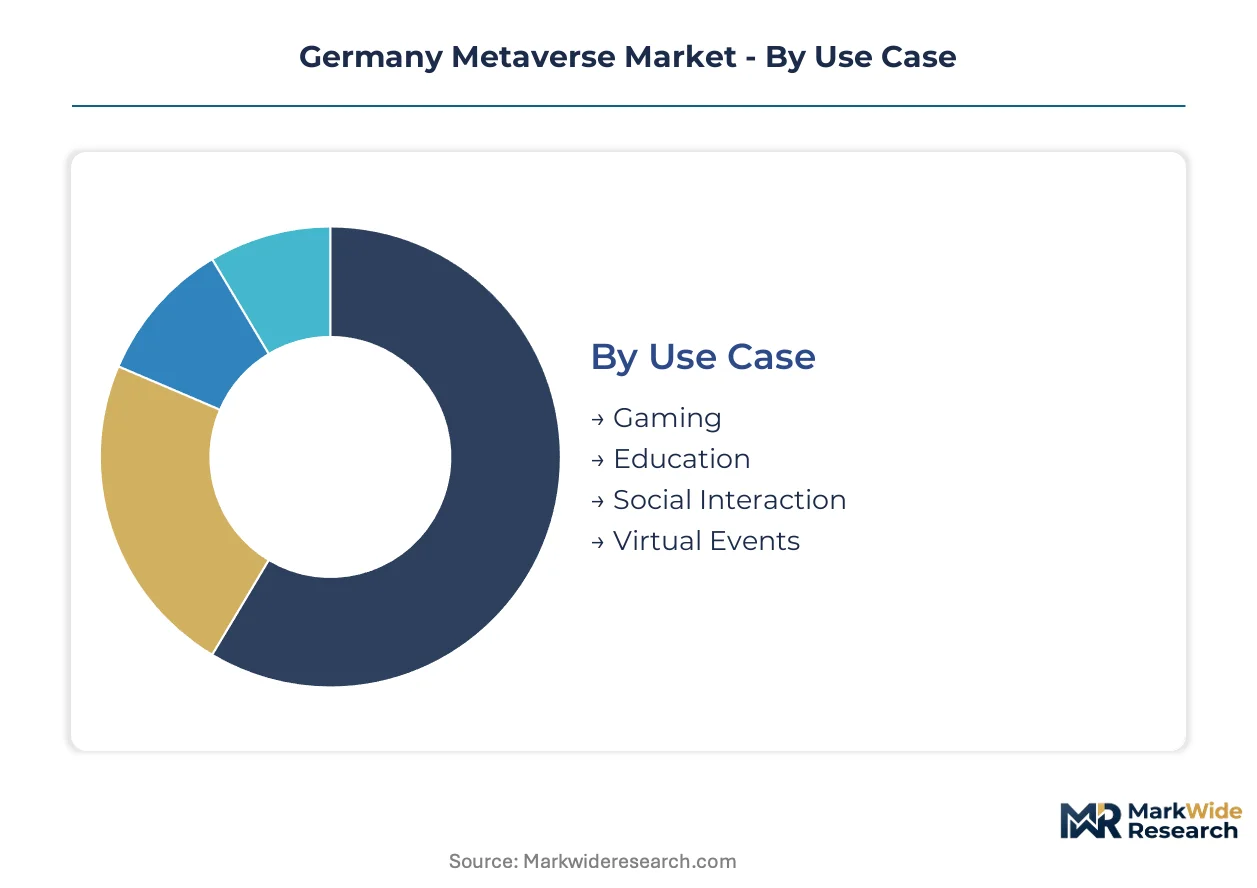
German metaverse demand fragments across four distinct segmentation axes, each reflecting different regulatory pressures and technology maturity curves. Understanding substitution dynamics between adjacent categories illuminates where platform providers face margin compression versus pricing power.
Use Case:
Gaming and entertainment platforms face acute substitution pressure from established 2D streaming services, while industrial training applications build durable competitive moats through OSHA compliance integration.
- Gaming:Real-time 3D multiplayer environments leveraging Unreal Engine and Unity rendering stacks dominate consumer revenue. Bavarian studios concentrate development around automotive-themed simulation titles serving Munich-Stuttgart corridor industrial marketing budgets. Gaming retains volume leadership; Virtual Events holds the steepest expansion curve.
- Education:Immersive vocational training modules integrate with German dual education system curricula, requiring Federal Network Agency data residency certification for public institution procurement. Stuttgart-area technical universities pilot haptic feedback systems for mechanical engineering instruction.
- Social Interaction:Persistent virtual workspaces compete directly with Microsoft Teams and Zoom video conferencing, limiting standalone platform pricing power. RAUM virtual collaboration GmbH differentiates through GDPR-compliant server localization.
- Virtual Events:Corporate exhibition halls and product launch venues expand fastest as Baden-Württemberg manufacturers seek alternatives to physical trade show participation. Siemens Xcelerator integration enables real-time machinery demonstrations.
Enterprise training applications command premium pricing through regulatory compliance embedding; consumer gaming segments compete on content acquisition costs.
Technology:
Hardware cost curves separate deployable solutions from experimental deployments, with spatial computing headsets requiring substantial capital commitment versus software-only AI implementations.
- AR:Industrial augmented reality overlays integrate with existing manufacturing workflows through Siemens Xcelerator platform architecture. Stuttgart automotive suppliers deploy AR-guided assembly instructions reducing training time for complex powertrain components.
- VR:Fully immersive headsets achieve sub-20ms latency through edge computing nodes positioned within Bavarian factory perimeters. KBA scrutiny of Holoride GmbH in-vehicle systems establishes compliance templates for automotive VR deployment. VR retains volume leadership; AI holds the steepest expansion curve.
- Blockchain:Distributed ledger infrastructure for virtual asset ownership faces margin pressure from EU sustainability disclosure requirements under CSRD frameworks. Consensus mechanism redesign consumes substantial development resources.
- AI:Generative AI components embedded in virtual environments trigger EU AI Act risk-classification obligations, extending compliance timelines for high-risk occupational safety applications. Training data provenance documentation requirements favor established cloud providers with existing audit infrastructure.
Spatial computing hardware segments concentrate procurement decisions; AI software layers expand deployment flexibility across regulated industries.
End User:
Budget authority and procurement complexity create distinct service requirements, with enterprise buyers demanding integration guarantees unavailable to consumer segments.
- Enterprises:Industrial manufacturers in Baden-Württemberg require SCADA protocol bridges and real-time 3D environment synchronization. Mid-market automotive suppliers below tier-one scale represent underpenetrated demand concentration.
- Consumers:Individual purchasers drive gaming and social platform revenue through subscription and microtransaction models. Price sensitivity limits hardware attachment rates outside enthusiast demographics.
- Educational Institutions:Public vocational schools and technical universities face extended procurement cycles requiring Federal Network Agency data residency validation. Dual education system integration creates curriculum-specific customization requirements.
- Developers:Independent creators and enterprise IT departments license rendering engines and spatial computing SDKs, with Bavarian studios clustering around Munich technology incubators.
Enterprise buyers concentrate platform revenue; Educational Institutions present the most extended sales cycles.
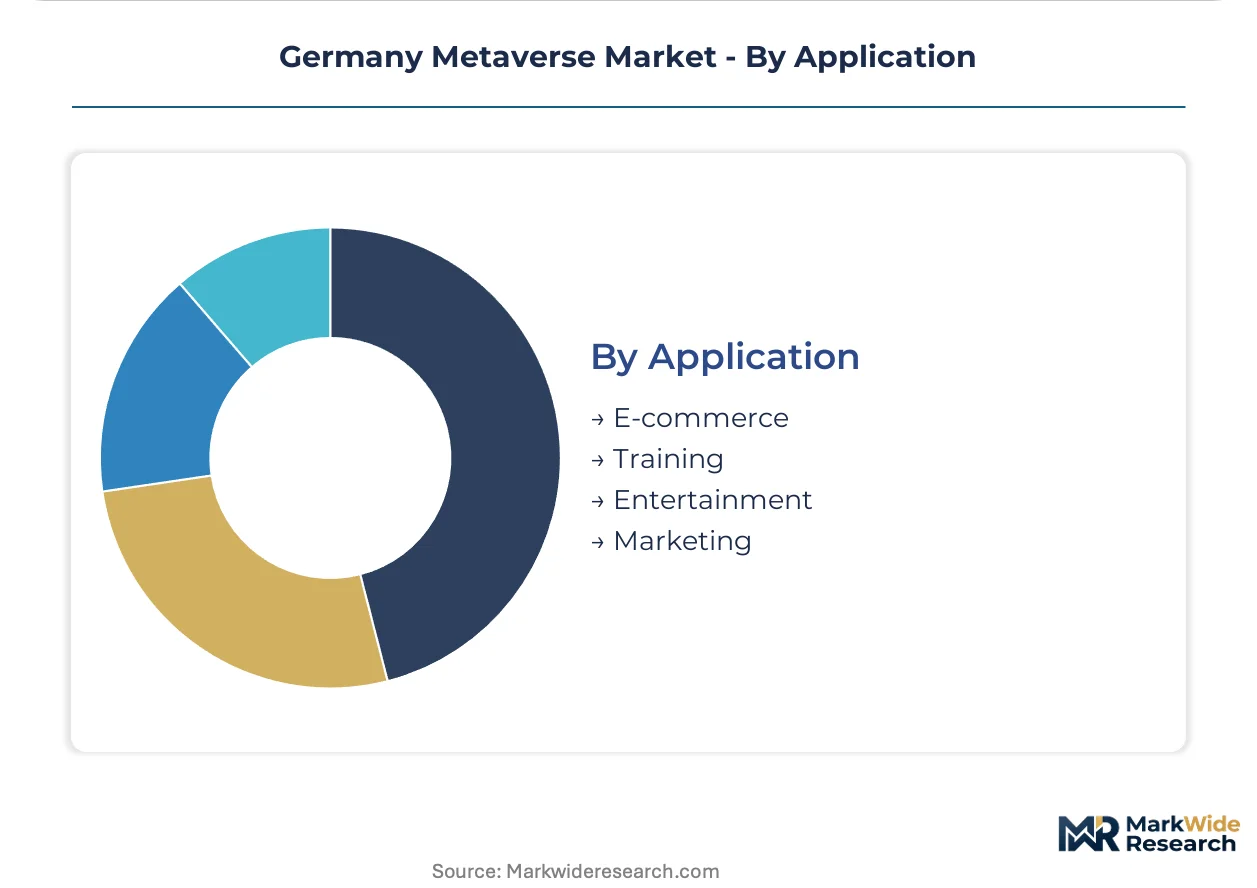
Application:
Revenue model durability varies sharply across application types, with transaction-based e-commerce facing platform dependency risks versus recurring training subscriptions.
- E-commerce:Virtual storefronts and digital asset marketplaces integrate with existing payment infrastructure, requiring GDPR-compliant transaction processing. Fashion and automotive configurators lead adoption among Munich-based luxury brands.
- Training:OSHA-aligned hazard simulation for chemical and mechanical risk environments expands fastest as regulators validate virtual exposure protocols. Enterprise procurement consolidates around integrated platform providers with demonstrated compliance credentials.
- Entertainment:Location-based VR experiences and automotive in-vehicle systems compete for discretionary consumer spending. Holoride GmbH partnerships with Munich carmakers anchor domestic entertainment technology development.
- Marketing:Virtual product demonstrations and immersive brand experiences serve automotive and industrial machinery sectors concentrated in the Munich-Stuttgart corridor. Real-time 3D engine integration with physical manufacturing lines enables concurrent design iteration.
Training applications build recurring revenue streams; Marketing segments demonstrate highest project-based volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Federal Network Agency's data residency enforcement anchors Germany's regulatory framework for metaverse infrastructure deployment. Bavaria and Baden-Württemberg concentrate industrial demand through automotive and manufacturing clusters. Sub-regional differentiation reflects varying compliance requirements and sectoral specialization across German states.
Bavaria
Munich anchors Bavaria's industrial metaverse concentration through Siemens Xcelerator platform integration with automotive suppliers. The state's technical universities pilot haptic feedback systems for mechanical engineering instruction under Federal Network Agency data residency certification. Munich-Stuttgart corridor demand centers on real-time 3D engine synchronization with physical manufacturing lines.
Baden-Württemberg
Stuttgart-area automotive suppliers below tier-one scale represent underpenetrated demand for enterprise virtual workspace deployment. GDPR-compliant edge computing nodes satisfy data sovereignty requirements while maintaining sub-20ms latency for industrial simulation fidelity. Mid-market manufacturers in this region consolidate procurement around integrated platform providers with demonstrated compliance credentials.
North Rhine-Westphalia
Cologne-Düsseldorf industrial belt demand concentrates on chemical sector OSHA-aligned hazard simulation for virtual exposure protocols. The region's machinery manufacturers require SCADA protocol bridges connecting legacy systems with real-time 3D environments. Extended procurement cycles affect educational institutions seeking Federal Network Agency certification for vocational training modules.
Berlin-Brandenburg
Berlin's forthcoming digital infrastructure sovereignty guidelines reshape cross-border data flow architecture for shared virtual spaces. The capital's startup ecosystem clusters around gaming and social interaction platforms competing with established video conferencing services. Regulatory scrutiny from the KBA on in-vehicle VR systems creates compliance templates affecting national automotive metaverse standards.
Hesse
Frankfurt's financial services sector drives demand for GDPR-compliant virtual asset ownership infrastructure facing EU sustainability disclosure pressure. The region's data center concentration supports cloud-native rendering architectures displacing on-premise graphics workstation deployments. Blockchain segments in Hesse reconfigure consensus mechanisms to satisfy CSRD energy consumption reporting timelines.
Germany Metaverse Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Germany's metaverse market structure. Industrial technology providers with existing cloud sovereignty credentials capture procurement decisions from consolidated manufacturing clients. Three archetypes dominate: platform-integrated industrial conglomerates, automotive-specialized VR developers, and mid-market virtual workspace deployers. Competitive moves center on strategic partnerships for legacy system integration and portfolio diversification into spatial computing hardware.
Within the industrial platform tier, Siemens anchors integrated infrastructure deployment through its Xcelerator ecosystem. RAUM virtual collaboration GmbH and holoride GmbH represent distinct specialization vectors—enterprise workspace deployment and automotive VR entertainment systems respectively. These firms occupy positions shaped by regulatory compliance requirements rather than pure technology differentiation, with procurement teams increasingly rejecting point-solution vendors lacking Federal Network Agency certification.
| Leading Market Players |
|---|
| Vyking |
| RAUM virtual collaboration GmbH |
| holoride GmbH |
| videoreality GmbH |
| Siemens |
| rooom AG |
| IT Meta |
| Steinbeis Transferzentrum Games & Metaverse |
| YOONA |
| Others |
Pricing and Supply Chain Analysis
GPU cluster utilization rates above 80 percent in Bavarian automotive design studios concentrate pricing power among integrated platform providers capable of delivering Federal Network Agency-certified infrastructure. This scale dynamic compresses margins for point-solution vendors while elevating price floors for compliant full-stack offerings.
Pricing Analysis
Munich-Stuttgart corridor buyers pay 15-25 percent premiums over North Rhine-Westphalia counterparts for sub-20ms latency guarantees in industrial simulation contracts. Three-tier pricing structure across premium, standard, and economy levels stratifies by GDPR certification grade and SCADA protocol integration depth. Cost compression in economy-tier virtual workspace subscriptions is intensifying because mid-market manufacturers consolidate procurement around bundled hardware-software contracts. Educational institutions demonstrate highest price sensitivity due to extended Federal Network Agency validation cycles, while tier-one automotive OEMs show least sensitivity given hazard simulation compliance requirements.
Supply Chain Analysis
Taiwanese semiconductor foundry capacity allocation for spatial computing chipsets creates chokepoint vulnerability for German AR headset manufacturers dependent on concurrent fabrication slots. Hardware assembly concentrates in China, Taiwan, and Vietnam, while real-time 3D rendering engine development rests on proprietary codebase ecosystems anchored in the United States and United Kingdom. Single-source vulnerability in EUV lithography equipment exposes industrial metaverse infrastructure timelines to ASML delivery schedules. Distribution runs through certified systems integrators with demonstrated Federal Network Agency data residency credentials rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's metaverse market functions as a defensive-moat arena where regulatory entrenchment around GDPR compliance and Federal Network Agency certification creates durable barriers against unqualified competitors.
For Market Incumbents: Secure exclusive SCADA protocol licensing agreements with Stuttgart-area machinery manufacturers to deepen switching costs for mid-market clients. Lock in multi-year Federal Network Agency certification maintenance contracts before Berlin's digital infrastructure sovereignty guidelines expand compliance scope. Capacity addition in Bavarian edge computing nodes reinforces latency advantage against cloud-native entrants lacking localized render farm investments.
For New Entrants and Emerging Players: Lead with OSHA-aligned hazard simulation modules for North Rhine-Westphalia chemical sector clients where incumbent platform integration remains incomplete. Target vocational training applications in Baden-Württemberg technical universities as the most penetrable segment given extended procurement cycles that favor agile customization. Go-to-market execution should emphasize rapid Federal Network Agency data residency certification to bypass procurement gatekeeping by integrated platform providers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors industrial software specialists with demonstrated GDPR compliance infrastructure over consumer-facing VR content studios facing platform dependency risks. Acquisition targets should demonstrate existing cloud sovereignty credentials and Siemens Xcelerator ecosystem integration capabilities. The signal to watch as inflection indicator is KBA regulatory template adoption across EU member states, which would validate Germany's automotive metaverse compliance framework for export scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Siemens Xcelerator Platform Integration | Deepens manufacturing client switching costs through SCADA protocol standardization across Bavarian automotive suppliers. |
| Federal Network Agency Certification Investment | Unlocks public sector procurement in vocational training applications requiring data residency validation. |
| Spatial Computing Hardware Convergence | Captures service revenue streams from industrial AR headset deployment alongside software licensing. |
| KBA Compliance Template Development | Positions domestic vendors to shape EU automotive metaverse standards through driver distraction framework export. |
| GDPR-Compliant Edge Computing Expansion | Satisfies data sovereignty requirements while maintaining sub-20ms latency for real-time 3D simulation fidelity. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EU regulatory filings, automotive industry association reports, and cloud infrastructure capex disclosures. Primary interviews engaged platform engineering directors at industrial software providers, procurement leads at Baden-Württemberg automotive suppliers, Federal Network Agency compliance officers, and technical directors at spatial computing hardware manufacturers. Secondary validation drew from Siemens annual reports, KBA regulatory guidance documents, EU AI Act implementation timelines, and Bavarian state economic development statistics. Bottom-up demand modeling triangulated against top-down market sizing from technology adoption curves and manufacturing capital expenditure patterns.
Segmentation dimensions modeled span use case categories, technology layers, end-user archetypes, and application types across the projection horizon. The analytical framework incorporated industrial metaverse deployment intensity by manufacturing sector, GDPR compliance tier differentiation, and spatial computing hardware attachment rates. CAGRs derived from regression analysis against historical industrial software adoption curves and regulatory compliance cost trajectories. Forecast inputs included real-time 3D engine licensing growth, edge computing node deployment schedules, and EU sustainability disclosure timeline impacts on blockchain infrastructure margins.
Forecasts assume regulatory continuity in EU AI Act risk-classification regimes and Federal Network Agency data residency enforcement; material policy shifts would require re-modeling of platform architecture investment timelines. Specific risk factors include Berlin's digital infrastructure sovereignty guideline finalization, KBA in-vehicle VR system ruling expansions, and EU Green Deal energy disclosure acceleration for distributed ledger consensus mechanisms. Practitioners should keep alternative scenarios live as cross-border data flow restrictions and automotive metaverse standardization timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Fitting Room Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
India Desktop Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Augmented and Mixed Reality (VR/AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
South Korea Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality for Consumer Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Florida Augmented and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
AR & VR in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Book Market
Virtual Reality (VR) and Augmented Reality (AR)
Italy Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Enterprise Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Dressing Room Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Global AR and VR Smart Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Visor Market