
 Asia Pacific Electric Vehicle Battery Anode Market | 2026-2036
Asia Pacific Electric Vehicle Battery Anode Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Electric Vehicle Battery Anode Market Insights
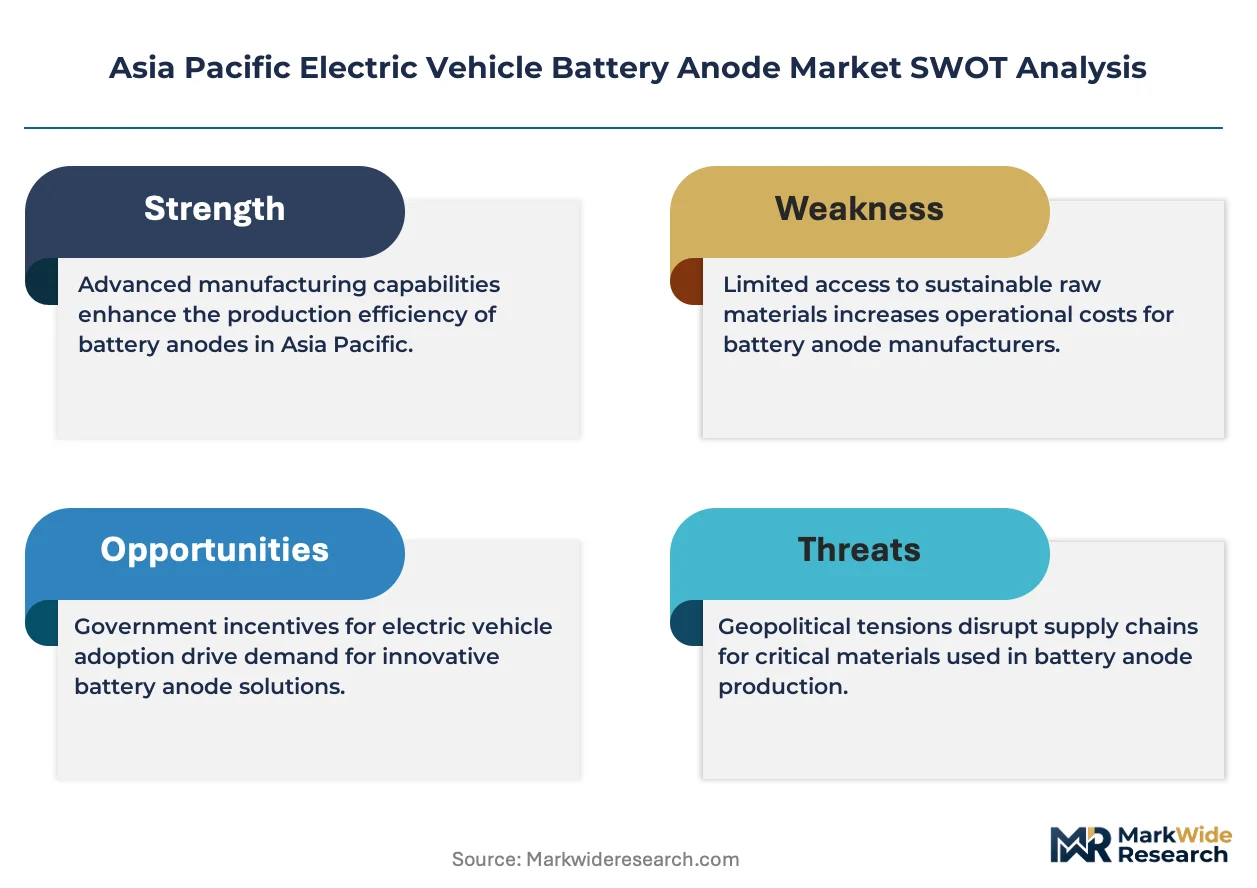
The performance gap between synthetic graphite anodes for mass-market electric vehicles and silicon-composite formulations for premium platforms is broadening. BTR New Material Group Co., Ltd. leverages its integrated mine-to-anode pipeline to dominate graphite supply for Chinese OEMs. Panasonic Holdings Corporation anchors its position through proprietary silicon-alloy R&D partnerships with Japanese automakers. POSCO Future M competes via captive needle coke supply from its steelmaking operations in South Korea.
The Asia Pacific Electric Vehicle Battery Anode comprises the negative electrode material in lithium-ion cells, typically structured from carbonaceous matrices with intercalation capacities near 372 mAh/g for graphite and exceeding 3,500 mAh/g for silicon composites, manufactured through calcination, milling, and surface coating processes to enable reversible lithium-ion storage during charge-discharge cycling. Graphite material type occupies the dominant share due to established supply chains and cost structures, though silicon blends represent the fastest-expanding category as energy density targets tighten. Battery manufacturers as an end-user segment control the deepest margin pools through direct long-term offtake agreements with anode producers, while OEMs increasingly bypass intermediaries through backward integration into cell manufacturing.
China's MIIT enforces GB standards for battery material traceability and carbon intensity disclosure, while Japan's METI coordinates domestic anode supply security through critical mineral stockpiling directives. South Korea's MFDS and KATS align with EU REACH-equivalent substance restrictions for exported cells, tightening purity thresholds for anode active materials. Stakeholders must monitor how China's SAMR implements dual carbon compliance deadlines for anode production facilities and whether Japan expands METI funding for domestic silicon anode pilot lines.
Market Dynamics
Passenger vehicle electrification across China, Japan, and South Korea is compressing anode procurement cycles and forcing material suppliers to synchronize capacity expansion with gigafactory ramp schedules. This demand pull is restructuring supply relationships around direct long-term offtake agreements rather than spot-market transactions.
Growth Catalysts
- China's dual carbon goals:National decarbonization mandates under MIIT are accelerating graphite anode capacity expansion in Jiangsu and Zhejiang provinces to serve domestic OEM electrification targets.
- Silicon-composite R&D:Japanese automakers are funding pilot production lines for silicon-alloy anodes to achieve energy density thresholds above 300 Wh/kg in premium battery platforms.
- Korean needle coke integration:Steelmaking byproduct streams from POSCO's Pohang operations are securing captive precursor supply for synthetic graphite anode manufacturing.
Market Restraints
- Petroleum needle coke price volatility:Feedstock costs for synthetic graphite anodes fluctuate with oil refining margins and steel electrode demand, compressing producer margins during upstream spikes.
- Chinese supply concentration:Over 70% of spherical graphite processing capacity sits in Shandong and Heilongjiang provinces, creating geographic vulnerability to regional environmental enforcement actions.
- Silicon expansion cycling degradation:Volume change during lithium intercalation limits silicon composite anodes to sub-10% blend ratios, capping energy density gains in mass-market cells.
Strategic Opportunities
- India's PLI scheme for cell manufacturing:Subsidies for domestic battery gigafactories in Gujarat and Tamil Nadu are creating first-mover anode supply contracts for non-Chinese material sources.
- Australian graphite beneficiation:Vertical mine-to-anode projects in Western Australia are positioning to bypass Chinese spherical graphite processing for Korean and Japanese cell makers.
- Japan's METI critical mineral stockpiling:State-funded inventory programs are creating guaranteed offtake volumes for domestic anode producers during demand troughs.
Industry Challenges
- Carbon accounting certification:China's SAMR enforcement of GB standards for production facility emissions disclosure requires anode makers to install continuous monitoring systems and third-party verification.
- Silicon anode pilot scale-up:Translating laboratory cycling stability into gigafactory coating line throughput remains unresolved, with yield losses concentrated at the electrode calendering stage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Electric Vehicle Battery Anode Market |
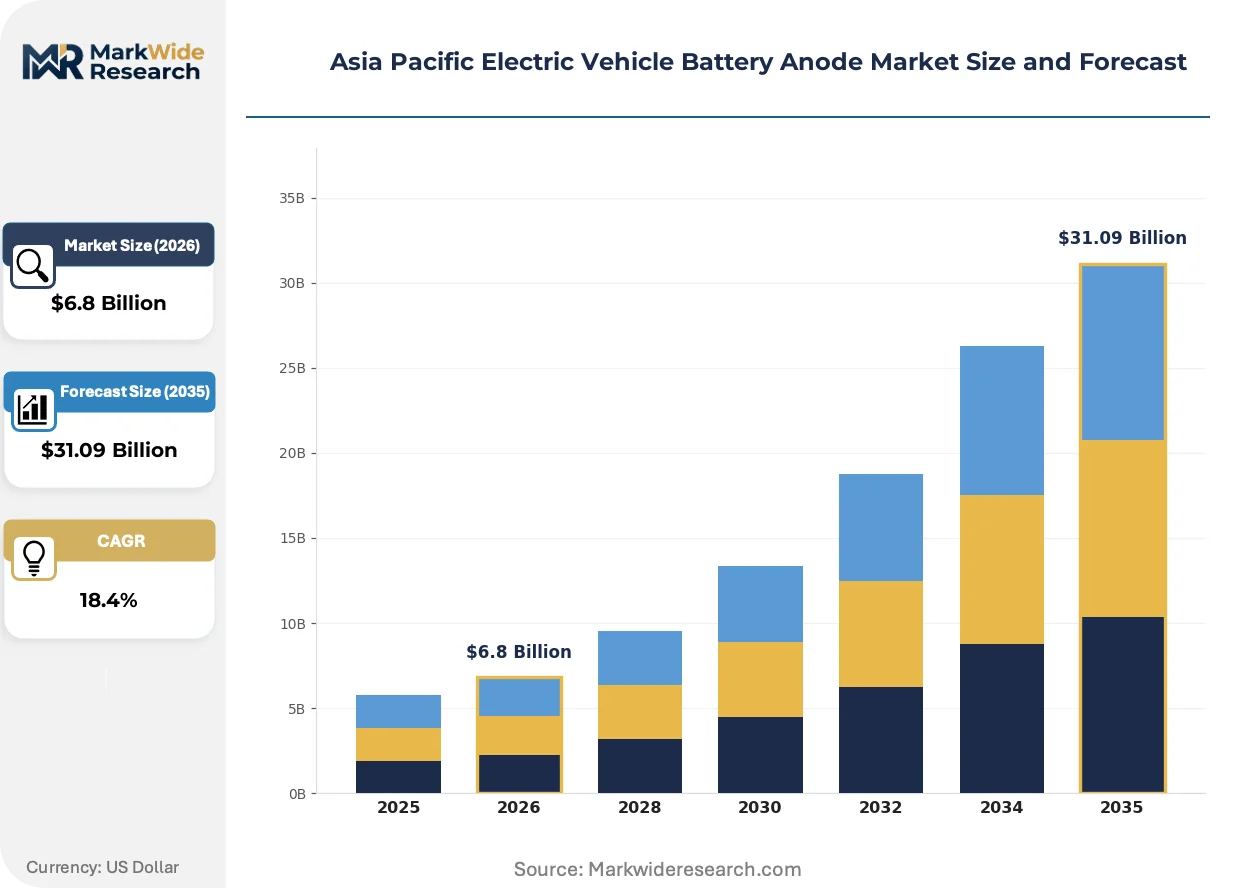
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Graphite, Silicon, Lithium Titanate, Others End User: OEMs, Aftermarket Providers, Fleet Operators, Battery Manufacturers Production Method: Coating, Extrusion, Compression Molding, Others Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, E-Bikes |
| Companies Covered | BTR New Material Group Co., Ltd., Himadri Speciality Chemical Ltd., Panasonic Holdings Corporation, Hitachi Chemical Company Ltd, Epsilon Advanced Materials Pvt. Ltd., Shenzhen Dynanonic Co., Ltd., Ningbo Shanshan Co., Ltd., Resonac Holdings Corporation, POSCO Future M, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Electric Vehicle Battery Anode Market Trends and Innovations
Material science advances and regulatory disclosure requirements are converging to reshape anode manufacturing processes and procurement relationships across the Asia Pacific region. These developments are compressing product development timelines while expanding the addressable performance envelope.
Pre-lithiation technology is automating capacity offset compensation in silicon-blend anodes, allowing cell makers to deploy higher silicon ratios without first-cycle losses. Korean battery manufacturers are integrating pre-lithiation stations into electrode coating lines at scale. This process automation is compressing the performance gap between laboratory formulations and mass-market cell specifications.
China's MIIT carbon intensity disclosure rules under dual carbon compliance frameworks are mandating scope 1 and 2 emissions reporting for anode active material production facilities. The industrial consequence is a capital reallocation toward electric calcination and renewable-powered milling operations. Synthetic graphite producers in Inner Mongolia are most affected, with several facilities installing dedicated solar arrays to meet Jiangsu-based cathode-anode integrated gigafactory procurement standards.
Direct long-term offtake agreements are displacing spot-market purchasing as the dominant procurement model for battery-grade anode materials. Korean cell makers are signing 5-7 year supply contracts with fixed volume floors and price adjustment clauses tied to needle coke indices. This pattern is most visible in procurement relationships between Seoul-headquartered battery divisions and their Chinese anode suppliers, where intermediary traders are being systematically excluded from contract structures.
Asia Pacific Electric Vehicle Battery Anode Market Segmentation
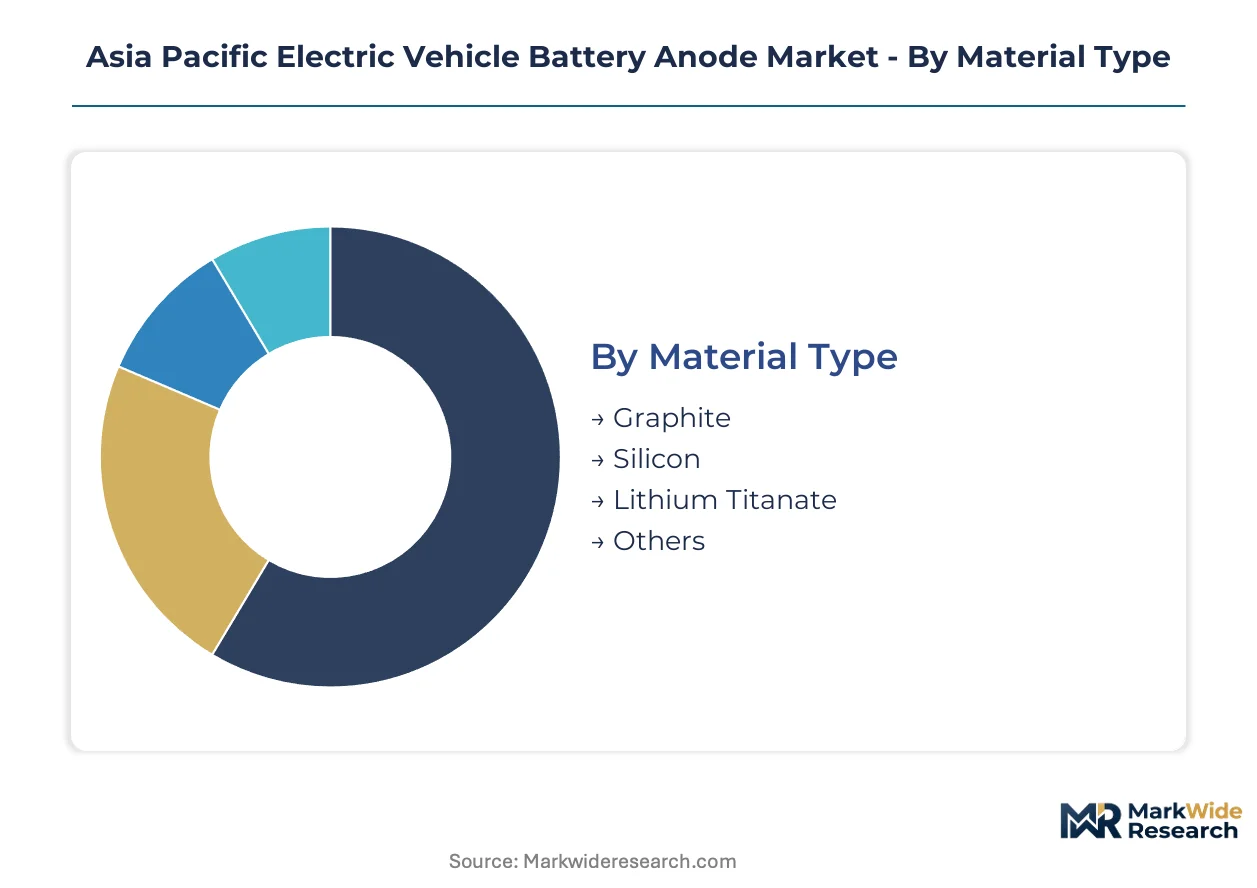
Anode procurement patterns diverge sharply across material chemistries and customer types. Battery manufacturers and OEMs impose distinct specification regimes that reshape supplier capability requirements and margin structures.
Material Type:
Customization intensity varies from commodity graphite specifications to highly tailored silicon composite formulations requiring co-development between material scientists and cell engineers.
- Graphite:Spherical natural and synthetic variants dominate procurement volumes through established intercalation chemistry near 372 mAh/g. Jiangsu and Zhejiang gigafactories source predominantly from Shandong and Heilongjiang processing clusters, with MIIT carbon intensity disclosure rules now filtering supplier qualification.
- Silicon:Composite formulations with carbon matrices accommodate volume expansion exceeding 300% during lithiation. Japanese automakers fund pilot lines through METI programs to breach 300 Wh/kg cell targets, though cycling stability constraints cap blend ratios below 10% in mass-market applications.
- Lithium Titanate:Zero-strain spinel structure enables ultra-fast charging for commercial vehicle depot operations.
- Others:Hard carbon and alloy systems serve niche sodium-ion and solid-state development programs.
Leading the category by volume: Graphite. Growing fastest: Silicon.
End User:
Procurement power concentrates with entities controlling cell manufacturing assets rather than vehicle assembly alone.
- Battery Manufacturers:Direct long-term offtake agreements with 5-7 year duration and needle coke index pricing clauses. Korean cell makers in Seoul systematically exclude intermediary traders from contract structures, capturing deepest margin pools through volume commitment.
- OEMs:Backward integration into cell manufacturing accelerates anode specification control. Chinese OEMs in Jiangsu province co-locate cathode-anode integrated gigafactories to compress logistics costs and synchronize ramp schedules.
- Aftermarket Providers:Fragmented demand for replacement cells in aging electric two-wheeler fleets.
- Fleet Operators:Procurement concentrated among commercial vehicle electrification programs with standardized duty cycles.
Controlling procurement volume: Battery Manufacturers. Expanding contractual influence fastest: OEMs.
Production Method:
Process selection tracks the tension between coating precision for high-performance anodes and throughput economics for mass-market supply.
- Coating:Slurry-based electrode deposition with calendering control for density uniformity. Korean manufacturers integrate pre-lithiation stations into coating lines to offset first-cycle capacity loss in silicon-blend formulations.
- Extrusion:Continuous forming for thick electrode architectures in commercial vehicle cells.
- Compression Molding:Dry electrode processing eliminating solvent recovery costs.
- Others:Vapor deposition and sintering routes for solid-state battery interfaces.
Dominating current installed capacity: Coating. Advancing toward commercial scale: Compression Molding.
Application:
Vehicle electrification intensity varies from premium passenger platforms demanding energy density to cost-optimized two-wheeler segments prioritizing cycle life.
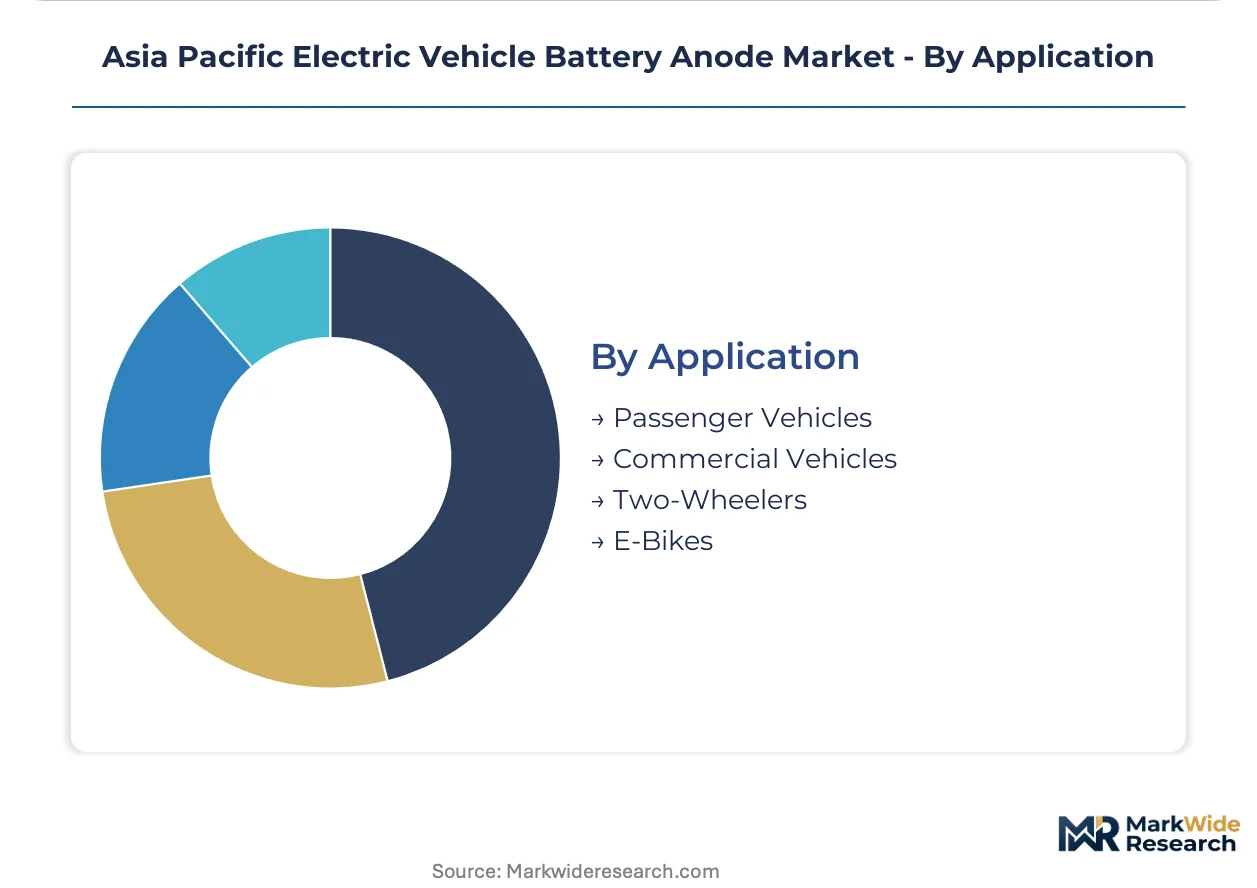
- Passenger Vehicles:Premium platforms specify silicon-composite anodes above 5% blend ratios, while mass-market models optimize around synthetic graphite cost structures. China's dual carbon goals compress procurement cycles as domestic OEM electrification targets tighten.
- Commercial Vehicles:Depot-charged bus and truck fleets favor lithium titanate for 10-minute fast charging despite energy density penalties.
- Two-Wheelers:Hard carbon and graphite blends balance cost against moderate cycle life requirements.
- E-Bikes:Entry-level lithium-ion and emerging sodium-ion systems for last-mile logistics.
Commanding procurement volume: Passenger Vehicles. Fastest policy-driven expansion: Commercial Vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Zhejiang provinces anchor anode procurement activity through cathode-anode integrated gigafactory clusters serving domestic OEM electrification programs. China's dual carbon compliance deadlines under MIIT are compressing supplier qualification timelines across the region.
China
Shandong and Heilongjiang processing clusters supply spherical graphite to Jiangsu-based battery manufacturers under tightening MIIT carbon intensity disclosure rules. SAMR enforcement of GB standards for production facility emissions is forcing anode makers to install continuous monitoring systems. Inner Mongolia synthetic graphite producers are deploying dedicated solar arrays to meet procurement standards from Zhejiang gigafactories.
Japan
METI coordinates domestic anode supply security through critical mineral stockpiling directives and silicon-alloy R&D funding for premium battery platforms. Japanese automakers are backing pilot production lines to breach 300 Wh/kg cell energy density thresholds. Kanto-based material suppliers are securing guaranteed offtake volumes through state-funded inventory programs during demand troughs.
South Korea
POSCO's Pohang steelmaking operations provide captive needle coke supply for synthetic graphite anode manufacturing serving Seoul-headquartered battery divisions. MFDS and KATS align with EU REACH-equivalent substance restrictions for exported cells, tightening purity thresholds. Korean cell makers are signing 5-7 year supply contracts with fixed volume floors and needle coke index pricing clauses.
India
Gujarat and Tamil Nadu are attracting first-mover anode supply contracts through PLI scheme subsidies for domestic battery gigafactories. The country's national industrial policy regulator is channeling incentives toward cell manufacturing localization. Hard carbon and graphite blend demand is concentrating in two-wheeler electrification programs with standardized duty cycles.
Australia
Western Australia vertical mine-to-anode projects are positioning to bypass Chinese spherical graphite processing for Korean and Japanese cell makers. The country's national resources regulator is monitoring beneficiation capacity expansion for battery material export qualification. Perth-based mining operations are integrating with Asian coating line specifications for direct long-term offtake agreements.
Asia Pacific Electric Vehicle Battery Anode Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the anode supply chain, with integrated mine-to-anode operators commanding procurement relationships against specialized coating technology licensors. The market structure concentrates around three tiers: captive precursor suppliers with steelmaking or mining origins, independent graphite processors with Shandong and Heilongjiang facility networks, and silicon-composite specialists backed by automaker R&D partnerships. Dominant competitive moves include backward integration into needle coke or spherical graphite processing, and strategic partnerships binding anode makers to cell manufacturer coating line specifications.
Among China-based material groups, BTR New Material Group Co., Ltd. and Ningbo Shanshan Co., Ltd. exemplify the integrated processor archetype with mine-to-anode pipeline control. Panasonic Holdings Corporation and POSCO Future M occupy positions spanning the captive supply and premium technology tiers, with the former representing Japanese silicon-alloy development partnerships and the latter anchoring Korean needle coke integration from steelmaking operations.
| Leading Market Players |
|---|
| BTR New Material Group Co., Ltd. |
| Himadri Speciality Chemical Ltd. |
| Panasonic Holdings Corporation |
| Hitachi Chemical Company Ltd |
| Epsilon Advanced Materials Pvt. Ltd. |
| Shenzhen Dynanonic Co., Ltd. |
| Ningbo Shanshan Co., Ltd. |
| Resonac Holdings Corporation |
| POSCO Future M |
| Others |
Pricing and Supply Chain Analysis
Mine-to-anode pipeline integration by Chinese processors anchors supply positions while compressing pricing power for independent traders excluded from direct long-term offtake agreements. This structural consolidation concentrates margin capture with BTR New Material Group and Ningbo Shanshan, forcing spot-market intermediaries toward volume discounting or exit.
Pricing Analysis
Yield-guaranteed contract pricing dominates procurement relationships between Korean cell makers and Chinese anode suppliers, with 5-7 year agreements incorporating needle coke index adjustments and volume floors. Price differentiation separates premium silicon-composite formulations backed by METI-funded Japanese automaker partnerships from mass-market synthetic graphite tiers sourced through Jiangsu gigafactory specifications. Cost compression in synthetic graphite runs through petroleum needle coke feedstock volatility, squeezing processor margins during upstream spikes. Battery manufacturers exhibit lowest price sensitivity through captive volume commitments, while aftermarket providers face acute margin pressure from fragmented two-wheeler replacement demand.
Supply Chain Analysis
MIIT carbon intensity certification gates supplier qualification for Jiangsu and Zhejiang cathode-anode integrated gigafactories, filtering Shandong and Heilongjiang processing clusters through emissions disclosure mandates. Raw material flows draw from Australian spherical graphite beneficiation projects, Korean needle coke byproduct streams from POSCO Pohang operations, and Chinese petroleum coke refining outputs. Single-source vulnerability concentrates in Chinese spherical graphite processing exceeding seventy percent of regional capacity, exposing procurement networks to environmental enforcement disruptions. Distribution runs through direct long-term offtake agreements systematically excluding intermediary traders from Seoul-headquartered battery division procurement structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from MIIT dual carbon compliance deadlines is forcing smaller anode processors without continuous emissions monitoring systems toward acquisition or capacity mothballing.
For Market Incumbents: Anticipate silicon-composite R&D displacement threats from Japanese automaker pilot lines by securing METI-funded partnership slots or accelerating pre-lithiation coating line integration. Defensive moves center on backward integration into needle coke supply through steelmaking joint ventures or Australian spherical graphite offtake agreements, while certification investment in SAMR-compliant emissions disclosure systems preserves Jiangsu gigafactory procurement access against uncertified competitors. For New Entrants and Emerging Players: Premium-to-economy price-point gaps in Indian PLI-subsidized Gujarat and Tamil Nadu cell manufacturing clusters offer white-space entry for hard carbon and graphite blend suppliers serving two-wheeler electrification programs. Target Australia's Western Australia vertical mine-to-anode projects as qualification pathways into Korean and Japanese cell maker supply chains bypassing Chinese processing concentration. Go-to-market positioning emphasizes non-Chinese origin certification for EU REACH-equivalent export compliance. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap anode processors with SAMR-certified emissions infrastructure and established Jiangsu gigafactory relationships facing succession or liquidity constraints. Long-term viability over the mid-decade window favors integrated mine-to-anode operators with captive precursor supply and direct OEM coating line partnerships over asset-light coating technology licensors. Watch for MIIT enforcement acceleration on Inner Mongolia synthetic graphite facilities as inflection indicator for certified capacity scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Needle Coke Supply | POSCO's Pohang steelmaking operations secure captive precursor feedstock for Korean synthetic graphite anode manufacturing. |
| Pre-lithiation Coating Line Integration | Korean battery manufacturers automate capacity offset compensation in silicon-blend anodes to deploy higher silicon ratios. |
| Australian Spherical Graphite Beneficiation | Western Australia vertical mine-to-anode projects bypass Chinese processing concentration for Japanese and Korean cell makers. |
| METI Silicon-Alloy Pilot Line Funding | Japanese automaker partnerships breach 300 Wh/kg cell energy density thresholds through state-backed R&D programs. |
| SAMR Emissions Certification Investment | Inner Mongolia synthetic graphite producers deploy solar arrays to meet Jiangsu gigafactory carbon intensity disclosure standards. |
Research Methodology
Multi-period observation of anode procurement contract structures, gigafactory ramp schedules, and MIIT regulatory enforcement patterns anchored the trend analysis, supplemented by interviews with coating line engineers at Korean battery divisions, procurement leads at Jiangsu-based OEMs, graphite processing plant managers in Shandong, and METI program officers. Secondary validation drew from MIIT GB standard filings, SAMR emissions disclosure registries, Korean customs needle coke import data, and Australian resources regulator beneficiation permits. Bottom-up capacity aggregation across spherical graphite processing clusters was triangulated against top-down gigafactory demand projections from OEM electrification targets.
Input-output matrices modeled anode material flows across material type, end user procurement power, production method, and application segments throughout the forecast period. CAGRs were derived from elasticity-adjusted gigafactory deployment schedules and OEM electrification policy trajectories. Forecast inputs incorporated needle coke price index correlations, silicon composite blend ratio adoption curves, and MIIT compliance deadline acceleration scenarios.
Underlying measurement precision varies by segment; direct long-term offtake agreement terms carry tighter precision than spot-market transaction estimates. Forecasts reflect documented assumptions regarding OEM backward integration timelines and METI funding continuity. A model refresh is warranted upon material change in SAMR enforcement intensity or Japanese silicon-anode pilot line yield breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium-Ion Stationary Battery Market
Lithium-ion Battery
North America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium-Ion Battery Metal Market
Lithium-ion Battery
Outdoor Lithium Battery Power Supplies Market
Lithium-ion Battery
Automotive Lithium Based Battery Market
Lithium-ion Battery
Global Next Generation Batteries Market
Lithium-ion Battery
Lithium-Ion Battery Wet-Process Separator Market
Lithium-ion Battery
South America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Advanced Lithium-Ion Batteries Market
Lithium-ion Battery
Lifepo4 Battery Market
Lithium-ion Battery
India Electric Vehicle Battery Anode Market
Lithium-ion Battery
Laminated Lithium Ion Secondary Battery Market
Lithium-ion Battery
UAV Lithium Battery Market
Lithium-ion Battery
Lithium Manganate Battery Market
Lithium-ion Battery
Lithium Cobalt Oxide Market
Lithium-ion Battery
Lithium and Lithium Ion Battery Electrolytes Market