
 United States Battery Cell Market | 2026-2036
United States Battery Cell Market Size, Share, and Industry Trends Forecast 2026-2036
United States Battery Cell Market Analytics
Multi-source cathode supply contracts is restructuring procurement patterns across the United States battery cell landscape. Tesla leverages its Nevada-based cell production to reduce import dependency for vehicle packs. SK Battery America anchors its Georgia operations to serve Hyundai and Volkswagen assembly plants in the Southeast. Panasonic sustains its technical partnership with Tesla while expanding standalone capacity for broader OEM qualification.
A battery cell is an electrochemical device comprising an anode, cathode, separator, and electrolyte that converts stored chemical energy into electrical energy through reversible ion transfer, with lithium-ion variants achieving energy densities of 250-300 Wh/kg at the cell level. The United States Battery Cell Market serves electric vehicle powertrain integration, grid-scale storage, and portable electronics requiring sustained discharge cycles. Lithium-ion chemistry dominates current manufacturing output due to established supply chains and performance maturity, while solid-state technology attracts the fastest-growing R&D investment pool as manufacturers target higher energy density with reduced thermal risk. Automotive OEMs represent the most concentrated end-user segment, absorbing capacity from multiple producers under long-term offtake agreements.
The Inflation Reduction Act, administered through IRS and Department of Energy guidance, ties federal EV tax credits to domestic battery sourcing thresholds, directly conditioning market access on North American assembly. EPA tailpipe standards and NHTSA fuel economy rules accelerate OEM electrification timelines, expanding contracted cell demand. OSHA and NFPA standards govern factory safety and thermal runaway containment in production facilities. Stakeholders must track how Treasury Department guidance on foreign entity of concern rules reshapes joint venture structures and raw material qualification pathways.
Market Dynamics
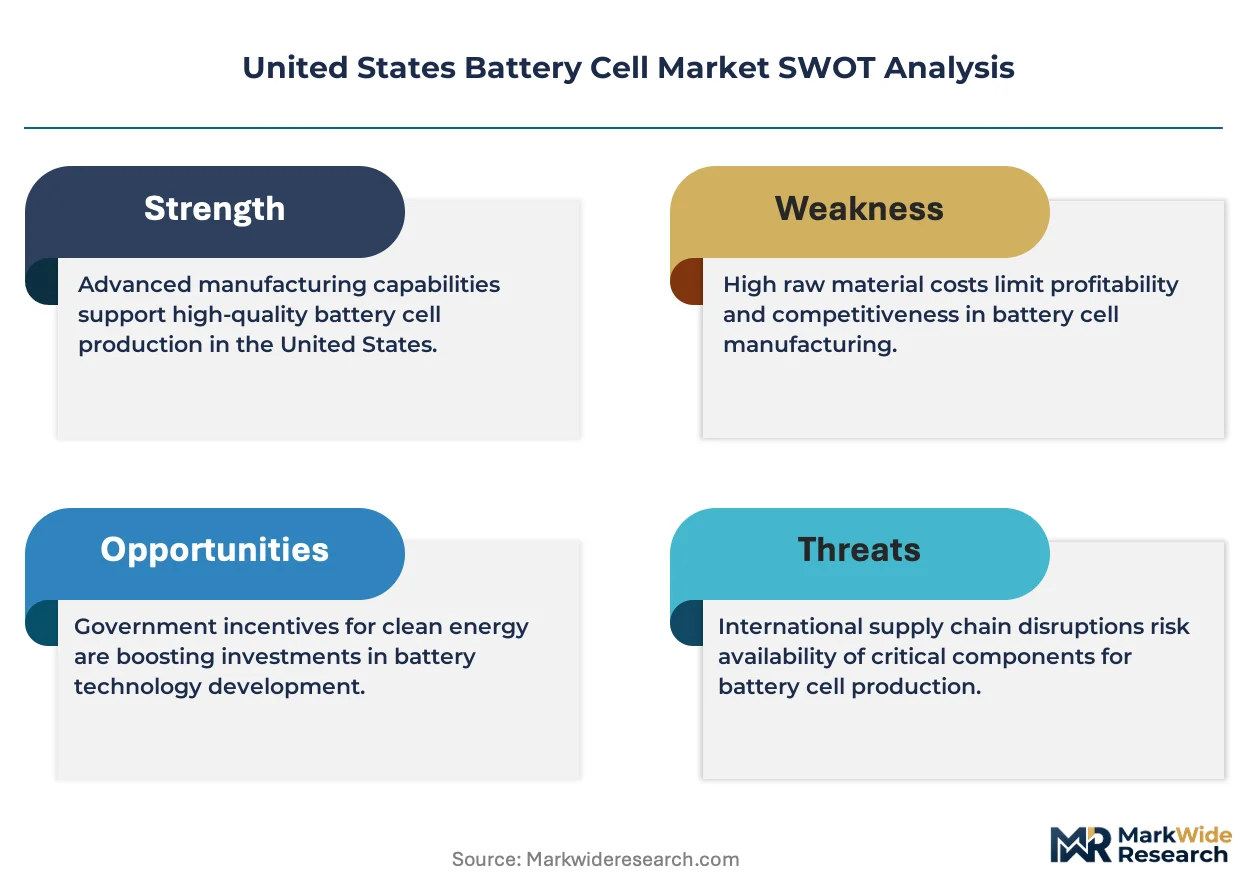
The Inflation Reduction Act's domestic content thresholds are compressing supply chain timelines as OEMs race to qualify North American cell sources before credit phase-outs begin. This regulatory pressure is accelerating gigafactory construction across the Southeast and Midwest while forcing raw material suppliers to establish domestic processing capacity.
Growth Catalysts
- IRA Domestic Content Requirements:Federal EV tax credits now mandate escalating North American battery component percentages, redirecting procurement toward domestic gigafactories and away from Asian supply chains.
- Logistics Fleet Electrification:Amazon, UPS, and FedEx procurement teams are contracting dedicated cell volumes for medium-duty delivery vehicles, creating anchor demand outside passenger automotive.
- Solid-State R&D Pipelines:Department of Energy funding through the Battery Manufacturing and Recycling Grants program is accelerating pilot lines for lithium-metal anode architectures with higher energy density targets.
Market Restraints
- Lithium Hydroxide Price Volatility:Spodumene concentrate contracts from Australian hard-rock mines expose US cathode producers to input cost swings that compress margin predictability.
- Separator Film Import Dependency:Polyolefin separator substrates concentrate in Japanese and South Korean suppliers, creating single-source risk for US cell assembly lines.
- Cell Formation Bottlenecks:Electrochemical conditioning equipment for initial charge-discharge cycles requires 14-21 day factory occupancy, constraining effective throughput at greenfield facilities.
Strategic Opportunities
- Grid-Scale Storage Procurement:Utility-scale battery installations under FERC Order 2222 participation rules are opening long-duration contract windows independent of automotive cycle volatility.
- Southeast Manufacturing Cluster:Georgia, Tennessee, and South Carolina offer combined port access, automotive assembly proximity, and right-to-work labor frameworks for integrated cell-to-pack operations.
- Recycling Feedstock Integration:Black mass processing infrastructure under EPA hazardous waste permitting pathways can secure domestic lithium, nickel, and cobalt streams outside primary mining jurisdictions.
Industry Challenges
- Electrolyte Formulation Talent Scarcity:Cell manufacturers compete for PhD-level electrochemists capable of optimizing additive packages for high-voltage cathode compatibility.
- UL 9540A Certification Timelines:Thermal runaway propagation testing for utility-scale installations extends qualification cycles by 8-12 months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Battery Cell Market |
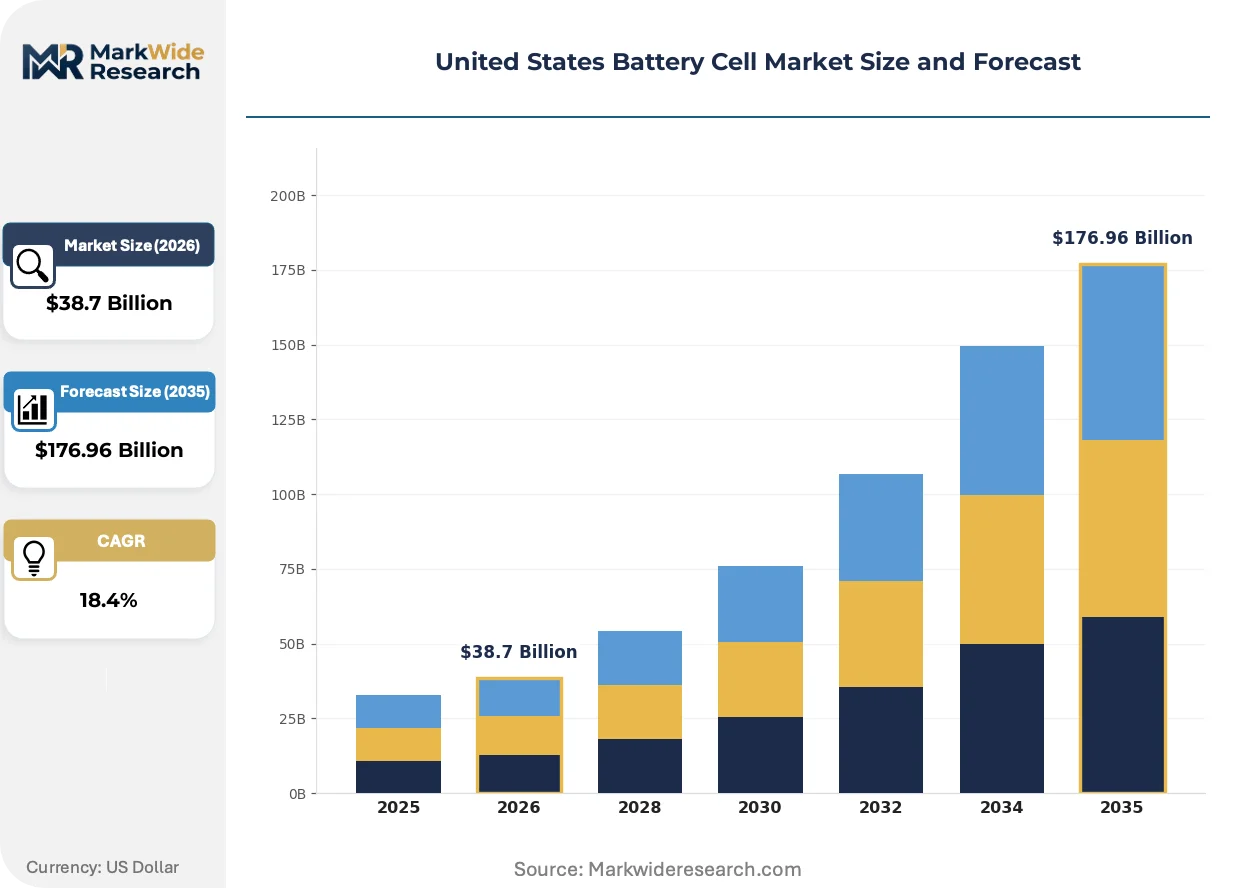
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $176.96 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-metal Hydride, Lead-acid, Solid-state End User: Consumer Electronics, Automotive OEMs, Renewable Energy, Industrial Equipment Application: Electric Vehicles, Portable Devices, Energy Storage Systems, Uninterruptible Power Supply Technology: Battery Management, Supercapacitors, Wireless Charging, Fast Charging |
| Companies Covered | Tesla, Ultium Cells, SK Battery America, A123 Systems, EnerSys, Panasonic, LG Energy Solution, Microvast, Clarios, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Battery Cell Market Evolving Landscape
Silicon-anode architectures and dry electrode coating methods are compressing manufacturing energy intensity while boosting energy density targets. These process shifts are redrawing equipment supplier relationships and factory layout requirements across domestic production sites.
Dry electrode coating is absorbing capital allocation from traditional slurry-based methods as manufacturers target 15-20% reduction in electrode drying energy. SK Battery America and Tesla's Nevada operations are piloting solvent-free binder deposition for anode and cathode layers. This process shift is absorbing engineering resources previously directed toward incremental chemistry improvements, compressing the timeline for next-generation cell architectures.
EPA tailpipe standards finalized under the Clean Air Act are mandating 50% fleet electrification by 2030 for light-duty vehicles, binding OEM procurement commitments to federal compliance timelines. The regulatory pressure is forcing long-term offtake contracting at fixed volumes regardless of near-term demand fluctuations. Automotive powertrain divisions are responding by embedding cell procurement teams within supplier quality organizations.
Fleet operators are consolidating procurement through direct cell sourcing rather than pack-level purchasing, disintermediating traditional tier-one battery integrators. Amazon's Rivian van program and Walmart's medium-duty trials are establishing precedent for buyer-controlled cell specification. This pattern is most visible in California and Texas where state-level zero-emission vehicle mandates intersect with large logistics hub concentrations.
United States Battery Cell Market Segmentation
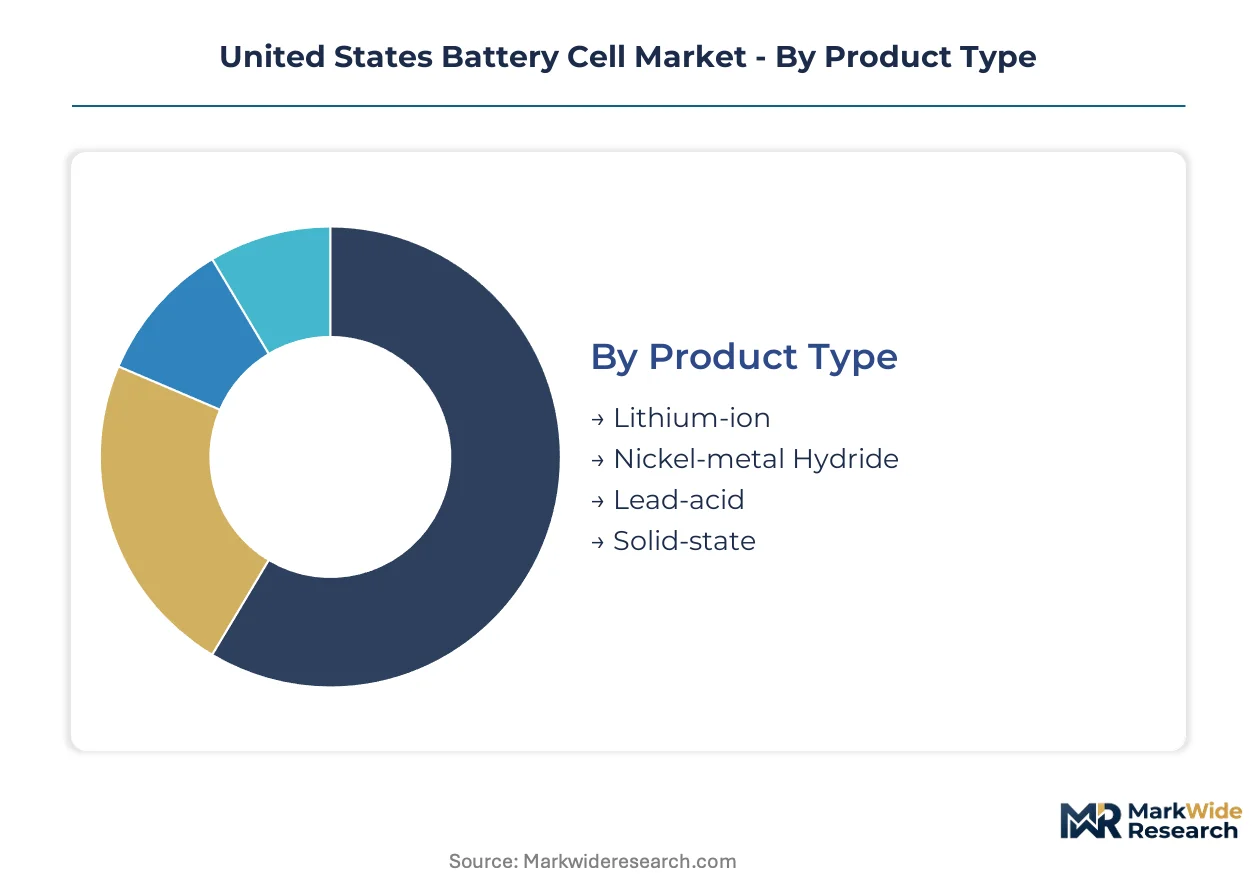
Battery cell procurement patterns diverge sharply across chemistry types and end-use applications, with capital requirements and qualification timelines varying by an order of magnitude. Understanding these segment boundaries clarifies where manufacturing investments concentrate and which technology transitions threaten incumbent positions.
Product Type:
Capital intensity varies most dramatically across chemistry platforms, with gigafactory-scale lithium-ion facilities requiring multi-billion dollar commitments versus legacy lead-acid operations that repurpose existing industrial infrastructure.
- Lithium-ion:NMC and LFP cathode variants dominate current US manufacturing output, with energy densities of 250-300 Wh/kg enabling 300+ mile electric vehicle ranges. Michigan and Nevada production lines supply Tesla, Ford, and GM assembly plants under IRA-compliant domestic content rules. Gigafactory construction timelines of 24-36 months lock in capacity commitments before demand materialization.
- Solid-state:Lithium-metal anode architectures with ceramic or sulfide electrolytes target 400+ Wh/kg densities while eliminating thermal runaway risks. Department of Energy grants through the Battery Manufacturing and Recycling program are funding pilot lines at QuantumScape and Solid Power facilities in California and Colorado. Commercial qualification remains 3-5 years behind lithium-ion timelines.
- Nickel-metal Hydride:Toyota maintains limited US production for hybrid powertrains where lower energy density tolerates smaller pack sizes. Kentucky and West Virginia facilities serve Camry and RAV4 hybrid assembly.
- Lead-acid:Flooded and AGM variants persist in starter battery and industrial backup applications where cost sensitivity outweighs energy density requirements. Recycling infrastructure in Missouri and Pennsylvania captures near-complete material recovery rates.
Lithium-ion absorbs the bulk of installed capacity; solid-state is expanding most quickly in R&D allocation terms.
End User:
Customer procurement sophistication spans from commodity spot purchasing to decade-long offtake agreements with embedded price collars and volume minimums.
- Automotive OEMs:Detroit Three and Tesla procurement teams negotiate direct cell supply contracts bypassing traditional pack integrators, embedding quality engineers at supplier facilities for 18-24 month qualification cycles. Long-term agreements specify annual volume minimums with penalty clauses for shortfall.
- Renewable Energy:Utility-scale developers under FERC Order 2222 procurement rules contract 10-20 year service agreements, prioritizing cycle life degradation warranties over energy density metrics. Texas and California ISO markets drive the steepest expansion trajectory for grid-tied storage.
- Consumer Electronics:Smartphone and laptop manufacturers source cylindrical and pouch cells through Asian trading houses, with minimal domestic US assembly presence.
- Industrial Equipment:Forklift and material handling fleets at Amazon, Walmart, and Target distribution centers convert from lead-acid to lithium-ion for opportunity charging compatibility.
Automotive OEMs command the largest contracted volumes; renewable energy developers are climbing the fastest in annual procurement growth.
Application:
Application-specific performance requirements dictate electrode formulation choices and factory equipment configurations, with electric vehicle and grid storage demands pulling manufacturing in divergent directions.
- Electric Vehicles:Cylindrical 2170 and 4680 formats dominate passenger automotive, with cell-to-pack architectures eliminating module-level components. Fast-charge capability of 10-80% in 20 minutes requires silicon-doped anode formulations and advanced electrolyte additives.
- Energy Storage Systems:Prismatic LFP cells prioritize 6,000+ cycle life and thermal stability over gravimetric density, with containerized installations scaling to 100+ MWh per site. ERCOT and CAISO market participation rules mandate four-hour duration minimums.
- Portable Devices:Pouch and cylindrical formats in 18650 and 2170 sizes serve power tool and personal electronics markets with standardized discharge rate specifications.
- Uninterruptible Power Supply:Lead-acid and lithium-ion hybrid configurations protect data center and healthcare critical loads, with UL 1973 safety certification governing installation approval.
Electric vehicle applications absorb dominant manufacturing allocation; energy storage systems are gaining share fastest in new capacity announcements.
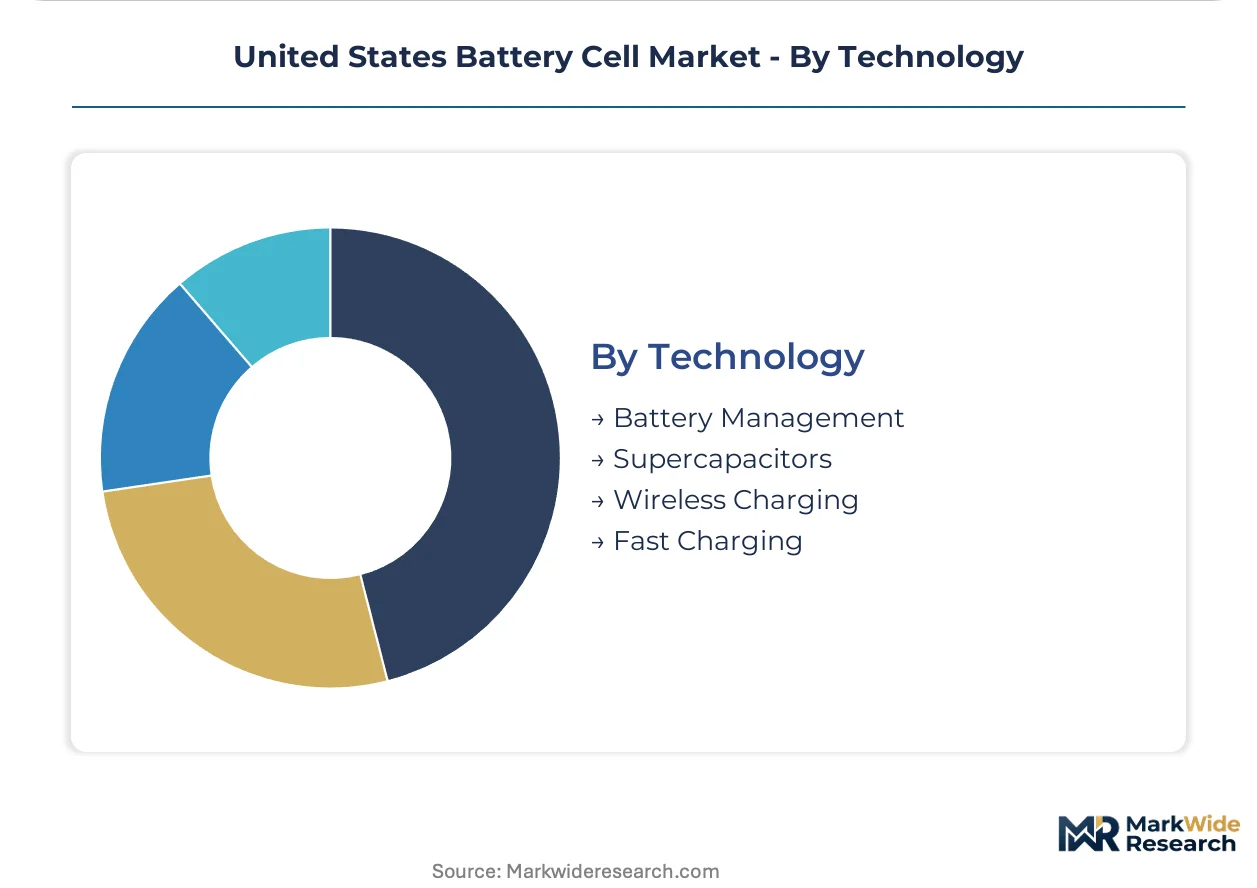
Technology:
Enabling technologies determine cell performance ceilings and manufacturing yield rates, with battery management systems representing the highest-margin component layer outside the electrochemical stack itself.
- Battery Management:ASIL-D functional safety-rated electronics monitor cell-level voltage and temperature with millisecond response latency, preventing propagation during single-cell faults. Texas Instruments and Analog Devices supply integrated circuits to domestic pack assemblers.
- Fast Charging:800V architectures and liquid-cooled connectors enable 350kW peak rates, requiring electrode porosity optimization and electrolyte conductivity enhancement. Electrify America and Tesla Supercharger networks validate cell durability under extreme C-rate cycling.
- Supercapacitors:Activated carbon double-layer devices bridge power gaps in hybrid transit buses and wind turbine blade pitch systems, with Maxwell Technologies maintaining US production.
- Wireless Charging:Inductive pad systems for fleet vehicles and consumer devices remain limited by efficiency losses and alignment tolerance constraints.
Battery management systems capture the highest value per unit; fast charging infrastructure is expanding most quickly in deployment velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spodumene concentrate from Australian hard-rock mines feeds cathode production lines across the United States battery cell landscape, conditioning regional capacity distribution around processing infrastructure and IRA-compliant assembly nodes.
Michigan
Ford and GM powertrain divisions anchor cell demand through dedicated offtake agreements with Ultium Cells and LG Energy Solution. The state's Department of Environment, Great Lakes, and Energy administers air quality permits for gigafactory expansions. Holland and Warren host electrode coating and cell assembly operations serving Detroit automotive assembly plants.
Tennessee
SK Battery America operates its $2.5 billion facility to supply Hyundai and Volkswagen Southeast assembly plants under multi-year contracts. The Tennessee Department of Economic and Community Development coordinates workforce training grants for battery manufacturing technicians. Spring Hill and Chattanooga form a dual-node cluster linking cell production to vehicle final assembly.
Georgia
Rivian and Hyundai anchor demand for high-nickel cathode cells through direct procurement teams embedded at supplier facilities. The Georgia Environmental Protection Division oversees hazardous waste permitting for electrolyte formulation operations. Ellabell and Bryan County concentrate greenfield construction of integrated cell-to-pack facilities.
Nevada
Tesla's Gigafactory sustains the largest domestic cylindrical cell output for vehicle and energy storage applications. The Nevada Division of Environmental Protection regulates lithium processing tailings from nearby Clayton Valley brine operations. Storey County hosts the densest concentration of cell formation and aging capacity in the Western United States.
California
QuantumScape and Solid Power pilot solid-state architectures through Department of Energy-funded demonstration lines targeting 400+ Wh/kg densities. The California Air Resources Board enforces zero-emission vehicle mandates that bind OEM procurement to in-state technology development. San Jose and San Diego host the deepest pools of electrochemistry PhD talent for next-generation electrolyte formulation.
United States Battery Cell Market Competitive Landscape
Global majors compete with regional champions across domestic content qualification pathways, creating a tiered structure where IRA compliance thresholds separate contract-eligible from excluded suppliers. The vendor base clusters around three strategic archetypes: integrated automotive OEMs with captive cell production, independent Korean and Japanese producers with US assembly presence, and domestic specialists serving industrial and defense niche applications. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with producers racing to qualify North American sources before federal credit phase-outs accelerate.
Within the integrated automotive tier, Tesla and Ultium Cells exemplify backward integration strategies that bypass traditional pack assemblers. Among Korea-based producers, SK Battery America and LG Energy Solution anchor Southeast manufacturing clusters through joint ventures with domestic OEMs. Panasonic occupies a bridging position between Japanese technical heritage and US-based expansion for broader customer qualification.
| Leading Market Players |
|---|
| Tesla |
| Ultium Cells |
| SK Battery America |
| A123 Systems |
| EnerSys |
| Panasonic |
| LG Energy Solution |
| Microvast |
| Clarios |
| Others |
Value Network & Pricing Analysis
Spodumene concentrate benchmark prices from Australian hard-rock mines cascade through cathode precursor costs, compressing margins for US cell producers while amplifying pricing power for integrated miners with captive lithium streams.
Pricing Analysis
Warranty bundling separates automotive OEM contracts from industrial spot purchases, with cycle-life guarantees and thermal runaway liability coverage embedded in long-term offtake agreements. Three-tier pricing structure across premium, standard, and economy levels reflects IRA domestic content compliance tiers, with fully qualified North American cells commanding premium placement against import-dependent alternatives. Cost compression in standard-tier supply is intensifying because cathode active material costs dominate bill-of-materials exposure. Fleet operators at Amazon and UPS demonstrate highest price sensitivity through consolidated volume tenders, while defense contractors accept premium positioning for security-cleared supply chains.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Detroit Three and Tesla procurement teams, bypassing traditional pack integrators entirely. Geographic concentration draws from Australian spodumene mines, Chilean and Argentine brine operations, and Indonesian nickel processing, with each node exposing US cathode producers to sovereign resource policy shifts. Polyolefin separator substrates, electrolyte salt formulations, and conductive carbon additives constitute critical component dependencies with limited domestic alternatives. Single-source vulnerability concentrates in Japanese and South Korean separator film suppliers, where factory outages would idle US cell formation lines within weeks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around IRA-compliant domestic content thresholds, with Treasury Department foreign entity of concern rules forcing non-qualifying producers toward joint venture restructuring or exit.
For Market Incumbents: Lock in raw material offtake through equity stakes in Australian spodumene and Chilean brine assets before competitor procurement absorbs available supply. Secure formation equipment capacity at greenfield sites to eliminate throughput bottlenecks that constrain revenue recognition timelines. For New Entrants and Emerging Players: Capture grid-scale storage procurement windows under FERC Order 2222 participation rules, where utility developers prioritize cycle-life warranties over automotive energy density metrics. Target recycling feedstock integration through black mass processing partnerships that bypass primary mining cost structures. For Investors and Strategic Acquirers: Distressed-cycle entries favor solid-state pilot-line operators in California and Colorado with Department of Energy grant backing and qualified technical teams. Watch commercial qualification timelines for lithium-metal anode architectures as the inflection signal separating viable platforms from stranded R&D expenditure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Processing | Captures margin from Australian spodumene concentrate through domestic hydroxide conversion. |
| IRA-Compliant Domestic Content Qualification | Unlocks federal EV tax credit eligibility for OEM customers under Treasury Department guidance. |
| Solid-State Pilot Line Scale-Up | Positions for 400+ Wh/kg density targets with reduced thermal runaway risk profiles. |
| Grid-Scale Storage Supply Agreement | Secures 10-20 year revenue streams independent of automotive demand cyclicality. |
| Recycling Feedstock Partnership | Establishes domestic nickel, cobalt, and lithium streams outside primary mining jurisdictions. |
Research Methodology
Multi-period observation of gigafactory construction permits, cathode active material import volumes, and IRA tax credit qualification filings anchored the trend analysis, supplemented by interviews with cell manufacturing executives, OEM procurement directors, utility storage developers, and electrode equipment suppliers. Secondary validation drew from Department of Energy grant disclosures, FERC interconnection queue data, EPA hazardous waste permitting records, and SEC filings from publicly traded battery producers. Bottom-up capacity build-up and top-down demand absorption models were cross-checked for triangulation integrity.
Input-output matrices mapped cell chemistry variants against end-use applications, with segmentation dimensions spanning lithium-ion format types, solid-state development stages, automotive OEM versus grid storage demand, and regional production cluster economics. CAGRs were derived from installed capacity ramp schedules and offtake contract volume trajectories across the projection horizon. Forecast inputs incorporated electrolyte formulation talent availability, separator film import lead times, and cell formation equipment delivery backlogs.
The model holds under sustained IRA domestic content enforcement and stable lithium hydroxide contract structures; deviation in Treasury foreign entity of concern rule expansion or Australian mining export restrictions would shift capacity deployment timelines. Periodic stress-testing of base assumptions is recommended against evolving EPA tailpipe standard stringency and NHTSA fuel economy rulemakings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Germany Electric Vehicle Battery Anode Market
Lithium-ion Battery
Southeast Asia Lithium-Ion Battery Market
Lithium-ion Battery
Lithium-Ion Battery Anode Market
Lithium-ion Battery
Laminated Lithium Ion Secondary Battery Market
Lithium-ion Battery
Lithium Battery Cells for Passenger Car Market
Lithium-ion Battery
Global Lithium Mining Market
Lithium-ion Battery
Cylindrical Lithium-Ion Battery Market
Lithium-ion Battery
Global Nanowire Battery Market
Lithium-ion Battery
India Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium-Ion Batteries Electric Bike Market
Lithium-ion Battery
Lithium Ion Secondary Battery Sales Market
Lithium-ion Battery
United States Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Lithium Manganate Battery Market
Lithium-ion Battery
Lithium Iodide Market
Lithium-ion Battery
India Lithium-Ion Battery Market
Lithium-ion Battery
Global Rechargeable Poly Lithium-Ion Batteries Market