
 Europe Solid State Battery Market | 2026-2036
Europe Solid State Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Solid State Battery Market Insights
A capital-intensity divergence between thin-film specialists and lithium-metal scale players is rotating competitive dynamics across the European landscape. Ilika plc leverages its UK-based pilot manufacturing to dominate niche medical and industrial micro-battery segments. Robert Bosch GmbH anchors its position through deep backward integration into solid electrolyte materials and automotive qualification protocols. Samsung SDI Co., Ltd. competes via Korean-European technology transfer, positioning its pilot line in Europe to capture premium automotive supply slots.
A solid-state battery replaces flammable liquid electrolytes with ion-conductive ceramics, polymers, or sulfide glasses, achieving energy densities above 400 Wh/kg while eliminating thermal runaway risks. The technology serves electric vehicle propulsion, medical implants, and aerospace power systems where safety margins and volumetric efficiency command priority. Thin-film batteries occupy established revenue pools in micro-power applications, while lithium metal batteries capture the fastest growth trajectory as automotive OEMs validate 800-volt architectures. Composite batteries concentrate margin pools at the materials interface, where Solvay SA controls specialty polymer electrolyte supply chains.
EMA chemical safety assessments, REACH substance registration requirements, and the EU Green Deal industrial policy collectively shape cell chemistry roadmaps and factory permitting timelines across European member states. The F-Gas Regulation restricts fluorinated compounds in manufacturing processes, pushing developers toward oxide and sulfide electrolyte formulations. Stakeholders must monitor automotive OEM qualification cycles and electrolyte material supply security as the decisive variables for manufacturing location and partnership strategy.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing development timelines for solid-state chemistries, forcing automotive OEMs to pre-qualify suppliers before pilot production scales. This regulatory pressure is concentrating procurement decisions around sulfide and oxide electrolyte platforms that bypass fluorinated manufacturing processes.
Growth Catalysts
- REACH substance registration:Early movers completing ECHA dossiers for lithium-metal anodes secure preferential factory permitting in Germany and France.
- Baden-Württemberg manufacturing corridor:Battery gigafactory clusters in this German state generate localized demand for solid-state cell qualification batches.
- Sulfide electrolyte chemistry:Korean-European technology transfer agreements accelerate automotive platform integration timelines.
Market Restraints
- Lithium metal foil supply:European refining capacity for battery-grade lithium metal remains concentrated at a single German supplier.
- CE marking complexity:Solid-state cells face ambiguous classification under existing battery directive frameworks, extending approval cycles.
- Thin-film manufacturing equipment:Vacuum deposition tools for oxide electrolytes rely on Japanese and Korean equipment vendors with 18-month order backlogs.
Strategic Opportunities
- Bavaria aerospace cluster:Munich-area satellite manufacturers seek solid-state power systems for orbital applications with extreme thermal cycling requirements.
- CSRD disclosure mandates:Corporate sustainability reporting requirements create demand for batteries with verified supply chain carbon footprints.
- Medical implant convergence:Cardiac device OEMs in Switzerland and Ireland are evaluating thin-film solid-state alternatives to conventional lithium-iodine cells.
Industry Challenges
- Solid electrolyte interface engineering:European universities produce insufficient PhD-level specialists in ceramic processing for battery applications.
- Dry room infrastructure:Sulfide electrolyte manufacturing requires sub-1% humidity environments, demanding capital-intensive facility retrofits.
- Automotive qualification protocols:OEM validation cycles for 800-volt architectures extend 36-48 months, compressing supplier cash conversion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Solid State Battery Market |
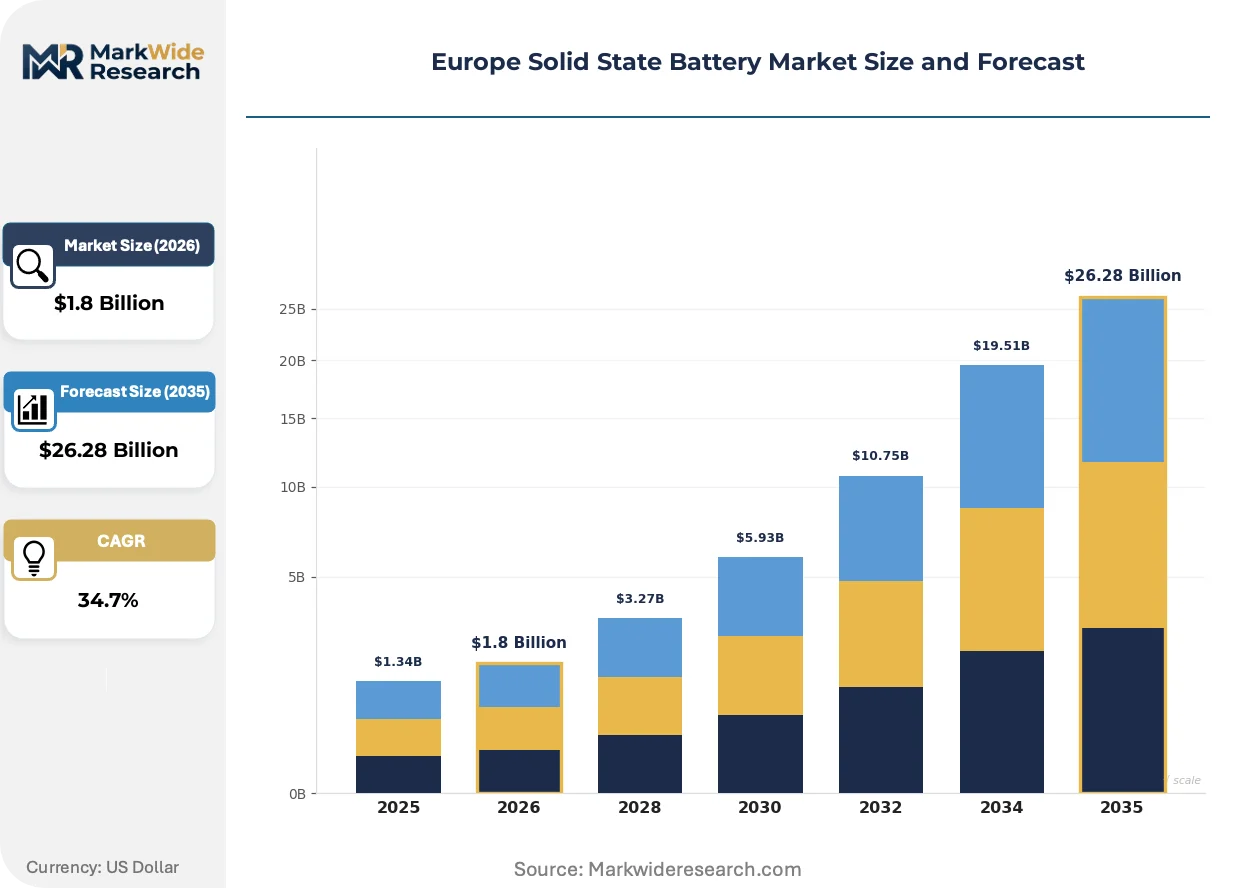
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $26.28 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin-Film Batteries, Lithium Metal Batteries, Solid Polymer Batteries, Composite Batteries Application: Consumer Electronics, Automotive, Aerospace, Industrial End User: Manufacturers, Original Equipment Manufacturers, Research Institutions, Component Suppliers Technology: Electrolyte Materials, Anode Materials, Cathode Materials, Cell Design |
| Companies Covered | Ilika plc, Robert Bosch GmbH, BlueSolutions, Schaeffler, Basquevolt, LionVolt, Samsung SDI Co., Ltd., Solvay SA, Saft, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Solid State Battery Market Trends and Innovations
Sulfide-based solid electrolytes are overtaking oxide platforms in automotive qualification programs, while polymer-ceramic composites capture industrial micro-battery niches. These chemistry shifts are restructuring materials supply chains and equipment vendor relationships across European manufacturing hubs.
Oxide ceramic electrolytes, traditionally favored for thermal stability, are decomposing into specialized applications where their brittleness is manageable. Medical device manufacturers in Switzerland adopt these materials for implantable sensors requiring absolute dendrite suppression. The structural consequence is decomposing the oxide segment into a premium-tier supply pool distinct from high-volume automotive chemistries.
The F-Gas Regulation restricts fluorinated compounds in electrolyte manufacturing processes, pushing developers toward sulfide and oxide formulations. Industrial consequence includes extended R&D timelines as firms reformulate around banned perfluorinated polymer binders. Automotive OEMs in Germany and France are responding by pre-qualifying sulfide-electrolyte suppliers ahead of 2027 platform launches.
Automotive OEMs now require suppliers to co-locate pilot lines near vehicle assembly plants, displacing centralized Asian cell manufacturing. This geographic tethering disrupts established lithium-ion procurement patterns. The shift is most visible in Germany, where BMW and Volkswagen have mandated solid-state supplier presence within 300 kilometers of Munich and Wolfsburg engineering centers.
Europe Solid State Battery Market Segmentation
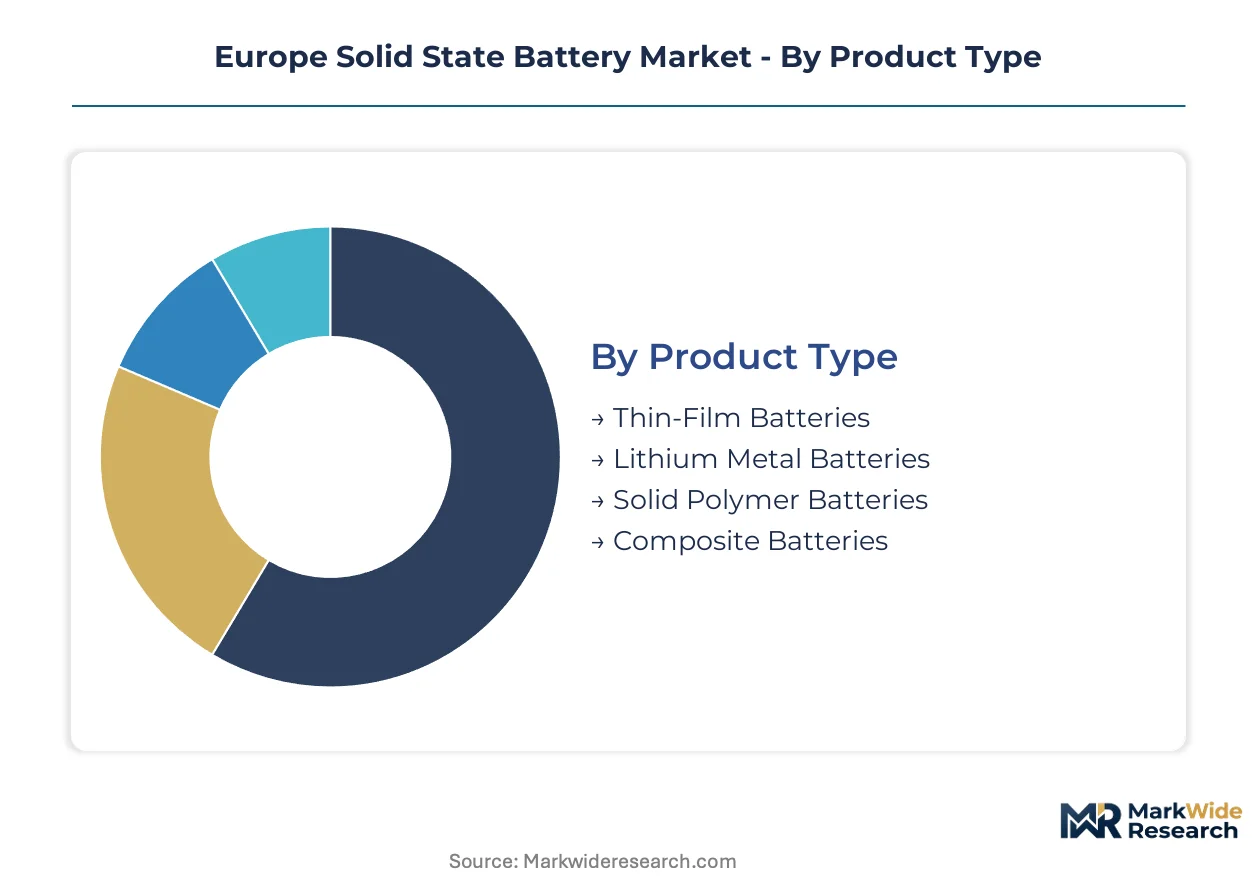
Segmentation in the Europe solid state battery market reveals divergent chemistry requirements across automotive qualification protocols and medical device safety standards. Each category carries distinct regulatory footprints that determine factory location and partnership structures.
Product Type:
REACH substance registration requirements and F-Gas Regulation compliance create tiered entry barriers across solid-state form factors, favoring chemistries that bypass fluorinated manufacturing processes.
- Thin-Film Batteries:Oxide ceramic electrolytes deposited via vacuum sputtering achieve sub-millimeter form factors for implantable medical devices. Swiss cardiac device manufacturers in the Lake Geneva corridor specify these cells for absolute dendrite suppression in pacemaker applications.
- Lithium Metal Batteries:Metallic lithium anodes paired with sulfide or oxide electrolytes deliver energy densities above 400 Wh/kg for electric vehicle propulsion. German automotive OEMs in Baden-Württemberg pre-qualify these cells for 800-volt platform integration under accelerated EU Green Deal timelines.
- Solid Polymer Batteries:Dry polymer electrolytes offer intermediate conductivity with simplified manufacturing humidity requirements. Industrial sensor networks in France evaluate these for moderate-temperature deployment.
- Composite Batteries:Ceramic-polymer hybrid electrolytes balance ionic conductivity with mechanical flexibility. Solvay SA specialty polymer supply chains dominate the materials interface for this segment.
Established volume favors lithium metal batteries; emerging adoption favors thin-film batteries.
Application:
End-use concentration in Germany's manufacturing corridors drives application-level procurement clustering around automotive and aerospace qualification centers.
- Consumer Electronics:Wearable device manufacturers in Finland and Sweden source micro-scale solid-state cells for extended cycle life in compact form factors. ECHA substance dossiers for lithium-metal anodes streamline cross-border component shipments.
- Automotive:BMW and Volkswagen engineering centers in Munich and Wolfsburg mandate supplier co-location within 300 kilometers. Sulfide electrolyte platforms dominate qualification programs for next-generation electric vehicle architectures.
- Aerospace:Munich-area satellite manufacturers specify solid-state power systems for orbital thermal cycling extremes. Bavaria's aerospace cluster generates localized demand for radiation-hardened cell designs.
- Industrial:Factory automation OEMs in Italy deploy solid-state backup power for robotic systems requiring maintenance-free operation across temperature extremes.
Automotive applications concentrate procurement volume; aerospace applications command premium pricing tiers.
End User:
Customer type determines contract structure, with automotive OEMs imposing multi-year qualification protocols that compress supplier cash conversion timelines.
- Manufacturers:Cell production specialists in Germany and France scale pilot lines to serve automotive platform integration. CE marking ambiguity under existing battery directive frameworks extends their approval cycles.
- Original Equipment Manufacturers:Vehicle and device assemblers pre-qualify suppliers before pilot production scales. Their procurement decisions concentrate around sulfide and oxide electrolyte platforms that satisfy F-Gas Regulation constraints.
- Research Institutions:University laboratories in the Netherlands and Belgium advance ceramic processing techniques for solid electrolyte interface engineering. EU funding programs support their pre-competitive materials development.
- Component Suppliers:Specialty chemical firms and equipment vendors supply electrolyte precursors and vacuum deposition tools. Japanese and Korean equipment vendors maintain 18-month order backlogs for oxide electrolyte manufacturing systems.
Original equipment manufacturers drive volume commitments; research institutions shape next-generation chemistry roadmaps.
Technology:
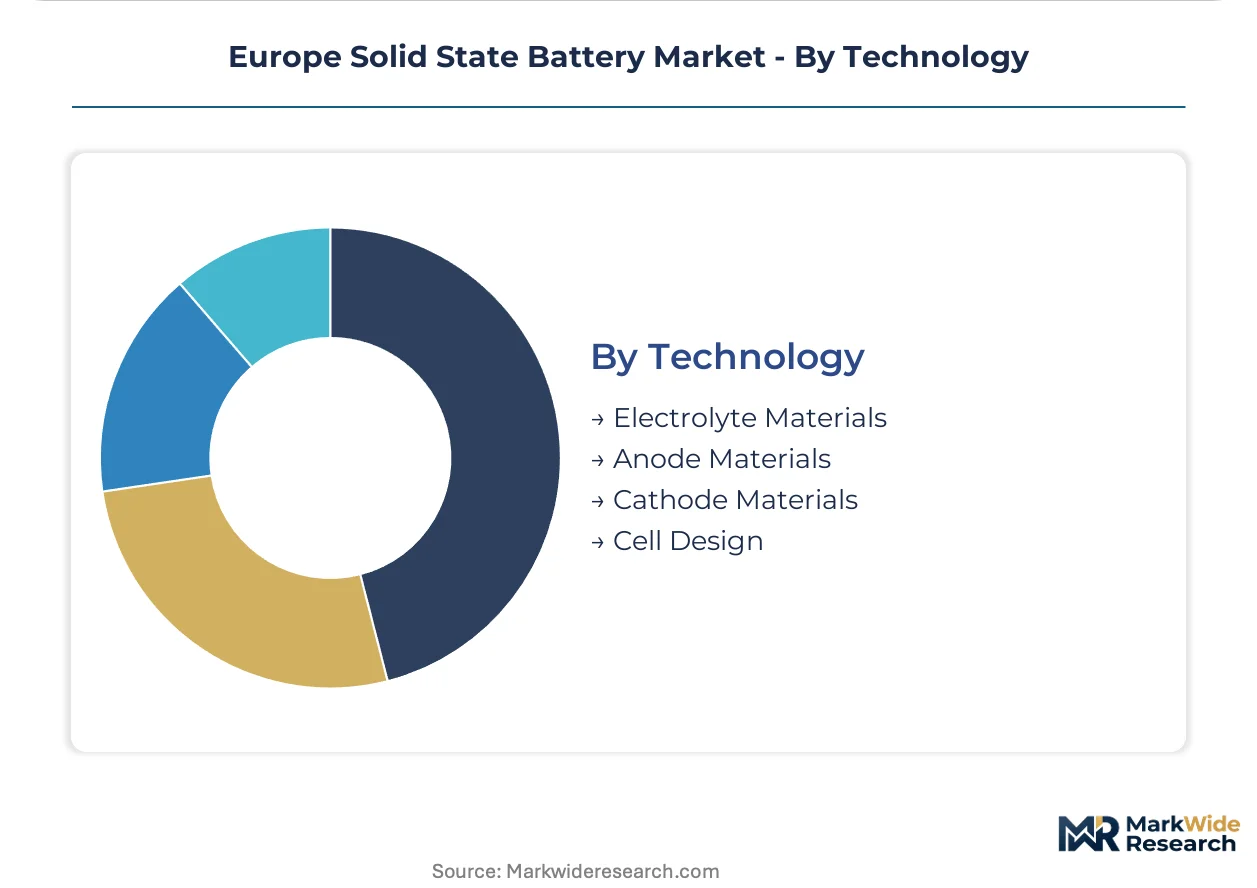
Materials specialization determines margin capture, with electrolyte formulations commanding the steepest technical differentiation.
- Electrolyte Materials:Sulfide glasses and oxide ceramics conduct lithium ions without flammable liquid components. Korean-European technology transfer agreements accelerate sulfide platform automotive integration timelines.
- Anode Materials:Lithium metal foils require battery-grade refining capacity concentrated at a single German supplier. This supply concentration creates qualification bottlenecks for scale players.
- Cathode Materials:High-nickel layered oxides and conversion-type cathodes pair with solid electrolytes for enhanced energy density. NCM and NCA chemistries adapt existing lithium-ion supply chains.
- Cell Design:Stacked and wound architectures accommodate solid-state mechanical constraints. Dry room infrastructure requirements for sulfide electrolyte manufacturing demand sub-1% humidity environments.
Electrolyte materials concentrate technical differentiation; cell design standardizes manufacturing scale economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs in Germany exhibit the lowest price elasticity, absorbing premium solid-state cell costs for 800-volt platform integration. French aerospace buyers and Swiss medical device manufacturers show intermediate sensitivity, while Italian industrial automation purchasers prioritize total cost of ownership over upfront cell pricing.
Germany
BMW and Volkswagen engineering centers in Munich and Wolfsburg mandate supplier co-location within 300 kilometers for just-in-time qualification batches. The KBA enforces automotive battery safety protocols that compress supplier approval timelines under EU Green Deal acceleration clauses. Baden-Württemberg's battery gigafactory corridor generates concentrated demand for sulfide-electrolyte pilot production.
France
Saft and aerospace OEMs in the Île-de-France region procure solid-state cells for satellite power systems requiring radiation hardening. ANSM medical device regulations align with MDR requirements for implantable battery biocompatibility. The Nouvelle-Aquitaine cluster hosts BlueSolutions manufacturing for industrial micro-battery applications.
United Kingdom
Ilika plc's Oxfordshire pilot facility serves medical implant manufacturers seeking absolute dendrite suppression in cardiac devices. The MHRA implements post-Brexit battery safety frameworks that diverge from CE marking pathways. Oxford-Cambridge Arc research institutions advance ceramic processing techniques for solid electrolyte interfaces.
Netherlands
LionVolt scales thin-film manufacturing for wearable electronics OEMs in the Eindhoven high-tech corridor. The Dutch Enterprise Agency channels national hydrogen and battery subsidies toward solid-state R&D consortia. Brainport Eindhoven's semiconductor equipment ecosystem supplies vacuum deposition tools for oxide electrolyte production.
Switzerland
Swiss cardiac device manufacturers in the Lake Geneva corridor specify oxide ceramic solid-state cells for pacemaker applications. Swissmedic enforces stringent biocompatibility standards that exceed baseline EU MDR requirements. Basel's pharmaceutical chemistry cluster generates cross-industry demand for specialty polymer electrolyte materials.
Europe Solid State Battery Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the European solid-state battery landscape. German automotive suppliers and Korean-European joint ventures anchor the upper tier through captive electrolyte material production and OEM qualification relationships. The middle tier comprises UK-based thin-film specialists, French industrial battery fabricators, and Dutch micro-battery scale-ups. Belgian chemical conglomerates and Swiss medical device suppliers occupy niche positions at the materials interface. Dominant competitive moves include backward integration into solid electrolyte precursor supply and geographic co-location mandates imposed by automotive OEMs.
Within the integrated automotive tier, Robert Bosch GmbH exemplifies deep backward integration into solid electrolyte materials and automotive qualification protocols. Samsung SDI Co., Ltd. occupies a Korean-European technology transfer position, leveraging pilot line presence to capture premium automotive supply slots. Ilika plc represents the thin-film specialist archetype, anchoring UK-based pilot manufacturing for medical and industrial micro-battery segments where absolute dendrite suppression commands priority pricing.
| Leading Market Players |
|---|
| Ilika plc |
| Robert Bosch GmbH |
| BlueSolutions |
| Schaeffler |
| Basquevolt |
| LionVolt |
| Samsung SDI Co., Ltd. |
| Solvay SA |
| Saft |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month order backlogs for vacuum deposition tools from Japanese and Korean vendors compress supplier cash conversion timelines and concentrate pricing power with equipment manufacturers. This lead-time constraint forces European solid-state battery developers to absorb premium capital costs or defer pilot line scaling, reshaping competitive positioning between thin-film specialists and lithium-metal scale players.
Pricing Analysis
After-sales service contracts and extended qualification support drive lifetime value for automotive OEM relationships. Three-tier pricing structure across premium, standard, and economy levels separates sulfide-electrolyte automotive cells from oxide ceramic medical implants and solid polymer industrial units. Cost compression in the standard tier is intensifying because Korean-European technology transfer agreements accelerate sulfide platform commoditization. Automotive OEMs in Baden-Württemberg exhibit the lowest price sensitivity, absorbing premium cell costs for 800-volt platform integration, while Italian industrial automation purchasers prioritize total cost of ownership over upfront pricing.
Supply Chain Analysis
Strategic stockpiling of lithium metal foil dominates inventory strategy given single-source refining concentration at one German supplier. Geographic supply concentration centers on Germany for electrolyte precursor chemicals, South Korea for sulfide glass manufacturing equipment, and Japan for vacuum deposition tools. Raw material dependencies rest on battery-grade lithium metal, ceramic oxide powders, and specialty polymer binders. Single-source vulnerability in lithium metal refining creates qualification bottlenecks for scale players. Distribution runs through direct OEM partnerships with co-location mandates within 300 kilometers of Munich and Wolfsburg engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PhD-level specialist shortages in ceramic processing for battery applications constrain manufacturing scale-up across European production hubs. This capability gap favors incumbents with captive materials expertise and challenges new entrants seeking rapid qualification.
For Market Incumbents: Fortify backward integration into solid electrolyte precursor supply chains to defend margin position against Korean-European joint ventures accelerating sulfide platform scale. Add dry room infrastructure capacity in Baden-Württemberg before 2027 platform launches concentrate demand. CE marking ambiguity under existing battery directive frameworks threatens approval timeline competitiveness. For New Entrants and Emerging Players: Lead with thin-film oxide ceramic specialization for Swiss cardiac device manufacturers where absolute dendrite suppression commands priority pricing and incumbent presence remains limited. Bavaria aerospace cluster demand for radiation-hardened satellite power systems offers underpenetrated entry point. Partner with Brainport Eindhoven semiconductor equipment ecosystem to bypass 18-month Japanese tool backlogs. For Investors and Strategic Acquirers: Long-term, this sits as a materials-chemistry consolidation play because electrolyte formulation IP determines margin capture in solid-state architectures. Target specialists with ECHA dossier completion for lithium-metal anodes and established automotive OEM qualification relationships. Watch sulfide-electrolyte automotive platform integration timelines as inflection indicator for manufacturing location decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrolyte Precursors | Captive sulfide glass supply secures automotive OEM qualification slots against Korean competitors. |
| Dry Room Infrastructure Expansion | Sub-1% humidity manufacturing capability unlocks sulfide platform scale in Baden-Württemberg corridor. |
| CE Marking Pathway Investment | Battery directive framework clarity accelerates approval cycles for German cell manufacturers. |
| Korean-European Technology Transfer | Pilot line presence captures premium supply relationships with BMW and Volkswagen engineering centers. |
| Medical Implant Partnership | Swiss cardiac device specifications for oxide ceramics open premium-tier revenue pools outside automotive. |
Research Methodology
A spread of perspectives from automotive platform engineers, solid electrolyte materials scientists, dry room infrastructure specialists, and ECHA regulatory affairs leads converged on the working assumptions driving chemistry roadmap conclusions. Primary interview insights combined with secondary validation from EU Green Deal policy documents, F-Gas Regulation compliance filings, REACH substance registration databases, and automotive OEM procurement disclosures. Bottom-up cell production capacity estimates and top-down electric vehicle platform integration timelines were triangulated to cross-check volume assumptions.
Segmentation dimensions modeled include electrolyte chemistry type, battery form factor, end-use application, and automotive OEM qualification status across the projection horizon. CAGRs were derived from production capacity buildout schedules and platform integration commitment timelines. Forecast inputs incorporated sulfide-electrolyte manufacturing yield assumptions and dry room capital cost trajectories specific to European facility construction.
The analysis sits within stated boundaries; outcomes outside accelerated EU Green Deal timeline enforcement or sustained lithium metal supply concentration would require recalibration. Forecasts reflect documented assumptions regarding automotive OEM co-location mandates and F-Gas Regulation chemistry constraints. Revision becomes warranted when Korean-European technology transfer agreement volumes cross thresholds that reshape sulfide platform commoditization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Li-Sulfur Battery Market
Lithium-ion Battery
Automotive Lithium-Sulfur Battery Market
Lithium-ion Battery
Italy Electric Vehicles Battery Anode Market
Lithium-ion Battery
Silicon Anode Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Polymer Battery Market
Lithium-ion Battery
Lithium-Ion Batteries Electric Bike Market
Lithium-ion Battery
Lithium Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Europe Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium Battery Pack Market
Lithium-ion Battery
Lithium-Ion Battery Wet-Process Separator Market
Lithium-ion Battery
Lithium Manganate Battery Market
Lithium-ion Battery
Graphite Anode for LIB Market
Lithium-ion Battery
China Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
North America Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium Ion Secondary Battery Sales Market
Lithium-ion Battery
UAV Lithium Battery Market