
 Lithium Iodide Market | 2026-2036
Lithium Iodide Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Iodide Market Outlook
EU battery passport mandates under the EU Green Deal is consolidating downstream traceability requirements for specialty lithium salts. Albemarle Corporation leverages its Chilean brine operations to sustain long-term iodide precursor availability. American Elements specializes in ultra-high-purity battery-grade formulations that anchor North American solid-state battery pilot lines. Leverton Lithium competes on European distribution reach for pharmaceutical-grade material.
Lithium iodide is an ionic salt composed of lithium and iodine with high ionic conductivity exceeding 10⁻³ S/cm at room temperature, manufactured through direct reaction of lithium metal or lithium carbonate with hydroiodic acid followed by crystallization and drying. Its primary purpose centers on serving as a solid electrolyte component in next-generation batteries and as a reagent in organic synthesis and pharmaceutical manufacturing. Battery-grade material commands the dominant volume position given solid-state battery development timelines, while pharmaceutical-grade applications retain the strongest margin profile due to stringent purity certification requirements. Energy storage applications are expanding fastest as cylindrical and prismatic cell formats incorporate iodide-doped electrolyte architectures.
FDA pharmaceutical purity standards, EPA hazardous substance reporting under TSCA, and REACH registration requirements in Europe collectively shape product specifications and market access conditions for lithium iodide suppliers. China's SAMR enforces GB standards for battery material safety that directly influence export qualification protocols. Stakeholders must monitor solid-state battery commercialization milestones and evolving pharmaceutical excipient regulations to align capacity investments with demand timing.
Market Dynamics
Solid-state battery commercialization timelines are compressing procurement cycles for battery-grade lithium iodide, forcing electrolyte salt suppliers to pre-qualify material streams years ahead of cell production ramp-ups.
Growth Catalysts
- South Korean cathode integration:Domestic suppliers are embedding iodide-based solid electrolytes into NCM precursor manufacturing, creating captive demand for high-purity lithium iodide feedstock.
- China's GB standards:SAMR-enforced energy storage safety protocols now mandate iodide-doped electrolyte architectures in grid-scale battery deployments, accelerating qualification requirements.
- EU battery passport mandates:Downstream traceability requirements under the EU Green Deal are consolidating specialty lithium salt procurement around certified supply chains.
Market Restraints
- Iodine feedstock volatility:Chilean caliche ore and Japanese brine extraction dominate global iodine supply, exposing lithium iodide producers to concentrated geographic risk.
- REACH registration friction:ECHA substance evaluation timelines for lithium iodide are extending market access lead times for European battery material entrants.
- Sulfide electrolyte substitution:Argyrodite and LGPS-type solid electrolytes are displacing iodide-based formulations in certain automotive cell architectures.
Strategic Opportunities
- Pharmaceutical excipient expansion:FDA-certified lithium iodide for organic synthesis reagents commands margin premiums above battery-grade material.
- Indian PLI scheme alignment:Domestic cell manufacturing incentives are creating first-mover advantage for iodide precursor localization.
- Solid-state flow battery convergence:Hybrid electrochemical systems pairing iodide catholytes with lithium metal anodes are opening stationary storage applications.
Industry Challenges
- Battery-grade certification timelines:OEM qualification protocols for solid-state cell integration require 18-24 month validation cycles.
- Electrolyte integration complexity:Iodide salt handling protocols clash with existing sulfide and oxide electrolyte manufacturing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Iodide Market |
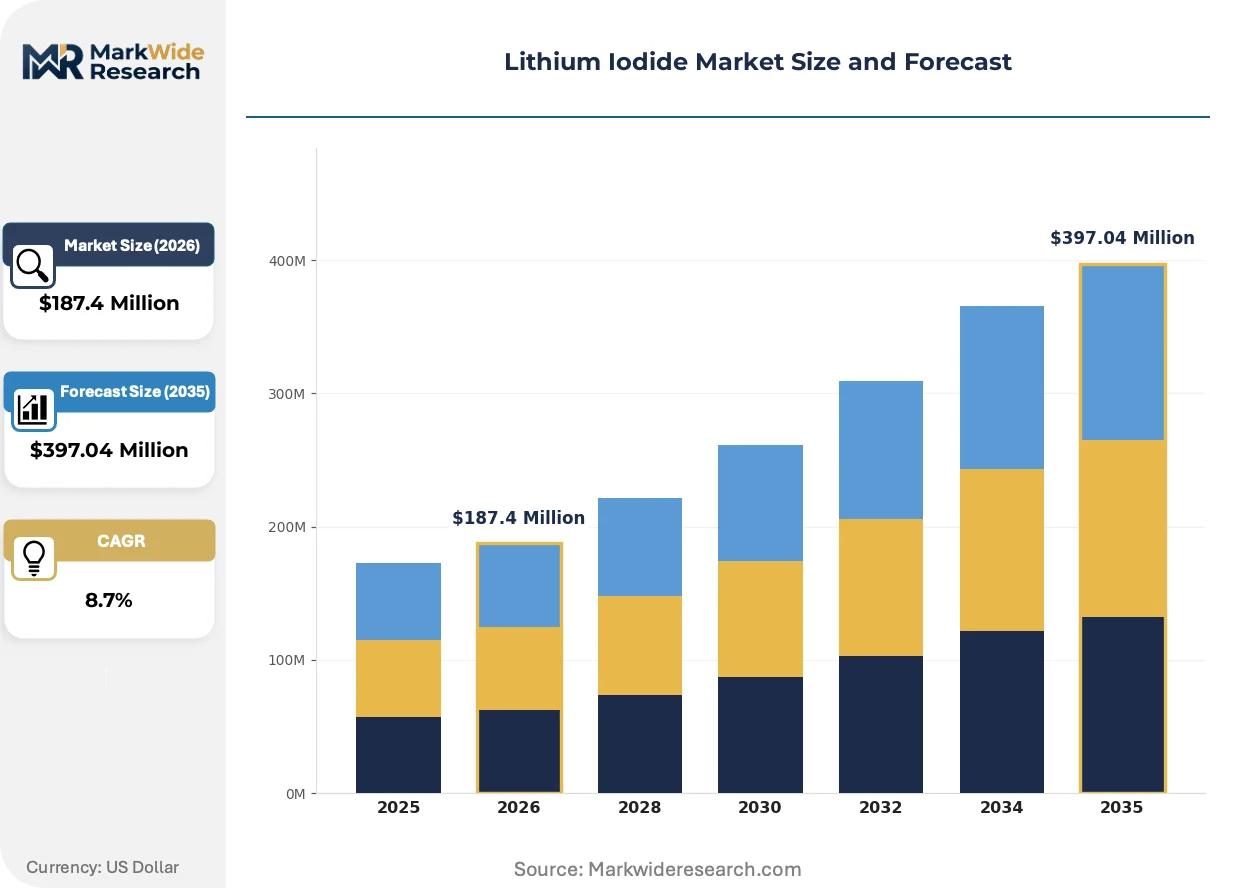
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Grade, Technical Grade, Pharmaceutical Grade, Industrial Grade End User: Aerospace, Electronics, Healthcare, Renewable Energy Application: Pharmaceuticals, Energy Storage, Photographic Film, Chemical Synthesis Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Albemarle Corporation, American Elements, Leverton Lithium, Shanghai China Lithium, Triveni Chemicals, Merck KGaA, Shanghai Oujin Lithium, Samrat Pharmachem, Nanjing Taiye Chemical Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Iodide Market Strategic Shifts
Electrolyte architecture evolution is fragmenting material specifications across automotive, grid storage, and consumer electronics verticals, forcing suppliers to maintain parallel product development tracks.
Argentum-stabilized lithium iodide composites are integrating into ceramic-polymer hybrid electrolyte matrices for cylindrical cell formats. South Korean cathode material producers are adopting these formulations at pilot scale, compressing the timeline for solid-state battery commercialization. This integration is enabling thinner separator designs while maintaining ionic conductivity thresholds above 10⁻³ S/cm.
China's dual carbon policy framework is accelerating GB standard revisions for energy storage safety, directly influencing iodide-based electrolyte qualification protocols. SAMR enforcement of updated battery material specifications is redirecting domestic procurement toward certified precursor suppliers. Cell manufacturers in Shenzhen and Ningbo are restructuring supply agreements to accommodate these regulatory timelines.
Long-term offtake contracting is displacing spot market purchasing for battery-grade lithium iodide. Solid-state battery developers are locking in multi-year supply commitments directly with precursor manufacturers, bypassing traditional chemical distributor channels. This pattern is most visible in East Asian manufacturing clusters, where cathode integrators are securing captive iodide streams ahead of production scale-up.
Lithium Iodide Market Segmentation
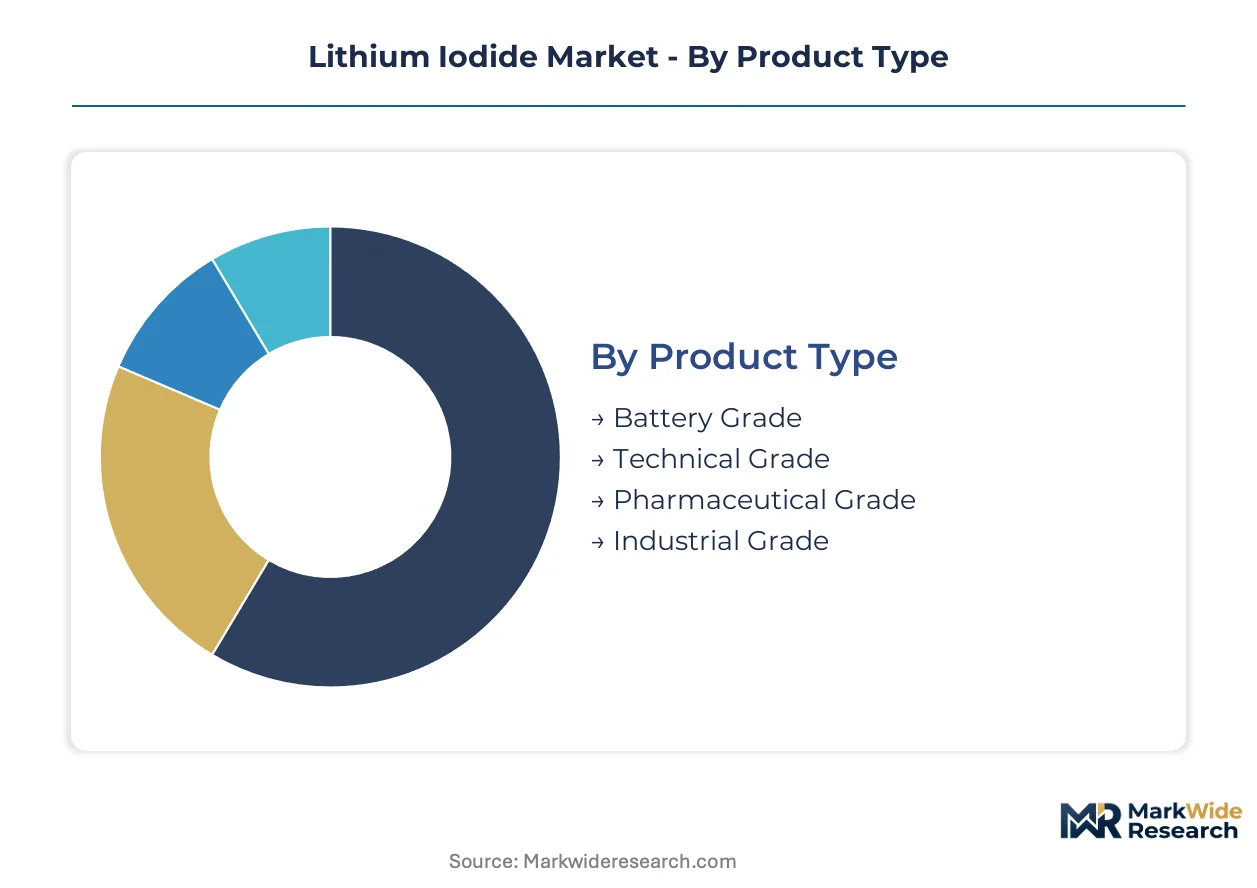
Segmentation in lithium iodide tracks divergent purity standards and handling protocols across battery chemistry and pharmaceutical synthesis applications. Specification thresholds separate commodity industrial material from certified battery-grade and pharmaceutical-grade streams with distinct margin structures and qualification timelines.
Product Type:
Product grade specifications determine ionic conductivity thresholds, impurity ceilings, and downstream qualification pathways across solid-state battery and pharmaceutical applications.
- Battery Grade:Material achieves ionic conductivity exceeding 10⁻³ S/cm at room temperature through controlled crystallization and drying protocols. South Korean cathode integrators in Seoul and Suwon are locking in multi-year offtake agreements with precursor manufacturers to secure feedstock ahead of solid-state cell production ramp-ups.
- Pharmaceutical Grade:FDA-certified formulations for organic synthesis reagents command stringent purity certification requirements and the strongest margin profile in the category. Demand concentrates in North American and European pharmaceutical manufacturing clusters where excipient regulations enforce batch-level traceability.
- Technical Grade:Intermediate purity material serves specialized chemical synthesis and laboratory applications with reduced certification overhead.
- Industrial Grade:Standard purity lithium iodide addresses bulk chemical processing and general industrial reagent demand with minimal qualification requirements.
Battery Grade leads on scale; Pharmaceutical Grade leads on momentum.
End User:
End-use concentration reflects divergent procurement cycles between aerospace qualification protocols and renewable energy storage deployment timelines.
- Renewable Energy:Grid-scale battery deployments in Shenzhen and Ningbo are restructuring supply agreements to accommodate SAMR-enforced GB standard revisions for energy storage safety. Cylindrical and prismatic cell formats incorporating iodide-doped electrolyte architectures are expanding procurement volumes fastest.
- Healthcare:Pharmaceutical manufacturing relies on certified excipient streams with batch-level documentation for organic synthesis applications. FDA enforcement of pharmaceutical purity standards maintains rigid supplier qualification barriers.
- Electronics:Consumer device battery developers are piloting solid-state cell formats with iodide-based electrolyte matrices for thinner separator designs.
- Aerospace:Specialized battery systems for aviation applications require extended qualification cycles and customized material specifications.
Renewable Energy leads on scale; Healthcare leads on momentum.
Application:
Application segmentation tracks the shift from legacy photographic demand toward electrochemical storage and pharmaceutical synthesis.
- Energy Storage:Solid-state battery developers are compressing procurement cycles and pre-qualifying material streams years ahead of cell production ramp-ups. Argentum-stabilized lithium iodide composites are integrating into ceramic-polymer hybrid electrolyte matrices for cylindrical cell formats at pilot scale in South Korean manufacturing clusters.
- Pharmaceuticals:Organic synthesis reagents demand ultra-high-purity formulations with comprehensive certification documentation. American Elements anchors North American supply for pharmaceutical-grade material serving FDA-regulated manufacturing.
- Chemical Synthesis:Laboratory and industrial reagent applications maintain steady demand for technical-grade material with moderate purity requirements.
- Photographic Film:Legacy silver halide photography applications represent declining demand concentration as digital imaging displaces chemical processing.
Energy Storage leads on scale; Pharmaceuticals leads on momentum.
Distribution Channel:
Channel structure is shifting as long-term offtake contracting displaces traditional distributor relationships for battery-grade material.
- Direct Sales:Solid-state battery developers are locking in multi-year supply commitments directly with precursor manufacturers, bypassing traditional chemical distributor channels. This pattern concentrates in East Asian manufacturing clusters where cathode integrators secure captive iodide streams.
- Distributors:Leverton Lithium competes on European distribution reach for pharmaceutical-grade material, maintaining inventory positions for qualified suppliers.
- Wholesalers:Bulk material movement for industrial-grade applications continues through established chemical wholesale networks.
- Online Retail:Small-volume laboratory and research procurement accesses technical-grade material through specialized chemical supply platforms.
Direct Sales leads on scale; Distributors leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chilean caliche ore deposits established the foundational iodine supply chain that enabled lithium iodide production scaling in the 1960s. This geological endowment concentrated precursor extraction in the Atacama Desert region before downstream processing expanded to East Asian battery manufacturing clusters.
China
Shenzhen and Ningbo cell manufacturers are restructuring supply agreements to accommodate SAMR-enforced GB standard revisions for energy storage safety. The dual carbon policy framework accelerates domestic qualification requirements for iodide-doped electrolyte architectures. Battery material suppliers in these coastal manufacturing hubs are securing captive precursor streams ahead of production scale-up.
South Korea
Seoul and Suwon cathode integrators are embedding iodide-based solid electrolytes into NCM precursor manufacturing, creating captive demand for high-purity lithium iodide feedstock. MFDS pharmaceutical regulations maintain parallel certification pathways for excipient-grade material. Domestic solid-state battery pilot lines are compressing procurement cycles for battery-grade formulations.
United States
North American solid-state battery developers are pre-qualifying material streams years ahead of cell production ramp-ups under EPA hazardous substance reporting protocols. FDA pharmaceutical purity standards anchor excipient demand in Boston and New Jersey pharmaceutical manufacturing clusters. American Elements positions ultra-high-purity formulations to serve these dual application verticals.
Germany
REACH registration requirements at ECHA are extending market access lead times for battery material entrants targeting European solid-state cell manufacturers. Leverton Lithium competes on distribution reach for pharmaceutical-grade material across the continent. Bavarian and North Rhine-Westphalian chemical processing hubs are restructuring procurement around certified supply chains.
Japan
Japanese brine extraction operations in Chiba and Miyazaki prefectures supplement Chilean caliche ore as secondary iodine feedstock for domestic lithium iodide production. METI industrial policy supports solid-state battery R&D timelines that compress electrolyte salt procurement cycles. Osaka-based chemical processors are integrating iodide precursors into ceramic-polymer hybrid electrolyte matrices.
Lithium Iodide Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the lithium iodide value chain, creating a tiered market structure where integrated brine operators face specialized chemical processors. The vendor base separates into three strategic archetypes: upstream-integrated miners with captive iodine streams, midstream specialty chemical formulators, and downstream battery material distributors. Consolidation pressure concentrates among brine-based producers while fragmentation persists in pharmaceutical-grade formulation. Dominant competitive moves include backward integration into iodine extraction and multi-year offtake contracting that bypasses traditional distributor channels.
Among North American specialty chemical suppliers, American Elements exemplifies the ultra-high-purity formulation archetype, while Albemarle Corporation anchors the upstream-integrated tier with Chilean brine operations. Leverton Lithium occupies a position within the European distribution-focused segment, competing on reach rather than manufacturing scale. These three players represent distinct strategic postures across the value chain without overlapping core competencies.
| Leading Market Players |
|---|
| Albemarle Corporation |
| American Elements |
| Leverton Lithium |
| Shanghai China Lithium |
| Triveni Chemicals |
| Merck KGaA |
| Shanghai Oujin Lithium |
| Samrat Pharmachem |
| Nanjing Taiye Chemical Industry |
| Others |
Value Chain & Pricing Dynamics
Upstream-integrated brine operators with sovereign-backed financing structures anchor supply-side discipline, translating captive iodine access into pricing power over specialty chemical formulators who must negotiate feedstock terms on volatile spot markets.
Pricing Analysis
Contract-based long-term offtake agreements dominate battery-grade procurement, separating certified pharmaceutical streams from industrial-grade spot transactions. Price differentiation rests on FDA certification tier and volume scale commitments, with pharmaceutical-grade material commanding substantial premiums over technical formulations. Cost compression in battery-grade supply is intensifying because South Korean cathode integrators are consolidating procurement around qualified precursors. Spot-market buyers in laboratory applications exhibit highest price sensitivity, while solid-state battery developers under OEM qualification timelines show least sensitivity due to multi-year validation requirements.
Supply Chain Analysis
Dual-sourcing requirements from cell manufacturers are forcing qualification of Chilean and Japanese iodine feedstock streams simultaneously. Supply draws from Chilean caliche ore extraction, Japanese brine operations in Chiba and Miyazaki prefectures, and emerging Indian chemical processing capacity. Raw material dependencies center on elemental iodine, lithium carbonate or metal feedstock, and hydroiodic acid reagents. Single-source vulnerability concentrates in Atacama Desert caliche deposits, where climatic disruptions or export restrictions would cascade through downstream battery material supply. Distribution runs through direct manufacturer relationships for battery-grade material, bypassing traditional chemical distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lithium iodide market compounds steadily as solid-state battery commercialization timelines compress procurement cycles into multi-year locked commitments. This structural shift toward captive supply agreements underpins predictable revenue visibility for qualified producers.
For Market Incumbents: Deploy backward integration into iodine extraction to secure feedstock margin control against Chilean caliche price volatility. Incumbent producers should simultaneously deepen SAMR GB standard certification investments to defend qualification status against sulfide electrolyte substitution threats from argyrodite and LGPS-type formulations. Captive precursor streams and regulatory compliance together form the defensive perimeter.
For New Entrants and Emerging Players: Specialty chemical distributors in European pharmaceutical corridors represent the most accessible channel partnership archetype for market entry. White-space targets concentrate on FDA-certified excipient formulations for North American organic synthesis applications, where American Elements' ultra-high-purity positioning leaves mid-tier purity gaps. Indian PLI scheme alignment for domestic cell manufacturing incentives offers parallel entry vector through precursor localization partnerships.
For Investors and Strategic Acquirers: Valuations sit cheapest among midstream specialty chemical formulators lacking captive iodine access but holding pharmaceutical-grade certification infrastructure. Five-to-ten year viability favors producers with dual battery-pharma revenue streams that buffer against solid-state electrolyte technology shifts. The signal to watch is South Korean cathode integrator announcement of captive iodide stream partnerships, which would mark inflection toward supply scarcity for independent precursor suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Iodine Extraction | Captive Atacama caliche access insulates Albemarle Corporation from feedstock price volatility. |
| Multi-year Offtake Contracting | Direct supply commitments from Seoul cathode integrators compress traditional distributor margins. |
| Pharmaceutical-grade Certification Investment | FDA excipient qualification opens margin-premium revenue streams for organic synthesis reagents. |
| GB Standard Alignment | SAMR energy storage safety protocols redirect Shenzhen procurement toward certified precursor suppliers. |
| Joint Venture for Indian Localization | PLI scheme partnerships create first-mover positioning in domestic cell manufacturing supply chains. |
Study Parameters
Multiple input streams — primary interviews with solid-state battery R&D directors, pharmaceutical procurement managers, and specialty chemical plant operators; secondary validation through SEC filings, customs trade databases, and SAMR GB standard documentation; plus ECHA REACH registration tracking — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured qualification timeline data from South Korean cathode integrators and Shenzhen cell manufacturers. Secondary sources included Chilean mining ministry production statistics, Japanese METI industrial policy briefings, and FDA pharmaceutical excipient certification records.
Data-stream reconciliation across the projection horizon applied analytical frameworks modeling grade tier, end-use application, and regional regulatory cluster dimensions. CAGRs were derived through segment-level growth rate synthesis and cross-validation against upstream iodine demand forecasts. Industry-specific inputs incorporated solid-state battery pilot line deployment schedules and pharmaceutical manufacturing capacity expansion announcements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to sulfide electrolyte substitution rates and Chilean caliche export policy shifts. Deviation in SAMR enforcement intensity for GB standard compliance would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
LAMEA Solid State Battery Market
Lithium-ion Battery
Lithium-Sulfur Battery Market
Lithium-ion Battery
EV SOLID State Battery Market
Lithium-ion Battery
Europe Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium Battery Wet Separator Market
Lithium-ion Battery
Marine Lithium-Ion Battery Market
Lithium-ion Battery
Manganese Dioxide Lithium Battery Market
Lithium-ion Battery
Sodium-Ion Battery Market
Lithium-ion Battery
France Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Global Next Generation Batteries Market
Lithium-ion Battery
Lithium Ion Secondary Battery Sales Market
Lithium-ion Battery
Solid Electrolyte for Lithium Ion Battery Market
Lithium-ion Battery
Cylindrical Lithium-Ion Battery Market
Lithium-ion Battery
Silicon Anode Lithium-Ion Battery Market
Lithium-ion Battery
Lithium-Air Battery Market
Lithium-ion Battery
United Kingdom Lithium-Ion Battery for Electric Vehicle Market