
 Lifepo4 Battery Market | 2026-2036
Lifepo4 Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Lifepo4 Battery Market Insights
Multi-source cathode procurement is consolidating around vertically integrated Chinese suppliers. CATL leverages captive lithium refining and phosphate mining to control raw material costs across its prismatic cell lines. BYD sustains in-house cathode production at its Shenzhen and Xining plants, insulating margin pools from spot lithium volatility. Panasonic Energy competes through joint-venture partnerships with automotive OEMs in Japan and North America, though it remains dependent on external cathode offtake agreements.
Lithium iron phosphate batteries employ an olivine-structured cathode with nominal voltage of 3.2V and cycle life exceeding 3,000 charge-discharge events at 80% depth of discharge, serving applications where thermal stability and cost per kilowatt-hour outweigh energy density requirements. Prismatic cells dominate electric vehicle traction packs due to superior pack-level volumetric efficiency and structural integration with battery management systems. Energy Storage Systems represent the fastest-growing application segment as utility-scale developers prioritize four-to-eight hour duration configurations with minimal degradation over fifteen-year operational lifespans.
FCC safety standards govern stationary energy storage installations across the United States, while China's GB standards mandate nail penetration and overcharge tolerance testing for cells deployed in commercial vehicles. The EU Battery Regulation introduces digital passport requirements and recycled content thresholds that will reshape supply chain documentation and material recovery obligations. Stakeholders must monitor evolving certification timelines across these jurisdictions to align product qualification cycles with customer procurement windows.
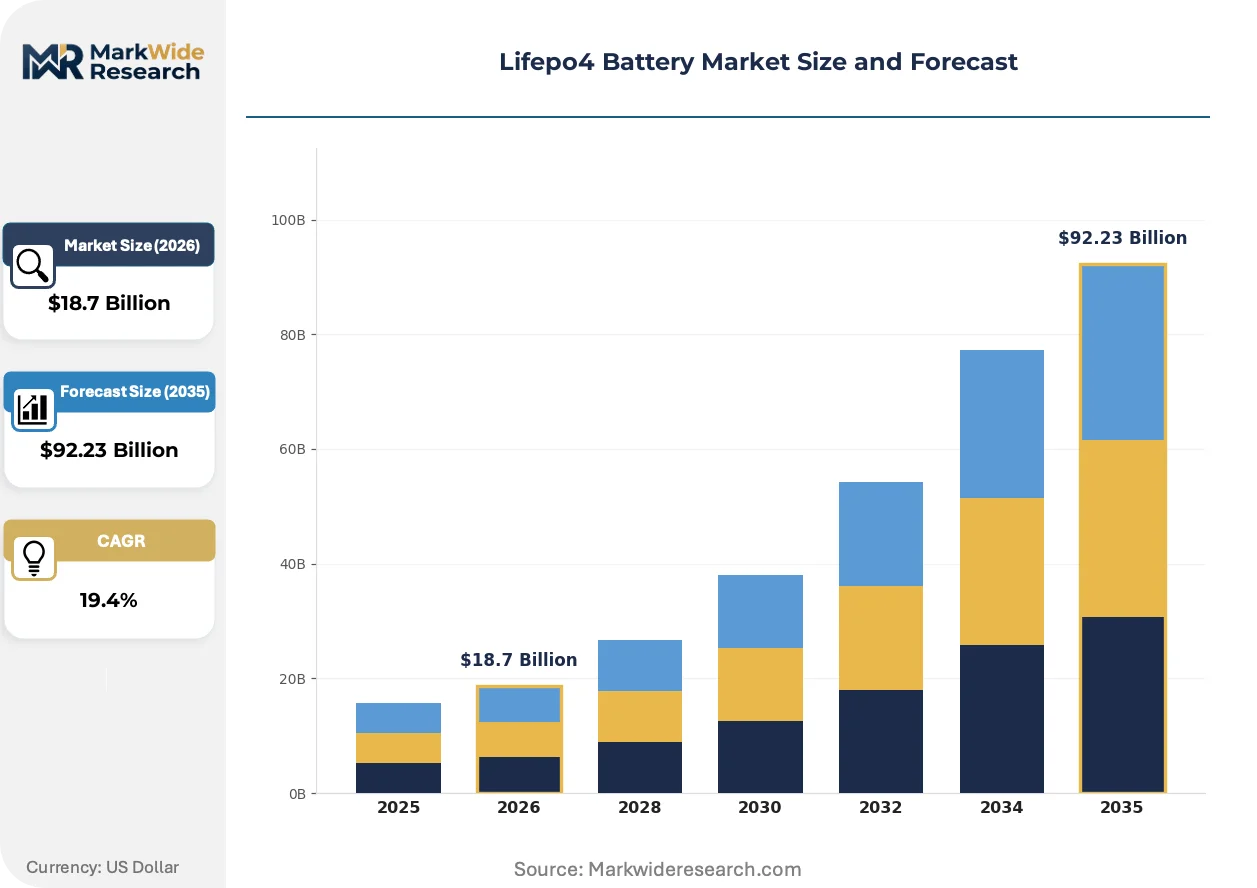
Market Dynamics
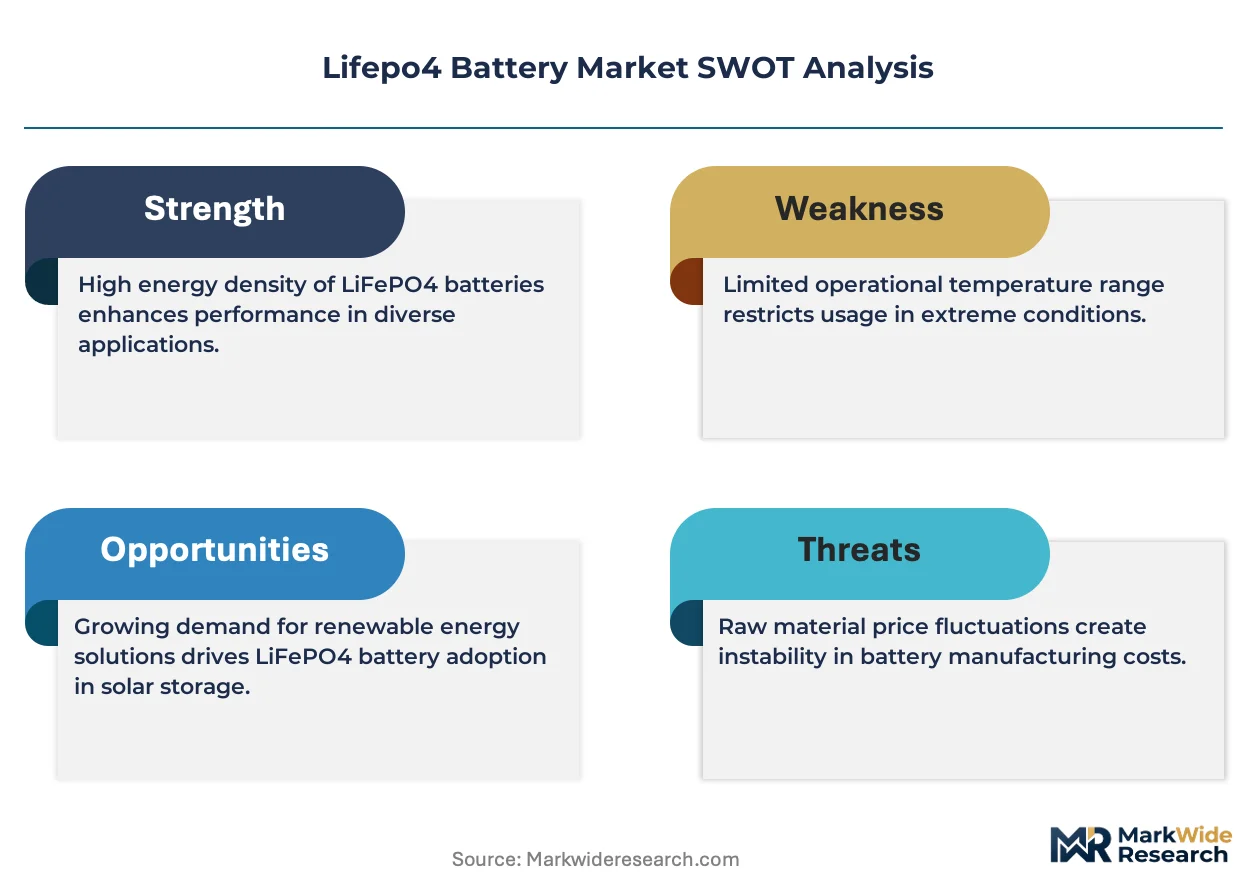
Prismatic cell architectures are consolidating procurement power around cathode precursor clusters in Jiangsu and Fujian, compressing logistics costs and qualification timelines for electric vehicle pack integrators.
Growth Catalysts
- EU Battery Regulation:Digital passport mandates and recycled content thresholds are forcing supply chain documentation upgrades, advantaging early-compliant cell producers in European fleet procurement.
- Utility-scale storage:Four-to-eight hour duration configurations with fifteen-year operational lifespans are displacing gas peakers in grid interconnection queues across multiple jurisdictions.
- Phosphate mining integration:Captive lithium refining and cathode precursor production within 200 kilometers of gigafactories is compressing raw material cost volatility for prismatic cell lines.
Market Restraints
- Lithium carbonate spot volatility:Cathode precursor pricing swings transfer directly to cell bill-of-materials, compressing margin pools for non-integrated pack assemblers.
- Jiangsu-Fujian supply concentration:Overreliance on China's eastern manufacturing corridor creates geopolitical and logistics contingency exposure for non-Chinese automotive OEMs.
- Energy density ceiling:Olivine-structured cathodes cap pack-level gravimetric performance, excluding lithium iron phosphate from premium electric vehicle segments requiring maximum range.
Strategic Opportunities
- India stationary storage:CEA mandates and state-level renewable purchase obligations are opening procurement windows for containerized battery systems in grid-scale deployments.
- Second-life automotive packs:Retired electric vehicle traction batteries with residual cycle capacity are converging with behind-the-meter commercial applications, creating circular material flows.
- North American IRA incentives:Domestic content credits are pulling cathode active material production toward integrated cell manufacturing in the United States and Canada.
Industry Challenges
- GB standards compliance timelines:Nail penetration and overcharge tolerance testing for commercial vehicle cells extends product qualification cycles, compressing customer procurement windows.
- Pack-BMS integration complexity:Prismatic cell structural bonding with battery management systems requires specialized thermal runaway modeling capabilities scarce outside tier-one integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lifepo4 Battery Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic, Cylindrical, Pouch, Large Format Application: Electric Vehicles, Energy Storage Systems, Power Tools, Consumer Electronics End User: Residential, Commercial, Industrial, Utility Installation: Fixed, Portable, Integrated, Customizable |
| Companies Covered | CATL, BYD, EVE Energy, LG Energy Solution, CALB, Gotion High-Tech, A123 Systems, Panasonic Energy, Samsung SDI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lifepo4 Battery Market Trends and Innovations
Cell-to-pack architectures are eliminating module-level components, compressing pack mass and assembly cost while demanding new thermal management and structural bonding competencies from integrators.
Dry electrode coating is expanding into prismatic cell production lines, eliminating solvent-based slurry processing and reducing drying energy consumption by half. European gigafactory operators are piloting the transition to compress capex intensity and environmental permitting timelines. The technology is expanding into markets where carbon footprint disclosure requirements are tightening procurement specifications.
China's GB standards for commercial vehicle battery safety are mandating nail penetration tolerance and overcharge survival testing at cell level. The regulations are disqualifying legacy cobalt-based chemistries from bus and logistics fleet procurement, tilting supplier qualification toward lithium iron phosphate architectures. Domestic manufacturers with in-house testing laboratories are compressing certification cycles versus import-dependent competitors.
Fleet operators are consolidating cell procurement through direct long-term offtake agreements, disintermediating traditional distributor networks and demanding pack-level performance guarantees. Logistics operators with predictable route profiles are prioritizing cycle life and thermal stability over energy density, compressing supplier margins on premium cobalt-nickel alternatives. This pattern is most visible in European and North American commercial electric vehicle deployments where total cost of ownership modeling dominates capital allocation decisions.
Lifepo4 Battery Market Segmentation
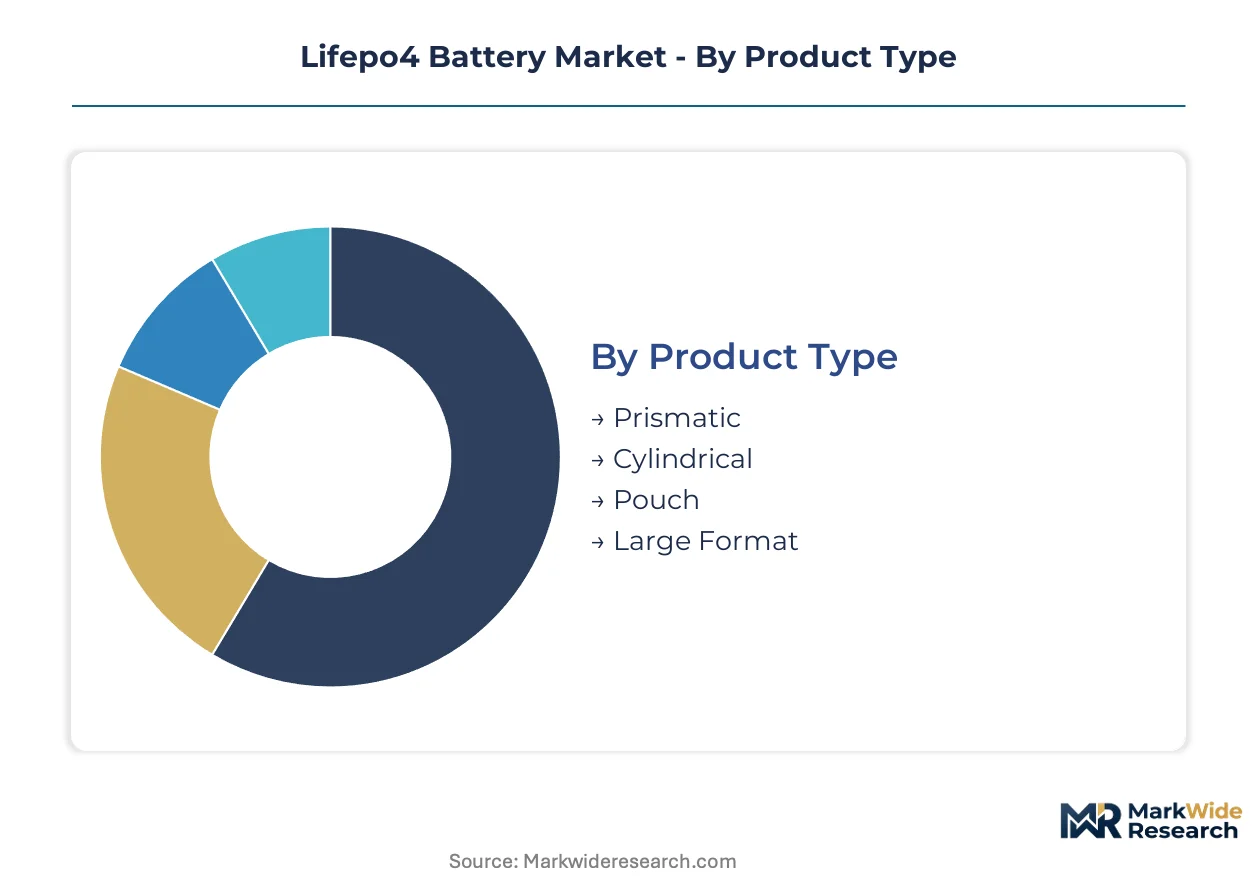
Cell geometry and application requirements create divergent procurement patterns across the lithium iron phosphate value chain. Buyers prioritize thermal stability, cycle life, and pack integration compatibility over energy density in most volume segments.
Product Type:
Cost tier separates mass-market buyers from specialized integrators seeking form-factor flexibility.
- Prismatic:Rectangular aluminum-cased cells with superior volumetric packing efficiency and structural rigidity dominate electric vehicle traction packs. Jiangsu and Fujian manufacturing corridors concentrate supply within 200 kilometers of cathode precursor facilities, compressing logistics costs for automotive OEMs.
- Cylindrical:Rolled electrode assemblies with standardized diameters suit power tool and consumer electronics applications requiring mechanical durability and automated assembly compatibility. Demand clusters in high-volume manufacturing hubs serving cordless equipment brands.
- Pouch:Flexible polymer-laminated enclosures maximize gravimetric energy density for weight-constrained applications. Cell-to-pack architectures are eliminating module-level components, demanding new thermal bonding competencies.
- Large Format:Oversized single-cell designs reduce interconnection complexity in containerized energy storage systems. Utility-scale developers prioritize four-to-eight hour duration configurations with minimal degradation over fifteen-year operational lifespans.
Volume sits with prismatic architectures; growth tilts toward large format cells for stationary storage.
Application:
End-use durability requirements determine cathode specification and cell qualification intensity.
- Electric Vehicles:Commercial logistics fleets prioritize cycle life exceeding 3,000 charge-discharge events at 80% depth of discharge. China's GB standards mandate nail penetration and overcharge tolerance testing, disqualifying legacy cobalt-based chemistries from bus procurement.
- Energy Storage Systems:Grid-scale and behind-the-meter installations demand fifteen-year operational lifespans with predictable degradation curves. India's CEA mandates and state-level renewable purchase obligations are opening procurement windows for containerized systems.
- Power Tools:High-discharge-rate cylindrical cells serve professional cordless equipment requiring mechanical shock resistance. OEMs specify JIS standards compliance for Japanese market access.
- Consumer Electronics:Low-cost pouch and cylindrical formats power portable devices with moderate cycle requirements. Safety certification under IEC and UN transportation regulations governs cross-border shipment eligibility.
Revenue concentrates in electric vehicle traction; expansion accelerates most quickly in utility-scale storage.
End User:
Customer scale determines procurement channel structure and performance guarantee requirements.
- Residential:Behind-the-meter solar-plus-storage installations in Germany and Australia drive demand for compact wall-mounted systems. Homeowners prioritize warranty terms and installer network density over upfront cost minimization.
- Commercial:Retail and logistics facilities deploy peak-shaving systems to manage demand charges. Second-life automotive packs with residual cycle capacity are converging with this segment, creating circular material flows.
- Industrial:Manufacturing campuses require uninterrupted power supply configurations with fast-response capability. FCC safety standards govern stationary installations across the United States.
- Utility:Transmission operators procure multi-megawatt containerized arrays for grid stabilization and renewable firming. Long-term offtake agreements disintermediate traditional distributor networks.
Contract value peaks with utility deployments; customer count expands fastest in residential segments.
Installation:
Integration depth shapes supplier technical support obligations and margin structure.
- Fixed:Permanently mounted rack and container systems dominate utility and industrial deployments. Pack-BMS integration complexity requires specialized thermal runaway modeling capabilities.
- Portable:Mobile power stations and recreational vehicle applications prioritize ruggedized enclosures and rapid deployment. European outdoor equipment brands specify IP ratings and CE marking compliance.
- Integrated:OEM-embedded designs in electric vehicles and industrial machinery demand collaborative engineering programs. Direct long-term offtake agreements consolidate procurement power with fleet operators.
- Customizable:Modular architectures allowing voltage and capacity reconfiguration serve specialized industrial and defense applications. Low-volume production runs sustain premium pricing against standardized alternatives.
Shipment volume favors fixed installations; margin expansion concentrates in customizable configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium phosphate deposits and captive refining capacity in Jiangsu and Fujian anchor China's dominance in cathode precursor supply. These eastern manufacturing corridors compress logistics costs for prismatic cell producers serving electric vehicle and stationary storage demand. Geographic diversification remains limited as alternative production centers struggle to match integrated feedstock access.
China
Commercial logistics fleets and utility-scale developers drive procurement volumes for prismatic and large-format cells. GB standards from MIIT mandate nail penetration and overcharge tolerance testing, disqualifying legacy cobalt-based chemistries from bus procurement. Jiangsu and Fujian provinces concentrate gigafactory capacity within 200 kilometers of cathode precursor facilities, compressing qualification timelines for automotive OEMs.
United States
Grid interconnection queues and renewable firming requirements accelerate utility-scale storage deployments. IRA domestic content credits pull cathode active material production toward integrated cell manufacturing in Michigan and Nevada. The Southeast automotive corridor attracts pack assembly investments seeking proximity to commercial EV fleet operators.
Germany
Industrial behind-the-meter installations and residential solar-plus-storage systems sustain demand for containerized and wall-mounted configurations. EU Battery Regulation digital passport requirements and recycled content thresholds reshape supply chain documentation obligations. Bavaria hosts testing laboratories compressing certification cycles for cells entering European commercial vehicle procurement.
India
State-level renewable purchase obligations and CEA mandates open procurement windows for grid-scale battery systems. BIS safety standards govern cell import eligibility and domestic assembly qualification. Gujarat and Maharashtra manufacturing hubs develop pack integration capacity to serve containerized energy storage deployments.
South Korea
Power tool OEMs and consumer electronics brands sustain cylindrical cell demand for high-discharge-rate applications. MFDS and KTL certification requirements govern transportation and safety compliance. Seoul Capital Area R&D centers pilot dry electrode coating transitions to reduce drying energy consumption in prismatic production lines.
Lifepo4 Battery Market Competitive Landscape
Global majors compete with regional champions across cathode precursor integration and pack-BMS qualification capabilities. The vendor base stratifies into three tiers: vertically integrated cell producers with captive lithium refining, pack assemblers dependent on external cathode offtake, and specialized integrators focused on thermal management and structural bonding. Strategic moves concentrate on backward integration into phosphate mining and joint-venture partnerships with automotive OEMs seeking supply security.
Within the integrated-producer tier, CATL and BYD exemplify archetypes of upstream control over lithium refining and cathode precursor production. Panasonic Energy occupies a position representing partnership-dependent competitive models, relying on external cathode supply agreements rather than captive feedstock. These three anchors illustrate divergent margin pool capture strategies across the prismatic cell value chain.
| Leading Market Players |
|---|
| CATL |
| BYD |
| EVE Energy |
| LG Energy Solution |
| CALB |
| Gotion High-Tech |
| A123 Systems |
| Panasonic Energy |
| Samsung SDI |
| Others |
Pricing and Supply Chain Analysis
Commercial fleet procurement consolidation around fifteen-year performance guarantees is forcing cell producers to absorb degradation risk into contract pricing, compressing margin pools for non-integrated assemblers. This buyer-side pressure reverberates upstream through cathode precursor markets, where captive lithium refining confers decisive cost control.
Pricing Analysis
Performance-guarantee bundling separates premium-tier integrators offering pack-level cycle-life warranties from standard-tier competitors selling cells without degradation commitments. Three-tier pricing structure across premium, standard, and economy levels tracks certification intensity—GB standards compliance for Chinese commercial vehicles commands premium positioning against generic IEC-certified alternatives. Price erosion runs through the economy tier as Jiangsu-Fujian supply concentration enables volume discounts for automotive OEMs with direct offtake agreements. Utility-scale developers exhibit lowest price sensitivity due to total-cost-of-ownership modeling dominance, while consumer electronics buyers drive hardest bargain on per-kilowatt-hour metrics.
Supply Chain Analysis
Single-source vulnerability sits with China's Jiangsu and Fujian provinces, where over 70% of cathode precursor capacity clusters within 200 kilometers of prismatic cell gigafactories. Lithium carbonate, phosphate rock, and graphite anode materials draw from concentrated mining jurisdictions—Australia, Chile, and Mozambique anchor upstream extraction. Tariff exposure on Chinese cell imports threatens margin structures for European pack assemblers lacking alternative supply routes. Distribution runs through direct long-term offtake agreements with automotive OEMs and utility developers, disintermediating traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cathode active material capacity constraints in North America and Europe prop pricing premiums for compliant cell supply, creating a supply-constrained market structure through the mid-decade horizon.
For Market Incumbents: To counter IRA domestic content credit eligibility gaps, CATL and BYD should accelerate cathode precursor joint ventures in Michigan and Nevada while deepening GB standards certification capabilities to compress European qualification timelines. Backward integration into phosphate mining insulates margin pools from spot lithium volatility. For New Entrants and Emerging Players: India's CEA-mandated grid-scale storage procurement represents the most penetrable demand pocket, with state-level renewable purchase obligations opening containerized system deployment windows. Second-life automotive pack refurbishment for commercial behind-the-meter applications offers white-space positioning with lower capital intensity than greenfield cell manufacturing. For Investors and Strategic Acquirers: The window for entry favors vertically integrated mid-cap specialists with captive cathode production and in-house thermal runaway modeling capabilities. Dry electrode coating technology transitions and EU Battery Regulation compliance infrastructure serve as inflection indicators for capability moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Mining | Captive feedstock access compresses raw material cost volatility for prismatic cell lines. |
| GB Standards Certification Investment | In-house testing laboratories compress qualification cycles versus import-dependent competitors. |
| North American Cathode Precursor Joint Venture | IRA domestic content credits pull active material production toward integrated cell manufacturing. |
| Dry Electrode Coating Transition | Eliminates solvent-based processing, reducing drying energy consumption and capex intensity. |
| Second-Life Pack Refurbishment Capability | Retired electric vehicle batteries with residual capacity converge with behind-the-meter commercial applications. |
Research Methodology
Multi-period observation of cathode precursor pricing spreads, gigafactory capacity utilization rates, and fleet procurement contract terms anchored the trend analysis, supplemented by interviews with cell engineering directors, utility-scale storage procurement officers, automotive platform battery leads, and cathode material supply planners. Secondary validation drew from MIIT production license disclosures, customs trade data for lithium carbonate and phosphate rock, SEC filings of listed battery producers, and IEA stationary storage deployment databases. Bottom-up cell shipment aggregation triangulated against top-down electric vehicle and energy storage system demand modeling.
Segment-weighting across cell geometry, application durability requirements, and end-user procurement scale determined revenue distribution within the analytical framework. Prismatic, cylindrical, pouch, and large-format architectures were modeled separately with distinct degradation curves and replacement cycle assumptions. CAGRs derived from logistic diffusion curves fitted to fleet electrification mandates and renewable firming targets. Forecast inputs incorporated GB standards compliance timelines, IRA credit phase-in schedules, and EU Battery Regulation recycled content thresholds.
Revisions become necessary when lithium carbonate spot volatility exceeds historical bands, when geopolitical restrictions disrupt Jiangsu-Fujian supply corridors, or when alternative cathode chemistries achieve cost parity. Forecasts reflect documented assumptions about fleet electrification pace and grid interconnection queue clearance rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Nanobolt Lithium Tungsten Batteries Market
Lithium-ion Battery
India Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium-Ion Batteries Electric Bike Market
Lithium-ion Battery
Lithium Ion Capacitor Market
Lithium-ion Battery
Manganese Dioxide Lithium Battery Market
Lithium-ion Battery
Lithium Hydroxide Market
Lithium-ion Battery
Automotive Lithium-Ion Battery Cell Market
Lithium-ion Battery
Aluminium Ion Battery Market
Lithium-ion Battery
Global Lithium Mining Market
Lithium-ion Battery
Lithium-Ion Battery Rechargeable Hearing Aids Market
Lithium-ion Battery
Asia-Pacific Solid State Battery Market
Lithium-ion Battery
Lithium-Ion Forklift Battery Market
Lithium-ion Battery
Lithium-Ion UPS System Market
Lithium-ion Battery
Li Air Battery Market
Lithium-ion Battery
France Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium-Ion Batteries for Electric Vehicles Market