
 Water Dispersible Polymers Market | 2026-2036
Water Dispersible Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Water Dispersible Polymers Market Outlook
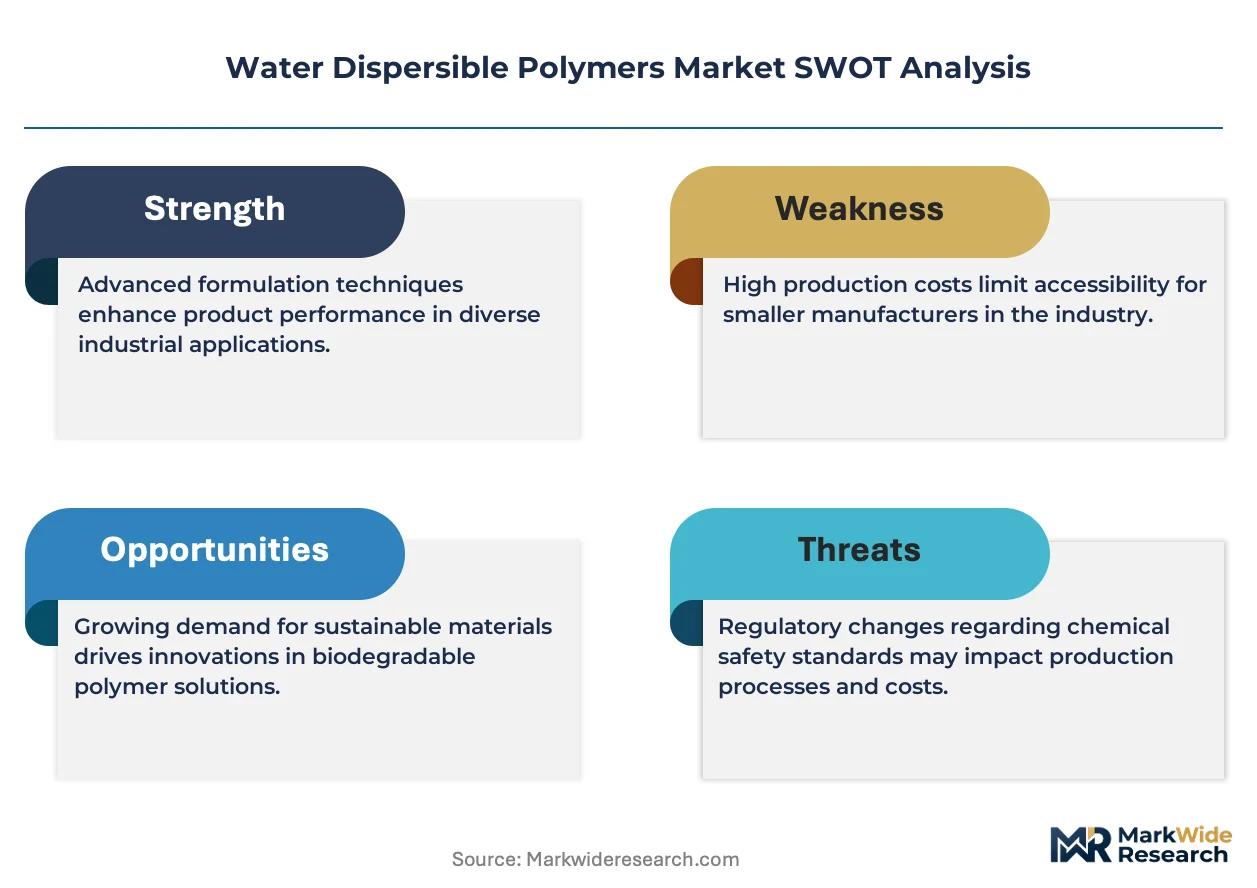
Multi-source procurement for cellulose ether intermediates is hardening as formulators seek supply security against feedstock volatility. BASF SE leverages captive acrylate production to stabilize raw material access across European coating lines. Dow Inc. anchors North American supply through integrated polyvinyl alcohol manufacturing at its Texas Gulf Coast complex. Kemira Oyj differentiates via specialized dispersant chemistry for water treatment and construction applications.
Water dispersible polymers comprise macromolecules engineered with hydrophilic functional groups that enable spontaneous dissolution or dispersion in aqueous media without organic co-solvents, typically manufactured through controlled free-radical polymerization or etherification of polysaccharide backbones to achieve target viscosities between 500 and 50,000 mPa·s. These materials function primarily as rheology modifiers, protective colloids, and film-forming agents in formulations where solvent-borne systems face regulatory or cost constraints. Cellulose derivatives occupy the largest value share due to decades of formulation familiarity in construction mortars and pharmaceutical tablet coatings. Acrylic polymers represent the fastest-expanding category, driven by architectural coating reformulations in Asia-Pacific and Latin America where low-VOC mandates intensify. Starch derivatives retain mature demand patterns in paper sizing and textile sizing, though margin compression from agricultural feedstock price swings constrains producer profitability.
REACH registration requirements in Europe compel extensive toxicological dossiers for acrylic monomer building blocks, elevating compliance costs for importers and favoring producers with established substance volume tracking. EPA TSCA Section 5 premanufacture notifications govern new polymer introductions in the United States, creating procedural delays for novel dispersible chemistries targeting personal care and detergent markets. BIS certification under Indian standards IS 15111 and IS 15497 mandates quality testing for construction-grade redispersible powders, shaping market access for regional and imported suppliers. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions across jurisdictions, as fluorinated dispersant chemistries face substitution pressure from bio-based alternatives.
Market Dynamics
REACH registration dossiers for acrylic monomer building blocks are elevating compliance costs across European supply chains, compelling producers to consolidate substance volume tracking capabilities or exit the region entirely.
Growth Catalysts
- Low-VOC architectural coating mandates:Reformulation pressures in Asia-Pacific construction markets are accelerating acrylic polymer substitution for solvent-borne systems in exterior paints and protective coatings.
- Pharmaceutical excipient demand:Tablet coating and controlled-release applications in China's expanding generic drug manufacturing base are pulling cellulose ether consumption upward.
- Infrastructure cement modification:Germany's federal transport investment programs are expanding specification of redispersible powders in tunnel linings and bridge deck repairs.
Market Restraints
- Propylene oxide feedstock volatility:Cellulose ether producers face margin compression from petrochemical intermediate price swings that resist downstream pass-through.
- Acrylate monomer supply concentration:European coating formulators depend on a narrow supplier base for hydroxyethyl acrylate, creating vulnerability to force majeure disruptions.
- Fluorinated chemistry substitution pressure:Per- and polyfluoroalkyl substance restrictions under EU F-Gas Regulation and state-level US bans are eliminating dispersant applications in high-performance coatings.
Strategic Opportunities
- Bio-based starch derivative formulations:Agricultural feedstock processors in India can capture construction-grade dispersant demand under BIS IS 15111 certification pathways.
- Water treatment dispersant specialization:Mining and oilfield chemical service providers are opening specification windows for tailored anionic polymers in tailings management.
- Personal care silicone replacement:Carbomer and acrylate copolymer producers are targeting formulation gaps created by cyclical silicone supply constraints in South Korean cosmetic manufacturing.
Industry Challenges
- Polymer characterization expertise scarcity:Analytical laboratories capable of molecular weight distribution testing for REACH dossiers command premium pricing and extended lead times.
- Legacy mortar formulation integration:Construction chemical distributors face technical support burdens when retrofitting redispersible powders into established jobsite mixing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Dispersible Polymers Market |
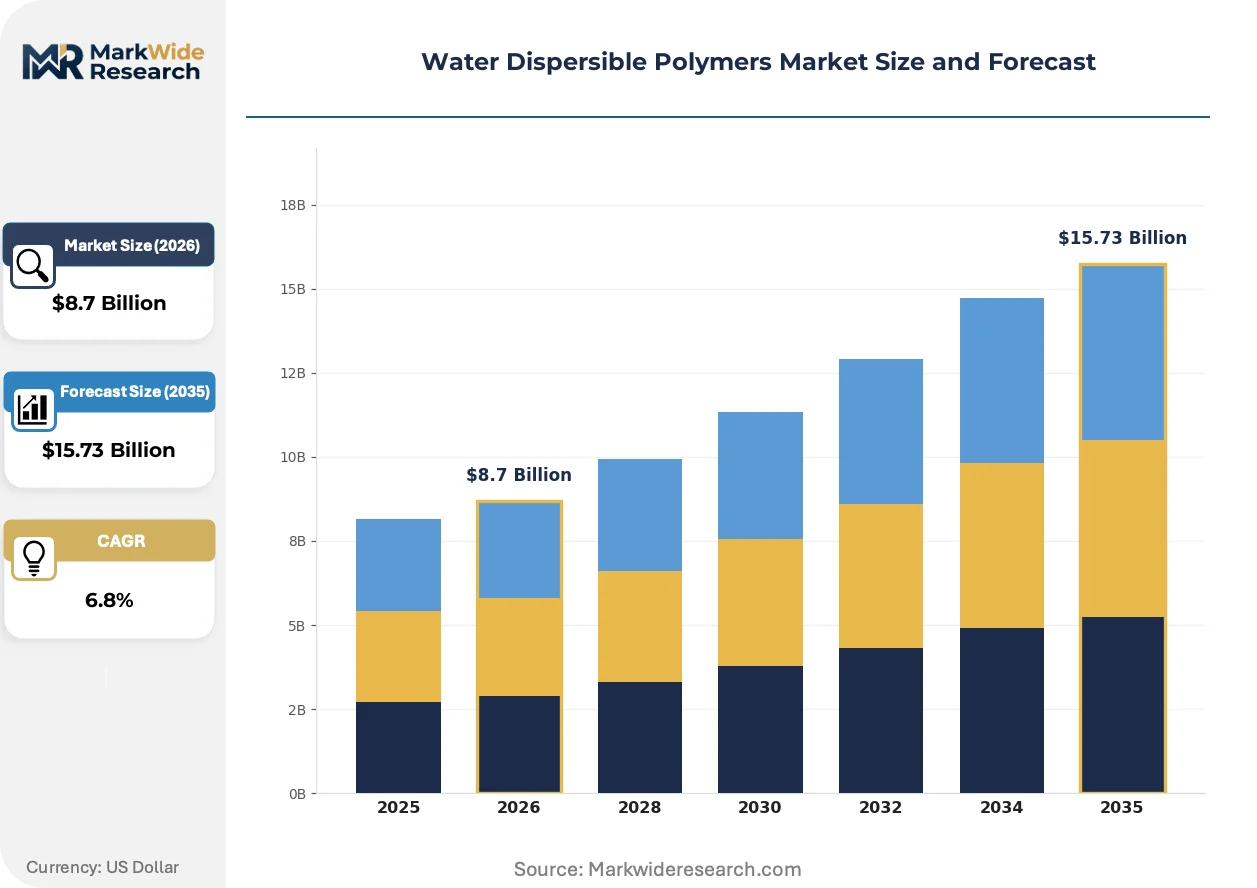
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starch Derivatives, Cellulose Derivatives, Polyvinyl Alcohol, Acrylic Polymers Application: Coatings, Adhesives, Textiles, Personal Care End Use Industry: Construction, Agriculture, Detergents, Pharmaceuticals Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | BASF SE, Dow Inc., Ashland Global Holdings Inc., Arkema S.A., DuPont de Nemours Inc., SNF Group, Kuraray Co. Ltd., Kemira Oyj, Nouryon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Dispersible Polymers Market Strategic Shifts
Reformulation chemistry is pivoting toward aqueous systems as regulatory thresholds for volatile organic compounds tighten across multiple jurisdictions simultaneously.
Cellulosic nanofibril technology is absorbing film-forming functions in architectural coatings previously served by conventional hydroxyethyl cellulose. European paint manufacturers are piloting these materials at pilot scale for exterior masonry primers. The structural consequence is absorbing volume from commodity cellulose ether grades while commanding formulation premiums in certified low-carbon building products.
EPA TSCA Section 5 premanufacture notification requirements are extending lead times for novel dispersible polymer introductions into personal care and detergent applications. The procedural burden favors incumbent producers with established PMN track records and existing consent order portfolios. Small-volume specialty polymer entrants are responding by prioritizing European notification pathways under REACH polymer exemptions.
Construction chemical procurement is consolidating specification authority from regional distributors to national ready-mix concrete producers with centralized R&D functions. This channel compression is displacing technical sales relationships at the jobsite level. The shift is most visible in Germany and France where major cement producers have acquired mortar formulation capabilities.
Water Dispersible Polymers Market Segmentation
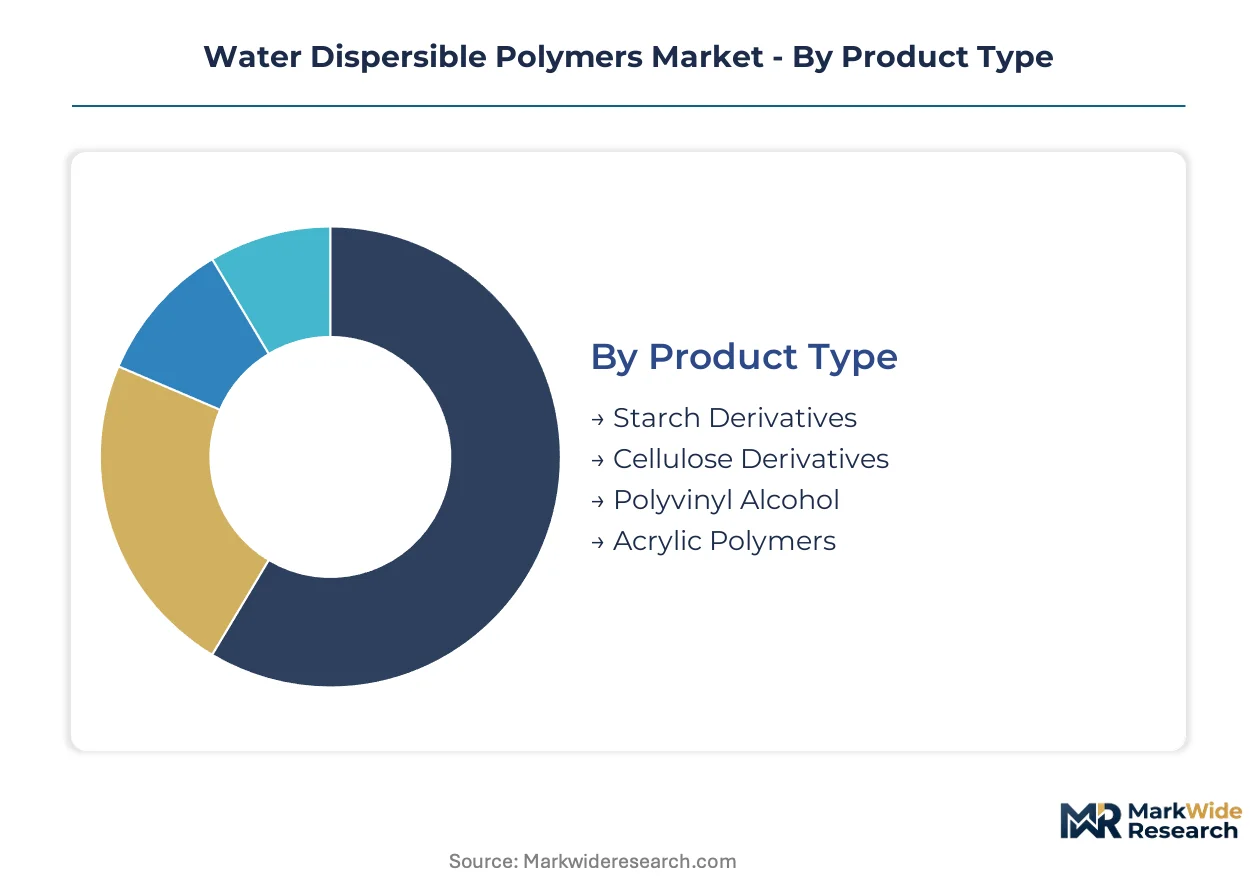
Water dispersible polymers serve divergent performance requirements across construction mortars, pharmaceutical coatings, and personal care formulations. Segment boundaries reflect distinct rheology specifications, regulatory compliance burdens, and procurement channel structures that shape supplier economics.
Product Type:
Reformulation cycles in architectural coatings and cement modification are driving substitution between synthetic and bio-based polymer backbones as VOC thresholds tighten.
- Cellulose Derivatives:Etherified polysaccharide backbones—hydroxyethyl, hydroxypropyl, and carboxymethyl grades—deliver pseudoplastic flow control in cementitious systems. German tunnel rehabilitation projects under federal transport programs are absorbing record volumes of methylcellulose for shotcrete applications.
- Acrylic Polymers:Carboxyl-functionalized acrylate copolymers synthesized via emulsion polymerization achieve film-forming properties without coalescing solvents. China's exterior coating reformulations under provincial low-VOC mandates are pulling hydroxyethyl acrylate consumption upward faster than any other product category.
- Starch Derivatives:Oxidized and esterified starches provide biodegradable sizing for paper and textile processing. Agricultural feedstock price volatility constrains margin stability for Indian processors serving domestic textile clusters.
- Polyvinyl Alcohol:Partially hydrolyzed grades function as protective colloids and film formers in adhesives and construction redispersible powders. Texas Gulf Coast integrated production anchors North American supply security.
Cellulose derivatives sit at the top of the volume ranking, with acrylic polymers climbing the fastest.
Application:
Cost tier stratification separates commodity construction applications from specification-grade pharmaceutical and personal care formulations requiring extensive toxicological dossiers.
- Coatings:Architectural paints, industrial primers, and masonry finishes employ water dispersible polymers for viscosity stability and open-time extension. REACH-registered cellulose ethers dominate European exterior masonry coatings.
- Adhesives:Pressure-sensitive, construction, and packaging adhesives leverage tackification and cohesive strength from polyvinyl alcohol and acrylic dispersions. Tile adhesive specifications in Germany mandate redispersible powder content for freeze-thaw resistance.
- Textiles:Warp sizing and fabric finishing operations utilize starch derivatives and polyvinyl alcohol for abrasion resistance during weaving. Indian BIS certification under IS 15111 governs quality testing for construction-grade dispersants crossing into technical textile applications.
- Personal Care:Carbomer and acrylate copolymers provide rheology control in lotions, creams, and hair styling products. South Korean cosmetic manufacturers are substituting silicone with aqueous polymer systems amid cyclical siloxane supply constraints.
Coatings commands the largest value position, while personal care exhibits the steepest expansion trajectory.
End Use Industry:
Customer type segmentation separates project-driven construction procurement from continuous manufacturing demand in detergents and pharmaceuticals.
- Construction:Cement modifiers, tile adhesives, self-leveling underlayments, and repair mortars specify redispersible powders and cellulose ethers for workability retention. German ready-mix concrete producers have centralized formulation authority, compressing regional distributor technical relationships.
- Pharmaceuticals:Tablet film coatings, controlled-release matrices, and capsule binders require pharmacopeia-compliant cellulose ethers with validated heavy metal and microbial specifications. China's expanding generic drug manufacturing base is pulling excipient-grade hydroxypropyl methylcellulose consumption upward.
- Detergents:Anti-redeposition polymers and rheology modifiers for liquid formulations employ acrylic copolymers and modified celluloses. EPA TSCA Section 5 premanufacture notifications delay novel polymer introductions for this application.
- Agriculture:Seed coatings and controlled-release fertilizer matrices utilize starch derivatives and polyvinyl alcohol for biodegradability compliance. Margin pressure from agricultural commodity cycles constrains specialty polymer penetration.
Construction anchors volume demand, with pharmaceuticals gaining share fastest.
Distribution Channel:
Supply concentration in acrylic monomer production is forcing channel consolidation toward direct relationships with integrated polymer producers.
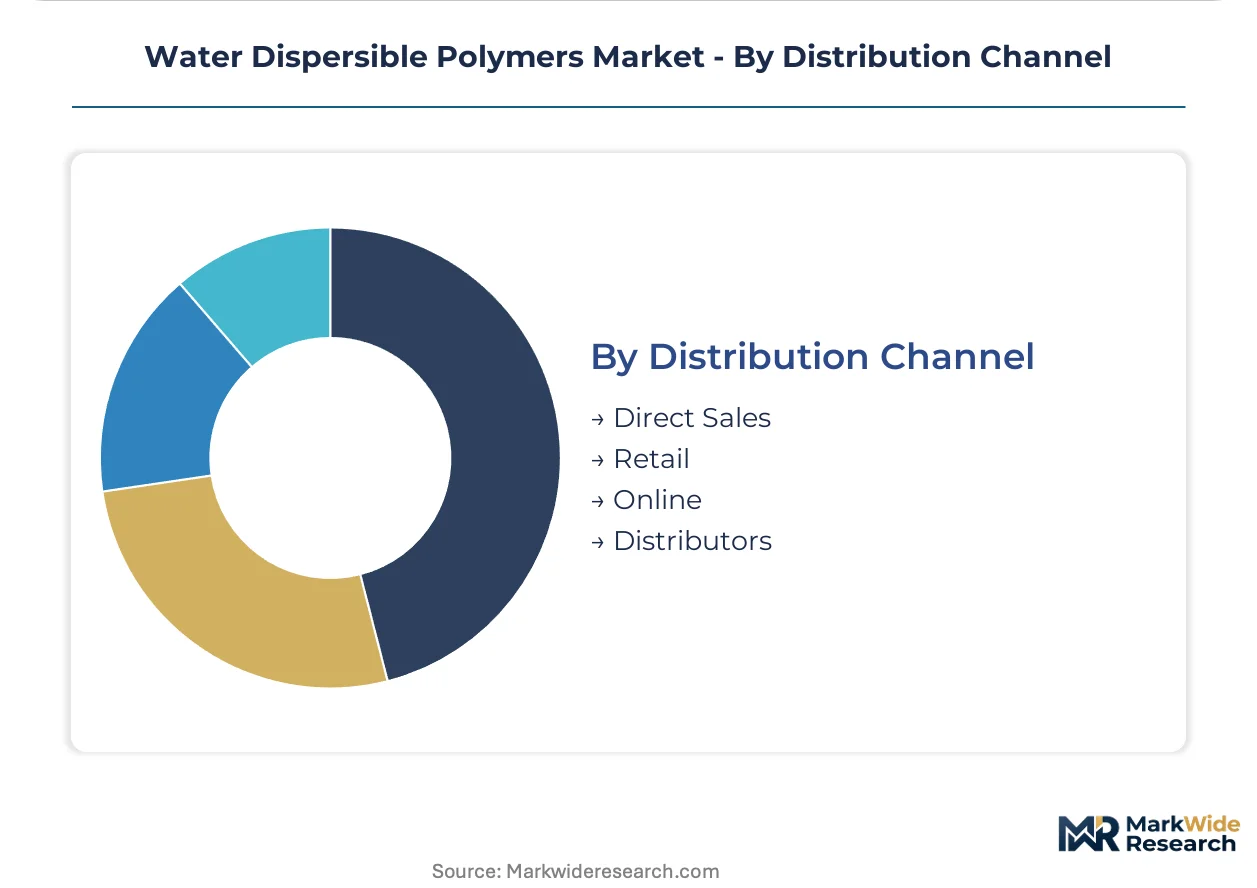
- Direct Sales:National ready-mix concrete producers and multinational coating manufacturers procure bulk cellulose ethers and redispersible powders through frame contracts. BASF SE leverages captive acrylate production to stabilize supply access for direct accounts.
- Distributors:Regional construction chemical distributors maintain technical service relationships with smaller mortar formulators and specialty applicators. Legacy jobsite mixing protocol integration creates support burdens for redispersible powder introductions.
- Online:E-procurement platforms serve small-volume personal care formulators and research laboratories requiring rapid sample access. Limited lot traceability constrains pharmaceutical-grade polymer sales through this channel.
- Retail:Home improvement and professional trade counters supply modified celluloses for DIY tile adhesive and skim coat applications. Price transparency pressures margin capture for commodity grades.
Direct sales occupies the dominant volume position, with online channels expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing water dispersible polymer production toward jurisdictions with streamlined chemical registration frameworks, as REACH compliance costs in Europe widen cost-of-compliance gaps with Asia-Pacific manufacturing bases.
China
Provincial low-VOC mandates in Jiangsu and Guangdong are accelerating architectural coating reformulations that pull hydroxyethyl acrylate consumption upward. MEE enforcement of dual carbon goals tightens emissions standards for emulsion polymerization facilities. The Yangtze River Delta concentration of pharmaceutical excipient manufacturers is expanding hydroxypropyl methylcellulose capacity for tablet coating applications.
Germany
Federal transport investment programs are expanding redispersible powder specifications for tunnel linings and bridge deck repairs across Bavaria and North Rhine-Westphalia. ECHA REACH registration dossiers for acrylic monomer building blocks elevate compliance costs for coating formulators. The Cologne-Düsseldorf industrial corridor hosts centralized R&D functions of major ready-mix concrete producers that have compressed regional distributor relationships.
United States
EPA TSCA Section 5 premanufacture notifications delay novel dispersible polymer introductions for personal care and detergent applications. Texas Gulf Coast integrated polyvinyl alcohol manufacturing anchors North American supply security against propylene oxide feedstock volatility. Houston-area chemical service providers are opening specification windows for tailored anionic polymers in mining tailings management.
India
BIS certification under IS 15111 and IS 15497 mandates quality testing for construction-grade redispersible powders, shaping market access for regional and imported suppliers. Agricultural feedstock processors in Gujarat are capturing construction-grade dispersant demand through bio-based starch derivative formulations. The Mumbai-Pune industrial belt concentrates textile sizing operations that utilize oxidized starches for warp sizing applications.
South Korea
Cyclical siloxane supply constraints are driving cosmetic manufacturers in Seoul and Gyeonggi Province to substitute silicone with carbomer and acrylate copolymer systems. MFDS cosmetic ingredient regulations govern polymer safety assessments for personal care formulations. The Busan-Ulsan chemical complex houses acrylate production capacity serving regional coating and adhesive markets.
Water Dispersible Polymers Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue bio-based specialty formulations and water treatment dispersant applications. The market structure reflects moderate consolidation around integrated petrochemical players with captive monomer supply, while regional specialists retain footholds in construction-grade redispersible powders. Three archetypes dominate: multinational chemical conglomerates with backward integration into acrylate intermediates, cellulose ether specialists with pharmaceutical-grade certification capabilities, and water treatment-focused polymer houses with mining and oilfield service relationships. Capacity expansion and strategic partnerships represent the dominant competitive moves, as producers seek to secure feedstock access and expand geographic coverage.
Within the multinational chemical tier, BASF SE and Dow Inc. exemplify producers with integrated manufacturing footprints that stabilize raw material access across regional coating lines. Kemira Oyj occupies a position among specialized dispersant chemistry providers targeting water treatment and construction applications. These three anchors represent distinct strategic postures: captive supply security, geographic diversification, and application-specific technical differentiation.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Ashland Global Holdings Inc. |
| Arkema S.A. |
| DuPont de Nemours Inc. |
| SNF Group |
| Kuraray Co. Ltd. |
| Kemira Oyj |
| Nouryon |
| Others |
Value Chain & Pricing Dynamics
Provincial low-VOC mandates across Jiangsu and Guangdong provinces are compelling coating formulators to accelerate acrylic polymer procurement, forcing supply chains to reroute toward integrated acrylate producers and compressing margins on spot-market intermediates. This demand-side specification shift concentrates purchasing power among national ready-mix concrete producers and multinational coating manufacturers, amplifying price leverage for backward-integrated suppliers while squeezing regional distributors.
Pricing Analysis
Propylene oxide and acrylate monomer cost pass-through dominates pricing dynamics across cellulose ether and acrylic polymer grades. Three-tier pricing structure across premium, standard, and economy levels separates pharmacopeia-certified excipients from construction-grade cellulose ethers and commodity starch derivatives. Cost compression in standard-grade construction polymers is intensifying because agricultural feedstock volatility resists downstream pass-through. Regional mortar formulators exhibit highest price sensitivity, while pharmaceutical tablet coaters accept premiums for validated heavy metal and microbial specifications.
Supply Chain Analysis
Regional distribution centers in the Texas Gulf Coast, Yangtze River Delta, and Cologne-Düsseldorf corridor coordinate hub-and-spoke delivery patterns for bulk cellulose ethers and redispersible powders. Manufacturing concentrates in China, Germany, and the United States, with feedstock supply anchored in Saudi Arabian propylene derivatives and US Gulf Coast petrochemical complexes. Raw material sourcing draws from propylene oxide, purified cotton linters, and vinyl acetate monomer streams. Single-source vulnerability in hydroxyethyl acrylate intermediates exposes European coating formulators to force majeure disruptions. Distribution runs through direct frame contracts with national ready-mix producers and construction chemical distributors serving regional applicators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The water dispersible polymers market functions as a stable compounder, with infrastructure cement modification and pharmaceutical excipient demand providing steady volume anchors across economic cycles.
For Market Incumbents: Deploy captive acrylate production to stabilize raw material access against monomer supply concentration risks. Expand pharmacopeia-certified cellulose ether capacity in the Yangtze River Delta to capture China's generic drug manufacturing growth. Deepen technical service relationships with national ready-mix concrete producers to defend against channel compression displacing regional distributors. For New Entrants and Emerging Players: Bio-based starch derivative formulations certified under BIS IS 15111 offer a technology-first wedge into India's construction-grade dispersant market. Water treatment dispersant specialization for mining tailings management presents penetrable white space with limited incumbent technical presence. Pursue direct sales partnerships with Houston-area chemical service providers to bypass established distributor relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with cellulose ether specialists possessing pharmaceutical-grade certification capabilities and established REACH dossier portfolios. Long-term viability over a multi-year horizon favors producers with integrated monomer supply and construction end-use diversification. Watch MEE enforcement of dual carbon goals in China as an inflection signal for emulsion polymerization capacity rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylate Monomers | BASF SE's captive production stabilizes supply access for European coating lines against force majeure disruptions. |
| Pharmacopeia-Certified Capacity Expansion | Excipient-grade hydroxypropyl methylcellulose investment captures China's expanding generic drug manufacturing base. |
| Long-term Supply Agreement with Ready-Mix Producers | Frame contracts with German cement producers compress regional distributor technical relationships toward direct procurement. |
| Joint Venture for Bio-Based Starch Derivatives | Gujarat agricultural processors leverage BIS certification pathways to supply construction-grade dispersants domestically. |
| Green Manufacturing Transition | Cellulosic nanofibril pilot programs in European paint manufacturing absorb volume from commodity cellulose ether grades. |
Study Parameters
Bottom-up construction mortar and pharmaceutical coating modeling reconciled against top-down acrylic monomer and cellulose ether production tracking forms the analytical core of this study. Primary interviews with plant managers at emulsion polymerization facilities, procurement leads at multinational coating manufacturers, technical R&D directors at construction chemical distributors, and regulatory affairs specialists at pharmaceutical excipient suppliers combined with secondary validation. Secondary sources include customs and trade data from major exporting jurisdictions, Cefic and ACC industry reports, SEC 10-K filings from listed chemical producers, and ECHA REACH registration dossiers for acrylic monomer building blocks.
Input-output matrices map propylene oxide and acrylate monomer availability against cellulose ether, acrylic polymer, and redispersible powder production capacity across the analysis window. Segmentation dimensions encompass product type tier, end-use industry, application specification, and regional production hub. CAGRs derive from modeled volume-demand relationships across construction, pharmaceutical, detergent, and agriculture end-uses, with feedstock price elasticity and regulatory compliance cost trajectories informing price evolution assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MEE emissions enforcement in China, REACH registration cost escalations in Europe, and propylene oxide feedstock volatility. Outputs reflect documented assumptions around infrastructure spending trajectories and low-VOC mandate adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Resorcinol Formaldehyde Resin Market
Polymers & Resins
Melamine Formaldehyde Resin Powder Market
Polymers & Resins
South America Polyamide Market
Polymers & Resins
Middle East LLDPE Market
Polymers & Resins
High Density Polyethylene (HDPE) Market
Polymers & Resins
Asia-Pacific Engineering Plastics Market
Polymers & Resins
China Geopolymer Market
Polymers & Resins
Europe Chromatography Resins Market
Polymers & Resins
Polymer Modifiers Market
Polymers & Resins
Extruded Polystyrene Market
Polymers & Resins
Cellulosic Polymers Market
Polymers & Resins
Filled Fluoropolymer Market
Polymers & Resins
Global Resin Market
Polymers & Resins
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Global Polyolefin Powders Market
Polymers & Resins
Expanded Polystyrene (EPS) Market