
 Acetal (POM) Copolymer Market | 2026-2036
Acetal (POM) Copolymer Market Size, Share, and Industry Trends Forecast 2026-2036
Acetal (POM) Copolymer Market Outlook
Direct supply agreements between resin producers and tier-one automotive suppliers is tilting toward longer-term contracts with embedded volume commitments. Celanese Corporation leverages its integrated acetal manufacturing network across the United States and Europe to sustain pricing leverage on copolymer grades. BASF SE anchors its position through specialized compounding capabilities that serve industrial component makers requiring tight dimensional tolerances. DuPont competes on legacy brand recognition in precision gear applications where material consistency commands premium positioning.
Acetal (POM) copolymer is a formaldehyde-based thermoplastic engineered through copolymerization with cyclic ethers, yielding a semi-crystalline structure with melting points near 165°C and superior hydrolytic stability compared to homopolymer variants. The material serves precision mechanical applications where low friction, high stiffness, and resistance to hydrocarbons are essential. Glass-filled grades dominate structural load-bearing segments such as automotive under-hood components where creep resistance determines part longevity. Copolymer formulations represent the fastest-expanding product category as processors prioritize processability and broader chemical resistance over the marginal stiffness gains of homopolymer alternatives. Electrical insulator applications in connector housings and switchgear components concentrate margin pools for compounders offering UL-certified flame-retardant variants.
EPA regulations in the United States and REACH in the European Union constrain formaldehyde emissions during resin production and processing, elevating compliance costs for non-integrated compounders. FDA food-contact approvals and NSF drinking water certifications in North America create gated market access for copolymer grades entering consumer appliance and plumbing segments. Stakeholders must monitor formaldehyde reclassification proceedings under the EU CLP framework and corresponding state-level initiatives in California, as any hazard escalation would cascade through supply chain qualification requirements and reformulation timelines.
Market Dynamics
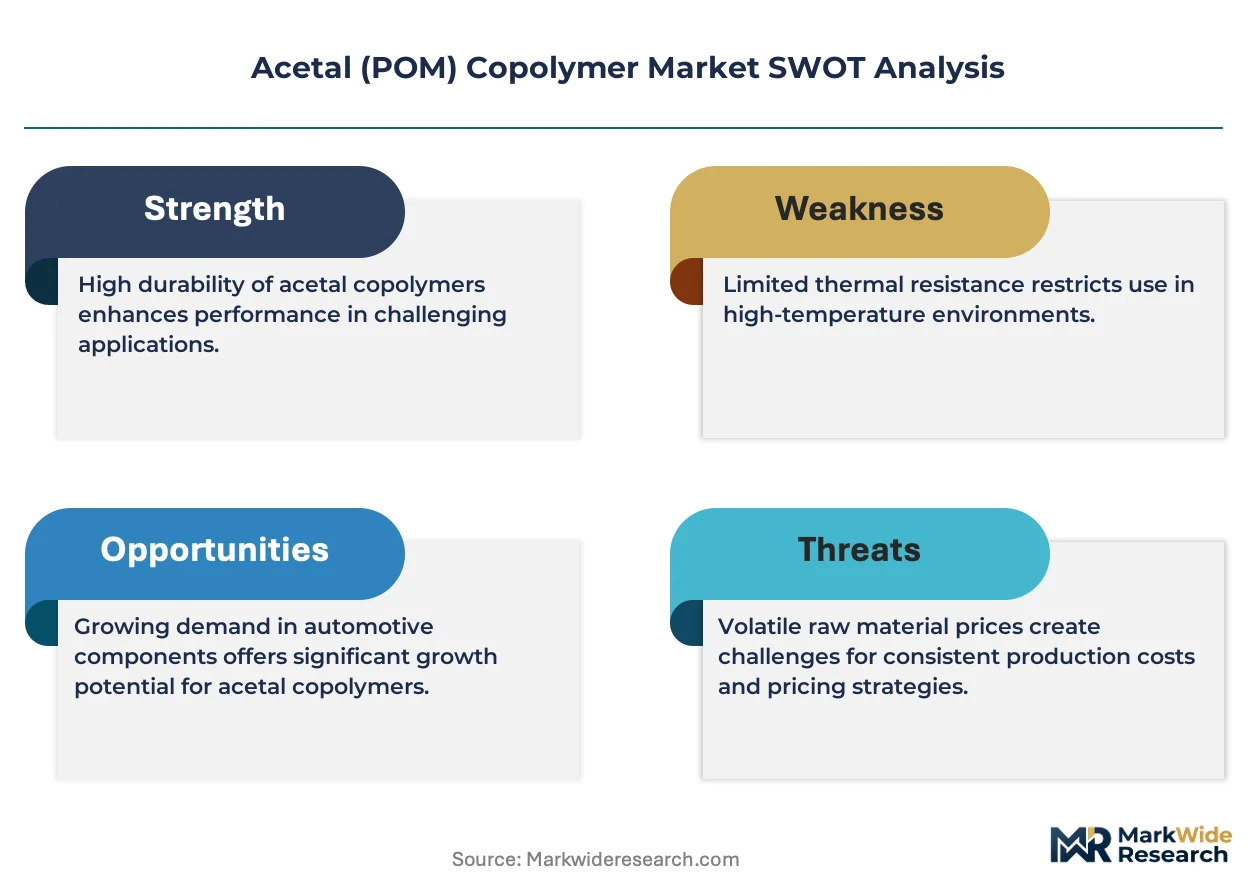
Formaldehyde emission thresholds under REACH and EPA frameworks are compressing the addressable supply base, forcing compounders to absorb certification costs or exit certifiable grades entirely.
Growth Catalysts
- Fuel system component demand:Automotive OEMs in Germany and Japan specify POM copolymer for direct injection fuel rails and quick-connect fittings where hydrolytic stability prevents degradation from biofuel blends.
- REACH Article 33 disclosure requirements:The regulation's Substances of Very High Concern list pressures converters toward certified low-emission grades, creating preference premiums for compliant suppliers.
- Glass-filled grade innovation:Reinforced formulations with 25-30% glass fiber content enable metal replacement in structural brackets, expanding addressable load-bearing applications.
Market Restraints
- Formaldehyde feedstock volatility:Methanol price swings and natural gas cost pressure transmit directly to resin economics, squeezing margin for non-integrated compounders.
- Homopolymer substitution in stiffness-critical gears:Delrin and equivalent homopolymer grades retain preference in precision transmission components where creep modulus determines specification.
- Chinese supply concentration:Raw acetal resin capacity clusters in Shandong and Jiangsu provinces, exposing buyers to single-origin disruption risk and logistics bottlenecks.
Strategic Opportunities
- NSF/ANSI 61 drinking water certification:North American plumbing fixture manufacturers seek compliant grades for valve bodies and faucet cartridges, opening margin pools in residential construction.
- Electric vehicle thermal management:Battery module housings and coolant manifolds require hydrolysis-resistant polymers capable of 150°C continuous service in glycol environments.
- Direct mill-to-molder digital procurement:Resin producers bypass distributor tiers through platform-based spot contracting and VMI programs with high-volume processors.
Industry Challenges
- Compounding technician scarcity:Specialized knowledge of twin-screw extrusion parameter control and glass fiber dispersion is concentrating among aging workforces in Ohio and Ludwigshafen.
- UL 94 V-0 flame retardant certification timelines:Compounders face 18-24 month approval cycles for halogen-free FR grades, delaying entry into connector and switchgear segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetal (POM) Copolymer Market |
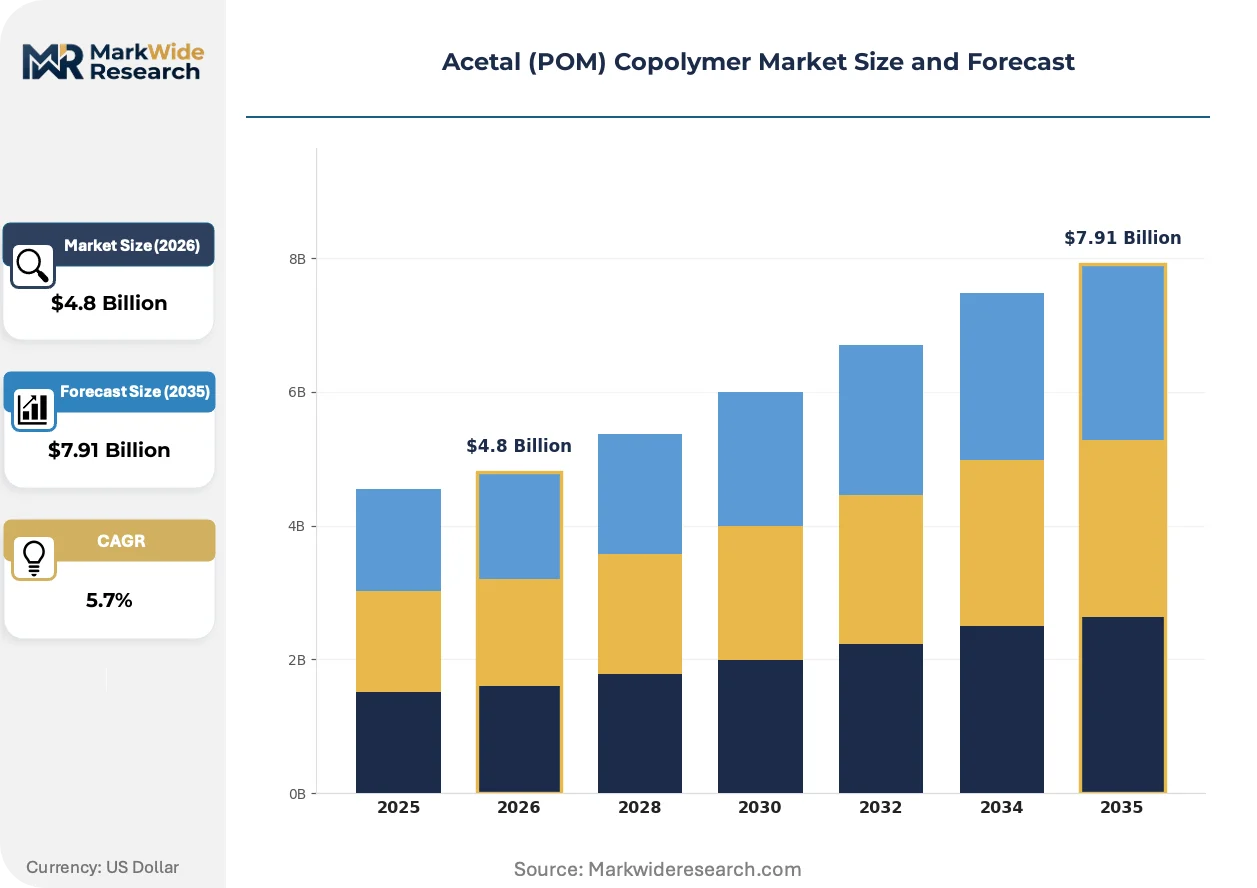
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homopolymer, Copolymer, Glass-Filled, Mineral-Filled Application: Automotive Parts, Consumer Goods, Industrial Components, Electrical Insulators End User: Manufacturers, OEMs, Distributors, Retailers Form: Pellets, Sheets, Rods, Films |
| Companies Covered | Celanese Corporation, BASF SE, DuPont, Polyplastics Co., Ltd., Asahi Kasei Corporation, Korea Engineering Plastics Co., Ltd., Mitsubishi Gas Chemical Co., Inc., Daicel Corporation, Delrin USA, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetal (POM) Copolymer Market Strategic Shifts
Digital twin integration across injection molding workflows is compressing qualification cycles and enabling real-time viscosity control, reshaping how processors validate copolymer grade suitability.
Closed-loop recycling of post-industrial POM scrap is virtualizing raw material input streams for select automotive tier suppliers. BMW and Mercedes-Benz procurement teams now specify minimum 30% regrind content in non-structural interior clips. This technology is virtualizing virgin resin demand in closed supply chains where material traceability meets OEM sustainability scorecards.
EPA formaldehyde emissions standards under the Toxic Substances Control Act are tightening permissible thresholds for resin production facilities. Compounders without thermal oxidizer upgrades face operational constraints or facility closures. Small and mid-scale processors in Michigan and Ohio are consolidating or seeking toll compounding arrangements to maintain market access.
Long-term offtake agreements with embedded price collars are displacing spot market purchasing among high-volume automotive molders. Tier-one suppliers in Stuttgart and Nagoya now contract 3-5 year resin supply with volume flex provisions and technical service commitments. This pattern concentrates procurement leverage among processors with scale to commit, squeezing independent molders into distributor channels with less favorable terms.
Acetal (POM) Copolymer Market Segmentation
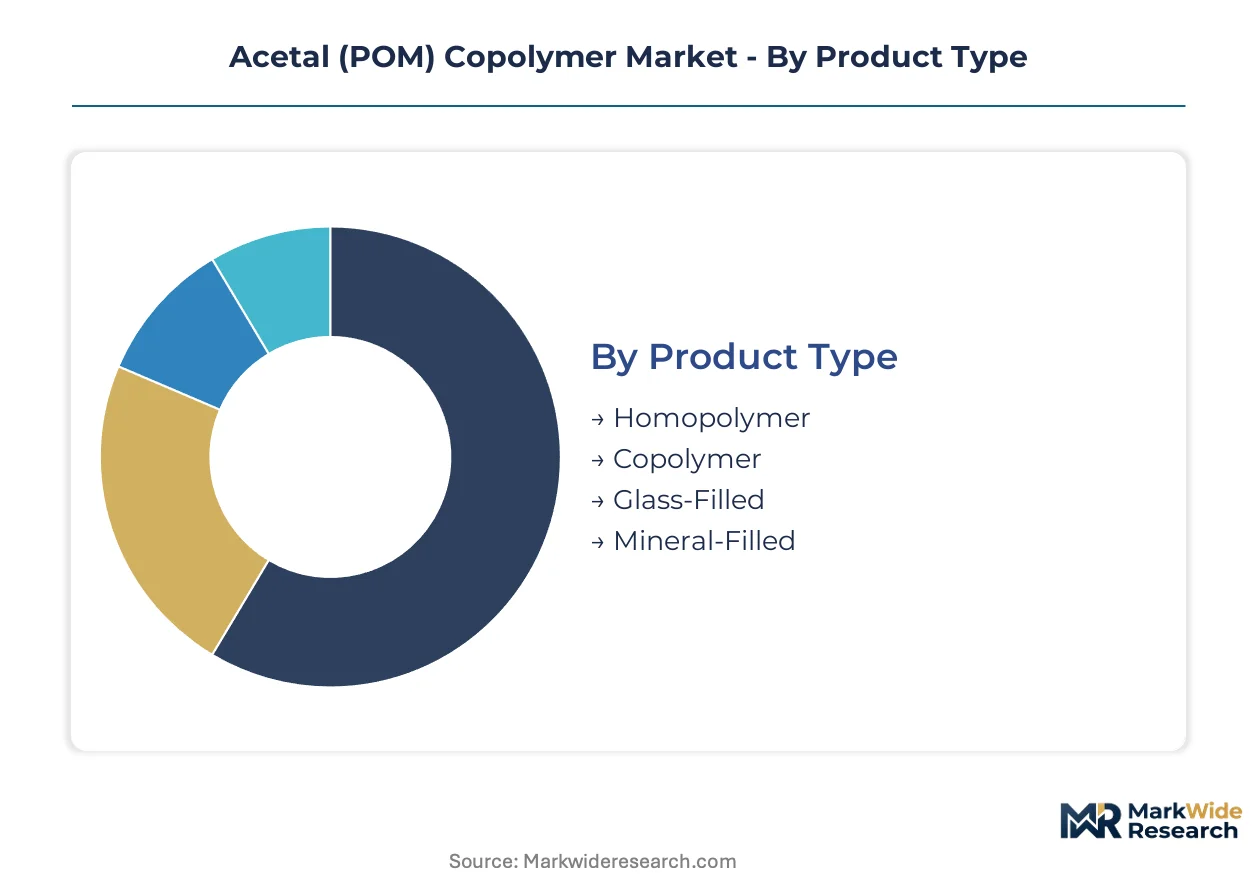
Acetal copolymer procurement patterns diverge sharply across product grades and customer tiers. Specification requirements from automotive OEMs, industrial component makers, and electrical manufacturers create distinct demand clusters with incompatible certification and performance thresholds.
Product Type:
Cost tier differentiation separates commodity grades from engineered formulations with embedded compliance premiums.
- Homopolymer:Delivers maximum crystallinity and stiffness for precision gear applications where creep resistance determines part longevity. Demand concentrates in Stuttgart and Nagoya automotive transmission suppliers specifying Delrin-equivalent grades for load-bearing mechanical components.
- Copolymer:Superior hydrolytic stability and broader chemical resistance make this the default specification for fuel system components and plumbing fixtures. Processors in China's eastern manufacturing corridor prioritize copolymer processability for high-volume injection molding of automotive under-hood parts.
- Glass-Filled:Reinforced formulations with 25-30% fiber content enable metal replacement in structural brackets.
- Mineral-Filled:Lower-cost option for non-structural interior automotive clips where dimensional stability matters less than material economy.
Copolymer commands the established base. The steepest expansion runs through glass-filled grades.
Application:
End-use performance requirements dictate formulation selection and certification pathways.
- Automotive Parts:Direct injection fuel rails, quick-connect fittings, and under-hood components specify hydrolysis-resistant grades capable of withstanding biofuel blends and glycol coolant exposure. German and Japanese OEM procurement teams enforce REACH Article 33 disclosure and EPA emission compliance through qualified supplier lists.
- Consumer Goods:Faucet cartridges, appliance components, and food-contact applications require FDA approvals and NSF drinking water certifications. North American plumbing fixture manufacturers in Michigan and Ohio represent concentrated demand for certified low-emission grades.
- Industrial Components:Precision gears, conveyor system parts, and bearing housings prioritize dimensional tolerance and wear resistance.
- Electrical Insulators:Connector housings and switchgear components concentrate margin pools for UL-certified flame-retardant variants.
Automotive parts command the established base. The steepest expansion runs through electrical insulators.
End User:
Customer type determines contract structure, volume scale, and technical service intensity.
- Manufacturers:Injection molders and extrusion houses serving multiple industries require flexible procurement with spot market access and regrind programs.
- OEMs:Tier-one automotive and appliance manufacturers negotiate 3-5 year offtake agreements with embedded price collars and volume flex provisions. Mercedes-Benz and BMW procurement teams now specify minimum regrind content thresholds in sustainability scorecards.
- Distributors:Channel intermediaries face margin compression as resin producers bypass tiers through direct mill-to-molder digital platforms.
- Retailers:Small-volume processors dependent on distributor channels encounter less favorable terms and limited technical support.
OEMs command the established base. The steepest expansion runs through manufacturers.
Form:
Physical format determines processing equipment compatibility and supply chain logistics.
- Pellets:Standard injection molding feedstock dominating high-volume automotive and consumer goods production.
- Sheets:Thermoforming and machining stock for industrial component fabricators requiring near-net-shape starting material.
- Rods:Bar stock for precision gear and bearing manufacturers using CNC machining centers.
- Films:Specialized format for electrical insulation and thin-wall applications with tight thickness tolerances.
Pellets command the established base. The steepest expansion runs through films.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure anchors European acetal resin distribution, while China's Ningbo-Zhoushan port complex manages the world's largest formaldehyde derivative throughput.
United States
Automotive fuel system manufacturers in Michigan and Ohio specify POM copolymer for direct injection components and biofuel-resistant fittings. EPA formaldehyde emission standards under the Toxic Substances Control Act constrain resin production facility operations, forcing thermal oxidizer upgrades. The Ohio River Valley chemical corridor hosts compounding operations serving tier-one automotive suppliers with REACH-compliant low-emission grades.
Germany
Stuttgart-based transmission suppliers demand Delrin-equivalent homopolymer grades for precision gear applications where creep modulus determines specification. REACH Article 33 disclosure requirements pressure converters toward certified low-emission copolymer formulations. The Ludwigshafen chemical cluster concentrates specialized compounding capabilities for industrial component makers requiring tight dimensional tolerances.
China
Injection molders in the Yangtze River Delta serve domestic automotive OEMs and export-oriented consumer electronics brands with high-volume copolymer processing. GB standards and MIIT regulations govern formaldehyde emissions in resin production facilities. Shandong and Jiangsu provinces cluster raw acetal resin capacity, exposing buyers to single-origin disruption risk and logistics bottlenecks.
Japan
Nagoya automotive OEM procurement teams enforce 3-5 year resin supply contracts with volume flex provisions and technical service commitments. METI industrial standards and JIS certification requirements shape material qualification pathways for precision mechanical components. The Chubu region concentrates tier-one supplier engineering centers specifying hydrolysis-resistant grades for hybrid powertrain applications.
South Korea
Battery module manufacturers seek hydrolysis-resistant polymers capable of 150°C continuous service in glycol coolant environments for electric vehicle thermal management. MFDS regulations and K-REACH chemical registration requirements create compliance thresholds for imported resin grades. The Busan-Ulsan industrial belt hosts compounding operations serving Hyundai-Kia procurement networks with glass-filled structural formulations.
Acetal (POM) Copolymer Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. The vendor base concentrates among integrated resin producers with captive formaldehyde supply and regional compounding networks. Three archetypes dominate: integrated petrochemical conglomerates with backward control over feedstock, specialized engineering plastics compounders with certification depth, and regional toll processors serving distributor channels. Capacity expansion and direct mill-to-molder digital procurement represent the dominant competitive vectors reshaping channel economics.
Among integrated petrochemical conglomerates, Celanese Corporation and BASF SE exemplify the feedstock-integrated archetype with manufacturing networks spanning multiple continents. DuPont occupies a position on the legacy brand recognition tier for precision gear applications. Korea Engineering Plastics Co., Ltd. and Polyplastics Co., Ltd. represent Asia-Pacific specialists with regional compounding depth. Mitsubishi Gas Chemical Co., Inc. anchors the Japanese engineering plastics segment with formaldehyde derivative integration.
| Leading Market Players |
|---|
| Celanese Corporation |
| BASF SE |
| DuPont |
| Polyplastics Co., Ltd. |
| Asahi Kasei Corporation |
| Korea Engineering Plastics Co., Ltd. |
| Mitsubishi Gas Chemical Co., Inc. |
| Daicel Corporation |
| Delrin USA, LLC |
| Others |
Value Chain & Pricing Dynamics
The Ningbo-Zhoushan port complex handles formaldehyde derivative throughput that feeds Shandong and Jiangsu resin capacity, creating freight cost asymmetries between coastal Chinese processors and inland European compounders who face divergent landed cost structures for REACH-certified versus standard grades.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and volume commitment. Premium tiers capture UL-certified flame-retardant and NSF drinking water grades where compliance documentation commands margin premiums. Standard grades serve high-volume automotive molders with 3-5 year offtake agreements. Economy tiers supply distributor channels for small processors. Cost compression in standard grades is intensifying because methanol feedstock volatility transmits directly to non-integrated compounders. Independent molders dependent on spot purchasing exhibit highest price sensitivity, while tier-one automotive suppliers with embedded volume commitments show lowest elasticity.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculations for REACH-compliant grade procurement. Raw acetal resin capacity clusters in Shandong and Jiangsu provinces, with secondary compounding networks in Germany and the United States. Feedstock economics hinge on methanol pricing and natural gas cost pressure. Single-origin concentration in China's eastern manufacturing corridor exposes buyers to logistics bottlenecks and disruption risk. Distribution runs through direct mill-to-molder digital platforms that displace traditional distributor tiers for high-volume processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle thermal management applications represent an early-cycle expansion story, with battery module housings and coolant manifolds driving hydrolysis-resistant polymer adoption before mainstream penetration.
For Market Incumbents: Build certification moats around UL 94 V-0 flame-retardant and NSF/ANSI 61 drinking water approvals to defend against emerging regional compounders in South Korea and China. Invest in thermal oxidizer upgrades to maintain EPA formaldehyde emission compliance as small-scale processors face facility closures. Anchor procurement leverage through backward integration into captive formaldehyde supply. For New Entrants and Emerging Players: Build out toll compounding arrangements serving Michigan and Ohio automotive tier suppliers squeezed by incumbent direct contracting. Target North American plumbing fixture manufacturers seeking certified low-emission grades for valve bodies and faucet cartridges. Pursue platform-based spot contracting as the go-to-market angle to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized engineering plastics compounders with certification depth over commodity resin producers. The 5-10 year viability window rewards targets with embedded automotive OEM relationships and sustainability scorecard compliance. Monitor formaldehyde reclassification proceedings under EU CLP framework as the inflection indicator for supply chain qualification disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Mercedes-Benz and BMW procurement teams now specify minimum regrind content thresholds. |
| Backward Integration | Celanese leverages captive formaldehyde supply to sustain pricing leverage on copolymer grades. |
| Green Manufacturing Transition | Closed-loop recycling of post-industrial POM scrap virtualizes virgin resin demand in closed supply chains. |
| Capacity Expansion | Glass-filled grade innovation enables metal replacement in structural brackets for load-bearing applications. |
| Joint Venture | Regional toll processors seek partnerships to maintain market access amid EPA thermal oxidizer mandates. |
Study Parameters
Initial hypotheses were tested against primary input from resin procurement managers at tier-one automotive suppliers, compounding plant engineers, distribution channel partners, and technical R&D directors at engineering plastics compounders and refined through secondary validation against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA emission compliance records. Bottom-up demand modeling across grade tiers and end-use segments was triangulated with top-down market sizing.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry cluster, certification level, and regional production hub. CAGRs were derived from growth driver elasticity analysis and substitution dynamics. Industry-specific forecast inputs incorporated automotive production schedules, electric vehicle platform ramp timelines, and plumbing fixture construction cycle correlation.
Stress conditions across methanol price volatility, formaldehyde reclassification scenarios, and Chinese logistics disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory stability and feedstock cost transmission. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Homopolymer Resins Market
Polymers & Resins
Global Polyethylene (PE) Foam Market
Polymers & Resins
Polyolefin Compound Market
Polymers & Resins
Liquid Saturated Polyester Resin Market
Polymers & Resins
Global Vinyl Ester Market
Polymers & Resins
UV Cure Resins Market
Polymers & Resins
Melamine Formaldehyde Resin Powder Market
Polymers & Resins
South America Polyamide Market
Polymers & Resins
Metallocene Polyolefin Market
Polymers & Resins
Polyvinyl Chloride Resins Market
Polymers & Resins
Polyetherketone Market
Polymers & Resins
Vinyl Acetate Monomer (VAM) Market
Polymers & Resins
Polylysine Market
Polymers & Resins
Acrylonitrile Butadiene Styrene (ABS) Market
Polymers & Resins
Latent Curing Agents for Epoxy Resin Market
Polymers & Resins
Polymer Resin Market