
 China Automotive Parts Magnesium Die Casting Market | 2026-2036
China Automotive Parts Magnesium Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
China Automotive Parts Magnesium Die Casting Market Outlook
China is rewriting the competitive map for automotive magnesium die casting as domestic capacity expansions in Jiangsu and Zhejiang provinces draw foreign joint ventures inland. Ryobi Group leverages its hot-chamber expertise to supply transmission housings for domestic EV platforms. Meridian Lightweight Technologies anchors North American design know-how within Chinese manufacturing joint ventures. Georg Fischer AG competes through precision-machined chassis components serving European OEMs with local Chinese production.
Automotive parts magnesium die casting involves injecting molten magnesium alloy—typically AZ91D or AM60B with 90% magnesium content—into hardened steel dies at temperatures between 640°C and 680°C to produce complex, thin-walled structural components with high strength-to-weight ratios. The process primarily serves vehicle weight reduction mandates where every kilogram saved improves fuel efficiency or electric range. Engine blocks and transmission housings dominate current volume given their mature tooling ecosystems and established supply agreements with OEMs. Chassis components represent the fastest-growing product category as multi-material vehicle architectures integrate magnesium cross-members and subframes for structural rigidity without mass penalty.
China's Ministry of Ecology and Environment enforces dual carbon targets that restrict energy-intensive alloy smelting, while SAMR administers GB standards governing magnesium alloy composition and die-cast dimensional tolerances for automotive safety. BIS-equivalent conformity assessments for export-bound components add compliance layers for Tier-1 suppliers serving multinational OEMs. Stakeholders must monitor how MEE emissions audits reshape foundry location economics and whether GB standard revisions will mandate recycled magnesium content thresholds.
Market Dynamics
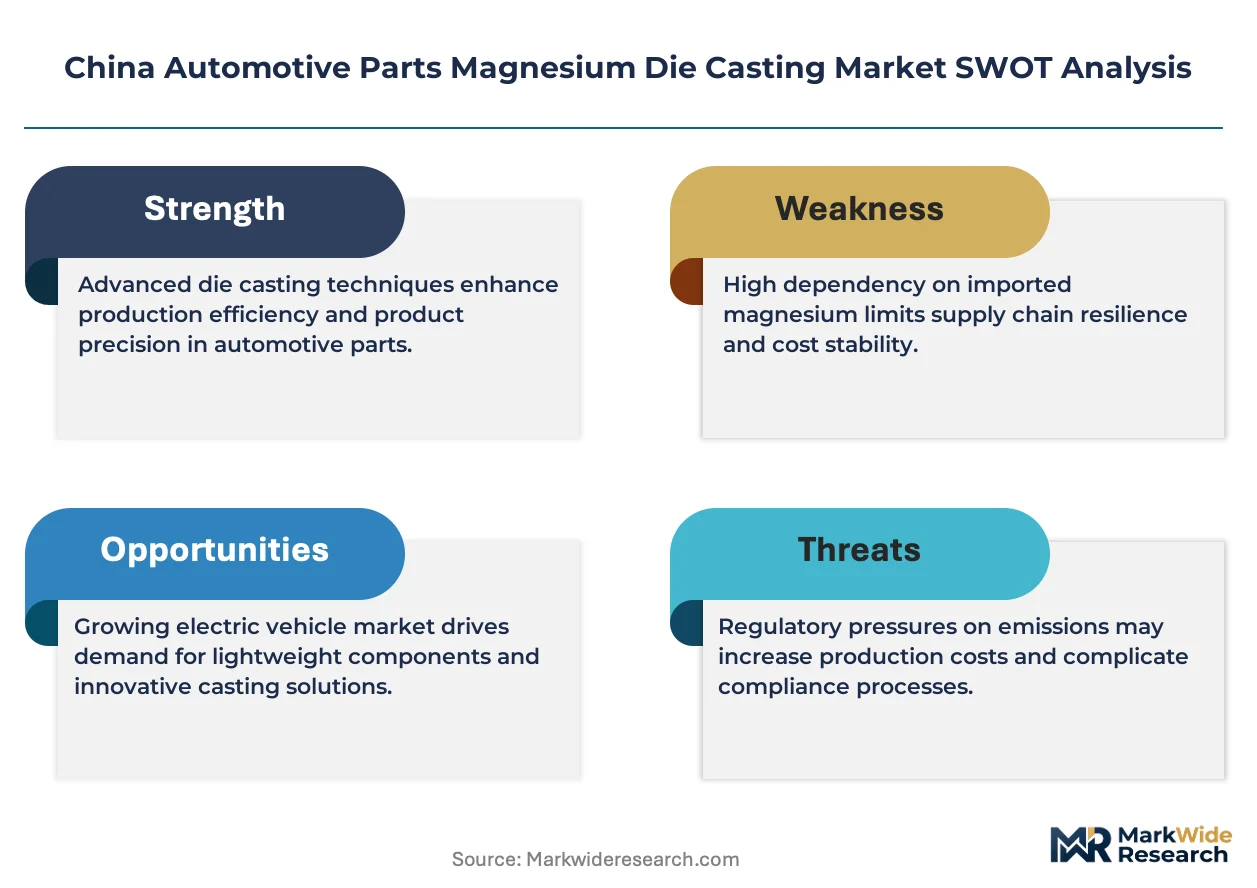
China's dual carbon mandates under MEE oversight are compressing foundry economics and accelerating process modernization across the Yangtze River Delta cluster. Tier-1 suppliers face simultaneous pressure to reduce smelting emissions while scaling output for domestic EV platforms.
Growth Catalysts
- Dual carbon enforcement:MEE emissions audits are forcing alloy processors to adopt cleaner melting technologies, creating competitive advantage for compliant foundries.
- EV platform expansion:Domestic electric vehicle OEMs specify magnesium transmission housings and battery enclosures to offset lithium-ion pack mass.
- Jiangsu-Zhejiang capacity clustering:Co-location of die-casting facilities with vehicle assembly plants in the Yangtze River Delta reduces logistics costs and tooling lead times.
Market Restraints
- Primary magnesium price volatility:Energy-intensive smelting of dolomite ore ties alloy costs to thermal power pricing, compressing foundry margins during peak demand periods.
- AZ91D supply concentration:Domestic alloy production concentrates in Shanxi and Ningxia provinces, exposing Tier-1 suppliers to regional logistics disruptions.
- Aluminum substitution in chassis:High-pressure aluminum die casting competes for structural subframes where crash-performance requirements exceed current magnesium alloy capabilities.
Strategic Opportunities
- Recycled magnesium mandates:Anticipated GB standard revisions may mandate post-consumer content thresholds, rewarding early movers with captive recycling infrastructure.
- Hot-chamber process convergence:Integration of vacuum-assisted die casting with real-time thermal monitoring enables thinner-wall components for battery tray applications.
- Central China inland expansion:Hubei and Anhui provinces offer lower energy costs and proximity to emerging EV assembly corridors outside the saturated coastal cluster.
Industry Challenges
- Process engineer scarcity:Hot-chamber magnesium die casting requires specialized expertise in melt handling and oxidation prevention that outpaces vocational training output.
- GB certification timelines:SAMR dimensional tolerance testing for safety-critical chassis components extends qualification cycles for new part introductions.
- Multi-material integration complexity:Joining magnesium castings to aluminum extrusions and steel stampings in mixed-material architectures demands novel friction-stir welding protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Automotive Parts Magnesium Die Casting Market |
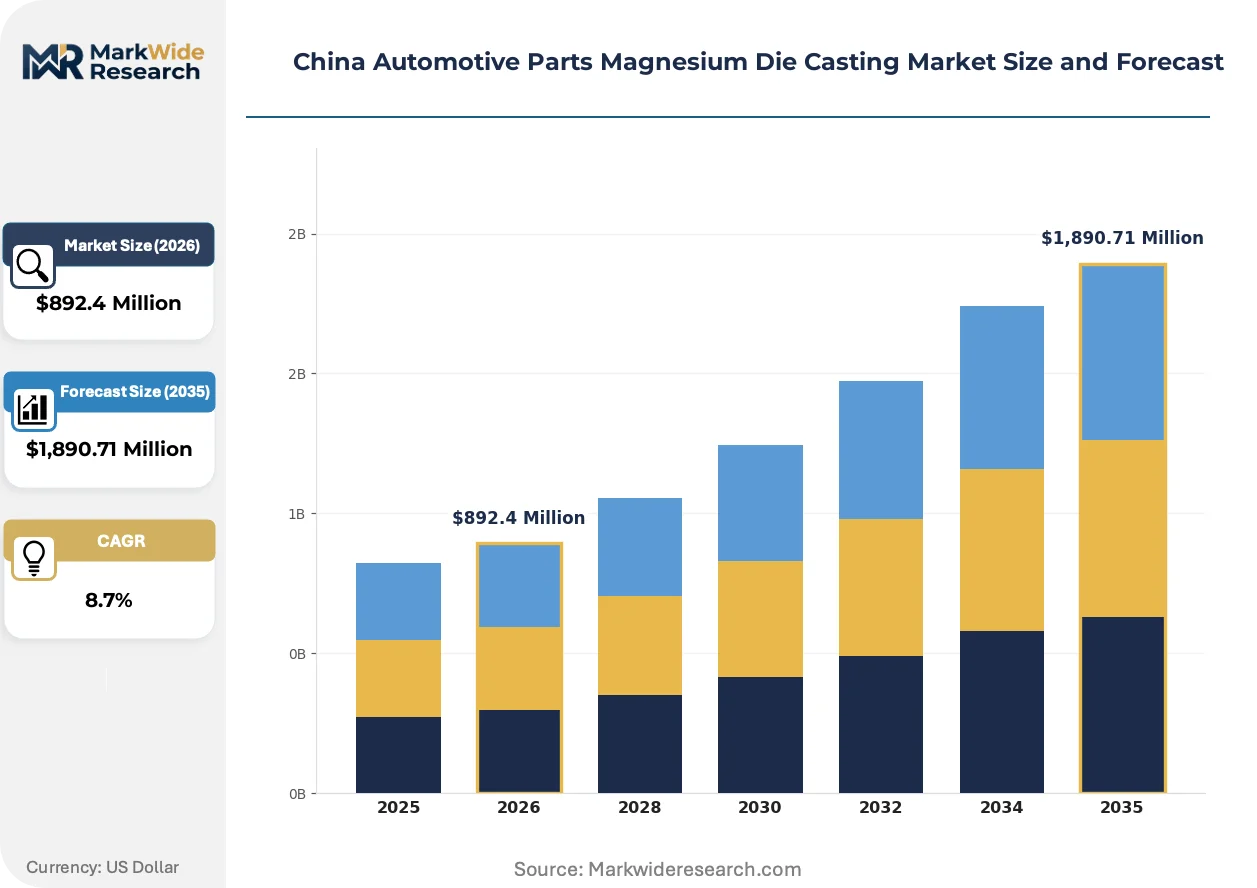
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,890.71 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Body Panels, Engine Blocks, Transmission Housings, Chassis Components Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Performance Vehicles Manufacturing Stage: Prototype Production, Mass Production, Secondary Operations, Quality Testing End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Pace Industries, Ryobi Group, Meridian Lightweight Technologies, KSM Casting Group, Handtmann Metallgusswerk GmbH, Georg Fischer AG, Shiloh Industries, CITIC, Gibbs Die Casting Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Automotive Parts Magnesium Die Casting Market Strategic Shifts
Process intensification and regulatory tightening are compressing traditional foundry models while opening technical pathways for lighter, more complex structural castings. Equipment suppliers and alloy developers are racing to match the precision requirements of next-generation EV architectures.
Thixomolding semi-solid magnesium forming is rendering obsolete conventional cold-chamber die casting for intricate electronic housing geometries. Domestic EV battery suppliers specify thixomolded enclosures for thermal management modules, eliminating porosity defects that plague liquid-metal injection. This process shift is compressing tooling changeover schedules and reducing secondary machining requirements for thin-wall components.
MEE enforcement of dual carbon targets is mandating furnace electrification and flue-gas capture retrofits at magnesium smelters. Alloy processors in Ningxia province face production suspensions during emissions audit periods, disrupting just-in-time supply to Yangtze River Delta foundries. Tier-1 suppliers are responding by qualifying secondary smelters with integrated renewable power contracts.
Consolidated procurement by domestic EV OEMs is displacing fragmented sourcing through independent trading houses. BYD and NIO now contract directly with alloy processors for multi-year AZ91D supply agreements, bypassing traditional distributor networks. This channel compression is most visible in Jiangsu province, where foundries dedicate furnace capacity to single-customer qualification runs.
China Automotive Parts Magnesium Die Casting Market Segmentation
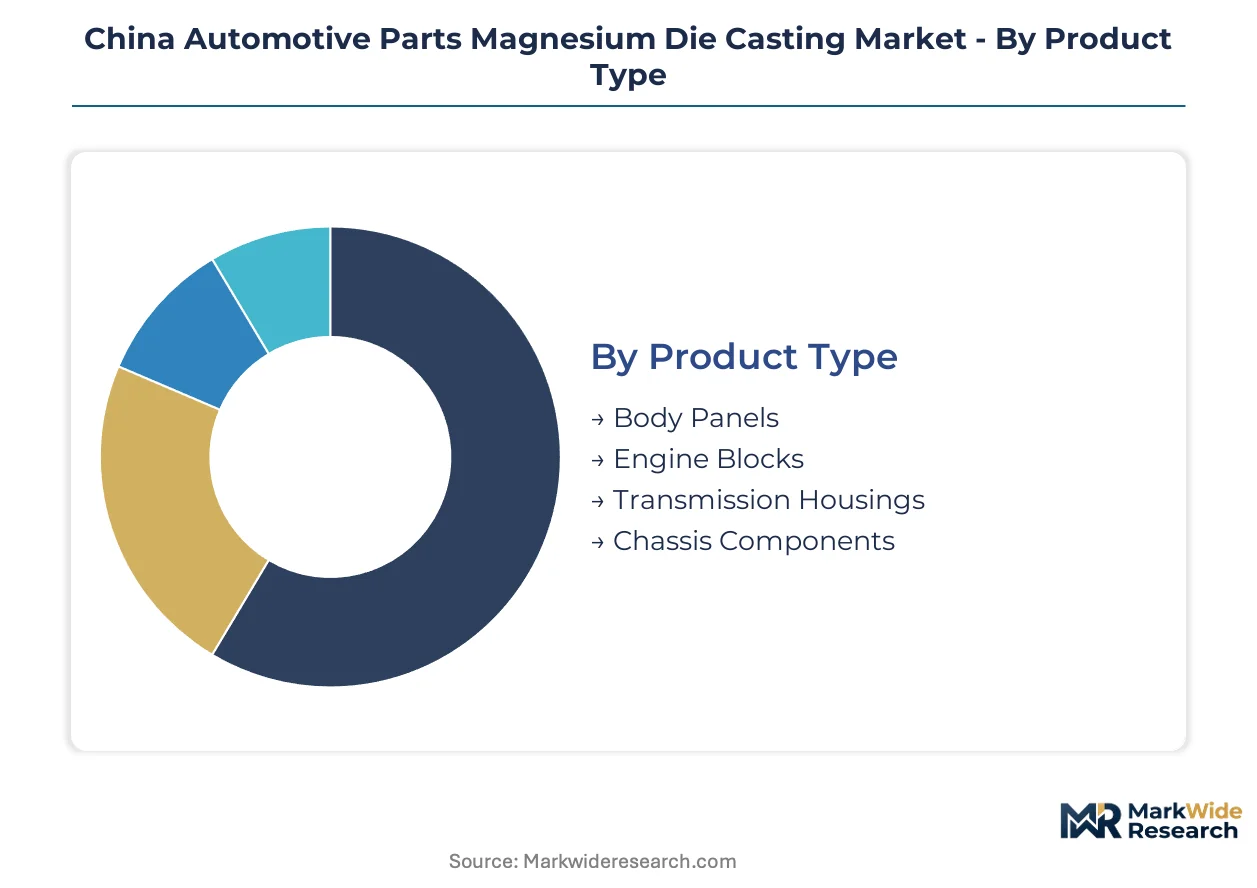
Magnesium die casting serves heterogeneous demand profiles across vehicle architectures, production scales, and supply chain tiers. Segment boundaries reflect technical maturity, regulatory pressure points, and procurement consolidation patterns shaping foundry investment decisions.
Product Type:
Application intensity varies by structural load requirements and surface finish specifications across vehicle assemblies.
- Transmission Housings:AZ91D alloy dominates with excellent castability and corrosion resistance for gear containment. Demand concentrates in Yangtze River Delta foundries serving domestic EV platforms where integrated e-axle architectures require compact, lightweight housings to offset battery mass.
- Chassis Components:AM60B delivers superior ductility and impact absorption for cross-members and subframes. Jiangsu province foundries report accelerating qualification cycles for magnesium subframes as multi-material architectures displace stamped steel in premium EV platforms.
- Engine Blocks:Conventional internal combustion applications retain volume through established tooling amortization and repair part demand.
- Body Panels:Thin-wall cosmetic applications remain limited by surface finish requirements and dent resistance thresholds.
Transmission housings command the established base. The steepest expansion runs through chassis components.
Application:
Vehicle electrification intensity reshapes alloy specification and volume concentration across mobility segments.
- Electric Vehicles:Battery enclosure and thermal management module demand drives thixomolding adoption for porosity-critical applications. Zhejiang province suppliers co-locate with NIO and XPeng assembly plants to reduce logistics friction for just-in-sequence delivery.
- Passenger Vehicles:ICE-dominant platforms retain magnesium steering wheels and seat frames through mature supply agreements. Shanxi alloy processors maintain furnace dedication for high-volume interior component programs.
- Commercial Vehicles:Weight reduction mandates for electric bus and light truck fleets create emerging specification pathways.
- Performance Vehicles:Low-volume, high-specification chassis castings prioritize mechanical properties over unit cost optimization.
Passenger vehicles anchor current volume. Electric vehicle applications are climbing the fastest as platform architectures consolidate.
Manufacturing Stage:
Process depth determines margin capture and technical barrier positioning for foundry operators.
- Mass Production:Hot-chamber die casting at 640-680°C with automated ladling systems achieves cycle times under 60 seconds for transmission housings. Jiangsu-Zhejiang cluster foundries invest in real-time thermal monitoring to maintain dimensional stability across high-volume runs.
- Secondary Operations:CNC machining, surface treatment, and assembly integration capture value beyond raw casting. Tier-1 suppliers in Anhui province are qualifying captive machining centers to meet SAMR dimensional tolerance requirements for safety-critical chassis components.
- Prototype Production:Soft tooling and rapid iteration support new platform development cycles.
- Quality Testing:X-ray inspection and metallurgical validation ensure compliance with GB standards for automotive safety applications.
Mass production secures the revenue foundation. Secondary operations offer the steepest margin expansion trajectory.
End User:
Procurement consolidation and technical specification authority determine foundry customer strategy.
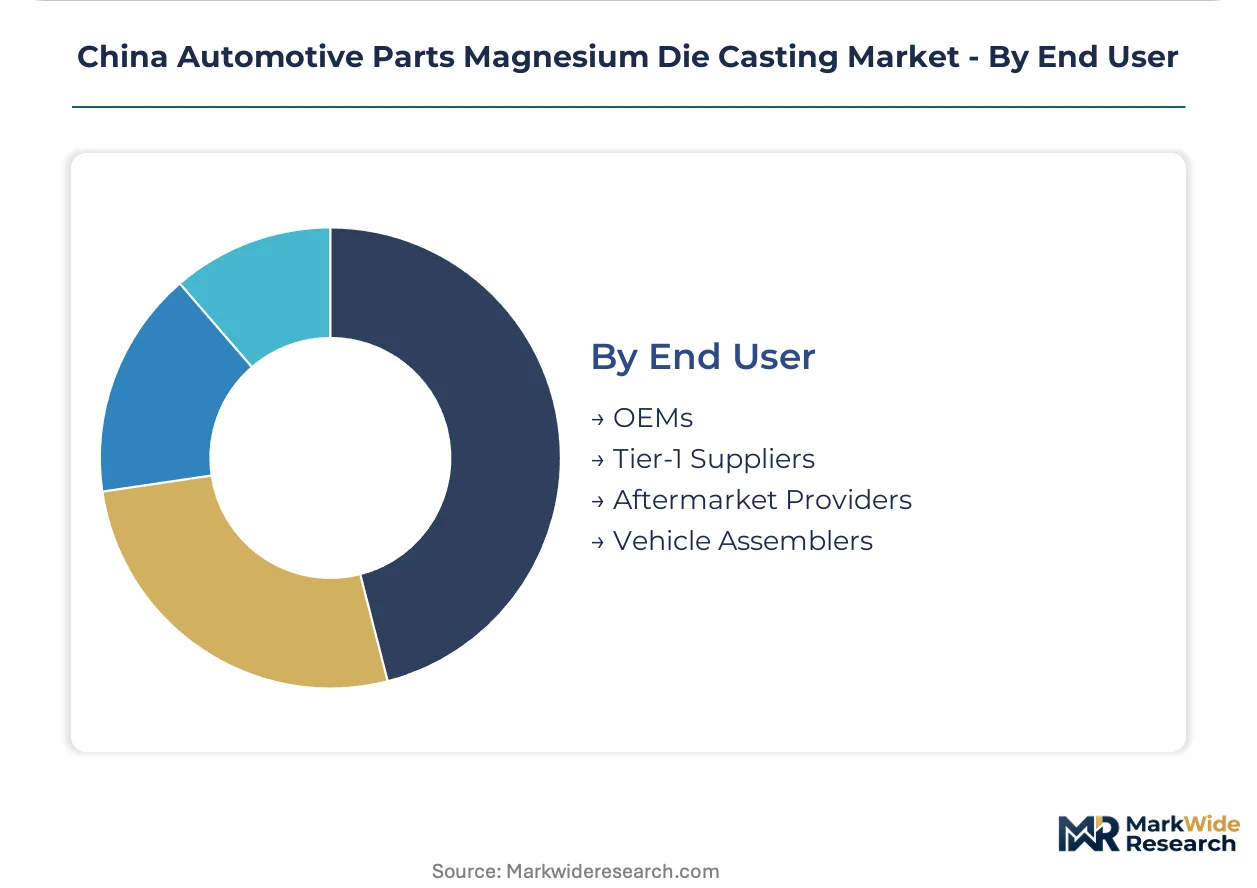
- Tier-1 Suppliers:Continental and Bosch-affiliated foundries manage multi-OEM programs with dedicated furnace qualification runs. These suppliers absorb SAMR certification complexity and interface directly with vehicle assembly sequencing systems.
- OEMs:BYD and NIO direct alloy procurement agreements bypass traditional distributor networks, compressing channel margins. Hubei province foundries report contract structures tying furnace capacity to single-customer volume commitments.
- Vehicle Assemblers:Contract manufacturers without captive casting capability source through qualified supplier lists.
- Aftermarket Providers:Replacement transmission housings and engine components serve repair market demand with lower specification stringency.
Tier-1 suppliers dominate technical qualification pathways. OEM direct procurement is gaining share fastest through platform consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta port network underwrites China's dominance in automotive magnesium die casting, with Ningbo-Zhoushan and Shanghai terminals handling dolomite ore imports and alloy exports for the world's largest vehicle production base.
Jiangsu Province
BYD and NIO assembly plants in Changzhou and Suzhou pull die-cast transmission housings from co-located foundries. SAMR enforces GB standards for dimensional tolerances on safety-critical chassis components. The Taicang-Nantong corridor concentrates hot-chamber capacity dedicated to EV platform supply.
Zhejiang Province
Ningbo anchors primary magnesium smelting with integrated alloy production feeding Yangtze River Delta foundries. MEE emissions audits suspend operations during peak pollution periods, forcing qualification of backup suppliers. The Hangzhou Bay industrial belt hosts thixomolding specialists serving battery enclosure demand.
Anhui Province
Hefei's emergence as an EV assembly hub draws inland capacity expansion from coastal suppliers seeking lower energy costs. Provincial industrial policy offers tax incentives for foundries establishing captive machining centers. The Hefei-Chaohu manufacturing corridor builds secondary operations capacity for SAMR-certified chassis components.
Hubei Province
Wuhan's automotive heritage supports magnesium die casting for commercial vehicle and bus electrification programs. Central China location reduces logistics friction to emerging EV corridors outside saturated coastal markets. The Wuhan-Xiaogan industrial zone qualifies suppliers for direct OEM procurement contracts bypassing distributor networks.
Shanxi Province
Taiyuan and Yuncheng concentrate domestic primary magnesium smelting from local dolomite reserves, supplying alloy to downstream foundries. Energy-intensive smelting operations face MEE production caps during thermal power shortage periods. The province maintains furnace dedication for high-volume interior component programs serving legacy passenger vehicle platforms.
China Automotive Parts Magnesium Die Casting Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in a structure shaped by OEM procurement consolidation and alloy supply concentration. The vendor base splits between captive foundries serving single OEM platforms and independent suppliers qualifying across multiple vehicle programs. Three archetypes dominate: coastal cluster specialists with hot-chamber expertise, inland expansionists capturing central China EV growth, and alloy-integrated players controlling primary smelting capacity. Competitive moves center on geographic relocation to lower-cost provinces and backward integration into captive magnesium recycling infrastructure.
Among Japan-based industrial conglomerates, Ryobi Group exemplifies the hot-chamber specialist archetype with established Yangtze River Delta presence. Swiss-engineered precision manufacturers like Georg Fischer AG occupy positions serving European OEMs through Chinese production joint ventures. North American lightweighting specialists including Meridian Lightweight Technologies anchor design-to-manufacture capabilities within domestic joint venture structures. These players represent contrasting geographic origins and tier positioning without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| Pace Industries |
| Ryobi Group |
| Meridian Lightweight Technologies |
| KSM Casting Group |
| Handtmann Metallgusswerk GmbH |
| Georg Fischer AG |
| Shiloh Industries |
| CITIC |
| Gibbs Die Casting Group |
| Others |
Value Chain & Pricing Dynamics
Primary magnesium smelter concentration in Shanxi and Ningxia provinces exposes Tier-1 suppliers to MEE emissions audit suspensions that compress pricing tier spreads between premium SAMR-certified chassis components and standard transmission housings while forcing supply chain redundancy investments.
Pricing Analysis
Volume-discount tiering structures separate premium AM60B chassis castings with full SAMR dimensional certification from standard AZ91D transmission housings and economy-grade interior components. Price differentiation hinges on alloy grade purity and GB standard compliance tier, with OEM direct procurement agreements compressing distributor margins. Cost compression in the standard tier is intensifying because consolidated BYD and NIO contracts eliminate spot-market flexibility. Aftermarket providers exhibit highest price sensitivity; OEM captive foundries show least.
Supply Chain Analysis
Supplier-financing facilities with extended payment terms have become standard for Yangtze River Delta foundries qualifying Hubei and Anhui inland capacity. Geographic supply concentration centers on China for primary smelting, with secondary alloy processing clustering in Jiangsu and Zhejiang. Raw material dependencies include dolomite ore, thermal power for smelting energy, and specialized hot-chamber die casting equipment. Single-source vulnerability runs through Shanxi-Ningxia smelter concentration during MEE audit periods. Distribution feeds from foundry co-location with EV assembly plants through just-in-sequence delivery contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hot-chamber process engineer scarcity constrains foundry expansion timelines, with specialized melt handling expertise outpacing vocational training output across the Yangtze River Delta cluster.
For Market Incumbents: Insulate furnace capacity through captive recycling infrastructure investments ahead of anticipated GB post-consumer content mandates. Secure SAMR certification for safety-critical chassis components before qualification cycles extend further. Aluminum high-pressure die casting substitution for structural subframes represents the priority threat demanding alloy ductility R&D response. For New Entrants and Emerging Players: Central China inland provinces—specifically Hubei and Anhui—offer the most penetrable entry point with lower energy costs and proximity to emerging EV corridors outside saturated coastal markets. Battery enclosure thixomolding for thermal management modules presents a specification gap with limited incumbent qualification. Direct OEM procurement contract structures bypassing distributor networks provide the clearest go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors alloy-integrated players with captive smelting and secondary machining capabilities. Long-term viability over the coming decade hinges on backward integration into primary magnesium production or forward integration into SAMR-certified chassis component machining. Watch MEE enforcement intensity on Shanxi smelter production caps as the inflection signal for supply disruption premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Magnesium Recycling Infrastructure | Positions foundries ahead of anticipated GB post-consumer content mandates for automotive safety components. |
| SAMR Certification Investment for Chassis Components | Unlocks premium pricing tiers for AM60B subframes in multi-material EV architectures. |
| Inland Capacity Expansion to Hubei-Anhui Corridor | Reduces energy costs and MEE audit exposure while capturing central China EV assembly growth. |
| Thixomolding Process Qualification | Enables porosity-critical battery enclosure supply to domestic EV thermal management module specifications. |
| Direct OEM Procurement Contract Structuring | Bypasses distributor margin compression through multi-year AZ91D volume commitments with BYD and NIO. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SAMR regulatory filings, MEE emissions audit disclosures, and Yangtze River Delta industrial cluster development reports. Primary interviews engaged foundry operations managers, OEM platform engineers at BYD and NIO, Tier-1 supplier procurement leads, and alloy processor technical directors. Secondary validation drew from vehicle production databases, customs trade records for dolomite ore and magnesium alloy flows, and GB standard revision drafts. Bottom-up capacity modeling triangulated against top-down EV platform content-per-vehicle estimates.
Forecast inputs include segment-level alloy specification trends, MEE enforcement trajectory on smelter emissions, and EV platform architecture shifts toward multi-material construction. Segmentation dimensions span product type, propulsion architecture, manufacturing stage depth, and end-user procurement channel. CAGRs were derived from elasticity-adjusted volume projections across the analysis window. Industry-specific inputs incorporate thixomolding adoption curves and SAMR certification timeline assumptions.
Stress conditions across primary magnesium price volatility, MEE audit suspension frequency, and aluminum substitution rates for chassis applications were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on dual carbon policy continuity and EV platform consolidation patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Germany Passenger Vehicles Lubricants Market
Automotive Parts
UK Automotive Parts Zinc Die Casting Market
Automotive Parts
Global Automotive Hydraulic Brake Market
Automotive Parts
Automotive Intercooler Market
Automotive Parts
Automotive Fuel Rail Market
Automotive Parts
Autocatalyst Market
Automotive Parts
Global Automotive Door Hinges Market
Automotive Parts
Argentina Automotive Actuators Market
Automotive Parts
Automotive Paint Robots Market
Automotive Parts
Automotive Hydraulic Filters Market
Automotive Parts
Auto Parts Manufacturing Market
Automotive Parts
France Automotive Actuators Market
Automotive Parts
Motorcycle Battery Chargers Market
Automotive Parts
Automotive Valve Stem Seal Market
Automotive Parts
Automotive Electric Turbocharger Market
Automotive Parts
Fluid Couplings Market