
 Iran Automotive Engine Oils Market | 2026-2036
Iran Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Iran Automotive Engine Oils Market Foresight
Market Context with Strategic Players
The gap between premium synthetic formulations and commodity mineral oils is recalibrating channel economics across Iran's automotive lubricant sector. Sepahan Oil Company leverages its domestic refining integration to control feedstock costs for mid-tier blends. Ghatran Kaveh Motor Oil Co. competes through specialized distribution in Isfahan and Shiraz commercial corridors. FUCHS anchors its position among import-dependent premium buyers seeking OEM-certified specifications.
Technical Definition and Structural Segments
Iran automotive engine oils comprise base oil stocks blended with additive packages to reduce friction, dissipate heat, and prevent wear in internal combustion engines, with synthetic variants using Group III or PAO bases meeting API SP and ACEA C3 performance thresholds. Semi-synthetic grades occupy the fastest-expanding tier as Iranian fleet operators balance extended drain intervals against outright synthetic premiums. The 10W-40 viscosity grade dominates volume throughput due to compatibility with aging domestic vehicle parc, while 5W-30 gains share among newer passenger car imports. Heavy-duty trucks generate the most concentrated margin pool per liter sold, though passenger cars provide baseline volume stability.
Regulatory Frame and Forward-Looking Close
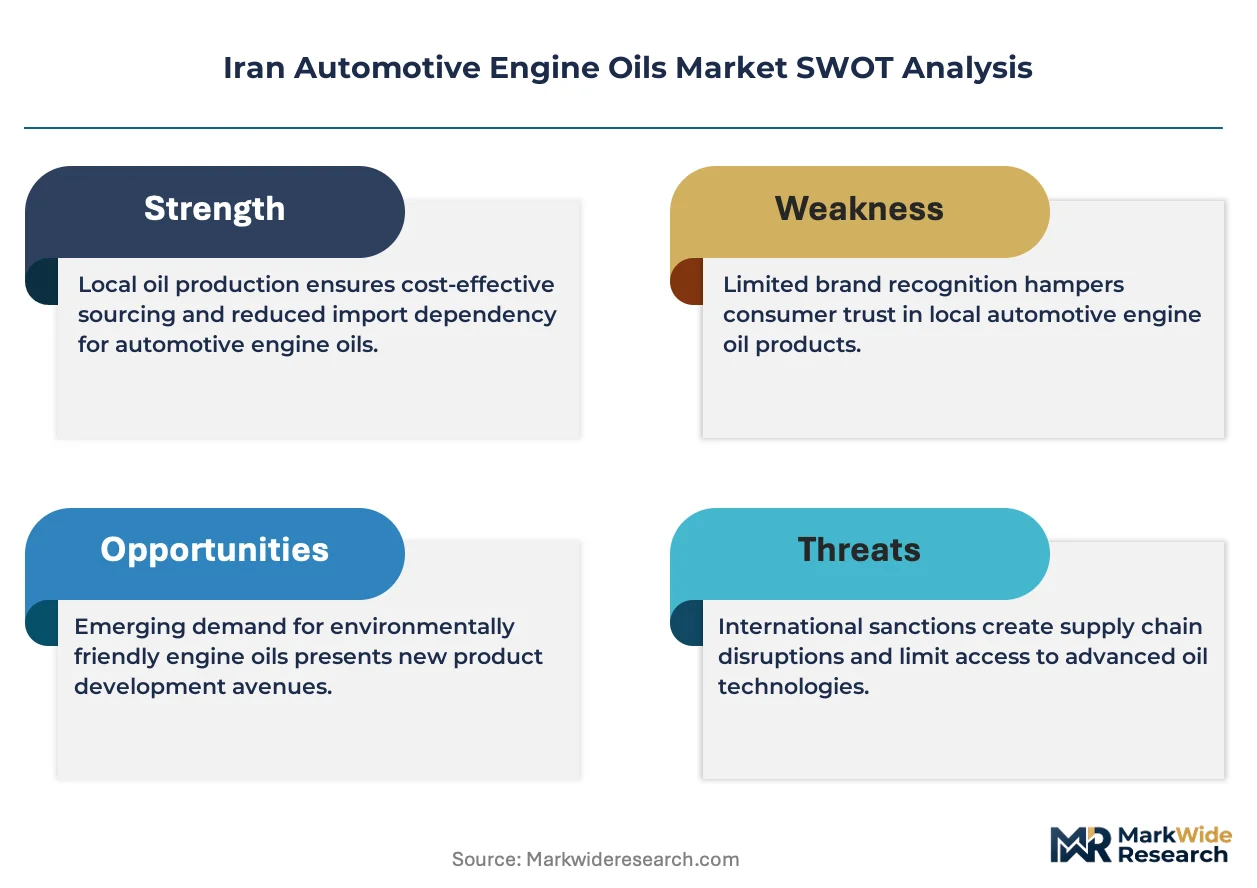
Iran's national standards body and the Institute of Standards and Industrial Research of Iran shape mandatory lubricant quality classifications, while the country's environmental regulator pushes waste oil recovery obligations that raise compliance costs for smaller blenders. The national oil company influences base oil allocation priorities that constrain independent formulators during supply tightness. Stakeholders must monitor whether domestic refining upgrades close the API Group II/III gap or perpetuate import dependence for premium base stocks.
Market Dynamics
Iran's automotive lubricant sector operates under the structural tension between domestic base oil availability and the technical requirements of modern engine platforms. The national oil company's allocation priorities determine feedstock access for independent blenders, while the Institute of Standards and Industrial Research of Iran escalates performance benchmarks that outpace local refining capabilities.
Growth Catalysts
- Commercial fleet expansion:Heavy-duty trucking corridors along the Tehran-Mashhad and Tehran-Bandar Abbas routes are extending lubricant consumption volumes through higher annual mileage accumulation and shorter drain intervals.
- API SP and ACEA C3 adoption:The country's national standards body is incrementally aligning mandatory classifications with international performance thresholds, forcing formulation upgrades that expand addressable premium segments.
- Isfahan manufacturing cluster density:Vehicle assembly plants and aftermarket service infrastructure concentrate demand in a 200-kilometer radius, reducing logistics costs for regional distributors.
Market Restraints
- API Group II/III base oil deficit:Domestic refining output remains weighted toward Group I stocks, forcing import dependence for synthetic and semi-synthetic formulations when sanctions disrupt trade finance channels.
- Waste oil recovery mandates:Environmental compliance obligations raise fixed costs for smaller blending operations lacking dedicated collection and re-refining infrastructure.
- Currency volatility exposure:Additive packages priced in hard currencies create margin compression for formulators unable to pass through exchange rate movements to price-sensitive fleet operators.
Strategic Opportunities
- Khorasan Razavi underpenetration:Mashhad's position as a pilgrimage and logistics hub hosts growing vehicle density with limited premium lubricant distribution depth relative to Tehran and Isfahan.
- Dual-fuel engine compatibility:CNG-gasoline hybrid powertrains prevalent in Iranian passenger cars require specialized thermal stability formulations that commodity mineral oils fail to deliver.
- Digital fleet management integration:Telematics-enabled oil condition monitoring is creating data-driven procurement relationships that bypass traditional distributor intermediaries.
Industry Challenges
- Additive chemist scarcity:Formulation expertise for low-SAPS (sulfated ash, phosphorus, sulfur) packages compatible with exhaust after-treatment systems concentrates in a handful of technical specialists.
- OEM certification timeline compression:Accelerated approval cycles for new vehicle platforms leave limited validation windows for lubricant qualification against proprietary engine tests.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iran Automotive Engine Oils Market |
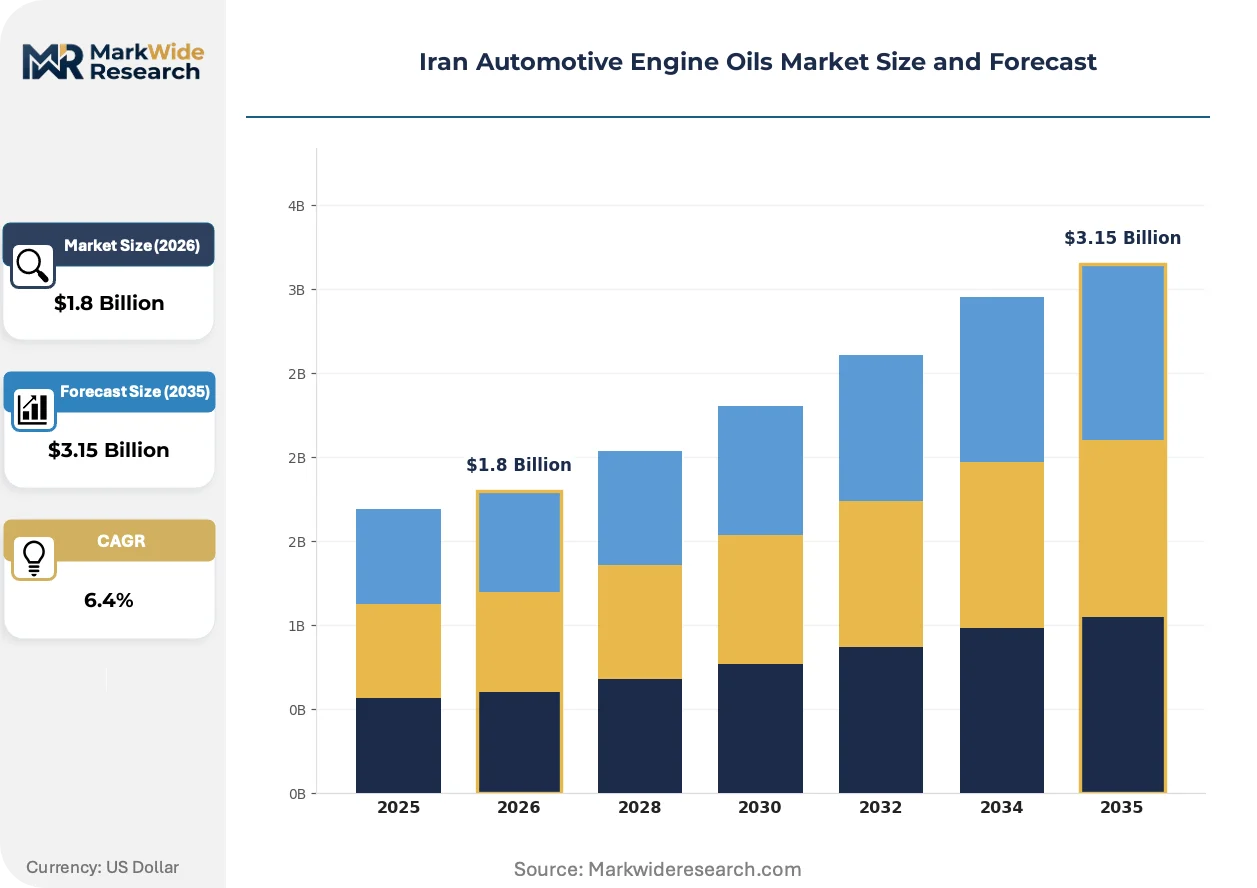
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Semi-Synthetic, Conventional, Mineral Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 End User: Passenger Cars, Commercial Vehicles, Motorcycles, Heavy-Duty Trucks Packaging Type: Bottle, Drum, Bulk, Pail |
| Companies Covered | Sepahan Oil Company, Ghatran Kaveh Motor Oil Co., Iranol Oil Company, FUCHS, Addinol, Behran Oil Company, Pardis Engine Oil Company, LIQUI MOLY, Pars Oil Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iran Automotive Engine Oils Market Shifts & Advancements
Formulation chemistry and procurement patterns are diverging from historical norms as Iranian blenders navigate feedstock constraints and fleet operators recalibrate total cost of ownership models. Three distinct vectors are restructuring competitive positioning.
Automated oil analysis systems using particle counters and viscosity sensors are automating condition-based drain interval decisions for Tehran-based commercial fleets. These platforms transmit real-time degradation data to fleet managers, compressing the traditional fixed-interval service model. The technology is automating procurement timing and reducing bulk inventory holdings for operators with centralized maintenance depots.
The Institute of Standards and Industrial Research of Iran is tightening mandatory limits on phosphorus and sulfur content in passenger car motor oils, mirroring ACEA C2/C3 low-SAPS frameworks. This regulatory trajectory elevates technical barriers for blenders reliant on conventional additive packages. Passenger car segments with gasoline particulate filters face the steepest compliance costs and shortest reformulation timelines.
Direct procurement relationships between large fleet operators and blending facilities are displacing traditional multi-tier distribution networks in Iran's trucking corridors. Volume buyers are consolidating annual lubricant requirements into single-source contracts with technical service attachments. This channel compression is most visible along the Tehran-Bandar Abbas corridor where container logistics operators command sufficient scale to negotiate formulation customization.
Iran Automotive Engine Oils Market Segmentation
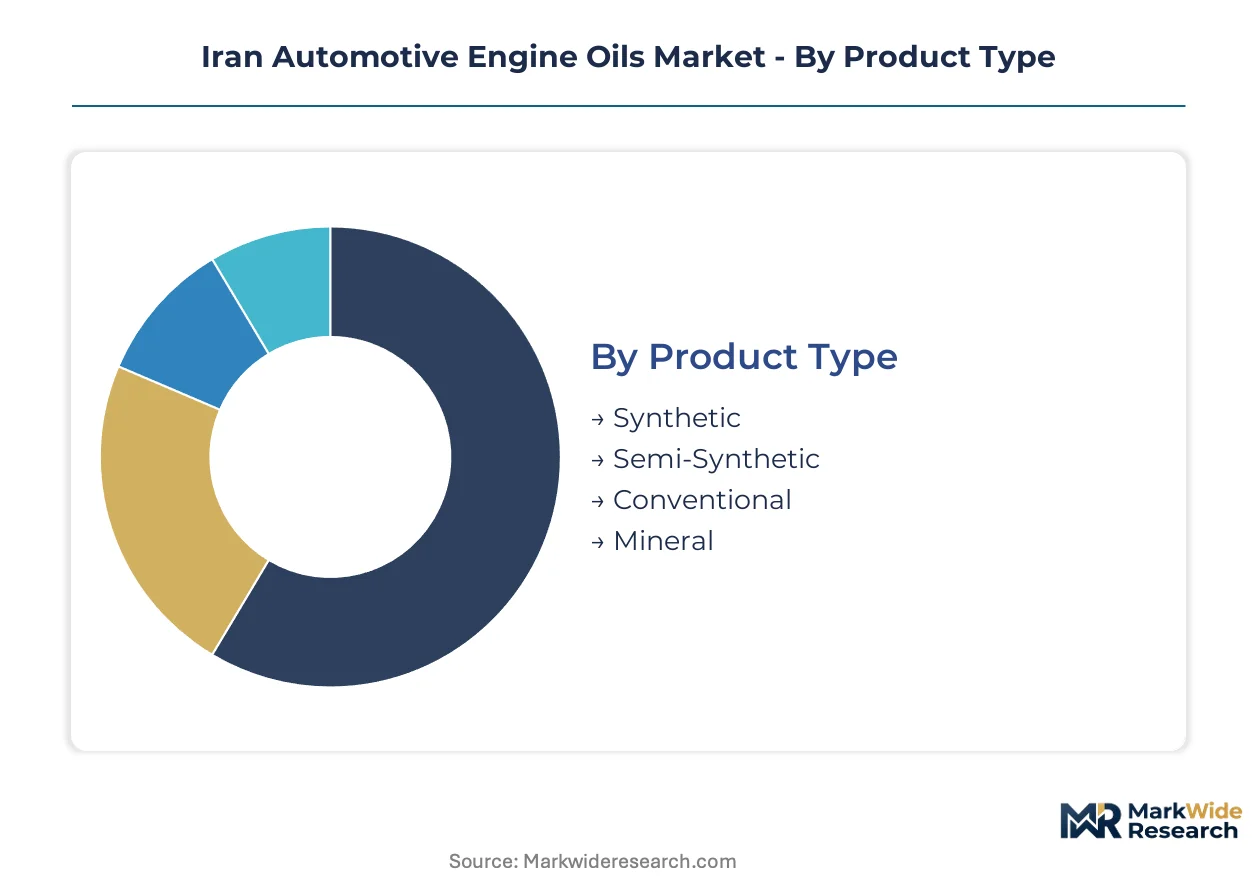
Engine oil segmentation in Iran reflects the structural gap between aging vehicle parc requirements and modern OEM specifications. Category boundaries determine margin capture, with premium formulations commanding price multiples despite feedstock import constraints.
Product Type:
Formulation chemistry separates addressable customer tiers and determines base oil sourcing strategy.
- Synthetic:Group III or PAO base stocks deliver API SP and ACEA C3 performance for turbocharged direct-injection engines. Tehran's import-dependent premium buyers absorb currency-driven price volatility for OEM-certified protection.
- Semi-Synthetic:Blended formulations balance extended drain intervals against outright synthetic premiums. Fleet operators along the Tehran-Bandar Abbas corridor favor this tier for total cost of ownership optimization.
- Conventional:Group I base oils serve price-sensitive maintenance shops in secondary cities with shorter service intervals.
- Mineral:Unadditized or lightly additized stocks dominate rural service points with minimal technical specification requirements.
Mature deployment sits with Mineral. Newer deployment is concentrated in Semi-Synthetic.
Viscosity Grade:
Climate conditions and engine architecture dictate grade selection across Iran's varied topography.
- 0W-20:Ultra-low viscosity formulations reduce cold-start friction for hybrid powertrains. Emerging demand concentrates in Tehran's newer import passenger car segment.
- 5W-30:Multi-season protection balances fuel economy with wear control. This grade gains share fastest among Isfahan's manufacturing cluster vehicle assembly plants.
- 10W-40:Higher viscosity film strength accommodates worn bearing clearances in aging domestic production vehicles. Volume throughput peaks in provincial fleet maintenance depots.
- 15W-50:Heavy-duty thermal stability protects turbocharged diesel commercial engines operating in southern Iran's elevated ambient temperatures.
Widespread deployment centers on 10W-40. Technical migration is accelerating toward 5W-30.
End User:
Application-specific duty cycles create divergent formulation and packaging requirements.
- Passenger Cars:CNG-gasoline hybrid powertrains prevalent in Iranian cities demand specialized thermal stability packages. Tehran's vehicle density drives volume concentration.
- Commercial Vehicles:High annual mileage accumulation and severe duty cycles generate the most concentrated margin pool per liter sold. Route density along Mashhad-Tehran corridor supports dedicated distribution infrastructure.
- Motorcycles:Small-displacement two-wheeler lubrication represents high-frequency, low-volume transactions through independent service points.
- Heavy-Duty Trucks:Extended drain interval programs and oil analysis monitoring compress procurement cycles for logistics operators with centralized maintenance control.
Volume stability resides with Passenger Cars. Margin expansion is concentrating in Heavy-Duty Trucks.
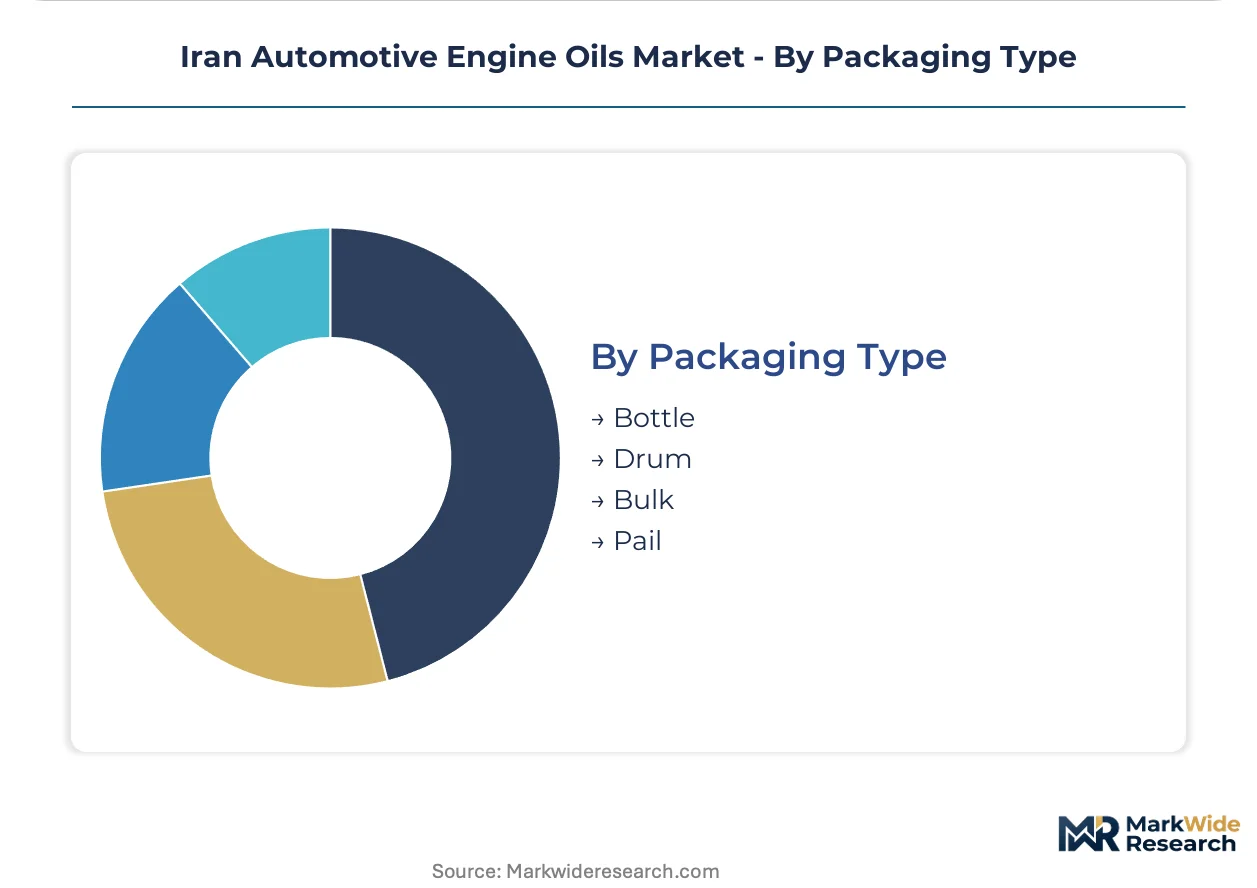
Packaging Type:
Channel economics and consumption scale determine packaging format selection.
- Bottle:Retail-ready 1-4 liter containers serve do-it-yourself consumers and independent workshops. Tehran's aftermarket retail density supports this format.
- Drum:200-liter steel containers balance portability with volume for mid-size fleet operators lacking bulk storage infrastructure.
- Bulk:Tanker or tote deliveries eliminate packaging cost for large-scale consumers with on-site storage and dispensing systems. Tehran-Mashhad corridor logistics hubs favor this approach.
- Pail:20-liter plastic containers bridge retail and industrial segments for small commercial operators.
Traditional volume flows through Bottle. Procurement efficiency is driving fastest expansion in Bulk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tehran's industrial belt concentrates Iran's automotive lubricant demand through vehicle density, fleet operator headquarters, and aftermarket service infrastructure clustering along the Tehran-Mashhad and Tehran-Bandar Abbas corridors.
Tehran Province
Commercial fleet operators and passenger car service centers drive concentrated lubricant throughput. The Institute of Standards and Industrial Research of Iran enforces evolving API SP alignment mandates from its Tehran headquarters. The capital's logistics hubs along the Tehran-Bandar Abbas corridor are consolidating bulk procurement relationships with blending facilities.
Isfahan Province
Vehicle assembly plants and manufacturing infrastructure generate sustained industrial demand. National environmental regulations push waste oil recovery obligations that raise compliance costs for regional distributors. The Isfahan-Shiraz commercial corridor hosts specialized distribution networks serving heavy-duty trucking routes.
Khorasan Razavi Province
Mashhad's position as pilgrimage and logistics hub creates growing vehicle density with limited premium lubricant distribution depth. The national oil company's base oil allocation priorities constrain independent formulators during supply tightness. Regional fleet operators are extending drain interval programs through oil analysis monitoring.
Hormozgan Province
Port logistics and container transport operators generate severe-duty lubricant consumption at Bandar Abbas. Currency volatility exposure affects additive package pricing for formulators serving import-dependent buyers. The Tehran-Bandar Abbas trucking corridor supports dedicated distribution infrastructure for bulk deliveries.
Fars Province
Shiraz commercial corridors connect agricultural and industrial transport networks with mid-tier lubricant demand. Domestic refining capabilities remain weighted toward Group I base stocks, forcing import dependence for synthetic formulations. Regional service infrastructure balances shorter drain intervals against price-sensitive fleet operator budgets.
Iran Automotive Engine Oils Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation chemistry and certification tiers, with synthetic and semi-synthetic specialists capturing value from OEM-certified specifications while mineral oil blenders compete on price in secondary markets. The vendor base spans state-linked refiners with captive base oil access, independent domestic blenders with regional distribution depth, and import-dependent premium specialists serving Tehran's quality-sensitive buyers. Three strategic archetypes define competitive positioning: integrated refiners controlling feedstock costs, regional distributors with corridor-specific logistics advantages, and premium importers leveraging international certification credibility. Capacity expansion and direct procurement relationships with large fleet operators represent the dominant competitive moves reshaping channel economics.
Among domestic integrated players, Sepahan Oil Company and Iranol Oil Company exemplify the refiner-blender archetype with upstream base oil access, while Ghatran Kaveh Motor Oil Co. occupies a position within the specialized regional distributor tier. FUCHS and LIQUI MOLY represent the import-dependent premium specialist archetype, anchoring their positioning among buyers seeking ACEA C3 and API SP certified formulations despite currency-driven price volatility. These named entities illustrate the structural segmentation between feedstock-integrated domestic operations and specification-driven international brands.
| Leading Market Players |
|---|
| Sepahan Oil Company |
| Ghatran Kaveh Motor Oil Co. |
| Iranol Oil Company |
| FUCHS |
| Addinol |
| Behran Oil Company |
| Pardis Engine Oil Company |
| LIQUI MOLY |
| Pars Oil Company |
| Others |
Supply & Pricing Matrix
Fleet operator consolidation along the Tehran-Bandar Abbas corridor is compressing procurement cycles and forcing blenders to absorb currency volatility on additive packages while maintaining contract pricing stability. This buyer-side pressure reshapes supplier economics, privileging formulators with captive base oil access over import-dependent competitors.
Pricing Analysis
Extended drain interval guarantees anchor value-based pricing for Tehran-based logistics operators calculating total cost of ownership across million-kilometer duty cycles. Three-tier pricing structure across premium synthetic, semi-synthetic, and mineral grades separates OEM-certified formulations from commodity blends, with API SP certification commanding measurable premiums. Cost compression in the mineral tier is intensifying because domestic Group I oversupply forces price competition among small regional blenders. Provincial fleet maintenance depots exhibit highest price sensitivity, while container logistics operators with centralized procurement accept synthetic premiums for uptime guarantees.
Supply Chain Analysis
Regional distribution centers in Tehran and Isfahan operate hub-and-spoke patterns radiating toward Mashhad and Bandar Abbas corridors. Base oil supply concentrates in Iran, with Group I stocks from domestic refineries and Group II/III dependence on South Korean and UAE import channels. Additive packages draw from German and US specialty chemical suppliers, creating tariff exposure through financial sanctions disrupting trade finance. Tehran-Mashhad corridor logistics hubs favor bulk tanker deliveries eliminating packaging cost, while secondary cities rely on drum and pail intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iran's automotive lubricant sector is navigating a formulation technology transition, with low-SAPS additive chemistry replacing legacy high-ash packages to meet tightening exhaust after-treatment compatibility requirements.
For Market Incumbents: To counter direct procurement relationships between large fleet operators and blending facilities, Sepahan Oil Company and Iranol should deepen backward integration into Group II/III base oil production through refining upgrades, while securing ACEA C3 certification investments to defend premium positioning against import brands. For New Entrants and Emerging Players: Digital oil condition monitoring platforms offer a technology-first wedge into Tehran's telematics-enabled fleet management procurement relationships. Khorasan Razavi Province presents the most penetrable geography, with Mashhad's growing vehicle density and limited premium distribution depth creating white-space for specialized regional distributors offering technical service attachments. For Investors and Strategic Acquirers: The window for entry favors domestic blenders with established corridor logistics and reformulation capabilities for CNG-gasoline hybrid thermal stability requirements. Acquisition targets should demonstrate API SP-ready technical infrastructure and bulk delivery relationships with Tehran-Bandar Abbas logistics operators. The signal to watch is Institute of Standards and Industrial Research of Iran acceleration of mandatory phosphorus and sulfur limits, which would compress reformulation timelines and strand conventional additive inventories.| Strategic Initiative | Industry Significance |
|---|---|
| Refining Upgrade for Group II/III Base Oil | Reduces import dependence for synthetic formulations when sanctions disrupt UAE and South Korean trade channels. |
| ACEA C3 Certification Investment | Opens OEM-certified premium segments among Tehran's quality-sensitive import vehicle service centers. |
| Digital Fleet Management Partnership | Bypasses traditional distributor intermediaries through telematics-enabled oil condition monitoring procurement. |
| Khorasan Razavi Distribution Expansion | Captures underpenetrated premium demand in Mashhad's pilgrimage and logistics hub vehicle density. |
| Waste Oil Recovery Infrastructure | Meets environmental compliance obligations that raise fixed costs for smaller blending competitors. |
Research Methodology
Customs declarations from the Islamic Republic of Iran Customs Administration, base oil allocation records from the National Iranian Oil Company, and Institute of Standards and Industrial Research of Iran regulatory filings formed the secondary backbone. Primary interviews with blending plant technical directors, fleet procurement managers at Tehran logistics operators, aftermarket distributors along the Isfahan-Shiraz corridor, and additive package procurement specialists at domestic formulators were combined with secondary validation. Bottom-up volume modeling from vehicle parc data and top-down value reconciliation from trade flow analysis enabled triangulation across independent estimation approaches.
Bottom-up modeling projected lubricant consumption from vehicle registration databases, duty cycle assumptions by vehicle class, and drain interval evolution patterns across the projection horizon. Segmentation dimensions included formulation chemistry tier, viscosity grade migration, end-use application duty cycle, and packaging format by fleet scale tier. CAGRs were derived from regression analysis against vehicle production forecasts and regulatory timeline assumptions for API SP alignment mandates. Industry-specific inputs encompassed CNG-gasoline hybrid penetration rates and oil analysis monitoring adoption curves among centralized fleet maintenance operations.
Several conditions sit outside the modeled scope, including unannounced sanctions modifications affecting base oil trade finance, abrupt currency regime shifts altering additive import economics, and domestic refining project delays extending Group II/III supply deficits. Forecasts reflect documented assumptions regarding regulatory alignment pacing and fleet modernization rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Brazil Automotive Parts Zinc Die Casting Market
Automotive Parts
North America Gear Market
Automotive Parts
Automotive Surface Coated Brake Market
Automotive Parts
Industrial Roller Chain Drives Market
Automotive Parts
Automotive Key Blanks Market
Automotive Parts
Japan Ball Bearing Market
Automotive Parts
Canada Automotive Pneumatic Actuators Market
Automotive Parts
Automotive Steel Market
Automotive Parts
Global Automotive Hydraulic Brake Market
Automotive Parts
Automotive Adaptive Engine Mounts Market
Automotive Parts
Qatar Passenger Vehicles Lubricants Market
Automotive Parts
Windshield Lifters Market
Automotive Parts
Automotive Mechanical Control Cable Market
Automotive Parts
Morocco Commercial Vehicles Lubricants Market
Automotive Parts
Camshaft Lifters Market
Automotive Parts
Colombia Commercial Vehicles Lubricants Market