
 China Electric Bus Market | 2026-2036
China Electric Bus Market Size, Share, and Industry Trends Forecast 2026-2036
China Electric Bus Market Analysis
Market Context with Strategic Players
The China electric bus market is recalibrating around a widening gap between premium intelligent fleets and commodity single-shift vehicles. BYD Company Limited leverages its in-house battery production to control cost structures across multiple provincial tenders. Zhengzhou Yutong Bus Co., Ltd. anchors the premium tier with integrated smart bus systems for first-tier city operators. King Long United Automotive Industry Co., Ltd. competes aggressively on volume in county-level transit upgrades where procurement budgets remain constrained.
Technical Definition and Structural Segments
China electric buses are zero-emission or low-emission passenger vehicles powered by battery electric, plug-in hybrid, or fuel cell systems, typically operating at 350-800V architectures with 200-500 kWh battery packs for urban duty cycles. These vehicles serve municipal transit, intercity shuttle, and dedicated corridor applications where operational predictability supports charging infrastructure planning. Battery electric configurations dominate procurement volumes, while fuel cell variants occupy early-adopter positions in heavy-duty regional routes where hydrogen supply chains are developing. Quick charge technology leads deployment in high-frequency public transport applications, whereas smart bus systems concentrate margin pools in premium fleet management contracts.
Regulatory Frame and Forward-Looking Close
China's MIIT enforces NEV penetration mandates and dual carbon targets that compel provincial transit bureaus to electrify procurement quotas, while SAMR administers GB standards governing battery safety and electromagnetic compatibility for commercial vehicle certification. Local regulators in Shenzhen and Shanghai supplement national frameworks with operating subsidy tiers tied to real-world energy consumption verification. Stakeholders must monitor how subsidy phase-out schedules interact with battery cost curves to determine whether total cost of ownership advantages sustain without fiscal support.
Market Dynamics
China's electric bus market is compressing around a supply squeeze in battery-grade lithium and provincial procurement calendars that front-load fleet replacements ahead of MIIT subsidy phase-out deadlines.
Growth Catalysts
- MIIT dual carbon mandates:Binding NEV penetration targets force municipal transit bureaus in Beijing and Shenzhen to electrify procurement quotas regardless of budget cycles.
- Coastal charging infrastructure density:High-utilization routes in Guangdong and Jiangsu provinces now support battery electric buses with sub-30-minute opportunity charging during layovers.
- Lithium iron phosphate chemistry:Domestic cell production cost curves favor LFP packs for single-shift county buses where energy density requirements are modest.
Market Restraints
- Raw material concentration:Qinghai and Sichuan lithium brine processing bottlenecks create input cost volatility for cathode active materials.
- County-level fiscal constraints:Third and fourth-tier city transit authorities lack balance sheet capacity for upfront battery electric bus premiums.
- Winter range degradation:Northern Heilongjiang and Jilin operators face 35-40% capacity loss in sub-zero conditions, forcing larger pack specifications.
Strategic Opportunities
- Yangtze River Delta hydrogen corridors:Shanghai and Nanjing are piloting fuel cell bus deployment along fixed intercity routes with state-backed hydrogen refueling infrastructure.
- V2G-enabled depot charging:Grid services revenue streams from bidirectional charging are opening for fleet operators with overnight parking capacity.
- Smart bus system integration:ADAS and fleet telematics packages command premium pricing in first-tier city tenders requiring real-time passenger analytics.
Industry Challenges
- High-voltage technician scarcity:County-level maintenance depots lack certified personnel for 600V+ battery pack diagnostics and isolation procedures.
- GB standard certification timelines:SAMR electromagnetic compatibility testing queues extend 8-12 months for new vehicle platforms, delaying provincial tender participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Electric Bus Market |
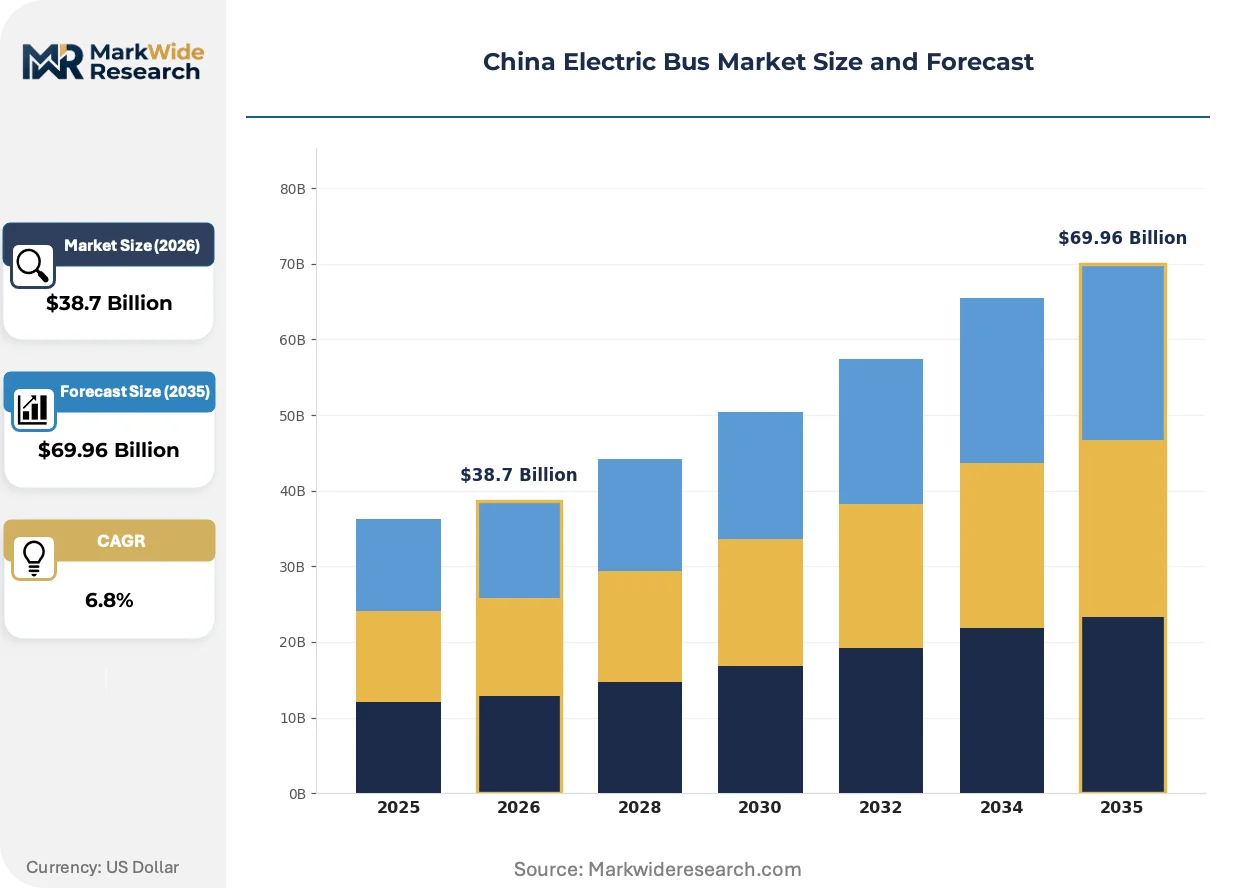
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bus Type: Double Decker, Coach, Mini Bus, Standard Bus Power Source: Battery Electric, Plug-in Hybrid, Fuel Cell, Hybrid Electric Application: Public Transport, Long-Distance Travel, Shuttle Services, School Transport Technology: Quick Charge, Regenerative Braking, Smart Bus Systems, Telematics |
| Companies Covered | King Long United Automotive Industry Co., Ltd., Daimler Buses, Zhengzhou Yutong Bus Co., Ltd., Chery Automobile Co., Ltd., Foton Motor Co., Ltd., BYD Company Limited, Zhongtong Bus Holdings Co., Ltd., Geely Automobile Holdings Limited, Anhui Ankai Automobile Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Electric Bus Market Emerging Trajectories
Intelligent fleet management systems and cell-to-pack architectures are compressing the traditional boundaries between vehicle hardware and energy infrastructure in China's transit electrification wave.
Cell-to-pack battery architectures are eliminating module housings to increase gravimetric density and reduce thermal management complexity. Tier-one city operators in Shenzhen and Guangzhou are specifying these platforms for 18-meter articulated buses where weight reduction extends range. This unifying design approach is collapsing the distinction between battery supplier and vehicle integrator roles in premium tenders.
MIIT's GB/T standards for battery safety and electromagnetic compatibility are tightening test severity for thermal runaway propagation and high-voltage isolation. Commercial vehicle OEMs must now submit full vehicle-level crash test data rather than component certifications. Heavy-duty fuel cell platforms face the most stringent new protocols, slowing their path to provincial procurement eligibility.
County transit authorities are consolidating fleet purchasing through provincial-level joint procurement consortia to extract volume pricing from manufacturers. Aggregated tenders in Shandong and Henan now cover 200-400 unit blocks across multiple municipal operators, displacing the historical model of fragmented city-by-city negotiations. This concentration is most visible in central China where fiscal constraints force smaller cities to band together.
China Electric Bus Market Segmentation
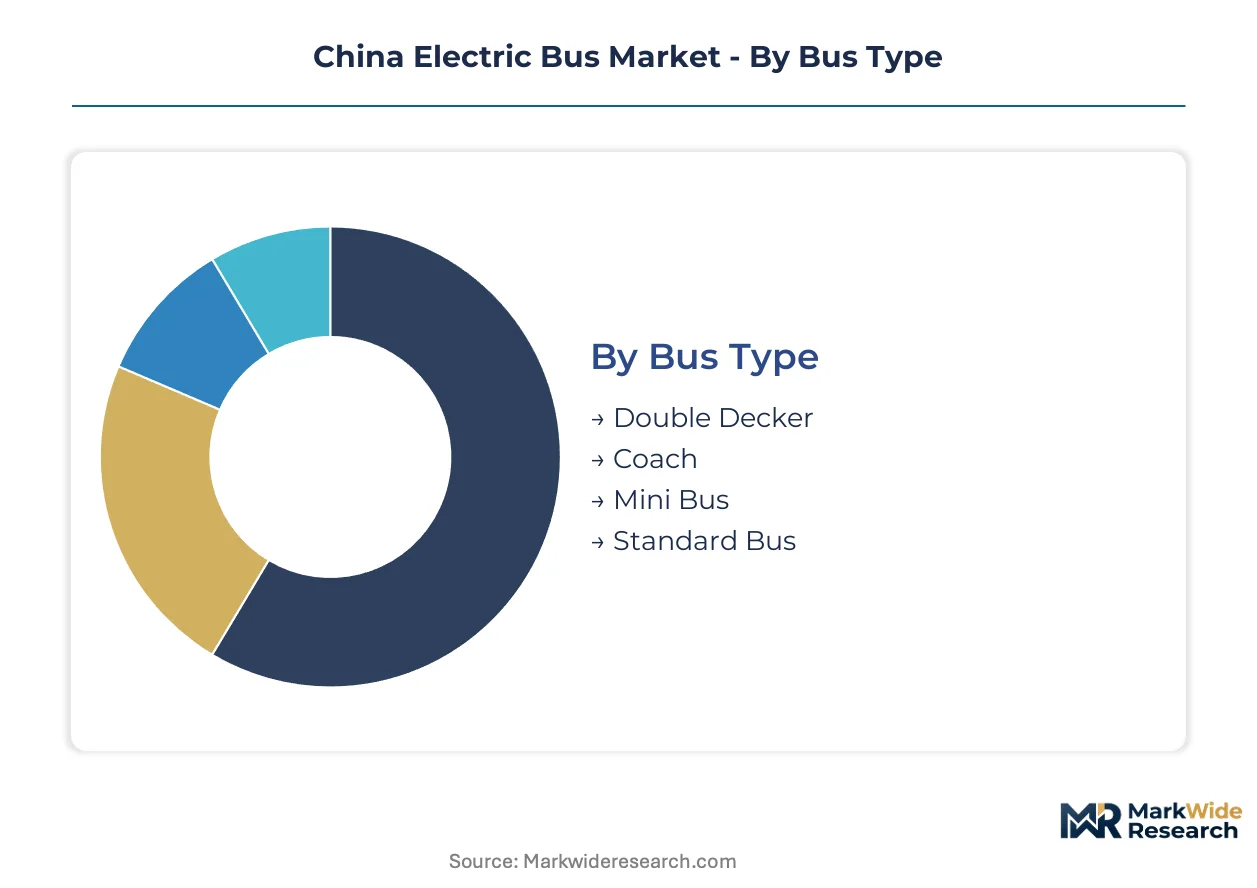
China's electric bus market fragments across four structural dimensions that determine procurement specifications, charging infrastructure requirements, and fleet management complexity. Transit authorities select configurations based on route duty cycles, passenger volumes, and grid integration capabilities rather than vehicle cost alone.
Bus Type:
Route passenger density and road geometry separate buyers in this category, with first-tier cities prioritizing high-capacity articulated platforms while county operators optimize for maneuverability on narrow streets.
- Standard Bus:12-meter single-deck configurations carry 80-100 passengers with 250-400 kWh battery packs. Beijing and Shenzhen municipal operators specify these for trunk routes with dedicated bus lanes and depot charging infrastructure.
- Double Decker:Two-level passenger compartments maximize capacity without extending vehicle length, requiring reinforced chassis and elevated center-of-gravity compensation. Guangzhou deploys these on tourist corridors and high-volume commercial districts where road width constraints limit articulated alternatives.
- Mini Bus:6-8 meter lengths serve last-mile connectivity and community shuttle routes in dense urban villages. Zhengzhou and Xi'an operators favor these for narrow historic districts where turning radii below 7 meters are mandatory.
- Coach:Intercity configurations with luggage compartments and highway-speed capability operate on 400-600 km routes. Demand concentrates in Yangtze River Delta corridor services connecting Shanghai to satellite cities.
Volume sits with Standard Bus configurations; growth tilts toward Double Decker for premium tourist and commercial district applications.
Power Source:
Energy infrastructure maturity and route predictability drive technology selection, with battery electric dominating where charging networks exist and fuel cell penetrating fixed intercity corridors.
- Battery Electric:Lithium iron phosphate cell chemistry dominates with 200-500 kWh packs operating at 350-800V architectures. Jiangsu and Guangdong provinces lead procurement volumes where opportunity charging stations enable sub-30-minute turnaround at terminuses.
- Fuel Cell:Proton exchange membrane systems with 30-40 kg hydrogen storage serve heavy-duty regional routes. Shanghai and Nanjing pilot these on fixed intercity corridors with state-backed hydrogen refueling infrastructure.
- Plug-in Hybrid:Dual-mode operation with 50-100 km electric range and diesel range extension addresses charging infrastructure gaps. Northern Heilongjiang operators specify these for winter reliability where battery degradation exceeds 35%.
- Hybrid Electric:Non-plug-in configurations with kinetic energy recovery serve stop-and-go urban cycles. County-level transit authorities in Henan deploy these as transition technology where grid capacity limits full electrification.
Procurement volume clusters in Battery Electric; steepest expansion trajectory belongs to Fuel Cell where hydrogen supply chains mature.
Application:
Service frequency and passenger predictability separate operational requirements, with high-utilization public transport justifying premium technology investments that intermittent shuttle services cannot amortize.
- Public Transport:High-frequency municipal trunk routes with 16-20 hour daily operation. Shenzhen and Beijing operators mandate intelligent dispatch systems and real-time passenger counting for these services.
- Shuttle Services:Corporate and residential compound transport with fixed schedules and captive passenger bases. Shanghai Pudong airport corridor and tech park circuits drive specification standardization.
- Long-Distance Travel:Intercity services exceeding 200 km with highway cruising profiles. Yangtze River Delta and Pearl River Delta economic zones support these with integrated charging networks.
- School Transport:Dedicated student services with enhanced safety specifications and limited daily utilization. Shandong province aggregates county-level demand through provincial procurement consortia.
Deployment scale favors Public Transport; technology upgrade intensity concentrates in Shuttle Services where private operators compete on service quality differentiation.
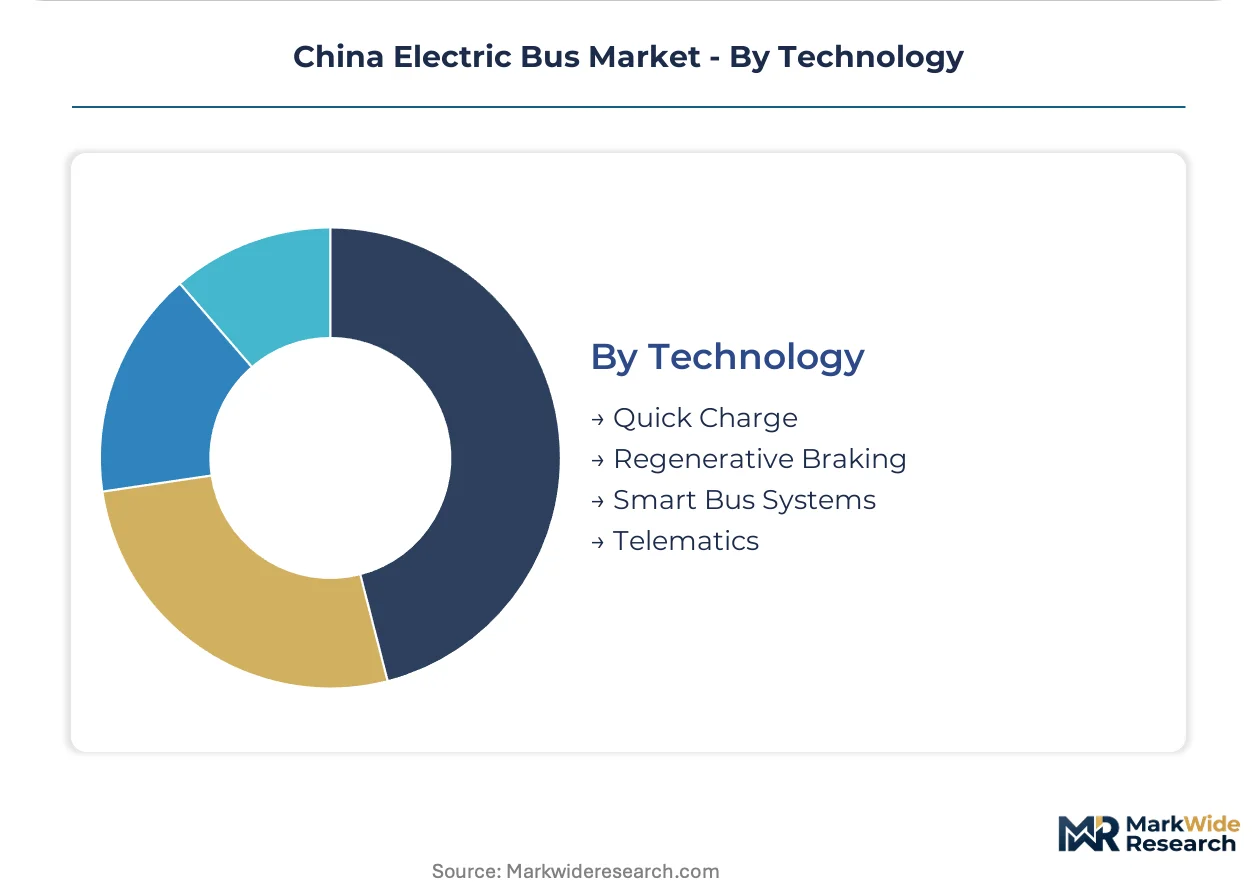
Technology:
Integration depth with fleet management platforms separates premium tenders from commodity procurement, with first-tier cities specifying full telematics suites while county operators prioritize basic electrification.
- Smart Bus Systems:Integrated ADAS, passenger analytics, and autonomous operation readiness. Shenzhen and Guangzhou specify these for BRT corridors requiring real-time traffic signal priority.
- Quick Charge:Pantograph and plug-in systems enabling 10-15 minute opportunity charging at route terminuses. High-frequency Guangdong trunk routes deploy 450 kW charging to maintain schedule adherence.
- Telematics:GPS tracking, energy consumption monitoring, and predictive maintenance algorithms. Provincial joint procurement consortia in Shandong and Henan standardize these for fleet aggregation.
- Regenerative Braking:Kinetic energy recovery systems with 15-25% efficiency in stop-and-go cycles. Baseline specification for all battery electric configurations regardless of application tier.
Adoption breadth extends across Regenerative Braking as standard equipment; value capture concentrates in Smart Bus Systems where first-tier city tenders command premium pricing for integrated platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors China's electric bus deployment density with over 16,000 battery electric units in municipal service, establishing the technical template that provincial transit bureaus now replicate across coastal and interior corridors.
Guangdong Province
Guangdong's Pearl River Delta cities command the deepest charging infrastructure networks, with Guangzhou and Shenzhen operators specifying 450 kW opportunity charging for high-frequency trunk routes. MIIT NEV penetration mandates bind municipal procurement quotas regardless of fiscal cycles. Foshan and Dongguan manufacturing clusters supply cell-to-pack battery architectures for articulated bus platforms.
Jiangsu Province
Jiangsu transit authorities leverage Yangtze River Delta grid integration to pilot V2G-enabled depot charging in Nanjing and Suzhou. SAMR GB standards enforcement accelerates electromagnetic compatibility certification for vehicles serving Shanghai satellite corridors. Changzhou and Wuxi industrial zones concentrate electric drivetrain component fabrication for provincial joint procurement consortia.
Beijing-Tianjin-Hebei
Beijing municipal operators face MIIT dual carbon targets compelling fleet electrification ahead of 2030 deadlines, with articulated buses prioritized for dedicated BRT corridors. Winter range degradation in sub-zero conditions forces larger battery pack specifications for Hebei provincial routes. Tianjin port infrastructure supports hydrogen refueling pilot programs for fuel cell intercity shuttles.
Shandong Province
Shandong's county-level transit authorities aggregate demand through provincial procurement consortia covering 200-400 unit blocks across multiple municipal operators. Fiscal constraints in third and fourth-tier cities necessitate volume pricing extraction from manufacturers. Qingdao and Yantai manufacturing bases supply lithium iron phosphate packs for single-shift county bus configurations.
Sichuan-Chongqing
Sichuan lithium brine processing from Qinghai feedstocks creates cathode active material supply concentration, with Chengdu operators testing fuel cell platforms on fixed intercity corridors. Chongqing's mountainous topography drives demand for regenerative braking optimization in stop-and-go urban cycles. Provincial transit bureaus coordinate with MIIT on GB standard compliance timelines for high-voltage platform certification.
China Electric Bus Market Vendor Landscape
Premium-margin players sit above commodity-margin players across battery integration depth and fleet management system sophistication, with the market consolidating around three strategic tiers. Tier-one positions concentrate with manufacturers controlling in-house cell production and intelligent platform architectures. Tier-two competitors compete on volume pricing for county-level procurement consortia. Tier-three specialists occupy narrow niches in hydrogen fuel cell or mini-bus configurations. Dominant competitive moves include backward integration into battery cell production and geographic expansion through provincial joint tender participation.
Within the premium-tier vector, BYD Company Limited and Zhengzhou Yutong Bus Co., Ltd. exemplify contrasting strategic archetypes. BYD represents the vertically integrated model with captive battery supply chains spanning multiple provincial tenders. Yutong occupies a position emphasizing integrated smart bus systems for first-tier city operators requiring real-time analytics. King Long United Automotive Industry Co., Ltd. anchors the volume-competitive tier, representing manufacturers competing aggressively on unit pricing for county-level fleet upgrades where procurement budgets remain constrained.
| Leading Market Players |
|---|
| King Long United Automotive Industry Co., Ltd. |
| Daimler Buses |
| Zhengzhou Yutong Bus Co., Ltd. |
| Chery Automobile Co., Ltd. |
| Foton Motor Co., Ltd. |
| BYD Company Limited |
| Zhongtong Bus Holdings Co., Ltd. |
| Geely Automobile Holdings Limited |
| Anhui Ankai Automobile Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed battery producers anchor supply-side discipline in China's electric bus market, with state-controlled lithium refiners in Qinghai and Sichuan enforcing long-term offtake pricing that insulates provincial transit bureaus from cathode material volatility. This ownership pattern compresses margin capture upstream while MIIT subsidy calendars force OEMs to absorb pack cost fluctuations within fixed tender ceilings.
Pricing Analysis
Value-based pricing anchored to total cost of ownership calculations dominates provincial procurement, with Beijing and Shenzhen operators amortizing battery premiums across 8-year service contracts. Price differentiation separates intelligent fleet platforms with telematics integration from commodity single-shift configurations lacking ADAS packages. Cost compression in county-level tenders is intensifying because Shandong and Henan joint procurement consortia extract volume discounts across 200-400 unit blocks. Third and fourth-tier city transit authorities exhibit highest price sensitivity; first-tier operators with dedicated BRT corridors show lowest sensitivity due to operating subsidy tiers tied to real-world energy consumption verification.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from provincial joint procurement consortia, bypassing traditional distributor networks for aggregated fleet orders. Manufacturing concentration centers on Guangdong, Jiangsu, and Shandong provinces where Foshan and Changzhou industrial zones fabricate cell-to-pack architectures and electric drivetrain components. Raw material flows draw from Qinghai and Sichuan lithium brine processing, plus imported cobalt hydroxide through Tianjin port infrastructure. Single-source vulnerability in cathode active material supply creates exposure to processing bottlenecks during provincial tender front-loading ahead of MIIT subsidy deadlines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's electric bus market functions as a vertical-integration race where captive battery production determines tender participation eligibility. Players pursuing upstream control over lithium refining and cell manufacturing gain pricing leverage in provincial fleet aggregation.
For Market Incumbents: To counter margin erosion from Shandong and Henan volume consortia, deepen backward integration into lithium iron phosphate cell production and secure Qinghai brine processing offtake agreements. Prioritize GB standard certification investment to compress SAMR electromagnetic compatibility testing queues from 8-12 months, accelerating provincial tender eligibility.
For New Entrants and Emerging Players: The 35-40% winter range degradation gap in Heilongjiang and Jilin creates penetrable white space for plug-in hybrid configurations with diesel range extension. Target northern provincial transit authorities lacking grid capacity for full electrification. Establish service partnerships with county-level maintenance depots to address high-voltage technician scarcity.
For Investors and Strategic Acquirers: MIIT announcement of accelerated dual carbon mandate enforcement is the leading indicator that premium intelligent fleet platforms will capture disproportionate margin expansion. Long-term viability over the next decade favors manufacturers with integrated smart bus system capabilities and V2G-enabled depot charging infrastructure. Monitor Yangtze River Delta hydrogen corridor pilot expansion as signal for fuel cell platform commercialization timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LFP Cell Production | Captive battery supply secures cost structure control across multiple provincial tenders. |
| Smart Bus System Platform Development | Integrated ADAS and telematics command premium pricing in Shenzhen and Guangzhou BRT corridors. |
| Provincial Joint Procurement Consortium Participation | Aggregated 200-400 unit blocks in Shandong and Henan displace fragmented city-by-city negotiations. |
| V2G-Enabled Depot Charging Infrastructure | Bidirectional charging opens grid services revenue streams for fleet operators with overnight parking capacity. |
| Fuel Cell Platform Certification Investment | GB standard compliance for hydrogen configurations accesses Shanghai-Nanjing intercity corridor pilots. |
Methodological Framework
Document review covered MIIT policy circulars, SAMR GB standard filings, and provincial transit bureau procurement notices, complemented by interviews with OEM platform engineers, battery supply chain managers, and municipal fleet operators. Secondary validation drew from vehicle production databases, customs records for lithium compound imports, and IHS Markit registration data. Bottom-up unit deployment estimates triangulated against top-down market value projections.
Historical deployment trajectories cross-referenced against expert panel input on subsidy phase-out schedules and battery cost curve assumptions. Segmentation modeling spanned bus type, power source, application, and technology integration depth across the projection horizon. CAGRs derived from slope analysis of year-over-year procurement volumes adjusted for MIIT mandate acceleration effects and charging infrastructure buildout timelines.
Inputs from provincial tender databases and OEM production disclosures were available through the study window; gaps in county-level fiscal capacity data introduce uncertainty bands around third and fourth-tier city electrification trajectories. Forecasts reflect assumptions regarding lithium price stabilization and GB standard certification throughput. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Van Market
Electric Vehicles
BEV Electric Drive Unit Market
Electric Vehicles
Europe Automotive Battery Thermal Management System Market
Electric Vehicles
Middle East and Africa Electric Vehicle Thermal Management System Market
Electric Vehicles
Electric Vehicle Air Conditioning Market
Electric Vehicles
ASEAN Countries Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
Saudi Arabia Electric Vehicle Market
Electric Vehicles
Automotive Battery Pack Compression Pad Market
Electric Vehicles
Electric Skateboard Market
Electric Vehicles
Global Electric Scooters Market
Electric Vehicles
Electric Tuk-Tuks Market
Electric Vehicles
Electric Water Pump for Electric Vehicles Market
Electric Vehicles
Agricultural Electric Vehicles Market
Electric Vehicles
Electric Vehicle Lithium-Ion Battery Market
Electric Vehicles
ASEAN E-Bike Market
Electric Vehicles
China Solar E-Bike Market