
 Electric Vehicle (EV) Coating Market | 2026-2036
Electric Vehicle (EV) Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle (EV) Coating Market Insights
Modular coating service packages is decoupling procurement decisions from traditional full-vehicle paint shop contracts, letting OEMs source battery-component coatings separately from exterior body programs. PPG Industries leverages its vertical integration into electrode binders and thermal barrier coatings to anchor premium positioning in EV-specific formulations. BASF SE sustains R&D intensity across waterborne base coat platforms, while Axalta Coating Systems competes through geographic dominance in North American OEM assembly plant proximity.
Electric Vehicle Coating comprises engineered film-forming systems applied to substrates including steel, aluminum, and composite battery housings, with film builds typically ranging from 15 to 150 microns depending on functional requirements; these coatings provide corrosion protection, dielectric insulation, thermal dissipation, and aesthetic finish for electrified powertrain architectures. Specialty Coatings leads product type value contribution due to battery-specific thermal management and fire-resistance formulations commanding formulation premiums. Waterborne technology dominates regulatory-compliant exterior body applications, while Powder Coatings extends fastest in chassis and underbody segments where thick-film edge coverage and zero-VOC profiles align with factory sustainability targets.
EPA regulates VOC emissions from automotive coating operations through Maximum Achievable Control Technology standards, while REACH restricts hazardous substance content in imported coating formulations, and China's MEE enforces dual carbon goals that tighten solventborne capacity permits. These frameworks collectively shift formulation investment toward compliant chemistries and reshape market access for non-conforming suppliers. Stakeholders must monitor evolving carbon border adjustments and battery safety certification requirements that will determine which coating platforms gain OEM qualification status.
Market Dynamics
Coating procurement fragmentation is splitting traditional full-vehicle paint shop contracts into modular battery-component and exterior-body sourcing streams, forcing formulators to qualify separately for thermal management and aesthetic programs.
Growth Catalysts
- China NEV production scaling:Domestic coating supply chains near cell manufacturing clusters in Jiangsu and Guangdong reduce logistics costs and qualification timelines for enclosure coatings.
- REACH VOC mandates:ECHA restrictions on solventborne formulations accelerate waterborne and powder coating R&D investments among EU-qualified suppliers.
- Thermal barrier functionality:Battery pack fire-resistance specifications now require ceramic-filled intumescent coatings that command formulation premiums over standard automotive clears.
Market Restraints
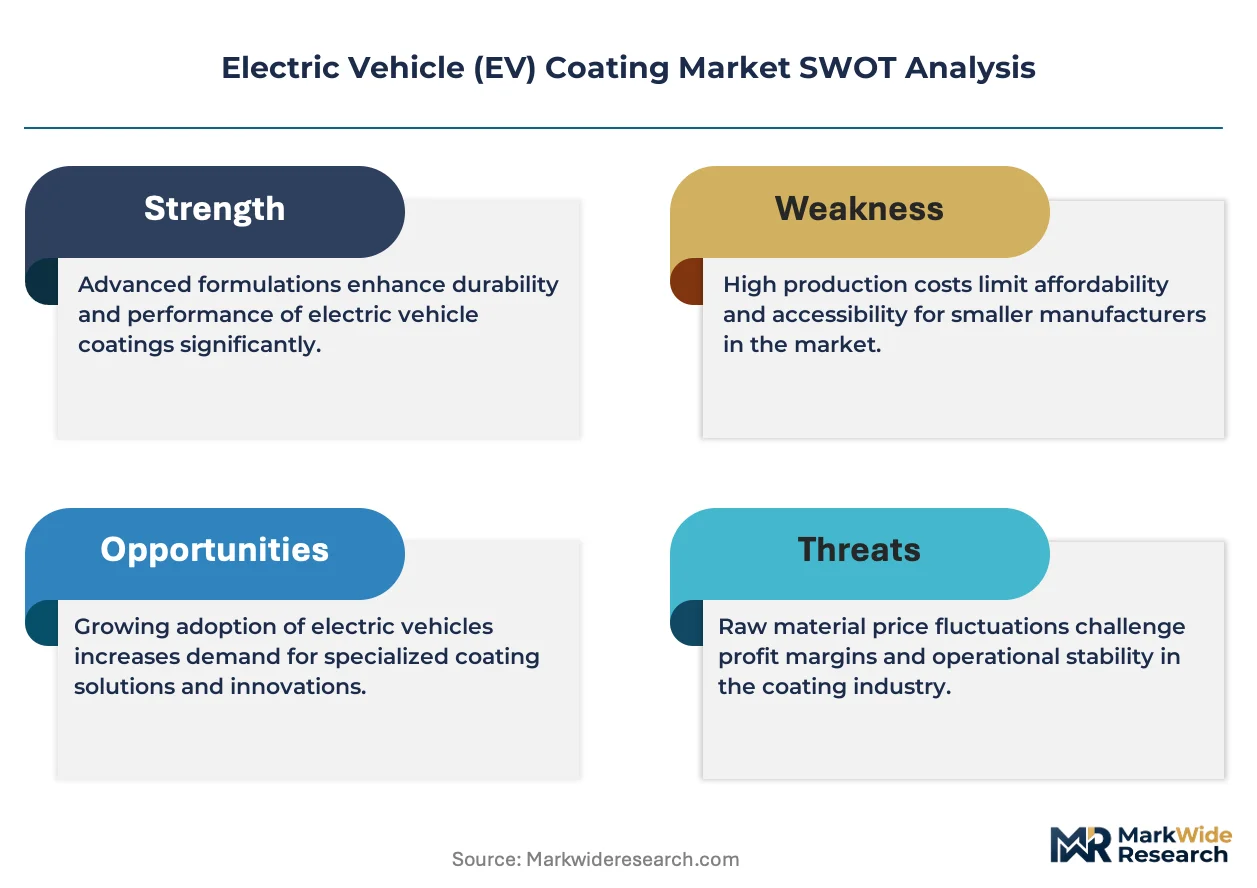
- Specialty resin supply concentration:Fluoropolymer and ceramic precursor production clusters in Germany and Japan create single-source vulnerability for high-temperature formulations.
- MEE dual-carbon permitting:China's Ministry of Ecology and Environment has frozen new solventborne capacity approvals in Shandong and Hebei provinces since 2023.
- Aluminum substrate variability:Cast versus extruded battery housing alloys require incompatible pretreatment chemistries, fragmenting coating process standardization.
Strategic Opportunities
- India PLI scheme for cell manufacturing:Domestic coating qualification programs for ACC battery plants in Gujarat and Tamil Nadu remain underdeveloped versus substrate supply.
- UV-curable powder convergence:Low-temperature cure platforms enable coating of thermally sensitive composite battery enclosures without substrate warping.
- Service bundling via electrode binders:Coating suppliers with captive binder production can anchor long-term contracts through integrated cell-component supply.
Industry Challenges
- Dielectric testing certification timelines:OEM validation protocols for 800V architecture insulation coatings extend 18-24 months versus 12 months for legacy 400V systems.
- Cross-functional coating expertise gaps:Battery thermal engineers and automotive paint shop operators lack shared vocabulary for specifying fire-resistance and appearance properties simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle (EV) Coating Market |
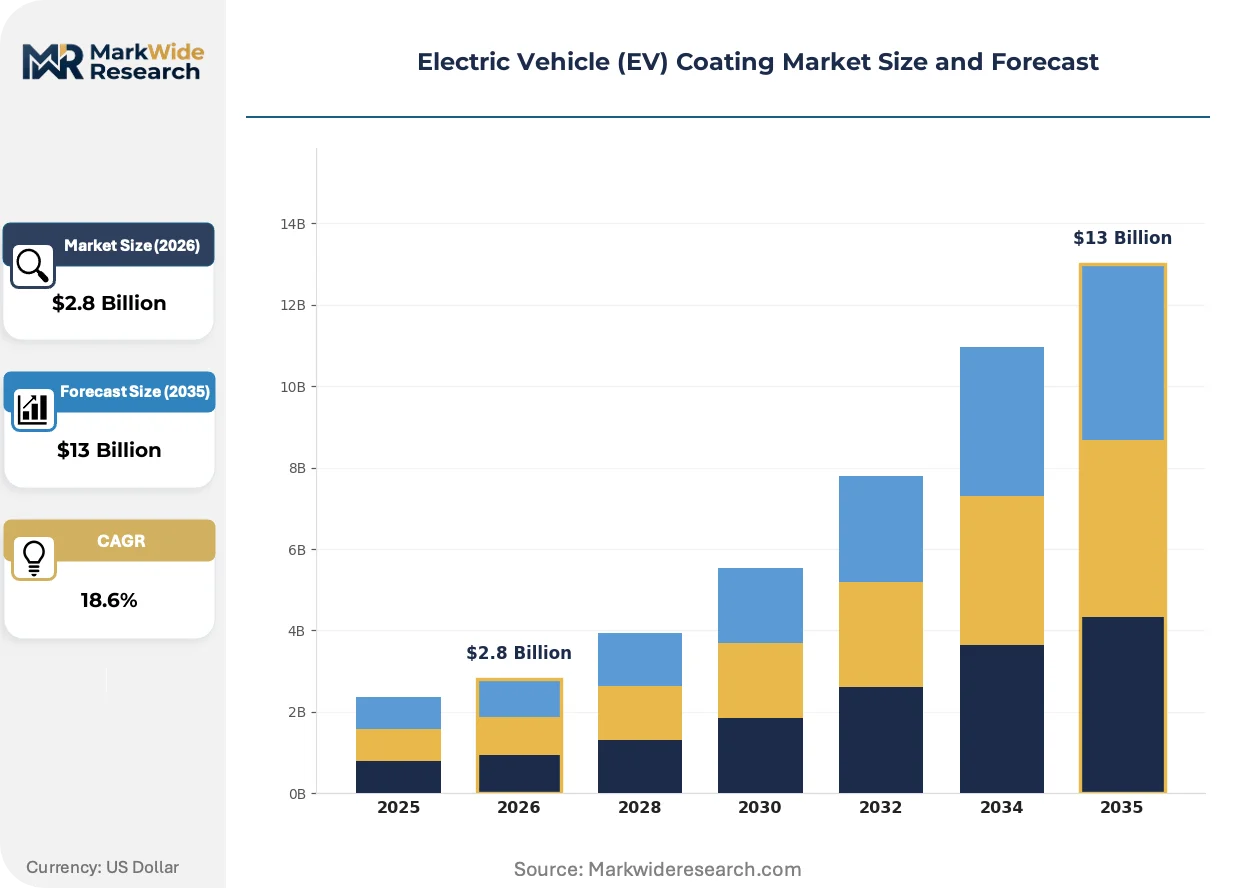
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Coat, Primer, Base Coat, Specialty Coatings Application: Interior Parts, Exterior Body, Chassis, Battery Components Technology: Waterborne, Solventborne, Powder Coatings, UV-Cured Coatings End User: OEMs, Aftermarket Providers, Repair Shops, Commercial Fleets |
| Companies Covered | PPG Industries, BASF SE, Axalta Coating Systems, Akzo Nobel, Sherwin-Williams Company, Nippon Paint Holdings, Kansai Paint, Jotun Group, TIGER, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle (EV) Coating Market Trends and Innovations
Formulation chemistry and application methods are diverging sharply between battery-specific functional coatings and exterior aesthetic programs, with regulatory pressure accelerating technology substitution in each stream.
Ceramic-filled thermal barrier coatings are rewriting how battery pack fire containment is engineered. Cell manufacturers in South Korea and China are specifying 500-micron intumescent films for module-to-pack barriers. This technology is compressing the traditional separation between passive thermal management materials and structural coatings.
EPA Maximum Achievable Control Technology standards for automotive coating operations are tightening VOC thresholds for assembly plant paint shops. OEMs in Michigan and Tennessee are retrofitting spray booths to capture and recycle waterborne overspray. Exterior body programs face the steepest compliance costs, pushing some volume toward powder primer-surfacer systems.
Battery enclosure coating contracts are unbundling from full-vehicle paint shop agreements, with procurement teams at European and Chinese OEMs now running separate RFQs for cell-housing thermal management versus body-in-white programs. Tier-1 suppliers in Bavaria and Stuttgart report compressed decision cycles as battery engineering groups gain independent vendor selection authority.
Electric Vehicle (EV) Coating Market Segmentation
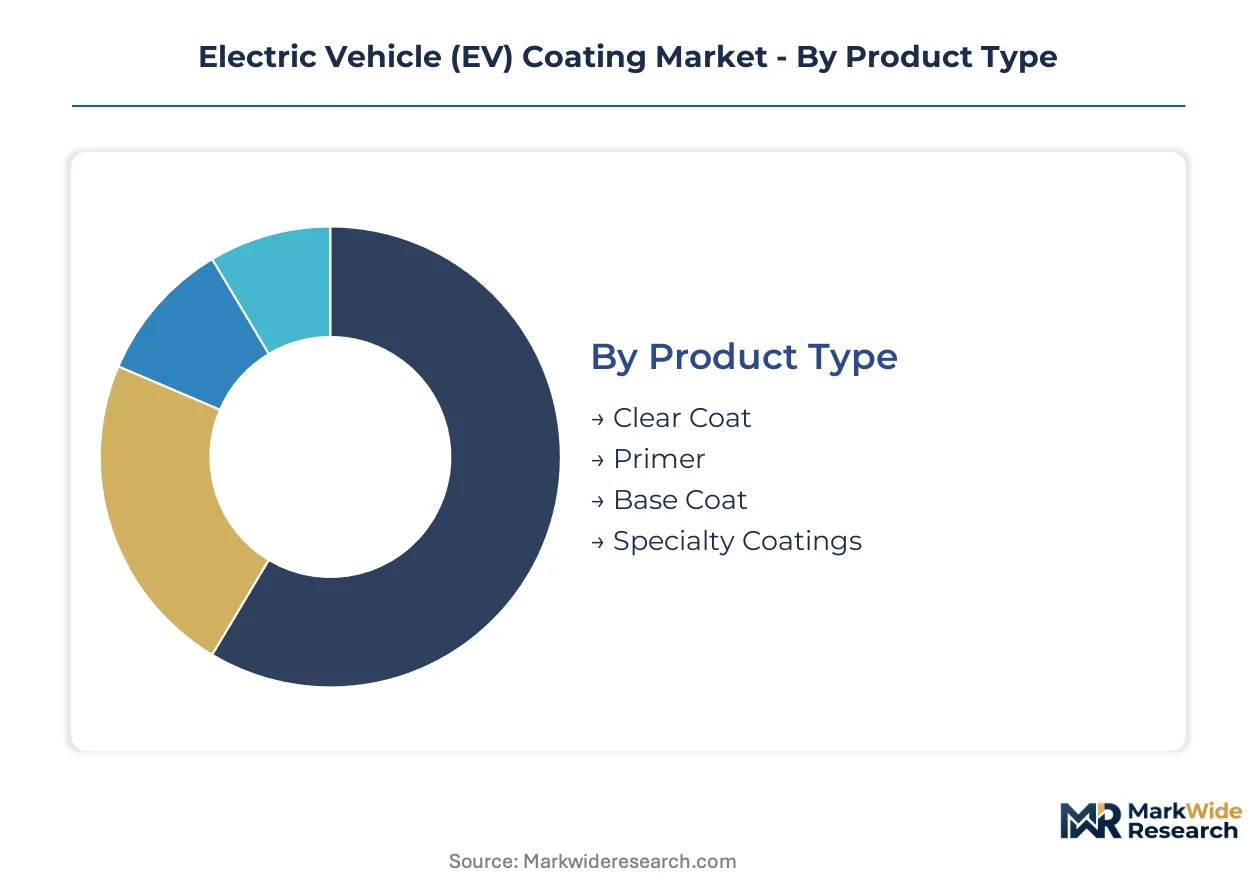
Coating procurement in electrified vehicle manufacturing fragments across thermal management, structural protection, and aesthetic finish requirements. Each segment carries distinct formulation specifications, regulatory compliance burdens, and qualification timelines that reshape supplier positioning.
Product Type:
Volume production concentrates in high-throughput exterior formulations, while premium capture sits with battery-specific functional systems commanding technical certification premiums.
- Specialty Coatings:Ceramic-filled intumescent and dielectric formulations provide fire containment and electrical insulation for battery enclosures. Demand clusters in Jiangsu and Guangdong cell manufacturing corridors where NEV OEMs specify 500-micron thermal barrier films. REACH VOC mandates accelerate waterborne variants of these high-performance systems.
- Clear Coat:Acrylic-urethane and ceramic-enhanced topcoats deliver gloss retention and scratch resistance for exterior body panels. Qualification timelines compress for suppliers with captive electrode binder production, anchoring long-term OEM contracts through integrated cell-component supply.
- Primer:Electrocoat and surfacer systems establish corrosion protection and adhesion for multi-substrate body construction.
- Base Coat:Pigmented layers provide color and UV durability, with waterborne platforms dominating EU-compliant exterior programs.
Mature deployment sits with Base Coat and Clear Coat exterior systems. Newer deployment is concentrated in Specialty Coatings for battery thermal management.
Application:
Procurement authority is splitting between traditional paint shop operations and independent battery engineering groups running separate vendor selection cycles.
- Battery Components:Module-to-pack barriers, cell housing exteriors, and cooling plate surfaces require dielectric strength and thermal dissipation. Cast versus extruded aluminum alloys demand incompatible pretreatment chemistries, fragmenting process standardization across enclosure suppliers.
- Exterior Body:Hood, door, and roof panels prioritize appearance retention and stone-chip resistance. EPA Maximum Achievable Control Technology standards tighten VOC thresholds, pushing Michigan and Tennessee assembly plants toward waterborne overspray recovery systems.
- Chassis:Underbody and structural members utilize thick-film powder systems for edge coverage and zero-VOC profiles.
- Interior Parts:Dashboard, trim, and seating components emphasize low-emission formulations and soft-touch finishes.
Procurement maturity is highest for Exterior Body programs. Fastest expansion is occurring in Battery Components as cell manufacturers gain independent sourcing authority.
Technology:
Regulatory pressure is compressing solventborne capacity while opening formulation investment toward compliant chemistries with factory sustainability alignment.
- Waterborne:Acrylic and polyurethane dispersions serve exterior base coat and clear coat applications with sub-100 g/L VOC content. ECHA restrictions on solventborne formulations accelerate R&D investment among EU-qualified suppliers retrofitting spray booths for overspray capture.
- Powder Coatings:Thermoset epoxy and polyester systems deliver thick-film edge coverage for chassis and battery housing interiors. Zero-VOC profiles align with China's MEE dual-carbon goals that have frozen new solventborne permits in Shandong and Hebei provinces.
- Solventborne:High-solids 2K urethanes persist in specialty applications requiring extreme chemical resistance.
- UV-Cured Coatings:Low-temperature cure platforms enable coating of thermally sensitive composite battery enclosures without substrate warping.
Established deployment sits with Waterborne exterior systems. Emerging deployment is concentrated in Powder Coatings for underbody and enclosure segments.
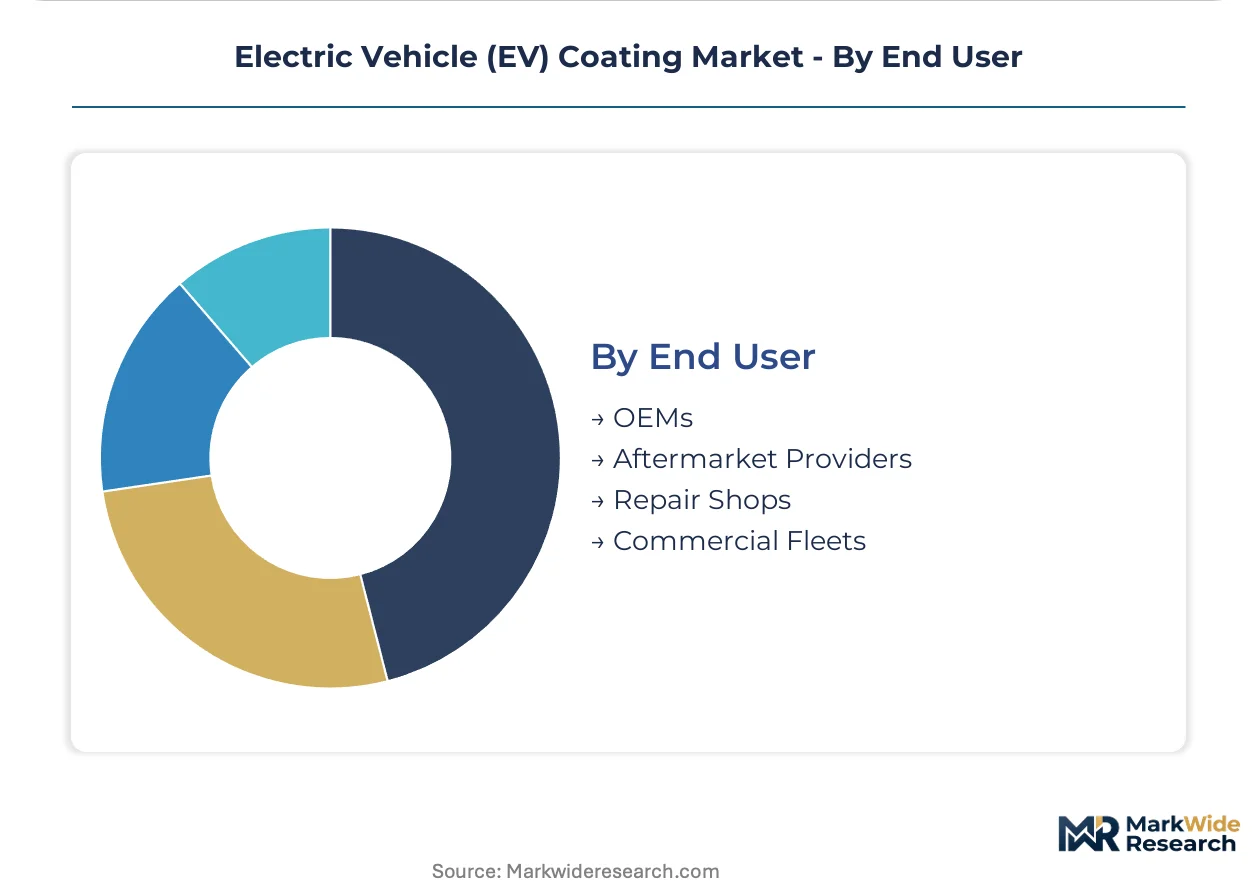
End User:
Contract structures diverge between integrated OEM paint shop agreements and modular battery-component sourcing with compressed decision cycles.
- OEMs:Integrated vehicle manufacturers specify full-vehicle coating systems through centralized procurement, though battery engineering groups in Bavaria and Stuttgart now run independent RFQs for cell-housing thermal management versus body-in-white programs.
- Aftermarket Providers:Refinish distributors supply color-matched repair formulations to collision centers and independent shops.
- Repair Shops:Single-location and multi-shop operators purchase toners and clears through distributor networks.
- Commercial Fleets:Logistics and rental operators negotiate volume maintenance contracts for vehicle refresh programs.
Contract maturity sits with OEM integrated programs. Newer procurement patterns are concentrated in Commercial Fleets as electrified logistics operators establish dedicated coating maintenance schedules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces the majority of NEVs globally yet consumes coating formulations at a lower value-per-vehicle than European assembly plants. Germany and the United States concentrate premium exterior coating demand. South Korea and Japan anchor specialty thermal barrier supply chains.
China
NEV production volumes in Jiangsu and Guangdong provinces drive coating procurement at cell manufacturing clusters. MEE dual-carbon permitting has frozen new solventborne capacity approvals in Shandong and Hebei since 2023. Domestic suppliers near BYD and CATL facilities in Shenzhen and Changzhou reduce qualification timelines for battery enclosure programs.
Germany
Bavarian and Stuttgart-based OEMs run separate RFQs for cell-housing thermal management versus body-in-white coating programs. REACH and EU Green Deal regulations mandate lower-VOC formulations, accelerating waterborne base coat investments. Industrial concentration in Baden-Württemberg hosts qualification laboratories for 800V dielectric coating validation.
United States
Michigan and Tennessee assembly plants retrofit spray booths to capture waterborne overspray under EPA Maximum Achievable Control Technology standards. Thermal barrier coating demand lags Asian and European adoption curves. Detroit-area engineering groups negotiate modular procurement contracts decoupled from full-vehicle paint shop agreements.
South Korea
Cell manufacturers specify 500-micron intumescent films for module-to-pack barriers, compressing the separation between passive thermal materials and structural coatings. MFDS and national battery safety frameworks shape fire-resistance certification protocols. Ulsan and Gyeonggi-do coating facilities serve Hyundai-Kia and Samsung SDI production networks.
Japan
Fluoropolymer and ceramic precursor production clusters create supply concentration for high-temperature formulations. METI industrial standards influence dielectric testing protocols for next-generation battery architectures. Nagoya and Kyushu-based material suppliers anchor specialty resin availability for regional coating formulators.
Electric Vehicle (EV) Coating Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation categories. The vendor base organizes into three tiers: integrated chemical conglomerates with captive resin production, independent coating formulators with geographic assembly plant proximity, and regional specialists in battery-specific functional systems. Consolidation pressure intensifies as OEM procurement teams unbundle battery-component from exterior-body contracts. Strategic moves center on backward integration into electrode binders and geographic co-location with cell manufacturing clusters.
Among diversified chemical conglomerates, PPG Industries, BASF SE, and Axalta Coating Systems occupy anchor positions. PPG exemplifies the integrated archetype through captive supply of electrode binders and thermal barrier formulations. BASF represents European-qualified suppliers accelerating waterborne platform R&D under REACH mandates. Axalta sits within the geographic proximity tier, leveraging North American OEM assembly plant relationships. These three firms illustrate how qualification for battery-specific programs increasingly determines competitive standing separate from traditional exterior coating contracts.
| Leading Market Players |
|---|
| PPG Industries |
| BASF SE |
| Axalta Coating Systems |
| Akzo Nobel |
| Sherwin-Williams Company |
| Nippon Paint Holdings |
| Kansai Paint |
| Jotun Group |
| TIGER |
| Others |
Pricing and Supply Chain Analysis
Epoxy resin price indices in Asia-Pacific feed directly into coating formulation costs, compressing margins for waterborne specialty coatings while amplifying premiums for ceramic-filled thermal barrier systems that OEMs cannot easily substitute.
Pricing Analysis
Margin tightening in standard exterior coatings reflects raw material pass-through limitations and aggressive volume contracting by procurement teams at Michigan and Tennessee assembly plants. Three-tier pricing structure across premium, standard, and economy levels stratifies by dielectric certification grade and captive electrode binder integration. Cost-down pressure on commodity clears accelerates because Chinese domestic suppliers near BYD facilities undercut EU-qualified incumbents on logistics. Commercial fleet operators exhibit highest price sensitivity, while cell manufacturers prioritize thermal performance over unit cost.
Supply Chain Analysis
Freight cost differentials between German fluoropolymer precursor clusters and Guangdong cell manufacturing corridors determine landed cost competitiveness for high-temperature formulations. Supply concentrates in Germany, Japan, and China for specialty resins, ceramic precursors, and waterborne acrylic dispersions respectively. Formulation draws from epoxy resins, polyurethane dispersions, and intumescent additives. Single-source vulnerability in Baden-Württemberg qualification laboratories for 800V dielectric testing creates bottleneck risk. Distribution runs through direct OEM supply agreements for battery-component programs and distributor networks for aftermarket refinish.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coating suppliers are racing to capture upstream electrode binder production and downstream thermal barrier qualification status as the primary levers for long-term contract anchoring.
For Market Incumbents: Deploy captive resin production to defend formulation margin against Chinese domestic suppliers expanding waterborne capacity under MEE dual-carbon permits. Accelerate 800V dielectric certification investments before validation timelines extend further. Consolidate position in Jiangsu and Guangdong cell manufacturing corridors through co-located technical service teams. For New Entrants and Emerging Players: Regional coating qualification programs for India's ACC battery plants in Gujarat and Tamil Nadu remain underserved versus substrate supply availability. UV-curable powder platforms for thermally sensitive composite enclosures offer technical differentiation without competing against established waterborne incumbents. Pursue joint development agreements with cell engineering groups rather than traditional OEM paint shop procurement. For Investors and Strategic Acquirers: The window for entry favors coating formulators with demonstrated thermal barrier OEM qualification and backward integration into ceramic precursor supply. Long-term viability hinges on decoupling from commodity exterior body programs toward battery-specific functional coatings. Monitor MEE permitting decisions in Shandong and Hebei as inflection signal for solventborne capacity rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrode Binders | Captive binder production anchors long-term cell-component supply contracts with CATL and BYD. |
| Geographic Co-location with Cell Clusters | Technical service proximity to Jiangsu and Guangdong facilities compresses qualification timelines. |
| UV-Curable Powder Platform Development | Low-temperature cure enables coating of thermally sensitive composite enclosures without warping. |
| 800V Dielectric Certification Investment | Extended validation protocols create qualification moats against unproven thermal barrier entrants. |
| Waterborne Formulation R&D Expansion | REACH and MEE regulatory pressure accelerates compliant chemistry substitution for solventborne systems. |
Research Methodology
Independent corroboration across coating formulator R&D directors, OEM battery engineering procurement leads, and cell manufacturing plant managers underwrites the qualitative findings. Primary interviews with thermal management specialists, paint shop operations heads, and aftermarket distributor principals combined with secondary validation against EPA MACT compliance filings, ECHA REACH substance restrictions, and China MEE permitting databases. Bottom-up coating volume estimates triangulated against top-down NEV production forecasts.
Comparable-period anchoring tied historical specialty coating penetration rates to forward battery enclosure specification trends across the projection horizon. Segmentation modeling incorporated product type, application, technology, and regional production cluster dimensions. CAGRs derived from slope analysis of qualification timeline compression and regulatory substitution elasticity. Forecast inputs included MEE dual-carbon permitting trajectories and 800V architecture adoption curves.
Revisions become necessary when battery safety certification protocols shift, ceramic precursor supply disruptions materialize, or carbon border adjustments alter EU market access conditions. Forecasts reflect documented assumptions about OEM procurement unbundling velocity and thermal barrier specification convergence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Germany Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Canada Solar E-Bike Market
Electric Vehicles
AC BEV On-Board Charger Market
Electric Vehicles
Automotive Intelligent Battery Sensor Market
Electric Vehicles
Electric Vehicle Cold Plates Market
Electric Vehicles
Latin America Electric Bus Market
Electric Vehicles
Europe Electric Vehicle Power Inverter Market
Electric Vehicles
APAC E-Bikes Market
Electric Vehicles
Battery-Swapping for Electric Two-Wheeler Market
Electric Vehicles
Africa Electric Scooter Market
Electric Vehicles
Indian E-Bike Rental Market
Electric Vehicles
Electric Vehicle Power Control Unit Market
Electric Vehicles
China Automotive High Performance Electric Vehicle Market
Electric Vehicles
Electromagnetic and Radio Frequency Interference Coating for Electric Vehicles Market
Electric Vehicles
South America Automotive High Performance Electric Vehicles Market
Electric Vehicles
BEV Electric Drive Unit Market