
 Electric Unicycle Market | 2026-2036
Electric Unicycle Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Unicycle Market Analysis
Aftermarket service revenue is rewriting profitability expectations for electric unicycle manufacturers as hardware margins compress. Begode leverages in-house motor winding capabilities to control repair turnaround times and parts availability. Inmotion anchors its position through firmware-locked battery ecosystems that steer consumers toward authorized service channels. KingSong competes on modular architecture that simplifies field repairs and reduces technician training costs.
An electric unicycle is a single-wheeled, self-balancing personal transporter powered by an electric hub motor, typically incorporating gyroscopic sensors and accelerometers to maintain rider stability across speeds from 10 to 50 kilometers per hour. These devices serve urban commuters and recreational riders seeking compact, portable alternatives to bicycles and electric scooters for distances under 15 kilometers. The high-performance product tier commands disproportionate margin contribution as enthusiasts prioritize motor output and suspension travel over entry-level pricing. Commuter end users represent the volume anchor, though recreational users sustain faster replacement cycles and accessory attachment rates. Lithium-ion battery configurations dominate the installed base, with lithium polymer variants gaining share in premium models where weight reduction justifies cell cost premiums.
FCC certification requirements in the United States constrain transmitter-equipped models and shape product development roadmaps for connectivity features. ECE R136 and CE marking protocols in Europe govern electromagnetic compatibility and mechanical safety standards that determine market access eligibility. China's GB standards and MIIT type-approval processes set baseline technical thresholds for domestic manufacturers that subsequently export. Stakeholders must monitor how evolving battery transportation regulations across aviation and rail networks reshape consumer purchase confidence and channel economics.
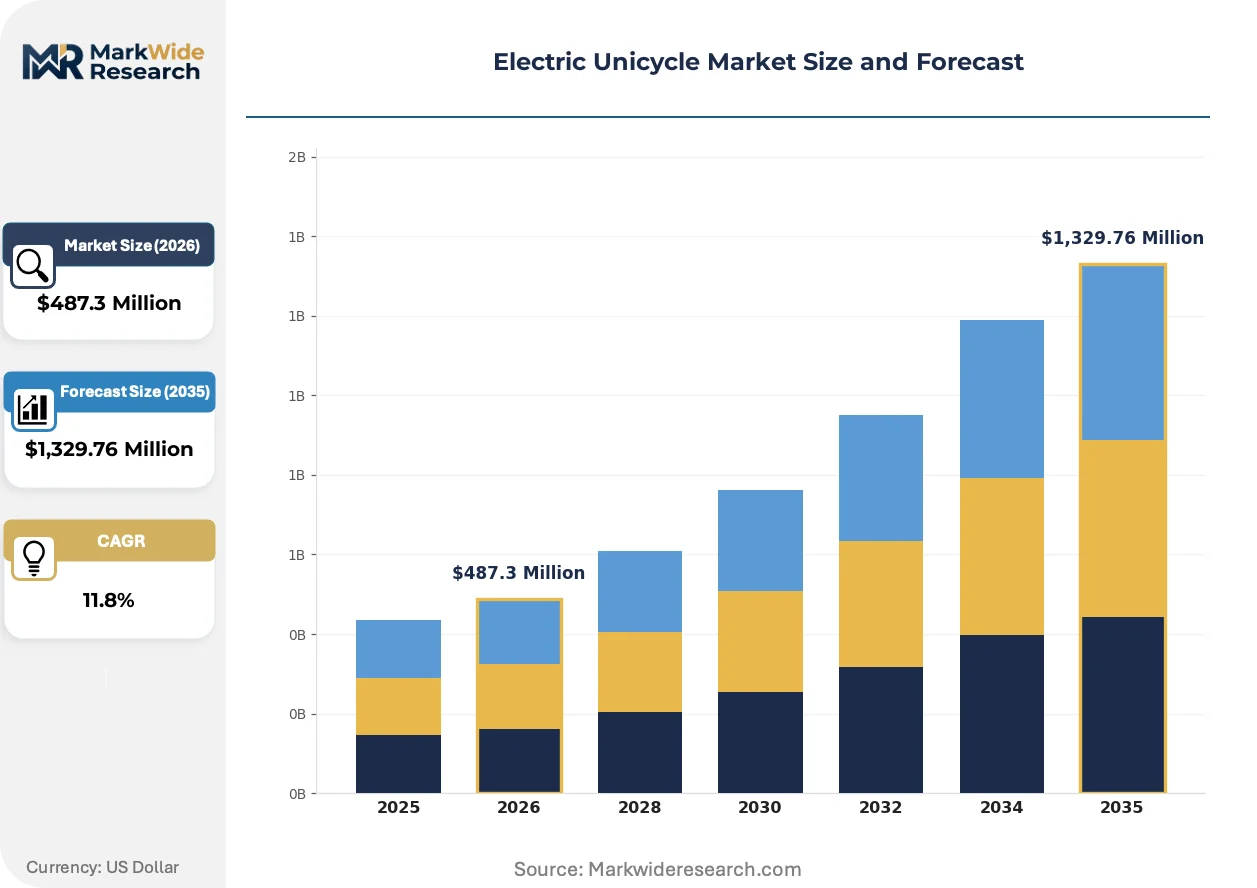
Market Dynamics
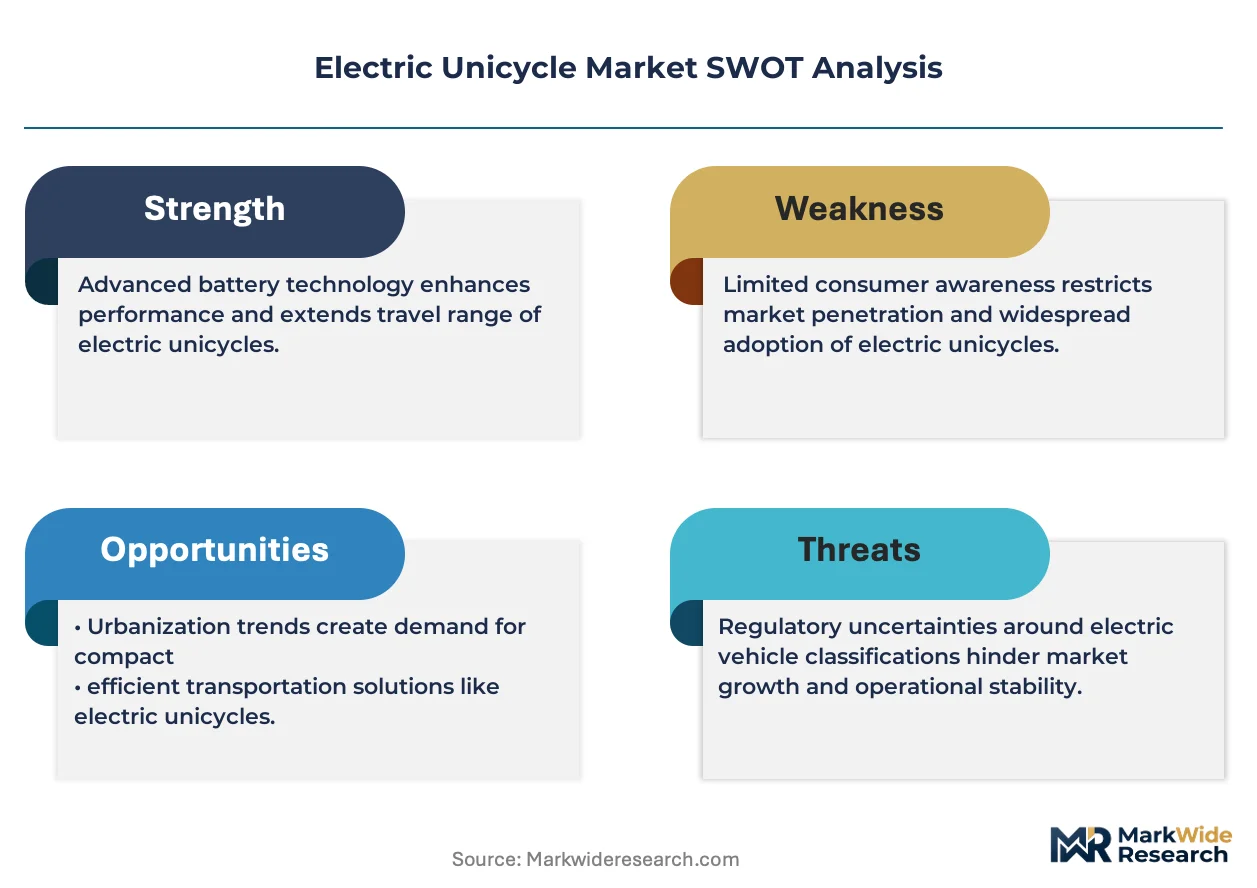
Aftermarket service revenue streams are restructuring profitability for electric unicycle manufacturers as hardware margins compress across all tiers. Firmware-locked battery ecosystems and modular repair architectures are diverging as competitive control points.
Growth Catalysts
- Lithium-ion energy density gains:Cell-level improvements are extending single-charge range capabilities for urban commuters beyond 15 kilometers without weight penalties.
- European last-mile delivery procurement:Urban logistics fleets in Amsterdam, Berlin, and Paris are expanding personal mobility device procurement for congestion-zone operations.
- Chinese manufacturing cluster maturation:Shenzhen and Dongguan component ecosystems have reduced assembly lead times and parts sourcing costs for electric micro-mobility devices.
Market Restraints
- Aviation battery transport restrictions:IATA lithium battery regulations constrain consumer purchase confidence for air-travel-dependent buyers and raise reverse logistics costs.
- Hub motor supply concentration:Winding and magnet supply chains concentrate in specific Chinese industrial zones, creating geographic single-source vulnerability.
- Solid-state battery cost premiums:Research-stage cell chemistries remain uneconomical for mass-market pricing despite range and safety advantages.
Strategic Opportunities
- Authorized service channel capture:Firmware-locked battery ecosystems steer consumers toward manufacturer-controlled repair networks, securing recurring revenue.
- Modular architecture standardization:Field-replaceable motor and battery modules reduce technician training costs and expand third-party service network viability.
- Rail network battery policy harmonization:National rail operators are revising personal mobility device carriage rules, potentially unlocking intercity commuter segments.
Industry Challenges
- Gyroscopic calibration technician scarcity:Sensor fusion and motor control expertise concentrates among a limited pool of specialized repair professionals.
- Multi-jurisdiction certification timelines:FCC, CE marking, and MIIT type-approval processes impose sequential market entry delays for transmitter-equipped models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Unicycle Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,329.76 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, High-Performance, Off-Road, Mini End User: Commuters, Recreational Users, Students, Tourists Weight Capacity: Below 70 kg, 70-100 kg, 100-130 kg, Above 130 kg Battery Type: Lithium-Ion, Lithium Polymer, Lead Acid, Others |
| Companies Covered | Airwheel, Begode, Inmotion, Solowheel, IPS, KingSong, Gotway, Rockwheel, Segway, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Unicycle Market Emerging Trajectories
Component-level control strategies are diverging across manufacturers as hardware commoditization accelerates. Repair ecosystem lock-in and modular openness represent opposing bets on customer retention.
Suspension systems are migrating from fixed rigid forks to adjustable air and coil-spring configurations in premium tiers. Enthusiast riders are adopting these systems for terrain versatility at speeds exceeding 35 kilometers per hour. This capability expansion is compressing the performance gap between electric unicycles and larger personal electric vehicles.
CE marking and ECE R136 protocols are tightening electromagnetic compatibility and mechanical safety thresholds for European market access. Manufacturers are redesigning transmitter modules and chassis structures to satisfy notified body requirements. High-performance models with integrated connectivity features face disproportionate compliance burden and retesting costs.
Fleet procurement departments are consolidating vendor relationships around total-cost-of-ownership metrics rather than unit pricing. Last-mile delivery operators in dense European cities are selecting suppliers based on field service response times and parts availability guarantees. This evaluation shift favors manufacturers with captive repair infrastructure over pure hardware vendors.
Electric Unicycle Market Segmentation
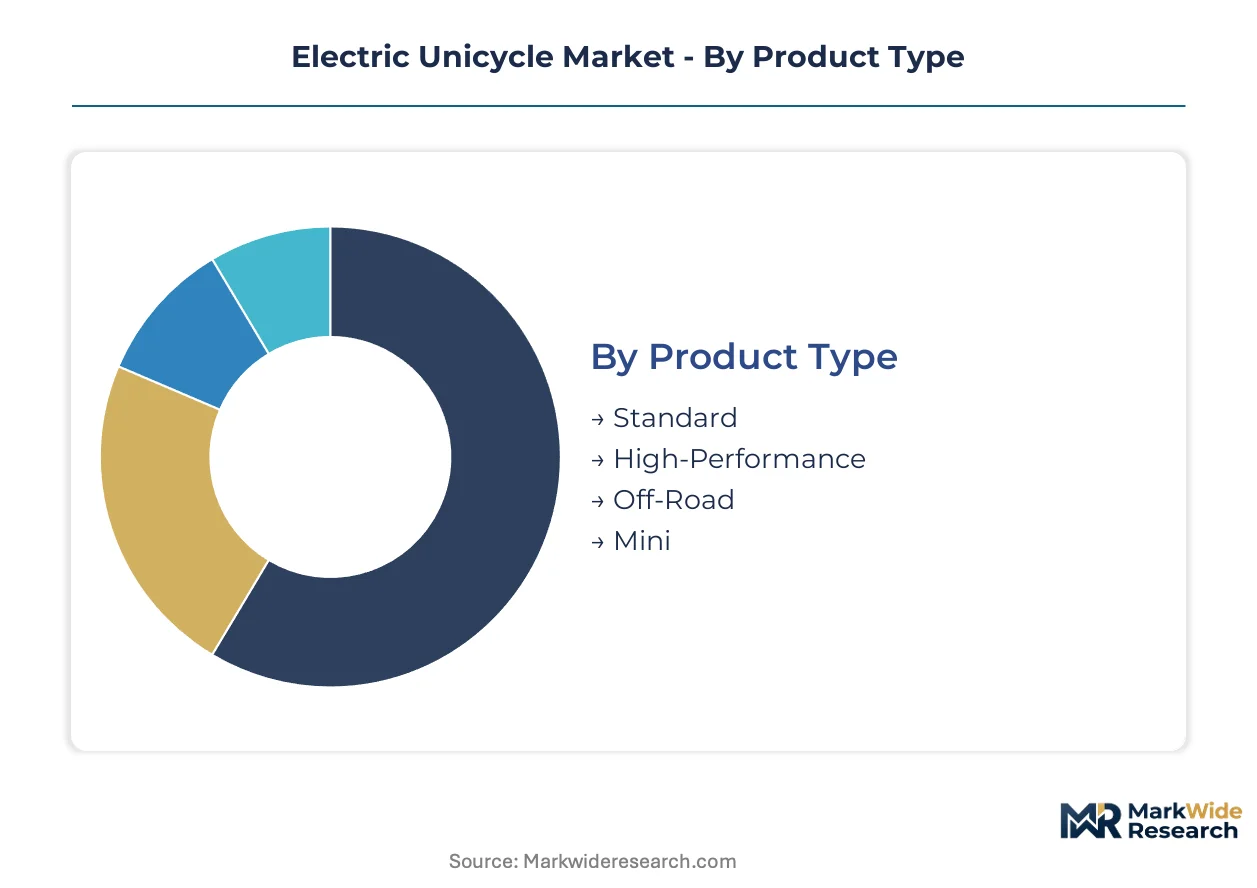
Segmentation in the electric unicycle market reveals divergent engineering priorities across rider profiles and use cases. Product architecture, battery chemistry, and load-bearing specifications each command distinct supply chain configurations and margin structures.
Product Type:
Mature commuter-oriented designs now coexist with emerging performance and terrain-specialized variants that rewrite component sourcing requirements.
- Standard:Single-motor hub designs with 10-15 kilometer range dominate urban procurement for last-mile logistics operators in Amsterdam and Paris. Fleet managers prioritize unit cost and parts commonality over suspension or connectivity features.
- High-Performance:Dual-motor configurations with 35+ kilometer per hour top speeds and active cooling systems attract enthusiast riders seeking motor output and suspension travel. This tier commands disproportionate margin contribution despite lower unit volumes.
- Off-Road:Knobby tire profiles and sealed bearing housings address trail and mixed-terrain applications.
- Mini:Reduced wheel diameters and foldable pedal designs target multimodal commuters with strict carry-on size constraints.
Standard retains volume leadership; High-Performance holds the steepest expansion curve.
End User:
Cost tier stratification separates institutional procurement from individual purchase patterns across rider demographics.
- Commuters:Daily trip distances under 15 kilometers drive demand for weather-sealed electronics and integrated lighting systems. Workplace charging infrastructure availability shapes purchase confidence in German and Dutch urban corridors.
- Recreational Users:Weekend riders sustain faster replacement cycles and accessory attachment rates for protective gear and performance upgrades. This segment tolerates premium pricing for suspension and range extensions.
- Students:Campus mobility needs concentrate in Chinese and European university towns with restricted automobile access.
- Tourists:Rental fleet demand fluctuates with seasonal travel patterns and guided tour operator vendor selections.
Commuters anchor manufacturer revenue stability; Recreational Users generate the highest per-customer lifetime value.
Weight Capacity:
Application context determines load-bearing engineering requirements across rider mass distributions.
- Below 70 kg:Lightweight chassis designs with polymer pedal structures serve adolescent and smaller-framed riders. Chinese domestic market volume concentrates here due to demographic weight distributions.
- 70-100 kg:Reinforced axle housings and expanded battery enclosures address the median adult rider profile. This bracket captures the majority of European fleet procurement specifications.
- 100-130 kg:Dual-rim construction and upgraded motor controllers accommodate heavier riders and cargo loads.
- Above 130 kg:Commercial-grade frame alloys and thermal management systems support delivery operator equipment loads.
70-100 kg dominates unit shipments; Above 130 kg is climbing the fastest as logistics fleet specifications tighten.
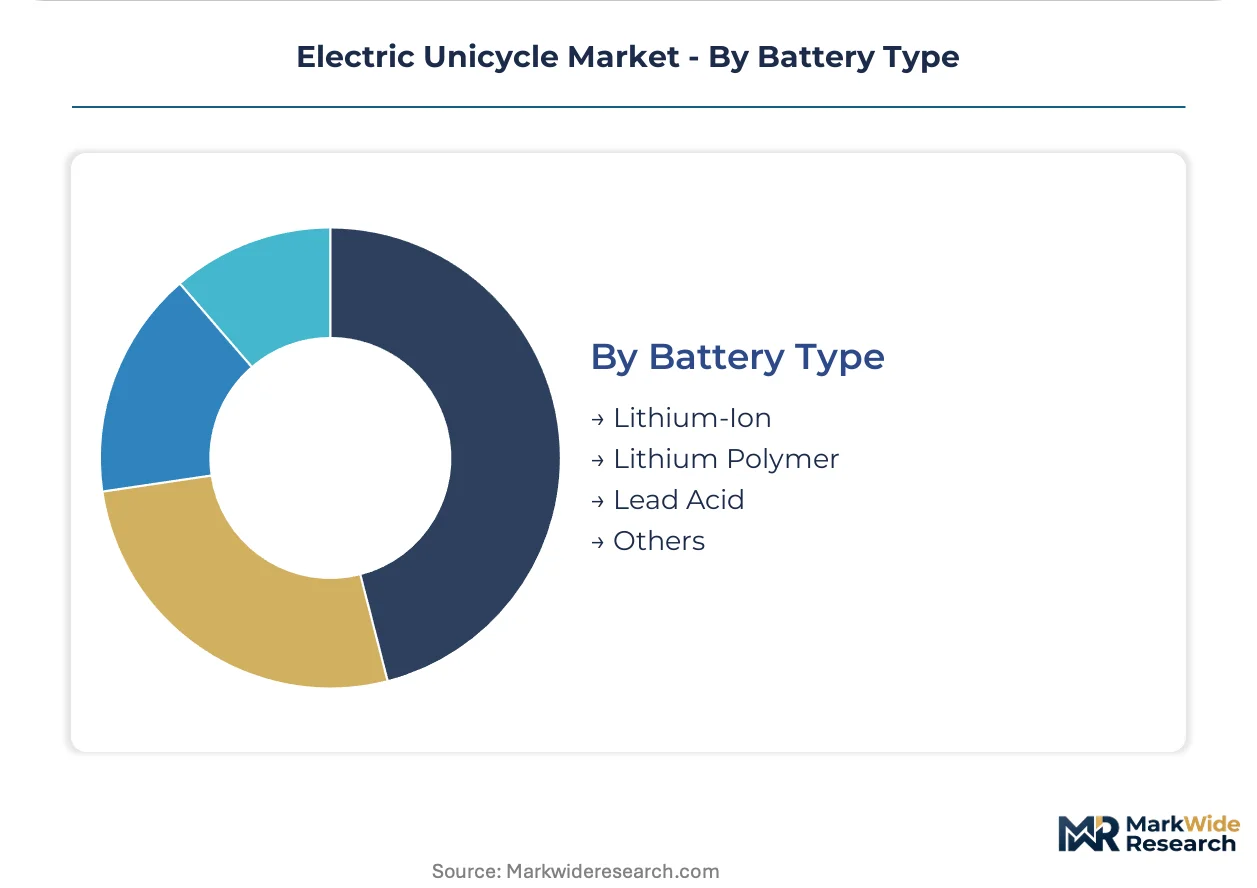
Battery Type:
Supply concentration in cylindrical cell manufacturing shapes chemistry adoption timelines and cost structures.
- Lithium-Ion:18650 and 21700 cylindrical cell configurations dominate the installed base with established BMS firmware ecosystems. Shenzhen cell pack assembly lines achieve lowest per-watt-hour costs at volume.
- Lithium Polymer:Pouch cell architectures enable non-rectangular battery enclosures that reduce chassis weight in premium tiers. Weight reduction justifies cell cost premiums for enthusiast models with aggressive power-to-mass targets.
- Lead Acid:Remaining presence in price-sensitive emerging market segments with limited charging infrastructure reliability.
- Others:Solid-state research-stage chemistries and experimental sodium-ion prototypes.
Lithium-Ion retains manufacturing scale advantages; Lithium Polymer is gaining share fastest in premium model line expansions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Chinese buyers prioritize unit economics above certification overhead. European fleet procurement tolerates premium positioning for service-response guarantees.
China
Domestic volume concentrates in commuter-tier specifications with 70-100 kg load brackets dominating. MIIT type-approval processes set baseline technical thresholds that export-oriented manufacturers must satisfy before accessing foreign markets. Shenzhen and Dongguan host mature component ecosystems where hub motor winding and battery pack assembly lines achieve lowest per-watt-hour costs.
Germany
Workplace charging infrastructure availability shapes purchase confidence across urban corridors. KBA and CE marking protocols govern electromagnetic compatibility standards that determine market access eligibility for transmitter-equipped models. Bavaria and North Rhine-Westphalia anchor fleet procurement decisions for last-mile logistics operators prioritizing total-cost-of-ownership metrics.
United States
Recreational users sustain faster replacement cycles and accessory attachment rates than commuter segments. FCC certification requirements constrain transmitter-equipped models and reshape product development roadmaps for connectivity features. California and Pacific Northwest metropolitan clusters concentrate enthusiast demand for high-performance tiers with suspension travel exceeding 35 kilometers per hour capabilities.
France
Paris-based logistics fleets are expanding personal mobility device procurement for congestion-zone operations. ECE R136 protocols tighten electromagnetic compatibility thresholds that manufacturers redesign transmitter modules to satisfy. Île-de-France and Provence-Alpes-Côte d'Azur concentrate rental fleet demand fluctuating with seasonal travel patterns.
Netherlands
Amsterdam urban logistics operators select suppliers based on field service response times and parts availability guarantees. CE marking and ECE R136 compliance determine eligibility for fleet procurement tenders. Randstad region anchors European procurement volume for standard-tier designs prioritizing unit cost and parts commonality.
Electric Unicycle Market Vendor Landscape
Capability concentration sits with specialist manufacturers; scale advantage sits with diversified mobility platforms. The vendor base organizes around three strategic archetypes: captive repair infrastructure operators, modular architecture specialists, and diversified personal mobility platforms. Consolidation pressure favors manufacturers with in-house motor winding or firmware-locked battery ecosystems. Dominant competitive moves include geographic expansion through certification sequencing and portfolio diversification into adjacent micro-mobility categories.
Within the specialist tier, Begode, Inmotion, and KingSong occupy distinct positioning vectors. Begode exemplifies manufacturers leveraging in-house production capabilities to control repair turnaround times. Inmotion represents the firmware-locked ecosystem approach that steers consumers toward authorized service channels. KingSong anchors the modular architecture vector that simplifies field repairs and reduces technician training costs for third-party service networks.
| Leading Market Players |
|---|
| Airwheel |
| Begode |
| Inmotion |
| Solowheel |
| IPS |
| KingSong |
| Gotway |
| Rockwheel |
| Segway |
| Others |
Supply Flow & Price Mechanics
Shenzhen-Dongguan freight corridors carry hub motor assemblies and cylindrical cell packs at rates that compress landed costs for European distributors while amplifying price differentiation between firmware-locked premium tiers and modular standard configurations. This logistics backbone concentrates procurement leverage among manufacturers with captive winding facilities, forcing spot-market buyers into unfavorable contract terms during peak procurement windows.
Pricing Analysis
Long-term offtake agreements dominate fleet procurement in Amsterdam and Berlin, locking in volume commitments for standard-tier unicycles with 70-100 kg load ratings. Spot purchasing persists in the recreational segment where enthusiast buyers prioritize immediate availability over price predictability. Price differentiation rests on certification grade (CE marking versus baseline compliance) and after-sales service bundling, with authorized repair networks commanding 15-25 point premiums. Cost compression in the standard tier intensifies as Chinese manufacturers expand direct-to-fleet sales, eroding distributor margins. Commuter fleet managers exhibit highest price sensitivity, while recreational users tolerate premium positioning for suspension-equipped dual-motor configurations.
Supply Chain Analysis
Contract manufacturing concentrates in Shenzhen and Dongguan, where Foxconn subsidiaries and specialized EMS providers assemble battery management systems and hub motor controllers for Begode, Inmotion, and KingSong. Raw material dependencies center on neodymium magnet supplies from Inner Mongolia processing facilities, lithium carbonate from Chilean-Argentine salares, and copper winding wire from Jiangxi smelters. Single-source vulnerability concentrates in gyroscopic sensor calibration equipment, where German and Japanese vendors control precision manufacturing. Distribution runs through direct OEM-to-fleet channels for institutional buyers and tiered distributor networks for individual consumers across European and North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service revenue layers expand faster than hardware sales as firmware-locked battery ecosystems and modular repair architectures capture recurring spend from fleet operators and enthusiast riders alike.
For Market Incumbents: Entrench control over authorized service channels by deepening backward integration into motor winding and battery pack assembly. Defend margin position against modular competitors by accelerating MIIT type-approval sequencing for transmitter-equipped models ahead of CE marking revisions. Prioritize captive repair infrastructure in Randstad and Bavaria where fleet procurement evaluates total-cost-of-ownership metrics. For New Entrants and Emerging Players: Establish a beachhead in the mini-segment serving multimodal commuters with strict carry-on size constraints across German and Dutch urban corridors. Target white-space in off-road configurations where knobby tire demand outpaces incumbent R&D investment. Pursue direct-to-tour-operator distribution for seasonal rental fleets in Provence-Alpes-Côte d'Azur and Pacific Northwest metropolitan clusters. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified personal mobility platforms seeking to divest non-core unicycle divisions amid hardware margin compression. Long-term viability hinges on service-attach rates rather than unit shipment growth. Monitor IATA lithium battery regulation harmonization as inflection indicator for consumer purchase confidence and reverse logistics economics.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware-Locked Ecosystem Development | Steers consumers toward authorized repair channels, securing recurring aftermarket revenue streams. |
| Modular Architecture Standardization | Reduces technician training costs and expands third-party service network viability for fleet operators. |
| CE Marking and ECE R136 Pre-Certification | Accelerates European market entry for transmitter-equipped models ahead of regulatory tightening. |
| Rail Network Battery Policy Harmonization | Unlocks intercity commuter segments as national operators revise personal mobility device carriage rules. |
| Hub Motor Supply Diversification | Mitigates geographic single-source vulnerability in winding and magnet supply chains concentrated in Chinese industrial zones. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with fleet procurement managers at Amsterdam and Berlin logistics operators, aftermarket service technicians, and MIIT certification consultants; and secondary validation against Shenzhen customs records, ECE R136 testing protocols, and IATA lithium battery guidance documents. Bottom-up triangulation cross-referenced manufacturer production disclosures with hub motor and battery cell import trajectories. Top-down validation assessed addressable commuter and recreational rider populations across urban corridors in Germany, France, Netherlands, and China.
Forecast inputs considered product type segmentation across standard, high-performance, off-road, and mini configurations alongside end-user stratification by commuters, recreational users, students, and tourists. Battery chemistry transitions from lithium-ion to lithium polymer variants and suspension system adoption curves in premium tiers shaped volume and value projections across the analysis window. CAGRs derived from fitted growth curves adjusted for aviation battery transport restriction scenarios and rail network policy evolution.
Sensitivities concentrate around IATA regulation revisions affecting consumer purchase confidence, solid-state battery cost breakthrough timelines, and gyroscopic calibration technician supply constraints. Forecasts reflect documented assumptions on fleet procurement growth rates and certification timeline compressions. Quarterly review of ECE R136 amendment proposals, MIIT type-approval queue lengths, and lithium carbonate spot price volatility is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
EV Platform Market
Electric Vehicles
China Automotive High Performance Electric Vehicle Market
Electric Vehicles
EV Transmission System Market
Electric Vehicles
Solar Car Market
Electric Vehicles
Asia Pacific Electric Commercial Vehicles Market
Electric Vehicles
Global Electric Vehicles Engineering Plastics Market
Electric Vehicles
Saudi Arabia E-Bike Market
Electric Vehicles
Latin America E-Bike Market
Electric Vehicles
Micro Electric Vehicle Market
Electric Vehicles
US Automotive High Performance Electric Vehicle Market
Electric Vehicles
Electric Vehicle Testing, Inspection, and Certification Market
Electric Vehicles
GCC Electric Vehicle Market
Electric Vehicles
New Energy Vehicle (NEV) Market
Electric Vehicles
Automotive Battery Pack Compression Pad Market
Electric Vehicles
Electric Vehicle Heating System Market
Electric Vehicles
Germany Automotive High Performance Electric Vehicles Market