
 Mexico Solar E-Bike Market | 2026-2036
Mexico Solar E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Solar E-Bike Market Insights
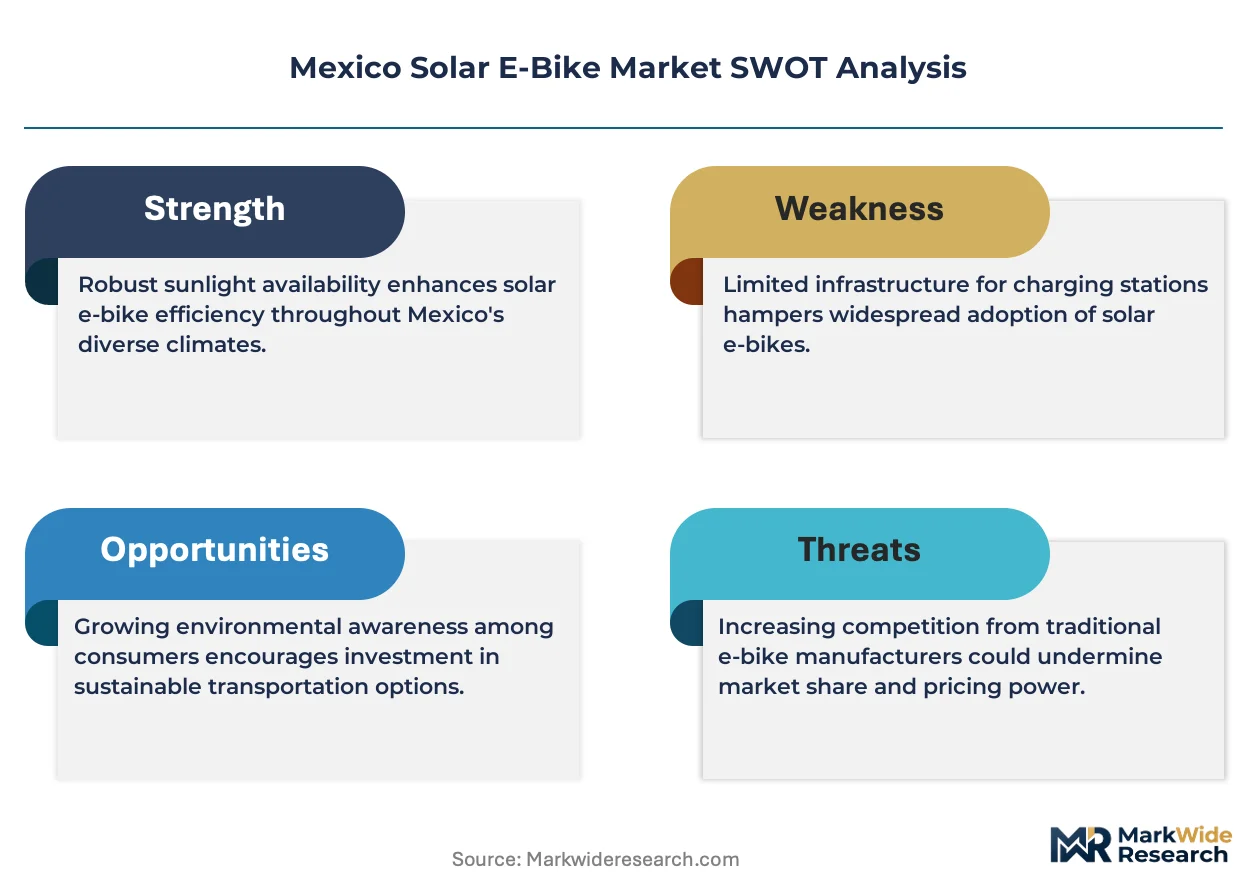
NOM-001-SEDE certification for electrical installations is collapsing the supplier base for solar charging systems, leaving only qualified integrators eligible for commercial contracts. Bicicletas Mercurio SA De CV leverages its domestic manufacturing footprint to control assembly costs in Guanajuato. Trek Bicycle Corporation competes through R&D intensity focused on photovoltaic frame integration. Rad Power Bikes anchors its position via direct-to-consumer channels that bypass traditional distributor markups.
A solar e-bike combines pedal-assist electric propulsion with onboard photovoltaic panels, typically monocrystalline silicon cells rated between 15-25 watts, to trickle-charge lithium-ion battery packs during daylight exposure; the primary purpose is to extend range without grid dependency for urban mobility and light commercial logistics. Commuter e-bikes dominate unit volume as Mexico City congestion charges push professionals toward two-wheel alternatives. Cargo e-bikes capture the fastest expansion among product types, with delivery services absorbing fleet-scale orders. Smart connectivity technology concentrates margin pools through subscription-based telemetry and theft-recovery services.
CRE, Mexico's energy regulator, oversees net-metering rules that determine whether solar e-bike charging stations qualify for distributed generation credits, while SEMARNAT enforces environmental standards on battery recycling and panel disposal. PROFECO's consumer protection mandates shape warranty requirements and replacement part availability across domestic sales channels. Stakeholders must monitor how pending reforms to the Electric Industry Law affect off-grid charging incentives before committing to fleet deployment strategies.
Market Dynamics
NOM-001-SEDE certification requirements are compressing the supplier base for commercial solar charging systems, forcing fleet operators toward qualified integrators and away from uncertified component vendors. This regulatory tightening intersects with diesel restriction zones in Mexico City to accelerate fleet electrification timelines.
Growth Catalysts
- Congestion Pricing:Mexico City's Hoy No Circula program and expanding zero-emission zones push delivery fleets toward solar e-bikes as compliance pathways. Professional commuters absorb unit volume as operating cost advantages compound.
- Photovoltaic Efficiency Gains:Monocrystalline silicon cell improvements extend trickle-charge rates during daylight exposure. Fleet operators capture range extension without grid dependency for last-mile routes.
- Guadalajara Metropolitan Demand:Solar irradiance levels above 5.5 kWh/m² daily overlap with dense urban logistics corridors. Delivery services concentrate procurement in this zone.
Market Restraints
- Lithium-Ion Battery Input Volatility:Cathode material cost swings compress assembler margins. Domestic pack production remains limited to imported cell supply.
- Qualified Integrator Concentration:NOM-001-SEDE certification requirements restrict commercial charging system deployment to a narrow vendor tier. Fleet procurement timelines extend to accommodate qualified supplier queues.
- Grid-Dependent Fast Charging:Solar panel wattage ratings of 15-25 watts deliver insufficient rapid-charge capability for high-turnover commercial use. Battery swap infrastructure substitutes for pure solar autonomy.
Strategic Opportunities
- Baja California Peninsula:Isolated grid infrastructure and elevated solar irradiance create off-grid mobility demand. Tourism operators and remote logistics services represent untapped fleet segments.
- Smart Connectivity Convergence:GPS telemetry and theft-recovery systems merge with photovoltaic monitoring. Subscription revenue pools detach from hardware margins.
- PROFECO Warranty Mandates:Extended replacement part requirements create aftermarket service revenue streams. Certified service networks capture recurring revenue from fleet maintenance contracts.
Industry Challenges
- Photovoltaic Integration Engineering:Frame-embedded panel durability testing exceeds standard bicycle certification timelines. Manufacturers absorb extended R&D cycles for commercial-grade weatherproofing.
- SEMARNAT Battery Recycling Compliance:End-of-life lithium-ion collection and disposal obligations add operational overhead. Fleet operators must document chain-of-custody for regulatory audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Solar E-Bike Market |
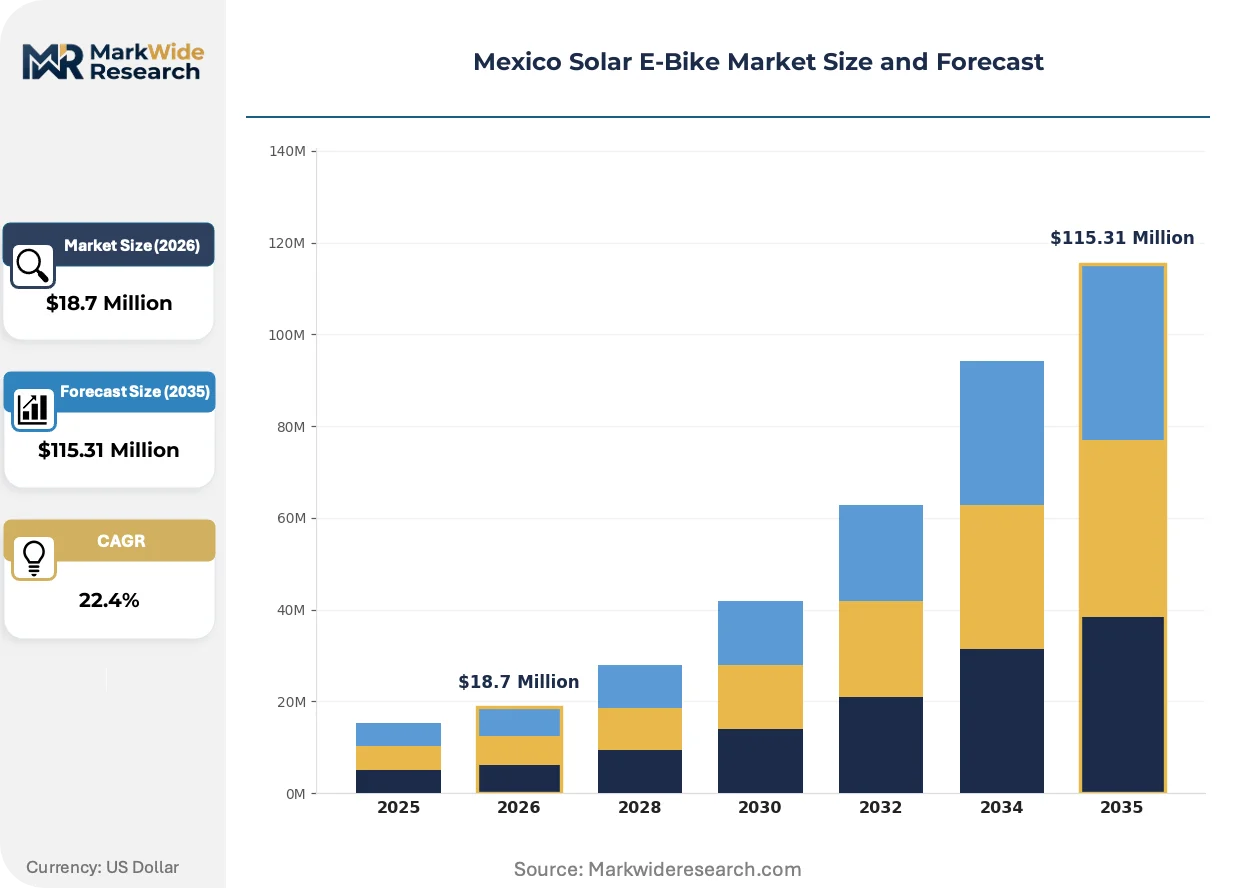
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $115.31 Million |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mountain E-Bikes, Commuter E-Bikes, Folding E-Bikes, Cargo E-Bikes Technology: Solar Panels, Lithium-Ion Batteries, Regenerative Braking, Smart Connectivity End User: Urban Commuters, Recreational Riders, Delivery Services, Eco-Conscious Consumers Distribution Channel: Online Retailers, Specialty Bike Shops, Supermarkets, Direct Sales |
| Companies Covered | Bicicletas Mercurio SA De CV, Distribuidora de Bicicletas Benotto, Specialized Bicycle Components, Trek Bicycle Corporation, Giant Bicycles, Yamaha Bicycles, Pedego Electric Bikes, Rad Power Bikes, Accell Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Solar E-Bike Market Trends and Innovations
Photovoltaic frame integration and smart connectivity layers are redefining product architecture in Mexico's solar e-bike segment. These shifts compress traditional component boundaries while opening subscription revenue streams.
Monocrystalline silicon cell embedding into bicycle frames delivers continuous trickle-charging during daylight exposure. Cargo fleet operators in Mexico City adopt these integrated systems fastest, prioritizing range autonomy over charging station dependency. The technology is bifurcating the market between premium frame-integrated designs and bolt-on panel retrofits.
CRE net-metering rule reforms under consideration would extend distributed generation credits to commercial solar charging stations. This policy evolution alters fleet total-cost-of-ownership calculations for depot-based operators. Guadalajara metropolitan logistics providers track these proceedings most closely given their concentration of solar charging infrastructure.
Direct-to-consumer channel expansion displaces traditional bicycle distributor networks for solar e-bike sales. Urban professionals in Mexico City purchase through manufacturer websites, bypassing retail markups and accessing configuration tools. This channel rotation concentrates margin capture with brands owning digital fulfillment infrastructure.
Mexico Solar E-Bike Market Segmentation
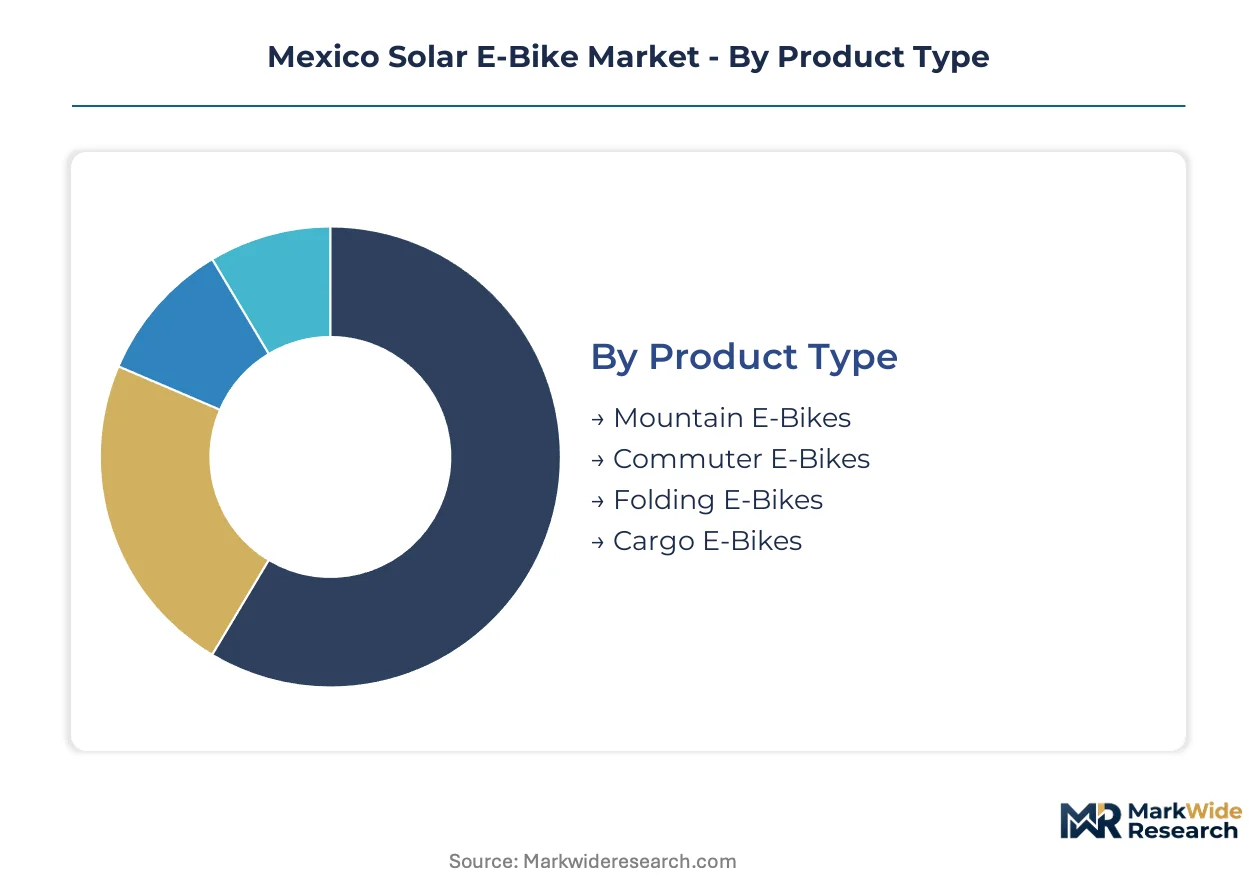
Segmentation in Mexico's solar e-bike market reveals how regulatory pressure and urban logistics demands fragment procurement behavior. Fleet operators, individual commuters, and recreational buyers each trigger distinct product specifications and channel preferences.
Product Type:
Margins pool in cargo configurations where fleet-scale contracts justify premium photovoltaic integration and extended warranty terms.
- Cargo E-Bikes:Reinforced frames accommodate 100-150 kg payloads with integrated monocrystalline panels rated 20-25 watts. Mexico City delivery fleets absorb volume as diesel restriction zones expand, prioritizing range autonomy over charging infrastructure dependency.
- Commuter E-Bikes:Lightweight aluminum frames with 15-20 watt solar arrays target Guadalajara metropolitan professionals navigating congestion pricing zones. This segment concentrates unit volume through direct-to-consumer channels that bypass traditional retail markups.
- Mountain E-Bikes:Off-road suspension systems with weatherproof panel housing serve Baja California tourism operators and recreational trail networks.
- Folding E-Bikes:Compact hinge mechanisms with detachable solar arrays address multi-modal commuters in dense urban cores.
Cargo E-Bikes hold installed capacity. Commuter E-Bikes is rotating up the share rankings.
Technology:
Smart connectivity layers capture recurring revenue through subscription telemetry, decoupling margin capture from hardware sales cycles.
- Smart Connectivity:GPS tracking, theft-recovery systems, and photovoltaic performance monitoring merge into subscription-based service tiers. Fleet operators in Mexico City adopt these systems fastest to manage distributed asset pools across depot networks.
- Solar Panels:Monocrystalline silicon cells embedded in frames or mounted as bolt-on accessories deliver 15-25 watt trickle-charging. Guadalajara's 5.5+ kWh/m² daily irradiance maximizes charge rates for commercial deployments.
- Lithium-Ion Batteries:NMC and LFP chemistries dominate pack configurations, with SEMARNAT recycling compliance adding operational overhead to end-of-life management.
- Regenerative Braking:Hub-motor energy recovery systems extend range in stop-start urban environments, particularly valued by delivery services.
Smart Connectivity commands service revenue density. Solar Panels is climbing the fastest in commercial procurement priority.
End User:
Delivery services concentrate procurement volume through fleet-scale tenders that reshape manufacturer capacity allocation.
- Delivery Services:Last-mile logistics operators in Mexico City and Guadalajara metropolitan zones absorb cargo e-bike production at contract scales. NOM-001-SEDE certification requirements filter vendor eligibility, extending procurement timelines.
- Urban Commuters:Professionals in congestion-priced districts purchase through direct-to-consumer platforms, configuring panel wattage and battery capacity to route profiles.
- Eco-Conscious Consumers:Sustainability-motivated buyers in Mexico City and Monterrey prioritize frame-integrated photovoltaic designs over bolt-on retrofits.
- Recreational Riders:Weekend cyclists in coastal tourism zones and mountain trail regions drive folding and mountain e-bike demand.
Delivery Services anchors fleet deployment scale. Eco-Conscious Consumers is gaining share fastest in premium channel mix.
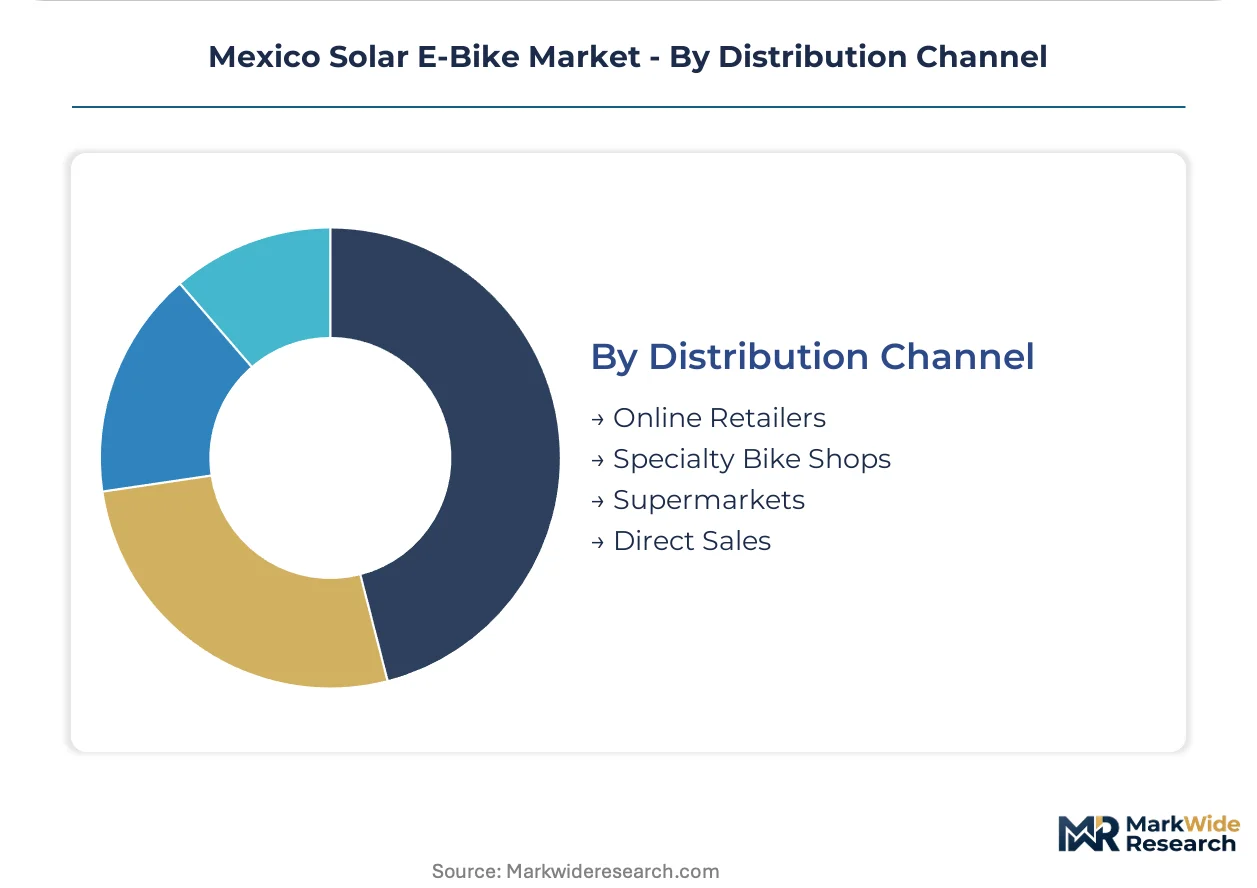
Distribution Channel:
Direct sales concentrate margin capture with manufacturers owning digital fulfillment infrastructure, displacing traditional distributor networks.
- Direct Sales:Manufacturer-owned websites and branded showrooms in Mexico City and Guadalajara configure photovoltaic specifications to customer profiles. PROFECO warranty mandates shape post-sale service obligations.
- Online Retailers:E-commerce platforms aggregate comparison traffic for commuter and folding segments, though NOM-001-SEDE certification limits commercial-grade product listings.
- Specialty Bike Shops:Independent retailers in metropolitan zones provide assembly and maintenance services, particularly for complex frame-integrated panel systems.
- Supermarkets:Mass-market channels move entry-level bolt-on solar kits and basic e-bike configurations with limited photovoltaic integration.
Direct Sales controls premium pricing power. Specialty Bike Shops is rotating up the share rankings through service attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal subsidies for renewable mobility infrastructure and state-level clean air mandates are redistributing solar e-bike procurement across Mexico's metropolitan corridors. Fleet operators track these incentive gradients when siting depot charging networks.
Mexico City Metro
Hoy No Circula diesel restrictions and expanding zero-emission zones compel delivery services toward electrified last-mile fleets. SEMARNAT air quality enforcement tightens commercial vehicle emissions thresholds quarterly. Iztapalapa and Venustiano Carranza districts concentrate solar charging depot construction for logistics operators.
Jalisco
Guadalajara's 5.5+ kWh/m² daily solar irradiance maximizes photovoltaic trickle-charge efficiency for commercial deployments. State energy agency incentives for distributed generation accelerate fleet-scale charging infrastructure. Zapopan logistics corridors absorb the highest cargo e-bike procurement volumes in western Mexico.
Nuevo León
Monterrey industrial parks generate cross-border e-commerce fulfillment demand requiring zero-emission last-mile solutions. State environmental regulations align with federal PROFECO warranty mandates for commercial vehicle procurement. San Pedro Garza García hosts pilot programs for solar-powered delivery microhubs.
Bajío Region
Guanajuato's manufacturing base supplies domestic assembly operations with reduced logistics costs for frame-integrated photovoltaic systems. State industrial development incentives attract component suppliers to the León-Silao-Irapuato corridor. Fleet operators source locally assembled units to bypass import tariff exposure.
Northern Border States
Baja California's isolated grid infrastructure and elevated solar irradiance create off-grid mobility demand for tourism and remote logistics operators. Cross-border e-commerce fulfillment from Tijuana generates last-mile delivery volume requiring charging autonomy. Mexicali solar resource levels support pure photovoltaic depot operations without grid backup dependency.
Mexico Solar E-Bike Market Competitive Landscape
Listed leaders compete with private specialists across certification compliance and channel reach. The supplier base compresses around NOM-001-SEDE qualified integrators capable of commercial-scale deployment. Three archetypes dominate: domestic manufacturers controlling assembly economics, multinational brands with photovoltaic R&D programs, and direct-to-consumer specialists bypassing distributor networks. Competitive moves concentrate on vertical integration into battery pack production and strategic partnerships with fleet operators for depot charging infrastructure.
Within the domestic manufacturing tier, Bicicletas Mercurio SA De CV and Distribuidora de Bicicletas Benotto exemplify cost-controlled assembly positioning. Among multinational competitors, Trek Bicycle Corporation and Giant Bicycles occupy positions defined by frame-integrated photovoltaic development intensity. Rad Power Bikes anchors the direct-to-consumer archetype through digital fulfillment infrastructure that captures margin otherwise lost to distributor markups.
| Leading Market Players |
|---|
| Bicicletas Mercurio SA De CV |
| Distribuidora de Bicicletas Benotto |
| Specialized Bicycle Components |
| Trek Bicycle Corporation |
| Giant Bicycles |
| Yamaha Bicycles |
| Pedego Electric Bikes |
| Rad Power Bikes |
| Accell Group |
| Others |
Pricing and Supply Chain Analysis
NOM-001-SEDE certification gates both supplier qualification and price differentiation simultaneously, compressing commercial charging system deployment to qualified integrators while stratifying procurement costs across certified and uncertified tiers. Fleet operators absorb extended timelines and premium pricing for NOM-001-SEDE-compliant installations, whereas individual commuters access lower-cost bolt-on configurations through direct-to-consumer channels.
Pricing Analysis
Certification level creates the primary spread between commercial-grade NOM-001-SEDE installations and consumer-tier bolt-on systems. Three-tier pricing structure across premium frame-integrated, standard certified, and economy retrofit levels reflects photovoltaic wattage ratings and warranty bundling. Cost compression in the economy tier is intensifying because imported panel assemblies face currency exposure. Delivery services demonstrate lowest price sensitivity due to total-cost-of-ownership compliance advantages, while individual commuters in Mexico City exhibit highest elasticity.
Supply Chain Analysis
Just-in-time inventory strategies dominate lithium-ion cell procurement given cathode material volatility, whereas strategic stockpiling concentrates among NOM-001-SEDE-certified integrators buffering against qualified supplier queues. Manufacturing concentrates in China for monocrystalline silicon cells, South Korea for battery pack assembly, and Mexico's Bajío Region for domestic frame integration. The supply chain rests on lithium carbonate, aluminum frame extrusions, and power electronics modules. Single-source vulnerability runs through Chinese photovoltaic cell supply. Distribution runs through direct-to-consumer platforms and fleet-scale integrator contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation across Mexico City and Guadalajara logistics corridors is shifting procurement leverage toward buyers, fragmenting manufacturer pricing power across fewer, larger accounts.
For Market Incumbents: Consolidate NOM-001-SEDE certification coverage across depot charging networks before qualified integrator queues extend further. Deepen backward integration into lithium-ion pack assembly to offset cathode material volatility. Threat substitution from battery swap infrastructure demands photovoltaic autonomy differentiation as the defensive anchor. For New Entrants and Emerging Players: Differentiate on Baja California off-grid configurations where grid isolation and tourism demand create white-space penetration. Target remote logistics operators and eco-tourism fleets with frame-integrated designs optimized for 6+ kWh/m² irradiance zones. Go-to-market through regional energy cooperatives bypassing metropolitan distributor saturation. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational bicycle manufacturers with stranded photovoltaic R&D assets outside core markets. Long-term viability hinges on CRE net-metering rule evolution extending distributed generation credits to commercial charging infrastructure. Watch SEMARNAT battery recycling compliance cost pass-through as the inflection signal for operational margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| NOM-001-SEDE Certification Expansion | Qualified integrator status unlocks fleet-scale contracts in Mexico City diesel restriction zones. |
| Photovoltaic Frame Integration R&D | Monocrystalline embedding durability extends warranty terms for commercial cargo deployments. |
| Battery Pack Assembly Localization | Guanajuato manufacturing reduces import tariff exposure and shortens fleet procurement timelines. |
| Smart Connectivity Platform Launch | Subscription telemetry generates recurring revenue detached from hardware margin cycles. |
| Baja California Distribution Partnership | Regional energy cooperatives access off-grid tourism and remote logistics demand clusters. |
Research Methodology
The analysis maps cargo e-bike fleet procurement, commuter direct-to-consumer channels, and off-grid tourism deployments, each validated through fleet operations managers, NOM-001-SEDE certified integrators, photovoltaic component suppliers, and energy regulatory specialists. Primary interview insights combined with secondary validation from CRE distributed generation filings, SEMARNAT environmental compliance records, PROFECO consumer protection databases, and customs trade data. Bottom-up unit economics triangulate against top-down market sizing across the projection horizon.
Consistency checks validated volume and value outputs against external benchmarks including vehicle registration databases, fleet operator procurement disclosures, and regional irradiance-adjusted deployment rates. Segmentation dimensions modeled span product type, technology tier, end-user archetype, and distribution channel, with CAGRs derived from installation capacity build-out trajectories and replacement cycle assumptions. Forecast inputs incorporate NOM-001-SEDE certification queue lengths and CRE net-metering rule reform probabilities.
Material uncertainties — lithium carbonate price volatility, CRE regulatory reform timing, and NOM-001-SEDE qualified integrator capacity constraints — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding fleet electrification mandates and solar irradiance stability. Revision becomes warranted when cathode material cost swings exceed historical bands or CRE distributed generation credit eligibility shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Canada E-Bike Market
Electric Vehicles
France Hybrid Electric Vehicle Battery Market
Electric Vehicles
Used EV Market
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
Global Industrial Electric Vehicle Market
Electric Vehicles
Train Battery Market
Electric Vehicles
South America Electric Vehicle (EV) Fluids Market
Electric Vehicles
United States Electric Car Market
Electric Vehicles
Bus Pantograph Charger Market
Electric Vehicles
Electric Vehicle Reducer Market
Electric Vehicles
E-Axle Market
Electric Vehicles
Electric Vehicle Battery Enclosure Market
Electric Vehicles
Extended Range Electric Vehicle (EREV) Market
Electric Vehicles
Middle-East and Africa E-Bike Market
Electric Vehicles
Netherlands Solar E-Bike Market
Electric Vehicles
Hybrid E-Scooter Market