
 Africa Electric Vehicle Market | 2026-2036
Africa Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Electric Vehicle Market Outlook
UN ECE R100 certification for battery safety in electric powertrains is unwinding competitive access across the continent, filtering out assemblers lacking testing infrastructure. BYD Co. Ltd. leverages its integrated battery-cell-to-vehicle manufacturing to undercut landed costs for African distributors. Ampersand sustains a swap-station network in Kigali and Nairobi that anchors its motorcycle-leasing model to commercial couriers. Spiro competes through pay-as-you-go battery subscriptions that reduce upfront acquisition barriers for ride-hailing drivers.
An Africa electric vehicle is a road-certified automobile or motorcycle propelled by one or more electric motors drawing energy from rechargeable battery packs, typically operating at 48V to 800V depending on vehicle class, with lithium-ion cells constituting the dominant chemistry for their superior energy density and cycle life. The primary purpose spans urban passenger mobility, freight logistics, and public transit decarbonization across cities where imported petroleum costs strain trade balances. Hatchback and sedan configurations lead unit volume among four-wheelers due to lower price points suited to emerging middle-class buyers, while the lithium-ion battery segment captures the dominant share of value as cell costs decline and solid-state alternatives remain pre-commercial. Fleet operators represent the fastest-growing customer segment because bulk procurement, predictable routes, and centralized charging allow faster payback calculus than dispersed individual ownership.
Kenya's Energy and Petroleum Regulatory Authority, Rwanda's Rwanda Utilities Regulatory Authority, and South Africa's National Regulator for Compulsory Specifications each enforce divergent import and safety standards that fragment homologation pathways for original equipment manufacturers. These regulatory layers shape demand by raising compliance costs for new entrants while creating protected niches for local assemblers who navigate certification complexity. Stakeholders must monitor how regional economic communities harmonize technical standards, as misaligned rules risk stranding charging infrastructure investments and duplicating testing expenditures across neighboring markets.
Market Dynamics
Kenya's exemption of electric vehicle parts from import duties and value-added tax is compressing total cost of ownership and accelerating fleet procurement decisions across East African urban corridors.
Growth Catalysts
- Kenya's fiscal exemption framework:Import duty and VAT waivers on EV components reduce landed costs for commercial fleet operators in Nairobi and Mombasa.
- Swap-station infrastructure:Battery exchange networks in Kigali and Nairobi eliminate range anxiety for courier and ride-hailing drivers operating predictable urban routes.
- Lithium-ion cell cost curves:Declining battery pack prices improve payback periods for two-wheeler electrification programs targeting last-mile delivery segments.
Market Restraints
- Homologation fragmentation:Divergent safety standards enforced by Kenya's Energy and Petroleum Regulatory Authority, Rwanda's Rwanda Utilities Regulatory Authority, and South Africa's National Regulator for Compulsory Specifications duplicate compliance expenditures for original equipment manufacturers.
- Charging infrastructure capital intensity:Grid reinforcement requirements and utility partnership negotiations delay station deployment in peri-urban zones outside Nairobi-Kigali-Lagos corridors.
- Petroleum price volatility hedging:Fleet operators retain hybrid vehicle exposure to manage diesel cost swings that distort total cost of ownership comparisons.
Strategic Opportunities
- Rwanda's regulatory harmonization leadership:Regional economic community alignment on UN ECE R100 battery safety certification would streamline cross-border vehicle certification pathways.
- Pay-as-you-go battery subscriptions:Asset-light financing models reduce upfront acquisition barriers for informal sector ride-hailing drivers in Lagos and Dar es Salaam.
- Solid-state chemistry convergence:Next-generation cell technologies promise enhanced energy density for long-haul freight electrification connecting East African trade corridors.
Industry Challenges
- UN ECE R100 testing infrastructure scarcity:Limited accredited laboratories in East Africa extend certification timelines for local assemblers seeking battery safety validation.
- Utility interconnection queues:Distribution network operators in Kenya and Rwanda face backlogs for commercial charging station grid connections that stall fleet operator deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Electric Vehicle Market |
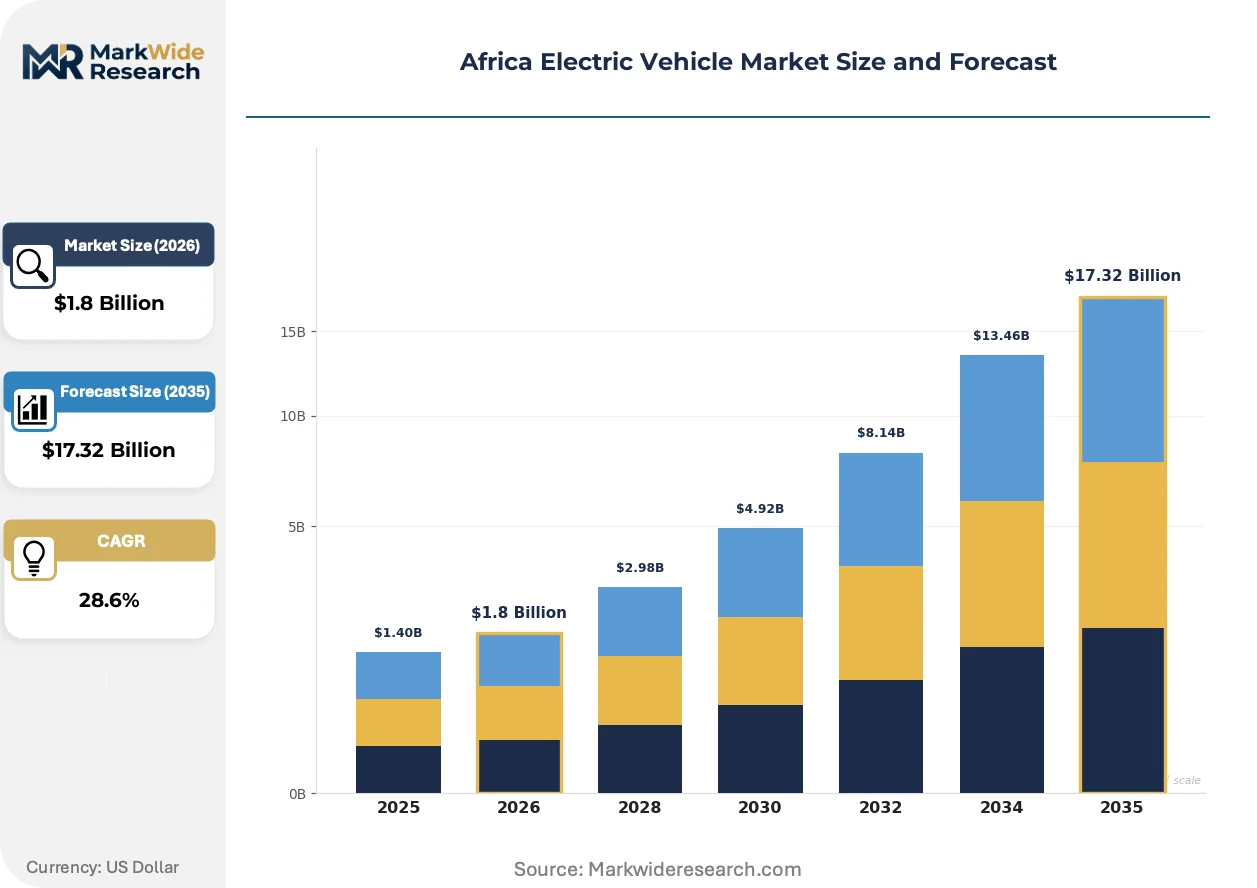
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Sedan, Hatchback, Truck Battery Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Solid-state Charging Infrastructure: Fast Charging, Home Charging, Public Charging, Wireless Charging Customer Segment: Fleet Operators, Individual Consumers, Government Agencies, Ride-sharing Services |
| Companies Covered | Nissan Motor Co., Ltd., Ampersand, BYD Co. Ltd., Roam Electric, BasiGo, Tesla Inc., Hyundai Motor Co., Spiro, Volkswagen AG, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Electric Vehicle Market Strategic Shifts
Electrification architectures are converging around modular battery platforms that decouple vehicle purchase from energy procurement, reshaping how commercial operators finance and operate electric fleets.
Silicon carbide power electronics are replacing silicon IGBTs in motor inverters for their superior thermal efficiency and switching speed. Fleet operators in Kenya's courier segment are specifying SiC-equipped drivetrains for reduced cooling system mass. The technology is miniaturizing inverter packaging to enable integrated motor-transmission assemblies that free chassis space for additional battery capacity.
Rwanda's Rwanda Utilities Regulatory Authority is mandating smart metering integration for all public charging stations to enable time-of-use tariff structures and demand response participation. This policy is forcing charging network operators to retrofit existing installations with cellular-connected energy management systems. Commercial fleet depots in Kigali are responding by consolidating charging windows to off-peak periods, altering daily vehicle utilization patterns.
Asset ownership models are fragmenting as fleet operators reject capital-intensive battery purchases in favor of energy-as-a-service contracts. Leasing providers in Nairobi and Lagos are unbundling vehicle chassis from battery packs, transferring cell degradation risk to specialized asset managers. This shift concentrates procurement influence among large fleet aggregators who negotiate volume-based energy pricing with swap-station operators.
Africa Electric Vehicle Market Segmentation
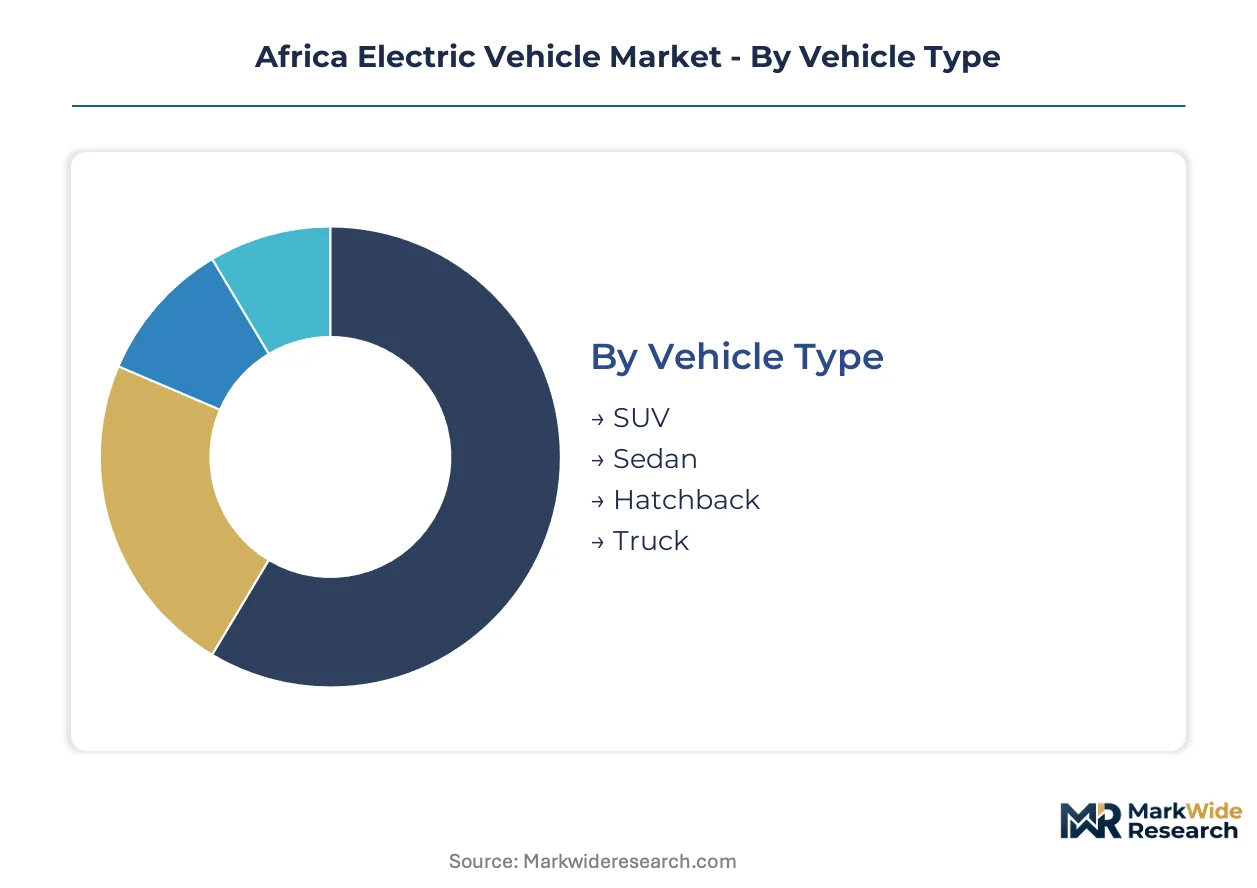
Segmentation reveals how electrification economics vary sharply across use cases and infrastructure access. Battery chemistry and customer type determine payback periods, while vehicle configuration shapes total cost of ownership calculations for fleet procurement committees.
Vehicle Type:
Margin pools concentrate in configurations that balance battery capacity against import duty exposure under Kenya's component exemption framework.
- Sedan:Three-box architecture accommodates larger battery packs without chassis redesign, attracting corporate fleet managers in Nairobi who prioritize range over ground clearance. Demand clusters among banking and telecom sector procurement teams negotiating multi-year service contracts.
- Hatchback:Compact footprint minimizes battery cost while preserving urban maneuverability; Kenya's VAT waiver on EV parts makes this configuration the entry point for emerging middle-class buyers in Mombasa and Kisumu. Two-wheeler graduates seeking four-wheel upgrade paths drive volume expansion here.
- SUV:Higher ground clearance suits rural road conditions but battery mass increases landed cost disproportionately.
- Truck:Freight electrification remains nascent; solid-state chemistry convergence would unlock long-haul viability across East African corridors.
The dominant share belongs to Hatchback, while Sedan is closing the gap fastest among formal sector fleet operators.
Battery Type:
Cost trajectories diverge based on energy density requirements and local testing infrastructure availability.
- Lithium-ion:NMC and LFP chemistries dominate pack assembly for their superior cycle life and declining cell prices; Rwanda's swap-station networks standardize around these formats to enable cross-vehicle compatibility. Courier fleets in Kigali specify LFP variants for thermal stability during high-frequency daily cycling.
- Solid-state:Pre-commercial prototypes promise doubled energy density for heavy-duty applications; Kenya's Energy and Petroleum Regulatory Authority has not yet published certification pathways, delaying manufacturer homologation timelines. Long-haul truck electrification depends on this chemistry maturation.
- Lead-acid:Survives only in price-sensitive informal segments with minimal range requirements.
- Nickel-metal Hydride:Legacy hybrid applications retain niche presence but lack scale for pure EV deployment.
Lithium-ion commands installed capacity leadership, though Solid-state carries the steepest expansion trajectory contingent on regulatory clarity.
Charging Infrastructure:
Capital deployment patterns reflect grid reinforcement requirements and utility partnership maturity across urban corridors.
- Fast Charging:DC rapid installations concentrate along Nairobi-Kigali highway corridors where fleet operators require sub-30-minute turnaround; Kenya Power interconnection queues currently extend deployment timelines. Commercial depot operators are bypassing public networks through captive solar-battery buffering systems.
- Swap-station:Battery exchange infrastructure eliminates range anxiety for motorcycle couriers operating fixed urban routes; Ampersand's Kigali-Nairobi network anchors this model to commercial lease agreements. Asset-light energy procurement is displacing plug-in charging for two-wheeler segments.
- Home Charging:Residential installations lag due to prepaid meter limitations and informal settlement electrical access constraints.
- Public Charging:Rwanda's smart metering mandate is retrofitting existing stations with cellular-connected demand response capability.
- Wireless Charging:Inductive pad trials remain pilot-scale with no commercial deployment.
Swap-station networks are expanding most quickly in East African urban corridors, while Fast Charging retains capex concentration among utility-affiliated operators.
Customer Segment:
Purchasing authority is consolidating among entities capable of negotiating volume-based energy pricing and centralized maintenance contracts.
- Fleet Operators:Bulk procurement, predictable routes, and captive charging infrastructure compress payback periods below individual ownership economics; logistics companies in Lagos and Nairobi are specifying modular battery platforms to unbundle vehicle from energy asset ownership. Procurement committees demand standardized swap-station access across multi-city operating territories.
- Ride-sharing Services:Platform drivers prioritize total cost per kilometer over upfront acquisition; Spiro's pay-as-you-go battery subscriptions reduce capital barriers in Dar es Salaam and Lagos informal transport markets. Daily revenue share models align payment capacity with utilization intensity.
- Individual Consumers:Financing access constraints limit penetration to salaried professionals in formal employment.
- Government Agencies:Public procurement mandates drive pilot deployments but volume remains constrained by budget cycles.
Fleet Operators retain the dominant procurement volume position, while Ride-sharing Services are gaining share fastest through subscription-based asset access models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kenya's fiscal exemption framework for electric vehicle components is compressing total cost of ownership and accelerating procurement decisions across East African urban corridors connecting Nairobi, Mombasa, and Kisumu.
Kenya
Corporate fleet managers in Nairobi prioritize sedan configurations for multi-year service contracts with banking and telecom sectors. Kenya's Energy and Petroleum Regulatory Authority enforces battery safety standards that extend certification timelines for local assemblers. The Nairobi-Mombasa corridor anchors swap-station deployment for courier fleets operating high-frequency daily routes.
Rwanda
Ampersand's battery exchange network in Kigali eliminates range anxiety for commercial motorcycle operators on predictable urban routes. Rwanda's Utilities Regulatory Authority mandates smart metering integration for all public charging stations to enable time-of-use tariffs. Commercial depots in Kigali consolidate charging windows to off-peak periods, altering daily vehicle utilization patterns.
South Africa
The National Regulator for Compulsory Specifications enforces divergent safety standards that raise compliance costs for new entrants while protecting local assemblers. Cape Town and Johannesburg clusters concentrate charging infrastructure investments among utility-affiliated operators. Fleet operators in Gauteng retain hybrid vehicle exposure to manage diesel cost volatility.
Nigeria
Ride-hailing drivers in Lagos prioritize pay-as-you-go battery subscriptions that reduce upfront acquisition barriers in informal transport markets. The country's national energy regulator faces interconnection backlogs for commercial charging station grid connections. Lagos-Ibadan corridor logistics companies specify modular battery platforms to unbundle vehicle from energy asset ownership.
Tanzania
Platform drivers in Dar es Salaam adopt daily revenue share models that align payment capacity with utilization intensity. The country's utilities regulatory framework remains less developed than Kenya or Rwanda, delaying standardized certification pathways. Peri-urban zones outside Dar es Salaam experience delayed station deployment due to grid reinforcement requirements.
Africa Electric Vehicle Market Competitive Environment
Player mix skews toward integrated battery-cell-to-vehicle manufacturers and asset-light energy service providers. Market structure concentrates procurement influence among large fleet aggregators who negotiate volume-based energy pricing with swap-station operators. Two strategic archetypes dominate: integrated manufacturers with captive battery supply and subscription-based leasing providers transferring cell degradation risk to specialized asset managers. Competitive moves center on backward integration into lithium-ion cell production and geographic expansion along Nairobi-Kigali-Lagos corridors.
Within the integrated manufacturing tier, BYD Co. Ltd. and Nissan Motor Co., Ltd. occupy positions that exemplify scale-driven cost compression through in-house battery production. Among East Africa-focused energy service providers, Ampersand and Spiro represent the asset-light archetype unbundling vehicle chassis from battery pack ownership. Tesla Inc. sits within the premium-tier vector targeting corporate fleet segments with higher performance specifications. Hyundai Motor Co. and Volkswagen AG anchor the diversified automotive group tier leveraging existing distribution networks for market entry.
| Leading Market Players |
|---|
| Nissan Motor Co., Ltd. |
| Ampersand |
| BYD Co. Ltd. |
| Roam Electric |
| BasiGo |
| Tesla Inc. |
| Hyundai Motor Co. |
| Spiro |
| Volkswagen AG |
| Others |
Value Chain & Pricing Dynamics
Take-or-pay battery supply contracts between East African fleet operators and Chinese cell manufacturers lock in both cathode material access and landed cost predictability across multi-year procurement cycles. Kenya's VAT exemption on EV components compresses import duty exposure for assemblers negotiating these offtake structures.
Pricing Analysis
Certification level under UN ECE R100 creates the primary spread between premium-tier integrated manufacturers and local assemblers facing extended testing timelines. Subscription-based battery-as-a-service models dominate commercial two-wheeler segments, while hatchback configurations attract price-sensitive individual buyers through Kenya's component duty waivers. Cost compression in entry-level segments is intensifying as BYD's captive cell production undercuts landed costs for African distributors. Fleet operators exhibit the lowest price sensitivity due to volume-based energy pricing negotiations, whereas informal ride-hailing drivers in Lagos face acute upfront acquisition constraints.
Supply Chain Analysis
China and South Korea anchor lithium-ion cell production feeding East African pack assembly operations. Kenyan and Rwandan vehicle assemblers draw from imported NMC and LFP cells, with silicon carbide power electronics sourced from Taiwanese foundries. Single-source vulnerability concentrates in cathode active material supply chains controlled by Chinese refiners. Distribution runs through Nairobi and Kigali logistics hubs serving fleet depots and swap-station networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where UN ECE R100 certification complexity filters out competitors lacking testing infrastructure relationships.
For Market Incumbents: Shield market position by deepening backward integration into lithium-ion cell production to neutralize BYD's landed cost advantage. Prioritize certification investment in Kenya's Energy and Petroleum Regulatory Authority testing pathways to extend compliance timelines for emerging assemblers. For New Entrants and Emerging Players: UN ECE R100 fast-track partnerships with Rwandan testing facilities open white-space access in Kigali's courier fleet segment. Target Dar es Salaam's ride-hailing market through pay-as-you-go battery subscriptions that bypass upfront capital barriers. Deploy asset-light leasing models unbundling chassis from energy procurement. For Investors and Strategic Acquirers: Swap-station network operators with established utility interconnection relationships represent the highest-conviction acquisition archetype. Monitor Rwanda Utilities Regulatory Authority harmonization initiatives as the inflection signal for cross-border certification scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cathode material offtakes with Chinese refiners secure cell cost predictability for Kenyan assemblers. |
| Charging Infrastructure Partnership | Utility-affiliated interconnection agreements in Nairobi bypass Kenya Power queue backlogs for fleet depots. |
| Platform Standardization | Modular battery formats across two-wheeler fleets enable cross-vehicle swap-station compatibility in Kigali. |
| Geographic Manufacturing Footprint | Local assembly operations in Mombasa exploit Kenya's import duty exemptions on EV components. |
| Software-Defined Vehicle Investment | Cellular-connected energy management systems meet Rwanda's smart metering mandate for demand response. |
Study Parameters
Operator-level perspectives from fleet procurement managers, swap-station network engineers, utility interconnection officers, and regulatory compliance leads anchored the qualitative base. Primary interviews triangulated against secondary sources including Kenya Energy and Petroleum Regulatory Authority filings, Rwanda Utilities Regulatory Authority tariff orders, UN ECE homologation databases, and East African Community trade statistics. Bottom-up vehicle deployment estimates and top-down market sizing converged through cross-validation.
Sensitivity analysis tested forecast robustness across lithium price volatility scenarios and duty exemption policy continuity assumptions throughout the projection horizon. Segmentation dimensions modeled include vehicle configuration, battery chemistry, charging infrastructure type, and customer procurement authority. CAGRs derived from deployment trajectory analysis incorporating fleet operator conversion timelines and utility partnership maturation curves.
Underlying assumptions cover regulatory harmonization progress and cathode material cost curves, with deviation risk concentrated in petroleum price volatility hedging behavior and interconnection queue durations. Recalibration cycles align with material shifts in EAC standardization initiatives and cell chemistry commercialization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
China Electric Truck Market
Electric Vehicles
Electric Vehicle (EV) Ball Bearings Market
Electric Vehicles
North America Wireless Electric Vehicle Charging Market
Electric Vehicles
Recreational Vehicle (RV) Batteries Market
Electric Vehicles
Vietnam E-Bike Market
Electric Vehicles
US Electric Mobility Market
Electric Vehicles
Electric Vehicle (EV) Coating Market
Electric Vehicles
Vehicle Battery Market
Electric Vehicles
Oman EV Market
Electric Vehicles
One Wheel Electric Scooter Market
Electric Vehicles
Agricultural Electric Vehicles Market
Electric Vehicles
North America Electric Vehicle Thermal Management System Market
Electric Vehicles
US Automotive High Performance Electric Vehicle Market
Electric Vehicles
Electric Vehicle Heating System Market
Electric Vehicles
India Electric Vehicle Market
Electric Vehicles
Europe Automotive High Performance Electric Vehicle Market