
 Electric Two Wheelers MRO Market | 2026-2036
Electric Two Wheelers MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Two Wheelers MRO Market Foresight
Fleet operator procurement is consolidating across metropolitan last-mile delivery networks, concentrating aftermarket service contracts among fewer high-volume buyers. Ather Energy leverages its proprietary charging infrastructure to lock in recurring maintenance revenue streams. Hero MotoCorp anchors its MRO positioning through India's dense rural service network, while Gogoro differentiates via its battery-swapping architecture that shifts service economics from component replacement to subscription-based uptime guarantees.
Electric Two Wheelers MRO encompasses the technical servicing, component replacement, and system refurbishment of electric motorcycles and scooters, requiring specialized handling of lithium-ion battery packs, brushless DC motors, and CAN-bus electronic controllers operating at 48V–72V. The primary commercial purpose centers on extending vehicle operational life while ensuring battery thermal stability and regenerative braking efficiency across high-cycle urban use. Battery services command the dominant margin pool within the Component dimension due to cell degradation diagnostics and second-life repurposing workflows. Fleet Operators represent the fastest-growing End User category, driven by electrification mandates across logistics and ride-hailing platforms that demand predictive maintenance to minimize downtime.
India's CEA battery safety standards and China's GB/T electric motorcycle technical specifications shape product compliance requirements and aftermarket part interchangeability across Asia's largest volume markets. The EU's F-Gas Regulation and REACH chemical restrictions additionally govern coolant and lubricant formulations used in thermal management systems, raising service protocol complexity for European-imported vehicles. Stakeholders must monitor how battery passport traceability requirements under emerging circular-economy frameworks will restructure spare parts authentication and technician certification pathways.
Market Dynamics
Fleet operator consolidation across last-mile delivery networks is compressing service contract structures toward predictive uptime models and away from transactional part replacement economics.
Growth Catalysts
- India's PLI scheme for advanced chemistry cells:Domestic battery manufacturing incentives are shortening component lead times and reducing import dependency for MRO providers servicing the country's expanding electric two-wheeler parc.
- Battery-as-a-service commercial models:Subscription-based ownership structures separate hardware from energy costs, generating recurring diagnostic and swap-station maintenance revenue streams for specialized service networks.
- Lithium-ion thermal runaway protocols:CEA battery safety standards mandate specialized handling infrastructure, creating certified service network requirements that advantage established MRO operators over informal mechanics.
Market Restraints
- Cobalt and lithium price volatility:Raw material cost swings in cell chemistry inputs compress margins on battery pack refurbishment services, forcing hedging strategies or pass-through pricing that fleet buyers resist.
- Controller firmware fragmentation:Proprietary CAN-bus architectures across OEM lineups prevent standardized diagnostic tool deployment, raising technician training costs and inventory complexity for multi-brand service centers.
- REACH chemical restrictions:EU coolant and lubricant formulation compliance adds procurement overhead for thermal management system servicing, disadvantaging smaller independent workshops against franchised networks.
Strategic Opportunities
- Second-life battery repurposing:Stationary energy storage applications for degraded electric two-wheeler packs create refurbishment revenue streams and circular-economy compliance pathways under emerging battery passport frameworks.
- Swap-station infrastructure densification:Urban last-mile corridors in China's eastern manufacturing belt offer concentrated service demand for battery logistics and rapid-exchange maintenance contracts.
- ISO 26262 functional safety certification:Growing motor controller complexity creates technician credentialing service opportunities for training providers targeting fleet maintenance departments.
Industry Challenges
- High-voltage safety technician scarcity:48V–72V system handling requires specialized certification pathways that outpace vocational training program throughput in high-volume markets.
- Multi-OEM diagnostic tool fragmentation:Proprietary software interfaces force service centers to maintain redundant equipment inventories, compressing capital efficiency and technician productivity metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Two Wheelers MRO Market |
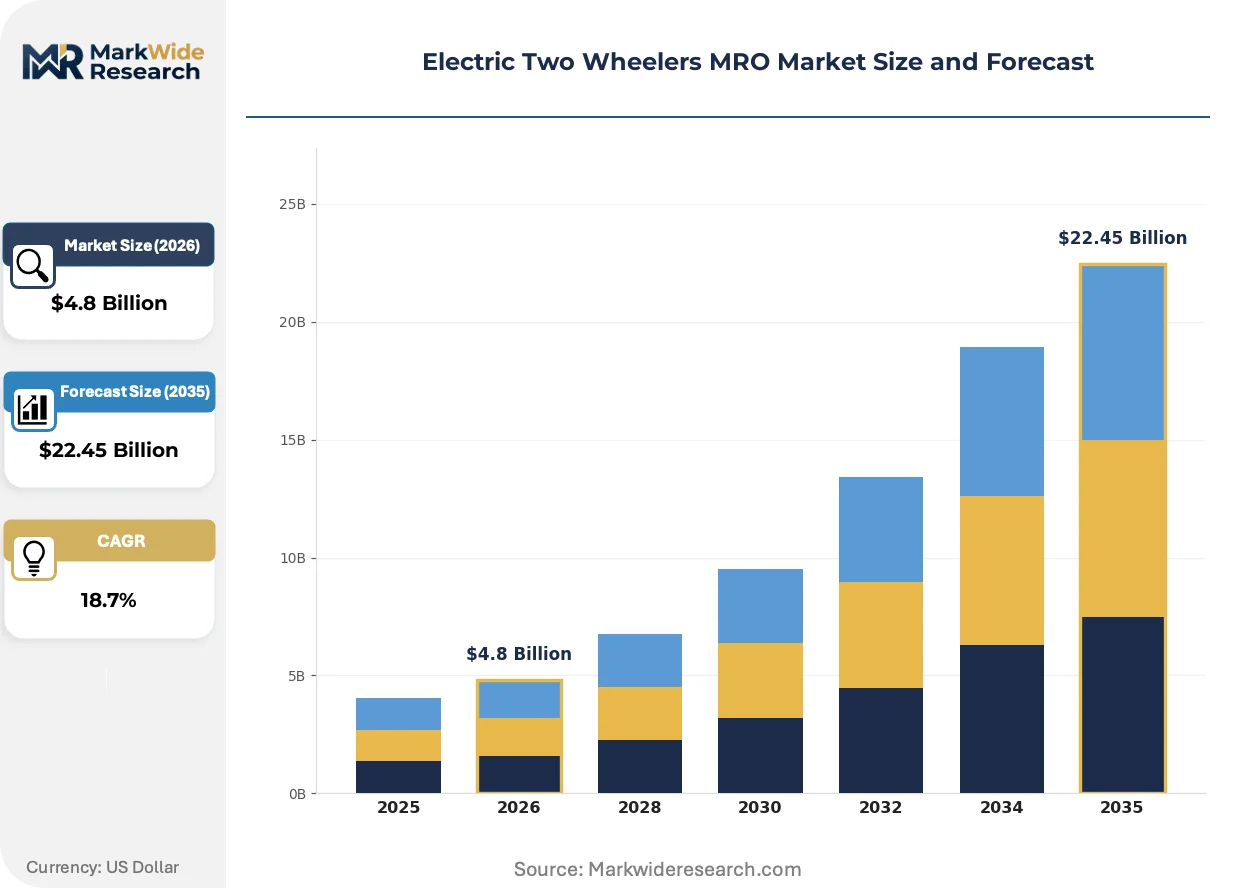
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Repair, Overhaul, Refurbishment Component: Battery, Motor, Electronic Controller, Chassis End User: Personal Users, Fleet Operators, Delivery Services, Government Entities Usage Type: Lightweight, Heavy-Duty, Commuter, Off-Road |
| Companies Covered | Ather Energy, Yadea, Hero MotoCorp, Yamaha Motor Company, Gogoro, Bajaj Auto, Ola Electric, Niu Technologies, TVS Motor Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Two Wheelers MRO Market Shifts & Advancements
Diagnostic automation and connected vehicle architectures are compressing maintenance response cycles while shifting value capture from component sales to data-enabled predictive interventions.
Artificial intelligence-driven cell degradation prediction is converging with telematics platforms to enable preemptive battery pack replacement scheduling. Fleet operators in high-rotation logistics applications are adopting these systems fastest, with urban delivery networks leading deployment. This convergence is compressing unplanned downtime incidents while transferring diagnostic value from physical inspection to algorithmic monitoring subscriptions.
China's GB/T electric motorcycle technical specifications are harmonizing connector and communication protocols across domestic manufacturers. The standardization reduces spare part SKU proliferation for service networks operating multi-brand fleets. Aftermarket providers in the Shenzhen-Dongguan corridor are consolidating procurement around these unified interfaces, simplifying inventory management for high-volume maintenance operations.
Subscription-based service bundling is displacing transactional part-and-labor billing across commercial fleet accounts. Full-cost maintenance contracts covering batteries, motors, and controllers are penetrating last-mile delivery and ride-hailing verticals first. This model concentrates most visibly in Indian metropolitan markets where fleet electrification mandates accelerate total-cost-of-ownership transparency requirements.
Electric Two Wheelers MRO Market Segmentation
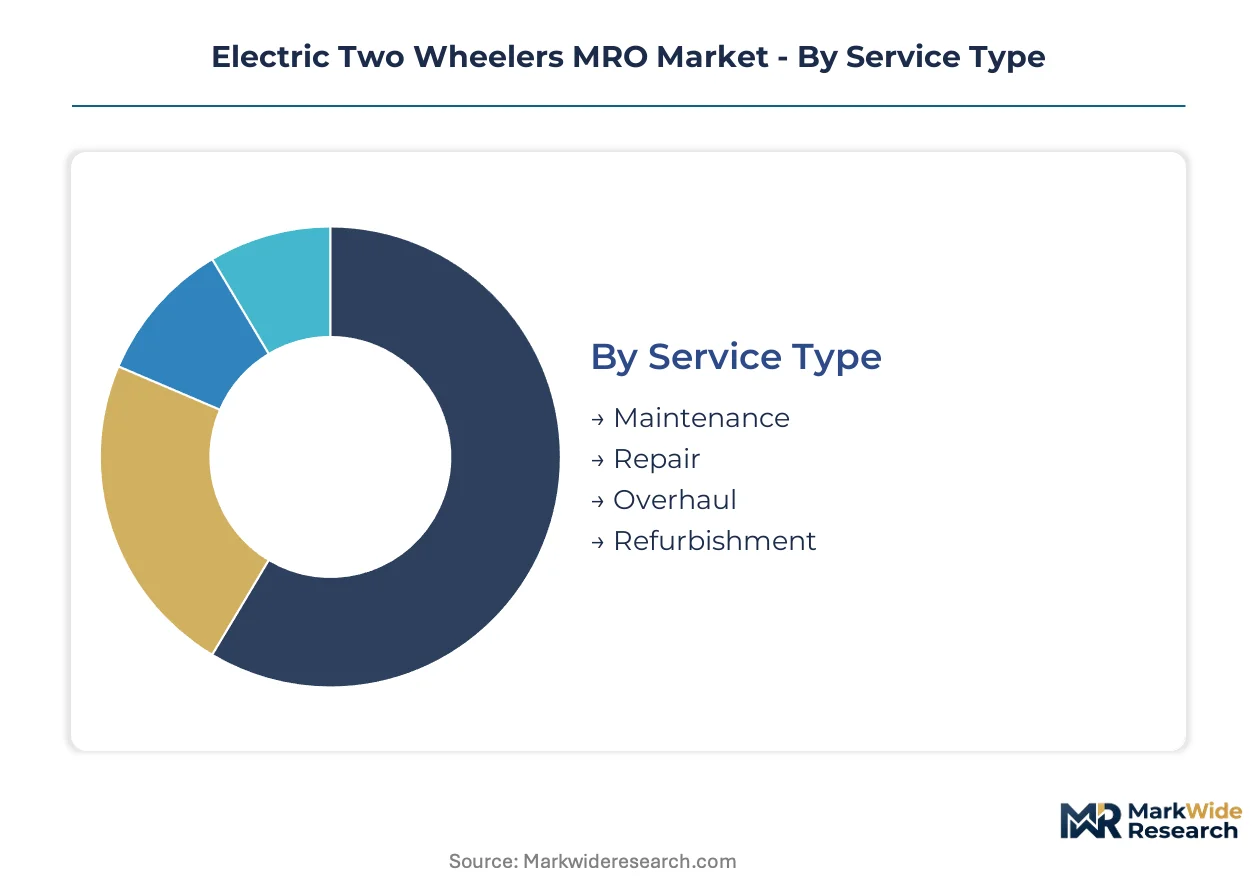
Service differentiation across electric two-wheeler MRO hinges on voltage architecture specialization and thermal management protocols. Segmentation reveals where margin pools concentrate and which customer contracts warrant dedicated infrastructure investment.
Service Type:
Procurement patterns diverge sharply between reactive break-fix engagements and contracted lifecycle management.
- Maintenance:Scheduled preventive protocols address brake pad wear, tire pressure monitoring, and thermal management system calibration at 48V–72V. Fleet operators in China's Shenzhen-Dongguan corridor consolidate these contracts around swap-station uptime guarantees, locking in recurring revenue streams.
- Repair:Unplanned interventions target CAN-bus diagnostic faults, motor controller failures, and collision damage. India's CEA battery safety standards mandate certified handling infrastructure, restricting this work to authorized networks and compressing informal mechanic participation.
- Overhaul:Systematic component replacement extends vehicle operational life.
- Refurbishment:Second-life battery repurposing for stationary storage applications.
Maintenance leads volumes today; refurbishment is gaining share fastest.
Component:
Margin concentration tracks replacement frequency and technical certification barriers.
- Battery:Lithium-ion pack diagnostics, cell balancing, and thermal runaway prevention dominate service economics. Degradation prediction algorithms enable preemptive replacement scheduling, with fleet operators adopting these systems fastest in high-rotation logistics applications.
- Motor:Brushless DC unit rewinding, bearing replacement, and efficiency testing. China's GB/T harmonization of connector protocols reduces spare part SKU proliferation for multi-brand service networks.
- Electronic Controller:Firmware updates and CAN-bus architecture troubleshooting face proprietary interface fragmentation.
- Chassis:Structural integrity assessment and suspension component replacement carry lower technical barriers.
Battery services command the dominant margin pool; controller work is expanding most quickly.
End User:
Contract structures and uptime sensitivity separate commercial from consumer demand profiles.
- Fleet Operators:Last-mile delivery and ride-hailing platforms demand predictive maintenance to minimize downtime. Subscription-based service bundling displaces transactional billing across Indian metropolitan markets where electrification mandates accelerate.
- Personal Users:Individual owners prioritize cost minimization over uptime guarantees, concentrating demand at informal service points.
- Delivery Services:High-cycle urban use patterns accelerate wear rates and compress replacement intervals.
- Government Entities:Municipal procurement emphasizes compliance documentation and certified technician chains.
Fleet operators anchor commercial revenue; delivery services show the steepest expansion trajectory.
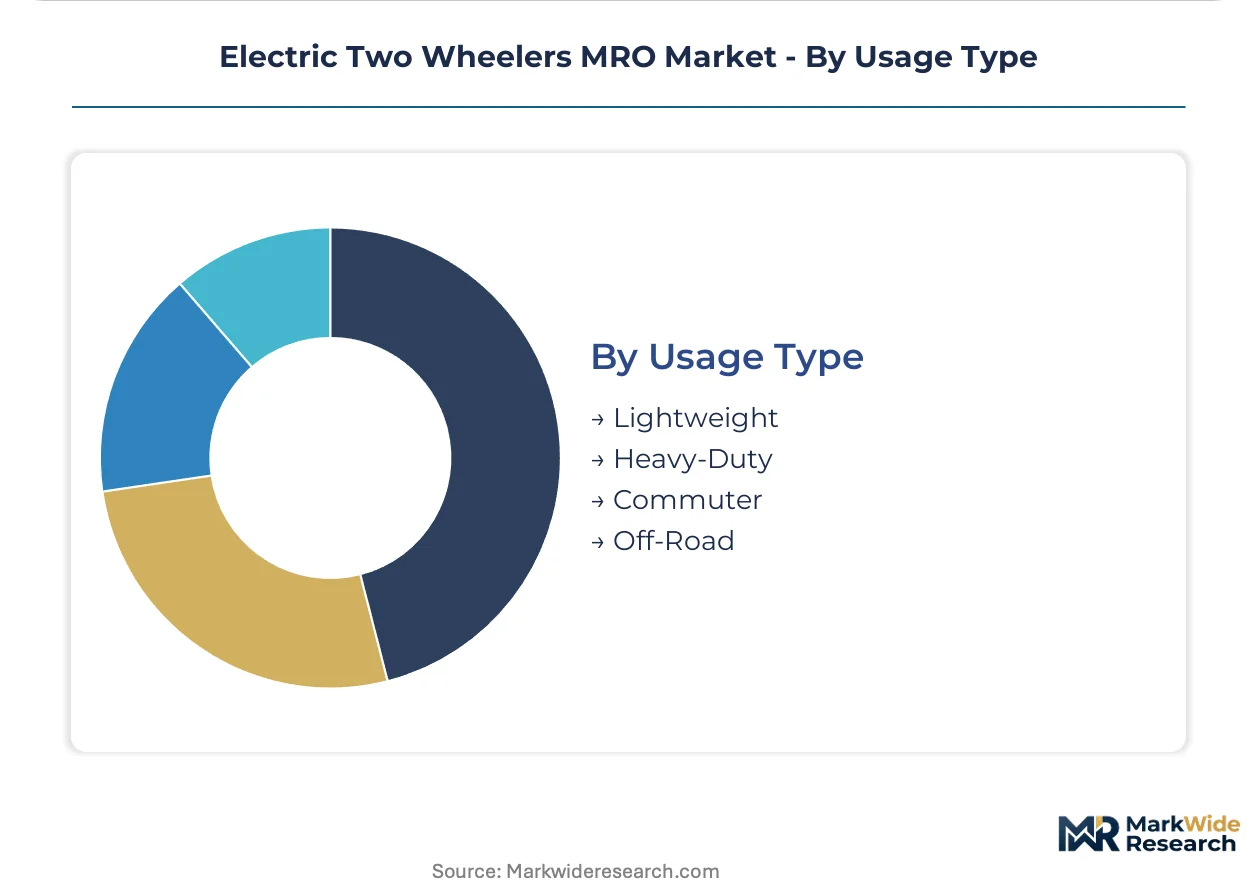
Usage Type:
Powertrain stress profiles and environmental exposure determine service protocol intensity.
- Commuter:Moderate daily mileage with predictable duty cycles. India's dense urban corridors generate concentrated demand for rapid-turnaround maintenance at high-frequency touchpoints.
- Heavy-Duty:Sustained high-load operation accelerates motor thermal degradation and battery cell imbalance.
- Lightweight:Lower power draw reduces component stress but increases crash damage frequency.
- Off-Road:Suspension and chassis impacts dominate service requirements.
Commuter vehicles drive current service volumes; heavy-duty applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor generates denser service network clustering than India's emerging metropolitan hubs, though both markets concentrate procurement around battery-centric maintenance protocols.
China
Fleet electrification across logistics platforms and ride-hailing networks sustains aftermarket demand in the Yangtze River Delta and Pearl River Delta. GB/T electric motorcycle technical specifications harmonize connector protocols, reducing spare part SKU proliferation. Shenzhen and Dongguan anchor multi-brand service operations where swap-station infrastructure densifies fastest.
India
Last-mile delivery mandates in Mumbai, Delhi-NCR, and Bangalore compress replacement intervals for high-cycle commercial vehicles. The PLI scheme for advanced chemistry cells redirects component sourcing toward domestic supply chains. Hero MotoCorp leverages rural service density while Ather Energy locks recurring revenue through proprietary charging infrastructure.
Germany
REACH chemical restrictions and F-Gas Regulation govern coolant formulations in thermal management systems, raising protocol complexity for service centers. KBA certification requirements structure technician credentialing pathways. Bavaria and Baden-Württemberg concentrate premium-tier maintenance contracts for high-performance electric motorcycles.
United States
NHTSA safety standards and state-level zero-emission vehicle mandates accelerate fleet electrification in California and New York Metro corridors. EPA regulations influence battery recycling and second-life repurposing workflows. Los Angeles and San Francisco Bay Area logistics networks drive predictive maintenance adoption among commercial operators.
Japan
METI energy transition targets and JIS standards shape battery handling certification requirements for high-voltage systems. Kanto and Kansai regions concentrate urban commuter service demand. Tokyo and Osaka metropolitan areas host specialized networks addressing brushless DC motor efficiency testing and CAN-bus diagnostic protocols.
Electric Two Wheelers MRO Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the Electric Two Wheelers MRO landscape, creating tiered competitive dynamics. The vendor base spans established two-wheeler manufacturers extending service networks, battery technology firms capturing recurring diagnostics revenue, and infrastructure operators monetizing swap-station uptime. Three archetypes dominate: integrated OEM service networks, independent multi-brand maintenance chains, and battery-as-a-service platform operators. Capacity expansion in certified high-voltage handling infrastructure and strategic partnerships around second-life battery repurposing represent the primary competitive vectors.
Among India-based specialists, Ather Energy and Hero MotoCorp exemplify contrasting network strategies, while Gogoro occupies a position within the battery-swapping platform tier. Ather Energy represents the proprietary infrastructure archetype through integrated charging and maintenance ecosystems. Hero MotoCorp anchors the rural penetration model leveraging dense service reach. Gogoro exemplifies subscription-based uptime economics that shift value capture from component replacement to energy access guarantees.
| Leading Market Players |
|---|
| Ather Energy |
| Yadea |
| Hero MotoCorp |
| Yamaha Motor Company |
| Gogoro |
| Bajaj Auto |
| Ola Electric |
| Niu Technologies |
| TVS Motor Company |
| Others |
Supply & Pricing Matrix
Fleet operator procurement consolidation across Indian last-mile delivery networks anchors pricing power in subscription-based uptime guarantees rather than transactional part replacement. This buyer concentration compresses margins for independent workshops while franchised networks capture recurring revenue through certified high-voltage handling contracts.
Pricing Analysis
Capacity additions in China's eastern manufacturing corridor are reshaping price floors for lithium-ion battery pack refurbishment services. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and volume commitment, with ISO 26262 functional safety credentials commanding material premiums. Cost compression in the economy tier is intensifying because cobalt and lithium price volatility forces hedging strategies that smaller operators cannot sustain. Fleet buyers exhibit the lowest price sensitivity due to electrification mandate compliance deadlines, while personal users concentrate demand at informal service points where cost minimization dominates.
Supply Chain Analysis
India's PLI scheme for advanced chemistry cells is redirecting component sourcing toward domestic battery manufacturing clusters in Gujarat and Tamil Nadu. Supply chains draw from China, South Korea, and Japan for lithium carbonate, electrolyte formulations, and separator membranes. Single-source vulnerability concentrates in proprietary CAN-bus controller firmware where OEM lock-in prevents standardized procurement. Distribution runs through authorized service networks for high-voltage battery work, while chassis and motor components flow via traditional aftermarket wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's CEA battery safety standards function as a regulatory compounder by mandating certified handling infrastructure that eliminates informal mechanic participation and concentrates demand among authorized networks.
For Market Incumbents: Anchor market position through backward integration into second-life battery repurposing capabilities that satisfy emerging circular-economy compliance requirements. Invest in ISO 26262 technician credentialing programs to defend against battery-as-a-service platform operators capturing diagnostic revenue streams. Expand swap-station infrastructure density in China's Shenzhen-Dongguan corridor where fleet operator consolidation creates captive demand. For New Entrants and Emerging Players: Begin with heavy-duty commuter fleet maintenance contracts in Indian metropolitan markets where electrification mandates accelerate total-cost-of-ownership transparency requirements. Target government entity procurement verticals that emphasize compliance documentation and certified technician chains over price minimization. Deploy predictive maintenance software subscriptions as the primary go-to-market angle to bypass capital-intensive physical infrastructure requirements. For Investors and Strategic Acquirers: Battery-as-a-service platform operators are the most active acquirer in this space, seeking diagnostic software capabilities and certified high-voltage handling networks. Long-term viability hinges on circular-economy regulatory maturation that transforms battery passport traceability from compliance cost into competitive moat. Watch for CEA standard enforcement intensity as the inflection indicator separating authorized network expansion from informal mechanic market share recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Swap-Station Infrastructure Densification | Captures recurring battery logistics revenue in China's eastern manufacturing corridor where fleet uptime guarantees concentrate demand. |
| Second-Life Battery Repurposing | Creates refurbishment revenue streams under India's PLI scheme while satisfying CEA circular-economy compliance pathways. |
| ISO 26262 Functional Safety Certification | Differentiates service networks as motor controller complexity outpaces vocational training program throughput. |
| Predictive Maintenance Platform Integration | Shifts value capture from physical inspection to algorithmic monitoring subscriptions for high-rotation logistics fleets. |
| Domestic Supply Chain Localization | Shortens component lead times under India's advanced chemistry cell incentives while reducing import dependency exposure. |
Research Methodology
Coverage spans China, India, Germany, the United States, and Japan, with primary inputs from each market informing demand calibration. The research combines structured interviews with fleet operations directors, aftermarket service network managers, battery technology procurement leads, and high-voltage safety training providers with secondary validation against GB/T technical specifications, CEA safety standards, REACH chemical restrictions, and NHTSA safety standards. Trade flow databases, OEM service network disclosures, and circular-economy regulatory filings supplement primary intelligence. Bottom-up service revenue estimates triangulate against top-down vehicle parc projections.
Granularity extends to voltage architecture specialization, thermal management protocol intensity, and end-user contract structure across the projection horizon. Segmentation dimensions include service type, component category, end-user archetype, and usage intensity profile. CAGRs derive from logistic curve adoption modeling applied to fleet electrification mandate timelines and battery degradation replacement cycles. Forecast inputs incorporate lithium-ion cell chemistry cost trajectories and swap-station infrastructure deployment schedules without year-specific anchoring.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments, abrupt raw material supply disruptions, and OEM vertical integration into captive service networks. Forecasts reflect documented assumptions regarding technician certification program expansion rates and battery passport implementation timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
France Automotive High Performance Electric Vehicles Market
Electric Vehicles
Japan Electric Car Market
Electric Vehicles
Electric Tuk-Tuks Market
Electric Vehicles
Global Electric Classic Car Market
Electric Vehicles
NGO Steel in Electric Vehicle Market
Electric Vehicles
Europe Electric Scooter Market
Electric Vehicles
Electric Vehicle Regenerative Braking System Market
Electric Vehicles
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market
Electric Vehicles
Europe Fuel Cell Electric Vehicle Market
Electric Vehicles
Europe Electric Vehicle Market
Electric Vehicles
Battery-Swapping for Electric Two-Wheeler Market
Electric Vehicles
United Kingdom Hybrid Electric Vehicle Battery Market
Electric Vehicles
Fuel-Cell Electric Vehicle Insulation Market
Electric Vehicles
EV Thermal System Market
Electric Vehicles
Electric Vehicle Skateboard Chassis Market
Electric Vehicles
Car Battery Chargers Market