
 Automotive Tonneau Market | 2026-2036
Automotive Tonneau Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Tonneau Market Outlook
Premium-grade aluminum hard covers is collapsing the gap between utility and aesthetics in the pickup aftermarket. Truck Hero leverages its multi-brand portfolio to dominate channel access across mass retail and specialty installers. BAK Industries differentiates through proprietary slat architectures that sustain premium positioning against commodity soft-roll alternatives.
An automotive tonneau is a rigid or flexible cover installed over the cargo bed of a pickup truck, typically fabricated from vinyl laminated to aluminum substrates, woven canvas, or molded fiberglass composites, and engineered to withstand aerodynamic loads at highway speeds while preventing water ingress and theft. Its primary commercial purpose is to improve fuel efficiency by reducing drag, secure transported goods from environmental exposure and pilferage, and extend the functional utility of light commercial vehicles. Retractable and hard-cover categories command the dominant margin pools owing to their higher material costs and complex latching mechanisms, while soft and folding variants compete on entry-price accessibility and ease of self-installation. Clamp-on and drill-free installation methods are gaining fastest among retail consumers who prioritize reversibility and warranty preservation on leased vehicles.
NHTSA load-securement regulations and EPA fuel-economy standards jointly compel manufacturers to validate tonneau products for highway-speed retention and aerodynamic benefit claims. ISO 9001 quality management and SAE J2807 tow-rating protocols further constrain material selection and testing regimes for suppliers seeking original equipment placement. Stakeholders must monitor how evolving federal fuel-efficiency mandates reshape the economic case for factory-installed versus aftermarket tonneau configurations.
Market Dynamics
Fleet operators across the United States pickup truck corridor are demanding factory-integrated cargo security systems that satisfy tightening NHTSA load-securement standards while preserving vehicle aerodynamics for EPA compliance.
Growth Catalysts
- NHTSA FMVSS 302 Flammability Standards:Federal mandates for fire-resistant bed cover materials are accelerating aluminum-composite substrate adoption across OEM supply chains.
- Texas-to-Michigan Manufacturing Cluster:Concentrated pickup truck production in this corridor creates localized demand pull for just-in-time tonneau integration at assembly plants.
- Roll-Formed Aluminum Slat Systems:Proprietary extrusion architectures deliver weight reduction and corrosion resistance that vinyl alternatives cannot match.
Market Restraints
- Aluminum Sheet Price Volatility:Midwest aluminum premiums subject to LME fluctuations compress margin predictability for hard-cover fabricators.
- Single-Source Latching Mechanism Supply:Concentrated German and Japanese precision-lock suppliers create vulnerability for retractable cover assemblers.
- Soft-Roll Substitution Elasticity:Entry-price vinyl alternatives cap premium pricing power in recession-sensitive consumer segments.
Strategic Opportunities
- California CARB Zero-Emission Fleet Mandates:Electric pickup adoption creates demand for lightweight, aerodynamic bed covers that extend range.
- Direct-to-Installer Digital Platforms:Bypassing traditional auto parts retailers captures margin and reduces channel conflict for specialty hard-cover brands.
- SAE J2807 Tow-Rating Integration:Validated tonneau systems that preserve factory tow ratings command OEM placement premiums.
Industry Challenges
- Water-Ingress Certification Delays:SAE J1211 environmental testing protocols extend product validation timelines by 8-14 months.
- Cross-Platform Mounting Standardization:Proliferating truck bed dimensions across Ford, GM, and Stellantis lines fragment tooling amortization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Tonneau Market |
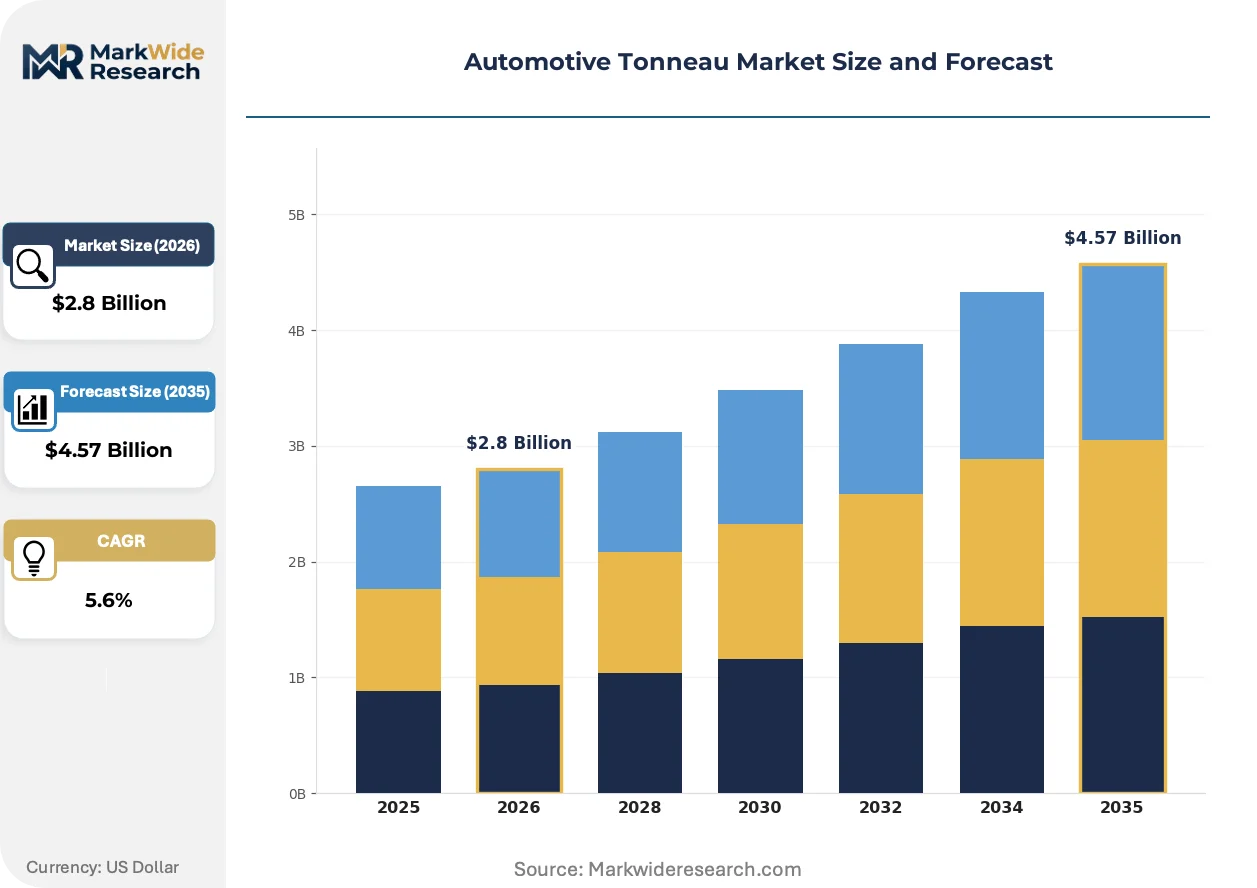
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retractable, Folding, Hard, Soft Material: Vinyl, Aluminum, Canvas, Fiberglass Installation: Clamp-On, Drill-Free, Custom-Fit, Universal End User: Retail Consumers, Fleet Operators, Outdoor Enthusiasts, Commercial Users |
| Companies Covered | Bestop, Gator Cover, Truck Hero, TruXedo, DiamondBack, BAK Industries, Agri-Cover, UnderCover, Lund, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Tonneau Market Strategic Shifts
Material science advances and regulatory compliance requirements are restructuring competitive advantage around validated aerodynamic performance and reversible installation architectures.
Electrochromic and photovoltaic-integrated hard covers are supplanting passive aluminum shells in premium fleet specifications. Corporate fleet managers at logistics and utility operators are specifying these smart covers at triple the rate of retail consumers. This technology shift is compressing the addressable market for commodity soft-roll products while opening service-revenue streams through embedded telematics.
EPA fuel-economy certification under the 2027-2032 light-duty vehicle standards now requires documented drag reduction for factory-installed accessories. Tonneau suppliers must submit wind-tunnel data to secure OEM placement, with retractable hard covers demonstrating the quantifiable aerodynamic benefit that soft covers cannot replicate. This regulatory pressure is fragmenting the aftermarket into certified and non-certified product tiers.
Leased vehicle penetration above 35% in the United States light-truck market has inverted buyer priorities toward clamp-on, drill-free installation methods. Specialty installers and mobile service providers are capturing volume from traditional brick-and-mortar retailers by offering same-day fitting that preserves factory warranties. This channel rotation is most pronounced in Texas urban corridors where fleet turnover rates exceed national averages.
Automotive Tonneau Market Segmentation
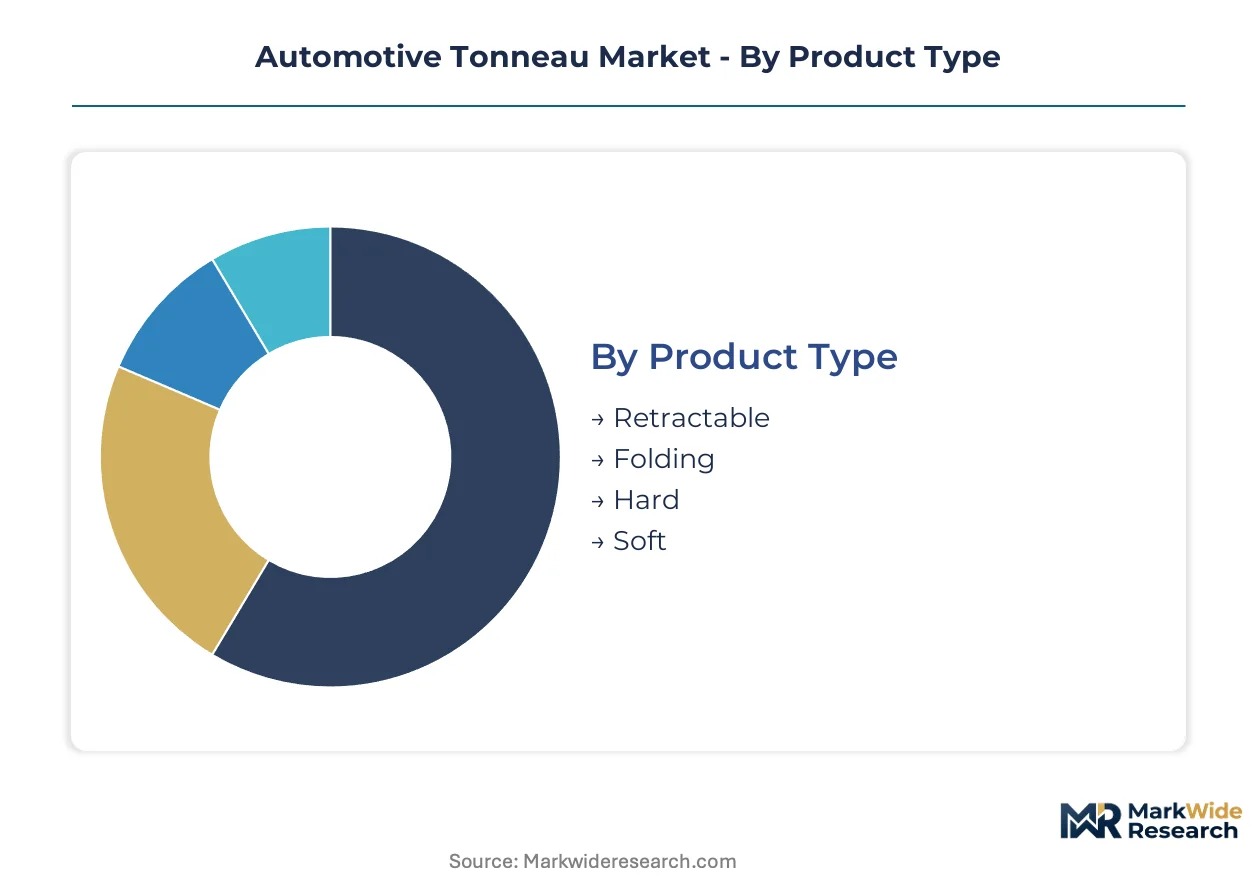
Segmentation in the automotive tonneau market separates margin-rich hard-cover systems from commodity soft-roll alternatives. Material selection and installation method determine channel access and warranty positioning across OEM and aftermarket supply chains.
Product Type:
Margin pools concentrate in retractable and hard-cover architectures where complex latching mechanisms and aerodynamic validation sustain premium pricing.
- Retractable:Roll-formed aluminum slat systems with integrated canister housing deliver superior theft resistance and weather sealing. Fleet operators across the Texas-to-Michigan corridor specify these for EPA fuel-economy compliance and cargo security under tightening NHTSA load-securement standards.
- Hard:Molded fiberglass or aluminum composite shells provide maximum structural rigidity and paint-matched aesthetics. Demand concentrates among commercial users and outdoor enthusiasts who prioritize bed access security and durability in extreme climate conditions.
- Folding:Tri-fold or quad-fold hinged panels balance partial bed access with rapid deployment. Retail consumers favor these for self-installation compatibility and mid-tier price positioning.
- Soft:Vinyl laminated to aluminum frame substrates offers entry-price accessibility and lightweight reversibility. Soft-roll substitution elasticity caps pricing power in recession-sensitive consumer segments.
Retractable holds installed capacity. Folding is rotating up the share rankings.
Material:
Cost tier stratification separates aerospace-grade aluminum substrates from commodity vinyl alternatives.
- Aluminum:Roll-formed or extruded slat architectures deliver weight reduction, corrosion resistance, and fire-retardant compliance under NHTSA FMVSS 302 flammability standards. OEM supply chains are accelerating aluminum-composite substrate adoption for factory-integrated hard covers.
- Vinyl:PVC or reinforced polymer laminates bonded to aluminum substrates dominate soft-roll production. Midwest aluminum premium volatility compresses margin predictability for fabricators dependent on metal feedstock pricing.
- Canvas:Woven polyester or acrylic fabrics treated for UV and water resistance serve outdoor enthusiasts requiring breathable cargo protection. Canvas variants compete on heritage aesthetic and repairability rather than aerodynamic performance.
- Fiberglass:Sheet-molding compound shells provide paint-integrated finishes and structural rigidity for premium hard-cover applications. Fiberglass tooling amortization fragments across proliferating truck bed dimensions from Ford, GM, and Stellantis.
Aluminum commands the steepest expansion trajectory. Fiberglass is climbing the fastest in premium fleet specifications.
Installation:
Customer type dictates installation architecture preference, with leased vehicle penetration above 35% inverting priorities toward reversibility.
- Clamp-On:Bed-rail gripping systems require no drilling and preserve factory warranties. Clamp-on methods are gaining fastest among retail consumers in Texas urban corridors where fleet turnover rates exceed national averages.
- Drill-Free:Rail-mounted brackets using existing stake pockets or tie-down points enable same-day fitting by mobile service providers. Specialty installers are capturing volume from traditional brick-and-mortar retailers through this channel rotation.
- Custom-Fit:Vehicle-specific mounting hardware engineered for precise bed dimension matching. Custom-fit systems command OEM placement premiums where SAE J2807 tow-rating integration must be validated.
- Universal:Adjustable rail systems accommodating multiple bed widths and rail configurations. Universal products compete on inventory efficiency for mass retail channels but sacrifice fit precision.
Clamp-On holds installed capacity. Drill-Free is gaining share fastest among specialty installer networks.
End User:
Application requirements separate factory-integrated fleet procurement from self-directed retail purchasing.
- Fleet Operators:Corporate logistics and utility managers specify electrochromic and photovoltaic-integrated hard covers at triple the rate of retail consumers. California CARB zero-emission fleet mandates are creating demand for lightweight, aerodynamic bed covers that extend electric pickup range.
- Retail Consumers:Individual pickup owners prioritize ease of installation, warranty preservation, and entry-price accessibility. Leased vehicle penetration has inverted buyer priorities toward clamp-on, drill-free methods.
- Outdoor Enthusiasts:Recreational users demand weather-resistant cargo protection for camping, hunting, and marine equipment transport. Canvas and soft-roll variants retain preference for breathability and rapid deployment.
- Commercial Users:Construction, landscaping, and service trades require maximum security and tool storage integration. Hard-cover and retractable systems dominate where theft prevention and professional appearance drive specification.
Fleet Operators hold installed capacity. Commercial Users are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexican assembly plants export tonneau-integrated pickup trucks to the United States corridor from Texas to Michigan, creating cross-border demand pull for just-in-time cargo cover systems.
United States
Fleet operators across the Texas-to-Michigan manufacturing corridor specify factory-integrated retractable hard covers for EPA fuel-economy compliance. NHTSA FMVSS 302 flammability standards accelerate aluminum-composite substrate adoption in OEM supply chains. Detroit and Dallas-Fort Worth anchor concentrated demand for validated aerodynamic bed covers.
Canada
Resource extraction industries in Alberta and British Columbia drive commercial hard-cover procurement for tool security in remote worksites. Environment and Climate Change Canada regulations on vehicle emissions create pull for aerodynamic accessories. The Ontario manufacturing belt around Windsor supplies cross-border pickup production with integrated cargo systems.
Mexico
Assembly plants in Nuevo León and the Bajío Region produce pickup trucks for North American export, embedding tonneau integration into manufacturing workflows. Mexican automotive manufacturing standards align with US EPA and NHTSA protocols for factory-installed accessories. Monterrey anchors supplier clustering for just-in-time bed cover delivery to assembly lines.
Germany
Precision-lock component suppliers in Baden-Württemberg and Bavaria dominate latching mechanism supply for retractable cover assemblers worldwide. KBA vehicle certification requirements constrain material selection and testing regimes for suppliers seeking European placement. Stuttgart engineering clusters develop corrosion-resistant aluminum extrusion architectures.
China
Aluminum sheet and vinyl laminate producers in Guangdong and Zhejiang provinces feed global tonneau substrate supply chains. MIIT fuel-efficiency standards for light commercial vehicles create domestic demand for aerodynamic bed covers. The Yangtze River Delta manufacturing hub concentrates roll-forming equipment production for aluminum slat systems.
Automotive Tonneau Market Competitive Environment
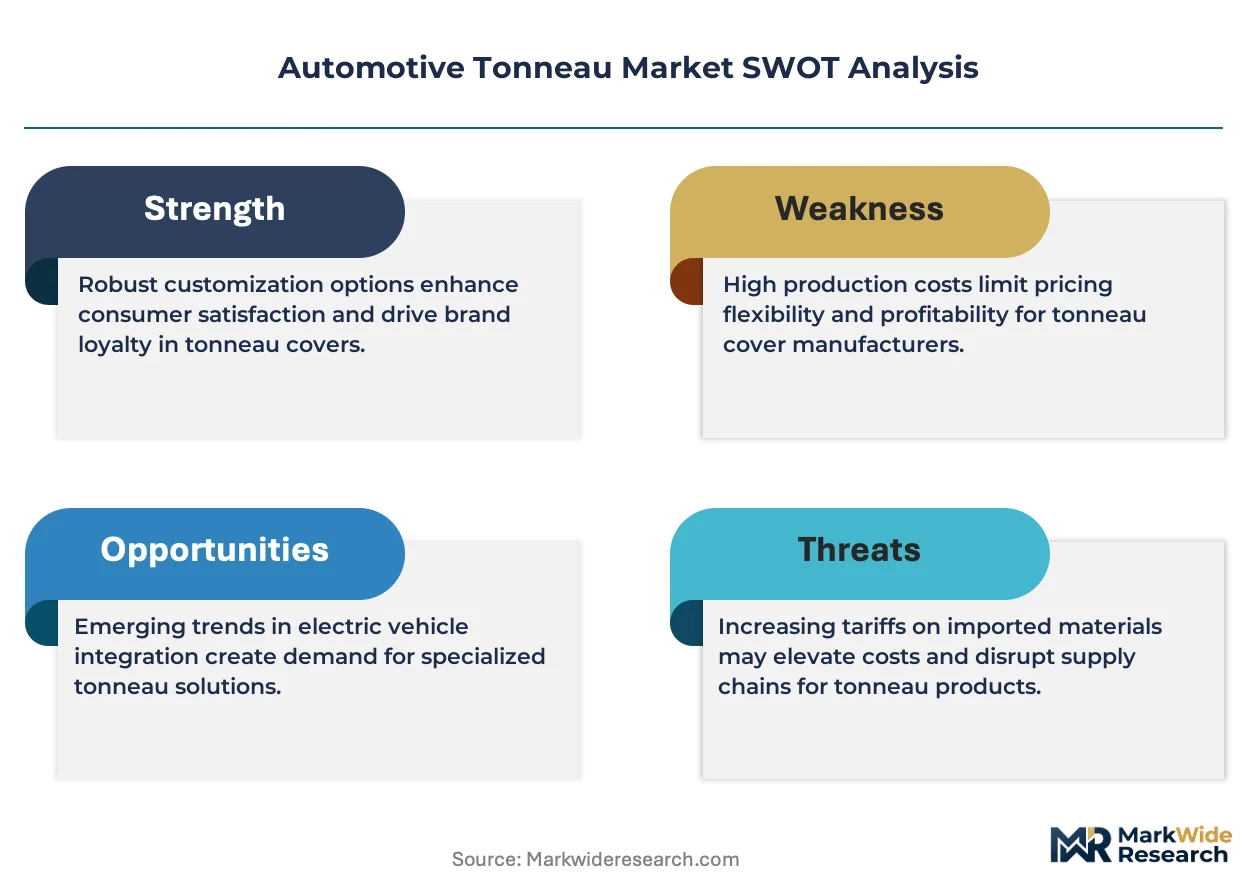
Listed leaders compete with private specialists across channel access and installation method coverage. The vendor base separates into multi-brand portfolio operators, proprietary technology developers, and regional fabrication specialists. Three archetypes dominate: scale-driven mass retailers, innovation-focused hard-cover engineers, and mobile service-integrated installers. M&A activity concentrates on brand portfolio consolidation, while capacity expansion targets aluminum extrusion and canister housing production.
Within the premium hard-cover tier, Truck Hero and BAK Industries exemplify divergent strategic positioning. Truck Hero anchors multi-brand channel dominance across mass retail and specialty installer networks. BAK Industries occupies a position as a proprietary technology developer with differentiated slat architectures. DiamondBack represents the specialized fabricator archetype with focused regional penetration. These three companies collectively illustrate how scale, innovation, and specialization carve distinct competitive positions in a market fragmenting between certified OEM supply and aftermarket accessibility.
| Leading Market Players |
|---|
| Bestop |
| Gator Cover |
| Truck Hero |
| TruXedo |
| DiamondBack |
| BAK Industries |
| Agri-Cover |
| UnderCover |
| Lund |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day aluminum slat lead times from Midwest mills concentrate pricing power among hard-cover fabricators with captive extrusion capacity, while vinyl-dependent assemblers absorb commodity volatility through contract pass-through clauses. This inventory compression at the substrate tier separates margin-stable retractable cover suppliers from soft-roll competitors exposed to spot-market PVC fluctuations.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on SAE J2807 tow-rating certification and NHTSA FMVSS 302 flammancy compliance, with certified systems commanding placement premiums. Cost compression in entry-tier vinyl segments is intensifying because soft-roll substitution elasticity caps recovery of aluminum premium spikes. Fleet procurement officers show least price sensitivity due to EPA fuel-economy compliance mandates, while self-install retail consumers in leased-vehicle segments exhibit highest elasticity.
Supply Chain Analysis
Inventory compression at the precision-lock tier—where Baden-Württemberg and Bavarian suppliers dominate latching mechanism supply—creates vulnerability for retractable cover assemblers lacking dual-source qualification. Raw material flows draw from Midwest aluminum mills, Guangdong vinyl laminate producers, and Zhejiang roll-forming equipment manufacturers. Single-source dependency on German and Japanese lock suppliers represents the primary structural risk. Distribution runs through mass retail auto parts chains, specialty installer networks, and direct-to-fleet digital platforms serving Texas-to-Michigan corridor demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against drill-free soft-roll alternatives that capture recession-sensitive volume from premium hard-cover incumbents. Fleet electrification and CARB zero-emission mandates accelerate demand for lightweight aerodynamic systems that commodity vinyl cannot satisfy.
For Market Incumbents: Consolidate aluminum extrusion capacity in the Texas-to-Michigan corridor to secure substrate supply against Midwest premium volatility. Deepen SAE J2807 certification pipelines to defend OEM placement against uncertified aftermarket competitors. Control specialty installer channel access through same-day fitting service partnerships that preserve fleet warranty positioning.
For New Entrants and Emerging Players: Lead with electrochromic and photovoltaic-integrated hard covers targeting California CARB zero-emission fleet mandates where corporate logistics managers specify smart covers at triple retail rates. Penetrate the commercial user segment through mobile service-integrated installation platforms bypassing traditional brick-and-mortar retail. Deploy direct-to-installer digital platforms capturing margin from fragmented specialty networks.
For Investors and Strategic Acquirers: Carve-out targets emerge from multi-brand portfolio operators with underutilized aluminum canister housing capacity and dormant OEM certification pathways. Long-term viability centers on validated aerodynamic performance under tightening EPA fuel-economy standards. Monitor SAE J1211 water-ingress certification completion rates as inflection indicator for product pipeline velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Extrusion Capacity Expansion | Captive substrate supply insulates margin from Midwest LME premium volatility. |
| SAE J2807 Tow-Rating Certification | Validated systems command OEM placement premiums against uncertified aftermarket alternatives. |
| Direct-to-Installer Digital Platform | Bypassing mass retail captures margin and reduces channel conflict for specialty brands. |
| Electrochromic Cover Development | Smart covers penetrate California CARB fleet mandates where corporate procurement concentrates. |
| Dual-Source Latching Mechanism Qualification | Mitigates single-source vulnerability to German and Japanese precision-lock suppliers. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributor category managers, specialty installer operations heads, and fleet logistics procurement officers. Secondary validation drew from NHTSA FMVSS filings, EPA fuel-economy certification databases, SAE technical standards documentation, vehicle production registries, and aluminum trade association pricing data. Bottom-up volume builds across product type, material, installation method, and end-user segments were triangulated against top-down market sizing from corridor-level demand aggregation.
Across the analysis window, the forecasting framework modeled retractable, hard, folding, and soft product architectures; aluminum, vinyl, canvas, and fiberglass material tiers; clamp-on, drill-free, custom-fit, and universal installation methods; and fleet operator, retail consumer, outdoor enthusiast, and commercial user end-use segments. CAGRs were derived from segment-level volume trajectories weighted by corridor-specific production and registration data. Aluminum premium volatility curves and NHTSA regulatory compliance timelines served as primary forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained pickup truck production volumes in the Texas-to-Michigan corridor, stable NHTSA load-securement enforcement, and aluminum premium band containment would require recalibration. Forecasts reflect documented assumptions regarding fleet electrification adoption curves and CARB mandate expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Africa Automotive Engine Oils Market
Automotive Parts
Automotive Screenwash Products Market
Automotive Parts
Automotive Air Conditioning Electric Scroll Compressors Market
Automotive Parts
Automotive Wiper System Market
Automotive Parts
Europe Roll Forming Body in White Market
Automotive Parts
Air Springs Market
Automotive Parts
Asia-Pacific Passenger Vehicles Lubricants Market
Automotive Parts
Argentina Passenger Vehicles Lubricants Market
Automotive Parts
Japan Commercial Vehicles Lubricants Market
Automotive Parts
Bearing Steel Balls for New Energy Vehicles Market
Automotive Parts
Automotive Belts and Hoses Market
Automotive Parts
Automotive Radiator Hose Market
Automotive Parts
Automotive Winches System (AWS) Market
Automotive Parts
Malaysia Passenger Vehicles Lubricants Market
Automotive Parts
Spare Wheel Carrier Market
Automotive Parts
Automotive Electric HVAC Compressor Market