
 Folinic Acid Market | 2026-2036
Folinic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Folinic Acid Market Analysis
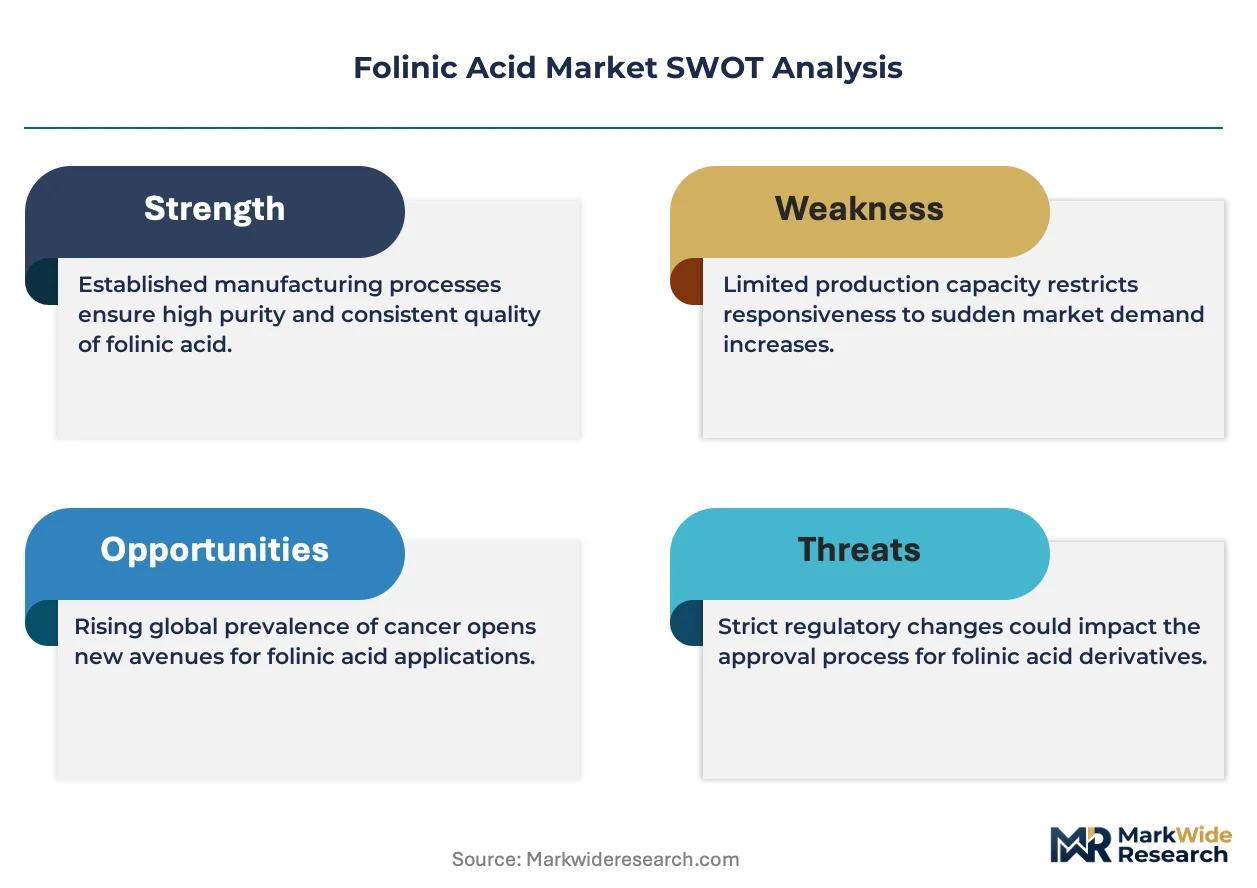
A capital-intensity divergence between large-scale fermentation specialists and small-batch API formulators is redrawing competitive boundaries in folinic acid supply. DSM N.V leverages integrated vitamin production platforms that span precursor synthesis to finished dosage. BASF SE anchors European supply through backward integration into petrochemical feedstocks. Jiangxi Tianxin Pharmaceutical Co. Ltd competes on cost-optimized fermentation scale out of China.
Folinic acid, or 5-formyltetrahydrofolic acid, is a reduced folate derivative with the molecular formula C20H23N7O7; manufacturers synthesize it via chemical reduction of folic acid or microbial fermentation, yielding a compound that bypasses dihydrofolate reductase to deliver bioavailable folate directly. Clinics and hospitals remain the dominant end-user channel, absorbing high-volume injectable volumes for cancer regimens. Tablet and capsule formats serve stable outpatient folate deficiency protocols with lower per-unit margins but steadier replenishment cycles.
FDA oversight of pharmaceutical-grade folate APIs and EMA's REACH-aligned impurity thresholds shape formulation standards and cross-border market access. The country's national pharmaceutical regulator in India enforces BIS quality benchmarks for export-oriented production. Stakeholders must monitor evolving pharmacopeial monographs and dual-source API qualification requirements to secure supply continuity.
Market Dynamics
Oncology clinics in the United States and Japan are consolidating purchasing power around high-purity injectable folinic acid, forcing API manufacturers to requalify production lines under tightening FDA and PMDA impurity thresholds.
Growth Catalysts
- EMA impurity mandates:The European Medicines Agency's revised nitrosamine thresholds for folate APIs are accelerating facility upgrades among European formulators, locking in quality-premium supply relationships.
- Colorectal cancer protocols:Folinic acid's role in FOLFOX and FOLFIRI regimens sustains hospital procurement volumes as chemotherapy administration shifts toward outpatient infusion centers.
- Fermentation scale-out:Chinese producers are expanding microbial production capacity, compressing unit costs for pharmaceutical-grade 5-formyltetrahydrofolic acid.
Market Restraints
- Petrochemical feedstock volatility:BASF SE's backward integration into toluene and pyridine precursors exposes European supply to energy price swings.
- Single-source API risk:Injectable-grade folinic acid concentrates among three fermentation specialists, creating vulnerability to batch contamination events.
- Oral folate substitution:Generic leucovorin tablets face price erosion from compounded 5-methyltetrahydrofolate alternatives in outpatient markets.
Strategic Opportunities
- Brazil's ANVISA fast-track:Streamlined oncology API registration opens import pathways for qualified Asian manufacturers.
- Pediatric oncology formulations:Liquid oral dosing formats for pediatric leukemia protocols remain underdeveloped relative to adult injectables.
- Direct-to-hospital distribution:Bypassing wholesale distributors through GPO-integrated logistics contracts captures margin from concentrated US hospital systems.
Industry Challenges
- Pharmacopeial harmonization delays:Divergent USP, EP, and JP monograph specifications for folate-related substances force redundant analytical method validation.
- Specialized fermentation expertise:Scaling microbial production of reduced folates requires strain engineering capabilities scarce outside established vitamin houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Folinic Acid Market |
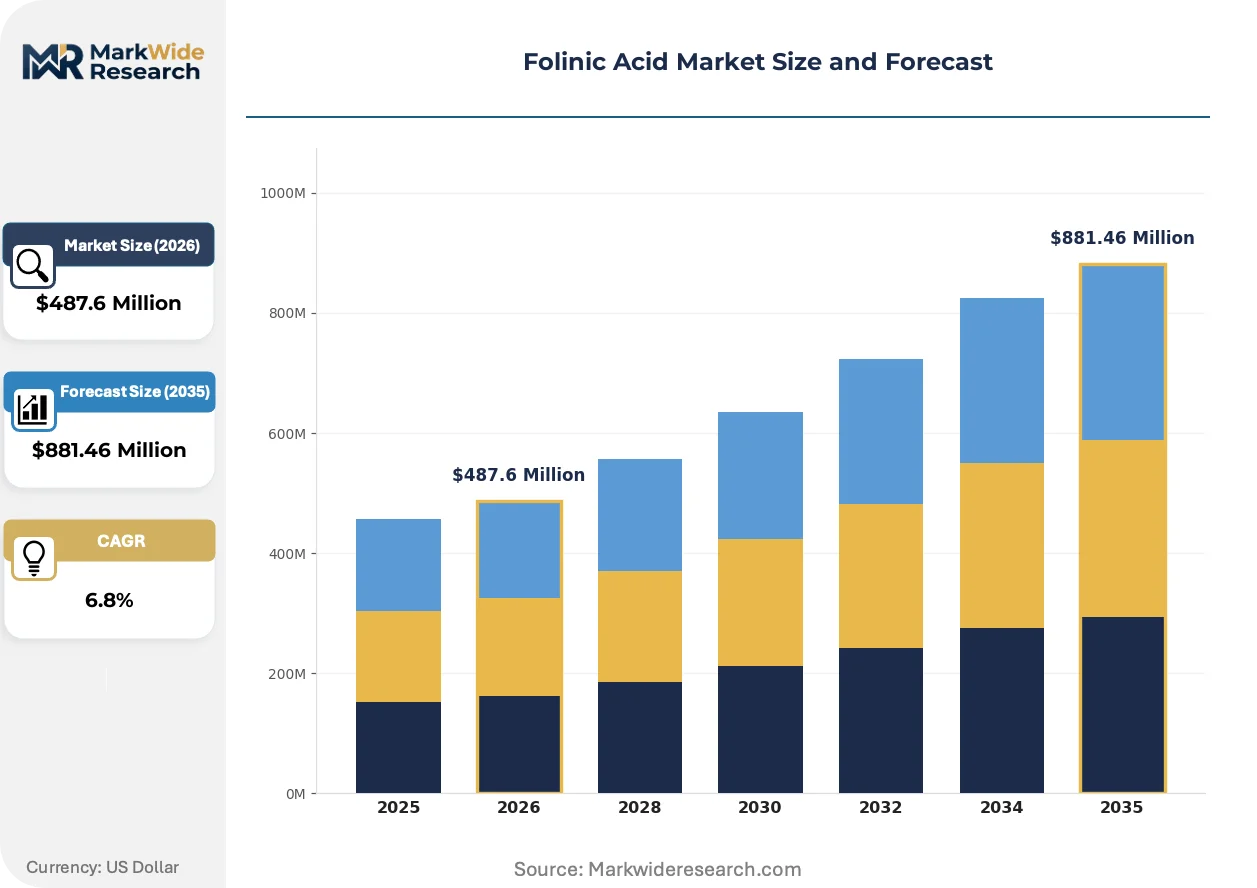
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Injections, Capsules, Solutions End User: Clinics, Hospitals, Home Care, Pharmacies Application: Cancer Therapy, Folate Deficiency, Nephrology, Surgery Distribution Channel: Online Pharmacy, Retail Pharmacy, Hospital Pharmacy, Direct Sales |
| Companies Covered | DSM N.V, BASF SE, Parchem Fine & Specialty Chemicals, Jiangxi Tianxin Pharmaceutical Co. Ltd, Medicamen Biotech Ltd, Xinjiang Wujiaqu Xingnong Cycle Chemical Co. Ltd, Zydus Pharmaceuticals Ltd, Emcure Pharmaceuticals Ltd, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Folinic Acid Market Emerging Trajectories
Continuous processing technologies and real-time release testing are compressing batch cycle times for folinic acid APIs, while regulatory convergence around ICH Q3D elemental impurity limits is reshaping qualification protocols.
Continuous manufacturing of folinic acid sodium salt is supplanting traditional batch crystallization in advanced API facilities. European oncology injectable producers are piloting these lines to halve production cycle times. The technology is enabling just-in-time inventory models that reduce working capital requirements for hospital procurement departments.
REACH-aligned substance registration deadlines for folate derivatives are forcing non-European exporters to appoint EU-based only representatives and submit extended safety data sets. This regulatory friction is consolidating import channels toward larger API houses with dedicated regulatory affairs teams. German and Dutch formulators are absorbing compliance costs through long-term supply agreements that lock out smaller competitors.
Consolidated purchasing by US hospital GPOs is compressing supplier rosters to qualified dual-source API relationships. Oncology clinics are shifting from spot procurement to 24-month framework contracts with price-volume bands. This concentration is most visible in the Southeast and Midwest hospital systems where Premier and Vizient purchasing cooperatives dominate formulary decisions.
Folinic Acid Market Segmentation
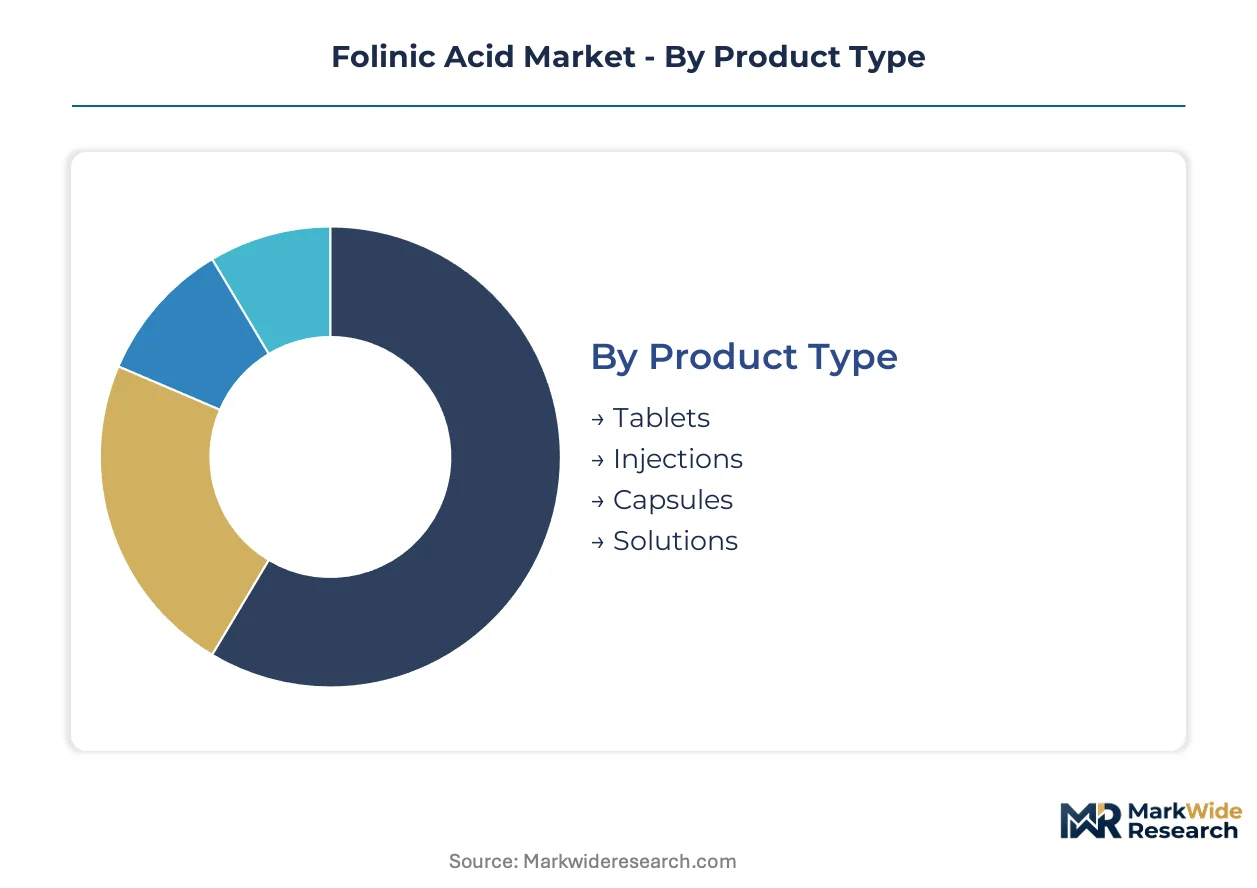
Folinic acid demand fragments across administration routes, care settings, and procurement channels. Each segment carries distinct regulatory burdens, margin profiles, and volume characteristics that reshape supplier priorities.
Product Type:
FDA and EMA purity mandates diverge sharply between sterile injectables and solid oral formats, creating tiered compliance costs.
- Injections:Lyophilized or liquid sterile formulations for intravenous or intramuscular delivery. Oncology clinics in the United States concentrate procurement around high-purity vials for FOLFOX and FOLFIRI regimens, with PMDA-aligned Japanese hospitals demanding equivalently stringent endotoxin thresholds.
- Tablets:Compressed oral dosage forms containing calcium or sodium folinate salts. German retail pharmacies drive replenishment cycles for stable outpatient folate deficiency protocols under EMA bioequivalence guidelines.
- Capsules:Gelatin or HPMC shells housing folinate powder blends. Home care channels in France favor this format for pediatric palatability under ANSM stability requirements.
- Solutions:Ready-to-use liquid oral or topical preparations. Brazilian oncology centers source these for enteral feeding compatibility under ANVISA fast-track registration pathways.
Injections handle the majority of throughput; Solutions is the fastest mover on share.
End User:
Procurement authority concentrates differently across institutional buyers, dictating contract structures and margin capture.
- Hospitals:Acute care institutions with centralized pharmacy operations and GPO-integrated purchasing. Premier and Vizient cooperatives in the US Southeast and Midwest dominate formulary decisions for high-volume injectable folinic acid.
- Clinics:Outpatient infusion and specialty care facilities. Japanese oncology clinics are consolidating purchasing power around 24-month framework contracts with price-volume bands.
- Home Care:Patients receiving folinate supplementation outside institutional settings. German statutory insurance reimbursement drives tablet and capsule demand for chronic folate deficiency management.
- Pharmacies:Community and retail dispensaries with direct patient contact. Indian export-oriented producers supply BIS-certified stock to hospital pharmacy chains serving nephrology protocols.
Hospitals command the largest volume commitments; Home Care is expanding most quickly as ambulatory care shifts accelerate.
Application:
Clinical indication determines dosing intensity, duration, and regulatory scrutiny levels for folinic acid deployment.
- Cancer Therapy:Adjunctive use in colorectal, gastric, and pediatric leukemia protocols requiring precise leucovorin rescue or 5-FU modulation. FDA oversight of pharmaceutical-grade APIs shapes formulation standards for US hospital procurement.
- Folate Deficiency:Correction of megaloblastic anemia and malabsorption syndromes. Stable outpatient demand in European retail channels under EMA REACH-aligned impurity thresholds sustains oral format volumes.
- Nephrology:Management of hyperhomocysteinemia in chronic kidney disease patients. Dialysis centers in Japan source specialized injection formats under PMDA quality mandates.
- Surgery:Perioperative nutritional support and methotrexate rescue in orthopedic and reconstructive procedures. Brazilian hospital systems are piloting direct-to-facility distribution for these lower-volume applications.
Cancer Therapy absorbs the dominant share of value; Nephrology shows the steepest expansion trajectory as dialysis populations grow.
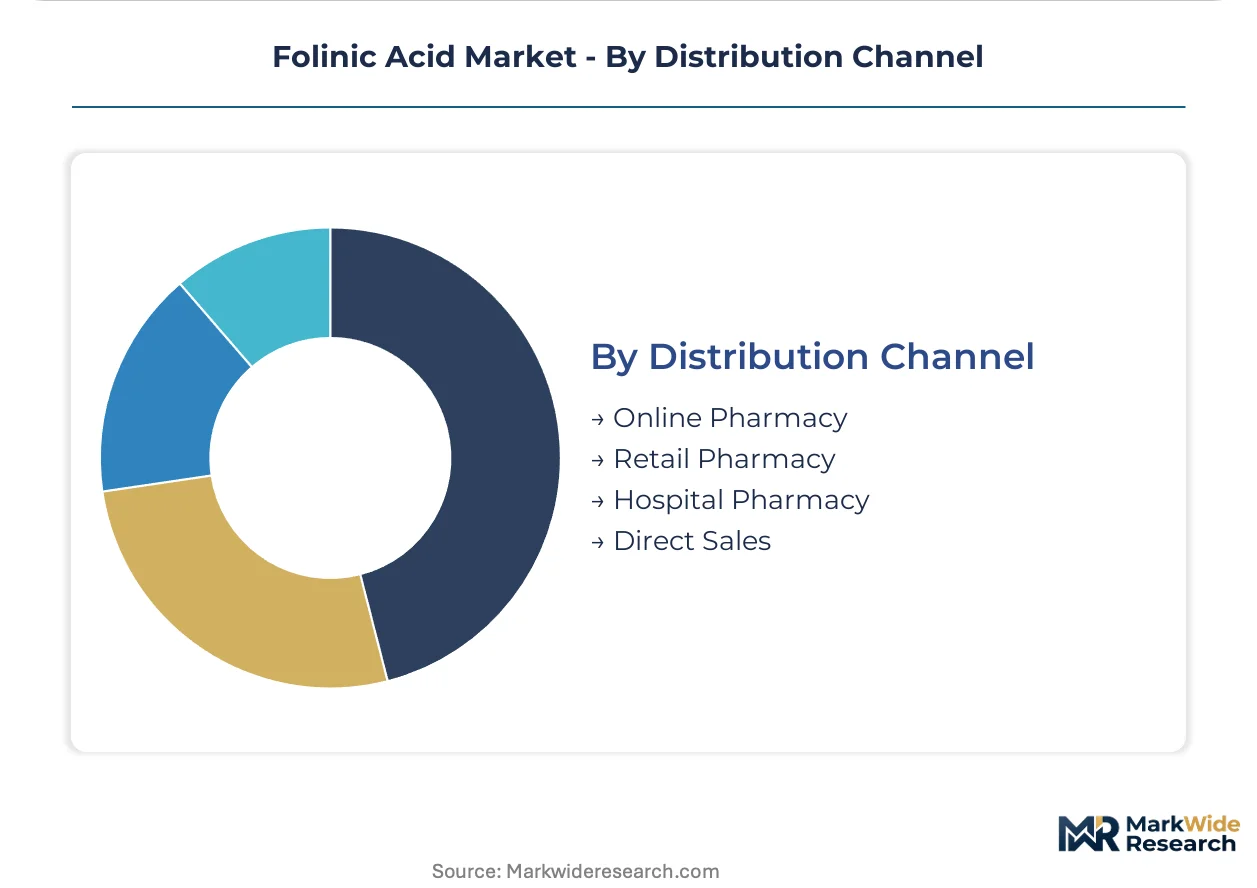
Distribution Channel:
Channel selection determines working capital requirements, regulatory documentation burdens, and end-user reach.
- Hospital Pharmacy:Captive dispensing operations within acute care institutions. US hospital GPOs are compressing supplier rosters to qualified dual-source API relationships with 24-month frameworks.
- Retail Pharmacy:Community-based dispensaries with walk-in patient access. German and Dutch formulators absorb REACH compliance costs through long-term supply agreements that lock out smaller competitors.
- Online Pharmacy:Digital platforms with home delivery capabilities. Indian BIS-certified producers leverage these channels for export-oriented folate tablet distribution to Southeast Asian markets.
- Direct Sales:Manufacturer-to-institution contracts bypassing wholesale intermediaries. Oncology injectable producers are piloting just-in-time inventory models that reduce working capital for US hospital procurement departments.
Hospital Pharmacy moves the bulk of injectable volume; Direct Sales is climbing the fastest as GPO-integrated logistics contracts proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: the United States and Japan prioritize high-purity injectables for oncology protocols, while Germany and India sustain oral format volumes through retail pharmacy and export channels respectively.
United States
Oncology clinics in the Southeast and Midwest concentrate purchasing power through Premier and Vizient cooperatives, driving demand for sterile injectable folinic acid in FOLFOX and FOLFIRI regimens. FDA pharmaceutical-grade API mandates shape formulation standards and cross-border market access. Hospital systems in Texas and Illinois are piloting direct-to-facility distribution models that bypass wholesale intermediaries.
Germany
Retail pharmacies in Bavaria and North Rhine-Westphalia anchor replenishment cycles for oral folinate tablets serving stable outpatient folate deficiency protocols. EMA REACH-aligned impurity thresholds force facility upgrades among domestic formulators, locking in quality-premium supply relationships. The country's chemical manufacturing corridor around Ludwigshafen supports backward-integrated precursor synthesis.
Japan
PMDA-aligned hospitals in Tokyo and Osaka demand equivalently stringent endotoxin thresholds for injectable folinic acid, consolidating procurement around 24-month framework contracts. Dialysis centers source specialized injection formats for hyperhomocysteinemia management in chronic kidney disease patients. The Kanto region's oncology clinics are shifting from spot procurement to volume-band agreements.
India
BIS-certified producers in Maharashtra and Gujarat supply export-oriented folate tablets to Southeast Asian markets through online pharmacy channels. The country's national pharmaceutical regulator enforces quality benchmarks for hospital pharmacy chains serving nephrology protocols. Domestic fermentation capacity is expanding to capture cost-optimized production of pharmaceutical-grade 5-formyltetrahydrofolic acid.
Brazil
ANVISA fast-track registration for oncology APIs is opening import pathways for qualified Asian manufacturers into São Paulo and Rio de Janeiro hospital systems. Oncology centers in the Southeast region source ready-to-use liquid preparations for enteral feeding compatibility. Direct-to-hospital distribution pilots are reducing working capital requirements for lower-volume surgical applications.
Folinic Acid Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with fermentation scale and precursor control determining competitive position. European and Chinese producers dominate API supply through contrasting production models: petrochemical-derived synthesis versus microbial fermentation. Three archetypes define the field—backward-integrated chemical conglomerates, fermentation-scale vitamin houses, and regional formulation specialists. Capacity expansion and dual-source API qualification are the dominant competitive moves as hospital GPOs compress supplier rosters.
Within the integrated chemical tier, DSM N.V and BASF SE exemplify divergent upstream strategies—DSM through vitamin production platforms spanning precursor to finished dosage, BASF through petrochemical feedstock integration. Jiangxi Tianxin Pharmaceutical Co. Ltd represents the cost-optimized fermentation archetype, with Chinese producers expanding microbial capacity to compress unit costs for pharmaceutical-grade output.
| Leading Market Players |
|---|
| DSM N.V |
| BASF SE |
| Parchem Fine & Specialty Chemicals |
| Jiangxi Tianxin Pharmaceutical Co. Ltd |
| Medicamen Biotech Ltd |
| Xinjiang Wujiaqu Xingnong Cycle Chemical Co. Ltd |
| Zydus Pharmaceuticals Ltd |
| Emcure Pharmaceuticals Ltd |
| Pfizer |
| Others |
Supply Flow & Price Mechanics
Injectable-to-oral substitution in folate delivery is redrawing procurement economics, compressing margins on tablet formats while concentrating pricing power among sterile API specialists serving US oncology clinics. This input shift simultaneously tilts supply geography toward Chinese fermentation scale and European chemical synthesis corridors.
Pricing Analysis
After-sales revenue from GPO-integrated service contracts and just-in-time logistics underwrites lifetime value capture for injectable folinic acid suppliers. Three-tier pricing structure across premium, standard, and economy levels stratifies by endotoxin grade and FDA certification tier, with PMDA-aligned Japanese hospitals least price-sensitive and Indian export tablet buyers most elastic. Cost compression in oral generics is intensifying because compounded 5-methyltetrahydrofolate alternatives displace leucovorin tablets in outpatient markets.
Supply Chain Analysis
Strait of Malacca transit routes anchor bulk pyridine and toluene feedstock flows feeding BASF SE's Ludwigshafen synthesis complex. API supply concentrates in China, India, and Germany, with microbial fermentation strains and petrochemical precursors as critical inputs. Single-source vulnerability haunts injectable-grade production where three fermentation specialists control hospital-grade output. Distribution runs through GPO-integrated hospital pharmacy channels in the US Southeast and Midwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Strain engineering capabilities for reduced folate microbial production are scarce outside established vitamin houses, creating durable moats for incumbents while constraining new entrant scale-up timelines.
For Market Incumbents: Compound backward integration into pyridine precursors to defend against BASF SE's petrochemical feedstock control and Chinese fermentation cost compression. Lock in dual-source API qualification with Premier and Vizient cooperatives before GPO roster consolidation completes. Prioritize continuous manufacturing line investments to halve batch cycle times for oncology injectable contracts. For New Entrants and Emerging Players: Differentiate on pediatric liquid oral dosing formats for leukemia protocols, a white space underdeveloped relative to adult injectables. Target Brazil's ANVISA fast-track pathway for oncology API registration, where qualified Asian manufacturers face streamlined import access. Pursue direct-to-hospital distribution contracts bypassing wholesale intermediaries in São Paulo hospital systems. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fermentation-scale vitamin houses seeking exit liquidity after capacity expansion cycles. Five-to-ten year viability hinges on regulatory convergence around ICH Q3D elemental impurity limits and REACH-aligned substance registration compliance. Watch for PMDA and FDA harmonization on folate-related substances monographs as inflection signal for qualification cost consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Scale-Up | Chinese producers expanding microbial output compress unit costs for pharmaceutical-grade 5-formyltetrahydrofolic acid. |
| Continuous Manufacturing Adoption | European oncology injectable producers pilot real-time release testing to enable just-in-time hospital inventory models. |
| Dual-Source API Qualification | US hospital GPOs compress supplier rosters to qualified relationships with 24-month framework contracts. |
| Pediatric Formulation Development | Liquid oral dosing for leukemia protocols remains underdeveloped versus adult injectable concentration. |
| Direct-to-Hospital Distribution | Bypassing wholesale intermediaries captures margin from concentrated Texas and Illinois hospital systems. |
Methodological Framework
A spread of perspectives from API manufacturing directors, hospital pharmacy procurement managers, regulatory affairs specialists at EMA-notified bodies, and GPO contracts administrators converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA filings, EMA assessment reports, pharmacopeial monograph revisions, and customs trade data for folate derivative flows. Bottom-up volume triangulation across administration routes and care settings was cross-checked against top-down market sizing from chemical industry associations.
Segmentation dimensions modeled include product type, end-user institution type, clinical application, and distribution channel across the analysis window. CAGRs were derived from elasticity-adjusted volume projections and price-band assumptions for injectable versus oral formats. Forecast inputs incorporated REACH registration deadline impacts, PMDA impurity threshold alignment timelines, and GPO contract renewal patterns.
Decision-makers should treat outputs as directional under stable regulatory harmonization and feedstock cost assumptions; material deviation in petrochemical volatility or batch contamination events would warrant model refresh. Practitioners should keep alternative scenarios live as EMA-FDA pharmacopeial convergence and Chinese fermentation capacity expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Hyaluronic Acid Raw Material Market
Pharmaceutical Ingredients
Global Glycine Supplement Market
Pharmaceutical Ingredients
Pharmaceutical Lactose Market
Pharmaceutical Ingredients
Global Dexamethasone Market
Pharmaceutical Ingredients
Global Tacrolimus Market
Pharmaceutical Ingredients
United States Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Originator Small Molecule Drug Market
Pharmaceutical Ingredients
Alpha Lipoic Acid API Market
Pharmaceutical Ingredients
Global Granisetron Market
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients CDMO Market
Pharmaceutical Ingredients
Cyprosin Market
Pharmaceutical Ingredients
Quinoline Market
Pharmaceutical Ingredients
Global Sugar-Based Excipients Market
Pharmaceutical Ingredients
Pharmaceutical Thermal Analysis Market
Pharmaceutical Ingredients
Albumin (As Excipient) Market
Pharmaceutical Ingredients
Synthetic Small Molecule API Market