
 Europe Electric Radiators Market | 2026-2036
Europe Electric Radiators Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Radiators Market Analysis
Aluminum is consolidating its position as the dominant heat-exchange material in Europe, displacing legacy cast-iron cores across mid-range and premium product lines. Glen Dimplex leverages its Irish manufacturing base to anchor supply across the British Isles and Nordic markets. Stelrad competes through deep specialization in panel radiator architectures, while Zehnder differentiates via design-forward radiators that command architectural specification channels.
Europe electric radiators are electrically powered heat emitters that convert electrical energy to thermal output through resistive elements, ceramic cores, or infrared panels, typically operating at wattages from 400W to 2,500W and serving as primary or supplementary space heating in buildings. Their core commercial purpose centers on zone-level temperature control without combustion infrastructure, enabling deployment in retrofits where gas connection proves impractical. Panel radiators lead volume across residential replacement cycles, while infrared radiators capture margin in commercial wellness and hospitality applications where radiant asymmetry matters. Smart controls represent the fastest-expanding technology segment, though traditional thermostatic products still dominate replacement demand in price-sensitive Southern European markets.
The EU Green Deal and F-Gas Regulation are accelerating building decarbonization mandates that directly phase out fossil-fuel heating in new construction across member states, while CE marking and Ecodesign requirements enforce minimum efficiency thresholds on electric heating products. ECHA chemical restrictions and national building codes in Germany, France, and Poland further shape material choices and installation standards. Stakeholders must monitor how national implementation of the EU AI Act intersects with smart heating algorithms and data privacy obligations.
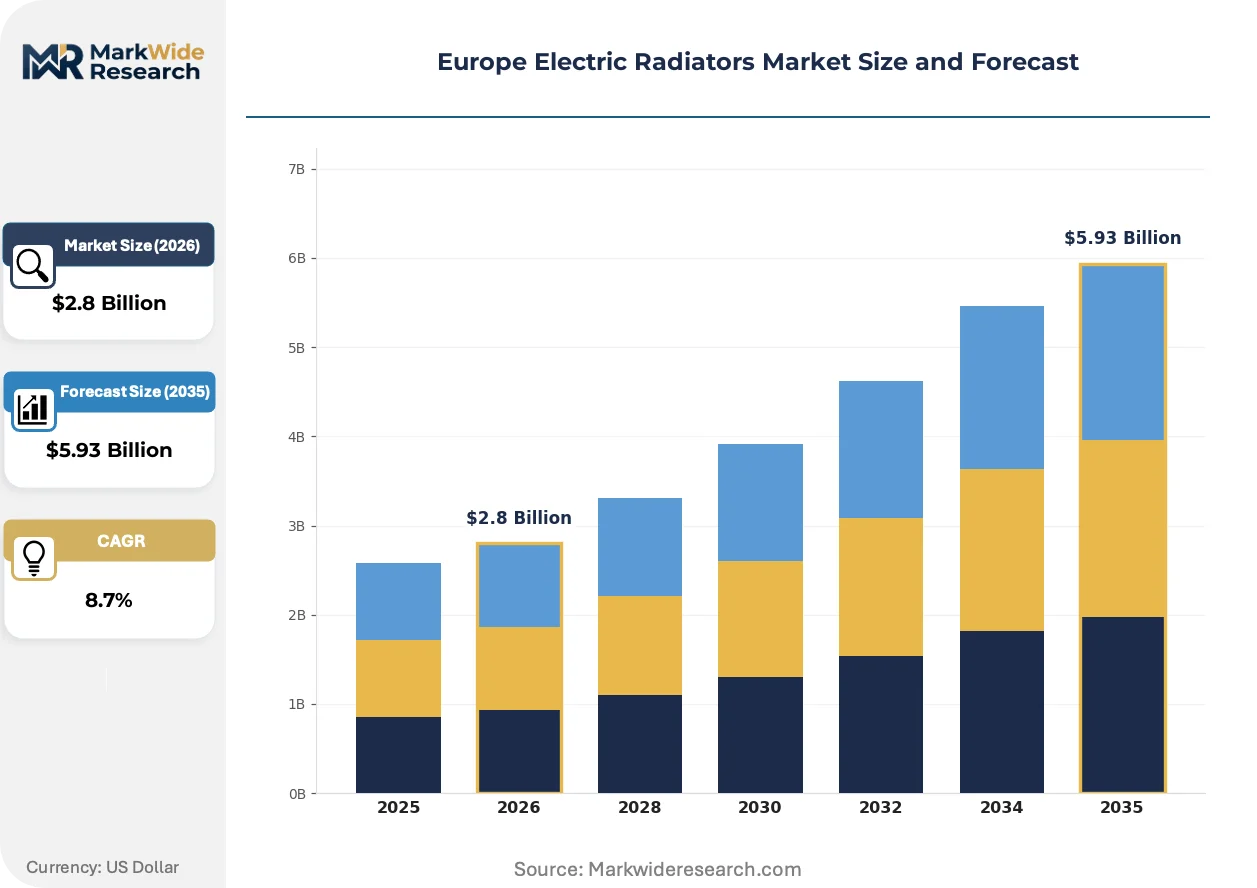
Market Dynamics
The EU Green Deal and F-Gas Regulation are forcing building decarbonization timelines that eliminate fossil-fuel heating in new construction, while ceramic core thermal mass technology redefines efficiency benchmarks across residential and commercial installations.
Growth Catalysts
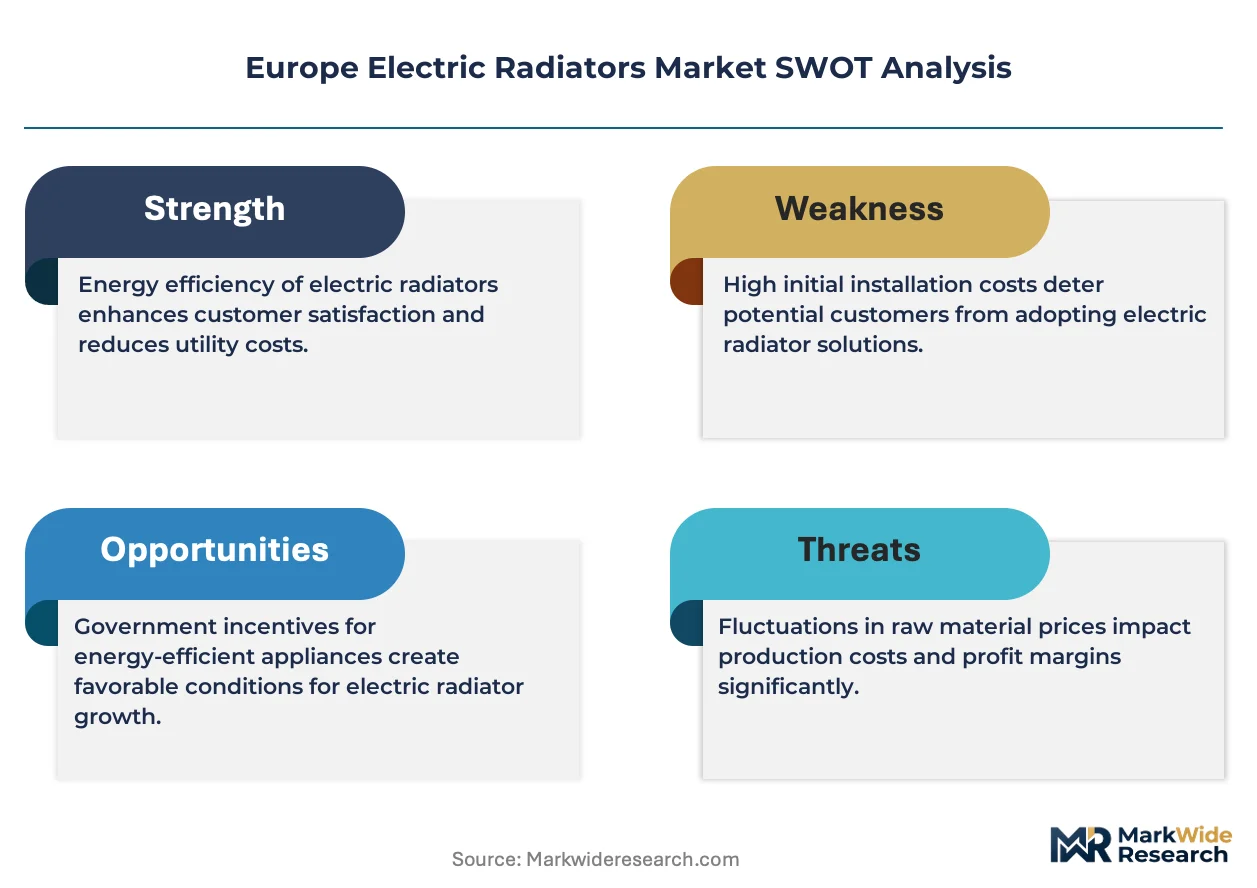
- Building energy performance mandates:The EU Green Deal tightens efficiency requirements for residential retrofits across Germany, France, and the United Kingdom. Electric radiators bypass gas connection infrastructure in dense urban cores.
- Ceramic core thermal mass:Advanced aluminum-ceramic composite materials extend heat retention cycles. German and Nordic manufacturers lead integration into mid-range product lines.
- Electrification tailwinds in Northern Europe:District heating limitations in rural Denmark, Sweden, and Finland accelerate zone-level electric heating deployment where gas-to-hydrogen transitions stall.
Market Restraints
- Electricity price volatility:Wholesale power cost fluctuations in Germany and the Netherlands compress operating cost advantages against heat pumps. Residential buyers face payback period uncertainty.
- Aluminum supply concentration:Primary aluminum smelting concentrates in Norway and Iceland. European fabricators remain exposed to energy-intensive production bottlenecks and carbon border adjustment costs.
- Heat pump substitution threat:Air-source and ground-source heat pumps capture efficiency-conscious segments in new construction. Electric radiators retreat to retrofit-only positioning in several member states.
Strategic Opportunities
- Smart control algorithm integration:Machine learning-enabled predictive heating converges with occupancy sensors. The EU AI Act creates compliance frameworks for data-driven temperature optimization.
- Polish and Romanian retrofit penetration:Building stock modernization programs in Eastern Europe lag Western adoption curves. Price-sensitive markets favor electric radiators over full heat pump conversions.
- Infrared panel wellness applications:Commercial hospitality and physiotherapy sectors in Austria and Switzerland specify radiant asymmetry solutions. Premium margins exceed standard panel radiators.
Industry Challenges
- Ecodesign certification timelines:CE marking and efficiency testing protocols delay product launches. Manufacturers navigate divergent national implementation of EU-wide standards.
- Legacy heating system integration:Hydronic compatibility and smart home protocol fragmentation complicate replacement cycles. Installers require retraining on electrical commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Radiators Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel Radiators, Convection Heaters, Infrared Radiators, Oil-Filled Radiators End User: Residential, Commercial, Industrial, Hospitality Technology: Smart Controls, Programmable Thermostats, Energy-Efficient Systems, Traditional Heating Installation Type: Wall-Mounted, Portable, Built-In, Ceiling-Mounted |
| Companies Covered | Glen Dimplex, Stelrad, Zehnder, Haverland, Elnur, Rointe, Electrorad, Jaga, Eskimo, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Radiators Market Emerging Trajectories
Ceramic core technology, algorithmic climate control, and procurement model evolution are restructuring how heating equipment reaches European buildings. These shifts compress replacement cycles and elevate service expectations.
Aluminum heat-exchange cores with embedded ceramic thermal mass store and release heat across extended duty cycles. Nordic residential developers specify these systems for passive house retrofits where rapid response matters. Ceramic-integrated electric radiators are converging with demand-response grid services, enabling utilities to modulate aggregate load during peak pricing events.
The F-Gas Regulation accelerates phase-out timelines for fossil-fuel heating in new French and German construction. National building codes in Poland and the Czech Republic tighten implementation schedules through 2030. Panel radiator manufacturers face compressed certification windows as Ecodesign requirements escalate minimum efficiency thresholds.
Facility managers in Dutch and Belgian commercial real estate unbundle heating equipment from installation contracts. Direct procurement from manufacturers via digital platforms displaces traditional wholesaler channels. This pattern concentrates in multi-site retail and hospitality operators seeking standardized fleet deployments across properties.
Europe Electric Radiators Market Segmentation
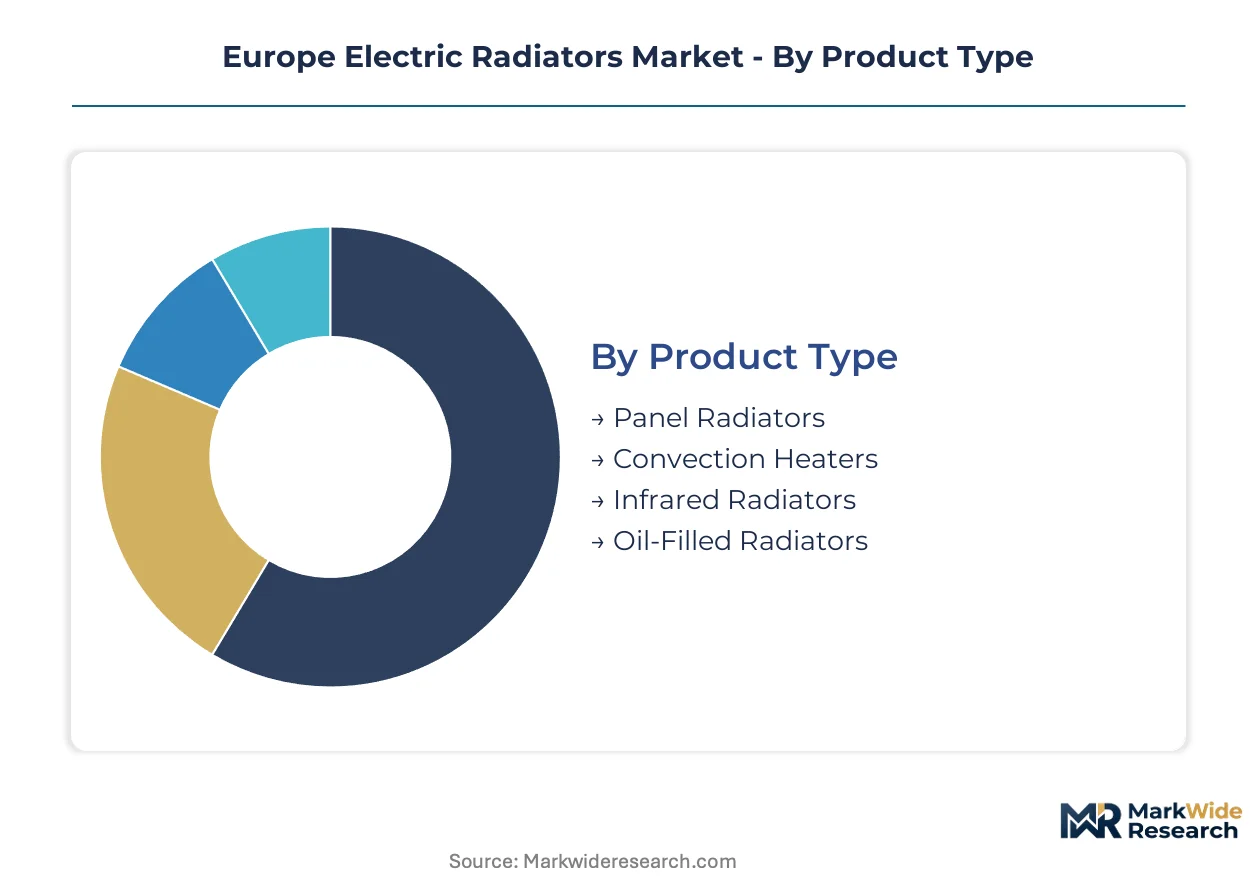
Product architecture, deployment context, and control sophistication determine procurement patterns across European electric radiators. Buyers prioritize retrofit compatibility in Germany and France, while Nordic markets emphasize grid-responsive thermal mass. Segmentation reveals where ceramic core and smart control premiums command specification.
Product Type:
Heat distribution physics and thermal response speed drive buyer selection between radiant and convective architectures.
- Panel Radiators:Aluminum-ceramic composite cores with extended heat retention cycles dominate residential replacement demand. German and UK retrofit contractors specify these for zone-level temperature control in multi-unit buildings where gas infrastructure is absent.
- Convection Heaters:Rapid-response fan-assisted units convert electrical energy to ambient warmth through forced air circulation. French and Polish price-sensitive markets favor these for supplemental heating in seasonal-use properties.
- Infrared Radiators:Surface-temperature panels deliver radiant asymmetry for wellness and hospitality applications. Austrian physiotherapy clinics and Swiss boutique hotels specify these for occupant comfort without air movement.
- Oil-Filled Radiators:Thermal fluid reservoirs provide slow-release heat in legacy residential stock. Southern European markets retain demand for these portable units in rental properties.
Panel radiators lead on scale; infrared radiators lead on momentum.
End User:
Building energy performance obligations and electrification timelines reshape demand concentration across customer categories.
- Residential:Single-family and multi-unit retrofits across Germany, France, and the United Kingdom drive volume. EU Green Deal mandates eliminate fossil-fuel alternatives in new construction, channeling replacement cycles toward electric options.
- Commercial:Office and retail properties in Dutch and Belgian urban cores deploy zone-level electric heating where district heating proves unavailable. Facility managers prioritize smart control integration for demand-response participation.
- Industrial:Workshop and warehouse applications in Poland and the Czech Republic favor high-wattage convection units. CE marking and Ecodesign compliance filter supplier selection in these price-sensitive markets.
- Hospitality:Hotels and wellness centers in Austria and Switzerland specify design-forward infrared panels. Premium margins attach to architectural specification channels and radiant comfort requirements.
Residential commands absolute volume; hospitality delivers steepest margin expansion.
Technology:
Control sophistication tiers separate compliance-grade products from premium positioning in Northern European markets.
- Smart Controls:Machine learning-enabled predictive heating converges with occupancy sensors and grid-responsive algorithms. Nordic utilities integrate these systems for aggregate load modulation during peak pricing events.
- Programmable Thermostats:Time-based temperature scheduling addresses efficiency requirements without connectivity premiums. French and German mid-market residential retrofits specify these for Ecodesign compliance.
- Energy-Efficient Systems:Ceramic core thermal mass and aluminum heat-exchange optimization meet escalating efficiency thresholds. CE marking protocols validate performance claims across member states.
- Traditional Heating:Basic thermostatic control dominates replacement demand in Southern European markets. Price sensitivity and installer familiarity sustain this category despite efficiency disadvantages.
Traditional heating retains installed base scale; smart controls gain share fastest.
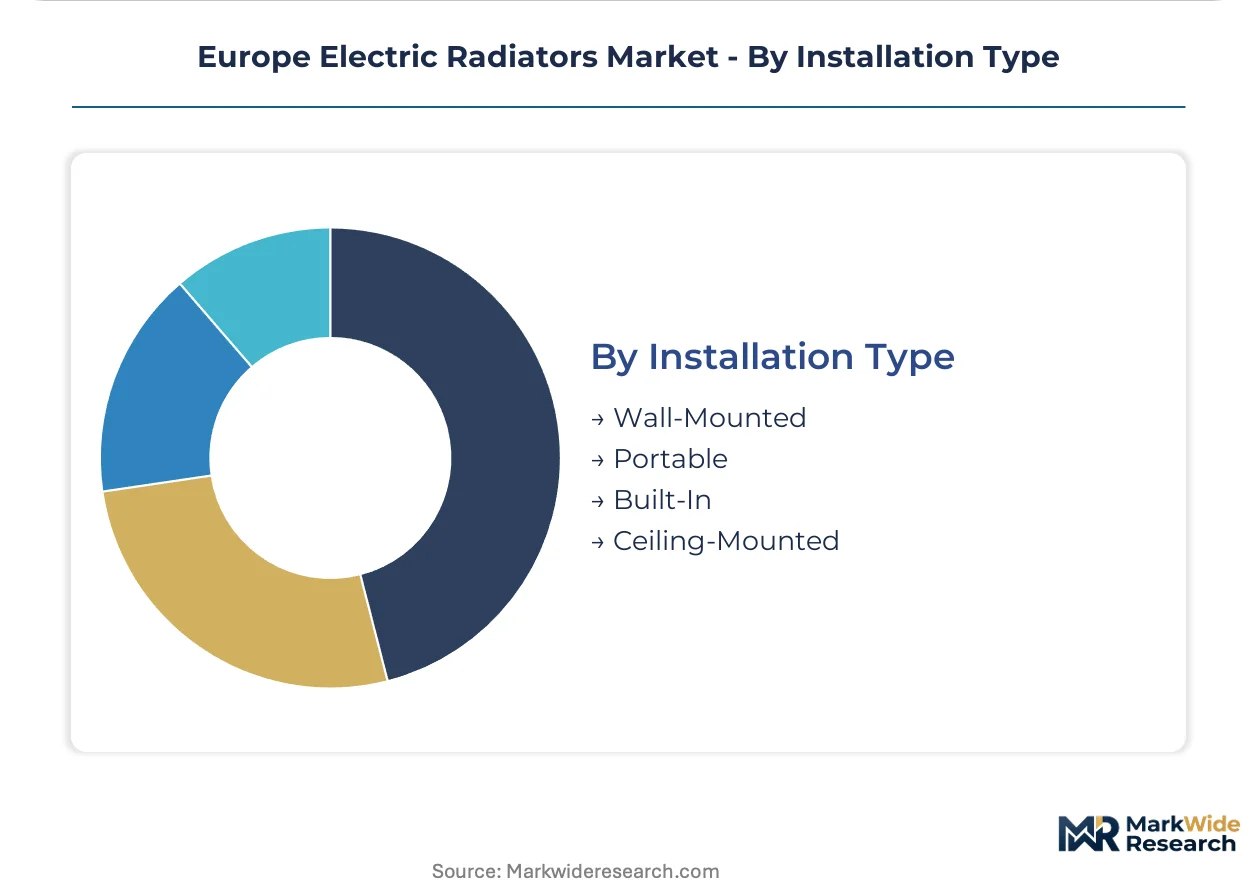
Installation Type:
Spatial constraints and permanence expectations determine hardware selection between fixed and mobile deployment.
- Wall-Mounted:Permanent bracket installation maximizes floor space in dense urban apartments. UK and German social housing retrofits specify these for tenant safety and durability.
- Portable:Castor-mounted units with plug-and-play commissioning serve seasonal and rental applications. Southern European markets retain demand for flexible heating without installation costs.
- Built-In:Recessed wall or floor integration delivers architectural minimalism. Premium residential developers in Switzerland and Austria specify these for passive house certification.
- Ceiling-Mounted:Overhead radiant panels address commercial wellness and industrial workspace applications. Infrared technology dominates this architectural configuration.
Wall-mounted installations anchor volume; built-in systems climb the fastest on design specification trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors European electric radiator manufacturing capacity, with fabrication clusters extending into Northern France and the Low Countries. National building codes and subsidy regimes create divergent adoption velocities across member states.
Germany
Residential retrofit contractors in North Rhine-Westphalia specify aluminum-ceramic panel radiators for multi-unit buildings lacking gas infrastructure. The Federal Ministry for Economic Affairs and Climate Action channels subsidies through the BEG (Federal Funding for Efficient Buildings) program. Manufacturing concentration in the Ruhr Valley supplies German and adjacent Benelux markets.
France
Urban cores in Île-de-France deploy zone-level electric heating where district heating proves unavailable. ANAH (National Housing Agency) renovation grants accelerate replacement cycles in social housing stock. Lyon-based distributors serve the Rhône-Alpes corridor with mid-range convection products.
United Kingdom
Social housing providers in Greater Manchester and the West Midlands favor wall-mounted permanent installations for tenant safety compliance. The Future Homes Standard phases out fossil-fuel heating in new construction from 2025. Glen Dimplex maintains Irish manufacturing capacity to anchor British Isles supply.
Poland
Building stock modernization programs in Warsaw and Kraków lag Western adoption curves, sustaining price-sensitive demand for portable and convection units. The Clean Air Program subsidizes heating replacements in single-family homes. Silesian fabricators compete on cost for Eastern European distribution.
Sweden
Rural electrification outpaces gas-to-hydrogen transitions in Scania and Västra Götaland, accelerating demand-response-enabled ceramic core systems. The Swedish Energy Agency mandates efficiency labeling aligned with EU Ecodesign. Stockholm-area utilities integrate aggregate load modulation for grid balancing services.
Europe Electric Radiators Market Vendor Landscape
Global majors compete with regional champions across distribution reach and retrofit specialization. The vendor base stratifies into three tiers: diversified heating conglomerates with broad European coverage, national specialists dominating domestic specification channels, and design-forward premium brands capturing architectural projects. Two archetypes predominate: manufacturers with captive aluminum-ceramic core production, and assemblers sourcing thermal mass components from Nordic suppliers. Competitive moves concentrate on smart control algorithm licensing and installer certification program expansion.
Among diversified heating conglomerates, Glen Dimplex anchors British Isles and Nordic supply through its Irish manufacturing base. Stelrad exemplifies deep specialization in panel radiator architectures, while Zehnder occupies a position within the design-forward tier commanding premium specification in Swiss and Austrian hospitality projects. These three represent distinct competitive vectors: geographic coverage, product architecture depth, and aesthetic differentiation.
| Leading Market Players |
|---|
| Glen Dimplex |
| Stelrad |
| Zehnder |
| Haverland |
| Elnur |
| Rointe |
| Electrorad |
| Jaga |
| Eskimo |
| Others |
Supply Flow & Price Mechanics
Smart control certification tiers split European electric radiators into sharply divergent pricing bands, with CE-marked algorithmic systems commanding premiums against basic thermostatic units while supply chains reorganize around aluminum-ceramic core fabrication clusters in Germany and Poland versus Nordic component sourcing for thermal mass integration.
Pricing Analysis
Aluminum ingot cost pass-through dominates manufacturer pricing decisions, with German fabricators adjusting panel radiator tags quarterly to LME movements. Three-tier pricing structure across premium, standard, and economy levels reflects Ecodesign tier certification, brand heritage, and smart control integration depth. Pricing pressure stems from heat pump substitution in new French and German construction, compressing electric radiator margins in efficiency-conscious segments. Polish and Romanian residential buyers exhibit highest price sensitivity, while Swiss hospitality specifiers absorb premium infrared panel costs without volume negotiation.
Supply Chain Analysis
Dual-sourcing mandates from Dutch and Belgian facility managers require qualification of at least two aluminum-ceramic core suppliers, driving German manufacturers to maintain parallel Nordic relationships despite higher logistics costs. Primary aluminum smelting concentrates in Norway and Iceland; fabrication clusters anchor in Germany's Ruhr Valley and Poland's Silesia region. Supply chain risk centers on carbon border adjustment exposure for energy-intensive aluminum imports. Distribution runs through direct procurement platforms displacing traditional wholesaler channels in multi-site commercial deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate in Eastern European retrofit markets where Polish and Romanian building modernization subsidies lag German BEG funding levels, creating margin capture potential for cost-optimized product lines.
For Market Incumbents: Anticipate heat pump encroachment in new construction by deepening captive aluminum-ceramic core production in Poland, insulating margin structure against Nordic supply cost volatility while accelerating smart control algorithm certification under the EU AI Act compliance timeline.
For New Entrants and Emerging Players: Launch via direct digital procurement platforms serving Dutch and Belgian multi-site retail operators, targeting standardized fleet deployment contracts in commercial real estate where incumbent wholesaler relationships remain sticky in residential channels.
For Investors and Strategic Acquirers: Consolidation pressure builds where design-forward specification brands lack captive thermal mass production, creating acquisition targets among Austrian and Swiss infrared panel specialists with architectural channel access but outsourced core supply. Long-term viability favors vertically integrated manufacturers with backward aluminum-ceramic control. The signal to watch is utility demand-response program expansion accelerating grid-responsive product premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Core Manufacturing Scale-Up | Captive production in Poland reduces carbon border exposure for German fabricators supplying Benelux markets. |
| Smart Control Algorithm Licensing | EU AI Act compliance frameworks create recurring revenue streams from Nordic utility demand-response partnerships. |
| Direct-to-Facility Procurement Platform | Dutch commercial real estate operators bypass wholesaler markups through manufacturer digital channels. |
| Eastern European Distribution Partnership | Polish and Romanian retrofit programs favor local assembly partnerships over Western direct sales. |
| Architectural Specification Channel Investment | Swiss and Austrian hospitality projects command premium margins for design-forward infrared panel systems. |
Methodological Framework
Direct dialogue with product development directors at German and Nordic manufacturers, procurement leads at Dutch facility management firms, installer networks across Poland and the UK, and regulatory affairs specialists tracking EU Ecodesign implementation anchored qualitative foundations. Secondary validation drew from CE marking databases, BEG and ANAH subsidy disbursement records, F-Gas Regulation implementation timelines, and aluminum trade flow customs data. Bottom-up channel volume estimates triangulated against top-down building stock electrification projections.
Analytical lenses combined bottom-up installer shipment tracking with top-down residential and commercial floor space electrification modeling across the projection horizon. Segmentation dimensions spanned product architecture, control technology tier, installation type, and national regulatory cluster. CAGRs derived from weighted scenario analysis of replacement cycle timing, subsidy program trajectories, and heat pump substitution elasticity. Forecast inputs incorporated utility demand-response program expansion rates and aluminum smelting capacity utilization in Norway and Iceland.
Forecast precision tightens around the base case; tail outcomes carry wider variance under electricity price volatility spikes or accelerated heat pump efficiency improvements. Deviation in EU Green Deal national implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Gas Insulated Switchgear Sales Market
Electrical Power Equipment
AC Drives Market
Electrical Power Equipment
Gas Insulated Switchgears (GIS) Market
Electrical Power Equipment
Magnetic Ballast Market
Electrical Power Equipment
South America Medium Voltage Switchgear Market
Electrical Power Equipment
Gas Circuit Breaker Market
Electrical Power Equipment
Latin America Hazardous Location Motor Starters Market
Electrical Power Equipment
Copper Ground Rod Market
Electrical Power Equipment
Alternator Regulator Market
Electrical Power Equipment
Taiwan Electric Power Equipment Market
Electrical Power Equipment
North America Air-Insulated Switchgear Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Cables Market
Electrical Power Equipment
Fault Circuit Indicator Market
Electrical Power Equipment
Transformer Oil Testers Market
Electrical Power Equipment
Global Duct Heaters Market
Electrical Power Equipment
Power Strip Market