
 Formalin Vials Market | 2026-2036
Formalin Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Formalin Vials Market Foresight
Aftermarket service revenue for vial re-sterilization and refurbishment is tilting margin pools away from virgin manufacturing. Thermo Fisher Scientific leverages its diagnostic distribution network to sustain recurring vial placements across North American hospital systems. Cardinal Health Inc. anchors its position through integrated supply contracts with regional pathology networks. Leica Microsystems Sales GmbH differentiates by bundling vial specifications with its histology instrumentation platforms.
Formalin vials are sealed containers engineered to preserve biological specimens in formaldehyde solution, typically manufactured from borosilicate glass or chemically resistant polymers with airtight closures preventing vapor leakage. Glass vials retain dominant share in high-throughput pathology labs where thermal stability and chemical inertness are non-negotiable, while plastic vials are capturing fastest growth in field-based veterinary diagnostics where weight reduction and breakage resistance outweigh premium material costs. Single-dose vials command elevated margins due to contamination-risk protocols in forensic analysis, whereas bulk packs serve cost-sensitive academic research laboratories with predictable volume forecasting.
FDA device regulations govern vial sterility claims in clinical diagnostic workflows, while EPA formaldehyde emission standards constrain manufacturing facility outputs and material selection. OSHA permissible exposure limits directly shape workplace handling requirements, driving demand for pre-sealed, reduced-vapor formulations in high-frequency lab environments. Stakeholders must monitor evolving chemical substance restrictions across multiple jurisdictions to anticipate reformulation investments and certification timelines.
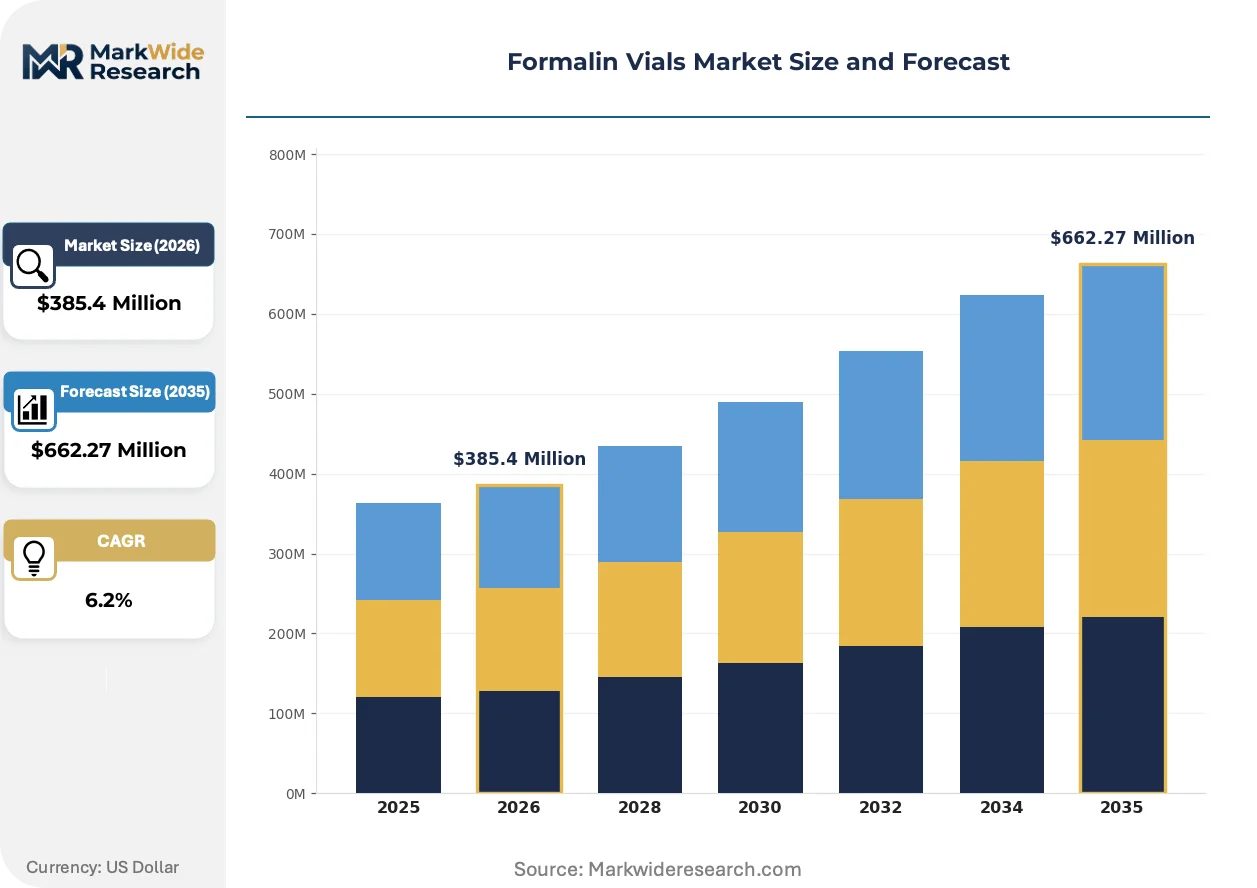
Market Dynamics
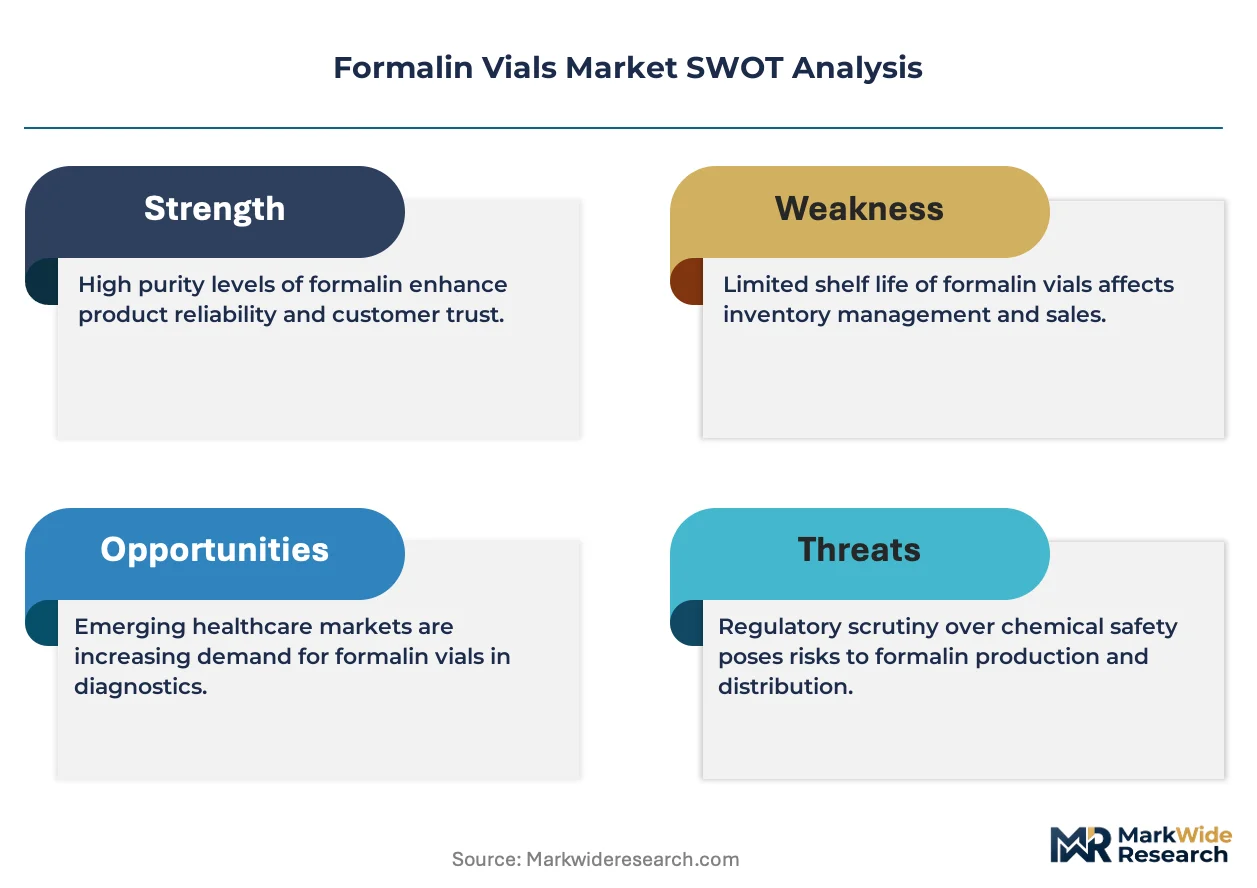
OSHA permissible exposure limits for formaldehyde are compressing allowable workplace concentrations, forcing manufacturers toward pre-sealed vial designs and vapor-barrier polymers that eliminate handling risk in high-frequency pathology environments.
Growth Catalysts
- Histology automation:Automated tissue processors in United States hospital labs require standardized vial dimensions and closure tolerances, creating pull for precision-manufactured containers.
- EPA emission controls:Manufacturing facility caps on formaldehyde release are concentrating production among facilities with advanced scrubbing infrastructure, advantaging scaled suppliers.
- Veterinary field diagnostics:Mobile necropsy services in Australia and Canada are adopting polymer vials for weight reduction during remote specimen collection.
Market Restraints
- Borosilicate glass supply concentration:Germany and China host the majority of pharmaceutical-grade glass furnace capacity, exposing buyers to energy cost volatility and logistics bottlenecks.
- Formaldehyde price volatility:Methanol feedstock fluctuations and natural gas input costs create margin pressure for solution-preparation operations.
- Polymer permeability limitations:Polypropylene and polyethylene vials exhibit measurable vapor transmission rates that disqualify them from long-term archival storage protocols.
Strategic Opportunities
- Point-of-care pathology:Brazil and Mexico are expanding regional diagnostic networks that lack cold-chain infrastructure, creating demand for ambient-temperature stable fixative systems.
- EU MDR harmonization:The Medical Device Regulation's quality system requirements are creating certification barriers that favor suppliers with existing notified body relationships.
- Digital pathology integration:Vial-embedded RFID tracking is converging with laboratory information systems to enable specimen chain-of-custody automation.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits for medical device classification are extending lead times for new market entrants by 12-18 months.
- Legacy instrument compatibility:Automated stainers and processors from established histology platforms require dimensional tolerances that constrain vial design innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Formalin Vials Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Vials, Plastic Vials, Amber Vials, Clear Vials, Sterile Vials Application: Pathology Labs, Research Laboratories, Forensic Analysis, Botanical Preservation, Veterinary Diagnostics End User: Medical Laboratories, Academic Institutions, Pharmaceutical Industries, Diagnostic Centers, Biotech Firms Packaging Type: Single-Dose Vials, Multi-Dose Vials, Bulk Packs, Screw Cap Vials, Snap Cap Vials |
| Companies Covered | Diapath S.p.A, Cardinal Health Inc., Leica Microsystems Sales GmbH, Histo-Line Laboratories Srl, Thermo Fisher Scientific, Genta Environmental Ltd., Carl Roth GmbH + Co. KG, Thomas Scientific, Global Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Formalin Vials Market Shifts & Advancements
Material science advances and regulatory stringency are jointly reshaping how formalin vials are specified, manufactured, and integrated into diagnostic workflows across hospital, research, and field environments.
Multi-layer co-extruded polymer vials incorporating ethylene vinyl alcohol barrier layers are migrating from niche veterinary applications into human clinical diagnostics. Reference laboratories in Germany and Japan are piloting these containers for high-throughput histology where breakage reduction outweighs material cost premiums. The shift is compressing glass vial dominance in segments where thermal stability requirements have relaxed.
REACH authorization requirements for formaldehyde under Annex XIV are compelling European manufacturers to document safe-use scenarios across the supply chain. Industrial consequence includes mandatory exposure scenario communication down to end-user laboratories. Academic research segments in France and the Netherlands are responding by consolidating purchases through distributors with established chemical safety compliance infrastructure.
Consolidated procurement through integrated delivery networks is displacing standalone purchasing by individual pathology departments. United States hospital systems are negotiating multi-year supply agreements that bundle vial specifications with fixative solutions and waste disposal services. This concentration is most visible in metropolitan healthcare clusters where laboratory services have centralized under regional health system umbrellas.
Formalin Vials Market Segmentation
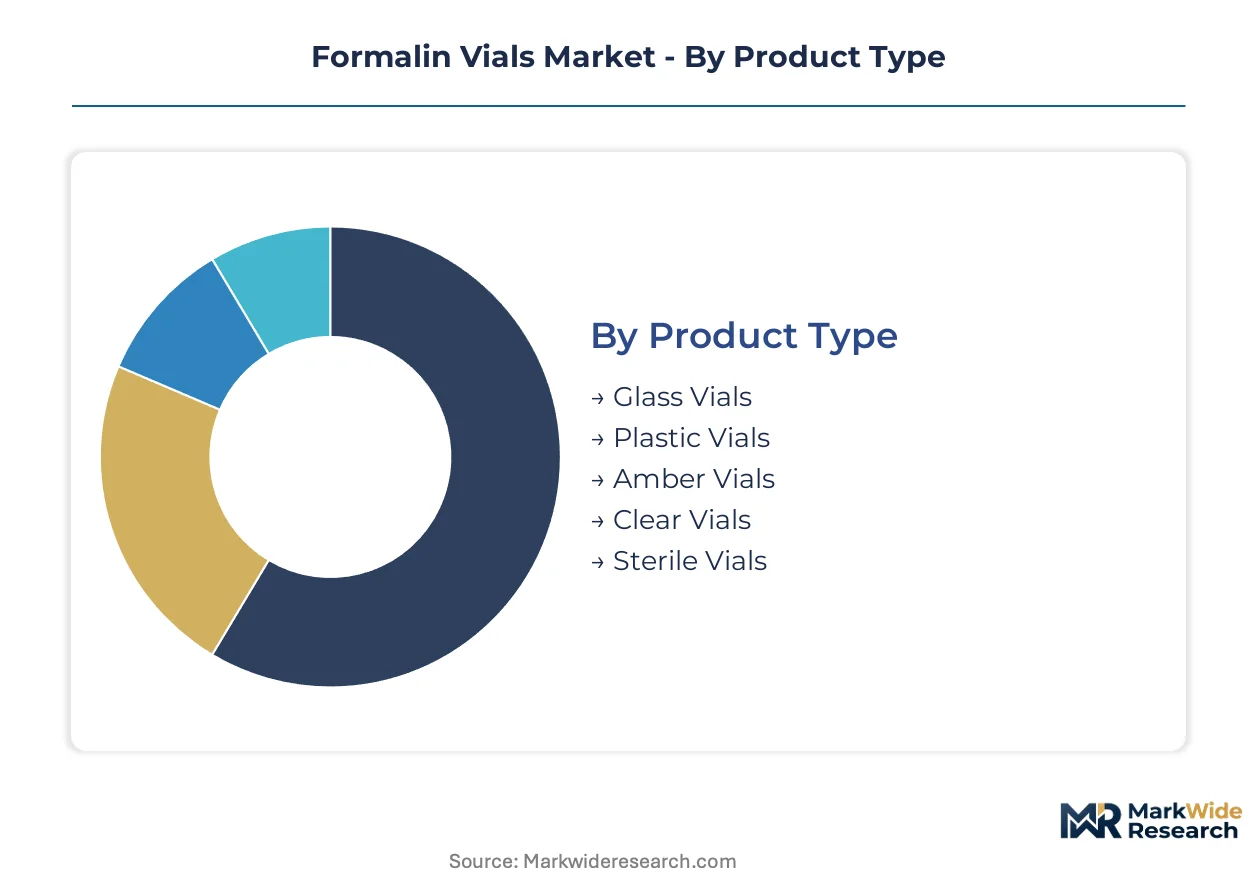
Formalin vial specifications diverge sharply across end-use environments, with material selection, closure design, and sterility claims calibrated to distinct handling protocols and regulatory exposures. Understanding these segment boundaries reveals where margin pools concentrate and which technical specifications command pricing premiums.
Product Type:
Mature glass formulations dominate high-throughput settings where thermal cycling resistance outweighs cost considerations, while emerging polymer technologies capture field applications prioritizing weight reduction and breakage tolerance.
- Glass Vials:Borosilicate construction delivers chemical inertness and thermal stability for automated tissue processors in United States hospital pathology labs. Demand concentrates in metropolitan healthcare clusters where histology automation requires dimensional precision and vapor-tight seals under repeated heating cycles.
- Plastic Vials:Polypropylene and polyethylene formulations reduce weight for mobile veterinary necropsy services in Australia and remote Canadian territories. Polymer permeability limitations restrict archival applications, but field diagnostics adoption is climbing fastest where cold-chain infrastructure is absent.
- Amber Vials:UV-blocking glass protects light-sensitive specimens in botanical preservation and certain forensic applications.
- Clear Vials:Unobstructed visual inspection supports rapid specimen verification in high-volume pathology workflows.
- Sterile Vials:Pre-sterilized packaging eliminates in-house autoclaving for biotech firms and diagnostic centers with ISO 13485 quality mandates.
Glass Vials retain volume leadership; Plastic Vials hold the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive hospital infrastructure from budget-constrained academic and field environments, with each tier demanding distinct performance specifications and compliance documentation.
- Pathology Labs:High-throughput histology operations in Germany and Japan require standardized vial dimensions compatible with automated stainers and processors. EPA emission controls and OSHA exposure limits drive preference for pre-sealed, reduced-vapor formulations in these high-frequency settings.
- Forensic Analysis:Chain-of-custody protocols in criminal investigations mandate single-dose vials with tamper-evident closures. Single-dose formats command elevated margins due to contamination-risk elimination and documentation requirements for evidence admissibility.
- Research Laboratories:Academic institutions in France and the Netherlands consolidate purchases through distributors with REACH-compliant chemical safety infrastructure. Bulk packs serve predictable volume forecasting with cost-sensitive procurement.
- Botanical Preservation:Herbarium and seed bank applications prioritize long-term archival stability over processing speed.
- Veterinary Diagnostics:Mobile necropsy services in Brazil and Mexico lack cold-chain infrastructure, creating demand for ambient-temperature stable fixative systems.
Pathology Labs anchor revenue concentration; Veterinary Diagnostics is gaining share fastest among application segments.
End User:
Customer type determines procurement channel and contract structure, with integrated delivery networks displacing standalone purchasing across consolidated healthcare systems.
- Medical Laboratories:Hospital-based pathology departments in United States metropolitan clusters negotiate multi-year supply agreements bundling vials with fixative solutions and waste disposal services.
- Academic Institutions:University research programs in Canada and Australia favor bulk procurement with flexible volume adjustments.
- Pharmaceutical Industries:GMP-compliant manufacturing operations require validated sterilization documentation and batch traceability.
- Diagnostic Centers:Independent reference laboratories prioritize RFID-embedded vials for laboratory information system integration.
- Biotech Firms:Early-stage companies in Cambridge and South San Francisco clusters demand small-lot flexibility with rapid specification changes.
Medical Laboratories dominate procurement volume; Diagnostic Centers show the most rapid adoption of smart-tracking formats.
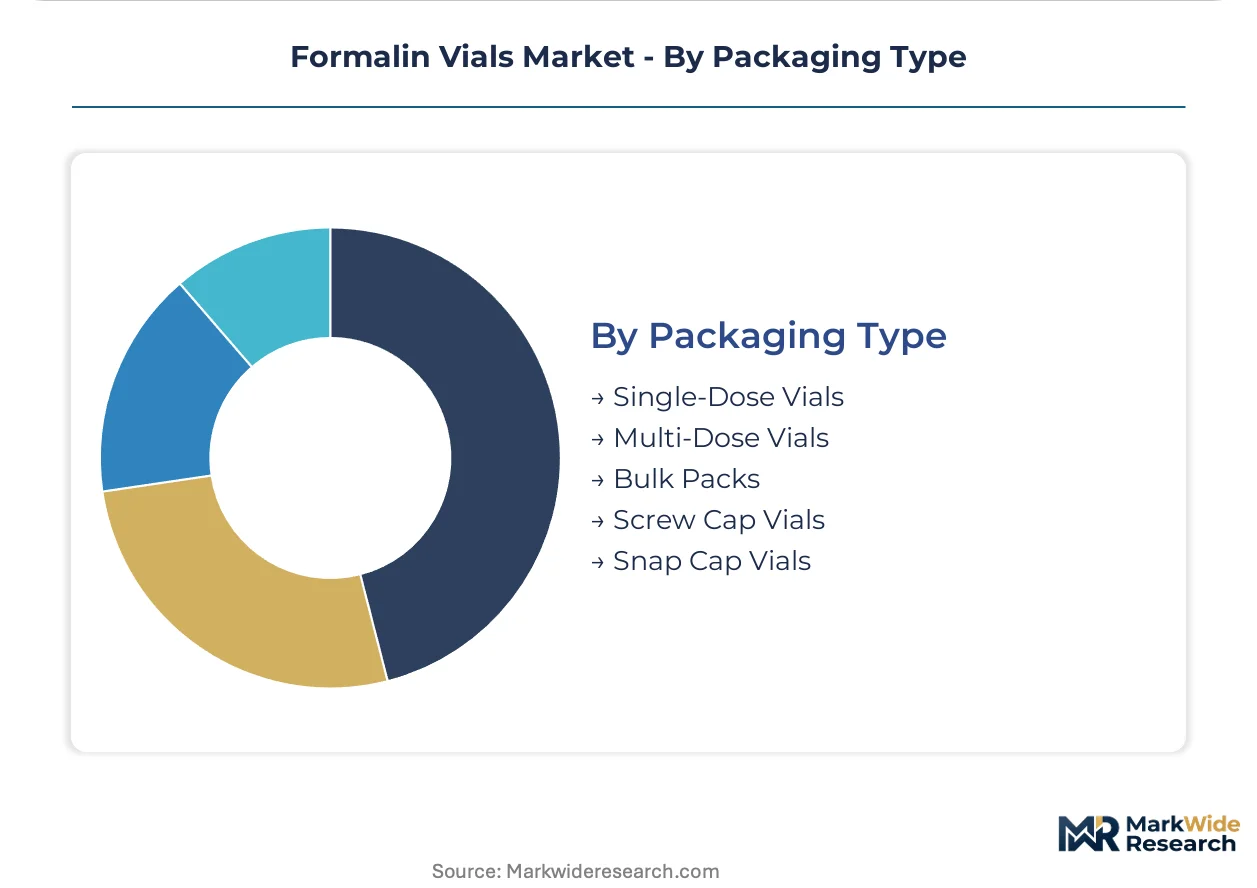
Packaging Type:
Volume scale separates premium single-unit formats from economy bulk configurations, with closure mechanism selection driven by automation compatibility and handling frequency.
- Single-Dose Vials:Pre-filled, pre-sealed units eliminate formaldehyde exposure during handling in OSHA-regulated United States hospital environments. Forensic and high-security applications pay substantial premiums for contamination-proof unit dosing.
- Multi-Dose Vials:Reclosable formats with vapor-barrier polymers serve medium-throughput research settings where specimen batching reduces per-unit cost.
- Bulk Packs:Academic laboratories with predictable volume forecasting capture lowest per-vial costs through pallet-scale procurement.
- Screw Cap Vials:Threaded closures enable resealing for interim specimen access in research protocols.
- Snap Cap Vials:One-handed operation supports high-frequency processing in automated workflow environments.
Bulk Packs retain volume leadership; Single-Dose Vials command the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Academic laboratories in France and the Netherlands consolidate purchases through REACH-compliant distributors, while United States hospital systems absorb premium pricing for OSHA-compliant pre-sealed formats without volume contraction.
United States
Metropolitan healthcare clusters in Boston, Houston, and the Research Triangle anchor histology automation adoption. OSHA permissible exposure limits for formaldehyde compress allowable workplace concentrations, forcing migration toward vapor-barrier polymers. Thermo Fisher Scientific leverages its diagnostic distribution network to sustain recurring vial placements across North American hospital systems.
Germany
Reference laboratories in Munich and Heidelberg pilot multi-layer co-extruded polymer vials for high-throughput histology. REACH authorization requirements for formaldehyde under Annex XIV mandate exposure scenario documentation down to end-user laboratories. Leica Microsystems Sales GmbH bundles vial specifications with its histology instrumentation platforms.
Japan
Tokyo and Osaka pathology labs demand standardized vial dimensions compatible with automated stainers. METI industrial standards shape material specifications for diagnostic device components. Dense diagnostic infrastructure concentrates procurement through integrated delivery networks serving regional health system umbrellas.
Brazil
Regional diagnostic networks in São Paulo and Minas Gerais lack cold-chain infrastructure, creating demand for ambient-temperature stable fixative systems. ANVISA medical device regulations govern vial sterility claims in clinical workflows. Mobile necropsy services adopt polymer vials for weight reduction during remote specimen collection.
Australia
Veterinary field diagnostics in Queensland and Western Australia prioritize breakage resistance over material cost premiums. The country's national pharmaceutical regulator enforces chemical safety standards for fixative handling. Mobile necropsy services drive fastest polymer vial adoption where cold-chain infrastructure is absent.
Formalin Vials Market Competitive Landscape
Capability concentration sits with diagnostic-integrated tiers; scale advantage sits with distribution-heavy players. The vendor base organizes around three strategic archetypes: instrumentation bundlers, supply chain integrators, and specialty chemical distributors. Consolidated procurement through integrated delivery networks favors suppliers with multi-year contract capacity. Two dominant competitive moves are portfolio diversification into fixative solutions and geographic expansion through distributor partnerships.
Among instrumentation-anchored specialists, Leica Microsystems Sales GmbH and Diapath S.p.A exemplify the bundling archetype that ties vial specifications to histology platforms. Cardinal Health Inc. and Thermo Fisher Scientific occupy positions on the supply-chain integration vector, leveraging distribution density to secure recurring placements. Histo-Line Laboratories Srl represents the specialty tier focused on pathology-specific configurations.
| Leading Market Players |
|---|
| Diapath S.p.A |
| Cardinal Health Inc. |
| Leica Microsystems Sales GmbH |
| Histo-Line Laboratories Srl |
| Thermo Fisher Scientific |
| Genta Environmental Ltd. |
| Carl Roth GmbH + Co. KG |
| Thomas Scientific |
| Global Scientific Inc. |
| Others |
Supply & Pricing Matrix
Borosilicate glass furnace capacity clustering in Germany and China anchors upstream margin capture, while downstream value pools concentrate with distributors bundling re-sterilization services and multi-year supply contracts. This upstream concentration forces vial manufacturers to absorb feedstock volatility or pass through via indexed pricing clauses in hospital system agreements.
Pricing Analysis
Aftermarket service revenue from vial re-sterilization and refurbishment programs now drives lifetime customer value beyond virgin manufacturing margins. Three-tier pricing structure across premium pre-sealed formats, standard screw-cap configurations, and economy bulk packs separates OSHA-compliant hospital systems from cost-sensitive academic laboratories. Pricing pressure stems from methanol feedstock fluctuations and natural gas input costs compressing solution-preparation margins. Academic institutions in France and the Netherlands exhibit highest price sensitivity through consolidated distributor purchasing, while United States metropolitan hospital clusters absorb premium pricing for vapor-barrier polymer formats without volume contraction.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for pathology network procurement, with supply-chain finance facilities emerging among distributors serving consolidated healthcare systems. Manufacturing draws from borosilicate glass feedstock concentrated in Germany and China, polymer resin suppliers in the United States and Saudi Arabia, and closure component specialists in Japan and Switzerland. Single-source vulnerability sits with pharmaceutical-grade glass furnace capacity exposed to European energy cost volatility. Distribution runs through integrated delivery networks displacing standalone pathology department purchasing across regional health system umbrellas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formalin vial demand is accelerating through histology automation and REACH-driven compliance consolidation, with material science advances in multi-layer barrier polymers creating a technological inflection point against legacy glass dominance.
For Market Incumbents: Build regulatory certification moats through accelerated ISO 13485 quality management system investments and notified body relationship deepening ahead of EU MDR harmonization deadlines. Threat from polymer barrier technology disruption demands backward integration into ethylene vinyl alcohol co-extrusion capabilities or exclusive supply agreements with materials innovators. Channel control levers include multi-year fixative-vial-waste bundling contracts with United States integrated delivery networks to lock out specialist competitors. For New Entrants and Emerging Players: Build out veterinary field diagnostics presence in Brazil and Mexico where cold-chain infrastructure gaps create ambient-temperature stable fixative demand unmet by incumbent hospital-focused suppliers. White-space targets include RFID-embedded smart vials for digital pathology integration and point-of-care regional networks lacking automated processor compatibility requirements. Go-to-market angle centers on mobile necropsy service partnerships with weight-optimized polymer vial configurations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across polymer barrier manufacturing as co-extrusion equipment costs decline and scale economies emerge, improving returns for mid-cap specialists against glass-dominated legacy players. Long-term viability over the next decade favors suppliers with dual-material capabilities and diagnostic instrument bundling relationships. Acquisition target archetype includes notified body-certified European distributors with REACH-compliant chemical safety infrastructure. Signal to watch is ANVISA medical device regulation tightening in Brazil accelerating formal import substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Layer Barrier Polymer Scale-Up | Ethylene vinyl alcohol co-extrusion investments capture glass-to-plastic substitution in high-throughput histology labs. |
| RFID-Enabled Vial Development | Embedded tracking convergence with laboratory information systems enables specimen chain-of-custody automation. |
| Integrated Delivery Network Contracting | Multi-year fixative-vial-waste bundling secures recurring placement across United States hospital system umbrellas. |
| REACH Compliance Infrastructure Investment | Exposure scenario documentation capabilities capture academic laboratory consolidation in France and the Netherlands. |
| Veterinary Field Diagnostics Expansion | Mobile necropsy partnerships in Australia and Canada exploit polymer weight advantages where cold-chain is absent. |
Research Methodology
Initial hypotheses were tested against primary input from pathology lab directors, histology instrumentation specialists, hospital GPO contracts managers, and veterinary field diagnostic operators and refined through secondary validation. Primary interviews explored tissue fixation protocol evolution, automation compatibility requirements, and procurement channel migration patterns. Secondary sources included FDA device regulation filings, EPA formaldehyde emission compliance databases, OSHA permissible exposure limit documentation, and European ECHA REACH authorization records. Bottom-up vial volume modeling by material type and application was triangulated against top-down fixative solution market sizing.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by product type, application environment, end-user procurement channel, and regional regulatory cluster. CAGRs were derived from installed base expansion of automated tissue processors, histology automation adoption curves, and veterinary field service growth trajectories. Industry-specific forecast inputs incorporated methanol feedstock price correlation models and glass furnace capacity utilization assumptions.
Stress conditions across formaldehyde price volatility bands, European energy cost scenarios, and polymer barrier technology adoption curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline stability and instrument platform compatibility standards. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
South America Isoamyl Acetate Market
Chemicals
Trichloroisocyanuric Acid Market
Chemicals
Asia-Pacific Acetic Acid Market
Chemicals
Cupric Chloride Market
Chemicals
Fluorine Derivatives Market
Chemicals
Global Oxo Alcohols Market
Chemicals
Benzoyl Alcohol Market
Chemicals
Aluminium Chloride Market
Chemicals
Lead Tetracetate Market
Chemicals
Europe Flame Retardant Chemicals Market
Chemicals
Potassium Permanganate Market
Chemicals
Uranyl Carbonate Market
Chemicals
Hypophosphorous Acid Market
Chemicals
Ammonia Market
Chemicals
N-Propanol Market
Chemicals
US Methanol Market