
 Cupric Chloride Market | 2026-2036
Cupric Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Cupric Chloride Market Analysis
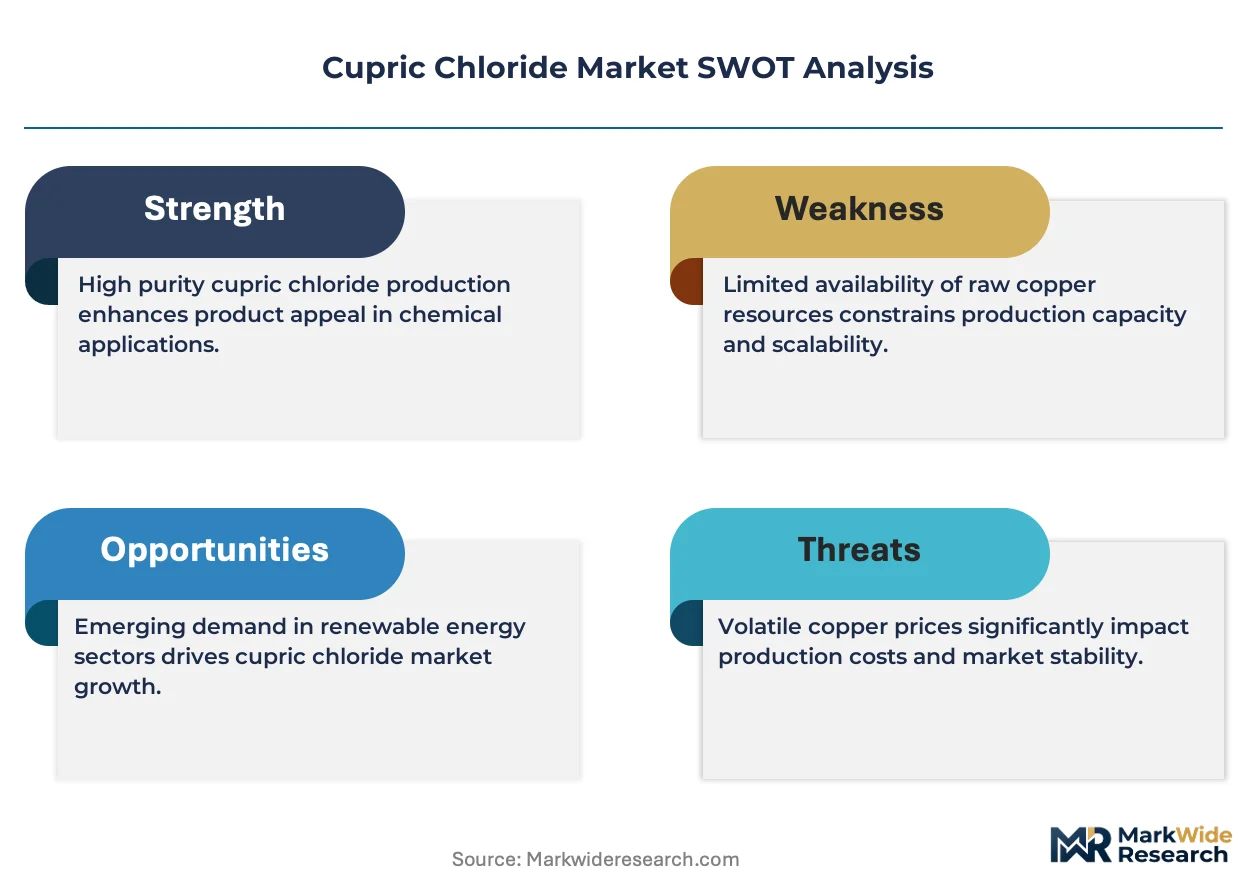
Aluminum chloride substitution in certain etching applications is hardening price competition at the commodity end of cupric chloride supply. BASF SE leverages its integrated precursor network to sustain margin on high-purity dihydrate grades. Dow Chemical Company anchors North American supply through captive chlorine sourcing and regional distribution density.
Cupric chloride is a copper(II) salt with the formula CuCl₂, typically supplied as anhydrous brown solid or blue-green dihydrate crystals with melting points near 498°C and 100°C respectively; manufacturers produce it via copper oxidation with chlorine or hydrochloric acid, and industrial buyers deploy it primarily as an oxidizing agent and copper source in metallurgical and chemical processes. Dihydrate grades dominate volume shipments due to safer handling profiles and broader compatibility with aqueous process lines, while anhydrous variants command premium positioning in moisture-sensitive catalyst applications. Electronics end-use consumption leads absolute demand as PCB etching cycles intensify, though water treatment applications show the fastest structural expansion amid tightening discharge regulations.
EPA hazardous waste rules and OSHA permissible exposure limits shape US manufacturing compliance costs, while REACH registration requirements in Europe restrict non-compliant import channels. China's GB standards and MEE environmental enforcement drive domestic producer consolidation and quality upgrading. Stakeholders must monitor regulatory divergence between jurisdictions to optimize supply chain routing and certification investments.
Market Dynamics
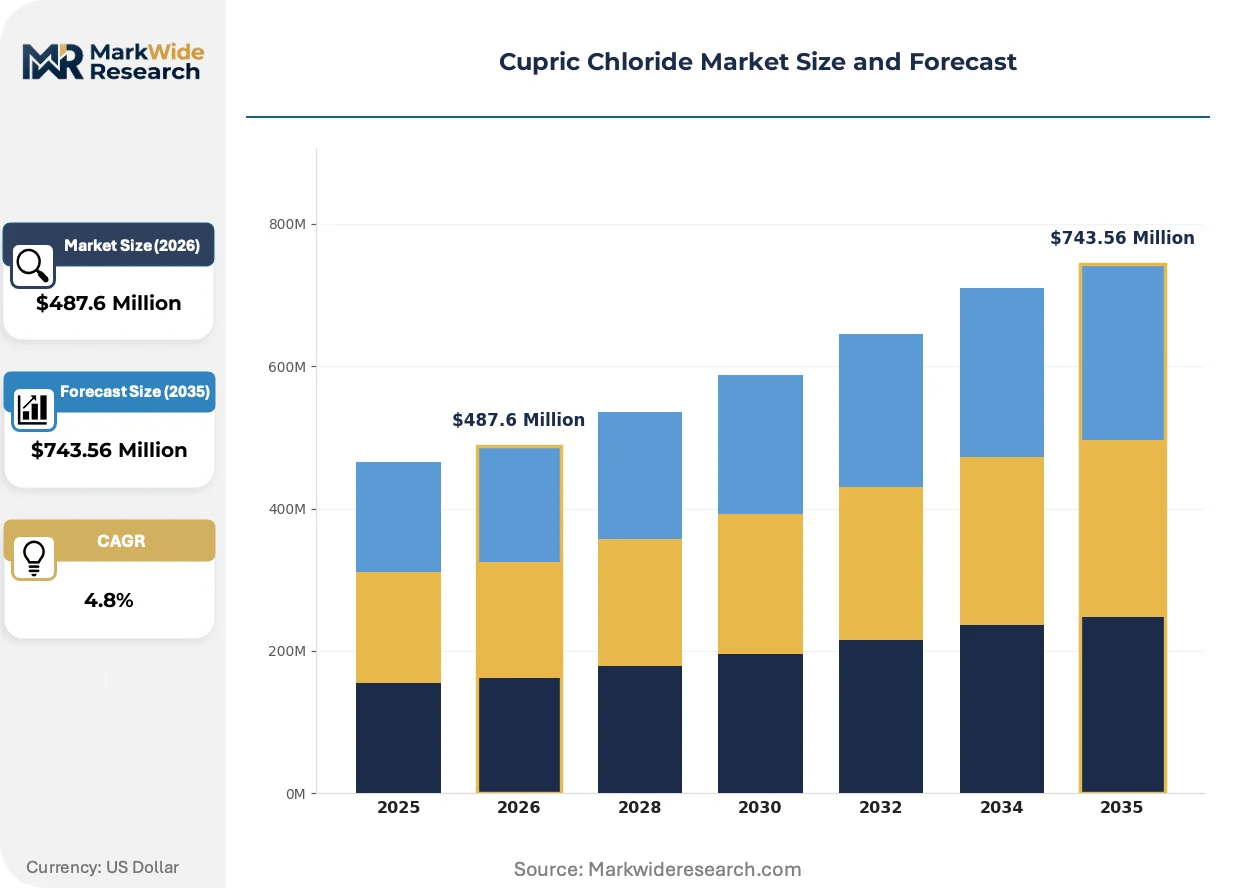
Printed circuit board fabrication cycles are intensifying copper etching demand, while REACH compliance in Europe and China's MEE enforcement are simultaneously tightening chemical handling standards and consolidating domestic producer bases.
Growth Catalysts
- Electronics manufacturing corridors:China's Shenzhen and Dongguan clusters anchor PCB etching demand, drawing concentrated cupric chloride procurement from regional chemical distributors.
- Water treatment mandates:EPA hazardous waste rules and tightening discharge regulations across US industrial zones are expanding cupric chloride deployment in wastewater oxidation applications.
- REACH registration requirements:European ECHA compliance is filtering non-compliant import channels, creating protected demand pockets for certified dihydrate suppliers.
Market Restraints
- Aluminum chloride substitution:Commodity etching applications face hardening price competition as buyers switch to lower-cost oxidizing agents in non-precision PCB segments.
- Chlorine feedstock volatility:Captive chlorine sourcing advantages concentrate among integrated chlor-alkali producers, squeezing standalone cupric chloride manufacturers.
- Anhydrous handling limitations:Moisture-sensitive catalyst applications require specialized packaging and storage infrastructure that restricts addressable market expansion.
Strategic Opportunities
- India's electronics PLI scheme:Production-linked incentives for semiconductor and PCB manufacturing are building new demand nodes in Gujarat and Tamil Nadu corridors.
- High-purity catalyst grades:Petrochemical and pharmaceutical oxidation processes are creating premium positioning for sub-ppm impurity dihydrate specifications.
- Closed-loop regeneration services:Spent etchant recovery and copper reclamation models are integrating with large PCB fabricators to capture recurring chemical service contracts.
Industry Challenges
- Certification timeline compression:Multi-jurisdiction REACH, EPA, and GB standard compliance requires parallel documentation streams that strain smaller producers' regulatory affairs capacity.
- Legacy aqueous process integration:Anhydrous grade adoption in moisture-sensitive catalyst lines demands retrofitting of existing dissolution and metering infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cupric Chloride Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anhydrous, Dihydrate, Liquid, Powder End User: Electronics, Agriculture, Water Treatment, Chemical Manufacturing Application: Electroplating, Fungicide, Catalyst, Wood Preservation Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | BASF SE, Dow Chemical Company, Brenntag North America, Tinco Group of Companies, SQM, Sigma Aldrich, Real Metal Chem, VWR International, Parikh, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cupric Chloride Market Emerging Trajectories
Process intensification in electronics fabrication and chemical recovery systems is reshaping how cupric chloride is supplied, consumed, and regenerated across industrial value chains.
Membrane electrolysis-based copper dissolution is integrating into high-volume PCB manufacturing lines, replacing traditional acid-chlorine batch oxidation. Taiwan and South Korean electronics foundries are adopting continuous-feed systems that reduce etchant variation and extend bath life. This integration is compressing spot market demand for standard-grade material while expanding long-term chemical service contracts.
REACH authorization procedures for copper compounds are tightening substance evaluation protocols across European manufacturing zones. Downstream users must now document substitution analysis and socioeconomic justification for continued cupric chloride deployment in non-essential applications. Specialty catalyst and fine chemical producers are most affected, accelerating migration toward pre-registered supply channels with full dossier compliance.
Consolidated procurement through integrated chemical distributors is displacing fragmented spot purchasing in North American electronics corridors. Large PCB fabricators in Texas and California are negotiating multi-year supply agreements with bundled technical service and waste handling provisions. This concentration is most visible in high-volume dihydrate consumption, where price transparency and logistics integration outweigh grade flexibility.
Cupric Chloride Market Segmentation
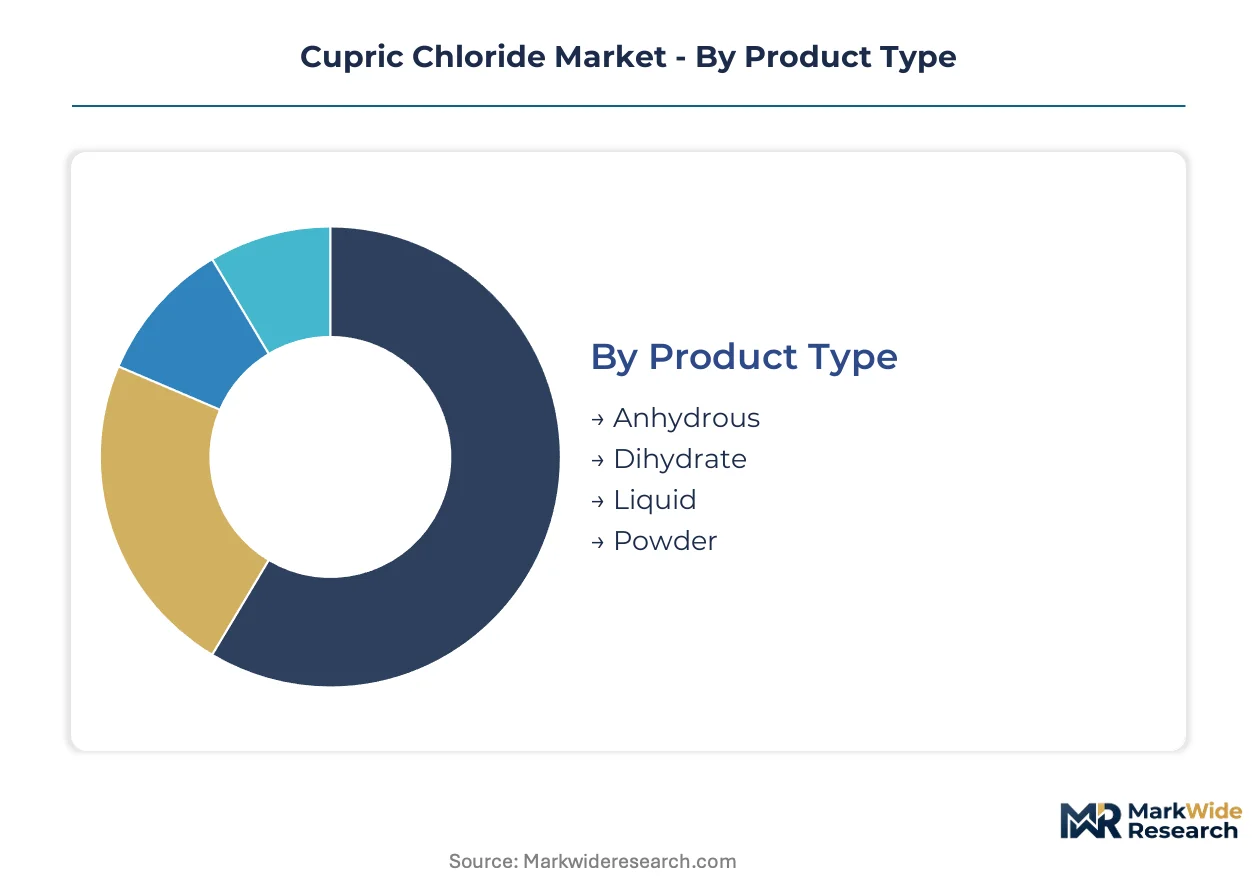
Cupric chloride procurement patterns diverge sharply across specification grades and end-use requirements. Electronics fabricators, agricultural formulators, and water treatment operators each impose distinct purity thresholds, packaging formats, and regulatory documentation demands that reshape supplier positioning.
Product Type:
Dihydrate crystals and anhydrous solids anchor the specification axis, with liquid and powder variants serving niche handling requirements.
- Anhydrous:Brown hygroscopic solid with 498°C melting point demands sealed packaging and inert atmosphere handling. Moisture-sensitive catalyst applications in pharmaceutical oxidation processes concentrate demand in Switzerland and Germany's fine chemical corridors, constrained by specialized storage infrastructure costs.
- Dihydrate:Blue-green crystalline form with safer aqueous dissolution profiles dominates volume shipments. PCB etching cycles in China's Shenzhen-Dongguan manufacturing belt drive procurement, supported by broader compatibility with existing process line infrastructure.
- Liquid:Pre-dissolved aqueous solutions eliminate on-site dissolution steps for small-scale water treatment operators.
- Powder:Fine-ground particulate serves agricultural fungicide blending where rapid tank dispersion matters.
Mature deployment sits with Dihydrate. Newer deployment is concentrated in Anhydrous.
End User:
Cost tier differentiation separates precision-grade consumers from commodity-volume buyers across industrial verticals.
- Electronics:PCB fabricators and semiconductor etching operations impose sub-ppm impurity specifications. Taiwan and South Korean foundries are consolidating procurement through multi-year chemical service contracts with bundled waste recovery provisions.
- Water Treatment:Municipal and industrial wastewater oxidation applications are expanding most quickly amid tightening EPA discharge rules across US manufacturing zones. Operators prioritize standardized dihydrate grades with consistent active chlorine content.
- Agriculture:Fungicide formulators blend cupric chloride into copper-based crop protection products, with demand clustering in Brazil's soybean belt and India's horticulture regions.
- Chemical Manufacturing:Petrochemical oxidation catalyst and dye intermediate producers source high-purity grades through pre-registered REACH-compliant channels.
Electronics commands premium pricing tiers. Water treatment is gaining share fastest on regulatory tailwinds.
Application:
Application-level demand concentrates where copper ion delivery or oxidation potential solves specific process constraints.
- Electroplating:Copper deposition baths in automotive and decorative finishing operations use controlled-purity solutions. German and Japanese plating shops emphasize bath stability over raw material cost.
- Catalyst:Petrochemical oxidation and pharmaceutical synthesis routes deploy anhydrous grades. ECHA authorization procedures are filtering non-compliant supply channels across European specialty chemical producers.
- Fungicide:Agricultural copper formulations leverage cupric chloride's solubility for foliar spray applications.
- Wood Preservation:Pressure-treatment facilities in North American construction supply chains use copper-based biocide solutions.
Electroplating maintains stable offtake. Catalyst applications are climbing the fastest on pharmaceutical process intensification.
Distribution Channel:
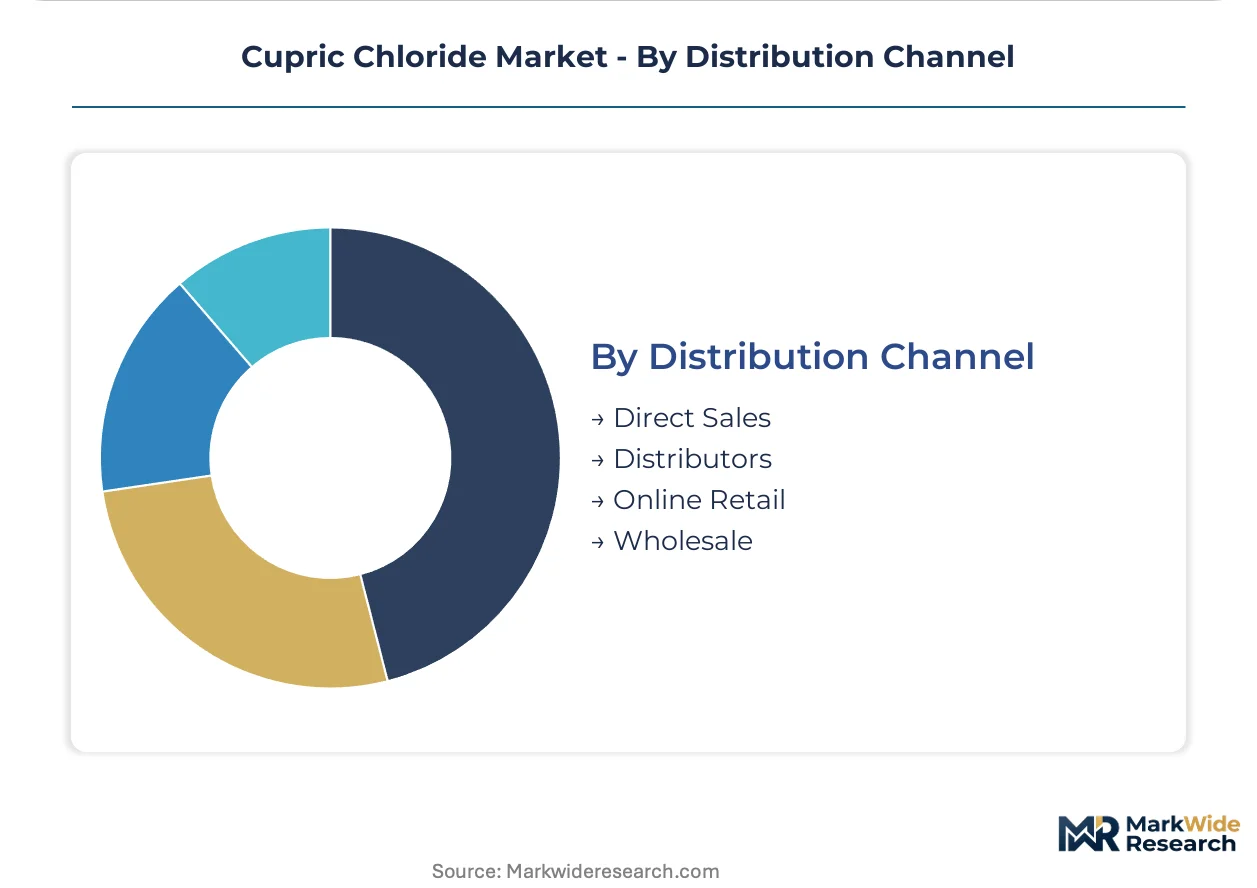
Customer scale and technical service requirements determine channel selection across procurement workflows.
- Direct Sales:Large PCB fabricators and chemical manufacturers negotiate volume contracts with producers. BASF SE and Dow Chemical Company anchor this channel through captive technical service teams.
- Distributors:Regional chemical distributors consolidate fragmented demand from mid-scale water treatment and agricultural formulators. North American electronics corridors show visible procurement concentration through this channel.
- Online Retail:Small-scale laboratory and R&D procurement flows through specialized chemical supply platforms.
- Wholesale:Agricultural supply cooperatives and commodity chemical traders handle fungicide-grade volume movements.
Direct sales lock in high-volume electronics demand. Distributor consolidation is displacing spot purchasing in mid-market segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's electronics manufacturing clusters in Gujarat and Tamil Nadu are attracting concentrated cupric chloride procurement through production-linked incentive corridors. Shenzhen's special economic zone anchors China's PCB etching demand. Germany's REACH-registered supply channels filter non-compliant imports across European specialty chemical producers.
China
Shenzhen and Dongguan manufacturing belts drive dihydrate consumption for high-volume PCB fabrication cycles. MEE environmental enforcement consolidates domestic producers and upgrades quality standards. Guangdong Province chemical distributors coordinate just-in-time delivery to electronics foundries.
United States
Texas and California PCB fabricators negotiate multi-year supply agreements with bundled waste recovery provisions. EPA hazardous waste rules and OSHA exposure limits shape manufacturing compliance costs. Gulf Coast chlor-alkali integration secures captive chlorine feedstock for regional producers.
Germany
Fine chemical corridors in Switzerland and Germany concentrate anhydrous grade demand for moisture-sensitive pharmaceutical oxidation. ECHA REACH authorization procedures tighten substance evaluation protocols. BASF SE leverages integrated precursor networks from Ludwigshafen operations.
India
Gujarat and Tamil Nadu electronics manufacturing corridors build new demand nodes through semiconductor PLI schemes. BIS standards and DGFT import regulations filter quality compliance. Regional chemical distributors consolidate procurement for mid-scale water treatment operators.
South Korea
Electronics foundries adopt continuous-feed etching systems that extend bath life and reduce spot market demand. MFDS chemical substance registration aligns with REACH-equivalent protocols. Busan-Ulsan industrial clusters anchor multi-year chemical service contracts.
Cupric Chloride Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated chlor-alkali producers commanding upstream cost advantages while standalone formulators compete on service bundling. The vendor base organizes around three archetypes: captive chlorine-integrated majors, high-purity specialty distributors, and regional regeneration service operators. Consolidation pressures concentrate among non-integrated manufacturers facing feedstock volatility. Competitive moves center on backward integration into chlorine sourcing and geographic expansion through distributor acquisition.
Among Germany-based chemical majors, BASF SE exemplifies the integrated archetype through captive precursor networks. Dow Chemical Company anchors North American positioning through regional distribution density and Gulf Coast chlorine integration. Brenntag North America occupies the specialty distributor tier, consolidating fragmented demand from mid-scale electronics and water treatment operators.
| Leading Market Players |
|---|
| BASF SE |
| Dow Chemical Company |
| Brenntag North America |
| Tinco Group of Companies |
| SQM |
| Sigma Aldrich |
| Real Metal Chem |
| VWR International |
| Parikh |
| Others |
Supply Flow & Price Mechanics
Membrane electrolysis-based copper dissolution is displacing traditional acid-chlorine batch oxidation across high-volume PCB manufacturing lines, compressing spot market demand for standard-grade material while concentrating procurement power among integrated chlor-alkali producers with captive feedstock control.
Pricing Analysis
Volume shipments of dihydrate crystals trade at commodity margins while anhydrous grades capture premium positioning. Three-tier pricing structure across pharmaceutical-grade, electronics-grade, and agricultural-grade specifications reflects purity certification and REACH dossier completeness. Cost compression in commodity etching applications stems from aluminum chloride substitution in non-precision PCB segments. Water treatment operators exhibit highest price sensitivity due to standardized active chlorine requirements, whereas pharmaceutical oxidation buyers prioritize batch consistency over unit economics.
Supply Chain Analysis
REACH registration and GB standard compliance function as qualification gates that filter non-certified suppliers from European and Chinese procurement channels. Manufacturing concentrates in China, Germany, and the United States, with Guangdong Province and Ludwigshafen anchoring regional production hubs. Chlorine feedstock, copper scrap, and hydrochloric acid constitute primary input dependencies. Single-source vulnerability runs through integrated chlor-alkali producers controlling captive chlorine supply. Distribution runs through consolidated chemical distributors in North America and direct mill-to-factory contracts in East Asian electronics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where chlorine feedstock security and regeneration service capabilities determine margin sustainability. Players are pursuing backward integration into chlor-alkali operations to neutralize feedstock volatility.
For Market Incumbents: Cement chlorine feedstock security through Gulf Coast chlor-alkali partnerships or Ludwigshafen-style integrated precursor networks. Lock in multi-year chemical service contracts with large PCB fabricators in Texas and California, bundling waste recovery and technical support to defend against aluminum chloride substitution in commodity etching tiers. For New Entrants and Emerging Players: E-commerce laboratory supply platforms offer the lowest-friction entry vector for small-scale R&D and pilot-scale procurement. Target India's Gujarat and Tamil Nadu electronics corridors where PLI-driven capacity expansion outpaces established distributor coverage. Lead with closed-loop regeneration services to differentiate from commodity spot suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical majors seeking regional distribution density. Five-to-ten year viability hinges on REACH dossier completeness and MEE environmental compliance positioning. Monitor ECHA authorization procedure timelines for copper compounds as the critical inflection signal for specialty grade demand compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali | Captive chlorine sourcing neutralizes feedstock volatility for integrated producers like Dow Chemical Company. |
| Closed-Loop Regeneration Services | Spent etchant recovery contracts with Taiwan foundries convert transactional sales into recurring revenue streams. |
| REACH Dossier Investment | Full ECHA compliance unlocks protected demand pockets among German fine chemical producers. |
| Regional Distributor Acquisition | Consolidation of North American mid-market channels mirrors Brenntag's electronics corridor positioning. |
| High-Purity Grade Capacity Addition | Sub-ppm impurity specifications serve pharmaceutical oxidation processes in Switzerland and Germany. |
Methodological Framework
Trade databases, SEC 10-K filings, and ECHA registration dossiers formed the secondary backbone, cross-referenced with primary interviews involving chlor-alkali plant managers, PCB procurement leads at Taiwanese foundries, European specialty chemical technical directors, and North American chemical distribution channel partners. Bottom-up and top-down triangulation validated volume estimates against customs data and downstream consumption patterns.
Bottom-up modeling anchored the analytical lens, aggregating segment-level demand across grade tier, end-use industry, and regional production hub. Top-down macroeconomic cross-checks incorporated electronics fabrication cycle intensity and water treatment regulatory enforcement trajectories. CAGRs derived from fitted trend extrapolation moderated by capacity constraint analysis and substitution elasticity estimates for aluminum chloride in commodity applications.
The model holds under stable chlorine feedstock availability and continued REACH authorization timelines; deviation in ECHA substance evaluation protocols or MEE enforcement intensity would shift specialty grade demand projections. A model refresh is warranted upon material change in copper compound regulatory classification or chlor-alkali capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Benzalkonium Bromide Market
Chemicals
Chloroplatinic Acid Market
Chemicals
Isopropyl Alcohol (IPA) Market
Chemicals
Thiourea Market
Chemicals
Carbon Tetrachloride Market
Chemicals
Calcium Carbide Market
Chemicals
Photographic Film Processing Chemicals Market
Chemicals
Cetostearyl Alcohol Market
Chemicals
Global Aluminum Hydroxide Market
Chemicals
Desalination Chemicals Market
Chemicals
Sulfuric Acid Market
Chemicals
Fungicide Active Ingredients Market
Chemicals
Anhydrides Market
Chemicals
Roofing Chemical Market
Chemicals
Global Syringaldehyde Market
Chemicals
China Methanol Market