
 US Methanol Market | 2026-2036
US Methanol Market Size, Share, and Industry Trends Forecast 2026-2036
US Methanol Market Insights
The EPA's Renewable Fuel Standard is rebalancing methanol demand toward low-carbon fuel pathways. Methanex Corporation leverages its Gulf Coast terminal network to sustain import dominance. Celanese Corporation anchors its Texas production complex to supply captive acetic acid operations. Southern Chemical Corporation differentiates through specialized logistics and distribution infrastructure.
Methanol is a light, volatile alcohol (CH3OH) produced primarily via steam methane reforming of natural gas, serving as a versatile chemical building block and alternative fuel carrier. Steam methane reforming remains the dominant production technology, though CO2 hydrogenation is gaining traction as carbon capture economics improve. Chemical feedstock applications occupy the largest volume share, while fuel cells represent the fastest-growing end-use segment driven by hydrogen economy investments. Methyl tertiary butyl ether production maintains steady demand from gasoline blending requirements.
FERC pipeline safety regulations and EPA emissions standards jointly shape production facility siting and operational compliance costs for US methanol producers. OSHA process safety management rules govern handling protocols at refining and derivative manufacturing sites. Stakeholders must monitor the trajectory of federal hydrogen hub investments and state-level low-carbon fuel standards to anticipate methanol's evolving role in the domestic energy transition.
Market Dynamics
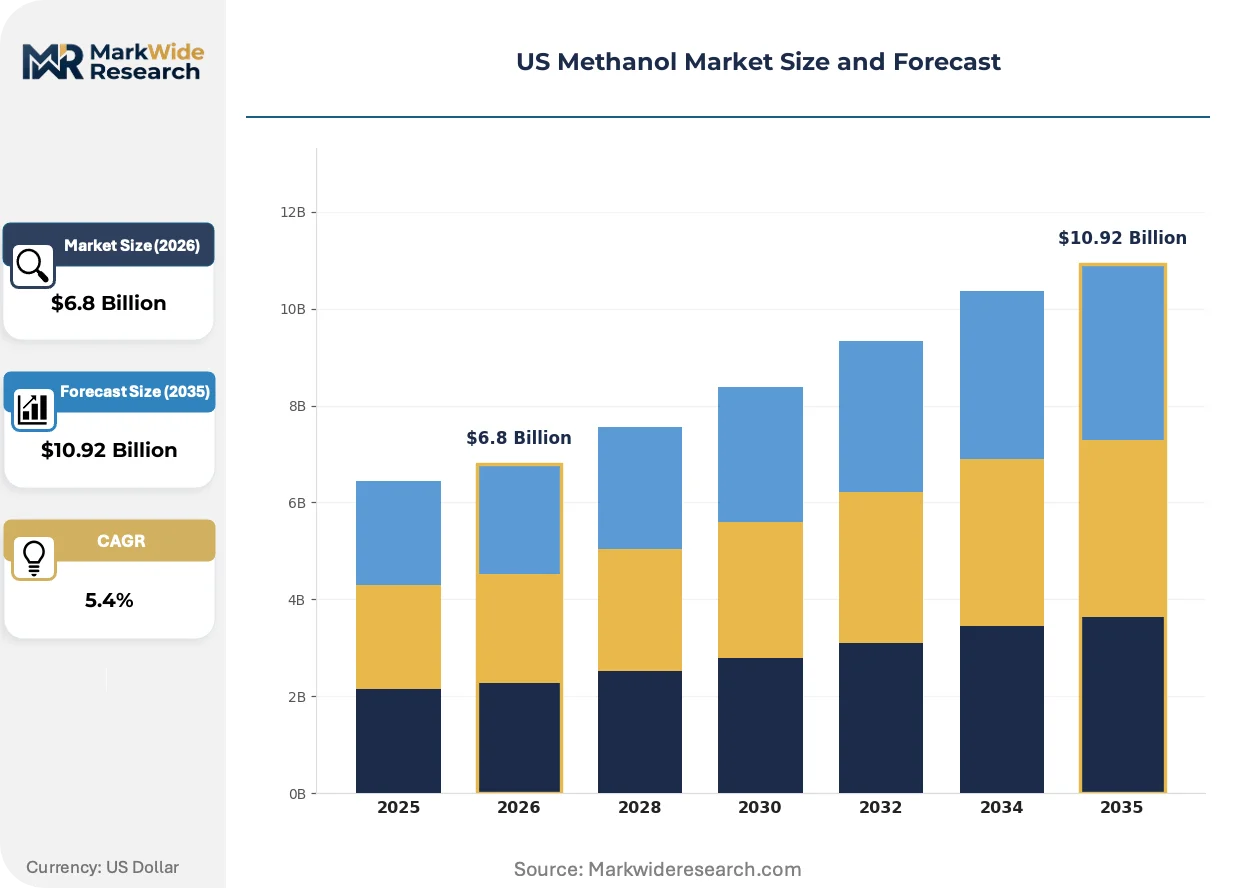
The US methanol market is rebalancing around EPA Renewable Fuel Standard mandates that tighten blending requirements while hydrogen hub investments accelerate fuel cell adoption. This dual pressure from fuel pathway regulation and clean energy capital deployment is restructuring production priorities and terminal infrastructure investments.
Growth Catalysts
- EPA Renewable Fuel Standard:Tightening renewable volume obligations for transportation fuels are expanding methanol's role as a low-carbon blending component and hydrogen carrier in compliance strategies.
- Automotive fuel cell deployment:OEMs and fleet operators are integrating methanol-to-hydrogen reforming systems for heavy-duty transport, creating dedicated offtake demand separate from chemical feedstock markets.
- Gulf Coast petrochemical corridor concentration:Existing natural gas pipeline networks and export terminal infrastructure in Texas and Louisiana reduce logistics costs for new production capacity.
Market Restraints
- Natural gas price volatility:Steam methane reforming economics depend on Henry Hub pricing, exposing margins to upstream commodity swings without long-term supply contracts.
- Import dependency concentration:Canadian and Trinidadian supply sources dominate seaborne imports, creating geographic supply risk during marine logistics disruptions.
- Carbon intensity benchmarking:State-level low-carbon fuel standards in California and Oregon disadvantage conventional production against electrolysis-based pathways.
Strategic Opportunities
- Carbon capture integration:CO2 hydrogenation technology convergence with existing reforming assets enables producers to access 45Q tax credits and qualify for clean hydrogen hub funding.
- Marine fuel adoption:International Maritime Organization sulfur regulations are opening methanol bunkering infrastructure at US ports for deep-sea vessel refueling.
- Regional hydrogen hub networks:Department of Energy-funded hubs in Texas, California, and the Midwest are creating distributed methanol-to-hydrogen conversion demand.
Industry Challenges
- Process safety certification timelines:OSHA process safety management audits and EPA risk management plan approvals extend commissioning schedules for new facilities by 18-24 months.
- Legacy system integration complexity:Retrofitting existing steam methane reforming plants with carbon capture equipment requires simultaneous FERC pipeline safety recertification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Methanol Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel, Chemical Feedstock, Solvent, Methanol Derivatives End User: Automotive, Construction, Energy, Chemicals Application: Fuel Cells, Methyl Tertiary Butyl Ether, Biodiesel Production, Acetic Acid Production Technology: Steam Methane Reforming, Gas-phase Catalytic, CO2 Hydrogenation, Methanol Synthesis |
| Companies Covered | Methanex Corporation, Celanese Corporation, Southern Chemical Corporation, OCI N.V., Proman Group, Valenz, Petroliam Nasional Berhad (PETRONAS), Mitsubishi Gas Chemical Company, HELM AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Methanol Market Trends and Innovations
Production technology and regulatory compliance frameworks are the primary forces reshaping competitive positioning in US methanol. Innovations in carbon capture integration, federal hydrogen policy implementation, and marine fuel certification are restructuring investment priorities.
Carbon capture utilization and storage technology is absorbing capital allocation from conventional capacity expansion. Producers are retrofitting steam methane reforming facilities with post-combustion capture systems to qualify for IRA production tax credits. The technology is absorbing project finance that would otherwise flow to greenfield plants, compressing the timeline for low-carbon methanol availability.
FERC pipeline safety regulations are tightening monitoring requirements for CO2 transport infrastructure. The rulemaking imposes real-time leak detection mandates on new carbon capture pipelines serving methanol production sites. Gulf Coast producers are responding by consolidating capture projects along shared trunkline corridors to distribute compliance costs.
Marine fuel certification is fragmenting procurement patterns for methanol offtake. Shipping lines are requiring IMO 2020-compliant methanol with verified carbon intensity scores, displacing undifferentiated spot market purchases. This shift is most visible at Port of Houston and Port of Long Beach, where dedicated methanol bunkering terminals are under development.
US Methanol Market Segmentation
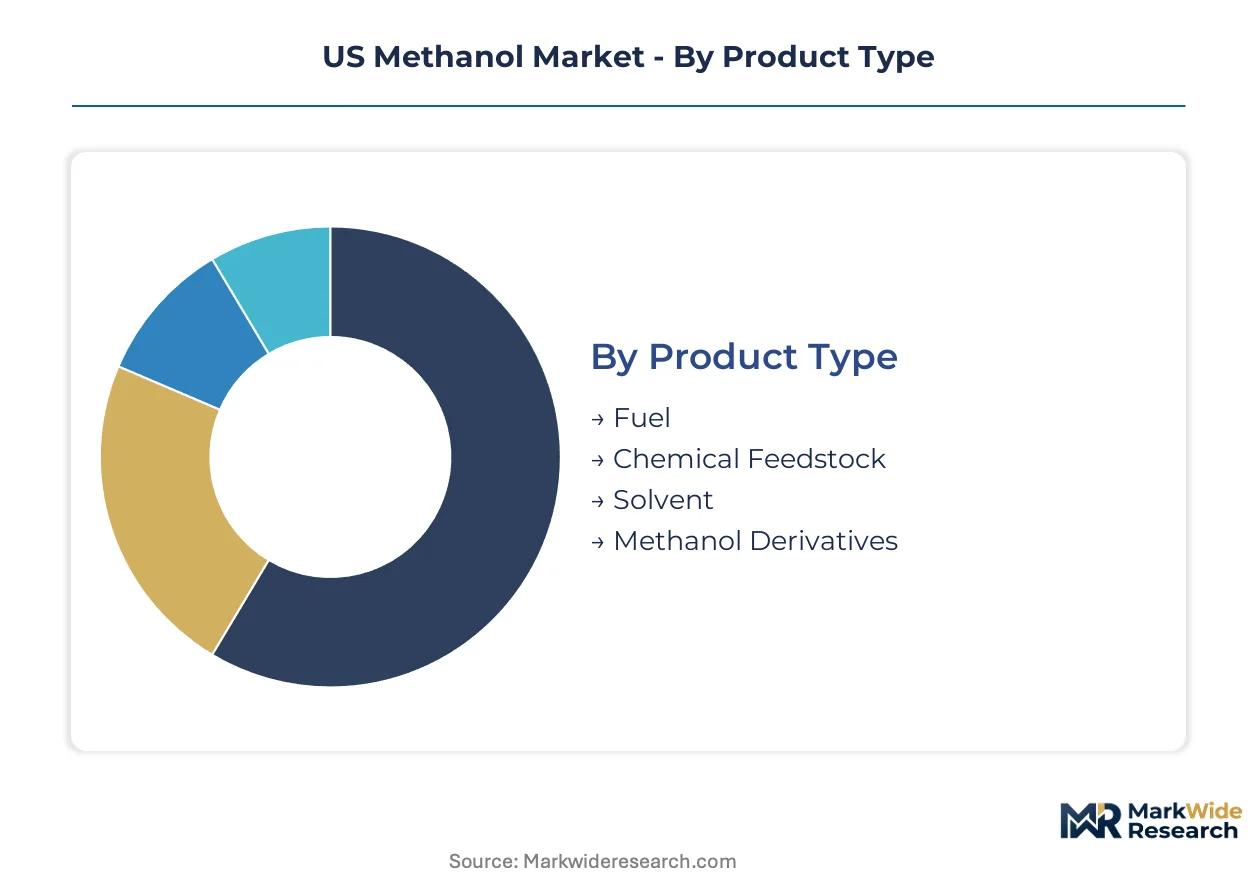
US methanol demand fragments across fuel pathways, chemical derivatives, and emerging hydrogen carrier applications. Each segment carries distinct capital requirements, regulatory exposure, and margin profiles that reshape investment allocation across the Gulf Coast production corridor.
Product Type:
Fuel-grade product commands the heaviest upfront investment due to EPA renewable fuel certification infrastructure and dedicated terminal storage requirements.
- Fuel:Transportation-grade methanol meets ASTM D1152 specifications for blending and direct combustion. Fleet operators in California and Texas are contracting dedicated volumes under low-carbon fuel standard compliance programs. EPA renewable volume obligations tighten annually.
- Chemical Feedstock:Industrial-grade material serves formaldehyde, acetic acid, and olefin production with purity thresholds above 99.85%. Demand concentrates along the Texas-Louisiana petrochemical corridor where derivative plants cluster near methanol terminals. Natural gas pipeline proximity reduces delivered cost.
- Solvent:Technical-grade methanol functions in paint thinners, adhesives, and pharmaceutical extraction processes. Specialty chemical blenders in Ohio and New Jersey purchase spot volumes for seasonal formulation cycles.
- Methanol Derivatives:Captive intermediate streams feed integrated methyl tert-butyl ether, dimethyl ether, and methyl methacrylate operations. Celanese and other acetyls producers consume these volumes internally.
Most installed capacity flows through Chemical Feedstock. Expansion is steepest in Fuel.
End User:
Automotive offtake carries the highest customer acquisition cost due to OEM qualification timelines and fuel cell system integration engineering.
- Automotive:Heavy-duty truck and bus manufacturers specify methanol-to-hydrogen reforming systems for zero-emission powertrains. Department of Energy hydrogen hub funding accelerates fleet pilot programs in Texas and California. Fuel cell stack suppliers qualify methanol purity to prevent catalyst poisoning.
- Construction:Formaldehyde-based resins for engineered wood panels consume methanol as primary feedstock. Housing starts in the Southeast drive seasonal demand swings for adhesive and insulation applications.
- Energy:Power generators and marine operators purchase methanol for dual-fuel combustion and fuel cell installations. Port of Houston bunkering infrastructure expands to serve deep-sea vessel retrofits.
- Chemicals:Integrated petrochemical producers operate captive methanol consumption for acetic acid, methylamines, and chloromethane synthesis. Texas Gulf Coast complexes achieve lowest delivered cost through pipeline integration.
Volume leadership sits with Chemicals. Share gains are most pronounced in Automotive.
Application:
Fuel cell applications demand the steepest capital commitment for reformer system certification and hydrogen purification equipment.
- Fuel Cells:Onboard methanol reforming generates hydrogen for proton exchange membrane stacks without compressed gas storage. Transit agencies in California and Hawaii deploy methanol-powered buses under state zero-emission mandates. System efficiency targets exceed 45% lower heating value.
- Methyl Tertiary Butyl Ether:Gasoline oxygenate production consumes methanol for etherification with isobutylene. Refiners in the Midwest and Gulf Coast maintain steady offtake under federal renewable fuel blending floors.
- Biodiesel Production:Transesterification catalyst and process solvent applications require technical-grade methanol volumes. Biodiesel producers in Iowa and Illinois purchase seasonal spot cargoes.
- Acetic Acid Production:Monsanto and Cativa process technologies consume methanol for carbonylation to acetic acid. Celanese operates dedicated pipeline supply to its Texas acetyls complex.
Installed capacity predominantly serves Methyl Tertiary Butyl Ether. Investment momentum clusters in Fuel Cells.
Technology:
Steam methane reforming retains the lowest marginal capital cost per ton for brownfield expansions, though carbon capture retrofits alter the calculus.
- Steam Methane Reforming:Conventional natural gas reforming with water-gas shift and methanol synthesis loops dominates US production. Gulf Coast facilities leverage Henry Hub pricing and existing pipeline networks. Post-combustion carbon capture retrofits qualify for IRA tax credits.
- CO2 Hydrogenation:Direct conversion of captured carbon dioxide with green hydrogen enables negative-carbon methanol certification. Pilot plants in Texas and California test electrolysis integration for clean hydrogen hub compliance.
- Gas-phase Catalytic:Fluidized bed and entrained flow reactors optimize for syngas conversion efficiency. licensors like Johnson Matthey and Haldor Topsoe supply catalyst and reactor designs.
- Methanol Synthesis:Low-pressure copper-zinc oxide catalyst loops complete the conversion from syngas to crude methanol. Distillation trains purify product to commercial grades.
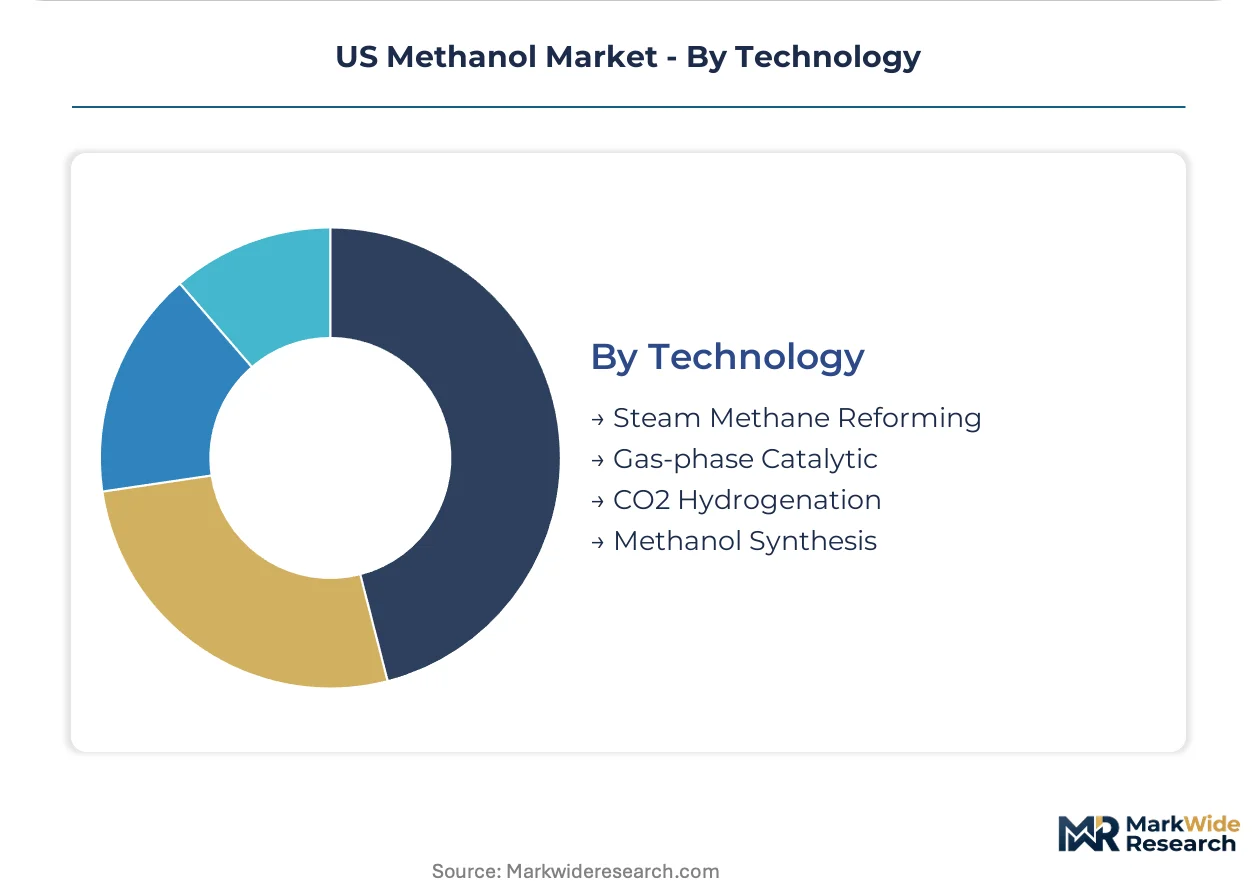
Operating capacity overwhelmingly employs Steam Methane Reforming. New project development favors CO2 Hydrogenation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical engineers and process operators cluster along the Gulf Coast corridor, anchoring methanol production capacity to Texas and Louisiana industrial zones. This workforce concentration shapes facility siting decisions and supply chain logistics across domestic markets.
Texas Gulf Coast
Steam methane reforming complexes in Beaumont-Port Arthur consume Henry Hub-priced natural gas for acetic acid and MTBE feedstock production. EPA Region 6 air quality permits govern stack emissions from synthesis loop operations. Houston Ship Channel terminals handle seaborne methanol imports from Trinidad and Venezuela while loading export cargoes for Asia-Pacific buyers.
Louisiana Industrial Corridor
Baton Rouge and Lake Charles host derivative manufacturing plants requiring pipeline-delivered methanol for formaldehyde and methylamine synthesis. Louisiana Department of Environmental Quality coastal use permits regulate waterfront facility expansions. The Mississippi River logistics network enables barge distribution to Midwest refineries and chemical processors.
California Low-Carbon Fuel Zone
Fleet operators in Los Angeles and Long Beach purchase fuel-grade methanol for hydrogen hub compliance and port truck retrofits. California Air Resources Board LCFS carbon intensity scoring disadvantages conventional production against electrolysis pathways. Port of Long Beach bunkering infrastructure serves dual-fuel vessel operators under IMO 2020 sulfur regulations.
Midwest Chemical Processing Belt
Refiners in Illinois and Ohio blend methanol-derived MTBE into gasoline pools under federal renewable volume obligations. FERC interstate pipeline tariffs influence delivered costs from Gulf Coast production sources. Chicago-area terminal operators manage seasonal inventory cycles for biodiesel catalyst and solvent applications.
Pacific Northwest Hydrogen Hub
Oregon and Washington state agencies pilot methanol-to-hydrogen conversion for maritime and heavy-duty transport under Department of Energy hub funding awards. State low-carbon fuel standards mirror California's carbon intensity benchmarking. Columbia River port facilities evaluate methanol bunkering for Asian trade lane vessels.
US Methanol Market Competitive Landscape
Capital-heavy producers with integrated reforming assets compete with asset-light traders and terminal operators for margin capture. The market structure concentrates around three strategic archetypes: integrated petrochemical conglomerates with captive consumption, merchant producers serving spot and contract offtake, and specialized logistics operators managing import terminal networks. Dominant competitive moves include carbon capture retrofit investments qualifying for IRA tax credits, and marine fuel certification partnerships with IMO-compliant shipping lines.
Among North American integrated producers, Methanex Corporation exemplifies the merchant producer archetype with terminal network control, while Celanese Corporation represents captive supply integration into downstream acetyls manufacturing. Southern Chemical Corporation occupies the specialized logistics tier, differentiating through distribution infrastructure rather than production ownership.
| Leading Market Players |
|---|
| Methanex Corporation |
| Celanese Corporation |
| Southern Chemical Corporation |
| OCI N.V. |
| Proman Group |
| Valenz |
| Petroliam Nasional Berhad (PETRONAS) |
| Mitsubishi Gas Chemical Company |
| HELM AG |
| Others |
Pricing and Supply Chain Analysis
California Air Resources Board low-carbon fuel standard certification gates both qualified supply and premium-tier pricing access for US methanol producers. EPA renewable volume obligations compound this filtering effect by restricting fuel-grade methanol participation to certified pathways.
Pricing Analysis
Bundled terminal-to-reformer service packages command premiums over unbundled spot cargo purchases. Three-tier pricing structure across certified low-carbon, standard fuel-grade, and undifferentiated chemical feedstock levels reflects carbon intensity scoring and terminal storage integration. Cost compression in standard fuel-grade material is intensifying because electrolysis-based hydrogen pathways are achieving scale. Fleet operators under state zero-emission mandates show least price sensitivity; spot chemical buyers exhibit highest elasticity.
Supply Chain Analysis
Domestic-content mandates in Department of Energy hydrogen hub funding awards are reshaping sourcing toward US-based CO2 capture and electrolysis equipment. Geographic supply concentration centers on Trinidad, Canada, and domestic Gulf Coast production. Raw material dependencies draw from Henry Hub natural gas, imported catalyst metals, and specialized reforming alloys. Single-source vulnerability runs through Trinidad marine terminal congestion. Distribution runs through Houston Ship Channel terminals, Mississippi River barge networks, and California pipeline corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US methanol market functions as a stable compounder anchored by EPA renewable fuel standard mandates that tighten annually regardless of economic cycles.
For Market Incumbents: Lock in long-term offtake agreements with California and Texas fleet operators before electrolysis-based hydrogen pathways achieve cost parity. Secure backward integration into carbon capture infrastructure to qualify for IRA production tax credits. Defend terminal network control against specialized logistics entrants by expanding shared trunkline corridors along the Gulf Coast.
For New Entrants and Emerging Players: Launch via tolling arrangements at underutilized Gulf Coast reforming facilities rather than greenfield construction. Target Pacific Northwest hydrogen hub pilots where incumbent terminal density remains lowest. Penetrate marine bunkering certification services at secondary ports before Houston and Long Beach terminal saturation hardens.
For Investors and Strategic Acquirers: Roll-up economics work for regional terminal operators because fragmented barge and storage assets lack scale to justify standalone carbon capture retrofits. Five-to-ten-year viability hinges on low-carbon fuel standard geographic expansion beyond California and Oregon. Monitor state-level clean hydrogen hub award announcements as the primary inflection indicator for regional demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit | Post-combustion capture systems unlock IRA 45Q tax credits for Gulf Coast reformers. |
| Marine Fuel Certification | IMO 2020-compliant methanol bunkering terminals attract deep-sea vessel operators at Houston. |
| Hydrogen Hub Partnership | DOE-funded regional hubs create dedicated methanol-to-hydrogen conversion demand in Texas. |
| Long-term Supply Agreement | Fleet operators under LCFS mandates contract certified low-carbon volumes through 2030. |
| Terminal Network Expansion | Shared CO2 trunkline corridors distribute FERC pipeline safety compliance costs across producers. |
Research Methodology
Coverage spans Texas, Louisiana, California, and the Pacific Northwest, with primary inputs from each regional production and consumption cluster. The research combines structured interviews with plant operations managers, procurement leads at downstream acetyls producers, marine terminal operators, and hydrogen hub program directors with secondary validation from EIA production data, EPA renewable fuel standard filings, FERC pipeline safety reports, and ACC industry statistics. Bottom-up capacity and demand modeling triangulates against top-down trade flow analysis.
Rate-of-change decomposition separates volume growth from price evolution across the projection horizon. The analytical framework segments by fuel grade tier, end-use application, production technology pathway, and regional regulatory cluster. CAGRs derive from weighted average of historical capacity utilization trends and announced project development timelines. Industry-specific forecast inputs include Henry Hub natural gas price scenarios and state-level low-carbon fuel standard stringency trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged natural gas price volatility or accelerated electrolysis cost declines. The analysis assumes EPA renewable volume obligation schedules proceed as published and hydrogen hub funding disbursements follow announced timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Superphosphoric Acid (SPA) Market
Chemicals
N-Acetyl D-Neuraminic Acid Market
Chemicals
Indonesia Nitric Acid Market
Chemicals
Maleic Acid Market
Chemicals
Whitening Ingredients Market
Chemicals
Gold Plating Chemicals Market
Chemicals
Sodium Tripolyphosphate (STPP) Market
Chemicals
Glycerol Carbonate Market
Chemicals
Aerosol Insecticides Market
Chemicals
Etidronic Acid Market
Chemicals
Asia-Pacific Surface Treatment Chemicals Market
Chemicals
Resorcinol Market
Chemicals
Formalin Market
Chemicals
Phosphorus Pentasulfide (P2S5) Market
Chemicals
Thiourea Market
Chemicals
Europe Fluorosilicic Acid Market