
 Trichloroisocyanuric Acid Market | 2026-2036
Trichloroisocyanuric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Trichloroisocyanuric Acid Market Analytics
Modular tablet-and-granule bundling is restructuring how municipal buyers and commercial pool operators evaluate procurement economics. Fluidra leverages its aquatics equipment ecosystem to anchor chlorine demand across European distribution networks. Nankai Chem sustains captive chlor-alkali integration that controls raw material cost volatility. Occidental differentiates through Gulf Coast manufacturing scale and direct rail access to bulk industrial accounts.
Trichloroisocyanuric acid is a chlorinated organic compound with the formula C3Cl3N3O3, manufactured through gas-phase chlorination of cyanuric acid to yield a stable solid with approximately 90% available chlorine content; it serves primarily as a slow-release disinfectant and oxidizer in water sanitation systems. Tablet formulations dominate margin pools due to dosage precision and storage stability, while powder demand concentrates in industrial cleaning applications where rapid dissolution matters. Granule configurations occupy a narrowing middle ground as pool operators shift toward pre-measured tablets or bulk powder systems.
EPA Office of Water standards, REACH registration requirements under ECHA, and China's GB disinfection specifications collectively determine product purity thresholds and import access conditions for chlorinated isocyanurate suppliers. The EU Biocidal Products Regulation adds compliance layers for swimming pool and drinking water applications. Stakeholders must monitor regulatory divergence between jurisdictions as it fragments certification costs and reshapes competitive access.
Market Dynamics
Municipal water treatment utilities are consolidating disinfectant procurement around tablet-form products that reduce handling complexity and dosing error rates. This shift compresses margin pools for powder suppliers while rewarding manufacturers with integrated tableting capabilities.
Growth Catalysts
- REACH registration requirements:ECHA's tightened purity standards for chlorinated isocyanurates are filtering out marginal European suppliers and concentrating volume with compliant producers.
- China's industrial cleaning sector:State-owned chemical distributors are locking in multi-year supply agreements, anchoring regional demand growth through captive procurement channels.
- Slow-release tablet technology:Dosage precision and storage stability advantages are displacing granular alternatives in commercial pool operator purchasing decisions.
Market Restraints
- Chlor-alkali input volatility:Caustic soda and chlorine gas price swings transmit directly to trichloroisocyanuric acid production economics, compressing margins during energy cost spikes.
- Supply concentration in Shandong Province:China's chemical manufacturing cluster creates geographic risk exposure for global buyers dependent on seaborne export volumes.
- Calcium hypochlorite substitution:Lower-cost alternatives are capturing share in price-sensitive industrial cleaning applications where rapid dissolution speed outweighs stability benefits.
Strategic Opportunities
- India's municipal water infrastructure:Underpenetrated tablet disinfectant adoption among urban water utilities offers first-mover positioning as BIS standards converge with international purity benchmarks.
- Wastewater reuse mandates:EPA Office of Water discharge requirements are expanding addressable demand for residual chlorine maintenance in tertiary treatment systems.
- Direct rail-to-plant distribution:Bypassing distributor markups through bulk delivery infrastructure is automating cost structures for large industrial accounts.
Industry Challenges
- EPA and REACH dual certification timelines:Parallel compliance pathways for swimming pool and drinking water applications extend product registration cycles and freeze capital deployment.
- Legacy powder system integration:Industrial cleaning facilities with existing bulk handling infrastructure face switching costs that delay tablet format conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trichloroisocyanuric Acid Market |
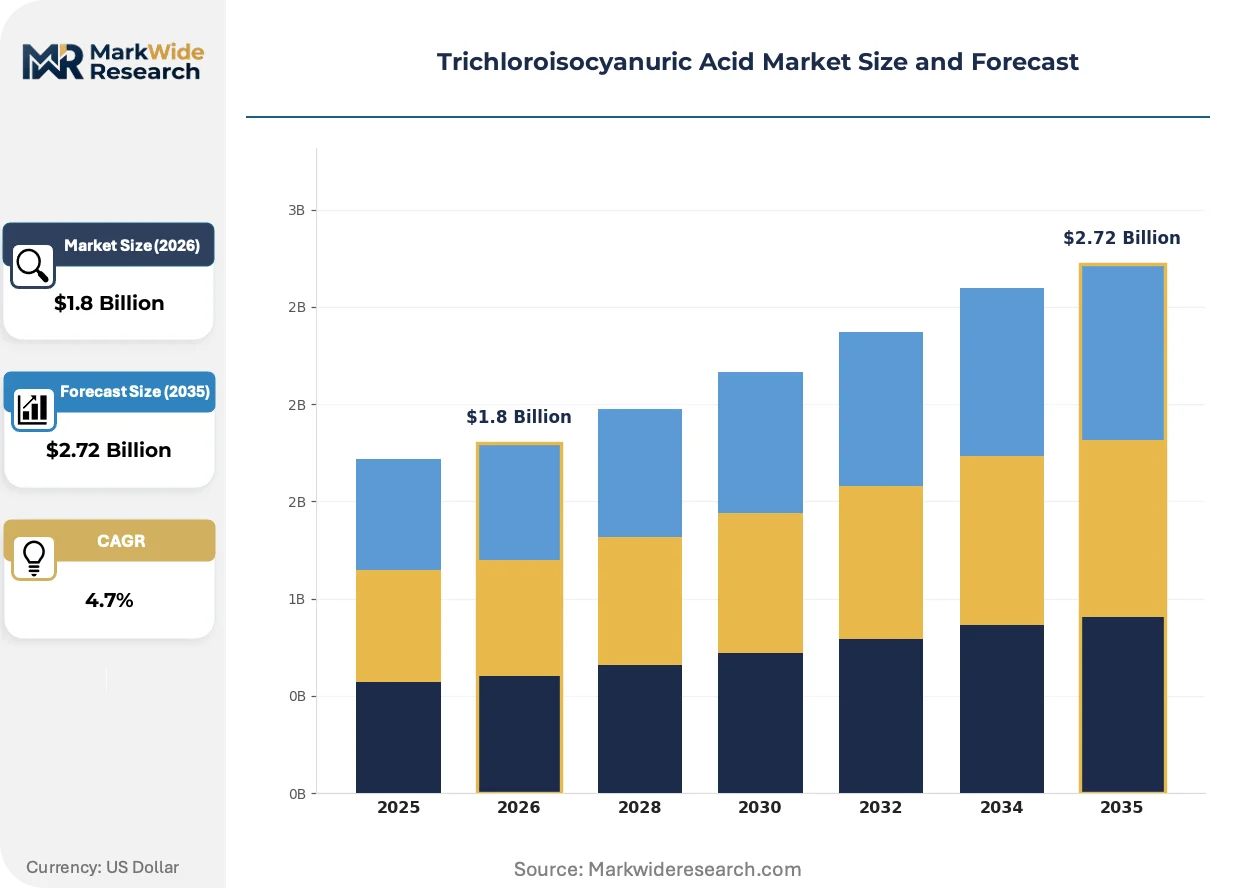
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Tablets, Powder, Liquid Application: Water Treatment, Swimming Pools, Disinfection, Industrial Cleaning End User: Households, Commercial, Industrial, Municipal Distribution Channel: Online Retail, Wholesale, Direct Sales, Distributors |
| Companies Covered | Fluidra, Nankai Chem, Occidental, Pat Impex, Nippon Soda, Clearon, Shikoku Chem, Jiheng Chem, Ercros, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trichloroisocyanuric Acid Market Evolving Landscape
Automation in dosing and monitoring systems is compressing the operational rationale for manual chemical handling. Regulatory divergence between jurisdictions is fragmenting certification economics. Buyer consolidation among municipal utilities is restructuring supplier relationship terms.
Precision tablet manufacturing with embedded dissolution-rate control is automating dosage calibration for pool operators and water treatment facilities. Commercial aquatics managers are adopting these systems to reduce labor hours and liability exposure. The technology is automating the displacement of granular products in mid-scale installations where manual dosing previously dominated.
EU Biocidal Products Regulation authorization requirements are extending compliance timelines for swimming pool and drinking water applications. Manufacturers must submit expanded toxicological dossiers to ECHA, raising fixed costs for market access. Smaller suppliers without dedicated regulatory affairs functions are exiting the European market, concentrating share with established registrants.
Long-term supply agreements with indexed pricing clauses are replacing spot-market purchasing among North American municipal utilities. Bulk procurement consortia are aggregating demand across multiple water districts, compressing supplier margins. This pattern is most visible in Texas and California, where regional water authorities are centralizing chemical purchasing decisions.
Trichloroisocyanuric Acid Market Segmentation
Trichloroisocyanuric acid procurement decisions split across dosage precision requirements, handling infrastructure, and regulatory compliance burdens. Buyers trade stability against dissolution speed while weighing labor costs against capital investment in dosing systems.
Product Type:
Dosage precision and storage stability drive format selection across municipal and commercial accounts.
- Tablets:Slow-release compressed forms with embedded dissolution-rate control enable automated feeder compatibility and reduce handling exposure. Municipal water utilities in Texas and California are consolidating procurement around tablet-form products that minimize dosing error rates and liability exposure.
- Powder:Rapid-dissolution crystalline product delivers immediate chlorine availability for industrial cleaning applications where speed outweighs stability requirements. China's state-owned chemical distributors are locking in multi-year powder supply agreements to serve manufacturing facility sanitation protocols.
- Granules:Intermediate particle size offers manual scoop dosing flexibility for mid-scale pool operators without automated systems.
- Liquid:Pre-dissolved solution eliminates dissolution equipment needs for small-scale household users and emergency response applications.
Volume sits with tablets; growth tilts toward powder.
Application:
Regulatory jurisdiction determines purity thresholds and registration burdens across use cases.
- Water Treatment:Drinking water and wastewater systems demand EPA Office of Water compliance and residual chlorine maintenance capability. Tertiary treatment reuse mandates in US municipalities are expanding addressable demand for stable disinfectant formulations.
- Swimming Pools:Commercial aquatics managers prioritize labor reduction through automated dosing systems with tablet feeders. EU Biocidal Products Regulation authorization requirements are extending compliance timelines and concentrating supply with established ECHA registrants.
- Disinfection:Surface and equipment sanitation protocols in healthcare and food processing require rapid-acting chlorine release.
- Industrial Cleaning:Manufacturing facility sanitation favors powder formats where bulk handling infrastructure already exists and calcium hypochlorite substitution pressure is strongest.
Revenue concentrates in water treatment; expansion is steepest in industrial cleaning.
End User:
Procurement scale and technical sophistication determine supplier relationship structures.
- Municipal:Bulk procurement consortia aggregate demand across water districts and compress margins through indexed long-term agreements.
- Commercial:Pool operators and facility managers balance labor cost reduction against capital investment in automated dosing infrastructure.
- Industrial:Large accounts leverage direct rail-to-plant distribution to bypass distributor markups and automate cost structures.
- Household:Small-volume consumers purchase through retail channels with limited technical specification requirements.
Contract value peaks with municipal buyers; margin expansion favors commercial accounts.
Distribution Channel:
Supply chain configuration reflects buyer scale and geographic concentration.
- Direct Sales:Bulk industrial and municipal accounts negotiate rail-delivered volumes with manufacturers possessing Gulf Coast manufacturing scale.
- Distributors:Regional chemical distributors serve mid-scale commercial accounts requiring technical support and inventory management.
- Wholesale:Volume aggregators supply smaller commercial operators and retail channels with standardized product grades.
- Online Retail:E-commerce platforms capture household and small commercial demand with limited technical consultation.
Tonnage flows through direct sales; channel development targets distributor consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of global trichloroisocyanuric acid output while the United States and Europe absorb premium-grade volumes for regulated water treatment applications. This production-consumption divide shapes trade flows and compliance requirements across major markets.
China
Shandong Province hosts the densest concentration of chlor-alkali integrated producers serving both domestic industrial cleaning demand and export markets. GB disinfection specifications under SAMR govern product purity for domestic water treatment use. Qingdao and Weifang chemical clusters are expanding tablet compression capacity to capture higher-margin municipal procurement contracts.
United States
Texas and California municipal water authorities are consolidating disinfectant purchasing through regional bulk procurement consortia. EPA Office of Water standards mandate residual chlorine maintenance capabilities in tertiary treatment systems. Gulf Coast manufacturing locations with direct rail access serve large industrial accounts bypassing distributor markups.
Germany
REACH registration requirements under ECHA are filtering out marginal suppliers and concentrating volume with established biocidal product registrants. The EU Biocidal Products Regulation extends compliance timelines for swimming pool and drinking water applications. Ludwigshafen and Leverkusen chemical corridors anchor formulation and distribution networks across continental Europe.
Japan
Commercial aquatics managers prioritize automated tablet feeder systems to reduce labor hours and liability exposure. METI oversees chemical safety standards while JIS specifications govern product grades for industrial applications. Osaka and Nagoya manufacturing bases supply precision-compressed tablet formats for regional pool operator networks.
India
Urban water utilities represent underpenetrated tablet disinfectant adoption as BIS standards converge with international purity benchmarks. CDSCO and state pollution control boards oversee chemical safety compliance for drinking water applications. Gujarat and Maharashtra industrial corridors are attracting contract manufacturing investments from multinational suppliers seeking tariff-advantaged production bases.
Trichloroisocyanuric Acid Market Competitive Landscape
The competitive structure tilts toward integrated chlor-alkali producers with captive raw material supply and specialized aquatics equipment ecosystems. Tier-one positions cluster around manufacturers possessing Gulf Coast or Shandong Peninsula manufacturing scale with direct rail or port access. Three archetypes dominate: integrated chemical conglomerates with backward control over chlorine gas supply, aquatics-focused equipment-and-chemical bundlers, and regional tablet compression specialists serving municipal procurement channels. Capacity expansion and regulatory compliance certification constitute the dominant competitive moves as marginal suppliers exit under REACH and EPA dual registration burdens.
Among integrated chemical producers, Occidental anchors the scale-driven tier with Gulf Coast manufacturing infrastructure, while Nankai Chem exemplifies captive chlor-alkali integration controlling raw material cost volatility. Within the aquatics equipment bundler archetype, Fluidra occupies a position leveraging its European distribution networks to anchor chlorine demand alongside pool hardware sales. These three companies represent distinct strategic positions: commodity-scale manufacturing, upstream raw material control, and downstream equipment-channel integration.
| Leading Market Players |
|---|
| Fluidra |
| Nankai Chem |
| Occidental |
| Pat Impex |
| Nippon Soda |
| Clearon |
| Shikoku Chem |
| Jiheng Chem |
| Ercros |
| Others |
Value Network & Pricing Analysis
Caustic soda and chlorine gas price indices transmit directly into trichloroisocyanuric acid production economics, compressing margins for non-integrated producers while rewarding chlor-alkali backward integration with cost buffers against energy volatility. This input-cost cascade stratifies pricing tiers across tablet, powder, and granule formats.
Pricing Analysis
Margin tightening in powder grades reflects calcium hypochlorite substitution pressure from industrial cleaning buyers prioritizing rapid dissolution speed over stability benefits. Three-tier pricing structure across premium, standard, and economy levels separates EPA-REACH dual-certified product from single-jurisdiction compliant grades and uncertified commodity material. Municipal procurement consortia in Texas and California exercise acute price sensitivity through indexed long-term agreements, while commercial pool operators absorb modest premiums for automated tablet feeder compatibility.
Supply Chain Analysis
Chlorine gas supply rests on Shandong Province chemical clusters in China, Gulf Coast chlor-alkali infrastructure in the United States, and Ludwigshafen-Leverkusen corridors in Germany. Cyanuric acid feedstock and compression equipment for tablet manufacturing constitute critical input dependencies. Single-source vulnerability concentrates in Shandong's export-oriented production base, exposing global buyers to seaborne logistics disruption. Distribution runs through direct rail-to-plant delivery for bulk industrial accounts, regional chemical distributors for mid-scale commercial buyers, and wholesale aggregators serving retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where REACH and EPA dual registration burdens are filtering marginal suppliers and concentrating volume with compliant incumbents.
For Market Incumbents: To counter calcium hypochlorite substitution in industrial cleaning, deepen backward integration into captive chlor-alkali production and expand tablet compression capacity in Qingdao-Weifang clusters to capture municipal procurement consolidation. Certification investment in ECHA toxicological dossiers secures European biocidal product authorization against registrant attrition. For New Entrants and Emerging Players: BIS standard convergence in India opens a window for tablet-format first-mover positioning among underpenetrated urban water utilities. Target Gujarat and Maharashtra contract manufacturing bases for tariff-advantaged production. Lead with precision dissolution-rate technology to differentiate from incumbent commodity supply. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated chlor-alkali producers with Gulf Coast or Shandong Peninsula manufacturing scale and direct rail-port access. Long-term viability hinges on regulatory compliance certification depth rather than spot-market volume capture. Watch EPA Office of Water tertiary treatment mandate expansion as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali | Captive caustic soda and chlorine gas supply insulates margin structures from energy cost volatility. |
| Tablet Compression Capacity Expansion | Qingdao-Weifang cluster investments capture municipal procurement shift toward slow-release formats. |
| Dual Certification Investment | EPA-REACH parallel registration concentrates market share as marginal suppliers exit under compliance burdens. |
| Direct Rail-to-Plant Distribution | Bypassing distributor markups automates cost structures for large industrial accounts in Texas and California. |
| Long-term Supply Agreement | Indexed pricing clauses with municipal procurement consortia lock volume against spot-market volatility. |
Research Methodology
Trade flow databases, customs records, and SEC 10-K filings formed the secondary backbone, cross-referenced with primary interviews involving chlor-alkali plant managers, municipal water utility procurement leads, pool operator facility managers, and chemical distribution channel partners. Bottom-up volume triangulation across tablet, powder, granule, and liquid formats converged with top-down market sizing validated against ECHA registration databases and EPA Office of Water compliance filings.
Historical trendline analysis of chlor-alkali input cost trajectories, municipal procurement pattern shifts, and regulatory compliance timeline extensions informed the projection framework across the analysis window. Segmentation modeling incorporated product format, application jurisdiction, end-user procurement scale, and distribution channel configuration. CAGRs derived from weighted average of volume growth in industrial cleaning, water treatment reuse mandates, and commercial aquatics automation adoption.
The model assumes a particular technology adoption path; alternative pathways for precision tablet dissolution-rate control would alter the outlook if granular or liquid formats recapture share. Forecasts reflect assumptions around REACH registration completion rates, Shandong export capacity utilization, and municipal procurement consolidation velocity. A small set of triggers—EPA tertiary treatment mandate expansion, BIS standard finalization in India, and calcium hypochlorite cost-position shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Welding Chemicals Market
Chemicals
Anticoagulant Rodenticides Market
Chemicals
Benzhydrol Market
Chemicals
Benzoyl Alcohol Market
Chemicals
Selenium Sulfide Market
Chemicals
(S)-(+)-2-Amino-1-Propanol Market
Chemicals
Global Waterproofing Chemicals Market
Chemicals
Diphenyl Sulfone Market
Chemicals
Linear Mercaptans Market
Chemicals
Insect Repellent Active Ingredients Market
Chemicals
Thiourea Market
Chemicals
India Metal Treatment Chemical Market
Chemicals
Iscotrizinol Market
Chemicals
Methyl Ethyl Ketone Peroxide (MEKP) Market
Chemicals
Decabromodiphenyl Ether Market
Chemicals
Global Fluorosilicic Acid Market