
 Asia-Pacific Acetic Acid Market | 2026-2036
Asia-Pacific Acetic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Acetic Acid Market Insights
Modular tank-container delivery is decoupling bulk acetic acid procurement from traditional dedicated-vessel contracts, letting mid-size buyers source smaller lots with reduced capital commitment. Celanese Corporation leverages its integrated methanol-to-acetic-acid chain across Singapore and Nanjing to sustain margin control. Jiangsu Sopo anchors domestic Chinese supply through coal-based syngas routes, while Daicel Corporation differentiates via high-purity glacial grades for pharmaceutical and electronics solvents.
Acetic acid is a two-carbon carboxylic acid with molecular formula CH₃COOH, typically produced via methanol carbonylation using rhodium or iridium catalysts at pressures around 30-60 bar and temperatures near 150-200°C; it serves as a fundamental chemical intermediate for vinyl acetate monomer, acetic anhydride, and ester solvents. Glacial acetic acid dominates value capture due to its purity requirements in pharmaceutical and food-grade applications, while acetic anhydride segments compete on derivative demand from cellulose acetate and aspirin production. Chemical production applications lead volume offtake, though food additives segments command premium pricing through FSSAI and CDSCO compliance burdens.
China's MEE enforces dual carbon emission intensity benchmarks that force carbonylation plants to upgrade catalyst efficiency or face output restrictions. India's BIS mandates IS 695 specifications for industrial acetic acid purity, while CDSCO tracks pharmaceutical-grade imports for excipient compliance. Japan's METI maintains JIS K 8355 standards that shape export eligibility from regional producers. Stakeholders must monitor carbon border adjustment mechanisms and catalyst technology shifts to preserve cost positions as regional energy transitions accelerate.
Market Dynamics
China's MEE dual carbon mandates are forcing carbonylation plants toward catalyst efficiency retrofits and carbon capture installation, compressing margin structures for coal-based producers while advantaging methanol-integrated operators with cleaner feedstock access.
Growth Catalysts
- Vinyl acetate monomer offtake:Construction adhesives and automotive coatings in eastern China drive derivative demand as Zhejiang and Jiangsu manufacturing clusters expand capacity.
- MEE emission intensity benchmarks:Regulatory pressure on carbon output per ton of acetic acid produced accelerates technology upgrades among carbonylation operators seeking compliance headroom.
- Modular tank-container logistics:Mid-size buyers across Southeast Asia source smaller lots without dedicated-vessel capital commitment, fragmenting procurement patterns.
Market Restraints
- Methanol price volatility:Feedstock cost swings from coal-to-chemicals capacity fluctuations in Shanxi and Inner Mongolia destabilize production economics for syngas-based routes.
- Coastal supply concentration:Zhejiang and Jiangsu provinces host disproportionate derivative manufacturing, creating geographic vulnerability to port congestion or regional emission shutdowns.
- High-purity import dependency:Pharmaceutical and electronics-grade glacial acetic acid relies on Japanese and Korean suppliers, exposing buyers to currency and shipping cost pressure.
Strategic Opportunities
- India pharmaceutical excipient demand:CDSCO compliance requirements for imported acetic acid create premium positioning for certified domestic production expansion.
- Carbon capture retrofit incentives:China's dual carbon framework rewards carbonylation plants installing post-combustion capture, opening technology licensing revenue streams.
- Modular biobased feedstock pilots:Fermentation-derived acetic acid from agricultural waste streams offers brand differentiation for food-grade and cosmetic solvent applications.
Industry Challenges
- Rhodium catalyst supply security:Precious metal sourcing from South African and Russian refiners creates working capital intensity and geopolitical exposure for carbonylation operators.
- BIS-IS 695 certification timelines:Indian industrial-grade approval processes extend market entry cycles for new suppliers, favoring incumbents with established testing relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Acetic Acid Market |
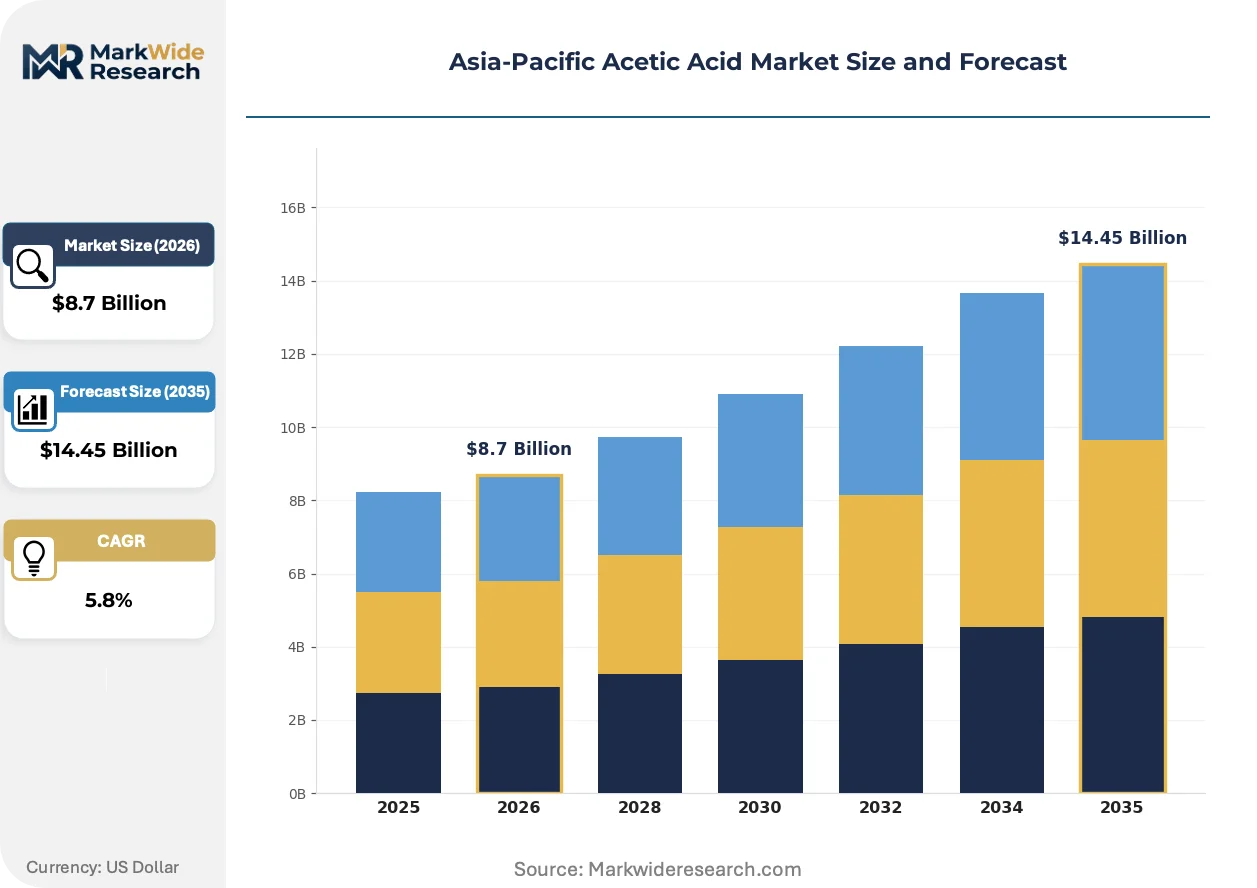
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glacial Acetic Acid, Anhydrous Acetic Acid, Diluted Acetic Acid, Acetic Anhydride Application: Food Additives, Chemical Production, Solvent Use, Textile Manufacturing End User: Food & Beverage, Chemicals, Plastics, Pharmaceuticals Delivery Mode: Bulk, Drums, Cylinders, Pails |
| Companies Covered | Shanghai Huayi (Group) Company, Jiangsu Sopo (Group) Co. Ltd., Celanese Corporation, Indian Oil Corporation Ltd., Gujarat Narmada Valley Fertilizers & Chemicals Limited, Eastman Chemical Company, Daicel Corporation, LyondellBasell Industries, Mitsubishi Chemical Group Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Acetic Acid Market Trends and Innovations
Technology convergence between carbonylation efficiency upgrades and carbon capture retrofits is compressing the cost gap between coal-based and natural gas-based production routes across the region.
Iridium-promoted rhodium catalyst systems is unifying high-selectivity acetic acid production with lower carbon intensity per ton output. Celanese and BP-licensed operators in Nanjing and Singapore are adopting these formulations to meet MEE benchmarks without capacity sacrifice. The technology is unifying margin preservation with regulatory compliance in a single capital deployment.
China's MEE dual carbon emission intensity benchmarks are forcing carbonylation plants to document carbon output per unit of production or face output restrictions. Plants without capture retrofits must purchase offset credits or throttle runs during compliance windows. Eastern China producers with integrated methanol supply chains are responding fastest due to feedstock traceability advantages.
Mid-size buyers across Southeast Asia are consolidating purchases through third-party tank-container operators rather than signing multi-year dedicated-vessel contracts. This spot-market behavior compresses supplier visibility into forward demand but reduces buyer inventory carrying costs. The pattern is most visible in Vietnam and Indonesia where derivative manufacturing capacity is fragmenting geographically.
Asia-Pacific Acetic Acid Market Segmentation
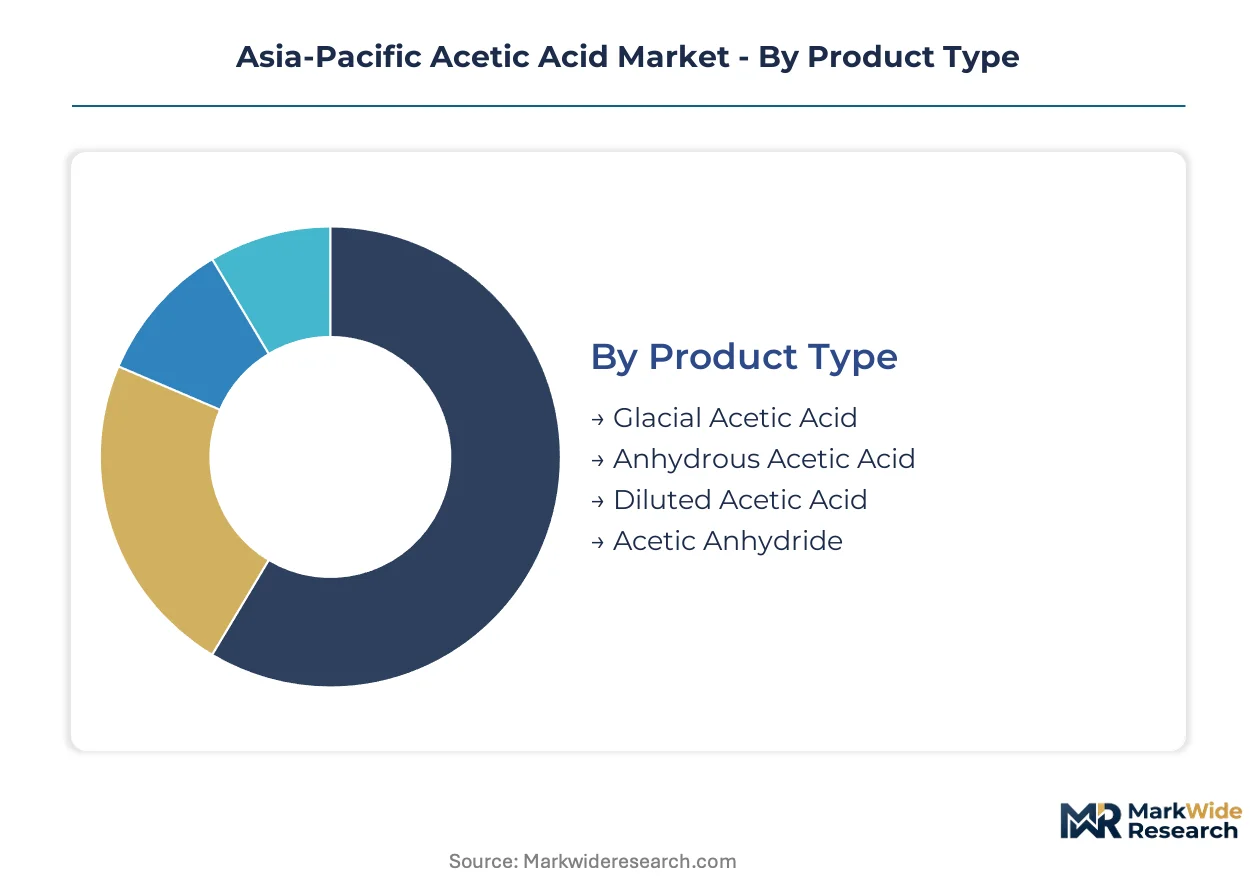
Acetic acid segmentation across the Asia-Pacific region reflects divergent purity requirements and logistics economics. Product grade determines regulatory pathway and margin capture, while delivery mode shapes working capital intensity for buyers across fragmented derivative manufacturing clusters.
Product Type:
Volume concentrates in industrial grades, yet premium capture belongs to high-purity formulations serving pharmaceutical and electronics solvents.
- Glacial Acetic Acid:Concentrated form with purity exceeding 99.5% by weight, meeting JIS K 8355 and pharmaceutical excipient specifications. Demand concentrates in eastern China's Zhejiang and Jiangsu provinces where electronics solvent and pharmaceutical manufacturing clusters require trace-metal-controlled feedstock. CDSCO compliance requirements for imported pharmaceutical-grade material sustain price premiums over industrial grades.
- Anhydrous Acetic Acid:Water-free specification critical for acetic anhydride production and moisture-sensitive chemical synthesis. Vinyl acetate monomer producers in Singapore and Nanjing favor this grade for catalyst protection in carbonylation loops. MEE emission intensity benchmarks favor producers with integrated methanol-to-acetic-acid chains that can guarantee anhydrous consistency without redistillation energy penalties.
- Diluted Acetic Acid:Standard industrial concentrations for textile processing and general chemical synthesis across Southeast Asian manufacturing zones.
- Acetic Anhydride:Derivative product for cellulose acetate and aspirin production, sourced from dedicated acetylation units rather than merchant acetic acid.
Today's leader: Glacial acetic acid. Tomorrow's challenger: Anhydrous grades as carbonylation efficiency upgrades compress purity premiums.
Application:
End-use concentration tracks construction and automotive sector expansion, with regulatory compliance burdens fragmenting procurement patterns across food-grade versus industrial channels.
- Chemical Production:Dominant volume channel encompassing vinyl acetate monomer, acetic anhydride, and ester solvent manufacturing. Zhejiang and Jiangsu derivative clusters absorb the majority of regional carbonylation output. Methanol price volatility from Shanxi and Inner Mongolia coal-to-chemicals capacity destabilizes production economics for syngas-based routes serving this segment.
- Food Additives:Acidulant and preservative applications governed by FSSAI and CDSCO purity mandates. Premium pricing reflects compliance documentation burdens and batch certification requirements. India's pharmaceutical excipient demand creates positioning opportunities for certified domestic production expansion.
- Solvent Use:Electronics and coatings applications requiring metal-ion specifications below 10 parts per billion.
- Textile Manufacturing:Fiber processing and dyeing applications across Vietnam and Indonesia where derivative capacity is fragmenting geographically.
Chemical production commands volume leadership. Food additives sustain margin premiums through regulatory certification barriers.
End User:
Customer concentration varies by purity requirement, with pharmaceutical and food-grade buyers accepting longer supply chains for certified material.
- Chemicals:Integrated and merchant producers of vinyl acetate monomer, acetic anhydride, and derivative esters. Celanese Corporation's methanol-to-acetic-acid integration across Singapore and Nanjing exemplifies margin control strategies in this segment. Coal-based syngas routes face compression from MEE dual carbon mandates.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient synthesis requiring glacial grades with comprehensive impurity profiling. Japanese and Korean suppliers dominate high-purity imports, exposing buyers to currency and shipping cost pressure.
- Food & Beverage:Acidulant applications with FSSAI compliance requirements in India and equivalent national food safety frameworks across Southeast Asia.
- Plastics:Vinyl acetate monomer feedstock for adhesives and coatings serving construction and automotive sectors.
Chemicals sector anchors volume offtake. Pharmaceuticals segment climbs fastest on excipient compliance tightening.
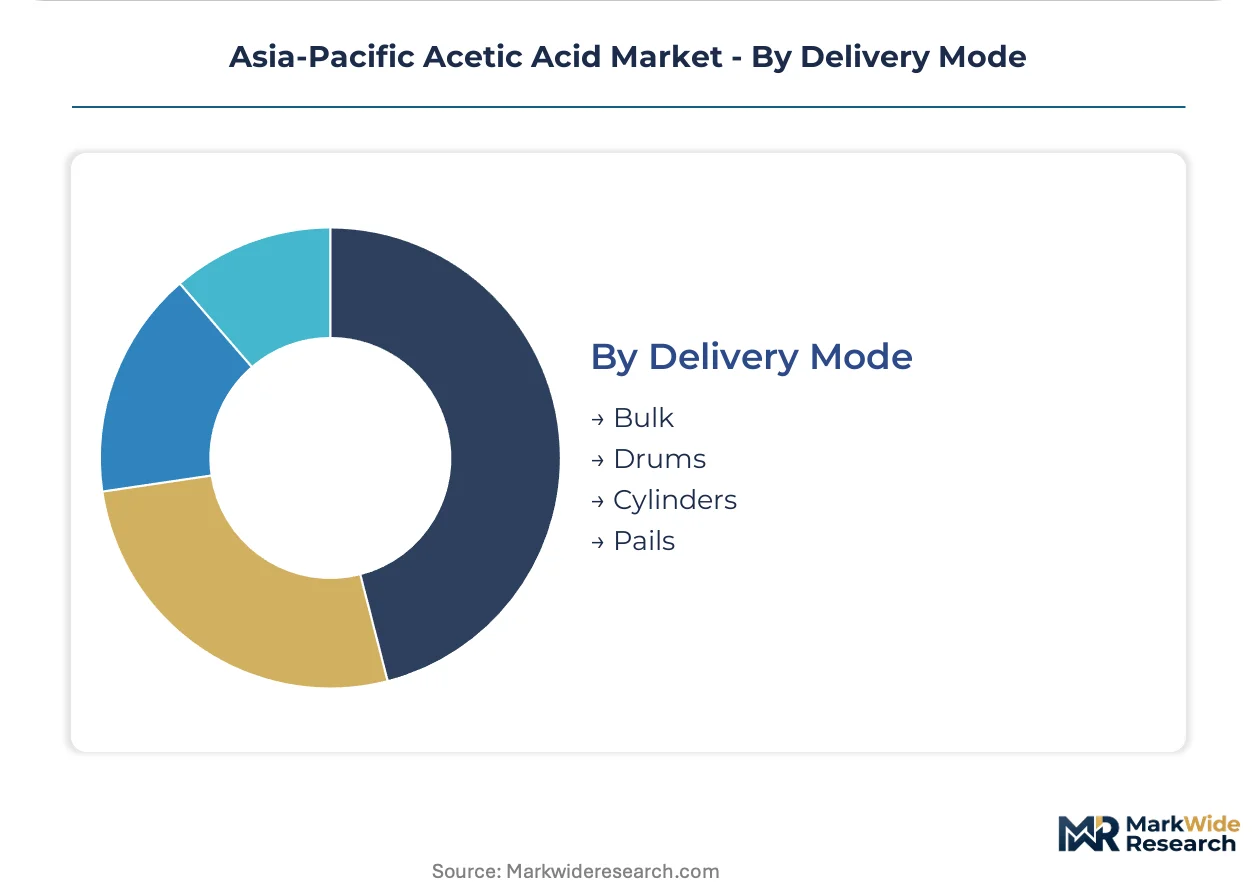
Delivery Mode:
Logistics configuration determines minimum viable order size and inventory carrying cost structures for buyers across the region.
- Bulk:Dedicated-vessel and pipeline delivery for integrated derivatives producers with continuous consumption profiles. Coastal concentration in Zhejiang and Jiangsu creates geographic vulnerability to port congestion or regional emission shutdowns.
- Drums:Standard intermediate packaging for mid-size chemical processors with batch manufacturing schedules.
- Cylinders:Pressurized containment for anhydrous and high-purity grades requiring moisture exclusion.
- Pails:Small-lot format for pharmaceutical and food-grade applications with stringent lot traceability requirements.
Bulk delivery retains volume dominance. Modular tank-container formats gain share among mid-size buyers seeking procurement flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acetic acid production scaled first through Japanese carbonylation technology transfer in the 1960s, then consolidated in Chinese coal-chemistry corridors during the 2000s. Today the Asia-Pacific market spans divergent feedstock regimes from Australian natural gas to Indian biomass pilots.
China
Vinyl acetate monomer demand from Zhejiang and Jiangsu construction adhesive clusters absorbs the majority of regional carbonylation output. MEE dual carbon emission intensity benchmarks force coal-based producers toward catalyst efficiency retrofits or carbon capture installation. The Yangtze River Delta manufacturing corridor hosts the densest derivative processing capacity, with Nanjing and Ningbo anchoring methanol-integrated supply chains.
India
Pharmaceutical excipient requirements under CDSCO compliance mandates sustain premium pricing for certified glacial grades. BIS-IS 695 industrial purity specifications extend market entry timelines for new suppliers. Gujarat's chemical manufacturing belt and Maharashtra's pharmaceutical corridors represent the fastest-expanding demand nodes for both industrial and food-grade material.
Japan
High-purity glacial acetic acid for electronics solvents and pharmaceutical applications commands sustained import demand from regional buyers. METI-administered JIS K 8355 standards shape export eligibility criteria for producers serving Japanese downstream markets. The Kansai industrial zone around Osaka maintains specialized acetylation capacity for cellulose derivative production.
South Korea
Petrochemical-integrated carbonylation units serving vinyl acetate monomer and acetic anhydride derivatives dominate domestic supply. MFDS pharmaceutical-grade specifications create compliance barriers for non-certified imports. The Ulsan petrochemical complex anchors national production capacity with downstream links to coatings and adhesive manufacturers.
Singapore
Jurong Island's methanol-to-derivatives integration attracts carbonylation operators seeking feedstock flexibility and carbon-efficient logistics. The city-state's position as a tank-container consolidation hub serves mid-size buyers across Indonesia and Vietnam. Regulatory alignment with international maritime standards supports transshipment of glacial grades to pharmaceutical markets throughout Southeast Asia.
Asia-Pacific Acetic Acid Market Competitive Landscape
Premium-margin players sit above commodity-margin players across purity-grade and certification-tier segmentation. The vendor base concentrates around three strategic tiers: integrated petrochemical majors with captive methanol supply, coal-chemistry specialists with syngas flexibility, and high-purity merchants serving pharmaceutical and electronics channels. Capacity expansion and catalyst technology licensing constitute the dominant competitive moves, with carbon capture retrofit partnerships emerging as a secondary vector.
Within the integrated petrochemical tier, Celanese Corporation and Mitsubishi Chemical Group Corporation exemplify margin control through methanol-to-derivatives chain ownership. Jiangsu Sopo anchors the coal-chemistry specialist position among Chinese domestic suppliers. Daicel Corporation occupies the high-purity merchant niche, representing the quality-certification archetype required for pharmaceutical and electronics-grade market access.
| Leading Market Players |
|---|
| Shanghai Huayi (Group) Company |
| Jiangsu Sopo (Group) Co. Ltd. |
| Celanese Corporation |
| Indian Oil Corporation Ltd. |
| Gujarat Narmada Valley Fertilizers & Chemicals Limited |
| Eastman Chemical Company |
| Daicel Corporation |
| LyondellBasell Industries |
| Mitsubishi Chemical Group Corporation |
| Others |
Pricing and Supply Chain Analysis
Modular tank-container procurement preferences among mid-size Southeast Asian buyers are fragmenting demand into smaller lots, forcing suppliers to absorb higher per-unit logistics costs or cede share to third-party logistics consolidators.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and economy-grade levels separates CDSCO-certified glacial material from BIS-IS 695 industrial specifications and undifferentiated bulk supply. Price differentiation hinges on certification burden and metal-ion purity thresholds, with pharmaceutical-grade commanding substantial premiums for traceability documentation. Cost compression in coal-based industrial tiers is intensifying because MEE emission intensity benchmarks force carbonylation operators toward catalyst retrofits or offset credit purchases. Chemical derivative manufacturers exhibit highest price sensitivity due to methanol feedstock volatility, while pharmaceutical excipient buyers accept premium positioning for compliance security.
Supply Chain Analysis
Regional distribution centers along the Yangtze River Delta and Singapore's Jurong Island anchor hub-and-spoke patterns serving Zhejiang, Jiangsu, and Southeast Asian derivative clusters. Manufacturing concentrates in China, Singapore, and South Korea, with feedstock supply drawing from Shanxi and Inner Mongolia coal-to-chemicals corridors and methanol import terminals. Rhodium catalyst sourcing from South African and Russian refiners creates single-source vulnerability for carbonylation operators. Distribution runs through dedicated-vessel contracts for integrated producers and modular tank-container networks for fragmented mid-size buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where MEE dual carbon emission intensity benchmarks are restructuring production economics and creating tiered compliance moats.
For Market Incumbents: Cement catalyst technology licensing revenue streams by retrofitting coal-based operators with iridium-promoted systems that satisfy MEE benchmarks without capacity sacrifice. Deepen backward integration into methanol supply chains across Nanjing and Singapore to buffer against Shanxi feedstock volatility. Defend margin position against emerging biobased fermentation pilots through carbon capture installation partnerships that preserve carbonylation cost advantages. For New Entrants and Emerging Players: Launch via certified pharmaceutical-grade production targeting CDSCO compliance gaps in Gujarat and Maharashtra corridors where import dependency exposes buyers to currency risk. Target India's BIS-IS 695 industrial segment through coastal manufacturing proximate to textile processing clusters in Vietnam and Indonesia. Exploit white-space in modular tank-container logistics consolidation serving mid-size derivative manufacturers seeking procurement flexibility without dedicated-vessel capital commitment. For Investors and Strategic Acquirers: Asymmetric upside sits with methanol-integrated operators possessing catalyst efficiency technology and MEE compliance headroom. Long-term viability favors assets with feedstock traceability advantages and carbon capture retrofit optionality. Monitor rhodium price volatility and South African supply disruptions as inflection indicators for working capital intensity across the carbonylation sector.| Strategic Initiative | Industry Significance |
|---|---|
| Catalyst Efficiency Retrofit | Iridium-promoted systems unify MEE compliance with margin preservation for carbonylation operators. |
| Carbon Capture Installation | Post-combustion capture partnerships open technology licensing revenue under China's dual carbon framework. |
| Backward Integration into Methanol | Feedstock traceability advantages accelerate MEE response speed for integrated producers. |
| Pharmaceutical-Grade Certification | CDSCO compliance investments capture premium positioning in India's excipient supply gap. |
| Modular Logistics Consolidation | Tank-container hub operations fragment procurement patterns across Southeast Asian derivative clusters. |
Research Methodology
Multiple input streams — carbonylation plant managers, downstream VAM procurement leads, pharmaceutical excipient quality directors, and tank-container logistics operators — were reconciled against customs trade data, MEE emission disclosure filings, CDSCO import registration databases, and SEC chemical company filings. Primary interviews with catalyst technology licensors and carbon capture engineering firms validated secondary intelligence on retrofit economics. Bottom-up capacity modeling and top-down demand triangulation across vinyl acetate monomer, acetic anhydride, and pharmaceutical solvent applications anchored volume estimates.
Data-stream reconciliation applied grade-tier, end-use industry, and regional production hub segmentation across the projection horizon. CAGRs derived from trend extrapolation of MEE compliance timelines, methanol feedstock cost trajectories, and pharmaceutical excipient demand curves. Industry-specific forecast inputs incorporated rhodium price volatility assumptions and coal-to-chemicals capacity expansion patterns in Shanxi and Inner Mongolia.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt MEE benchmark tightening or South African rhodium supply disruption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
China Methanol Market
Chemicals
Global E Series Glycol Ether Market
Chemicals
Hydrophobing Agents Market
Chemicals
Leather Tanning Chemicals Market
Chemicals
Silicone Textile Softeners Market
Chemicals
Global Glycine Market
Chemicals
Mining Flotation Chemicals Market
Chemicals
Canada Methanol Market
Chemicals
Africa Sodium Cyanide Market
Chemicals
Insect Repellent Active Ingredients Market
Chemicals
Industrial Odor Management Market
Chemicals
United States Construction Chemicals Market
Chemicals
Global P-Phenylenediamine Market
Chemicals
Guaiacol Market
Chemicals
Precious Metal Plating Chemicals Market
Chemicals
Acrylic Acids and Esters Market