
 N-Propanol Market | 2026-2036
N-Propanol Market Size, Share, and Industry Trends Forecast 2026-2036
N-Propanol Market Intelligence
Paint and coatings demand is broadening as architectural and automotive finishers shift toward low-VOC systems that rely on oxygenated solvents. BASF SE leverages its integrated C3 chemistry chain to secure feedstock flexibility across European and Asian production nodes. INEOS Group anchors its position through large-scale oxo-alcohol capacity at its Seal Sands facility. Sasol Limited differentiates via Fischer-Tropsch-derived propanol streams that serve specialty coating segments in South Africa and export markets.
N-Propanol is a three-carbon primary alcohol with the molecular formula C₃H₇OH, typically manufactured through hydroformylation of ethylene followed by hydrogenation, yielding a colorless liquid with a boiling point of 97 degrees Celsius and miscibility in water, organic solvents, and oils. Its primary industrial purpose centers on solvent applications, chemical synthesis, and surface-active formulations where moderate evaporation rates and favorable toxicological profiles matter. Industrial Grade product type dominates volume throughput for coatings and cleaning applications, while Pharmaceutical Grade commands premium positioning due to stringent USP and EP monograph compliance. Chemical Intermediates application is deepening as propylamines and propyl esters expand in agrochemical and polymer additive chains.
EPA regulates N-Propanol under TSCA Section 5 for new chemical notifications and OSHA sets permissible exposure limits at 200 ppm for workplace environments, while REACH in Europe mandates registration dossiers with full toxicological profiles for import volumes above one tonne annually. FDA oversight applies to pharmaceutical-grade material through ICH Q3C residual solvent guidelines, which cap propanol limits in drug substances. Stakeholders must monitor evolving bio-based certification schemes and carbon intensity accounting rules that will reshape feedstock sourcing decisions and capital allocation across production networks.
Market Dynamics
Waterborne coating formulations are absorbing oxygenated solvent volumes as architectural and automotive finishers retool lines under tightening VOC ceilings. This formulation shift concentrates purchasing power among large coatings manufacturers with dedicated solvent specifications.
Growth Catalysts
- REACH Purity Thresholds:Germany's chemical framework mandates higher-grade propanol for intermediate synthesis, pulling pharmaceutical-grade volumes into European supply chains.
- East Asian Coatings Expansion:Chinese and Korean paint manufacturers are expanding waterborne capacity, absorbing industrial-grade solvent at scale.
- Fischer-Tropsch Streams:Synthetic alcohol production from coal-to-liquid facilities offers alternative feedstock pathways for specialty coating segments.
Market Restraints
- Ethylene Feedstock Volatility:Hydroformylation economics hinge on ethylene pricing, exposing margins to naphtha-cracker output swings.
- Oxo-Alcohol Concentration:Large-scale European production nodes control bulk supply, limiting spot-market liquidity for mid-tier buyers.
- Isopropanol Substitution:Secondary alcohol alternatives compete in disinfectant and solvent cleaning applications where evaporation profiles overlap.
Strategic Opportunities
- Indian Pharmaceutical Demand:CDSCO oversight of active pharmaceutical ingredient manufacturing is expanding propyl-ester intermediate requirements.
- Biobased Certification Schemes:Emerging carbon-intensity accounting rules favor fermentation-derived propanol in European coatings procurement.
- Agrochemical Propylamines:Herbicide and fungicide synthesis chains are deepening consumption of propanol-derived intermediates in Brazil and Argentina.
Industry Challenges
- USP and EP Compliance Timelines:Pharmaceutical-grade certification requires extended validation cycles that strain working capital for smaller producers.
- Hydroformylation Catalyst Expertise:Rhodium and cobalt catalyst management demands specialized metallurgical skills scarce outside major integrated producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | N-Propanol Market |
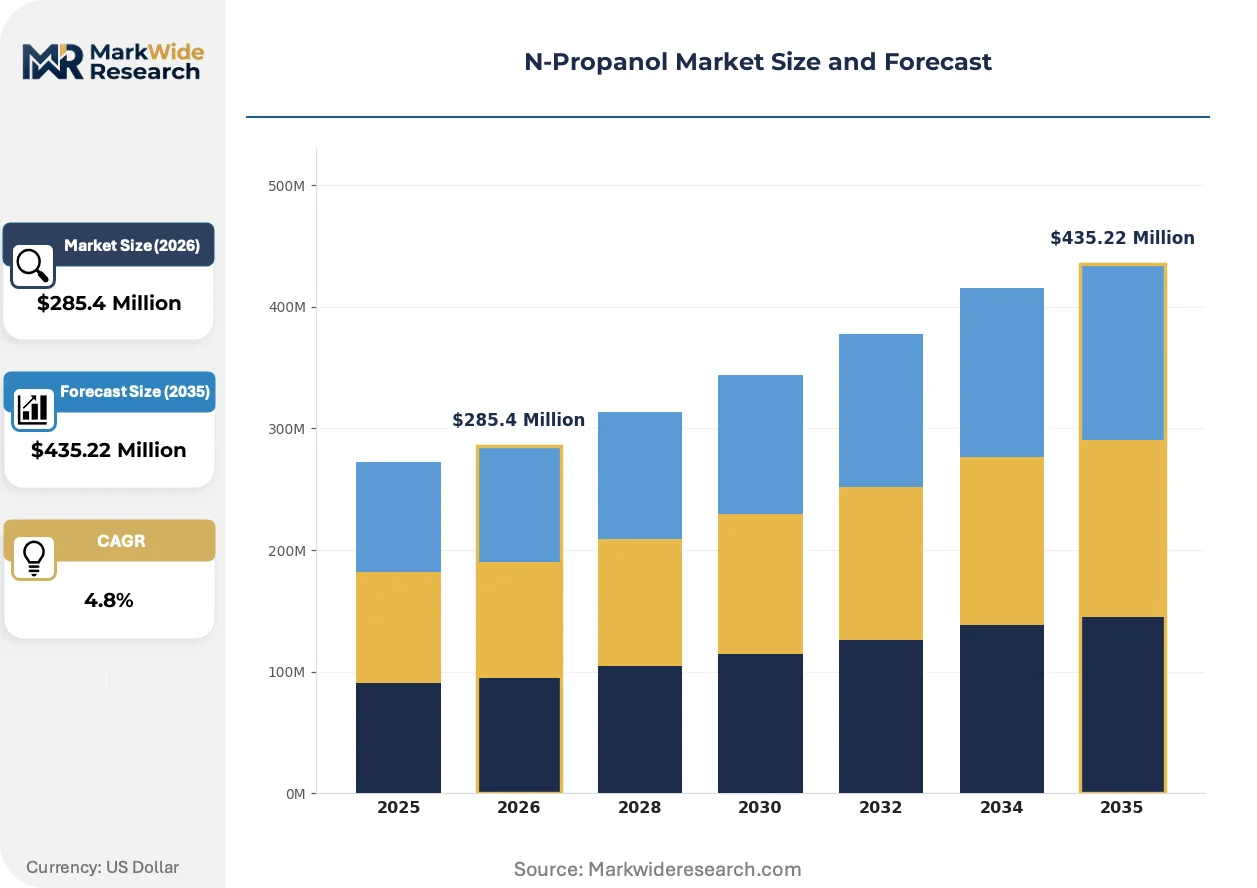
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $435.22 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Purity Grade, Bio-Based, Pharmaceutical Grade Application: Solvents, Antiseptics, Paint Additives, Chemical Intermediates End User: Chemicals, Pharmaceuticals, Coatings, Personal Care Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Oxea GmbH, INEOS Group, BASF SE, Zibo Nalcohol Chemical Co., Ltd., LyondellBasell Industries, Dow Inc., Sasol Limited, DuPont de Nemours, Inc., Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
N-Propanol Market Strategic Shifts & Innovations
Process intensification and regulatory chemistry are reshaping how propanol manufacturers configure feedstock flexibility and product slate optimization. Three developments warrant particular attention.
Membrane-based propanol-water separation is overtaking conventional distillation in new plant designs. Coatings manufacturers with stringent moisture specifications are specifying membrane-refined material. This shift compresses energy intensity in solvent finishing operations.
EPA's TSCA Section 5 notification requirements for new chemical substances are tightening data submission standards for propanol derivatives. Industrial users must now document full toxicological profiles for novel propyl ester formulations. Specialty chemical divisions are responding by pre-registering intermediate categories rather than individual compounds.
Pharmaceutical procurement teams are consolidating solvent suppliers against ICH Q3C residual solvent guidelines. Multi-site drug manufacturers now audit propanol producers for consistent impurity profiling across batches. This concentration is most visible among generic API manufacturers in India and China seeking USDMF acceptance.
N-Propanol Market Segmentation
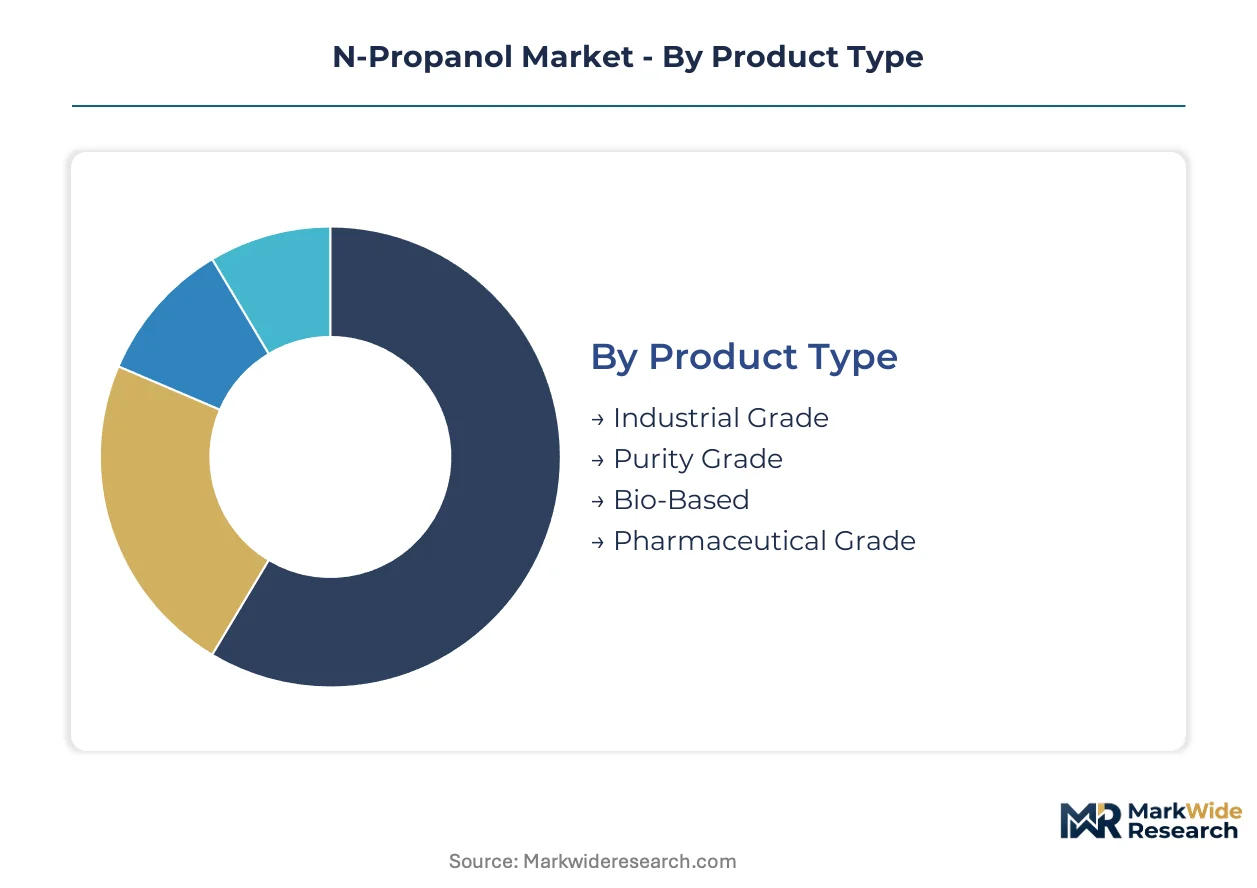
N-Propanol demand fragments across purity tiers and application specifications that dictate pricing power and supply chain access. Coatings manufacturers, pharmaceutical formulators, and chemical intermediates producers each impose distinct certification and logistics requirements that reshape competitive positioning.
Product Type:
Supply concentration favors large-scale hydroformylation operators with integrated hydrogenation and finishing capabilities. Smaller producers compete through bio-based or specialty pharmaceutical certifications that command premium positioning.
- Industrial Grade:Standard hydroformylation output serves coatings and cleaning applications where moisture content and color specifications remain permissive. Chinese and Korean waterborne paint manufacturers absorb the largest volumes as VOC regulations tighten. BASF and INEOS leverage integrated C3 chains to defend bulk pricing power.
- Pharmaceutical Grade:USP and EP monograph compliance requires extended validation cycles and batch-level impurity profiling. Indian generic API manufacturers concentrate procurement among audited suppliers seeking USDMF acceptance. CDSCO oversight is expanding validation requirements for propyl-ester intermediates.
- Purity Grade:Intermediate specification for electronics and specialty chemical synthesis where trace metal limits matter.
- Bio-Based:Fermentation-derived material qualifying under emerging European carbon-intensity accounting rules for coatings procurement.
Today's leader: Industrial Grade. Tomorrow's challenger: Pharmaceutical Grade.
Application:
Application mix reflects end-use migration toward waterborne systems and pharmaceutical synthesis chains. Solvent demand remains volume-dominant while chemical intermediates deepen value capture.
- Solvents:Oxygenated solvent properties—moderate evaporation rate, favorable toxicological profile, water miscibility—support architectural and automotive coating formulations. East Asian manufacturers are retooling lines under stricter VOC ceilings, pulling industrial-grade volumes. Membrane-based water separation is overtaking distillation in new plant designs to meet stringent moisture specifications.
- Chemical Intermediates:Propylamines and propyl esters expand in agrochemical and polymer additive chains. Brazilian and Argentine herbicide synthesis is deepening consumption. Rhodium and cobalt catalyst management demands specialized metallurgical skills scarce outside major integrated producers.
- Antiseptics:Disinfectant applications compete with isopropanol substitution where evaporation profiles overlap.
- Paint Additives:Flow and leveling agents in high-performance coating systems.
Solvents command current volume leadership. Chemical intermediates are climbing the fastest as agrochemical synthesis chains deepen propanol-derived consumption.
End User:
End-user concentration is shifting toward pharmaceutical and coatings procurement teams with consolidated supplier audits and dedicated solvent specifications.
- Chemicals:Agrochemical and polymer additive manufacturers driving intermediate demand.
- Pharmaceuticals:Multi-site drug manufacturers audit propanol producers for consistent impurity profiling across batches. ICH Q3C residual solvent guidelines cap propanol limits in drug substances, concentrating purchasing power among validated suppliers.
- Coatings:Large architectural and automotive finishers with dedicated solvent specifications and waterborne formulation expertise.
- Personal Care:Cosmetic and fragrance applications requiring odor and color consistency.
Coatings anchor present volume. Pharmaceuticals are gaining share fastest through consolidated procurement and regulatory validation requirements.
Distribution Channel:
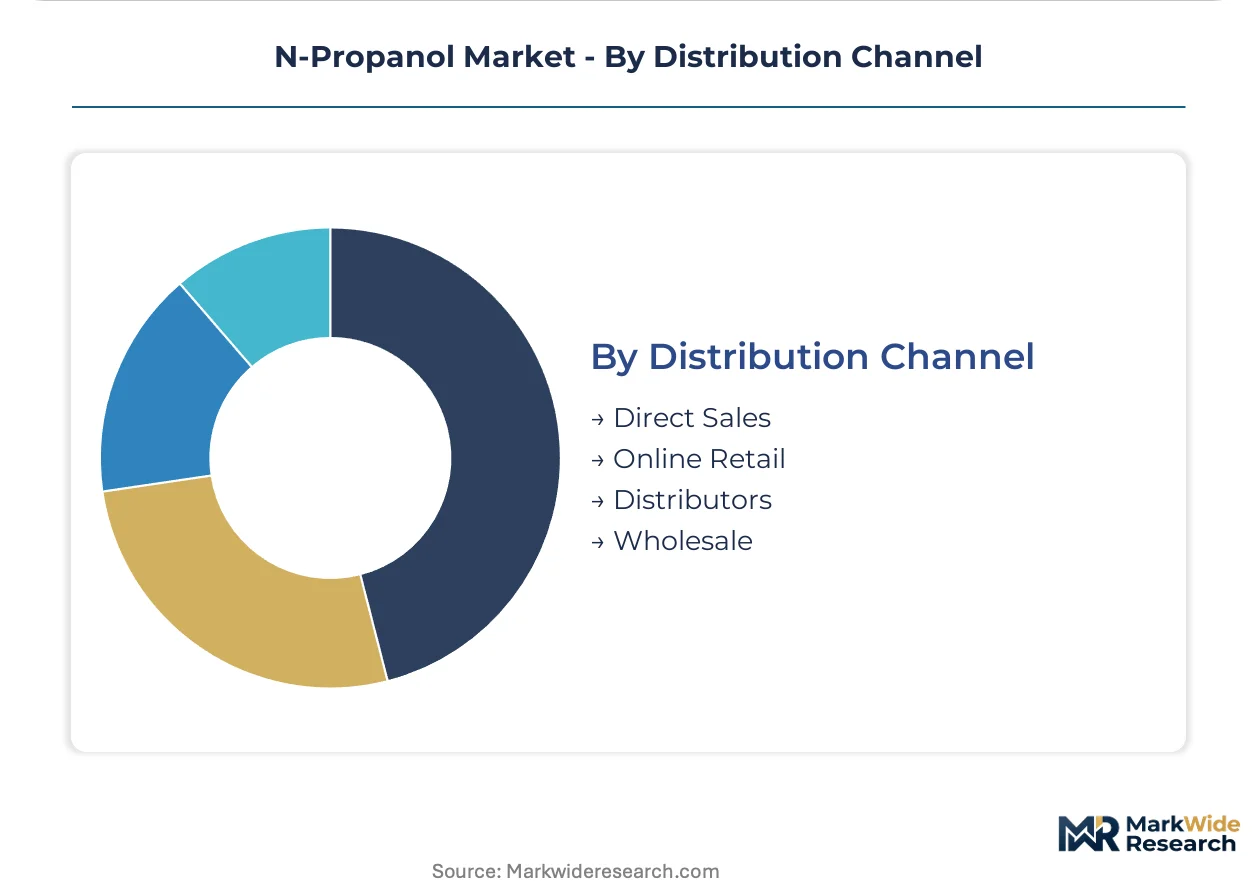
Channel structure reflects customer scale and specification complexity. Large-volume coatings and chemical manufacturers favor direct supply relationships.
- Direct Sales:Integrated producers supply large coatings and pharmaceutical manufacturers under long-term contracts with dedicated specifications.
- Distributors:Regional chemical distributors serve mid-tier buyers with spot requirements and mixed solvent procurement needs.
- Wholesale:Bulk terminal and tank farm access for industrial-grade volumes.
- Online Retail:Small-package laboratory and specialty chemical sales.
Direct sales dominate current value capture. Distributors represent the expanding channel for mid-tier buyers seeking supply security outside concentrated production nodes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping N-Propanol production geography as manufacturers relocate to jurisdictions with lower compliance burdens for hydroformylation operations. Cost-of-compliance gaps between REACH-regulated Europe and emerging Asian chemical hubs are accelerating capacity migration toward integrated petrochemical corridors.
China
Waterborne coatings manufacturers in the Yangtze River Delta and Pearl River Delta are absorbing industrial-grade solvent volumes as MEE enforces stricter VOC ceilings on architectural and automotive finishers. Zibo Nalcohol Chemical anchors production in Shandong Province, supplying domestic paint retooling campaigns.
Germany
REACH mandates higher purity thresholds for chemical intermediates, pulling pharmaceutical-grade propanol into European supply chains. BASF SE leverages integrated C3 chemistry at its Ludwigshafen complex to defend feedstock flexibility. The country's oxo-alcohol expertise concentrates specialized catalyst management capabilities.
United States
EPA TSCA Section 5 notifications are tightening data submission standards for propanol derivatives used in specialty coatings. Gulf Coast petrochemical corridors host hydroformylation capacity tied to ethylene feedstock from regional crackers. OSHA workplace exposure limits at 200 ppm shape handling protocols.
India
CDSCO oversight of active pharmaceutical ingredient manufacturing is expanding propyl-ester intermediate requirements. Gujarat and Maharashtra pharmaceutical clusters are consolidating solvent suppliers against ICH Q3C residual solvent guidelines. Generic API manufacturers seek USDMF acceptance through audited propanol sourcing.
South Africa
Sasol Limited's Fischer-Tropsch-derived propanol streams serve specialty coating segments across domestic and export markets. The Secunda coal-to-liquid complex offers alternative feedstock pathways distinct from ethylene-based hydroformylation. Regional agrochemical formulators in KwaZulu-Natal absorb intermediate volumes for herbicide synthesis.
N-Propanol Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated petrochemical majors controlling bulk hydroformylation output while regional distributors capture mid-tier spot demand. The vendor base concentrates around large-scale oxo-alcohol nodes with captive hydrogenation and finishing capabilities. Three archetypes dominate: integrated C3 chemistry operators, Fischer-Tropsch synthetic alcohol producers, and fermentation-derived bio-based specialists. Competitive moves center on backward integration into ethylene feedstock and membrane-based separation technology licensing to meet stringent moisture specifications.
Among European integrated operators, Oxea GmbH and BASF SE exemplify the C3 chemistry archetype with multi-node production footprints spanning Ludwigshafen and Asian licensing arrangements. INEOS Group anchors the scale-driven tier through its Seal Sands oxo-alcohol complex, representing concentrated Atlantic basin supply. Sasol Limited occupies a distinctive position as the Fischer-Tropsch specialist, leveraging coal-to-liquid feedstock differentiation for coating segments where synthetic alcohol properties command specification premiums.
| Leading Market Players |
|---|
| Oxea GmbH |
| INEOS Group |
| BASF SE |
| Zibo Nalcohol Chemical Co., Ltd. |
| LyondellBasell Industries |
| Dow Inc. |
| Sasol Limited |
| DuPont de Nemours, Inc. |
| Eastman Chemical Company |
| Others |
Cost & Logistics Intelligence
Ethylene feedstock index volatility cascades through hydroformylation economics into three-tier pricing structure across premium, standard, and economy levels. BASF and INEOS leverage captive C3 chemistry chains to buffer margin compression while mid-tier buyers absorb spot-market exposure from naphtha-cracker output swings.
Pricing Analysis
Distributor margin compression runs through industrial-grade spot transactions as Chinese waterborne coatings manufacturers consolidate procurement volumes. Pharmaceutical-grade pricing stratifies across premium, standard, and economy tiers driven by USP certification level and batch-level impurity profiling investment. Cost compression in industrial-grade material is intensifying because membrane-based separation technology licensing spreads among new plant designs. Generic API manufacturers in India exhibit highest price sensitivity due to USDMF validation timelines, while specialty coatings formulators in South Africa show lowest sensitivity for Fischer-Tropsch-derived specifications.
Supply Chain Analysis
Single-source vulnerability sits with rhodium and cobalt catalyst suppliers concentrated outside major integrated producers. Geographic supply concentration centers on Germany, China, and South Africa as dominant hydroformylation and Fischer-Tropsch production nodes. Raw material dependencies rest on ethylene from naphtha crackers, syngas from coal gasification, and specialized hydrogenation catalysts. Tariff exposure on catalyst imports from South Africa presents structural risk for European propylamine synthesis chains. Distribution runs through direct sales contracts for large coatings and pharmaceutical manufacturers, with regional chemical distributors capturing mid-tier spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
N-Propanol functions as a regulatory compounder where REACH purity thresholds and ICH Q3C residual solvent guidelines continuously elevate grade requirements across pharmaceutical and coatings applications.
For Market Incumbents: Acquire membrane-based separation technology licensing to defend pharmaceutical-grade positioning against emerging bio-based fermentation entrants. BASF and INEOS should extend backward integration into ethylene feedstock through regional cracker partnerships, as hydroformylation catalyst expertise scarcity outside Ludwigshafen and Seal Sands creates defensive moats against mid-tier competitors. For New Entrants and Emerging Players: Premium-economy price-point gap in Indian pharmaceutical-grade procurement offers white-space entry for fermentation-derived propanol qualifying under emerging carbon-intensity accounting rules. Target agrochemical propylamine intermediates in Brazil and Argentina where herbicide synthesis chains deepen consumption outside established European supply nodes. Go-to-market angle centers on CDSCO validation support bundled with solvent supply contracts. For Investors and Strategic Acquirers: Asymmetric upside sits with Fischer-Tropsch synthetic alcohol producers possessing coal-to-liquid feedstock differentiation and specialty coatings segment access. Long-term viability favors assets with captive syngas generation and membrane-refining capability across the analysis window. Acquisition target archetype: regional oxo-alcohol operators in East Asia with waterborne coatings customer concentration. Signal to watch: bio-based certification scheme adoption rates among European coatings procurement teams.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Feedstock | Captive naphtha-cracker access buffers margin exposure for Ludwigshafen and Seal Sands operators. |
| Membrane-Based Separation Technology Licensing | Membrane-refined material commands specification premiums from moisture-sensitive coatings formulators. |
| Pharmaceutical-Grade Certification Investment | USP and EP compliance opens USDMF acceptance pathways for Indian generic API manufacturers. |
| Long-term Supply Agreement with Coatings Manufacturers | Direct contracts with Chinese waterborne paint retooling campaigns secure volume commitments. |
| Joint Venture for Fischer-Tropsch Capacity Expansion | Coal-to-liquid feedstock differentiation serves specialty coating segments in South African export markets. |
Research Approach
Bottom-up coatings and pharmaceutical modeling reconciled against top-down hydroformylation capacity tracking forms the analytical core of this study. Primary interviews with plant managers at oxo-alcohol complexes, procurement leads at waterborne coatings manufacturers, technical R&D directors, and distribution channel partners combined with secondary validation from customs and trade data, SEC filings, ECHA registration dossiers, and CDSCO manufacturing facility inspections. Triangulation between demand-side consumption patterns and supply-side production economics ensures statistical integrity across segmentation dimensions.
Input-output matrix framing connects ethylene feedstock availability to hydroformylation output tiers, then maps grade-specific pricing to end-use absorption rates across the projection horizon. Segmentation dimensions modeled include purity grade tier, end-use industry, regional production hub, and certification requirement cluster. CAGRs were derived through regression analysis of historical consumption patterns against regulatory milestone timing and capacity expansion announcements. Forecast inputs incorporate membrane technology adoption curves and bio-based certification scheme penetration rates.
The model assumes a particular technology adoption path; alternative pathways for fermentation-derived propanol would alter the outlook if carbon-intensity accounting rules accelerate faster than projected. Forecasts reflect assumptions about REACH enforcement consistency and MEE VOC ceiling implementation timelines in Chinese provinces. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Monoisopropanolamine (MIPA) Market
Chemicals
Coagulant Market
Chemicals
Pyrogallol Market
Chemicals
Cummene Derivatives Market
Chemicals
Sodium Fluorosilicate Market
Chemicals
Sodium Ethyl P-Hydroxybenzoate Market
Chemicals
Xanthates Market
Chemicals
Roofing Chemical Market
Chemicals
Butylated Triphenyl Phosphate Market
Chemicals
Calcium Disodium Ethylene Diamine Tetra-Acetate Market
Chemicals
P-Hydroxybenzoic Acid (PHBA) Market
Chemicals
Global Hydrogen Fluoride Market
Chemicals
India Ethoxylates Market
Chemicals
Guaiazulene Market
Chemicals
Chlorosilane Market
Chemicals
Aerosol Insecticides Market