
 DNA Mass Ladder Market | 2026-2036
DNA Mass Ladder Market Size, Share, and Industry Trends Forecast 2026-2036
DNA Mass Ladder Market Analytics
Capillary electrophoresis and digital fragment analysis is fragmenting traditional agarose gel-based sizing workflows across molecular biology laboratories. Thermo Fisher Scientific leverages its integrated instrument-reagent ecosystem to sustain dominance in high-throughput sequencing facilities. New England Biolabs anchors its position through specialized enzyme-ladder bundled offerings that reduce protocol variability. Promega Corporation competes by extending its footprint in automated electrophoresis platforms that require certified mass standards.
DNA mass ladders consist of defined mixtures of DNA fragments with known base-pair lengths, typically ranging from tens to tens of thousands of base pairs, manufactured through controlled restriction enzyme digestion or PCR amplification for precise molecular weight calibration in nucleic acid separation. Pre-stained ladders now command the largest revenue share as laboratories prioritize workflow efficiency over manual staining steps, while RNA ladders represent the fastest-expanding product type amid accelerating transcriptomics research. Gel electrophoresis remains the dominant application segment due to its ubiquity in routine quality control, though sequencing-aligned ladder demand is capturing margin pools as NGS library validation requirements intensify.
The US FDA enforces quality system regulations that mandate traceable nucleic acid standards for diagnostic assay development, while the EU IVDR framework imposes stricter conformity assessment on molecular sizing reagents used in clinical settings. ISO 17025 accreditation requirements for analytical laboratories further shape procurement criteria, favoring suppliers with documented batch consistency and measurement uncertainty data. Stakeholders must monitor how evolving pharmacogenomics regulatory pathways in Japan and South Korea create new certification requirements for ladder products entering precision medicine supply chains.
Market Dynamics
Capillary electrophoresis platforms and automated fragment analyzers are compressing traditional agarose gel workflows, forcing ladder suppliers to certify mass standards for digital sizing outputs rather than visual band matching alone.
Growth Catalysts
- EU IVDR Conformity Pathways:The EU's In Vitro Diagnostic Regulation mandates traceable nucleic acid sizing standards for clinical molecular diagnostics, expanding procurement of certified ladders by diagnostic manufacturers seeking CE marking.
- Transcriptomics Research Expansion:Academic laboratories in the United States, Germany, and China are accelerating RNA ladder consumption for gene expression profiling and non-coding RNA characterization workflows.
- NGS Library Validation Protocols:High-throughput sequencing facilities require precise mass ladders for fragment size confirmation prior to cluster generation, embedding ladder standards into automated quality control pipelines.
Market Restraints
- Input Cost Volatility:Purified nucleic acid starting materials and restriction enzyme costs fluctuate with biopharma fermentation capacity constraints, pressuring batch-to-batch pricing consistency for premium ladder grades.
- Supply Concentration Risk:A limited number of GMP-certified manufacturers control high-purity DNA fragment production for clinical-grade ladders, creating vulnerability to single-site production disruptions.
- Technical Limitation in Digital Sizing:Fluorescent dye interaction variability between ladder and sample fragments introduces measurement uncertainty that capillary electrophoresis platforms struggle to fully algorithmically correct.
Strategic Opportunities
- Pharmacogenomics Certification in Japan:METI and PMDA pathways for precision medicine diagnostics are creating demand for ladder products with documented measurement uncertainty suitable for companion diagnostic development.
- Automated Electrophoresis Integration:Bundling certified mass ladders with capillary instrument consumable contracts locks in recurring revenue streams as laboratories standardize on integrated platform ecosystems.
- South Korean Biocluster Expansion:The Songdo and Osong bioclusters are attracting contract manufacturing organizations that require nucleic acid sizing standards for plasmid and viral vector quality control.
Industry Challenges
- ISO 17025 Accreditation Timelines:Analytical laboratories demand batch-specific measurement uncertainty data that smaller ladder suppliers struggle to generate within competitive quotation windows.
- Multiplex Dye Compatibility:Pre-stained ladder formulations must maintain spectral separation across evolving fluorescent detection channels, requiring continuous reformulation investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DNA Mass Ladder Market |
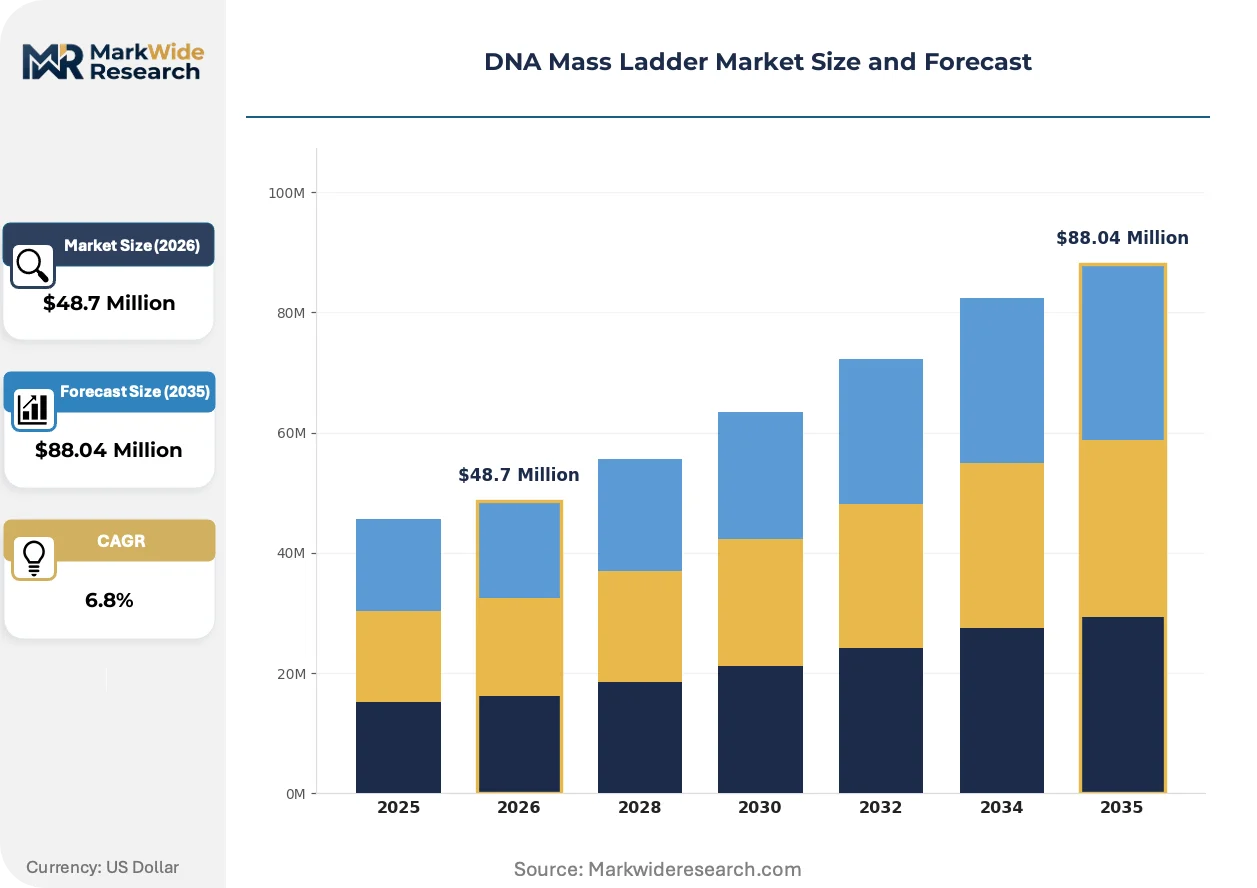
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-stained Ladders, DNA Ladders, RNA Ladders, Standard Ladders Application: Gel Electrophoresis, PCR Analysis, Sequencing, Cloning End User: Research Laboratories, Academic Institutions, Pharmaceutical Companies, Biotech Firms Packaging Type: Vials, Kits, Tubes, Disposable Formats |
| Companies Covered | Thermo Fisher Scientific, New England Biolabs, Promega Corporation, Bio-Rad Laboratories, Merck KGaA, Takara Bio, Agilent Technologies, QIAGEN, MilliporeSigma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DNA Mass Ladder Market Evolving Landscape
Digital fragment analysis platforms are recalibrating how laboratories validate nucleic acid size and concentration, compressing the traditional gel-based workflow into software-mediated sizing calls with stricter traceability requirements.
Capillary electrophoresis instrumentation is digitizing DNA mass ladder consumption patterns by replacing visual band interpretation with electropherogram-based sizing algorithms. Core sequencing facilities in the United States and China are adopting these platforms at accelerating rates. This shift is digitizing procurement criteria toward ladders with certified base-pair-to-mass conversion factors rather than approximate visual standards.
The EU IVDR framework is tightening conformity assessment requirements for nucleic acid sizing reagents used in clinical diagnostic settings. Manufacturers must now compile technical documentation demonstrating batch consistency and metrological traceability for CE-marked ladder products. Diagnostic assay developers in Germany and France are responding by qualifying dual-source ladder suppliers to mitigate certification timeline risks.
Consolidated purchasing by multi-site sequencing centers is compressing vendor negotiation cycles and unbundling after-sales technical support from consumable pricing. Large academic medical centers and contract research organizations are centralizing ladder procurement through group purchasing organizations. This pattern is most visible in the United States, where integrated delivery networks are standardizing on single-source ladder specifications across distributed laboratory networks.
DNA Mass Ladder Market Segmentation
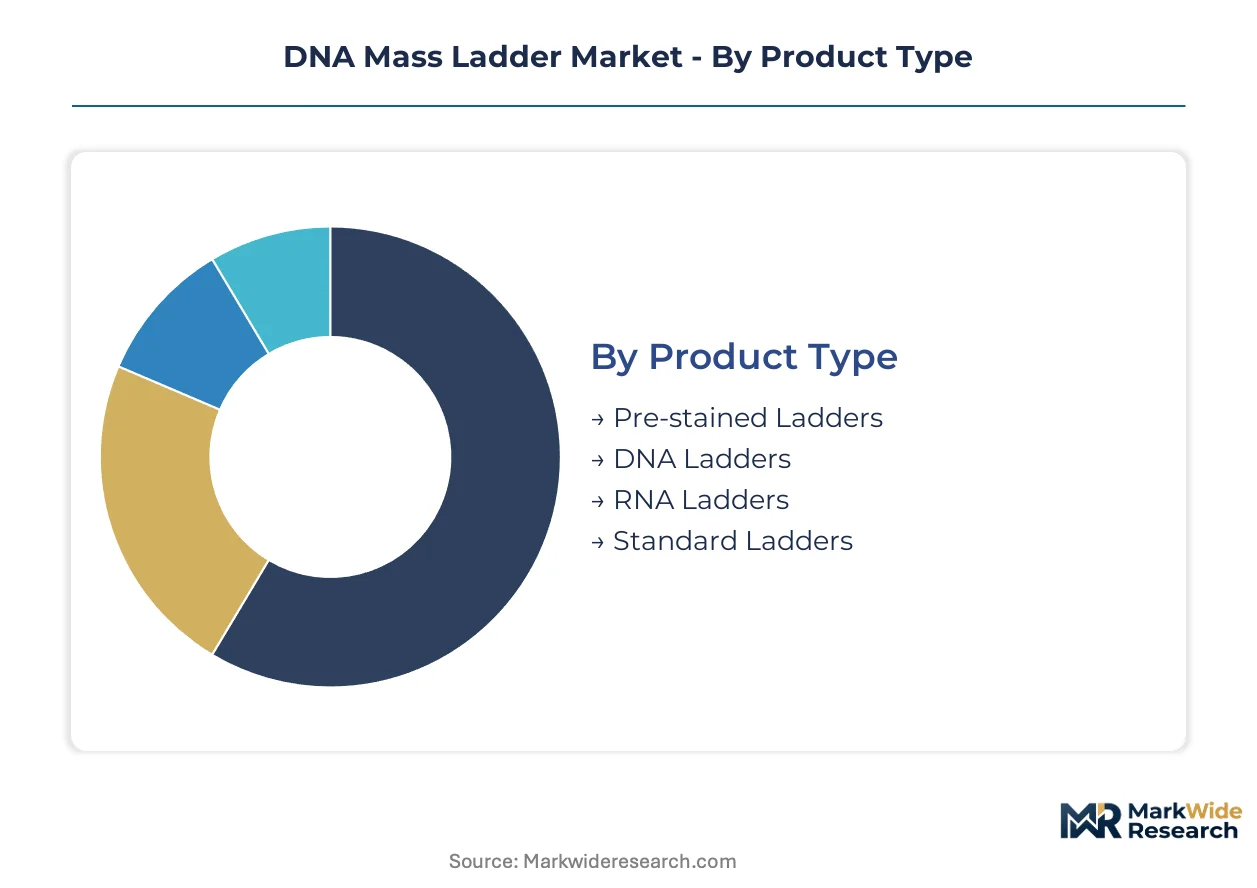
DNA mass ladder procurement patterns diverge sharply across product formats and end-use environments. Laboratories select ladder specifications based on workflow automation level, regulatory compliance tier, and detection platform compatibility.
Product Type:
Mature pre-stained formats dominate routine workflows while emerging RNA variants capture transcriptomics expansion.
- Pre-stained Ladders:These formulations integrate fluorescent dyes directly into DNA fragment mixtures, eliminating post-electrophoresis staining steps. Pharmaceutical companies in the United States and Germany prioritize these for high-throughput screening protocols where manual processing steps create bottlenecks. FDA quality system regulations for molecular diagnostics reinforce demand for lot-traceable pre-stained products with documented dye stability profiles.
- RNA Ladders:Defined RNA fragment mixtures calibrated for ribonucleic acid molecular weight standards. Academic institutions in China and Germany are accelerating consumption for non-coding RNA characterization and gene expression profiling workflows. The EU IVDR framework imposes stricter conformity assessment on RNA sizing reagents used in clinical transcriptomics, favoring suppliers with ISO 17025-accredited measurement uncertainty data.
- DNA Ladders:Conventional unstained DNA fragment standards requiring post-run visualization.
- Standard Ladders:Basic molecular weight calibration mixtures for non-regulated research environments.
Pre-stained ladders retain volume leadership; RNA ladders hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity gel workflows from premium sequencing validation segments.
- Gel Electrophoresis:The foundational nucleic acid separation technique employing agarose or polyacrylamide matrices. Research laboratories across the United States, Germany, and China consume these ladders for routine quality control of PCR products and plasmid preparations. Capillary electrophoresis platforms are compressing traditional gel workflows, forcing suppliers to certify mass standards for digital sizing outputs.
- Sequencing:NGS library validation demands precise fragment size confirmation prior to cluster generation. High-throughput sequencing facilities require certified base-pair-to-mass conversion factors rather than approximate visual standards. The EU IVDR framework tightens traceability requirements for sizing reagents used in clinical diagnostic sequencing pipelines.
- PCR Analysis:Amplicon size verification for polymerase chain reaction optimization.
- Cloning:Insert and vector confirmation for recombinant DNA construction.
Gel electrophoresis retains volume leadership; sequencing holds the steepest expansion curve.
End User:
Customer type determines procurement sophistication, with pharmaceutical buyers demanding GMP documentation that academic buyers rarely require.
- Research Laboratories:Core facilities and institutional service centers standardizing on integrated instrument-reagent ecosystems. Consolidated purchasing by multi-site sequencing centers in the United States is compressing vendor negotiation cycles.
- Pharmaceutical Companies:Molecular diagnostic developers requiring CE-marked ladders for EU IVDR compliance and FDA-traceable standards for companion diagnostic programs. These buyers qualify dual-source suppliers to mitigate certification timeline risks.
- Academic Institutions:University laboratories with flexible procurement protocols and price-sensitive reagent selection.
- Biotech Firms:Emerging companies prioritizing workflow efficiency over comprehensive documentation.
Research laboratories retain volume leadership; pharmaceutical companies hold the steepest expansion curve.
Packaging Type:
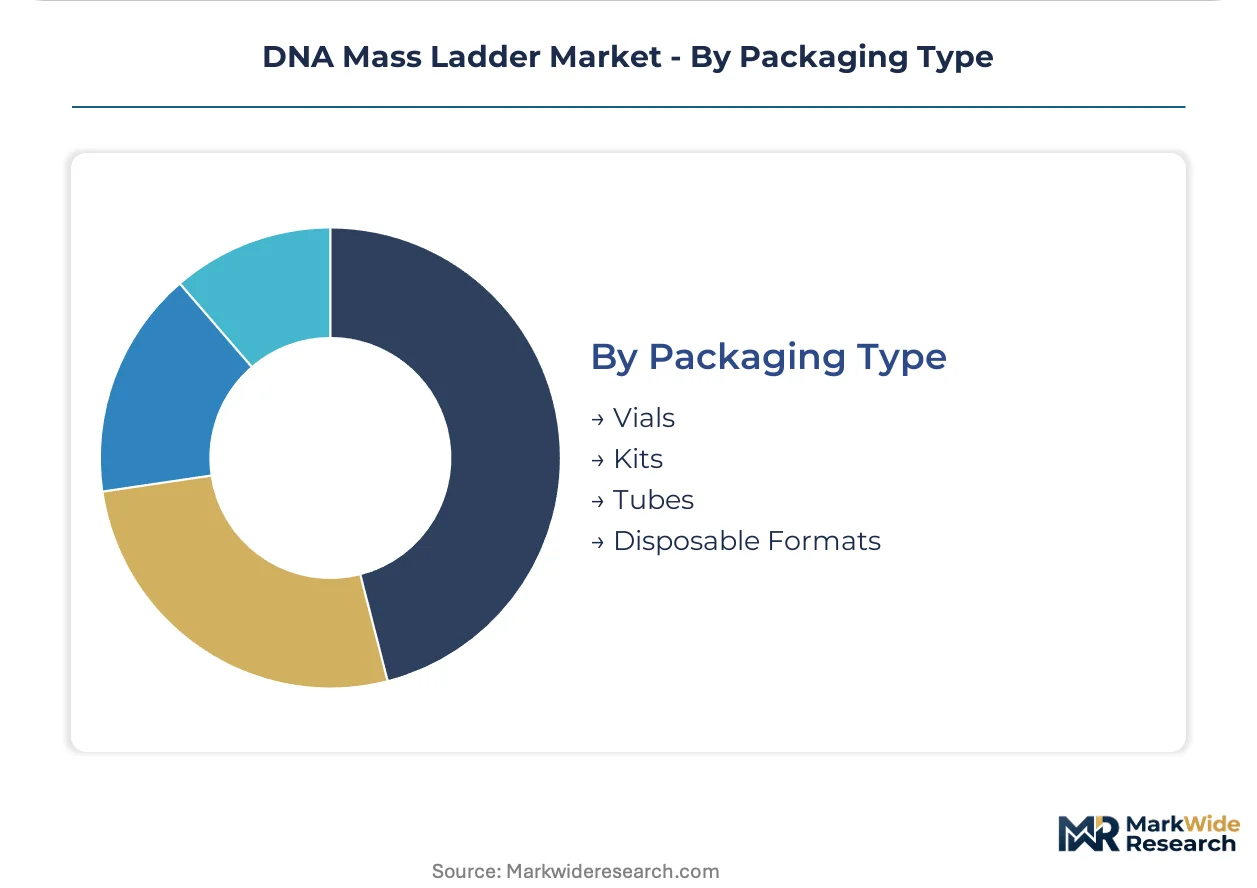
Supply concentration in vial manufacturing shapes format availability across customer tiers.
- Vials:Standard glass or plastic containers for bulk ladder storage and aliquoting.
- Kits:Bundled formulations combining ladders with loading buffers and reference materials. These configurations reduce protocol variability for automated electrophoresis platforms requiring certified mass standards.
- Tubes:Single-use polypropylene containers for individual reaction setups.
- Disposable Formats:Pre-loaded cartridges for capillary electrophoresis instrumentation digitizing consumption patterns in United States and China core sequencing facilities.
Vials retain volume leadership; disposable formats hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for DNA mass ladders favor net-importing research economies while manufacturing concentrates in countries with established biopharma fermentation infrastructure. The United States, Germany, and China maintain structural trade surpluses in high-purity nucleic acid standards.
United States
FDA quality system regulations for molecular diagnostics drive procurement of traceable nucleic acid sizing standards by diagnostic developers in Massachusetts and California. The agency mandates documented batch consistency for companion diagnostic programs. Greater Boston hosts contract manufacturing organizations requiring GMP-certified ladders for plasmid quality control.
Germany
EU IVDR conformity assessment requirements expand demand for CE-marked ladders among diagnostic manufacturers in Baden-Württemberg and Bavaria. EMA-aligned traceability standards favor suppliers with ISO 17025-accredited measurement uncertainty data. The Rhine-Main biocluster anchors production of clinical-grade RNA sizing reagents for transcriptomics workflows.
China
NMPA regulatory pathways for precision medicine diagnostics accelerate ladder consumption in Shanghai and Beijing genomics facilities. MIIT industrial biotech initiatives support domestic production of restriction enzyme-derived fragment standards. The Yangtze River Delta concentrates high-throughput sequencing infrastructure driving automated electrophoresis platform adoption.
Japan
METI and PMDA pharmacogenomics certification programs create demand for ladders with documented measurement uncertainty in Tokyo and Osaka. JIS standards for analytical reagents shape procurement criteria for nucleic acid sizing products. The Kanto region hosts core sequencing facilities standardizing on integrated instrument-reagent ecosystems.
South Korea
MFDS regulatory frameworks for molecular diagnostics expand ladder requirements in Seoul and Daejeon. Government biocluster investments in Songdo and Osong attract contract manufacturing organizations needing viral vector quality control standards. The capital region dominates automated electrophoresis platform deployment for NGS library validation.
DNA Mass Ladder Market Competitive Landscape
On the supply side, the industry is moderately consolidated around integrated life science conglomerates and specialized reagent manufacturers. Three strategic archetypes dominate: diversified instrument-reagent ecosystems, enzyme-specialist bundled offerings, and automated platform consumable suppliers. Competitive moves center on vertical integration into GMP-certified nucleic acid production and strategic partnerships with sequencing platform manufacturers.
Among diversified conglomerates, Thermo Fisher Scientific exemplifies the integrated ecosystem archetype through its instrument-reagent bundling approach. New England Biolabs occupies a position within the enzyme-specialist tier, leveraging restriction enzyme expertise for ladder production. Promega Corporation represents the automated platform alignment archetype, positioning certified mass standards for capillary electrophoresis workflows. These three companies anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| New England Biolabs |
| Promega Corporation |
| Bio-Rad Laboratories |
| Merck KGaA |
| Takara Bio |
| Agilent Technologies |
| QIAGEN |
| MilliporeSigma |
| Others |
Value Network & Pricing Analysis
GMP-certified nucleic acid production concentrates in the United States, Germany, and China, anchoring margin pools in clinical-grade ladder tiers where FDA and EU IVDR traceability requirements create pricing premiums. Pharmaceutical diagnostic developers absorb these premiums for companion diagnostic programs, while academic laboratories downstream face sharper cost compression from consolidated group purchasing organizations.
Pricing Analysis
Pharmaceutical companies anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on ISO 17025 certification grade and documented measurement uncertainty data. Cost compression in the economy tier is intensifying because academic buyers are consolidating procurement through multi-site sequencing centers. Research laboratories exhibit the highest price sensitivity, while diagnostic manufacturers seeking CE marking show the least.
Supply Chain Analysis
Extended payment terms from diagnostic OEMs are reshaping working capital requirements for ladder suppliers. Manufacturing concentrates in the United States, Germany, and China. Production draws from purified plasmid DNA, restriction enzymes, and fluorescent dye inputs. Single-source vulnerability in GMP-certified nucleic acid fermentation creates structural risk. Distribution runs through life science distributors and direct instrument-reagent bundled contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DNA mass ladder procurement is shifting toward service-attach models where certified mass standard subscriptions and batch-specific measurement uncertainty reporting expand faster than standalone reagent sales.
For Market Incumbents: Build switching-cost moats through integrated instrument-reagent ecosystems that embed ladder standards into automated electrophoresis platform consumable contracts. Defend against capillary electrophoresis platform displacement by certifying mass standards for digital sizing outputs rather than visual band matching alone. Deepen backward integration into GMP-certified nucleic acid production to control batch consistency documentation. For New Entrants and Emerging Players: Establish a beachhead in RNA ladders for transcriptomics workflows where academic consumption is accelerating fastest. Target South Korean bioclusters in Songdo and Osong where contract manufacturing organizations require viral vector quality control standards with limited incumbent presence. Lead with ISO 17025-accredited measurement uncertainty data as a qualification wedge against established suppliers lacking documented batch consistency. For Investors and Strategic Acquirers: Secondary-cycle assets sit with enzyme-specialist firms possessing restriction enzyme expertise that ladders production. Five-to-ten-year viability hinges on regulatory certification breadth across FDA, EU IVDR, and Japan PMDA pathways. Watch for pharmacogenomics diagnostic approvals in Japan and South Korea as volume inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Investment | FDA quality system regulations mandate documented batch consistency for companion diagnostic programs. |
| Automated Platform Integration | Capillary electrophoresis instrumentation in United States and China core facilities digitizes consumption patterns. |
| Dual-Source Supplier Qualification | EU IVDR conformity assessment timelines drive diagnostic manufacturers to mitigate certification risks. |
| RNA Ladder Portfolio Expansion | Transcriptomics research in Germany and China accelerates demand for ribonucleic acid molecular weight standards. |
| Pharmacogenomics Certification Pathway | Japan METI and PMDA precision medicine programs create documented measurement uncertainty requirements. |
Research Methodology
Initial hypotheses were tested against primary input from molecular diagnostic developers, sequencing facility directors, regulatory affairs specialists at ladder manufacturers, and academic laboratory procurement managers and refined through secondary validation. Sources included FDA quality system regulation filings, EU IVDR technical documentation databases, ISO 17025 accreditation registries, and customs trade data for nucleic acid reagent imports. Bottom-up segment sizing triangulated against top-down industry expenditure estimates.
Demand-supply balance modeling anchored projections across the analysis window. Segmentation dimensions included product format, application workflow, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to baseline consumption data. Forecast inputs incorporated NGS library validation protocol adoption rates and pharmacogenomics diagnostic pipeline progression.
Sensitivities concentrate around regulatory certification timeline delays, single-source GMP production disruptions, and capillary electrophoresis platform substitution rates. Forecasts reflect documented assumptions about batch consistency requirements and measurement uncertainty data demand trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Molecular Biomarkers for Cancer Detection Market
Genomics
Asia-Pacific Genetic Testing Market
Genomics
Short-Read Sequencing Market
Genomics
Single-Cell Omics Market
Genomics
Predisposition Biomarkers Market
Genomics
Global Next-Generation Sequencing (NGS) Services Market
Genomics
Cytogenetic Systems Market
Genomics
Digital Genome Market
Genomics
Next Generation Molecular Assay Market
Genomics
North America Microarray Market
Genomics
Antisense Oligonucleotides Market
Genomics
Europe Gene Synthesis (Research Use) Market
Genomics
Direct-To-Consumer (DTC) Genetic Testing Market
Genomics
Microbiome Sequencing Market
Genomics
US Genetic Testing Market
Genomics
Global Lab Automation in Genomics Market