
 Next-Generation Sequencing Data Analysis Market | 2026-2036
Next-Generation Sequencing Data Analysis Market Size, Share, and Industry Trends Forecast 2026-2036
Next-Generation Sequencing Data Analysis Market Intelligence
Cloud infrastructure is consolidating the economics of NGS data analysis by replacing capital-intensive on-premise server farms with elastic compute models that cut per-sample processing costs. Thermo Fisher Scientific leverages its instrument-software integration to anchor enterprise workflows across clinical and research settings. Illumina competes through proprietary analytics layers tied to its sequencing hardware, while QIAGEN specializes in secondary analysis pipelines that normalize variant calling across heterogeneous data sources.
Next-Generation Sequencing Data Analysis encompasses computational pipelines, statistical algorithms, and visualization frameworks that transform raw nucleotide reads from massively parallel sequencing instruments into interpretable genomic, transcriptomic, or epigenomic information, typically processing terabyte-scale FASTQ files through alignment, variant detection, and functional annotation stages to support diagnostic, therapeutic, or research decisions. Software solutions and bioinformatics platforms capture the dominant share of product-type revenue, though cloud services represent the fastest-expanding delivery category as laboratories outsource burst-compute needs. Among end users, pharmaceutical companies command premium pricing for validated clinical-grade pipelines, while academic institutions sustain volume demand through grant-funded open-source tool adoption.
FDA oversight of clinical NGS-based diagnostics through the In Vitro Diagnostics framework and HIPAA data-privacy mandates shape product development priorities for US-market entrants, while the EU AI Act and GDPR impose additional algorithmic-transparency and cross-border-transfer constraints on European deployments. ISO 13485 quality-management expectations and IEC 62304 software-lifecycle standards further govern supplier qualification for regulated clinical environments. Stakeholders must monitor evolving payer-coverage determinations for NGS-based tests as the critical variable determining whether analytical investments convert to sustainable revenue streams.
Market Dynamics
Cloud deployment architectures are displacing on-premise infrastructure as the dominant delivery model for NGS data analysis, compressing capital requirements and unlocking elastic compute for burst-processing workloads across pharmaceutical and academic laboratories.
Growth Catalysts
- FDA In Vitro Diagnostics Framework:The regulatory pathway for clinical-grade NGS-based diagnostics creates validated demand for compliant analytical pipelines among US-based diagnostic developers seeking reimbursement eligibility.
- Pharmaceutical precision drug development:Biopharma R&D organizations are embedding NGS analysis into target identification and patient stratification workflows, sustaining premium pricing for validated bioinformatics platforms.
- Academic medical center procurement:Grant-funded adoption at institutions in Boston, San Francisco, and other research clusters drives volume demand for open-source and commercial analysis tools.
Market Restraints
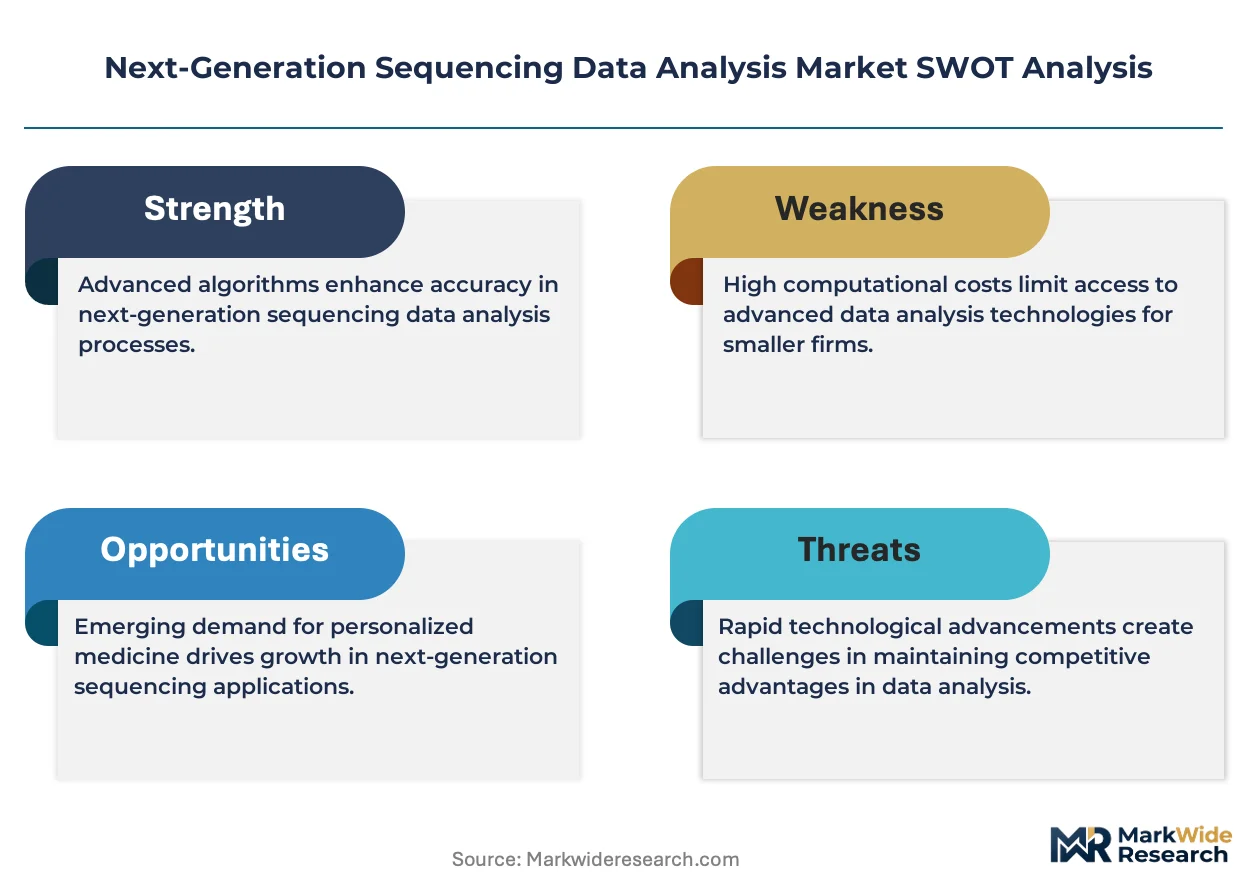
- Terabyte-scale storage and compute costs:Raw FASTQ file volumes from massively parallel sequencing instruments impose ongoing infrastructure expenditure even under cloud models.
- HIPAA and GDPR cross-border constraints:Data-privacy mandates complicate multi-site collaborations and cloud provider selection for international pharmaceutical sponsors.
- Specialized bioinformatics talent scarcity:Shortages of computational biologists proficient in variant calling algorithms and pipeline engineering limit deployment velocity.
Strategic Opportunities
- EU AI Act algorithmic transparency requirements:European regulatory mandates for explainable clinical decision-support systems create demand for interpretable NGS analysis frameworks.
- Secondary analysis pipeline standardization:Convergence of machine learning with variant normalization across heterogeneous sequencing platforms opens white space for interoperable tools.
- Direct-to-consumer genomics channel expansion:Wellness and ancestry testing platforms represent underpenetrated demand for streamlined, user-facing NGS interpretation interfaces.
Industry Challenges
- ISO 13485 and IEC 62304 certification timelines:Quality-management and software-lifecycle standards for clinical environments extend product development cycles and raise compliance costs.
- Legacy LIS/EHR integration complexity:Hospital information systems and electronic health record architectures require costly customization to ingest structured genomic results from NGS pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next-Generation Sequencing Data Analysis Market |
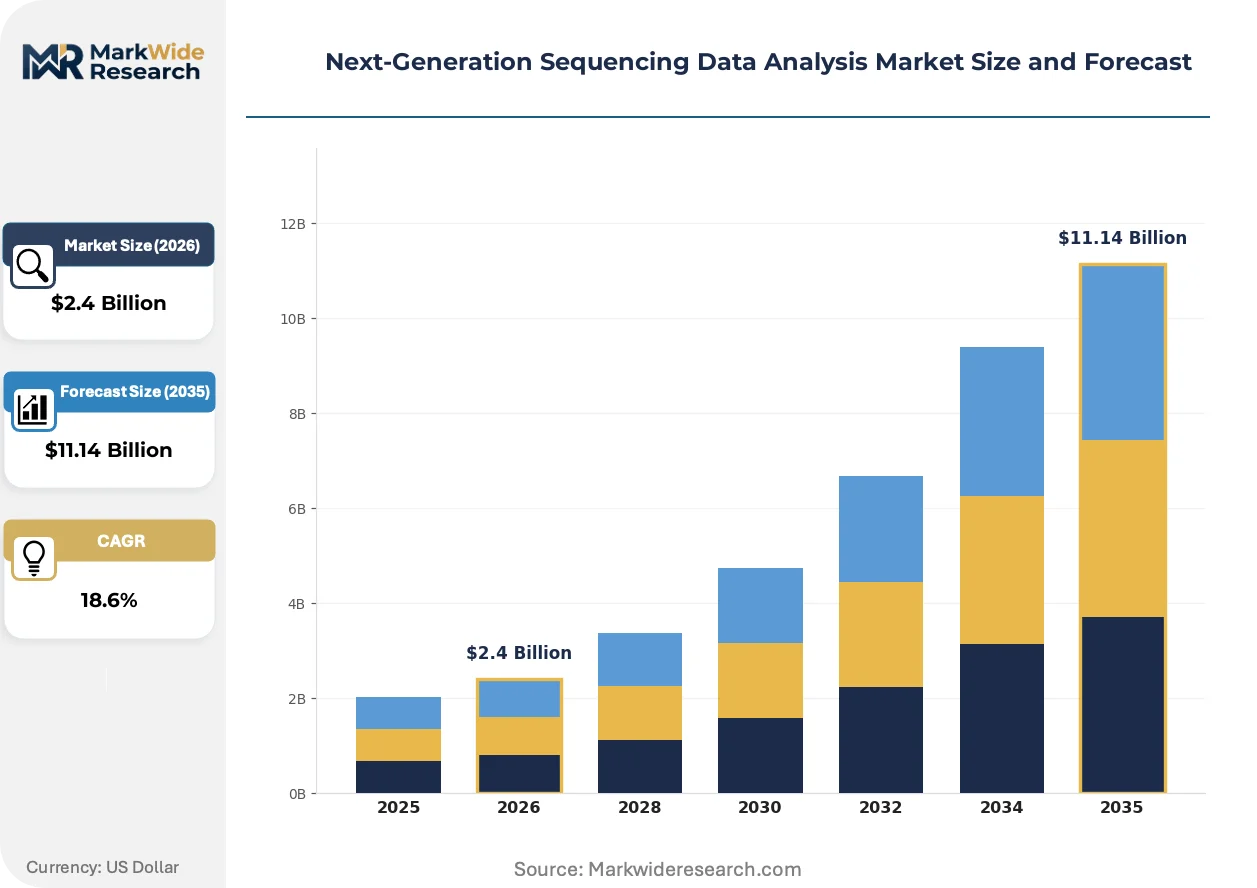
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $11.14 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Cloud Services, Data Analytics Tools, Bioinformatics Platforms End User: Academic Institutions, Pharmaceutical Companies, Clinical Laboratories, Research Organizations Deployment: On-Premise, Cloud-Based, Hybrid Solutions, SaaS Application: Genomics, Transcriptomics, Oncology, Microbiome Analysis |
| Companies Covered | Bio-Rad Laboratories, Inc., Eurofins Scientific, Thermo Fisher Scientific, Inc., F. Hoffmann-La Roche Ltd., Pacific Biosciences of California, Inc., QIAGEN, Illumina, Inc., DNAnexus Inc., Agilent Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next-Generation Sequencing Data Analysis Market Strategic Shifts & Innovations
Computational architectures and regulatory frameworks are actively reshaping how NGS data analysis capabilities are developed, deployed, and commercialized across research and clinical environments.
Containerized workflow orchestration is absorbing the complexity of multi-stage analytical pipelines, packaging alignment, variant calling, and annotation tools into portable, reproducible environments. Academic core facilities and mid-sized biotechs are adopting Kubernetes-based platforms at accelerating pace. This standardization is compressing the technical barrier to deploying production-grade bioinformatics without dedicated DevOps infrastructure.
The EU AI Act's risk-classification framework for clinical decision-support algorithms is reshaping product development priorities for European market entrants. Developers must now document training data provenance and algorithmic interpretability for high-risk applications. Diagnostic platform vendors targeting Germany, France, and the Netherlands are restructuring quality assurance processes to satisfy these mandates ahead of enforcement deadlines.
Pharmaceutical sponsors are consolidating vendor relationships around integrated instrument-software bundles rather than assembling multi-supplier toolchains. This concentration favors suppliers offering end-to-end workflows from sequencing through clinical reporting. The shift is most pronounced among US-based biopharma organizations managing large-scale oncology trials requiring rapid turnaround from sample to actionable variant report.
Next-Generation Sequencing Data Analysis Market Segmentation
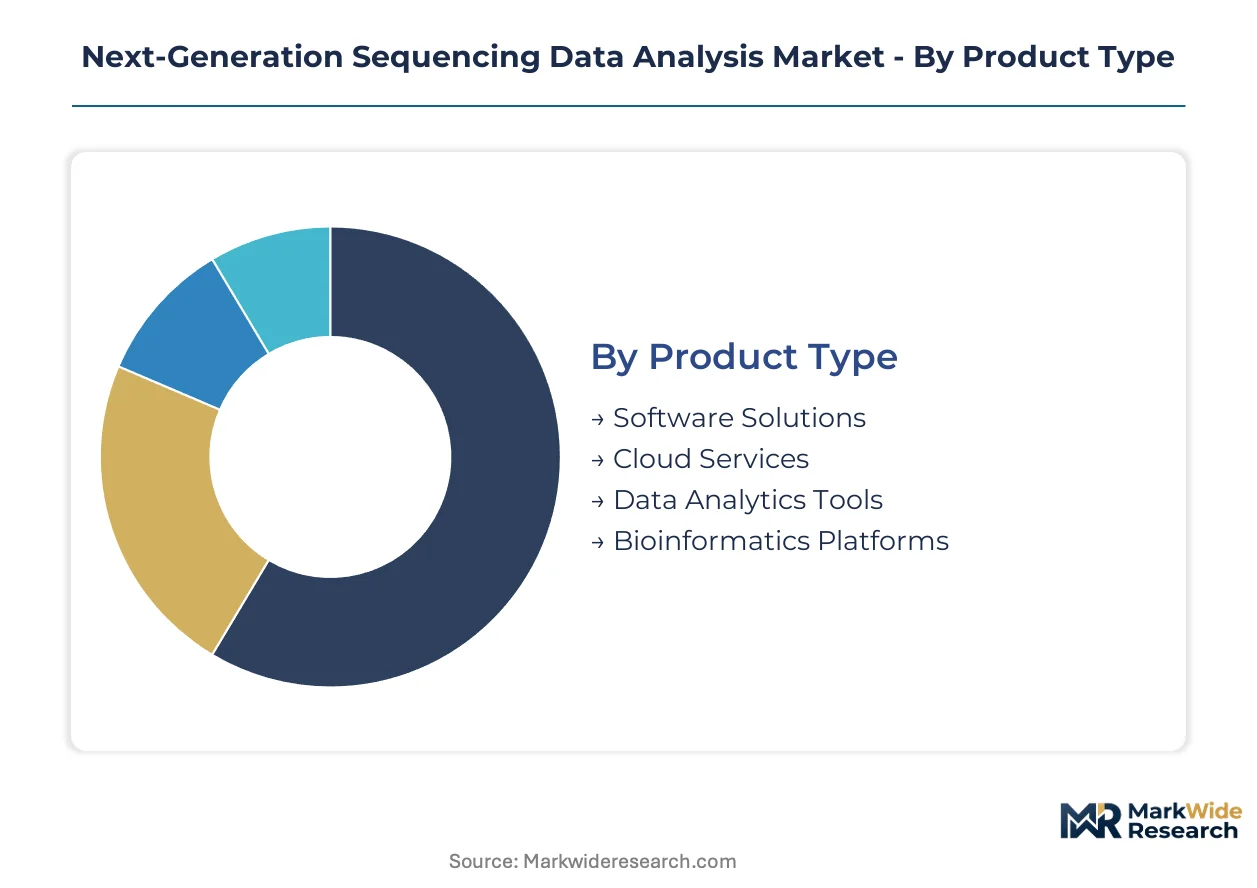
Segmentation in NGS data analysis reveals how computational workloads, regulatory requirements, and end-user sophistication stratify purchasing behavior across the value chain. Laboratories select product configurations based on data sovereignty needs, burst-compute patterns, and integration complexity with existing sequencing infrastructure.
Product Type:
Upgrade cycles for analytical software accelerate as sequencing platforms release new base-calling algorithms and reference genome builds, forcing laboratories to refresh computational stacks every 18-24 months to maintain analytical validity.
- Software Solutions:Licensed bioinformatics suites deployed on local workstations handle alignment, variant calling, and annotation through modular pipelines. Pharmaceutical companies in Boston and San Francisco sustain premium licensing for validated clinical-grade modules that satisfy FDA In Vitro Diagnostics framework requirements for diagnostic development.
- Cloud Services:Elastic compute resources provisioned through AWS, Google Cloud, or Azure handle burst-processing of terabyte-scale FASTQ files without capital infrastructure. Academic medical centers leverage grant-funded cloud credits to scale analyses during publication sprints without permanent server procurement.
- Data Analytics Tools:Specialized statistical packages for population genomics and multi-omic integration.
- Bioinformatics Platforms:End-to-end workflow environments combining pipeline orchestration with visualization layers.
Volume placements concentrate in Software Solutions; the faster expansion belongs to Cloud Services.
End User:
Customer type determines pricing tolerance, validation requirements, and procurement velocity across the NGS data analysis ecosystem.
- Pharmaceutical Companies:Biopharma R&D organizations embed NGS analysis into precision drug development workflows, requiring ISO 13485-compliant pipelines with full audit trails. These buyers command premium pricing for validated platforms that accelerate target identification and patient stratification in oncology trials.
- Academic Institutions:Grant-funded universities and medical schools drive volume demand through open-source tool adoption and core facility service models. Procurement concentrates at research clusters in Boston and San Francisco where NIH funding density supports dedicated bioinformatics staff.
- Clinical Laboratories:CAP-accredited diagnostic labs processing patient samples for hereditary cancer and pharmacogenomic testing.
- Research Organizations:Government institutes and nonprofit genomics consortia operating under public funding mandates.
Academic Institutions anchor current procurement volumes; Pharmaceutical Companies are climbing the fastest as clinical-grade pipeline investments accelerate.
Deployment:
Architecture decisions hinge on data residency requirements, HIPAA compliance scope, and the elasticity of analytical workloads.
- Cloud-Based:Fully managed infrastructure eliminating local server maintenance, with automatic scaling for burst-compute during large cohort analyses. Deployment accelerates among mid-sized biotechs lacking dedicated DevOps teams, though HIPAA Business Associate Agreements constrain provider selection for US clinical data.
- On-Premise:Physical servers maintained within institutional data centers for maximum data sovereignty. Retained by clinical laboratories processing protected health information under strict HIPAA controls, and by genome centers with predictable high-volume throughput justifying capital expenditure.
- Hybrid Solutions:Split architectures keeping sensitive raw data on-premise while outsourcing compute-intensive alignment to cloud.
- SaaS:Subscription-accessible platforms with zero local infrastructure footprint.
On-Premise retains share in regulated clinical settings; Cloud-Based deployment is gaining share fastest as vendor security certifications mature.
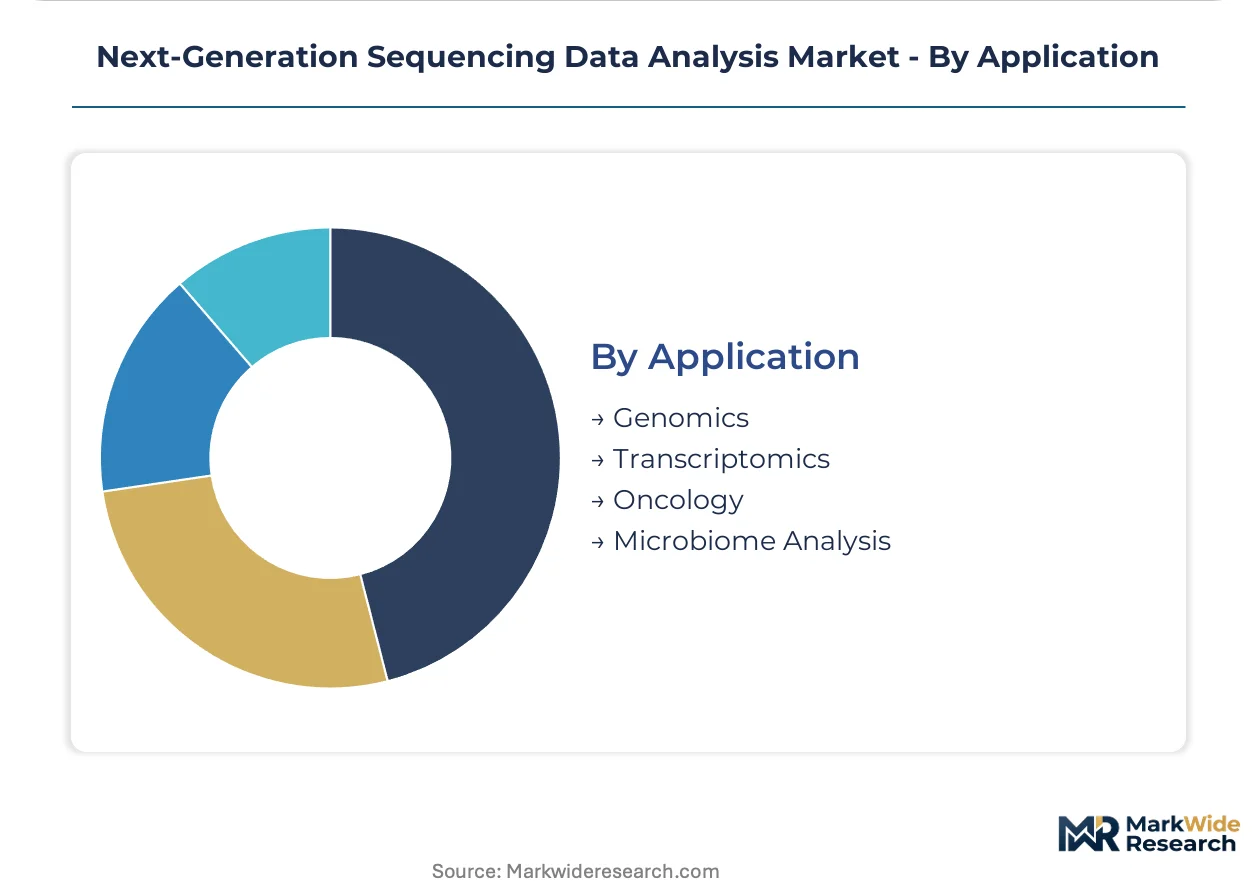
Application:
Analytical complexity and regulatory scrutiny vary sharply across biological domains, shaping tool selection and validation investment.
- Oncology:Tumor-normal paired analysis for somatic mutation detection and therapy selection demands the highest analytical rigor. Clinical laboratories in the United States invest heavily in FDA-aligned variant interpretation pipelines to support precision oncology programs at academic medical centers.
- Genomics:Germline variant detection for rare disease diagnosis and carrier screening represents the most mature application category. Standardized analytical workflows and curated variant databases reduce interpretation burden compared to somatic oncology applications.
- Transcriptomics:RNA-seq quantification and differential expression analysis for functional genomics research.
- Microbiome Analysis:16S rRNA and metagenomic sequencing for compositional profiling of complex microbial communities.
Genomics maintains the largest installed base; Oncology is expanding most quickly as liquid biopsy and minimal residual disease monitoring multiply sample volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical R&D investment concentrates procurement in the United States, where academic medical centers and biotech clusters sustain the highest analytical software licensing volumes. Cloud infrastructure adoption accelerates fastest in European markets confronting strict data sovereignty mandates. Regulatory divergence across jurisdictions forces vendors to maintain parallel compliance frameworks.
United States
NIH grant funding at academic medical centers in Boston and San Francisco drives sustained demand for open-source and commercial NGS analysis platforms. FDA In Vitro Diagnostics framework compliance requirements shape purchasing criteria for diagnostic developers seeking reimbursement eligibility. The Greater Boston biotech corridor anchors enterprise pipeline deployments for precision oncology trials.
Germany
EU AI Act algorithmic transparency mandates reshape product development priorities for clinical decision-support tools entering the German market. The country's national pharmaceutical regulator enforces MDR requirements for software qualifying as medical devices. The Munich-Heidelberg life sciences cluster concentrates adoption of ISO 13485-compliant analytical pipelines for hospital networks.
United Kingdom
NHS genomic medicine service expansion sustains procurement of validated variant interpretation platforms across regional laboratory hubs. GDPR cross-border transfer constraints complicate cloud provider selection for research collaborations spanning European and US sites. The Cambridge-London corridor anchors commercial bioinformatics vendor headquarters and academic partnerships.
China
NMPA regulatory pathways for gene sequencing diagnostic products accelerate localization of analytical software to satisfy domestic data residency requirements. The country's national medical products administration imposes cybersecurity review for health data processing platforms. The Yangtze River Delta biotech cluster drives volume demand for cloud-based secondary analysis services.
Japan
PMDA oversight of companion diagnostics creates validated demand for analytical pipelines supporting oncology drug approval pathways. METI funding programs for genomic medicine infrastructure expand core facility capacity at university hospitals. The Kanto region concentrates pharmaceutical sponsor investment in integrated sequencing-analysis workflows for clinical trials.
Next-Generation Sequencing Data Analysis Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with instrument-software integration favoring consolidated suppliers in clinical-grade applications while open-source tool adoption sustains fragmentation in academic research. The vendor base organizes around three strategic archetypes: sequencing platform incumbents bundling proprietary analytics, independent bioinformatics platform developers, and cloud-native workflow orchestration specialists. Competitive positioning hardens through M&A consolidation of point-solution vendors and strategic partnerships between instrument manufacturers and cloud infrastructure providers.
Among US-based life sciences conglomerates, Thermo Fisher Scientific, Inc. and Illumina, Inc. occupy positions as integrated platform anchors, while QIAGEN represents the specialized secondary analysis pipeline tier. These three entities exemplify divergent strategic postures: Thermo Fisher leverages instrument-software bundling across clinical and research settings, Illumina ties analytics layers to sequencing hardware ecosystems, and QIAGEN normalizes variant calling interoperability across heterogeneous data sources. European entrants including F. Hoffmann-La Roche Ltd. and Eurofins Scientific sit within the diagnostic service and clinical decision-support archetype, competing through validated regulatory submissions rather than raw computational scale. Cloud-native specialists such as DNAnexus Inc. occupy a distinct position emphasizing elastic infrastructure for burst-compute workloads without captive sequencing hardware.
| Leading Market Players |
|---|
| Bio-Rad Laboratories, Inc. |
| Eurofins Scientific |
| Thermo Fisher Scientific, Inc. |
| F. Hoffmann-La Roche Ltd. |
| Pacific Biosciences of California, Inc. |
| QIAGEN |
| Illumina, Inc. |
| DNAnexus Inc. |
| Agilent Technologies Inc. |
| Others |
Cost & Logistics Intelligence
Pharmaceutical sponsors consolidating vendor relationships around integrated instrument-software bundles are compressing pricing power for standalone analytics vendors. This procurement concentration forces suppliers to absorb certification costs or bundle professional services, eroding margins at the mid-market tier while premium clinical-grade pipelines retain pricing strength.
Pricing Analysis
Volume placements concentrate in grant-funded academic subscriptions at compressed price points, while margin capture concentrates in ISO 13485-validated clinical pipelines serving pharmaceutical sponsors. Three-tier pricing structure across premium, standard, and economy levels separates FDA-aligned diagnostic modules from research-grade toolkits and open-source alternatives. Pricing pressure stems from cloud infrastructure commoditization of raw compute, with AWS and Google Cloud driving cost compression in secondary analysis. Academic institutions exhibit highest price sensitivity through grant-funded procurement, while pharmaceutical companies tolerate premium licensing for validated audit trails.
Supply Chain Analysis
Freight costs for sequencing instrument hardware from the United States and China to European and Asian installation sites add 3-8% to total delivered cost, though software and cloud services face negligible logistics expenditure. The supply chain draws from semiconductor fabrication in Taiwan and South Korea for instrument components, cloud infrastructure provisioned through US-based hyperscalers, and specialized bioinformatics talent concentrated in Boston and San Francisco. Single-source vulnerability sits with Illumina's dominance in sequencing hardware, which conditions analytics software compatibility. Distribution runs through direct enterprise sales for pharmaceutical accounts and academic core facility service contracts for research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over sequencing hardware increasingly dictates analytics software attach rates. Players are pursuing downstream integration into clinical reporting and LIS/EHR connectivity to capture recurring revenue.
For Market Incumbents: Cement instrument-software bundling advantages by embedding proprietary analytics layers that lock in pharmaceutical sponsor workflows. Deepen ISO 13485 certification coverage across oncology and rare disease applications to defend against cloud-native entrants offering elastic compute without validation. Threat substitution from DNAnexus and similar platform-agnostic orchestrators demands preemptive channel control through hospital system partnerships.
For New Entrants and Emerging Players: The gap between premium clinical-grade pricing and economy-tier open-source tools creates white space for mid-market SaaS platforms with lightweight validation. Target academic medical centers in Boston and San Francisco transitioning from on-premise to hybrid cloud architectures. Penetrate through Kubernetes-native workflow portability that reduces DevOps burden for mid-sized biotechs lacking dedicated bioinformatics infrastructure.
For Investors and Strategic Acquirers: The window for entry favors cloud-native workflow orchestration specialists with established HIPAA Business Associate Agreements. Long-term viability hinges on regulatory moats around FDA-aligned clinical decision-support algorithms rather than raw computational scale. Watch for EU AI Act enforcement timelines as the inflection indicator determining whether interpretable analytics frameworks command premium multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Thermo Fisher's instrument-software bundling anchors enterprise workflows across clinical and research settings. |
| Regulatory Approval Pathway | FDA In Vitro Diagnostics framework compliance unlocks reimbursement eligibility for diagnostic developers. |
| Strategic Partnership | Cloud provider alliances with sequencing manufacturers accelerate elastic compute adoption for burst-processing workloads. |
| Acquisition of Specialist Firm | Consolidation of variant-calling point solutions addresses pharmaceutical demand for end-to-end oncology pipelines. |
| Geographic Expansion | EU AI Act algorithmic transparency mandates reshape product development for German and French market entry. |
Research Approach
FDA 510(k) filings, EMA medical device registrations, and ClinicalTrials.gov protocol specifications formed the secondary backbone for regulatory pathway mapping. Primary interviews with bioinformatics platform executives, diagnostic laboratory directors, pharmaceutical R&D procurement leads, and academic core facility managers validated demand patterns and pricing tolerance. Bottom-up triangulation across these sources was cross-checked against top-down market sizing from sequencing instrument shipment data and cloud infrastructure spend disclosures.
Bottom-up modeling tracked deployment architecture shifts, product type upgrade cycles, and end-user procurement velocity across the projection horizon. Segmentation dimensions included delivery model, validation tier, application complexity, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves rather than linear extrapolation. Forecast inputs incorporated NIH grant funding trajectories at Boston and San Francisco research clusters and pharmaceutical oncology trial initiation rates.
Inputs from regulatory filings and primary fieldwork were available through the study window; gaps in real-time cloud infrastructure pricing and emerging EU AI Act implementation guidance introduce uncertainty bands around European deployment forecasts. Stakeholders should weight assumptions against their own operating context and monitor evolving payer-coverage determinations for NGS-based diagnostics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Gene Amplification Technologies Market
Genomics
Microarray Biochips Market
Genomics
Europe Whole Exome Sequencing Market
Genomics
Forensic Genomics Market
Genomics
Global Blockchain in Genomic Data Management Market
Genomics
Global Long Read Sequencing Market
Genomics
Global Molecular Cytogenetics Market
Genomics
North America Whole Exome Sequencing Market
Genomics
Rare Disease Genetic Testing Market
Genomics
Middle East and Africa Genetic Testing Market
Genomics
Predisposition Biomarkers Market
Genomics
Genome Sequencing Market
Genomics
Whole Exome Sequencing (WES) Market
Genomics
Next-Generation Sequencing Library Preparation Market
Genomics
Reproductive Genetics Market
Genomics
Cytogenetic Systems Market