
 Europe DNA Sequencing Products Market | 2026-2036
Europe DNA Sequencing Products Market Size, Share, and Industry Trends Forecast 2026-2036
Europe DNA Sequencing Products Market Intelligence
Hospital-based molecular diagnostics is unwinding the historical dominance of academic research institutes as the primary buyer archetype for DNA sequencing products across Europe. Illumina leverages its installed base of sequencing platforms to sustain recurring consumable revenue streams throughout major European clinical hubs. Thermo Fisher Scientific anchors its position through integrated workflow solutions spanning sample preparation through data analysis. QIAGEN competes with specialized sample technologies that address automated nucleic acid extraction demands in high-throughput diagnostic laboratories.
Europe DNA Sequencing Products encompass instruments, consumables, and software systems that determine the order of nucleotides in DNA molecules using chemistries ranging from Sanger chain termination to nanopore-based single-molecule detection, with read lengths spanning from short 150-base-pair fragments to continuous million-base sequences for structural variant resolution. Next-generation sequencing platforms occupy the largest revenue share due to balanced throughput and cost economics for clinical and research applications, while third-generation sequencing represents the fastest-expanding category as long-read technologies address complex genomic regions previously inaccessible to short-read methods. Oncology applications command premium positioning within the application dimension, driven by tumor profiling requirements for targeted therapy selection across European comprehensive cancer centers.
EMA's In Vitro Diagnostic Medical Devices Regulation tightens performance validation requirements for sequencing-based diagnostic kits entering European markets, while GDPR frameworks constrain cross-border genomic data flows and biobank sharing arrangements that underpin large-scale population studies. The EU AI Act introduces conformity obligations for machine-learning components embedded in variant interpretation software, adding compliance layers to automated reporting pipelines. Stakeholders must monitor how national reimbursement authorities in France, Germany, and Italy calibrate sequencing coverage decisions against health technology assessments.
Market Dynamics
The European DNA sequencing products market is being fundamentally restructured by the migration of sequencing workflows from centralized academic core facilities into distributed hospital-based diagnostic laboratories, a shift that reconfigures purchasing authority toward clinical procurement departments and away from research grant administrators.
Growth Catalysts
- EMA's In Vitro Diagnostic Medical Devices Regulation:This framework creates formal pathways for sequencing-based companion diagnostics to gain market authorization, accelerating clinical adoption of tumor profiling assays in comprehensive cancer centers across France and Germany.
- Precision medicine programs:National health systems in the United Kingdom, Netherlands, and Sweden have established dedicated funding streams for genomic medicine, embedding sequencing into standard-of-care pathways for rare disease diagnosis and oncology treatment selection.
- Long-read sequencing platforms:These technologies are resolving complex structural variants and repetitive genomic regions previously inaccessible to short-read methods, opening new clinical applications in neurological and cardiovascular genetics.
Market Restraints
- Reagent supply concentration:Sequencing consumables depend on a limited number of specialized chemical suppliers concentrated in Germany and Switzerland, creating vulnerability to input cost volatility and single-source dependencies.
- GDPR genomic data constraints:Cross-border biobank sharing and multi-center research collaborations face legal friction from divergent national implementations of data protection rules, complicating large-scale population genomics initiatives.
- Capital intensity of platform acquisition:High-throughput sequencing instruments require substantial upfront investment and dedicated facility infrastructure, limiting adoption in smaller regional hospitals and diagnostic networks.
Strategic Opportunities
- Point-of-care sequencing in Italy and Spain:These markets show underpenetrated diagnostic infrastructure relative to northern Europe, creating expansion potential for compact, rapid-turnaround sequencing platforms in regional hospital networks.
- EU AI Act compliance services:Machine-learning components embedded in variant interpretation software now face conformity obligations, opening revenue streams for vendors offering regulatory documentation and validation support.
- Integration of epigenetic analysis:Convergence of DNA methylation profiling with standard sequencing workflows enables multi-modal diagnostic outputs, differentiating service offerings in oncology and prenatal screening segments.
Industry Challenges
- Bioinformatics workforce scarcity:Clinical laboratories face acute shortages of personnel trained in both genomic data analysis and diagnostic reporting standards, constraining operational scale-up despite instrument availability.
- CE-IVDR certification timelines:The transition from the previous IVD directive to the new regulation has extended approval durations for sequencing-based diagnostic kits, compressing product launch windows and requiring sustained regulatory investment.
- Laboratory information system integration:Sequencing platforms must interface with diverse legacy hospital IT architectures, creating implementation complexity and customization burdens for clinical customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe DNA Sequencing Products Market |
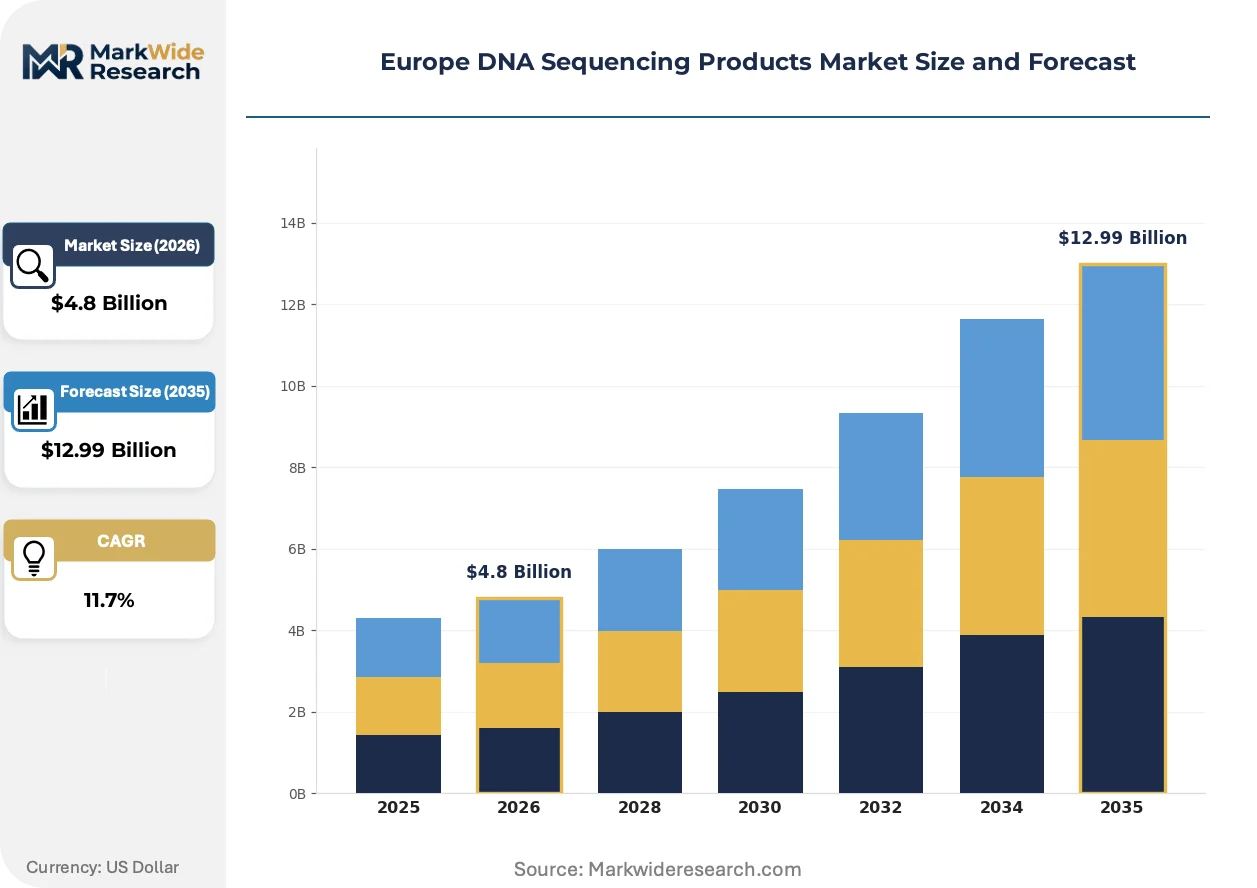
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sanger Sequencing, Next-Generation Sequencing, Third-Generation Sequencing, Whole Genome Sequencing Technology: Illumina, Ion Torrent, PacBio, Oxford Nanopore End User: Research Institutes, Hospitals, Pharmaceutical Companies, Academic Organizations Application: Oncology, Infectious Diseases, Genetic Disorders, Environmental Studies |
| Companies Covered | Illumina, Thermo Fisher Scientific, QIAGEN, Agilent Technologies, F. Hoffmann-La Roche, Pacific Biosciences of California, Danaher Corporation, Oxford Nanopore Technologies, Eurofins Scientific Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe DNA Sequencing Products Market Strategic Shifts & Innovations
Sequencing technology is diverging into specialized modalities optimized for distinct clinical use cases, while regulatory frameworks and procurement behaviors co-evolve to accommodate decentralized diagnostic production.
Nanopore-based single-molecule sequencing is fragmenting the historical dominance of optical detection methods in clinical microbiology and infectious disease surveillance. Hospital laboratories in the United Kingdom and Germany are deploying portable devices for rapid pathogen identification and antimicrobial resistance profiling. This technology is fragmenting the centralized reference laboratory model by enabling same-day diagnostic turnaround in acute care settings.
The EU AI Act introduces specific conformity obligations for machine-learning components within variant interpretation software used in clinical reporting. Developers must now document training data provenance, algorithmic performance validation, and human oversight protocols to achieve CE marking. Sequencing informatics vendors serving oncology and rare disease segments are restructuring product architectures to segregate AI-driven components into independently certifiable modules.
Consolidated purchasing by European hospital networks is compressing vendor margins and extending contract durations. Diagnostic procurement departments in France and the Netherlands now negotiate multi-year sequencing consumable agreements tied to minimum volume commitments and performance-based service level metrics. This concentration of buyer power favors vendors with integrated workflow solutions spanning sample preparation through clinical report generation.
Europe DNA Sequencing Products Market Segmentation
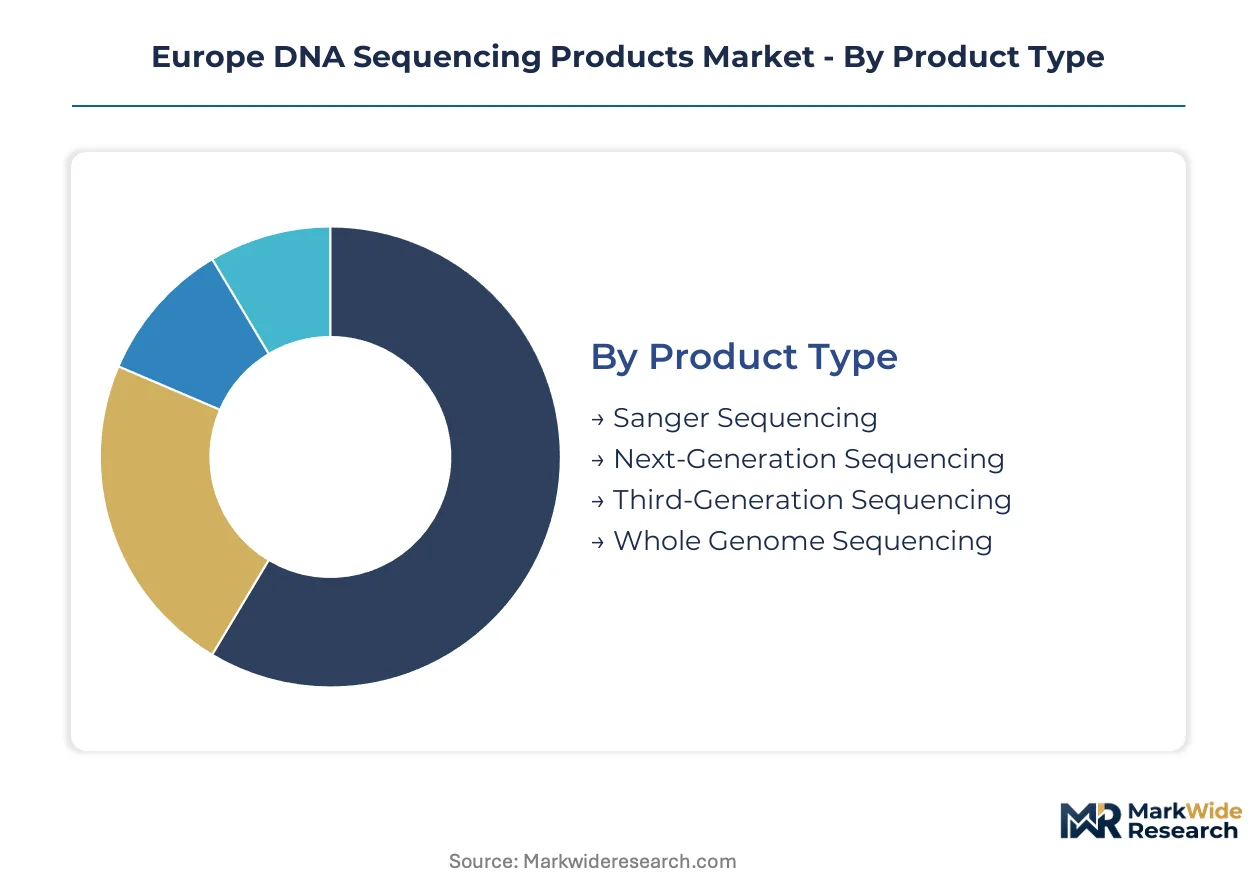
Segmentation reveals how DNA sequencing products flow through distinct procurement channels across European healthcare systems. Each dimension exposes different purchasing authorities, from research grant administrators to hospital diagnostic procurement departments.
Product Type:
Channel mix varies sharply by product category, with centralized academic core facilities dominating instrument sales while distributed hospital laboratories drive consumable volumes.
- Next-Generation Sequencing:Short-read platforms balance throughput and cost economics for high-volume clinical and research applications. German and French comprehensive cancer centers concentrate demand for tumor profiling workflows, with EMA's IVDR framework accelerating companion diagnostic kit registrations.
- Third-Generation Sequencing:Long-read technologies resolve complex structural variants and repetitive genomic regions through single-molecule detection. United Kingdom hospital networks are expanding fastest here, driven by rare disease diagnosis programs and neurological genetics applications previously inaccessible to short-read methods.
- Sanger Sequencing:Chain termination chemistry remains embedded in targeted validation workflows and smaller-scale clinical assays.
- Whole Genome Sequencing:Comprehensive nucleotide analysis commands premium positioning in national genomic medicine initiatives.
Next-Generation Sequencing dominates installed base. Third-Generation Sequencing is where expansion concentrates.
Technology:
Technology selection maps to end-use sophistication, with optical detection methods anchoring high-throughput clinical production and nanopore systems penetrating point-of-care deployments.
- Illumina:Sequencing-by-synthesis chemistry with fluorescent reversible terminators powers the majority of European clinical diagnostic output. United Kingdom and Netherlands hospital networks represent the densest installed base, with recurring consumable revenue streams sustained through multi-year service contracts.
- Oxford Nanopore:Single-molecule electronic sensing enables portable, rapid-turnaround sequencing without amplification steps. United Kingdom and German acute care settings are deploying these devices for same-day pathogen identification, fragmenting the centralized reference laboratory model.
- Ion Torrent:Semiconductor-based pH detection offers intermediate throughput for targeted panel applications.
- PacBio:Zero-mode waveguide technology delivers long-read accuracy for complex variant resolution.
Illumina commands the deepest installed base. Oxford Nanopore is gaining share fastest in clinical microbiology applications.
End User:
Customer type determines purchasing authority, with research institutes historically dominating instrument procurement and hospitals now driving consumable growth through diagnostic volume expansion.
- Hospitals:Clinical diagnostic laboratories are displacing academic core facilities as the primary volume driver for sequencing consumables. France and Germany lead this shift, with national health system funding embedding tumor profiling into standard oncology pathways.
- Research Institutes:Academic core facilities retain influence in instrument selection and technology evaluation. These centers concentrate in the United Kingdom and Germany, though their purchasing authority is narrowing as clinical procurement departments gain budget control.
- Pharmaceutical Companies:Drug developers deploy sequencing across biomarker discovery and patient stratification workflows.
- Academic Organizations:University-based laboratories maintain foundational research applications with grant-dependent procurement cycles.
Hospitals are displacing research institutes as the volume anchor. Pharmaceutical companies represent the steepest expansion trajectory for companion diagnostic partnerships.
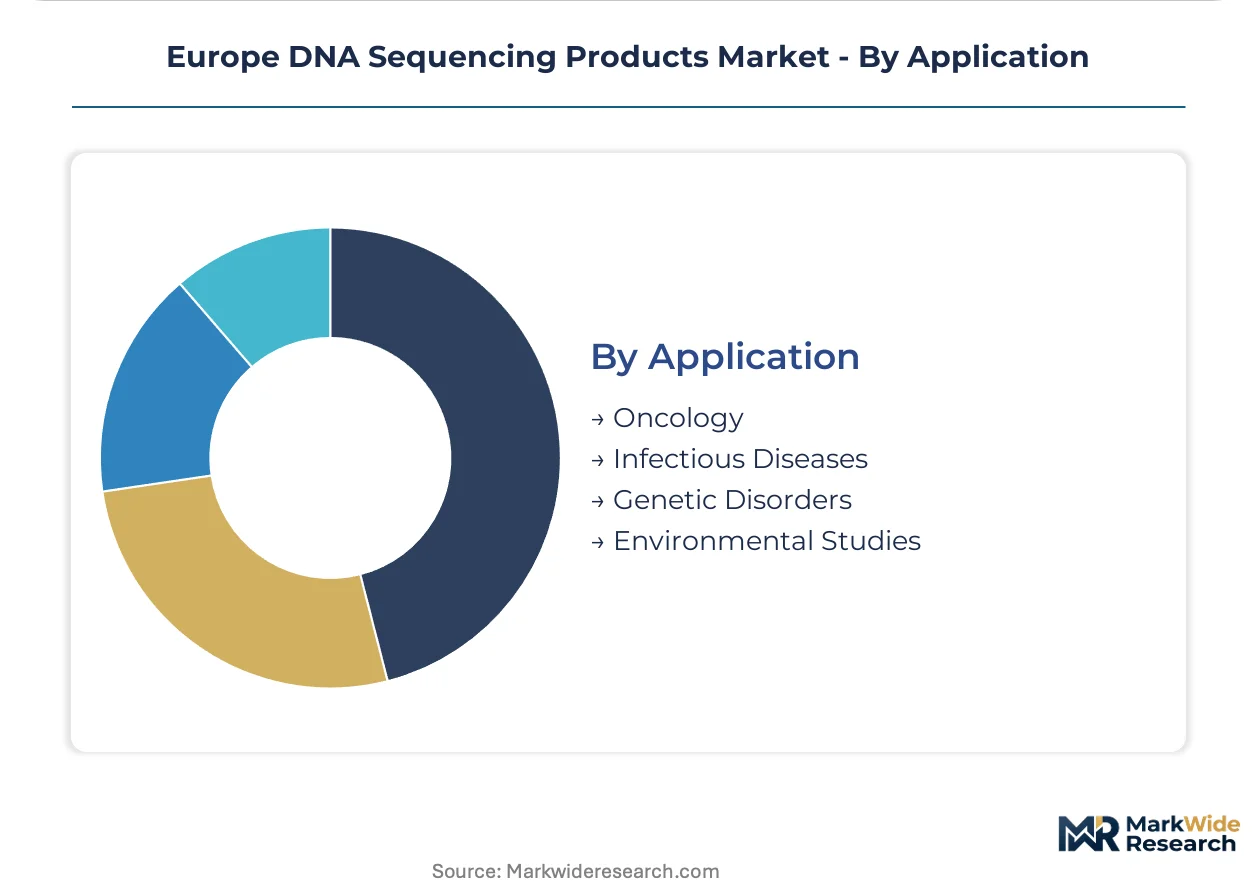
Application:
Application segmentation exposes margin differentiation, with oncology commanding premium pricing and infectious disease applications expanding through decentralized testing models.
- Oncology:Tumor profiling for targeted therapy selection generates the highest revenue per test across European sequencing markets. Comprehensive cancer centers in France, Germany, and the United Kingdom concentrate demand, with EMA's evolving companion diagnostics guidance reshaping product registration pathways.
- Infectious Diseases:Rapid pathogen identification and antimicrobial resistance profiling is migrating from centralized reference laboratories to hospital-based microbiology units. United Kingdom and German acute care networks are deploying nanopore platforms for same-day diagnostic turnaround.
- Genetic Disorders:Rare disease diagnosis programs in national health systems drive whole genome sequencing adoption.
- Environmental Studies:Metagenomic applications in biodiversity and pathogen surveillance support research funding streams.
Oncology anchors premium pricing. Infectious diseases is where point-of-care decentralization concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cross-border sequencing data infrastructure linking London, Amsterdam, and Frankfurt enables multi-center genomic studies that underpin Europe's precision medicine expansion. High-capacity fiber networks and harmonized cloud computing frameworks support real-time variant sharing between national health systems.
Germany
Comprehensive cancer centers in Heidelberg and Berlin drive tumor profiling demand for targeted therapy selection. EMA's IVDR framework accelerates companion diagnostic kit registrations through centralized assessment procedures. The Rhine-Main biotech cluster concentrates sequencing platform deployment across university hospitals and contract research organizations.
United Kingdom
The NHS Genomic Medicine Service embeds whole genome sequencing into rare disease pathways and oncology standards. GDPR implementation creates friction for cross-border biobank data flows with European research partners. The Cambridge-London corridor anchors nanopore platform adoption for rapid infectious disease diagnostics in acute care settings.
France
France Genomique's national infrastructure program funds high-throughput sequencing capacity in Paris, Lyon, and Marseille academic hospitals. ANSM and CNIL coordinate oversight of genomic data processing under divergent national GDPR interpretations. The Île-de-France region concentrates companion diagnostic development partnerships between pharmaceutical sponsors and sequencing service providers.
Netherlands
GenomeScan and national health insurer agreements establish reimbursement precedents for somatic tumor testing in Amsterdam and Rotterdam hospital networks. The EU AI Act conformity obligations reshape procurement specifications for variant interpretation software. The Eindhoven-Utrecht corridor hosts automated nucleic acid extraction manufacturing that supplies diagnostic laboratories across northwestern Europe.
Italy
Regional hospital networks in Lombardy and Emilia-Romagna expand molecular pathology capacity with EU cohesion fund support for precision medicine infrastructure. Underpenetrated diagnostic infrastructure in southern regions creates expansion potential for compact sequencing platforms. The Milan-Turin biotech cluster concentrates oncology-focused sequencing service providers serving pharmaceutical clinical trials.
Europe DNA Sequencing Products Market Key Industry Players
Concentration sits with integrated platform vendors that combine instrument hardware with recurring consumable revenue streams and regulatory-compliant software modules. The market structure favors vendors with multi-year service contracts spanning sample preparation through clinical report generation. Two strategic archetypes dominate: optical detection specialists leveraging installed base depth, and electronic sensing innovators capturing point-of-care decentralization. Competitive moves center on workflow integration acquisitions and IVDR certification acceleration for companion diagnostic partnerships.
Among North American-anchored platform developers, Illumina and Thermo Fisher Scientific occupy positions as archetypal integrated workflow providers, while Pacific Biosciences of California represents the long-read specialization vector. European-headquartered competitors include Oxford Nanopore Technologies, which anchors the portable electronic sensing segment, and QIAGEN, which exemplifies the sample-to-insight automation tier. These named entities illustrate how geographic origin and technology focus stratify competitive positioning across hospital procurement and research grant funding channels.
| Leading Market Players |
|---|
| Illumina |
| Thermo Fisher Scientific |
| QIAGEN |
| Agilent Technologies |
| F. Hoffmann-La Roche |
| Pacific Biosciences of California |
| Danaher Corporation |
| Oxford Nanopore Technologies |
| Eurofins Scientific Group |
| Others |
Cost & Logistics Intelligence
EMA's In Vitro Diagnostic Medical Devices Regulation gates both supplier qualification and price differentiation simultaneously, as CE-IVDR certification tiers separate premium companion diagnostic kits from standard research-use-only consumables while procurement departments in German and French hospital networks negotiate multi-year contracts tied to minimum volume commitments.
Pricing Analysis
Volume-discount tiering structures dominate sequencing consumable procurement, with three-tier pricing separating CE-IVDR certified companion diagnostics from standard clinical-grade reagents and economy-tier research-use products. Price differentiation rests on certification grade and after-sales service bundling, with IVDR-validated kits commanding substantial premia over uncertified alternatives. Cost compression in economy-tier reagents is intensifying because consolidated purchasing by Netherlands and French hospital networks extracts steeper volume discounts. Academic research institutes exhibit highest price sensitivity due to grant-dependent budgets, while comprehensive cancer centers prioritize assay reliability over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail for standard sequencing consumables, yet strategic stockpiling of specialized chemical inputs buffers against reagent supply concentration in Germany and Switzerland. Geographic supply concentration centers on German precision chemical manufacturers, Swiss specialty reagent suppliers, and Dutch automated extraction system producers. Raw material dependencies include fluorescent reversible terminators, semiconductor sequencing chips, and high-purity nucleotide triphosphates. Single-source vulnerability from limited qualified chemical suppliers creates exposure to input cost volatility. Distribution runs through direct vendor-to-laboratory relationships for high-value instruments, with regional distributors handling consumable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities now exceed hardware margins in European DNA sequencing, as recurring consumable revenue streams and regulatory-compliant software modules expand faster than instrument placement economics.
For Market Incumbents: Consolidate installed base loyalty through multi-year service contracts spanning sample preparation to clinical report generation, while accelerating backward integration into specialized reagent manufacturing to offset supply concentration risk from German and Swiss chemical suppliers. CE-IVDR certification investment represents the critical defensive lever against emerging entrants lacking regulatory documentation capabilities. For New Entrants and Emerging Players: Lead with point-of-care sequencing platforms targeting underpenetrated regional hospital networks in southern Italy and Spain, where diagnostic infrastructure gaps and EU cohesion fund availability create favorable entry conditions. A direct sales model emphasizing rapid turnaround time and minimal facility retrofit requirements addresses procurement authority shifts toward clinical departments. For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape by elevating variant interpretation software vendors with documented algorithmic validation protocols above hardware-focused platform developers. Long-term viability favors targets with integrated workflow solutions and established IVDR certification track records. The signal to watch is national reimbursement authority sequencing coverage decisions in France, Germany, and Italy.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVDR Certification Acceleration | EMA's centralized assessment procedures unlock companion diagnostic kit registrations across German and French cancer centers. |
| Workflow Integration Acquisition | Sample-to-insight automation addresses bioinformatics workforce scarcity constraining operational scale-up. |
| Point-of-Care Platform Launch | Compact sequencing systems penetrate underpenetrated Italian and Spanish regional hospital networks. |
| AI Compliance Service Development | Regulatory documentation support captures EU AI Act conformity obligations for variant interpretation software. |
| Reimbursement Strategy Investment | Health technology assessment alignment secures national health system funding for precision medicine programs. |
Research Approach
Operator-level perspectives from hospital laboratory directors, diagnostic procurement managers, regulatory affairs specialists at sequencing platform vendors, and biomedical informatics officers anchored the qualitative base. Primary interviews combined with secondary validation from EMA IVDR submission databases, hospital procurement contract registries, and national health technology assessment reports. Bottom-up instrument placement counts and top-down healthcare expenditure triangulation established market sizing boundaries.
Sensitivity analysis tested forecast robustness across alternative reimbursement scenarios and regulatory timeline assumptions over the projection horizon. Segmentation dimensions modeled include product type, technology platform, end-user category, and application area alongside regional regulatory cluster variations. CAGRs derived from instrument replacement cycles, consumable pull-through rates, and diagnostic test volume elasticity. Forecast inputs incorporated EMA approval velocity, national genomic medicine program funding trajectories, and GDPR implementation friction indices.
Underlying assumptions cover stable CE-IVDR certification capacity, continued national health system precision medicine funding, and unimpaired German-Swiss reagent supply corridors, with deviation risk concentrated in reimbursement authority coverage reversals and cross-border biobank data sharing restrictions. Revision becomes warranted when EU AI Act enforcement intensity or IVDR approval timeline extensions cross thresholds that materially alter vendor competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Agrigenomics Market
Genomics
Middle East and Africa Genetic Testing Market
Genomics
Europe Hereditary Cancer Testing Market
Genomics
Global Gene Amplification Technologies Market
Genomics
Reproductive Genetics Market
Genomics
Nutrigenomics Testing Market
Genomics
Transcriptomics Technologies Market
Genomics
Gene Sequencing Market
Genomics
Spatial Genomics and Transcriptomics Market
Genomics
Genetic Testing Panels Market
Genomics
Global Digital PCR Market
Genomics
Asia-Pacific Genetic Testing Market
Genomics
NGS-Based RNA-Sequencing Market
Genomics
Prenatal Genetic Testing Market
Genomics
Tumor-Sequencing Blood Testing Market
Genomics
Global Blockchain in Genomic Data Management Market