
 United Kingdom Metal Packaging Market | 2026-2036
United Kingdom Metal Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Metal Packaging Market Analytics
The UK Plastic Packaging Tax is repositioning beverage brand owners toward aluminum can formats ahead of escalating compliance costs. Ardagh Metal Packaging Trading UK leverages its integrated beverage can lines to capture migration volumes from PET bottles. Tata Steel Packaging anchors food can supply through tinplate capacity optimized for acidic food preservation. Crown Packaging Manufacturing UK Ltd differentiates via decorated two-piece aerosol and specialty can capabilities serving personal care multinationals.
United Kingdom metal packaging comprises rigid and semi-rigid containers, closures, and foils fabricated from aluminum, steel, or tinplate substrates through drawing, ironing, welding, or stamping processes, engineered to provide barrier protection against oxygen, light, and moisture for shelf-stable goods. Cans dominate volume throughput due to beverage industry pull and recycling infrastructure maturity, while foils command premium margin pools in pharmaceutical blister and lidding applications where barrier precision dictates specification. Aluminum leads material substitution trends as brands pursue weight reduction and magnet-compatible recycling streams, whereas tinplate sustains entrenched positions in retort-grade food containers where corrosion resistance remains non-negotiable.
The Environment Agency enforces Extended Producer Responsibility targets that obligate packaging producers to fund end-of-life collection and recycling, directly shaping format selection and lightweighting R&D priorities across the value chain. BSI standards for food contact materials and the UK REACH regime govern chemical migration limits and substrate composition, creating compliance thresholds that favor established suppliers with testing infrastructure and technical file capabilities. Stakeholders must monitor evolving modulated fee structures under EPR implementation and assess whether domestic recycling capacity expansion keeps pace with aluminum can demand acceleration.
Market Dynamics
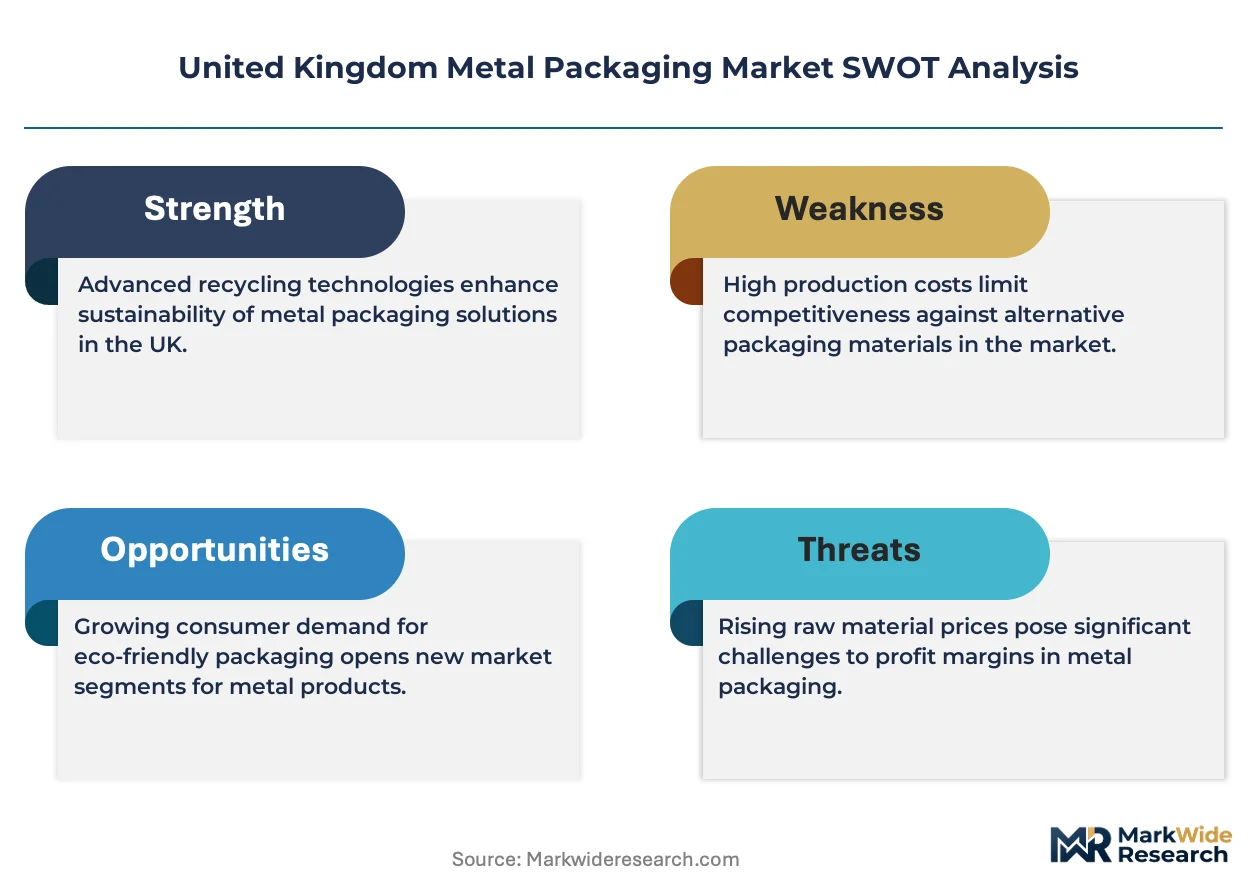
The UK Plastic Packaging Tax is compressing format substitution timelines as beverage brand owners accelerate aluminum can transitions ahead of escalating compliance costs. This regulatory pressure is electrifying capital deployment across Midlands canmaking clusters while reshaping supplier qualification criteria.
Growth Catalysts
- Extended Producer Responsibility reforms:The Environment Agency's modulated fee structures are accelerating lightweighting investments across steel and aluminum formats. Packaging producers now fund end-of-life collection, creating direct R&D pull for material efficiency.
- Midlands manufacturing corridor concentration:Canmaking clusters in England's Midlands serve beverage multinationals with integrated supply chains. Proximity to filling operations reduces logistics costs and carbon intensity.
- Aluminum recycling infrastructure maturity:Magnet-compatible sorting streams and established reprocessing capacity enable closed-loop claims. Brands leverage this for scope 3 emissions reduction targets.
Market Restraints
- Tinplate input cost volatility:Steel substrate pricing fluctuates with energy-intensive smelting economics. Food can manufacturers face margin compression during commodity spikes.
- Supply concentration in beverage cans:Carbonated soft drink bottlers dominate order books, creating demand cyclicality risk. Diversification into food and aerosol segments remains limited.
- Technical limitation in acidic food compatibility:Aluminum corrosion resistance falls short for high-acid retort applications. Tinplate maintains entrenched position despite weight penalties.
Strategic Opportunities
- Pharmaceutical blister foil expansion:Barrier precision requirements in drug packaging command premium margin pools. Domestic conversion capacity lags continental European suppliers.
- Wales and Northern England underpenetration:Peripheral UK regions lack canmaking infrastructure relative to Midlands density. Greenfield sites could capture regional beverage demand.
- UK REACH chemical migration alignment:Technical file capabilities favor established suppliers with testing infrastructure. Compliance thresholds create qualification barriers for new entrants.
Industry Challenges
- Tooling and die engineering skill scarcity:Deep-drawn can manufacturing requires specialized press operation expertise. Apprenticeship pipelines have thinned across West Midlands industrial zones.
- Legacy ERP integration with EPR reporting modules:Packaging producers must retrofit data systems for modulated fee calculations. Software vendors lack sector-specific compliance templates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Metal Packaging Market |
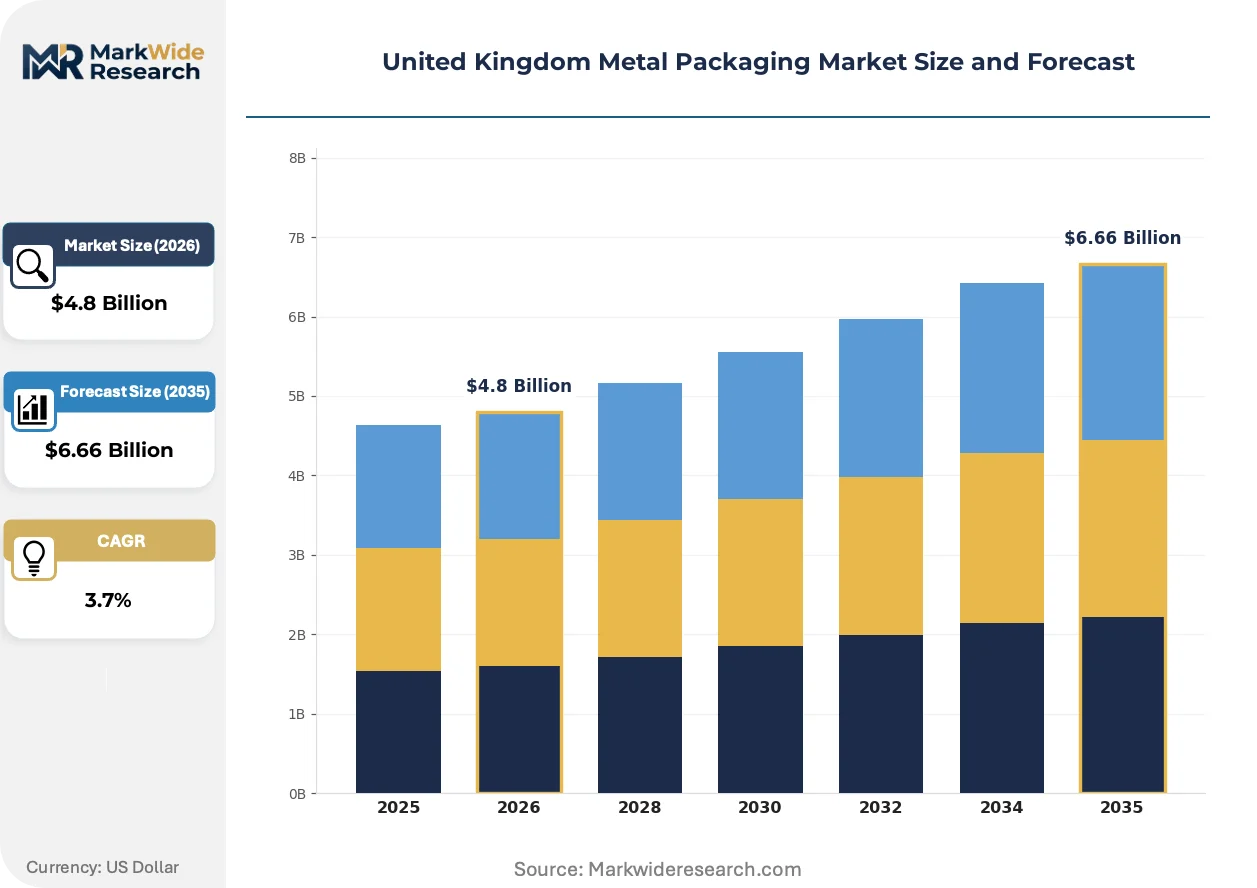
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cans, Foils, Trays, Containers Material: Aluminum, Steel, Tinplate, Others Application: Food, Beverage, Pharmaceuticals, Personal Care End User: Household, Industrial, Retail, Food Service |
| Companies Covered | Ardagh Metal Packaging Trading UK, William Say & Co Ltd, Ball Beverage Packaging Holdings UK Ltd, Tata Steel Packaging, Roberts Metal Packaging, Crown Packaging Manufacturing UK Ltd, Trivium Packaging BV, Eviosys, Can-Pack UK Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Metal Packaging Market Evolving Landscape
Digital printing and smart packaging interfaces are compressing decoration cycle times while enabling batch-level traceability. These capabilities are repositioning metal containers as data-capture endpoints rather than passive barriers.
Digital inkjet decoration is electrifying can design workflows by eliminating mechanical plate changeovers. Beverage brand owners now execute limited-edition campaigns with two-week turnaround versus traditional six-week lead times. This flexibility is compressing minimum order quantities and enabling regional flavor localization.
The Environment Agency's Extended Producer Responsibility enforcement is mandating recycled content verification across aluminum and steel formats. Producers must demonstrate mass balance through accredited certification bodies. Food can segments face the steepest compliance curve due to complex multi-material laminations.
Direct-to-retailer procurement consolidation is compressing distributor intermediation in beverage can supply. Major supermarket chains now negotiate frame contracts with Ardagh and Crown for private-label water and soft drink lines. This disintermediation is most visible in England's Southeast retail corridor where Tesco and Sainsbury's dominate shelf space allocation.
United Kingdom Metal Packaging Market Segmentation
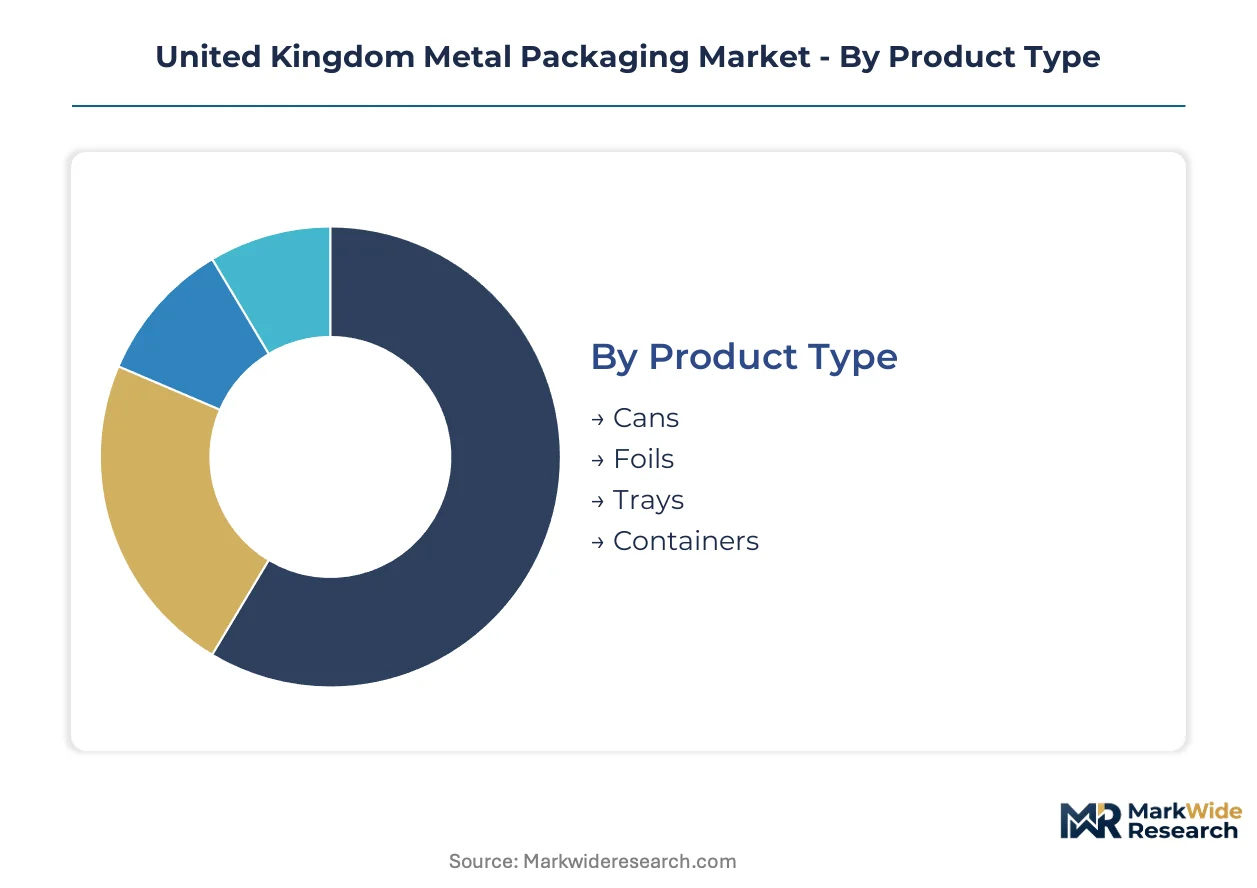
Segmentation in the United Kingdom metal packaging market reveals how regulatory pressure and material substitution reshape procurement patterns across substrate types and end-use applications. Format selection increasingly hinges on Extended Producer Responsibility compliance costs rather than traditional performance metrics alone.
Product Type:
Supply concentration in England's Midlands manufacturing corridor disproportionately favors high-throughput formats with dedicated canmaking infrastructure and integrated filling partnerships.
- Cans:Two-piece aluminum beverage containers and three-piece steel food cans dominate volume throughput due to established drawing and ironing press capacity. Carbonated soft drink bottlers in the Midlands corridor are expanding aluminum can orders ahead of plastic taxation deadlines, compressing supplier lead times.
- Foils:Thin-gauge aluminum rolls and sheets engineered for barrier applications in pharmaceutical blister packs and flexible lidding command premium positioning. Demand concentrates in Southeast England's pharmaceutical manufacturing zones where barrier precision requirements exceed commodity substrate capabilities.
- Trays:Semi-rigid aluminum and steel formed containers serve ready-meal and food service applications with retort compatibility limitations.
- Containers:Specialty drawn and stamped metal enclosures span aerosol, industrial, and decorative tin applications with fragmented regional demand.
Today's leader: Cans. Tomorrow's challenger: Foils.
Material:
Cost tier differentiation separates lightweight aluminum formats from corrosion-resistant steel substrates, with procurement patterns shifting toward magnet-compatible recycling streams.
- Aluminum:Non-ferrous substrate enabling significant weight reduction in beverage packaging with established closed-loop reprocessing infrastructure. The Environment Agency's modulated fee structures are accelerating lightweighting investments across aluminum formats as brands pursue scope 3 emissions reduction targets.
- Steel:Ferrous substrate sustaining entrenched positions in retort-grade food containers where structural rigidity under thermal processing remains non-negotiable. Tinplate food can manufacturers face margin compression during energy-intensive smelting commodity spikes.
- Tinplate:Electrolytically coated steel substrate optimized for acidic food preservation with corrosion resistance aluminum cannot match.
- Others:Niche substrates including chromium-coated steel and laminated metal composites serving specialized barrier applications.
Aluminum is climbing the fastest. Tinplate defends incumbent share in food preservation.
Application:
Volume concentration in beverage applications creates demand cyclicality risk, while pharmaceutical and personal care segments offer diversification into premium margin pools.
- Food:Retort-processed shelf-stable products and ambient-ready meals requiring corrosion-resistant tinplate or coated steel substrates. Technical limitations in aluminum corrosion resistance preserve steel's entrenched position despite weight penalties in high-acid applications.
- Beverage:Carbonated soft drinks, beer, and water driving aluminum can substitution from PET bottles ahead of UK Plastic Packaging Tax implementation. Direct-to-retailer procurement consolidation is compressing distributor intermediation as major supermarket chains negotiate frame contracts for private-label lines.
- Pharmaceuticals:Blister foil and lidding applications where barrier precision dictates specification and domestic conversion capacity lags continental European suppliers.
- Personal Care:Two-piece aerosol and specialty decorated can capabilities serving cosmetic and household product multinationals with compressed design cycle requirements.
Beverage commands current volume. Pharmaceuticals represent the steepest margin expansion trajectory.
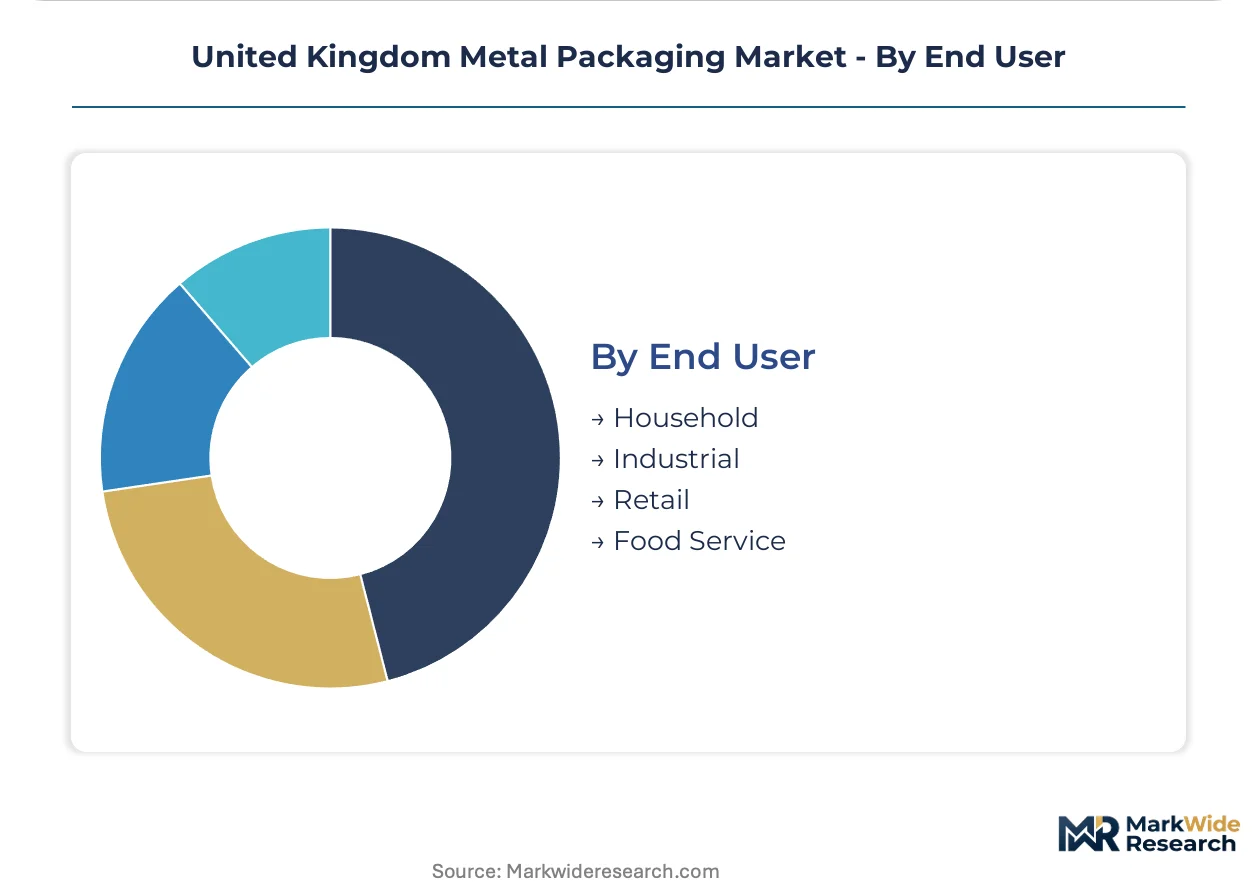
End User:
Customer type stratification reveals procurement consolidation among retail chains versus fragmented food service demand, with industrial users driving specification standardization.
- Household:Consumer-packaged goods in retail formats where recycling claims and shelf appeal influence format selection. Extended Producer Responsibility targets obligate packaging producers to fund end-of-life collection, directly shaping household-facing format selection.
- Industrial:Bulk chemical, lubricant, and process material containment requiring UN-certified and hazardous goods-compatible specifications. BSI standards for food contact materials and UK REACH regime govern chemical migration limits, creating compliance thresholds that favor established suppliers with testing infrastructure.
- Retail:Supermarket and convenience store shelf-ready packaging with direct supplier negotiation power concentrated in England's Southeast retail corridor.
- Food Service:Catering, hospitality, and institutional feeding applications with fragmented regional demand and limited format standardization.
Retail chains concentrate purchasing leverage. Food Service remains structurally fragmented with regional supply gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metal packaging fabrication in Britain traces its industrial lineage to nineteenth-century tinplate works in South Wales and the Black Country, where sheet steel rolling and canmaking co-evolved with brewing and food preservation demand. Today's geographic pattern retains this historical footprint while concentrating investment in England's manufacturing heartland.
Midlands
Beverage can demand from carbonated soft drink bottlers concentrates drawing and ironing press capacity across Birmingham, Wolverhampton, and Derbyshire. The Environment Agency's Extended Producer Responsibility modulated fees accelerate lightweighting R&D investment across aluminum formats. Canmaking clusters here serve multinational filling operations with integrated logistics reducing carbon intensity.
London and Southeast England
Pharmaceutical blister foil and lidding applications command premium positioning in Hertfordshire and Berkshire manufacturing zones where barrier precision exceeds commodity substrate capabilities. UK REACH chemical migration limits govern specification compliance. Southeast retail corridors host direct-to-supermarket procurement negotiations compressing distributor intermediation.
North England
Steel tinplate food can manufacturing sustains entrenched positions in Sheffield and Rotherham where corrosion-resistant retort-grade containers serve acidic food preservation. Energy-intensive smelting economics create input cost volatility pressuring margins. Technical apprenticeship pipelines have thinned across West Midlands industrial zones creating tooling expertise scarcity.
Wales
Historical tinplate production heritage in Port Talbot and Newport anchors steel substrate supply for food packaging applications. The UK's Plastic Packaging Tax implementation accelerates format substitution timelines toward aluminum alternatives. Peripheral canmaking infrastructure gaps relative to Midlands density create greenfield investment opportunities for regional beverage demand capture.
Scotland
Whisky and craft beverage bottling drives specialty decorated can demand across Glasgow and Edinburgh metropolitan areas. BSI standards for food contact materials govern substrate composition compliance. Distillery proximity to filling operations enables shorter supply chains for premium spirit packaging formats.
United Kingdom Metal Packaging Market Competitive Landscape
Capital-heavy integrated producers compete with specialized converters across substrate and format boundaries. The supplier base consolidates around beverage can scale leaders while fragmenting across food, aerosol, and specialty applications. Three archetypes dominate: multinational integrated packaging groups with captive aluminum rolling, steel-centric tinplate specialists serving retort food segments, and regional decorators focused on short-run specialty designs. Competitive dynamics center on capacity expansion in aluminum beverage lines and backward integration into substrate supply.
Among UK-registered operations, Ardagh Metal Packaging Trading UK and Crown Packaging Manufacturing UK Ltd exemplify integrated beverage can scale archetypes with Midlands corridor concentration, while Tata Steel Packaging anchors steel substrate supply for corrosion-resistant food applications. Ball Beverage Packaging Holdings UK Ltd occupies a position within aluminum format specialization. These entities represent the competitive tension between lightweight aluminum substitution momentum and tinplate's entrenched retort-grade performance.
| Leading Market Players |
|---|
| Ardagh Metal Packaging Trading UK |
| William Say & Co Ltd |
| Ball Beverage Packaging Holdings UK Ltd |
| Tata Steel Packaging |
| Roberts Metal Packaging |
| Crown Packaging Manufacturing UK Ltd |
| Trivium Packaging BV |
| Eviosys |
| Can-Pack UK Ltd |
| Others |
Value Network & Pricing Analysis
Tooling and die engineering expertise scarcity across West Midlands industrial zones widens labor-cost spreads between premium decorated specialty formats and commodity beverage can tiers. The Environment Agency's Extended Producer Responsibility modulated fees compress margin structures for producers lacking lightweighting R&D scale, forcing price-tier stratification that rewards integrated Midlands clusters.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations, with barrier precision certification and volume scale anchoring differentiation. Premium pharmaceutical blister foil commands substantial spreads over commodity beverage substrates due to UK REACH technical file compliance costs. Pricing pressure stems from tinplate input cost volatility during energy-intensive smelting commodity spikes. Private-label beverage bottlers exhibit highest price sensitivity, while pharmaceutical multinationals prioritize barrier performance over unit economics.
Supply Chain Analysis
Regional distribution centers across Birmingham and Wolverhampton operate hub-and-spoke patterns serving carbonated soft drink filling operations with integrated logistics. Substrate supply draws from Port Talbot steel rolling capacity and imported aluminum ingot streams. Raw material dependencies include electrolytic tinplate, aluminum coil stock, and specialty coating chemistries. Single-source vulnerability concentrates in Midlands canmaking press capacity. Distribution runs through direct-to-retailer frame contracts with major supermarket chains, compressing traditional distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom metal packaging market represents a late-cycle quality story as beverage brand owners migrate toward aluminum formats with closed-loop recycling claims ahead of plastic taxation deadlines. This demand-shift toward premium lightweight specifications rewards producers with integrated substrate supply and EPR compliance infrastructure.
For Market Incumbents: Anchor defensive positioning through backward integration into aluminum rolling capacity and captive recycling stream certification. The Environment Agency's evolving modulated fee structures threaten margin compression for producers lacking mass balance verification capabilities. Prioritize lightweighting R&D investment in beverage can lines while defending tinplate food can share through corrosion-resistant coating innovation. For New Entrants and Emerging Players: Direct-to-retailer digital procurement platforms offer lower-friction entry into private-label beverage supply. Wales and Northern England present the most penetrable geography given peripheral canmaking infrastructure gaps relative to Midlands density. Target pharmaceutical blister foil conversion capacity where domestic supply lags continental European competitors and barrier precision commands premium positioning. For Investors and Strategic Acquirers: Beverage multinational packaging procurement divisions are the most active acquirer in this space, pursuing captive canmaking capacity for scope 3 emissions reduction targets. Long-term viability centers on aluminum format specialization with EPR-compliant recycling infrastructure. Monitor Environment Agency enforcement intensity on recycled content verification as the key inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Lightweighting R&D Investment | The Environment Agency's modulated fees directly reward material efficiency improvements in aluminum beverage formats. |
| Backward Integration into Substrate Supply | Captive aluminum rolling capacity insulates margin compression from commodity spot volatility in ingot markets. |
| Pharmaceutical Blister Foil Capacity Expansion | Barrier precision requirements in Southeast England's pharmaceutical zones exceed domestic conversion capabilities. |
| EPR Compliance Infrastructure Buildout | Mass balance certification systems enable closed-loop recycling claims for beverage brand scope 3 targets. |
| Regional Greenfield Canmaking Sites | Wales and Northern England infrastructure gaps create first-mover capture opportunities for regional beverage demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with canmaking plant managers, beverage procurement directors, pharmaceutical packaging engineers, and recycling facility operators alongside secondary validation. Trade data from HM Revenue and Customs, British Metals Recycling Association statistics, Environment Agency EPR implementation guidance, and UK REACH technical documentation anchored supply-side modeling. Bottom-up capacity assessments triangulated against top-down demand segmentation across substrate types and end-use applications.
Comparable historical reference periods anchored projection modeling across the analysis window, with segmentation dimensions spanning material substrate, product format, application vertical, and geographic manufacturing cluster. CAGRs derived from fitted growth curves incorporating aluminum substitution momentum, EPR compliance cost trajectories, and beverage industry format shift elasticities. Forecast inputs included Midlands corridor capacity utilization rates and pharmaceutical manufacturing zone expansion pipelines.
The model assumes a particular technology adoption path; alternative pathways for digital inkjet decoration and smart packaging integration would alter the outlook for minimum order quantity compression and design cycle economics. Forecasts reflect documented assumptions on regulatory enforcement timelines and recycling infrastructure buildout rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Asia Pacific Metal Cans Market
Metal Packaging
Europe Metal Closures Market
Metal Packaging
Aluminium Bottle Market
Metal Packaging
Aluminum Aerosol Cans Market
Metal Packaging
North America Aluminium Cans Market
Metal Packaging
Thailand Metal Packaging Market
Metal Packaging
Brass Foils Market
Metal Packaging
3-Piece Metal Cans Market
Metal Packaging
Indonesia Metal Packaging Market
Metal Packaging
Middle East and Africa Food Cans Market
Metal Packaging
Tin Cans Market
Metal Packaging
Cans Market
Metal Packaging
North America Metal Cans Market
Metal Packaging
Egypt Metal Packaging Market
Metal Packaging
Household Aluminum Foils Market
Metal Packaging
South Africa Metal Packaging Market