
 Metal Aerosol Can Market | 2026-2036
Metal Aerosol Can Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Aerosol Can Market Outlook
Subscription-based refill programs for personal care aerosols is realigning how brands contract manufacturing capacity. Crown Holdings leverages its European coating technology to secure long-term supply agreements with cosmetic multinationals. Ball Corporation anchors North American aluminum supply through backward integration into recycled sheet production. Trivium Packaging differentiates via printed matte finishes that support premium household positioning.
Metal aerosol cans are cylindrical pressure vessels fabricated from aluminum or tinplate steel, typically featuring internal epoxy or polyester linings and precision-crimped valve mounts to contain propellants at 6-10 bar. They serve as the dominant primary packaging format for dispensed foams, sprays, and mists across consumer and industrial applications. Aluminum cans lead volume globally due to corrosion resistance and infinite recyclability, while specialty cans with custom diameters capture disproportionate margin pools in pharmaceutical and niche cosmetic segments. Steel cans sustain share in automotive and industrial channels where cost sensitivity and impact durability outweigh lightweighting priorities.
The EPA regulates volatile organic compound emissions under 40 CFR Part 59, directly limiting propellant chemistry and driving liner compatibility investments. REACH substance restrictions and EU Green Deal circularity benchmarks mandate minimum recycled content thresholds and restrict certain epoxy-based coatings, reshaping supplier qualification requirements across European conversion lines. Stakeholders must monitor evolving state-level extended producer responsibility frameworks in the United States and assess whether aluminum or steel platforms align better with emerging deposit-return schemes and carbon border adjustments.
Market Dynamics
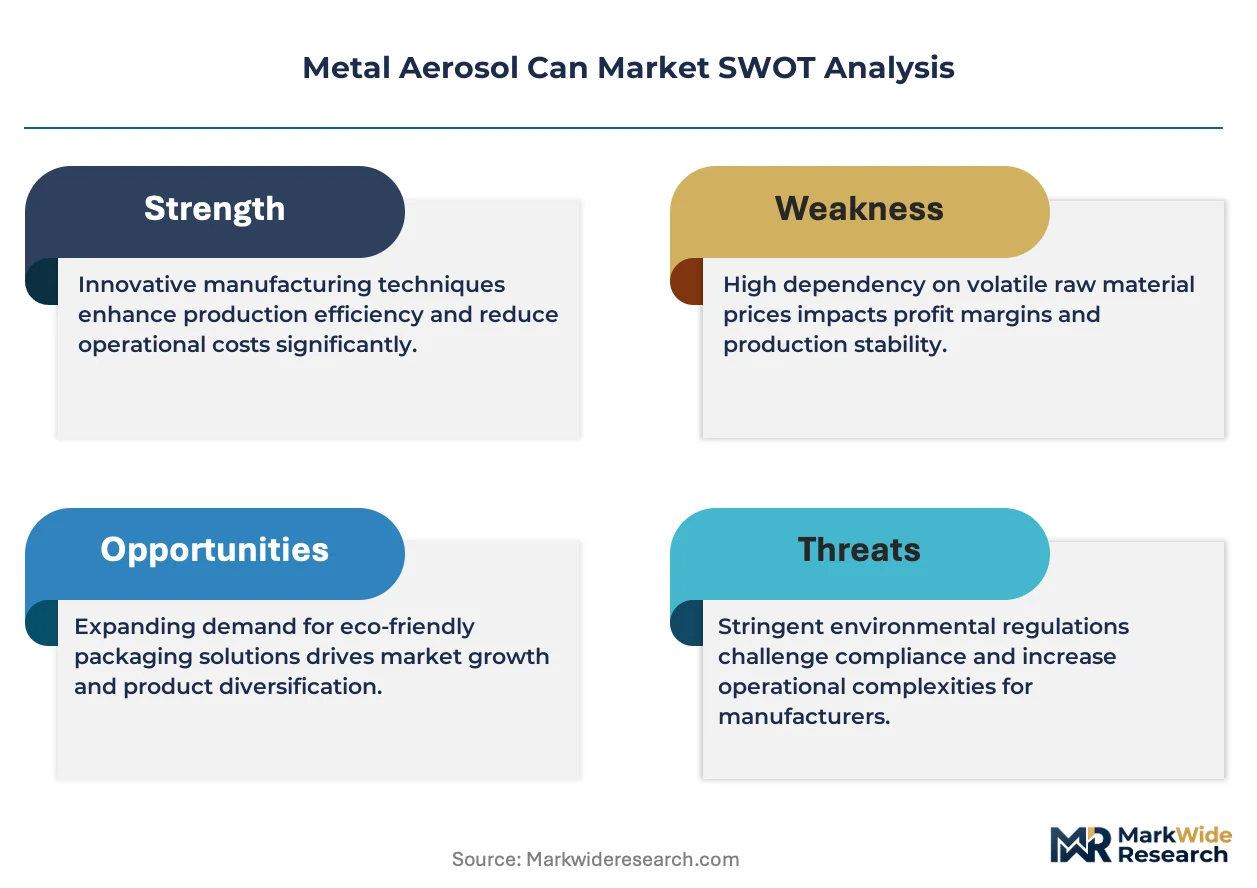
REACH substance restrictions and EU Green Deal circularity benchmarks are forcing material substitutions and liner innovations across European conversion lines, while Ball Corporation and Crown Holdings anchor supply through backward integration into recycled aluminum sheet production.
Growth Catalysts
- REACH mandates:Recycled content thresholds and epoxy coating restrictions in Europe accelerate qualification of compliant liner chemistries, pulling investment toward sustainable conversion lines.
- Personal care SKU expansion:Deodorant and dry shampoo aerosol launches in Brazil and Southeast Asia extend contract manufacturing demand for aluminum diameters.
- Recyclability premiums:Infinite-loop aluminum properties command preference in German cosmetic and household brand procurement, reinforcing high-speed production commitments.
Market Restraints
- Propellant chemistry limits:EPA 40 CFR Part 59 volatile organic compound caps constrain formulation flexibility and require liner compatibility testing cycles.
- Aluminum sheet concentration:Recycled aluminum supply clusters in Germany and the United States create geographic dependency for European and North American can makers.
- Steel substitution in industrial channels:Tinplate cans retain cost and impact-durability advantages in automotive aerosol applications, capping aluminum penetration.
Strategic Opportunities
- Subscription refill programs:Personal care brands are realigning manufacturing capacity contracts toward long-term supply agreements with coating-technology leaders.
- Extended producer responsibility frameworks:State-level deposit-return schemes in the United States favor aluminum platforms with established recycling infrastructure.
- Printed matte finishes:Premium household positioning through differentiated surface aesthetics opens margin pools beyond commodity cylinder production.
Industry Challenges
- Liner innovation timelines:Epoxy-to-polyester coating transitions require extended qualification periods with cosmetic multinationals, compressing product development windows.
- Valve-mount precision scaling:High-speed crimping equipment for 6-10 bar pressure vessels demands specialized maintenance expertise that concentrates in German engineering clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Aerosol Can Market |
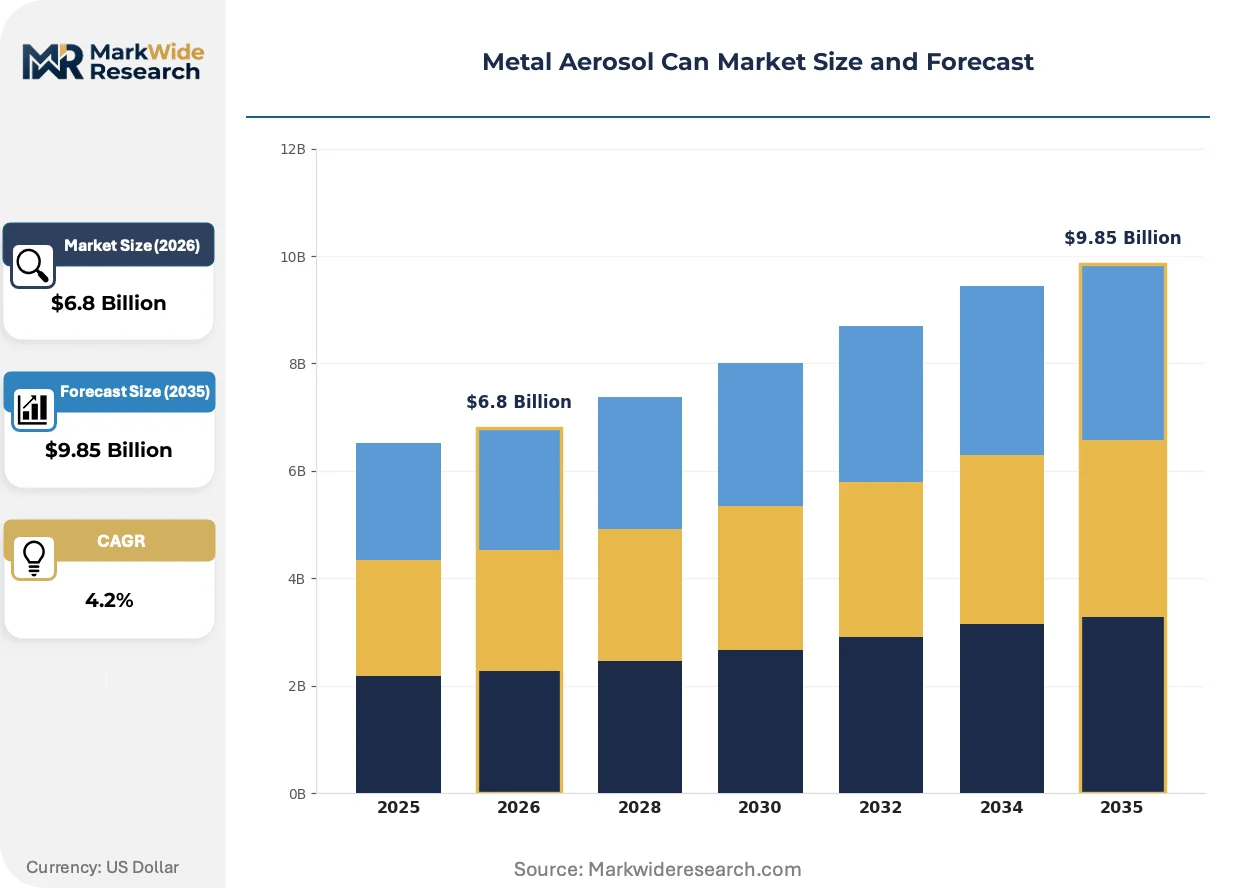
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Cans, Steel Cans, Combination Cans, Specialty Cans End Use: Personal Care, Household Products, Automotive, Industrial Products Diameter: Standard Diameter, Wide Diameter, Mini Diameter, Custom Diameter Finish Type: Matt Finish, Gloss Finish, Metallic Finish, Custom Finish |
| Companies Covered | Ball Corporation, Crown Holdings, Inc., Trivium Packaging, CCL Container, Toyo Seikan Co. Ltd., Ardagh Group, Mauser Packaging Solutions, EXAL Corporation, Nampak Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Aerosol Can Market Strategic Shifts
Coating chemistry unification, regulatory chemistry constraints, and procurement model evolution are compressing development cycles and reshaping how brands contract conversion capacity across personal care and household segments.
Water-based internal lining systems are unifying corrosion protection and volatile organic compound compliance in a single material platform. Cosmetic multinationals in Germany and France are accelerating adoption to meet REACH coating restrictions. This unification is compressing the supplier qualification pipeline from dual-track epoxy-and-polyester evaluations toward single-source water-based certification.
EPA 40 CFR Part 59 enforcement is tightening propellant formulation windows and forcing liner compatibility investments across North American production lines. Industrial aerosol makers face reformulation costs that commodity personal care producers absorb through volume scale. The automotive segment responds by retaining steel can platforms where impact durability outweighs lightweighting incentives.
Refill-based subscription contracts are displacing spot purchasing in personal care aerosol procurement. Brands in Brazil and Southeast Asia are locking multi-year manufacturing commitments with European coating-technology holders. This shift concentrates most visibly in dry shampoo and deodorant categories where SKU proliferation demands flexible diameter conversion.
Metal Aerosol Can Market Segmentation
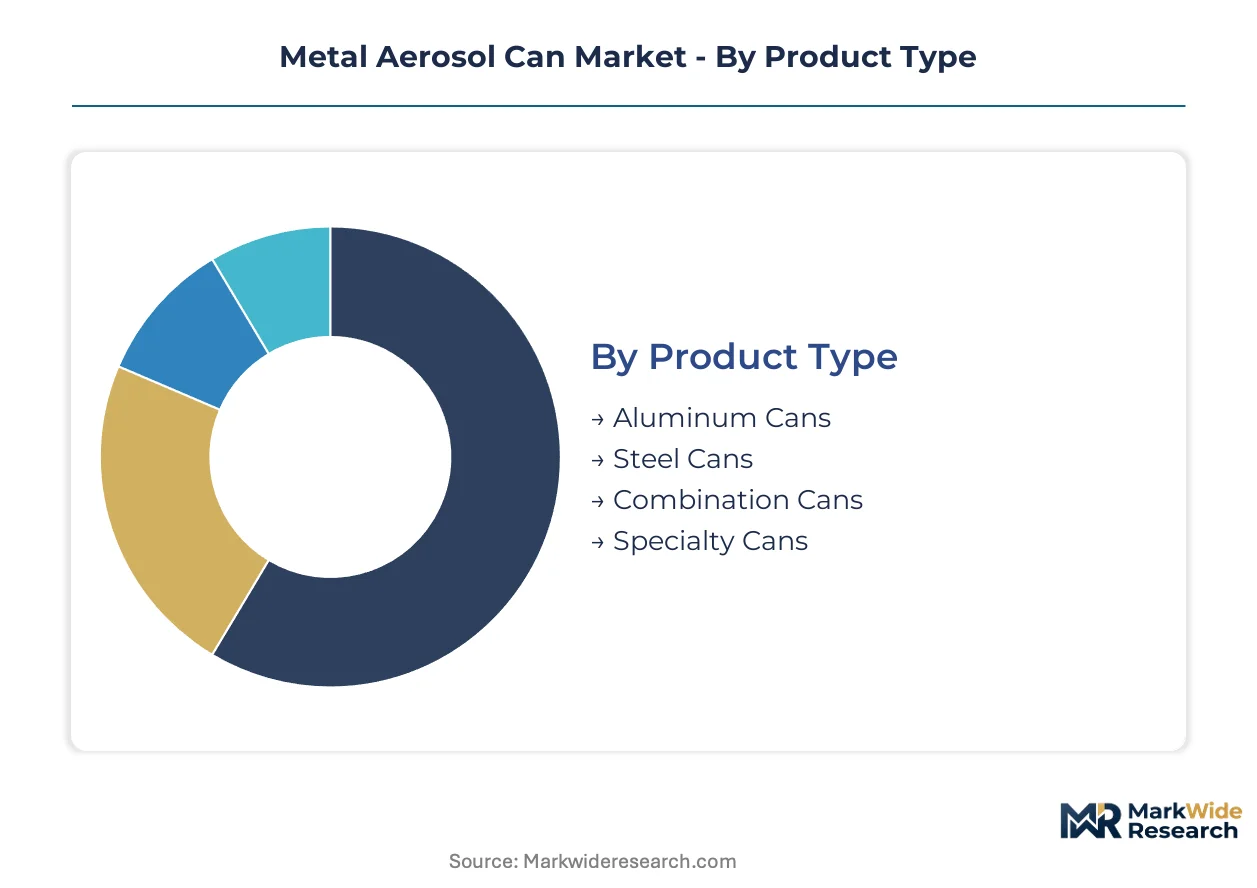
Metal aerosol can segmentation reflects divergent pressure requirements, recyclability mandates, and surface aesthetics across consumer and industrial channels. Specification choices directly determine liner chemistry investments, coating qualification timelines, and contract manufacturing terms.
Product Type:
Material selection governs corrosion resistance, pressure tolerance, and circular economy compliance across conversion lines.
- Aluminum Cans:Fabricated from recycled sheet stock with infinite-loop recyclability and 6-10 bar pressure tolerance. German cosmetic brands and Brazilian personal care manufacturers concentrate procurement here due to REACH-compliant coating compatibility and lightweighting advantages.
- Steel Cans:Tinplate construction delivers impact durability for automotive and industrial aerosols where cost sensitivity outweighs weight reduction priorities. German automotive suppliers and North American industrial channels sustain demand despite aluminum substitution pressure.
- Combination Cans:Hybrid aluminum-steel configurations balance cost and performance for mid-tier household products.
- Specialty Cans:Custom pressure ratings and liner specifications serve pharmaceutical and niche cosmetic segments with extended qualification requirements.
Mature deployment sits with Aluminum Cans. Newer deployment is concentrated in Specialty Cans.
End Use:
Application-specific propellant chemistry and liner compatibility requirements segment procurement behavior and contract structures.
- Personal Care:Deodorant and dry shampoo aerosols in Brazil and Southeast Asia drive SKU proliferation and flexible diameter conversion demand. Subscription refill programs are realigning long-term manufacturing capacity contracts toward coating-technology leaders.
- Household Products:Surface cleaners and air fresheners command printed matte finishes for premium positioning, opening margin pools beyond commodity cylinder production.
- Automotive:Impact durability requirements retain tinplate steel platforms despite lightweighting incentives elsewhere.
- Industrial Products:Solvent-based formulations face EPA 40 CFR Part 59 volatile organic compound constraints, requiring extended liner compatibility testing cycles.
Procurement volume clusters in Personal Care. Steepest expansion trajectory appears in Household Products.
Diameter:
Format dimensions determine valve-mount precision requirements and crimping equipment specifications across production lines.
- Standard Diameter:Dominant format for mass-market deodorants and household sprays with established high-speed conversion infrastructure.
- Wide Diameter:Expanded surface area supports foam dispensing and higher-volume personal care applications in Southeast Asian markets.
- Mini Diameter:Travel-size and sample formats gain traction in Brazilian personal care SKU expansion strategies.
- Custom Diameter:Pharmaceutical and niche cosmetic segments capture disproportionate margin pools through specialized pressure vessel engineering.
Equipment amortization favors Standard Diameter. Capacity investment is flowing toward Custom Diameter.
Finish Type:
Surface aesthetics differentiate brand positioning and determine coating chemistry unification pathways.
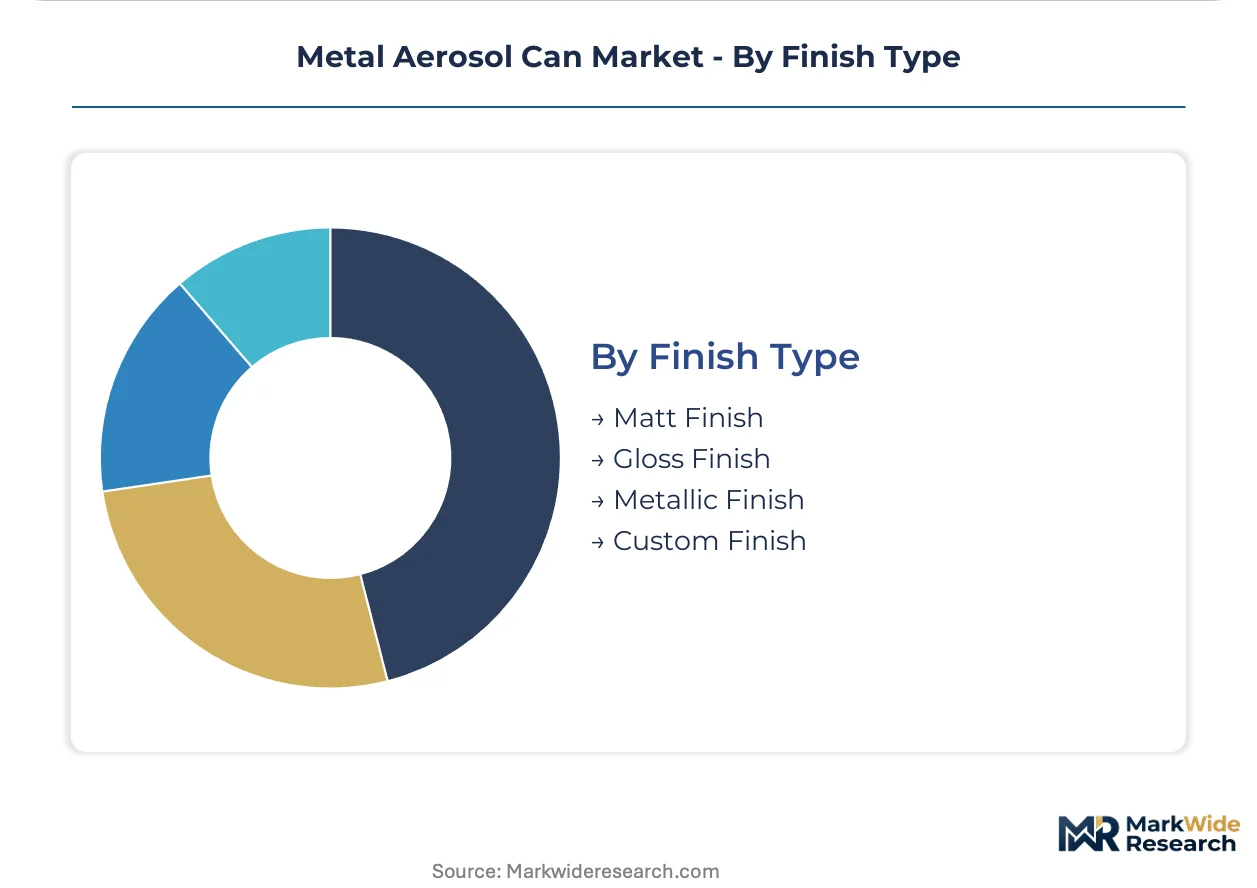
- Matt Finish:Premium household positioning through differentiated surface aesthetics opens margin pools beyond commodity production. Trivium Packaging leverages printed matte technology to secure cosmetic multinational contracts.
- Gloss Finish:High-sheen conventional coating dominates mass-market personal care with established epoxy and polyester qualification pathways.
- Metallic Finish:Aluminum substrate showcase format reinforces recyclability messaging for German Green Deal compliance.
- Custom Finish:Tactile and visual differentiation commands qualification premiums in pharmaceutical and luxury cosmetic segments.
Process standardization centers on Gloss Finish. Brand differentiation investment targets Matt Finish.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters in Germany and the United States supply conversion lines serving cosmetic and household brands across multiple continents. Consumption concentrates in Brazil and Southeast Asia where personal care aerosol SKU expansion accelerates. Regulatory divergence between REACH-compliant Europe and EPA-regulated North America shapes material qualification pathways.
Germany
Ball Corporation and Crown Holdings operate high-speed aluminum lines serving European cosmetic brands with infinite-loop recyclable cans. REACH substance restrictions and EU Green Deal circularity benchmarks mandate minimum recycled content thresholds and restrict certain epoxy-based coatings. The Rhine-Ruhr industrial corridor anchors coating-technology qualification pipelines for compliant liner chemistries.
United States
Household product manufacturers and automotive aerosol makers sustain demand across aluminum and tinplate platforms. EPA 40 CFR Part 59 volatile organic compound caps constrain propellant chemistry and drive liner compatibility investments. The Great Lakes manufacturing belt concentrates recycled aluminum sheet production through backward-integrated supply chains.
Brazil
Deodorant and dry shampoo aerosol launches drive SKU proliferation and flexible diameter conversion demand. ANVISA pharmaceutical and cosmetic regulations govern propellant safety and packaging material approvals. São Paulo industrial districts host contract manufacturing capacity serving Latin American personal care brand expansion.
China
Domestic personal care brands and export-oriented household product manufacturers absorb aluminum can volume at scale. GB standards and MIIT industrial policy guide packaging material specifications and recyclability targets. The Yangtze River Delta clusters conversion capacity for Southeast Asian market supply.
Indonesia
Expanding middle-class consumption of personal care aerosols supports wide-diameter can demand for foam dispensing applications. The national standards body coordinates alignment with ASEAN harmonized packaging regulations. Java-based manufacturing zones attract coating-technology partnerships with European equipment suppliers.
Metal Aerosol Can Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the metal aerosol can value chain. Ball Corporation and Crown Holdings anchor supply through captive recycled aluminum sheet production, while specialized coating-technology holders secure long-term cosmetic multinational contracts. Three archetypes dominate: integrated aluminum converters, tinplate specialists serving industrial channels, and coating-technology licensors. Competitive moves concentrate on capacity expansion in high-speed conversion lines and strategic partnerships for water-based liner qualification.
Among North American integrated converters, Ball Corporation exemplifies the backward-integrated archetype with captive supply chain control. Crown Holdings occupies a comparable position in European coating-technology leadership. Trivium Packaging represents the differentiated-finishes tier through printed matte capabilities that support premium household positioning. These three anchors illustrate how scale, technology licensing, and surface aesthetics stratify competitive positioning across personal care and industrial segments.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings, Inc. |
| Trivium Packaging |
| CCL Container |
| Toyo Seikan Co. Ltd. |
| Ardagh Group |
| Mauser Packaging Solutions |
| EXAL Corporation |
| Nampak Ltd |
| Others |
Value Chain & Pricing Dynamics
REACH-compliant coating mandates in Europe are forcing cosmetic multinationals to requalify liner chemistries, compelling converters to absorb qualification costs and pass through premiums for water-based systems. This specification pressure concentrates pricing power with coating-technology holders while squeezing commodity cylinder margins.
Pricing Analysis
Cost compression in standard-diameter aluminum cans intensifies as Brazilian and Southeast Asian personal care brands consolidate procurement volumes. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified water-based liners from conventional epoxy coatings and unlined steel alternatives. Price differentiation hinges on coating certification tier and volume scale commitments. Household product manufacturers exhibit highest price sensitivity due to commodity positioning, while German cosmetic brands accept premium positioning for infinite-loop recyclability messaging.
Supply Chain Analysis
Freight cost volatility for recycled aluminum sheet from Germany and the United States is reshaping geographic sourcing strategies for European and North American converters. Supply concentrates in the Rhine-Ruhr corridor and Great Lakes manufacturing belt, with raw material dependencies on post-consumer aluminum scrap, tinplate steel coil, and water-based resin chemistries. Single-source vulnerability sits with German engineering clusters for high-speed crimping equipment. Distribution runs through contract manufacturing networks serving personal care brand expansion in Brazil and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-speed conversion line capacity scarcity props pricing for qualified coating-technology holders, creating durable margin pools for incumbents with backward-integrated recycled sheet supply.
For Market Incumbents: Anticipate water-based liner qualification backlogs by expanding coating R&D partnerships with cosmetic multinationals in Germany and France. Defend position through captive recycled aluminum sheet production in the Great Lakes and Rhine-Ruhr corridors, insulating against scrap price volatility. Prioritize maintenance contracts for precision crimping equipment where German engineering expertise concentrates. For New Entrants and Emerging Players: The gap between premium matte-finish household positioning and economy steel-can industrial supply offers white-space entry points. Target mid-tier combination can configurations for Brazilian personal care contract manufacturers seeking flexible diameter conversion. Pursue coating-technology licensing partnerships rather than capital-intensive line builds. For Investors and Strategic Acquirers: The window for entry favors coating-technology licensors with established REACH qualification pipelines over commodity cylinder producers. Long-term viability rests on water-based chemistry platforms that unify corrosion protection and volatile organic compound compliance. Monitor EPA enforcement intensity for 40 CFR Part 59 as inflection signal for North American liner investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Liner Qualification | REACH-compliant coating investments secure long-term cosmetic multinational supply agreements. |
| Backward Integration into Recycled Sheet | Captive aluminum supply insulates converters from scrap price volatility in German and US markets. |
| High-Speed Conversion Line Expansion | Capacity additions in Brazil and Southeast Asia capture personal care SKU proliferation demand. |
| Printed Matte Finish Technology | Trivium Packaging's premium positioning opens margin pools beyond commodity cylinder production. |
| Subscription Refill Program Partnerships | Long-term manufacturing commitments displace spot purchasing in deodorant and dry shampoo categories. |
Study Parameters
Independent corroboration across plant managers at European conversion lines, procurement leads at Brazilian personal care brands, and coating-technology R&D directors underwrites the qualitative findings. Primary interviews with valve-mount equipment specialists and secondary validation through customs/trade data, SEC filings of publicly held converters, and ECHA substance restriction databases anchored the supply-side assessment. Bottom-up capacity tallies and top-down demand modeling triangulated volume estimates.
Comparable-period anchoring linked historical production data to forward projections across the analysis window. Segmentation dimensions modeled include material platform, end-use application, diameter format, and surface finish type. CAGRs derived from weighted average of demand trajectories in personal care SKU expansion, regulatory-driven coating transitions, and recyclability premium capture. Industry-specific inputs incorporated REACH compliance timelines and EPA enforcement intensity patterns.
Inputs from ECHA regulatory filings and Brazilian ANVISA approval databases were available through the study window; gaps in real-time coating qualification pipeline data introduce uncertainty bands around capacity expansion timelines. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and scrap aluminum price stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
India Metal Cans Market
Metal Packaging
Pressurized Metal Containers Market
Metal Packaging
Specialty Tin Cans Market
Metal Packaging
APAC Food Cans Market
Metal Packaging
Italy Metal Packaging Market
Metal Packaging
North America Metal Cans Market
Metal Packaging
Australia Metal Packaging Market
Metal Packaging
South Africa Metal Packaging Market
Metal Packaging
Germany Metal Packaging Market
Metal Packaging
Aluminum Cans Market
Metal Packaging
Metal Pails Market
Metal Packaging
Converter Aluminum Foil Market
Metal Packaging
Metal Drums Market
Metal Packaging
Metal Containers Market
Metal Packaging
Metal Cans Market
Metal Packaging
Aluminium Bottle Market