

Honeycomb Aluminum Foil Market Size, Share, and Industry Trends Forecast 2026-2036
Honeycomb Aluminum Foil Market Insights
Aerospace OEM demand is rebalancing the honeycomb aluminum foil market as commercial aviation programs scale lightweight structural components. Henan Mingtai Aluminum Industry anchors Chinese supply through integrated smelting-to-foil operations. Hexcel dominates North American aerospace-grade honeycomb core supply with proprietary bonding technologies. Plascore specializes in engineered cell geometries for satellite and defense platforms.
Honeycomb aluminum foil consists of thin-gauge aluminum sheet formed into hexagonal cell structures through adhesive bonding or brazing, typically ranging from 3.2 to 9.5 mm cell size and 18 to 72 kg per cubic meter density, serving as structural core material where strength-to-weight ratio determines performance. Aluminum alloy foils outperform pure aluminum in fatigue-critical aerospace applications, while coated variants capture margin pools in corrosive marine environments. Pre-cut panels represent the fastest-growing form segment as OEMs reduce on-site fabrication costs.
FAA airworthiness standards and EASA CS-25 certification requirements mandate flame resistance and smoke toxicity thresholds that shape product development cycles for aerospace suppliers. China's GB standards and MIIT industrial guidelines establish domestic technical baselines for automotive and electronics applications. Stakeholders must monitor evolving REACH substance restrictions and emerging battery thermal management standards that could redirect foil specification trends across European and Asian supply chains.
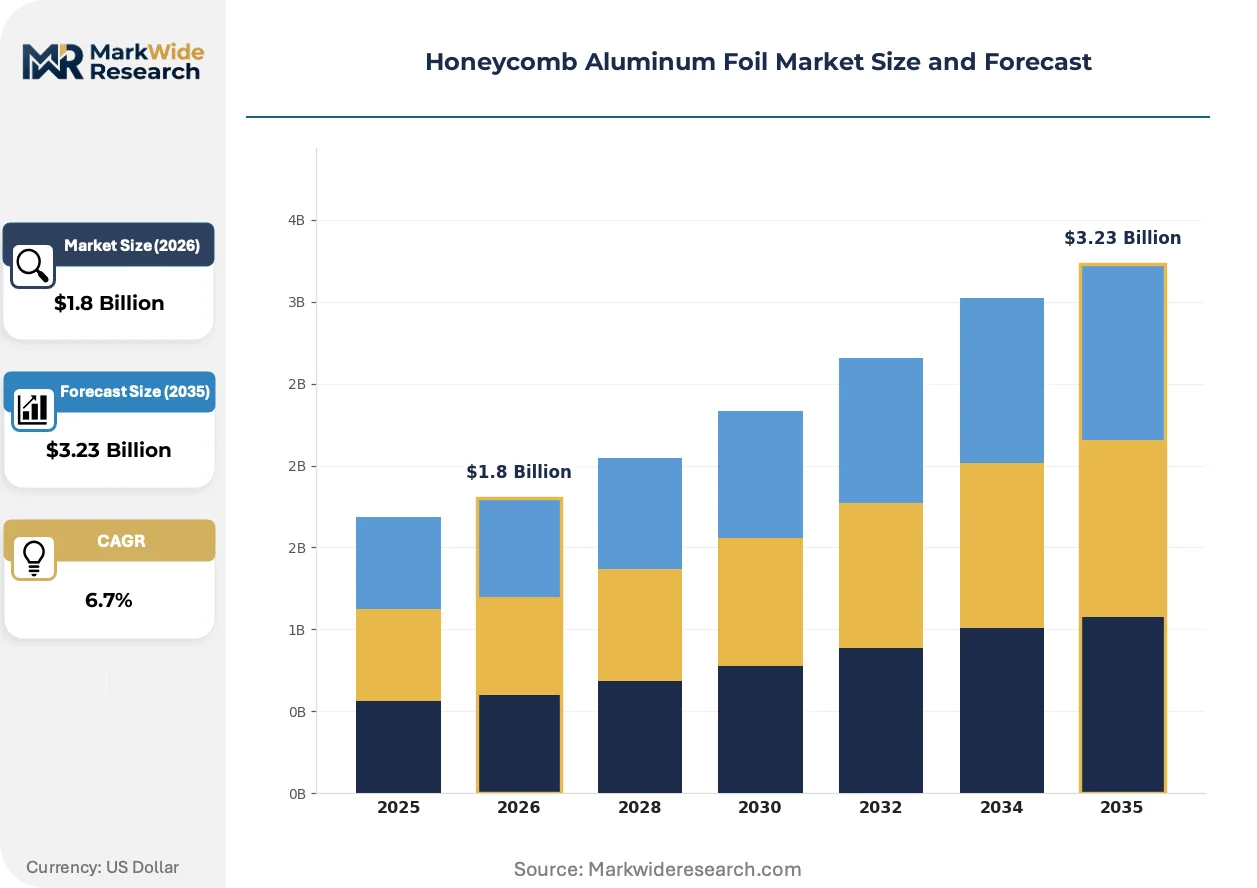
Market Dynamics
Aerospace OEMs are compressing supplier qualification cycles as next-generation aircraft programs demand lighter structural cores with certified flame resistance and fatigue performance. This pressure is reshaping how foil producers allocate R&D resources and manage certification pipelines.
Growth Catalysts
- EU Green Deal compliance:REACH substance restrictions are accelerating substitution of phenolic adhesives with water-based alternatives in European aerospace supply chains, creating specification windows for certified foil suppliers.
- Automotive lightweighting mandates:Battery enclosure thermal management requirements in electric vehicle platforms are pulling honeycomb aluminum foil into crash-resistant pack structures.
- Germany's industrial corridor concentration:Stuttgart-Munich-Hamburg aviation and automotive clusters generate dense demand for specialized cell geometries and pre-cut panel formats.
Market Restraints
- Primary aluminum price volatility:LME aluminum fluctuations compress margin pools for thin-gauge foil producers who cannot pass through input costs on long-term aerospace contracts.
- Chinese supply concentration:Integrated smelter-to-foil operations in Henan province control upstream ingot supply, creating dependency risk for non-integrated converters in other geographies.
- Brazing alloy substitution limits:3003-series aluminum honeycomb cores face technical barriers replacing nickel-based honeycomb in sustained-temperature engine nacelle applications above 150°C.
Strategic Opportunities
- India PLI scheme alignment:Production-linked incentives for advanced materials and aerospace components are drawing foil qualification programs toward Bengaluru and Hyderabad manufacturing zones.
- Satellite constellation buildouts:Low Earth orbit satellite platforms require ultra-lightweight panel cores with specific stiffness-to-mass ratios that aluminum honeycomb uniquely satisfies.
- Battery thermal runaway containment:Cell-to-pack architectures are specifying aluminum honeycomb as compression-resistant, thermally conductive interstitial material between lithium-ion cells.
Industry Challenges
- FAA-EASA dual certification timelines:Parallel airworthiness validation processes for flame resistance and smoke toxicity extend product launch cycles by 18-24 months for new foil grades.
- Adhesive formulation IP fragmentation:Proprietary bonding chemistries held by core manufacturers create licensing friction for foil suppliers seeking to qualify alternative adhesive systems.
- Skilled brazing technician scarcity:Controlled atmosphere brazing operations for aerospace-grade honeycomb require specialized welders whose training pipelines have not kept pace with demand recovery.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Honeycomb Aluminum Foil Market Trends and Innovations
Material science advances and certification-driven specification tightening are converging to redefine performance thresholds across aerospace, automotive, and energy storage applications. Three developments are restructuring competitive requirements.
Micro-cell aluminum honeycomb is expanding into satellite structural panels and drone airframes where gram-level weight reductions determine mission economics. SpaceX and OneWeb suppliers are specifying 3.2 mm cell sizes at sub-40 kg/m³ densities. This geometry is displacing traditional 6.4 mm configurations in payload-optimized platforms.
REACH substance restriction amendments are phasing out hexavalent chromium conversion coatings on aluminum foils by 2026, forcing suppliers to qualify trivalent chromium or zirconium-based pretreatments. Aerospace tier-1s in France and Germany are conducting accelerated corrosion testing on alternative surface treatments. EASA certification delays for new coating chemistries are compressing implementation timelines.
Consolidated procurement through designated material suppliers is replacing fragmented spot purchasing at major OEMs. Boeing and Airbus are directing tier-2 fabricators to approved foil sources with qualified bonding lines. This concentration is most visible in Hamburg and Toulouse assembly corridors where supply base reduction programs have eliminated secondary foil vendors from approved supplier lists.
Honeycomb Aluminum Foil Market Segmentation
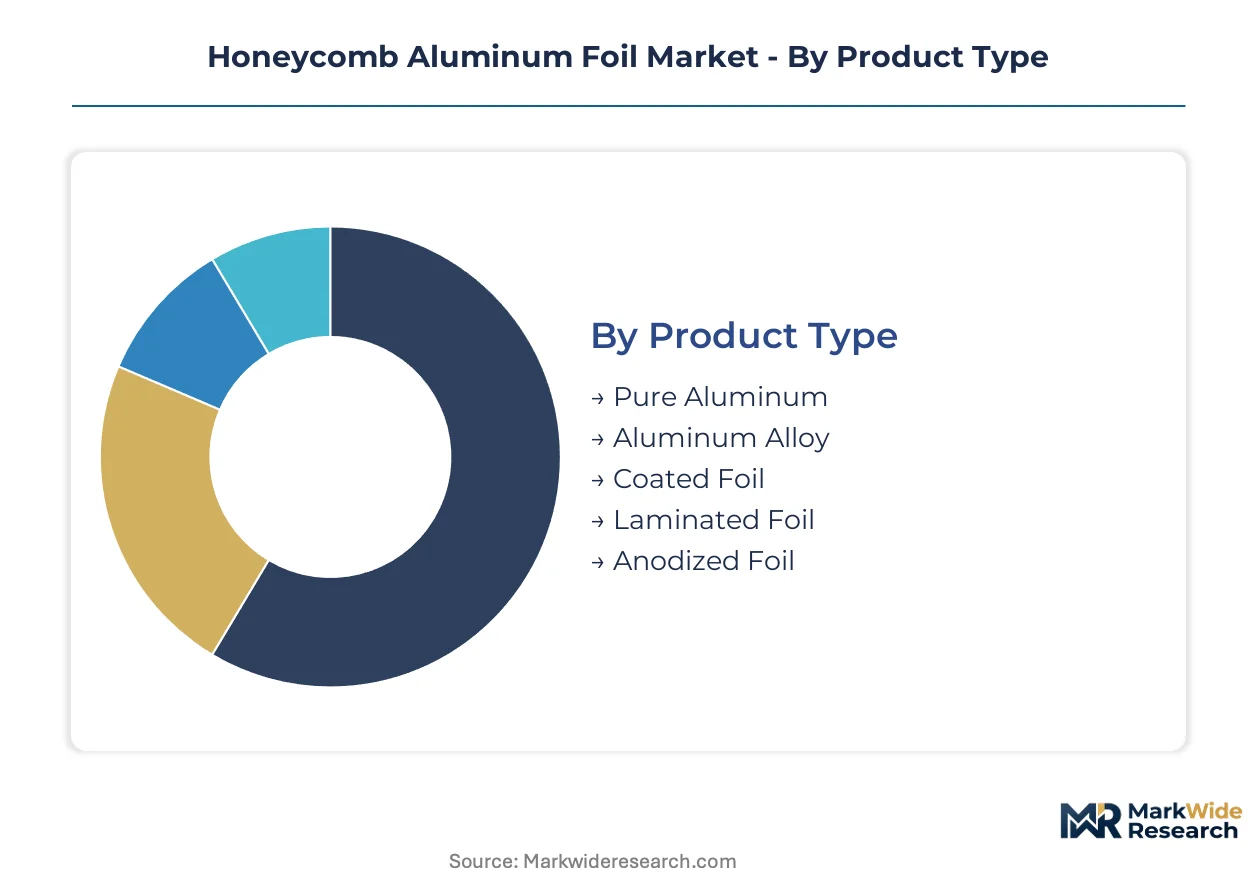
Honeycomb aluminum foil specifications diverge sharply across end-use contexts, with aerospace-grade alloys commanding premium certification overhead while packaging grades prioritize throughput economics. Understanding segment boundaries clarifies where technical differentiation commands pricing power versus where commodity dynamics dominate procurement decisions.
Product Type:
Standalone foil products serve discrete fabrication steps, whereas embedded variants integrate into bonded core assemblies requiring matched thermal expansion coefficients.
- Aluminum Alloy:3003 and 5052 series alloys deliver superior fatigue resistance and specific strength for aerospace load-bearing structures. Boeing 787 and Airbus A350 programs specify alloy foils for wing box and floor panel cores where cyclic loading exceeds pure aluminum endurance limits.
- Coated Foil:Phenolic resin or epoxy coatings provide corrosion barriers and adhesive bonding surfaces for marine and humid environment applications. Offshore platform suppliers in Norway and Brazil specify coated variants for helipad and accommodation module structures exposed to salt spray cycles.
- Pure Aluminum:1100 and 1145 grades offer maximum formability for non-structural packaging and thermal insulation uses where strength requirements remain minimal.
- Laminated Foil:Polymer-film laminates create moisture barriers for electronics packaging and sensitive equipment enclosures in semiconductor fabrication facilities.
- Anodized Foil:Electrochemical surface hardening produces wear-resistant layers for architectural panel applications requiring decorative finishes alongside structural core functions.
Aluminum alloy leads volumes today; coated foil is gaining share fastest.
Application:
Cost tier stratification separates specification-driven aerospace and automotive segments from price-sensitive packaging and construction uses.
- Automotive Insulation:Battery thermal management systems in electric vehicle platforms specify aluminum honeycomb as compression-resistant, thermally conductive interstitial material. Tesla Gigafactory suppliers and BYD qualification programs are pulling foil into cell-to-pack architectures requiring flame-resistant core structures.
- Electronics Shielding:5G infrastructure and satellite ground stations demand EMI-attenuating honeycomb panels with precise cell geometries. Ericsson and Nokia suppliers in Finland and Sweden specify tight-tolerance foils for base station enclosures.
- Heat Exchangers:Brazed aluminum honeycomb cores enable compact HVAC and industrial cooling systems where surface area density determines thermal performance.
- Packaging:Protective dunnage and display structures utilize low-density honeycomb for cushioning and rigidity in consumer goods logistics.
- Soundproofing:Acoustic core layers in rail and marine interiors absorb vibration energy through tuned cell resonance characteristics.
Automotive insulation commands the steepest price premiums; electronics shielding shows the sharpest volume acceleration.
End User:
Customer type determines qualification burden, with aerospace OEMs imposing 18-24 month certification cycles that lock out speculative suppliers.
- Aerospace OEMs:Airbus, Boeing, and COMAC mandate FAA-EASA dual certification for structural core materials. Tier-1 fabricators in Hamburg, Toulouse, and Xian face consolidated procurement directives limiting approved foil sources to pre-qualified bonding lines.
- Consumer Electronics Manufacturers:Apple and Samsung suppliers specify ultra-thin foils for laptop chassis and tablet enclosures where stiffness-to-weight ratios determine product ergonomics.
- Packaging Companies:Industrial converters in Germany's Ruhr region and China's Pearl River Delta purchase commodity-grade foils on spot pricing with minimal technical qualification.
- Construction Firms:Curtain wall and cladding contractors specify fire-rated honeycomb cores for high-rise facade systems subject to local building codes.
- Electrical Equipment Makers:Transformer and switchgear manufacturers utilize foil laminates for insulation and thermal management in power distribution hardware.
Aerospace OEMs dominate value capture; consumer electronics manufacturers are expanding procurement fastest.
Form:
Supply chain maturity separates standardized roll and sheet formats from engineered pre-cut and custom configurations requiring fabrication integration.
- Pre-Cut Panels:CNC-routed and adhesive-bonded panels arrive ready for assembly, eliminating on-site fabrication labor for tier-2 aerospace fabricators. Airbus Hamburg and Boeing Charleston facilities specify dimensionally certified panels to reduce production line variability.
- Rolls:Continuous coil formats serve high-volume packaging and insulation converters with automated slitting and forming equipment.
- Sheets:Flat stock formats bridge fabrication flexibility and handling efficiency for medium-volume industrial applications.
- Customized Shapes:Engineered contours match specific airframe or automotive panel geometries, requiring direct collaboration between foil mills and OEM engineering teams.
- Blanks:Rough-cut intermediate forms allow downstream processors to finalize dimensions for specialized thermal or acoustic applications.
Rolls maintain the broadest installed base; pre-cut panels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting honeycomb aluminum foil production toward jurisdictions with streamlined certification pathways and lower compliance overhead. Manufacturers are relocating bonding and finishing operations to exploit gaps between FAA-EASA dual-certification requirements and emerging-market technical standards.
United States
Aerospace OEM procurement consolidation drives demand concentration in Washington State and South Carolina assembly corridors. FAA airworthiness standards for flame resistance and smoke toxicity shape qualification timelines for structural core suppliers. Boeing Charleston and Everett facilities direct tier-2 fabricators toward pre-qualified foil sources with certified bonding lines.
Germany
EU Green Deal REACH compliance mandates accelerate substitution of phenolic adhesives with water-based alternatives across Stuttgart-Munich-Hamburg industrial clusters. EASA CS-25 certification requirements enforce strict material traceability for aerospace applications. Airbus Hamburg assembly operations specify dimensionally certified pre-cut panels to reduce production variability.
China
Integrated smelter-to-foil operations in Henan province control upstream ingot supply for domestic automotive and electronics applications. MIIT industrial guidelines and GB standards establish technical baselines for battery thermal management and lightweight vehicle structures. Zhengzhou and Luoyang manufacturing zones concentrate capacity for alloy foil production serving COMAC qualification programs.
India
Production-linked incentive schemes for advanced materials draw foil qualification programs toward Bengaluru and Hyderabad aerospace manufacturing zones. BIS standards and CDSCO technical requirements shape domestic certification pathways for structural core applications. Domestic OEMs are accelerating supplier development to reduce import dependency for satellite and defense platform materials.
France
EASA regulatory leadership positions Toulouse and Nantes as certification gatekeepers for European aerospace supply chains. ANSM and ECHA substance restriction enforcement drives accelerated corrosion testing on trivalent chromium surface treatments. Airbus Toulouse assembly corridors have eliminated secondary foil vendors through supply base reduction programs.
Honeycomb Aluminum Foil Market Competitive Landscape
Consolidated procurement through designated material suppliers dominates the current landscape as major OEMs compress approved vendor lists. The vendor base stratifies between integrated primary producers with captive smelting capacity and specialized converters focused on bonding and finishing operations. Three archetypes occupy distinct competitive positions: upstream-integrated aluminum mills, aerospace-certified core fabricators, and regional packaging-grade converters. Capacity expansion and strategic partnerships represent the primary competitive moves, with producers securing long-term alloy supply agreements and qualifying alternative adhesive systems to meet evolving REACH requirements.
Among upstream-integrated producers, Henan Mingtai Aluminum Industry and GuiZhou Chalco Aluminum exemplify the smelter-to-foil archetype with captive control over primary metal supply. Hexcel occupies a position within the aerospace-certified tier, representing the bonding-technology specialization required for structural core applications. These three companies anchor the competitive structure across distinct value chain segments, with geography and integration level determining relative positioning in procurement hierarchies.
| Leading Market Players |
|---|
| Ulbrich |
| Italcoat |
| Henan Mingtai Aluminum Industry |
| Yong Jie New Material |
| GuiZhou Chalco Aluminum |
| Jiangsu Dingsheng New Energy Materials |
| Hexcel |
| The Gill Corporation |
| Plascore |
| Others |
Pricing and Supply Chain Analysis
Aerospace OEM tier-1 fabricators concentrate procurement authority through consolidated approved vendor lists, driving a contract-based long-term offtake pricing model that rewards certified bonding lines with multi-year volume commitments. This buyer concentration shifts pricing power toward suppliers holding FAA-EASA dual certification, while spot-market converters face margin compression from LME aluminum volatility they cannot pass through.
Pricing Analysis
Distributor margins for aerospace-grade honeycomb core materials typically run 12-18 percent before tier-1 fabricator markups, with direct-to-OEM contracts commanding 8-12 percent discounts for qualified bonding lines. Pricing stratifies across aerospace-certified, automotive-qualified, and packaging-grade tiers, with certification level and alloy specification driving differentiation. Cost compression in commodity-grade foils is intensifying because Chinese smelter-to-foil operations flood export markets with surplus 1100-series capacity. Packaging converters in Germany's Ruhr region exhibit highest price sensitivity, while Airbus and Boeing procurement offices prioritize supply assurance over unit cost.
Supply Chain Analysis
Scrap aluminum recovery and core remanufacturing flows remain underdeveloped, with most end-of-life aerospace panels landfilled rather than refined back to ingot grade. Primary supply concentrates in China, Germany, and the United States, with Henan province ingot production feeding both domestic foil mills and export converters. Raw material flows draw from bauxite refining in Guinea and Australia, smelter-grade alumina from Brazil and Jamaica, and rolling slab from Russian and Canadian primary producers. Single-source vulnerability persists for aerospace-grade 3003 and 5052 alloy sheet, with qualified mill sources limited to three integrated producers globally. Distribution runs through designated material suppliers under Boeing and Airbus supply base reduction programs, bypassing traditional distributor networks for structural core applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EU REACH substance restriction amendments phasing out hexavalent chromium coatings by 2026 and redirecting specification demand toward qualified alternative surface treatments.
For Market Incumbents: Lock in long-term alloy supply agreements with Henan and Chalco smelter complexes before export quota tightening. Expand controlled atmosphere brazing capacity in Hamburg and Toulouse assembly corridors to capture tier-1 fabricator consolidation. Carbon fiber honeycomb substitution in satellite platforms threatens aluminum core share in stiffness-critical applications; defend by qualifying micro-cell geometries below 40 kg/m³ density for LEO constellation suppliers. For New Entrants and Emerging Players: Enter via battery thermal management qualification programs at Tesla Gigafactory and BYD cell-to-pack architectures, where automotive insulation specifications remain less consolidated than aerospace. India's PLI scheme for advanced materials offers the most penetrable geographic window, with Bengaluru aerospace clusters seeking domestic foil sources to reduce import dependency. Pursue joint development agreements with satellite platform integrators specifying ultra-lightweight panel cores, bypassing entrenched aerospace certification barriers. For Investors and Strategic Acquirers: Aerospace tier-1 fabricators are the most active acquirer in this space, seeking captive foil supply to secure bonding line capacity under consolidated procurement directives. Five-to-ten year viability hinges on REACH-compliant coating chemistry transitions and battery enclosure thermal management penetration. Monitor EASA certification timelines for trivalent chromium and zirconium-based pretreatments as inflection indicator for incumbent repositioning windows.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Coating Qualification | EASA certification of trivalent chromium pretreatments determines supplier eligibility for Airbus Hamburg and Toulouse assembly corridors. |
| Micro-Cell Geometry Scale-Up | SpaceX and OneWeb suppliers specify 3.2 mm cell sizes that displace traditional configurations in payload-optimized satellite platforms. |
| India PLI Alignment | Bengaluru and Hyderabad manufacturing zones draw foil qualification programs through production-linked incentives for aerospace components. |
| Battery Thermal Management Integration | Tesla Gigafactory and BYD cell-to-pack architectures specify aluminum honeycomb as compression-resistant interstitial material. |
| Long-Term Alloy Supply Agreement | Henan Mingtai and Chalco captive smelting operations control upstream ingot supply for non-integrated converters globally. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's aerospace procurement clusters and automotive manufacturing corridors. The approach combines structured interviews with tier-1 fabricator procurement directors, core manufacturer bonding line engineers, and aluminum mill technical sales leads, validated against secondary sources including FAA airworthiness directives, EASA CS-25 certification databases, EU REACH substance restriction amendments, and MIIT industrial guidelines. Customs data from Germany's Federal Statistical Office and China's General Administration of Customs anchor trade flow analysis. Bottom-up segment sizing triangulates against top-down OEM procurement disclosure patterns.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models honeycomb aluminum foil demand across alloy grade, end-use application, and customer type dimensions, with additional segmentation by cell geometry specification for satellite and aerospace applications. CAGRs derive from regression analysis against airframe production schedules, electric vehicle platform ramp rates, and LEO constellation deployment timelines. Industry-specific forecast inputs include COMAC C919 delivery trajectories and EU Green Deal implementation pacing for adhesive formulation substitution.
The model holds under stable LME aluminum pricing and current REACH enforcement timelines; deviation in alloy surcharges or accelerated hexavalent chromium phase-out would shift supplier margin structures. Forecasts reflect documented assumptions regarding OEM procurement consolidation and satellite platform material specifications. Practitioners should monitor EASA certification delays for alternative coating chemistries and India PLI scheme disbursement pacing for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.