
 Solvent-Based Inks Market | 2026-2036
Solvent-Based Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Solvent-Based Inks Market Outlook
Subscription-based color management and predictive maintenance software is pivoting how solvent ink vendors monetize their customer relationships beyond gallon shipments. Sun Chemical Corporation leverages its global pigment supply chain to sustain pricing power across gravure and flexographic accounts. Siegwerk Druckfarben AG anchors its position through specialized food-compliant formulations that navigate Europe's evolving safety standards.
Solvent-based inks comprise pigment or dye dispersions dissolved in volatile organic carrier systems, typically formulated with ketones, esters, or alcohols to achieve rapid drying and strong substrate adhesion on non-porous films. These formulations serve high-speed rotary printing processes where water-based alternatives fail to bond with polypropylene, polyethylene, or metallized surfaces. Gravure inks retain the largest volume share among product types due to their dominance in long-run flexible packaging for snack foods and confectionery. UV-curable technology within the technology segment is expanding fastest as converters seek to reduce solvent emissions without sacrificing print speed or abrasion resistance. Digital solvent inks remain a niche margin pool, concentrated in wide-format outdoor graphics and industrial decoration where short runs justify higher unit costs.
The EPA enforces VOC emission thresholds under the National Emission Standards for Hazardous Air Pollutants, forcing U.S. converters to install recovery systems or switch to compliant formulations. ECHA administers REACH restrictions on specific solvent chemistries, reshaping formulation choices for European suppliers and their export customers. China's MEE has tightened environmental inspections of printing clusters in Zhejiang and Guangdong provinces, accelerating domestic demand for lower-emission hybrid systems. Stakeholders must monitor regulatory divergence across these three jurisdictions to anticipate where formulation investment will yield durable market access.
Market Dynamics
REACH compliance deadlines and EPA volatile organic compound thresholds are forcing formulation chemistry changes across solvent ink supply chains, compressing margins for converters while opening premium tiers for compliant hybrid systems.
Growth Catalysts
- Export-oriented flexible packaging:Southeast Asian converters are scaling gravure capacity to serve cross-border snack food and confectionery brands, pulling solvent ink volumes into Vietnam and Thailand production clusters.
- Food-contact safety standards:ECHA migration limits on aromatic amines are compelling European brand owners to specify low-migration solvent formulations, creating specification premiums for compliant suppliers.
- Hybrid UV-solvent systems:These intermediate technologies bridge drying speed and emission reduction, allowing Chinese converters in Zhejiang province to maintain throughput under tightening MEE inspection protocols.
Market Restraints
- Ketone feedstock volatility:Methyl ethyl ketone and methyl isobutyl ketone prices track crude oil and acetone markets, exposing ink manufacturers to margin compression without pass-through pricing power.
- East Asian pigment concentration:Azo and phthalocyanine pigment synthesis clusters in eastern China create single-source dependency risks for European and North American formulators.
- Water-based substitution in porous substrates:Corrugated and paper packaging converters are migrating to water-based flexo for non-barrier applications, eroding addressable volume in commodity segments.
Strategic Opportunities
- India domestic label production:Foreign packaging investment relocating from China is building converting capacity in Gujarat and Maharashtra, creating localized solvent ink demand without import duty exposure.
- Digital solvent wide-format:Industrial decoration and outdoor graphics segments tolerate higher unit costs for short-run customization, opening margin pools outside commoditized flexible packaging.
- EU Green Deal chemical sustainability criteria:Biobased solvent content thresholds are creating specification pathways for renewable-derived ester formulations in premium European brand owner contracts.
Industry Challenges
- Colorimetric formulation expertise:Gravure and flexographic press operators with deep solvent ink viscosity and transfer control knowledge are retiring faster than vocational programs replace them.
- Legacy recovery system integration:Converters with existing solvent distillation infrastructure face capex burdens to retrofit for lower-VOC hybrid chemistries without full equipment replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solvent-Based Inks Market |
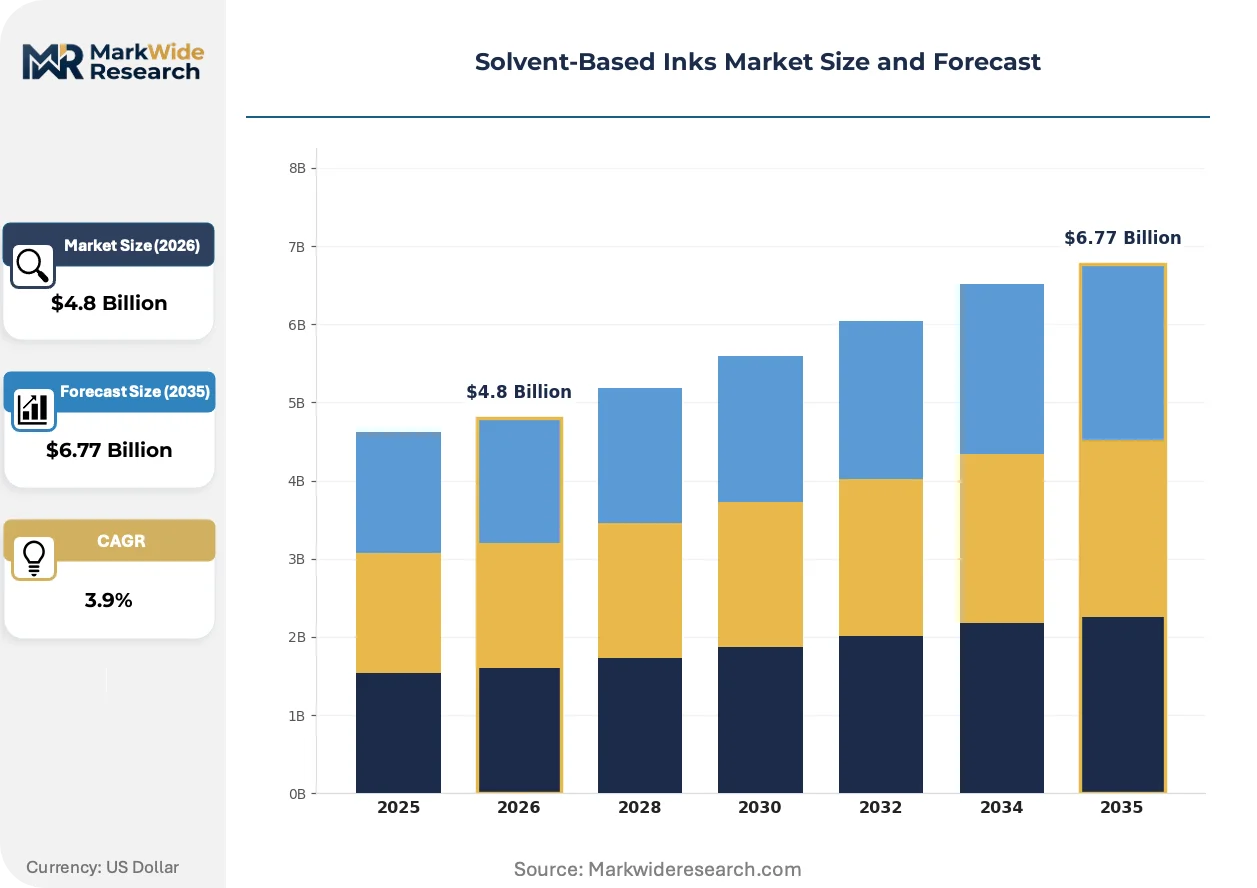
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.77 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexographic, Gravure, Screen, Digital End User: Packaging, Publishing, Textiles, Labels Technology: Conventional, UV-Curable, Aqueous, Hybrid Application: Food Packaging, Automotive, Electronics, Others |
| Companies Covered | Sun Chemical Corporation, Flint Group, Siegwerk Druckfarben AG & Co. KGaA, Toyo Ink SC Holdings Co. Ltd., Sakata INX Corporation, Tokyo Printing Ink Mfg. Co. Ltd., Dainichiseika Color & Chemicals Mfg. Co. Ltd., Huber Group, SICPA Holding SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solvent-Based Inks Market Strategic Shifts
Formulation chemistry and regulatory compliance architectures are converging to redefine competitive advantage, with technology vendors monetizing through service attachments rather than gallon shipments alone.
Hybrid UV-solvent curing technology is integrating nitrogen-inerted drying chambers with reduced solvent loads to achieve Class A surface finishes on metallized films. Flexible packaging converters in Germany and Italy are piloting these systems to maintain gravure throughput while satisfying TA Luft emission limits. This convergence is integrating equipment and chemistry suppliers into joint performance contracts that bundle ink supply with guaranteed emission compliance.
REACH Annex XVII restrictions on N-methyl-2-pyrrolidone and other reprotoxic solvents are forcing systematic reformulation of lamination adhesives and associated ink systems. European ink manufacturers are submitting updated safety data sheets and exposure scenarios to ECHA ahead of 2025 sunset dates. Flexible packaging specifications for European retail brands are tightening fastest, with technical teams rejecting legacy formulations that lack complete substance volume tracking.
Converters are consolidating supplier relationships around vendors offering predictive color management platforms and remote press-side support. Brand owner quality audits now prioritize digital proofing accuracy and batch-to-batch consistency over unit pricing alone. This consolidation is most visible in North American gravure operations serving multinational snack food accounts, where single-source ink partnerships reduce qualification overhead and simplify regulatory documentation.
Solvent-Based Inks Market Segmentation
Solvent-based ink purchasing decisions hinge on drying speed requirements, substrate compatibility, and emission compliance costs. Each segmentation dimension reveals distinct margin structures and supplier concentration patterns that reshape competitive positioning.
Product Type:
Gravure and flexographic systems operate as standalone converting investments with dedicated ink supply chains, while screen and digital formats embed solvent chemistry into broader equipment ecosystems.
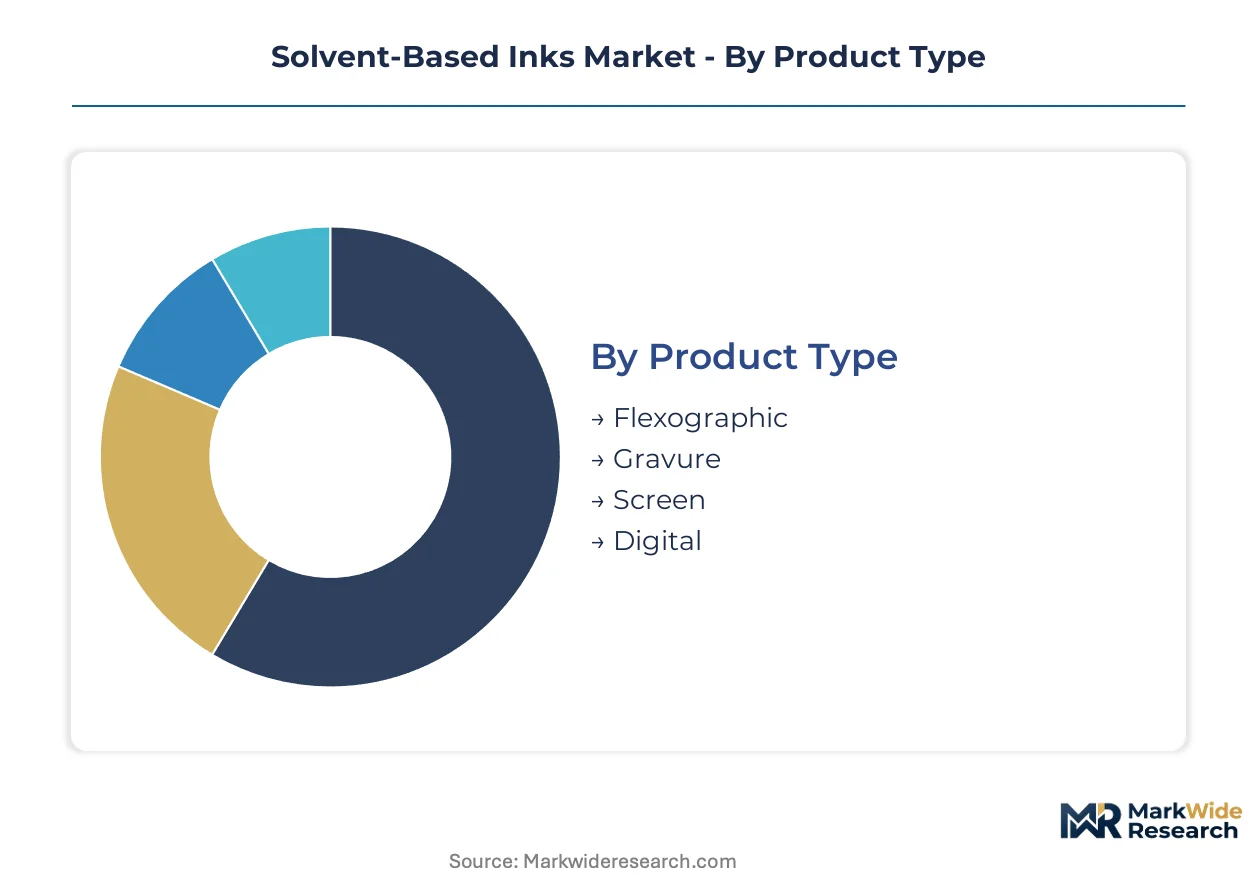
- Gravure:These formulations rely on toluene and ketone carriers to achieve deep cell wetting and rapid solvent release on high-speed rotary presses. Long-run flexible packaging for snack foods in Vietnam and Thailand pulls the heaviest volumes, though ECHA migration limits on aromatic amines are forcing reformulation investments.
- Flexographic:Lower-viscosity solvent systems bond with elastomeric photopolymer plates to print on corrugated pre-print and film substrates. Indian label converters in Gujarat are scaling flexo capacity to serve domestic pharmaceutical and food accounts without import duty exposure.
- Screen:Thixotropic solvent pastes deposit through mesh stencils for industrial decoration and membrane switch applications.
- Digital:Piezoelectric drop-on-demand systems use low-volatility solvent carriers for wide-format outdoor graphics where short runs justify premium unit economics.
Volume placements concentrate in Gravure; the faster expansion belongs to Digital.
End User:
Cost tier stratification separates barrier-grade packaging specifications from commodity publishing and textile applications.
- Packaging:Flexible film converters serving multinational snack brands demand low-migration solvent formulations with complete substance volume tracking for ECHA compliance. Southeast Asian export clusters in Vietnam and Thailand anchor procurement scale.
- Labels:Pressure-sensitive and shrink-sleeve applications in India and Mexico tolerate higher ink costs for shorter runs and faster changeovers.
- Publishing:Magazine and catalog printers compete with water-based alternatives on porous paper stocks.
- Textiles:Sublimation transfer printing on polyester fabrics uses solvent-based disperse dyes for sportswear and soft signage.
Margin capture peaks in Packaging; Labels are climbing the fastest.
Technology:
Application maturity separates entrenched conventional chemistries from emerging hybrid and UV-curable platforms.
- Conventional:High-solvent formulations with ketone and ester carriers retain dominance in legacy gravure infrastructure where recovery systems amortize emission costs.
- UV-Curable:Photoinitiator-acrylate systems eliminate solvent carriers entirely, satisfying MEE inspection protocols in Zhejiang province while maintaining print speed.
- Aqueous:Water-based alternatives with co-solvent boosters penetrate corrugated and paper packaging where porosity permits slower drying.
- Hybrid:Reduced-solvent formulations with nitrogen-inerted UV curing bridge emission compliance and metallized film adhesion in German and Italian pilot installations.
Installed base concentrates in Conventional; Hybrid systems are gaining share fastest.
Application:
Customer type differentiation separates food-contact safety specifications from industrial durability requirements.
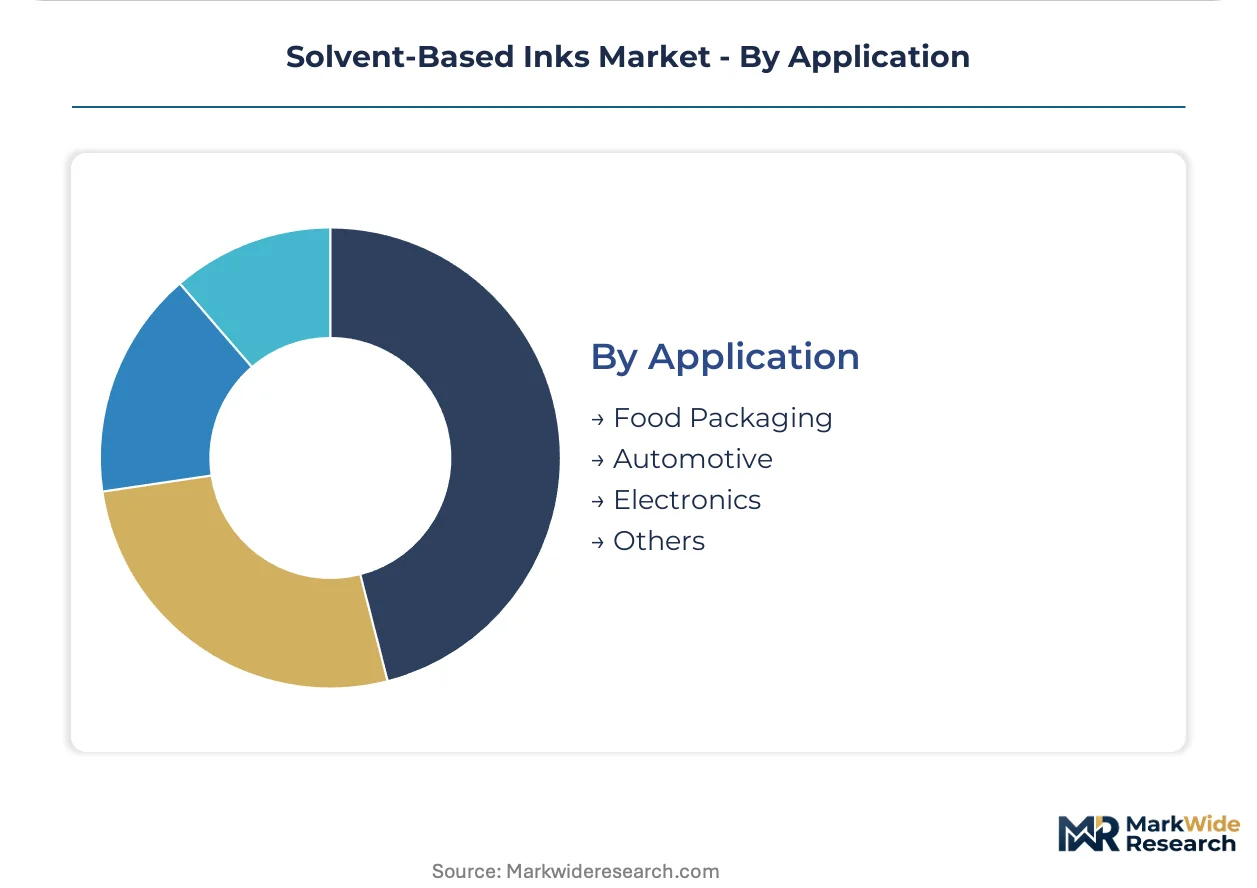
- Food Packaging:Laminated film structures for confectionery and savory snacks demand solvent inks with documented low-migration profiles under EFSA and FDA food-contact frameworks.
- Automotive:Dashboard overlays and membrane switches require abrasion-resistant solvent prints with extended outdoor durability.
- Electronics:Printed circuit board legends and touch panel decorations use precision solvent deposition on non-porous substrates.
- Others:Industrial decoration, outdoor signage, and specialty graphics complete the application map.
Procurement scale concentrates in Food Packaging; Electronics represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in East Asia while consumption pulls strongest from Southeast Asian export zones and European compliance-driven markets. This geographic split shapes formulation standards and supply chain investments across solvent ink procurement networks.
China
MEE environmental inspections in Zhejiang and Guangdong provinces are accelerating converter migration toward hybrid UV-solvent systems. The dual carbon goals framework pressures printing clusters to reduce VOC emissions without sacrificing metallized film throughput. Hangzhou and Dongguan industrial zones host the densest concentrations of gravure capacity serving domestic snack packaging demand.
Vietnam
Foreign flexible packaging investment relocating from China is building solvent ink demand in Binh Duong and Long An provinces. The country's export-oriented food processing sector requires low-migration formulations compliant with EU retail brand specifications. Ho Chi Minh City periphery clusters anchor the fastest capacity expansion in Southeast Asia.
Germany
TA Luft emission limits and REACH Annex XVII substance restrictions are forcing systematic reformulation of lamination ink systems. The EU Green Deal chemical sustainability criteria create specification pathways for biobased ester formulations in premium brand contracts. Bavarian and Baden-Württemberg converting corridors pilot nitrogen-inerted hybrid curing systems.
India
Gujarat and Maharashtra states are absorbing foreign packaging investment with localized solvent ink procurement avoiding import duty exposure. FSSAI food-contact safety standards are tightening label specifications for domestic pharmaceutical and food accounts. Ahmedabad-Mumbai industrial corridor clusters represent the steepest domestic demand trajectory.
United States
EPA National Emission Standards for Hazardous Air Pollutants enforce VOC thresholds requiring recovery system investments or compliant formulation switches. FDA food-contact frameworks govern migration limits for flexible packaging serving multinational snack brands. Midwest and Southeast converting belts maintain the largest installed gravure base.
Solvent-Based Inks Market Competitive Environment
Top-tier vendors anchor pigment-to-ink vertical integration, while mid-tier specialists compete on regional formulation agility and food-contact certification speed. The market structure consolidates around chemical conglomerates with captive raw material positions, with regional independents defending niche specifications. Three archetypes dominate: integrated pigment-ink manufacturers, formulation specialists with regulatory documentation depth, and equipment-chemistry bundlers. Competitive moves concentrate on backward integration into pigment synthesis and joint performance contracts tying ink supply to emission compliance guarantees.
Within the integrated chemical tier, Sun Chemical Corporation and Toyo Ink SC Holdings Co. Ltd. exemplify pigment-to-distribution control spanning multiple continents. Siegwerk Druckfarben AG occupies a position anchored to European food-contact safety documentation and REACH compliance architecture. These three represent distinct strategic postures: North American pigment dominance, Japanese diversified chemical integration, and European regulatory-specialist positioning.
| Leading Market Players |
|---|
| Sun Chemical Corporation |
| Flint Group |
| Siegwerk Druckfarben AG & Co. KGaA |
| Toyo Ink SC Holdings Co. Ltd. |
| Sakata INX Corporation |
| Tokyo Printing Ink Mfg. Co. Ltd. |
| Dainichiseika Color & Chemicals Mfg. Co. Ltd. |
| Huber Group |
| SICPA Holding SA |
| Others |
Value Chain & Pricing Dynamics
Hybrid UV-solvent curing adoption in German and Italian flexible packaging clusters simultaneously compresses formulation costs and concentrates procurement leverage among equipment-chemistry bundlers. This technology transition forces converters to abandon legacy solvent recovery amortization models while ink vendors capture pricing power through joint performance contracts.
Pricing Analysis
Cost-down pressure on gravure formulations accelerates because REACH Annex XVII sunset dates force systematic reformulation of lamination ink systems. Three-tier pricing structure across premium, standard, and economy levels separates ECHA-compliant low-migration formulations from commodity snack packaging grades and basic corrugated pre-print specifications. Price differentiation rests on certification depth and captive pigment supply positions. Water-based substitution in porous substrates renders corrugated converters most price-sensitive, while food-contact barrier film buyers absorb premiums for complete substance volume tracking.
Supply Chain Analysis
Dual-sourcing mandates from multinational snack brands compel ink vendors to qualify secondary pigment suppliers beyond eastern China azo and phthalocyanine synthesis clusters. Raw material dependencies center on methyl ethyl ketone, methyl isobutyl ketone, and specialty ester carriers. Geographic supply concentration in China, India, and Germany creates tariff exposure as EU carbon border adjustments reshape import economics. Distribution runs through regional blending facilities serving converting clusters in Vietnam, Thailand, and the US Midwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pigment synthesis capacity bottlenecks in East Asia prop pricing power for backward-integrated ink manufacturers, insulating compliant suppliers from ketone feedstock volatility.
For Market Incumbents: Cement pigment-to-ink vertical control through captive synthesis investments in Gujarat and Maharashtra industrial corridors. Defend formulation margins by accelerating REACH-compliant safety data sheet documentation ahead of European brand owner qualification cycles. Prioritize nitrogen-inerted hybrid curing partnerships with German equipment OEMs to lock in emission-guaranteed performance contracts.
For New Entrants and Emerging Players: Capture digital solvent wide-format margins in industrial decoration segments where short-run customization tolerates premium unit economics. Penetrate India domestic label production clusters building capacity in Ahmedabad-Mumbai corridors without import duty exposure. Lead with predictive color management software attachments rather than gallon-based transactional pricing.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-tier European formulation specialists with deep ECHA regulatory documentation archives. Five-to-ten year viability favors suppliers with biobased ester formulation pipelines aligned to EU Green Deal chemical sustainability criteria. Monitor MEE inspection protocol tightening in Zhejiang province as inflection signal for hybrid technology adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Synthesis | Captive azo and phthalocyanine supply insulates Sun Chemical and Toyo Ink from East Asian concentration risk. |
| Hybrid UV-Solvent System Deployment | Nitrogen-inerted curing pilots in Bavaria satisfy TA Luft limits while preserving metallized film throughput. |
| Predictive Color Management Platform Launch | Subscription software attachments pivot Siegwerk monetization beyond gallon shipments toward recurring revenue. |
| Biobased Ester Formulation Investment | Renewable-derived carriers unlock EU Green Deal premium specifications for European retail brand contracts. |
| Joint Performance Contract Structuring | Emission compliance guarantees bundled with ink supply consolidate converter relationships in North American gravure. |
Study Parameters
Multi-period observation of gravure capacity buildouts, REACH compliance submission timelines, and ketone feedstock price movements anchored the trend analysis, supplemented by interviews with flexible packaging plant managers, ink procurement leads at multinational snack brands, ECHA regulatory affairs specialists, and gravure press operators. Secondary validation drew from customs trade data, SEC 10-K filings of listed chemical conglomerates, and European Chemicals Agency restriction proposal documentation. Bottom-up volume modeling triangulated against top-down segment-weighted value projections.
Segment-weighting across product type, end user, technology, and application dimensions structured the analytical framework over the projection horizon. Gravure, flexographic, screen, and digital formats received distinct growth assumptions based on substrate compatibility constraints and emission compliance cost trajectories. CAGRs derived from elasticity-adjusted volume projections responding to regulatory threshold changes and converter capacity investment patterns.
The model holds under stable REACH enforcement timelines and MEE inspection intensity; deviation in EPA NESHAP threshold revisions or EU carbon border adjustment implementation would shift formulation economics and regional procurement patterns. A model refresh is warranted upon material change in biobased solvent cost parity or hybrid curing equipment penetration rates in Southeast Asian export clusters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Brazil Commercial Printing Market
Printing Inks
Screen Printing Mesh Market
Printing Inks
United States Printing Inks Market
Printing Inks
Functional Printing Market
Printing Inks
Plant Oil Based Printing Inks Market
Printing Inks
UV Cured Inks Market
Printing Inks
Rotogravure Printing Inks Market
Printing Inks
Radiation Curable Inks Market
Printing Inks
Global Gravure Printing Inks Market
Printing Inks
Global Light Changing Packaging Inks Market
Printing Inks
Non-Conductive Ink Market
Printing Inks
Textile Printing Ink Market
Printing Inks
Food Marking Inks Market
Printing Inks
Global UV (Ultraviolet) Curable Inks Market
Printing Inks
North America Ink Market
Printing Inks
Global Flexographic Inks Market