
 Printing Inks Market | 2026-2036
Printing Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Printing Inks Market Intelligence
The European Union's Corporate Sustainability Reporting Directive (CSRD) is shifting the cost-of-entry calculus by mandating extensive supply chain disclosures for ink manufacturers. Global leaders like Sun Chemical leverage their scale to absorb these compliance costs and invest in sustainable chemistries. In contrast, Siegwerk specializes in formulations for packaging applications, aligning its portfolio with circular economy principles. DIC Corporation sustains a strong position in Asia through extensive regional production networks.
Printing inks are complex formulations comprising pigments for color, binders to affix the colorant to a substrate, and a solvent or carrier vehicle to ensure flow. Their primary purpose is to transfer images, text, or designs onto diverse materials including paper, plastics, and textiles in commercial and industrial processes. Within ink types, UV-curable inks are gaining significant traction due to rapid drying times and low VOC emissions. The packaging application segment dominates demand, while digital printing technology is gaining share from traditional methods like flexographic and gravure printing.
Market access is governed by chemical safety regulations enforced by bodies such as the US Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA). These agencies set strict limits on heavy metals and volatile organic compounds (VOCs), directly influencing formulation choices and product development pipelines. Future profitability depends on navigating the divergent regulatory landscapes for food-contact materials and developing cost-effective, bio-derived ink solutions.
Market Dynamics
Stringent environmental regulations are the central structural force compelling a fundamental reformulation of printing inks. Mandates from bodies like the European Chemicals Agency and the US EPA are accelerating the displacement of solvent-based inks with sustainable alternatives.
Growth Catalysts
- Flexible Packaging Expansion:Surging food and beverage demand for flexible packaging drives consumption of compliant, high-performance inks.
- EU Green Deal Initiatives:Policies promoting circular economies create a premium market for recyclable or bio-based inks, aligning with CSRD disclosure goals.
- Digital Printing Adoption:The shift to digital for short-run jobs and personalization creates new demand for specialized inkjet formulations.
Market Restraints
- Pigment and Resin Volatility:High dependency on petrochemical feedstocks and specialty pigments exposes manufacturers to significant input cost fluctuations.
- Performance Gaps in Eco-Inks:Certain water-based inks face technical challenges in adhesion and durability on non-porous substrates compared to solvent-based versions.
- Divergent Food-Contact Regulations:Navigating conflicting standards from bodies like the US FDA and Europe's EFSA creates significant compliance hurdles and slows product launches.
Strategic Opportunities
- Inks for Smart Packaging:Development of conductive and thermochromic inks for interactive packaging creates a new, high-value application segment.
- Southeast Asian Packaging Growth:Expanding manufacturing sectors in nations like Vietnam and Indonesia offer significant growth potential for advanced packaging ink formulations.
- Bio-Derived UV-Curable Formulations:Combining the rapid curing of UV technology with renewable, bio-based raw materials presents an opportunity for premium, sustainable ink products.
Industry Challenges
- Formulation Chemistry Expertise:A scarcity of chemists skilled in developing novel bio-based and water-based formulations that meet performance and regulatory standards hinders product development.
- Lengthy Food-Contact Certification:The extensive testing required by bodies like EFSA for new food-contact inks creates significant delays in bringing products to market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printing Inks Market |
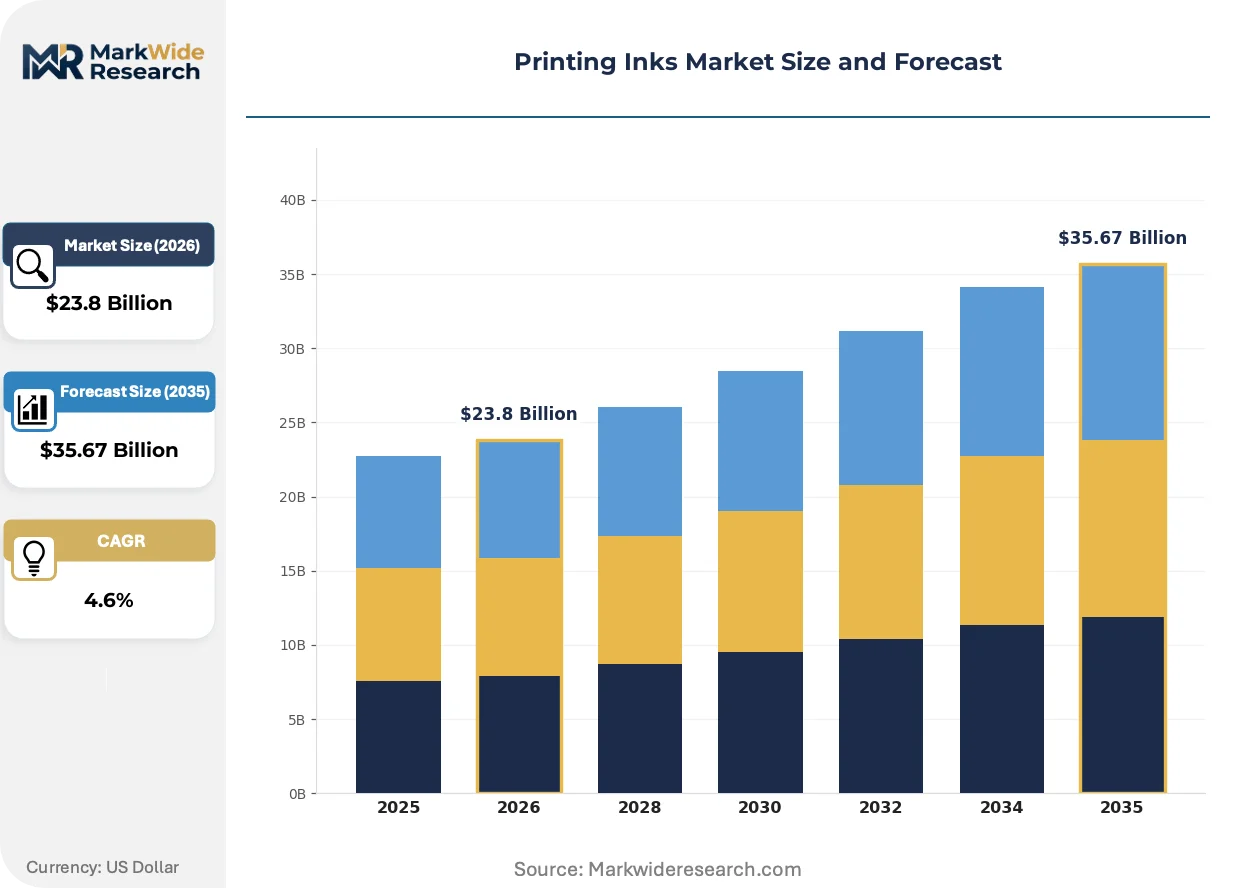
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $35.67 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ink Type: Solvent-Based, UV-Curable, Water-Based, Oil-Based, Energy-Curable Application: Packaging, Textile Decoration, Commercial Printing, Automotive Labeling, Electronics Marking Printing Technology: Flexographic, Gravure, Digital, Letterpress, Screen Printing End User Industry: Publishing Houses, Advertising Agencies, Textile Manufacturers, Electronics Producers, Construction Firms |
| Companies Covered | Flint Group, Siegwerk, Sun Chemical, Toyo Ink SC Holdings Co., Ltd., Sakata INX Corporation, INX International, Nazdar Ink Technologies, Huber Group, DIC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printing Inks Market Strategic Shifts & Innovations
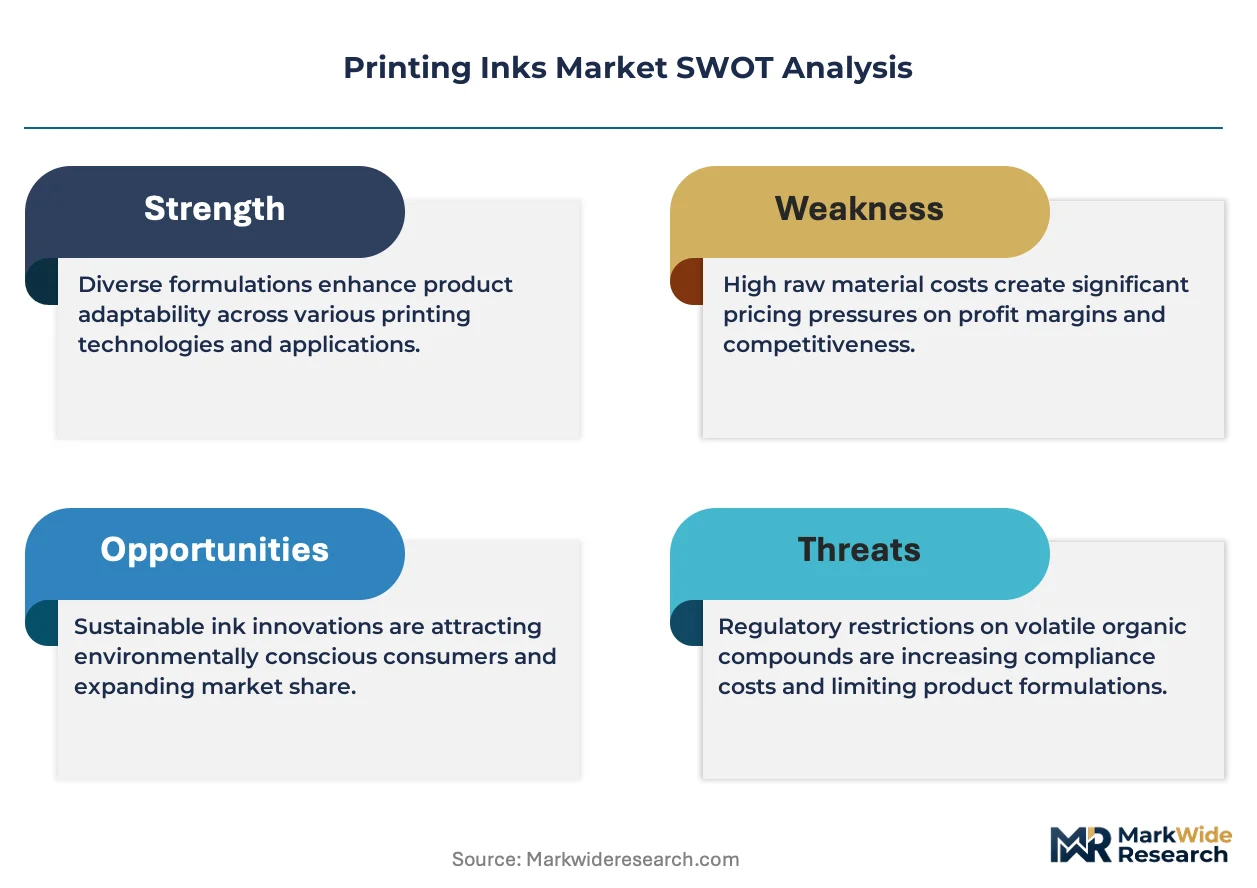
The evolution of printing inks is marked by a transition from mere colorants to functional materials integral to product performance and sustainability. This shift is driven by the dual pressures of circular economy mandates and the technical demands of digital printing processes.
UV-curable inks are formulations that cure almost instantly when exposed to ultraviolet light, offering high-speed production and low VOC emissions. Packaging converters and commercial printers are rapidly adopting this technology to increase throughput and meet environmental standards. This rapid curing capability is electrifying the label and flexible packaging sectors by enabling faster press speeds and reducing energy consumption compared to heat-drying methods.
European Union regulations, specifically the Corporate Sustainability Reporting Directive (CSRD), mandate comprehensive disclosure of environmental and social impacts. This forces ink manufacturers to provide detailed data on sourcing, carbon footprint, and end-of-life characteristics. The packaging ink segment is most affected, as brand owners demand documented, sustainable solutions for their own reporting.
Brand owners are increasingly demanding short-run, versioned, and personalized packaging to target specific consumer segments and promotions. This pattern disrupts the economics of traditional long-run analog printing like gravure, creating an opening for digital printing technologies. This demand for customization is most visible in the food, beverage, and cosmetics industries across North America and Europe.
Printing Inks Market Segmentation
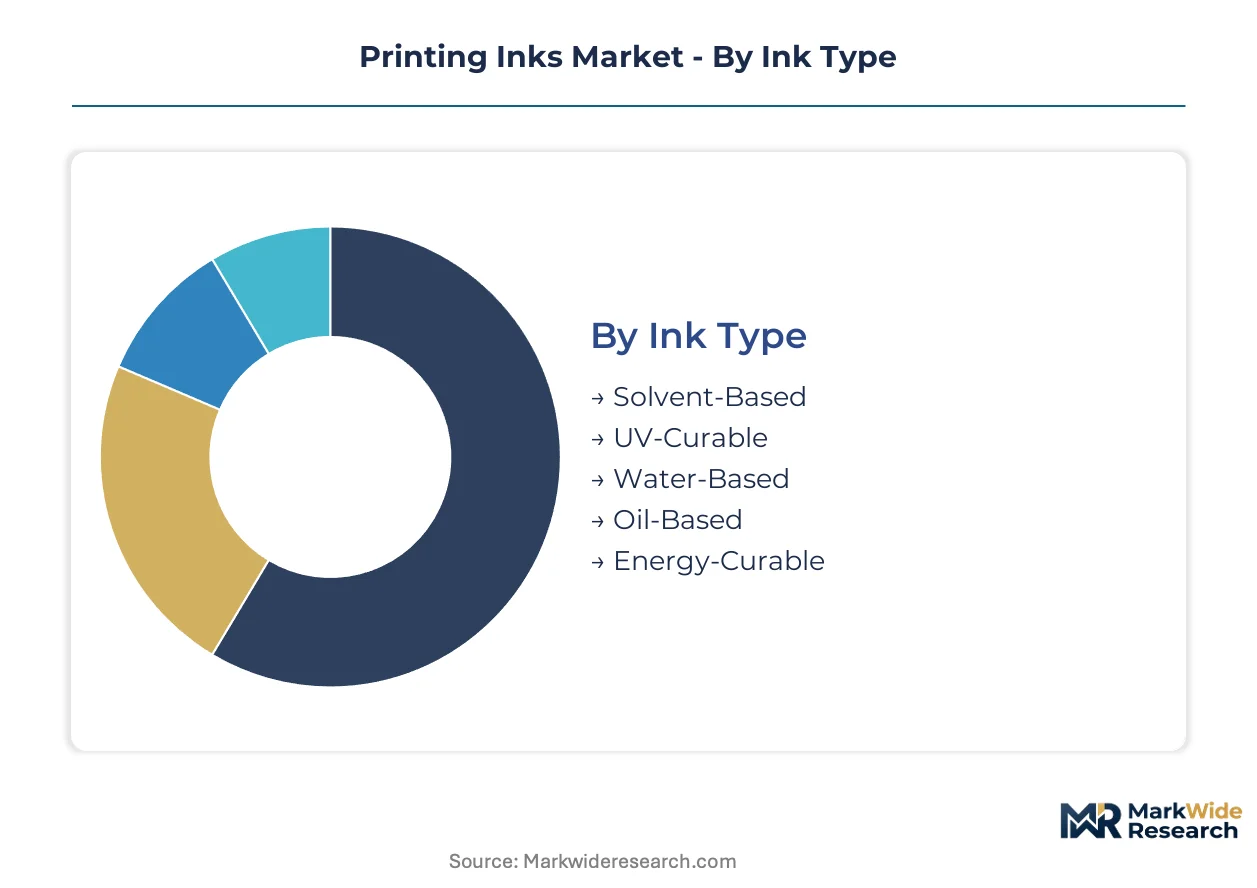
The printing inks market comprises diverse formulations and applications, reflecting varied performance requirements and regulatory pressures. Understanding these distinct segments is crucial for manufacturers to align product development with evolving industry demands and consumer preferences. Each segment addresses specific substrate needs and environmental compliance mandates.
Ink Type:
The market for printing inks is characterized by formulations designed for either standalone use in traditional printing or embedded within advanced, high-speed digital systems.
- UV-Curable:These inks polymerize instantly when exposed to ultraviolet light, offering rapid drying times and excellent adhesion. Demand concentrates in flexible packaging and label printing in Europe, driven by stringent VOC regulations and high-speed production needs.
- Water-Based:Formulated with water as the primary solvent, these inks offer low VOC emissions and easier cleanup. Their demand is significant in food packaging applications, especially in North America, as brand owners seek environmentally compliant and safer printing solutions.
- Solvent-Based:Using organic solvents as carriers, these inks provide strong adhesion and durability on non-porous substrates.
- Oil-Based:Typically utilized in offset printing, these inks offer vibrant colors and good print quality on paper and board.
- Energy-Curable:This category includes UV-curable and electron beam (EB) curable inks, known for instant drying and high resistance.
Solvent-Based inks lead volumes today; UV-Curable inks are gaining share fastest.
Application:
The diverse applications of printing inks range from high-volume, cost-sensitive segments to specialized, premium-priced niches demanding superior performance.
- Packaging:This segment involves inks used for printing on various packaging materials, including flexible films, cartons, and labels. It dominates demand globally, especially in the food and beverage sector, driven by consumer goods consumption and brand differentiation needs.
- Commercial Printing:Encompassing brochures, magazines, catalogs, and promotional materials, this segment relies on inks for high-quality visual reproduction. Demand is evolving with the shift towards shorter print runs and personalized content in Europe and North America.
- Textile Decoration:Inks in this category are applied to fabrics for apparel, home furnishings, and industrial textiles.
- Automotive Labeling:Specialized inks are required for durable, heat-resistant labels and markings on automotive components and interiors.
- Electronics Marking:This segment utilizes conductive or insulating inks for circuit boards, displays, and electronic components.
Packaging applications capture the largest volume; Electronics Marking applications are expanding most quickly.
Printing Technology:
Printing ink technologies span from established, general-purpose methods suitable for mass production to highly specialized digital systems for customized output.
- Flexographic:This relief printing method uses flexible plates and fast-drying inks, making it ideal for high-volume packaging and label printing. It remains a dominant technology in the food and beverage packaging sector across Asia-Pacific due to its efficiency and versatility.
- Digital:Encompassing inkjet and toner-based systems, digital printing allows for variable data and short-run customization. Its demand is surging in the cosmetics and pharmaceutical packaging industries in Europe for personalized product launches.
- Gravure:An intaglio printing process, gravure offers high image quality and long print runs, commonly used for magazines and flexible packaging films.
- Letterpress:One of the oldest printing techniques, letterpress is now primarily used for specialty items and fine art prints due to its tactile quality.
- Screen Printing:This versatile method pushes ink through a mesh stencil, suitable for textiles, signage, and electronics.
Flexographic technology maintains the largest market share; Digital technology shows the steepest expansion trajectory.
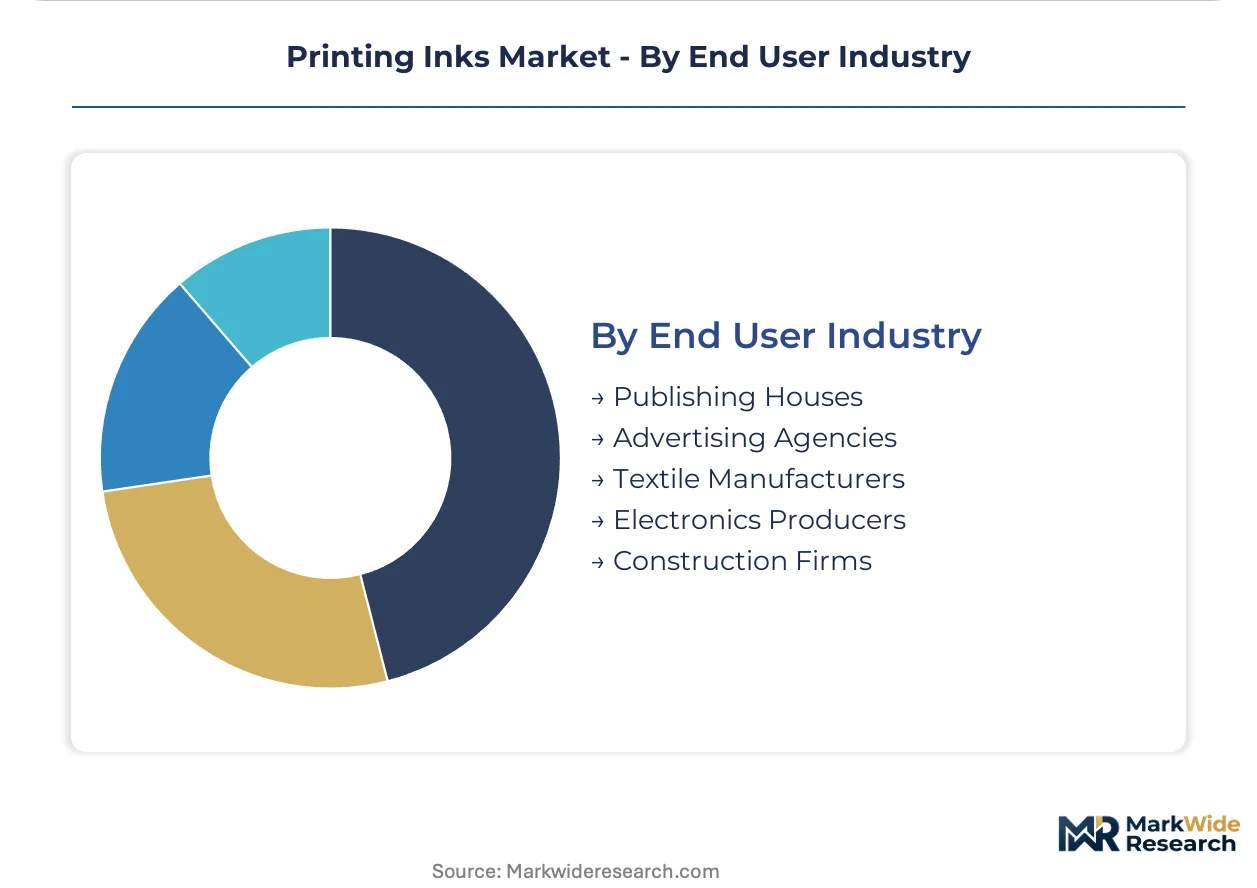
End User Industry:
The printing inks market serves a wide array of end-user industries, varying from those focused on mass-produced printed materials to those requiring highly specialized functional inks.
- Publishing Houses:This segment includes newspapers, books, and magazines, where inks provide visual content and branding. Demand is shifting with the decline of traditional print media, driving innovation in sustainable ink formulations for remaining print volumes.
- Textile Manufacturers:This industry uses inks for dyeing, pattern printing, and functional coatings on various fabrics. Growth is observed in digitally printed textiles for fashion and home decor, particularly in Southeast Asian markets.
- Advertising Agencies:These firms utilize inks for billboards, posters, promotional materials, and point-of-sale displays.
- Electronics Producers:This sector employs specialized inks for printed circuit boards, sensors, and conductive traces.
- Construction Firms:Inks are used for marking, labeling, and decorative elements on construction materials.
Publishing Houses continue to represent significant ink volume; Electronics Producers are driving the fastest growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A skilled workforce and robust manufacturing capabilities anchor the printing inks market across key global regions. China's expansive production base drives significant volume, while European nations focus on sustainable innovation. North America emphasizes advanced formulations and digital printing technologies.
China
China's vast manufacturing and export base drives substantial demand for printing inks, particularly in packaging applications. The nation's dual carbon goals promote the adoption of eco-friendly formulations and production methods. Industrial hubs like the Yangtze River Delta actively integrate advanced ink technologies into their extensive production networks.
Germany
Germany emphasizes high-performance and sustainable printing inks for its advanced manufacturing and packaging sectors. The EU Green Deal initiatives and ECHA regulations compel manufacturers to innovate in bio-based and low-VOC solutions. Specialized chemical clusters in North Rhine-Westphalia are at the forefront of developing next-generation ink chemistries.
United States
Demand in the United States stems from the expanding flexible packaging market and digital printing's personalization needs. The US EPA and FDA regulations significantly influence the development of safer, compliant ink formulations. Innovation centers in California and the Midwest actively pursue bio-derived and UV-curable ink technologies.
Japan
Japan's printing inks market benefits from strong demand in high-precision electronics marking and advanced packaging applications. METI guidelines and JIS standards encourage continuous product quality improvement and environmental performance. Manufacturers in the Kanto region focus on developing specialized functional inks for emerging industrial uses.
India
India's burgeoning consumer goods sector and textile manufacturing industries fuel substantial ink consumption. BIS standards and evolving environmental policies are driving the adoption of more sustainable ink options. Major industrial zones in Maharashtra and Gujarat are seeing increased investment in modern printing ink production facilities.
Printing Inks Market Key Industry Players
The competitive structure tilts toward global conglomerates with significant scale, alongside specialized niche players. This market exhibits a tiered landscape, where large chemical companies compete with focused ink manufacturers for market share. Global leaders often leverage their extensive R&D capabilities and broad geographic reach to absorb compliance costs. Strategic partnerships and targeted capacity expansion are common competitive moves observed across the industry.
Within the global leader archetype, Sun Chemical exemplifies companies leveraging extensive scale to absorb compliance costs and invest in sustainable chemistries. Siegwerk occupies a specialized position, focusing its portfolio on packaging applications and aligning its product development with circular economy principles. DIC Corporation anchors a strong position in Asia, sustained by its extensive regional production networks and deep understanding of local market dynamics. These players collectively demonstrate the diverse strategies employed to navigate evolving market demands and increasingly stringent regulatory pressures, particularly concerning environmental compliance.
| Leading Market Players |
|---|
| Flint Group |
| Siegwerk |
| Sun Chemical |
| Toyo Ink SC Holdings Co., Ltd. |
| Sakata INX Corporation |
| INX International |
| Nazdar Ink Technologies |
| Huber Group |
| DIC Corporation |
| Others |
Cost & Logistics Intelligence
Vertical integration by leading printing ink manufacturers anchors their supply positions and grants significant pricing power across key raw material inputs. This strategic control allows them to better manage costs and maintain competitive pricing in a complex regulatory environment.
Pricing Analysis
Bundled service offerings often characterize printing ink pricing, combining product with technical support. Contract-based long-term offtake agreements dominate for large-volume packaging converters, while smaller commercial printers often face transactional pricing. Price differentiation stems from performance characteristics, such as rapid UV-curable curing, and stringent food-contact certification levels. Pricing softness reflects intense competition in commodity ink segments and raw material input volatility. Commercial printing applications exhibit high price sensitivity, whereas specialized electronics marking applications prioritize performance over cost.
Supply Chain Analysis
Workforce availability in key manufacturing hubs like China, Germany, and the United States shapes the printing ink supply chain. Supply concentration for base chemistries and specialty pigments largely rests on these nations. The industry draws heavily from petrochemical feedstocks for resins and solvents, alongside a diverse range of colorant pigments. Commodity price volatility for these inputs presents a significant structural risk. Distribution typically runs through direct sales channels to large printing converters, complemented by a network of specialized chemical distributors for smaller-scale operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the printing inks market emerges from the premiumization of sustainable and functional formulations. This shift is driven by the rapid adoption of UV-curable inks, which offer significant cost-down benefits through faster production speeds and reduced energy consumption.
For Market Incumbents: Anticipate the ongoing regulatory pressures from bodies like ECHA and the US EPA by accelerating R&D into novel bio-based and water-based formulations. Consolidate market share through strategic acquisitions of specialized eco-ink producers to counter the threat from traditional solvent-based ink displacement. Invest in comprehensive certification processes for food-contact materials to secure premium segments. Expand localized production capabilities in high-growth regions like Southeast Asia to optimize supply chains.
For New Entrants and Emerging Players: Capture emerging demand in specialized functional inks for smart packaging applications, including conductive and thermochromic formulations. Target the rapidly expanding digital printing segment for short-run, personalized packaging in cosmetics and pharmaceuticals as a penetrable entry point. Develop bio-derived UV-curable formulations to align with EU Green Deal initiatives, offering a strong sustainability-focused go-to-market angle. Partner with digital press OEMs to integrate ink solutions directly into new printing platforms.
For Investors and Strategic Acquirers: Roll-up economics work for specialized ink formulators because regulatory complexity and R&D costs create significant barriers to entry. The long-term viability of the printing inks market remains strong, driven by sustained packaging demand and evolving sustainability mandates. Identify mid-sized firms with proprietary sustainable ink chemistries or robust regional distribution networks in Southeast Asia as prime acquisition targets. The accelerated consolidation of niche bio-based ink developers by larger chemical conglomerates signals a key inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for UV-Curable Inks | Increases supply of high-demand, low-VOC formulations for packaging converters in Europe. |
| Backward Integration into Specialty Pigments | Secures critical raw material supply and mitigates input cost volatility for ink manufacturers. |
| Green Manufacturing Process Transition | Aligns production with EU Green Deal initiatives and reduces environmental footprint for global leaders. |
| Long-Term Supply Agreements with Converters | Ensures stable demand and strengthens market position with major food and beverage packaging clients. |
| Joint Venture for Bio-Derived Ink R&D | Accelerates development of sustainable, renewable ink solutions meeting future regulatory standards like REACH. |
Research Approach
Coverage spans Europe, North America, and Asia-Pacific, with primary inputs from each region informing the analysis. This involved extensive interviews with R&D directors, procurement leads at packaging converters, environmental compliance officers, and sales managers across the value chain. Secondary validation drew from ECHA reports, US EPA guidelines, corporate sustainability disclosures, and industry association publications. A rigorous bottom-up and top-down triangulation process ensured data accuracy.
Ink type, application, printing technology, and end-user industry were modeled at a granular level across the analysis window. The analytical framework segmented the market by UV-curable and water-based inks, packaging and commercial printing applications, and flexographic and digital printing technologies. Compound annual growth rates were derived from historical growth patterns and future demand projections. Key forecast inputs included flexible packaging consumption trends and digital printing equipment sales.
Raw material price volatility, evolving chemical regulations, and geopolitical trade policies are the dominant revision risks. Forecasts reflect assumptions regarding technological adoption rates and sustained economic growth in key manufacturing regions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Waterborne Ink Market
Printing Inks
Global Water-Based Inks Market
Printing Inks
Thermochromic Ink Printing Market
Printing Inks
Flexo-Ink Market
Printing Inks
United States Printing Inks Market
Printing Inks
Lithographic Printing Chemicals Market
Printing Inks
Functional Printing Market
Printing Inks
Water-Borne Inks and Paints Market
Printing Inks
Solvent-Based Inks Market
Printing Inks
Inkjet Colorants Market
Printing Inks
Roll-To-Roll Type UV Imprinting Machines Market
Printing Inks
Printing Plate Market
Printing Inks
UV Cured Inks Market
Printing Inks
Textile Printing Ink Market
Printing Inks
Global Flexographic Inks Market
Printing Inks
Low-Odor Inkjet Inks for On-Line Food Coding in Aseptic Filling Market