
 Returnable Glass Bottle Ink Market | 2026-2036
Returnable Glass Bottle Ink Market Size, Share, and Industry Trends Forecast 2026-2036
Returnable Glass Bottle Ink Market Analysis
Beverage packaging is consolidating its position as the primary demand vertical for returnable glass bottle inks, while food packaging and personal care applications recede in relative share. Flint Group leverages its European manufacturing footprint to sustain supply relationships with major beverage bottlers. Siegwerk Druckfarben anchors its competitive stance through specialized ink systems designed for repeated wash cycles on returnable glass. Sun Chemical differentiates by controlling pigment dispersion technologies that withstand caustic cleaning protocols.
Returnable glass bottle ink denotes a specialized printing formulation engineered to adhere to glass substrates while surviving repeated industrial washing, caustic sterilization, and mechanical abrasion across multiple use cycles; these inks typically incorporate alkali-resistant resins and pigments stable at pH levels exceeding 12 during standard bottle cleaning operations. UV-curable ink leads product type demand due to its instant cure properties and superior resistance to alkaline detergents, while water-based formulations occupy the economy tier constrained by slower line speeds and moderate durability. Beverage manufacturers dominate end-user procurement through direct sales channels, with distributors capturing residual volume from smaller regional bottlers and cosmetic companies.
REACH and the EU Green Deal regulate chemical composition and recyclability claims across European ink production, while FDA indirect food contact standards govern formulations deployed on beverage containers in the United States. Germany's national packaging ordinance reinforces returnable system economics, directly sustaining ink demand tied to refillable bottle pools. Stakeholders must monitor evolving caustic wash protocols and substrate pre-treatment standards to align R&D investment with durability requirements.
Market Dynamics
UV-curable ink technology is compressing production cycle times while REACH compliance mandates are forcing reformulation investments across European supply chains, creating divergent cost pressures between premium and economy-tier producers.
Growth Catalysts
- REACH compliance deadlines:ECHA registration requirements for alkali-resistant resin chemistries are accelerating R&D spending among specialty ink formulators in Germany and France.
- Returnable bottle pool expansion:Beverage bottlers in Germany are scaling refillable glass infrastructure under national packaging ordinance incentives, directly lifting ink consumption for repeated-use labeling.
- UV-LED curing systems:Instant polymerization technology is enabling higher line speeds at caustic wash facilities without thermal substrate damage.
Market Restraints
- Photoinitiator supply concentration:Specialty photoinitiator manufacturing clusters in China create input cost volatility for UV-curable ink producers.
- Caustic wash protocol divergence:Inconsistent pH standards across beverage cleaning facilities force redundant formulation testing, elevating compliance overhead.
- Water-based ink performance ceiling:Slower drying kinetics and moderate alkaline resistance constrain water-based systems to lower-speed bottling lines.
Strategic Opportunities
- Personal care packaging conversion:Premium cosmetic brands in France are piloting returnable glass programs for skincare serums, opening niche ink demand outside beverage dominance.
- EU Green Deal circularity mandates:Packaging reuse targets under the European Commission's circular economy action plan will expand refillable bottle pools beyond Germany into Austria and the Netherlands.
- Hybrid UV-water formulations:Converging low-VOC water-based carriers with UV-curable functional resins is creating intermediate performance tiers for mid-speed bottlers.
Industry Challenges
- Pigment dispersion expertise scarcity:Formulation chemists capable of stabilizing inorganic pigments at extreme pH levels command premium compensation, constraining workforce scaling.
- Caustic resistance certification timelines:Third-party validation of 50+ wash cycle durability requires 18-24 month testing protocols, delaying new product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Returnable Glass Bottle Ink Market |
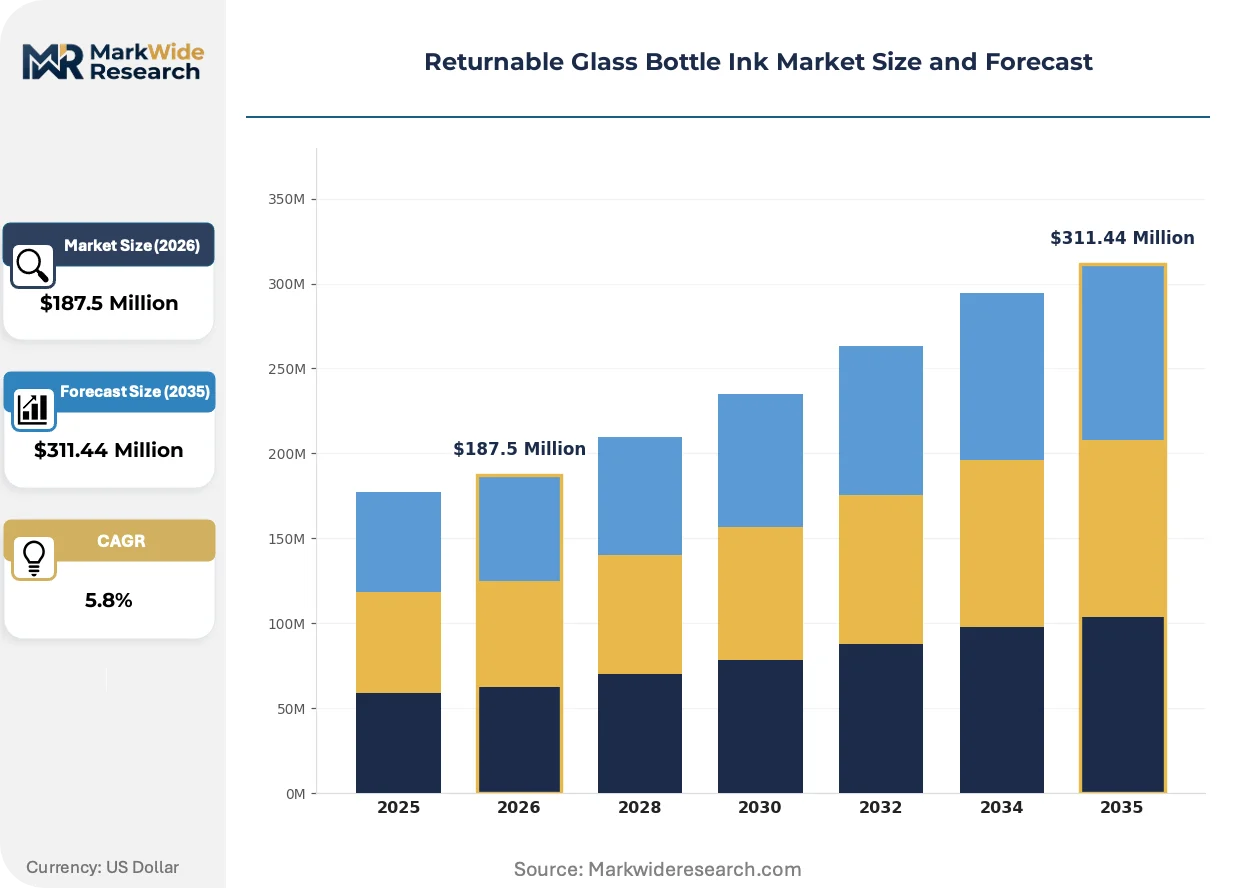
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $311.44 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based Ink, Solvent-Based Ink, UV-Curable Ink, Other Inks Application: Beverage Packaging, Food Packaging, Personal Care Products, Chemicals End User: Beverage Manufacturers, Cosmetic Companies, Chemical Producers, Food Processors Distribution Channel: Direct Sales, Online Retailers, Distributors, Wholesalers |
| Companies Covered | Flint Group, Siegwerk Druckfarben, TOYO INK SC HOLDINGS CO. LTD., Sakata INX Corporation, DIC Corporation, Sun Chemical, Markem-Imaje, Videojet Technologies, Linx Printing Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Returnable Glass Bottle Ink Market Emerging Trajectories
Formulation chemistry is pivoting toward alkaline stability as the defining performance vector, while regulatory chemical disclosure requirements are compressing formulation secrecy and accelerating collaborative supplier-bottler relationships.
UV-LED curable ink systems is expanding into high-speed beverage bottling lines previously served by thermal cure technologies. Major German bottlers are retrofitting existing lines with LED arrays to eliminate heat-related glass stress fractures. This technology is expanding into mid-tier regional producers who previously deferred capital investment due to thermal system footprint constraints.
REACH authorization requirements for specific photoinitiator chemistries are forcing substitution toward bio-based alternatives with equivalent reactivity profiles. ECHA's sunset date scheduling for conventional photoinitiators is compressing reformulation timelines to 36-month windows. German ink formulators are responding by pre-qualifying alternative chemistries through bilateral testing protocols with major beverage customers.
Direct procurement relationships between beverage manufacturers and ink formulators are displacing traditional distributor intermediaries for volume contracts. Large bottling cooperatives in Bavaria and North Rhine-Westphalia are consolidating specification authority at headquarters level, reducing regional purchasing autonomy. This concentration is most visible in Germany's multi-brand beverage conglomerates, where technical service integration now outweighs price-point competition in supplier selection criteria.
Returnable Glass Bottle Ink Market Segmentation
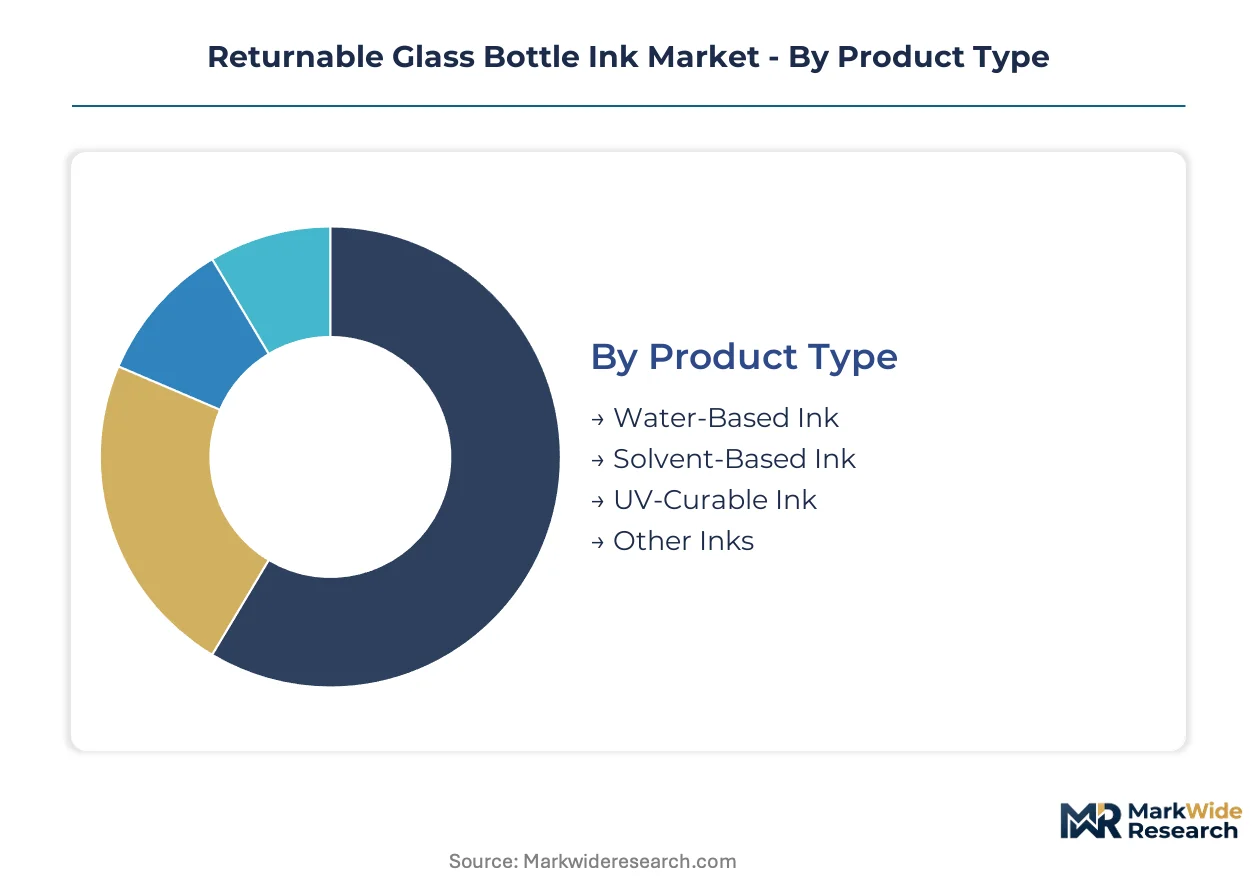
Returnable glass bottle ink procurement varies sharply by operational scale and wash-cycle intensity. Segmentation reveals where premium formulations command price premiums versus where economy tiers suffice.
Product Type:
Formulation chemistry determines whether inks operate as standalone high-performance systems or embed within broader coating architectures.
- UV-Curable Ink:Photoinitiator-triggered polymerization delivers instant cure at line speeds exceeding 600 bottles per minute. German beverage bottlers retrofitting LED arrays drive procurement concentration here, though REACH authorization deadlines for conventional photoinitiators compress reformulation timelines.
- Water-Based Ink:Acrylic or polyurethane dispersions in aqueous carriers offer lower VOC profiles but require thermal drying tunnels that constrain throughput. Mid-speed regional bottlers in France and Austria accept these trade-offs for compliance with local air quality ordinances.
- Solvent-Based Ink:Volatile organic solvent carriers provide aggressive substrate wetting on untreated glass surfaces.
- Other Inks:Hybrid and specialty formulations including dual-cure systems for niche cosmetic applications.
Volume placements concentrate in UV-curable systems; the faster expansion belongs to water-based alternatives as mid-tier producers upgrade environmental compliance.
Application:
Wash-cycle frequency and caustic exposure severity separate applications into distinct specification tiers.
- Beverage Packaging:Carbonated soft drinks, beer, and mineral water bottles endure 50+ industrial wash cycles at pH levels exceeding 12. REACH-compliant alkali-resistant resins and specialized pigment dispersions dominate procurement specifications here.
- Personal Care Products:Premium skincare serums and fragrances in returnable glass command higher per-unit ink spending despite smaller batch volumes. French cosmetic houses pilot refillable programs that demand decorative durability through fewer but chemically aggressive cleaning protocols.
- Food Packaging:Sauces, oils, and preserves in returnable glass require FDA or EFSA indirect food contact certification.
- Chemicals:Industrial and agricultural chemical containers prioritize chemical resistance over aesthetic retention.
Revenue concentration sits with beverage applications; personal care packaging climbs fastest as premium brands adopt circular packaging mandates.
End User:
Procurement scale and technical integration depth distinguish buyer categories.
- Beverage Manufacturers:Multi-brand conglomerates and cooperative bottlers in Bavaria and North Rhine-Westphalia consolidate specification authority at headquarters level, demanding direct technical service relationships rather than distributor intermediaries.
- Cosmetic Companies:L'Oréal and Estée Lauder supply chains in France and Switzerland specify small-batch decorative inks with batch-traceability documentation for premium positioning.
- Chemical Producers:Industrial container users prioritize functional coding durability over brand aesthetics.
- Food Processors:Mid-sized condiment and preserve manufacturers source through distributor networks with less stringent wash-cycle guarantees.
Procurement volume aggregates at beverage manufacturers; cosmetic companies expand their ink spending most rapidly through returnable glass conversion pilots.
Distribution Channel:
Channel selection tracks order scale and technical service requirements across end-user tiers.
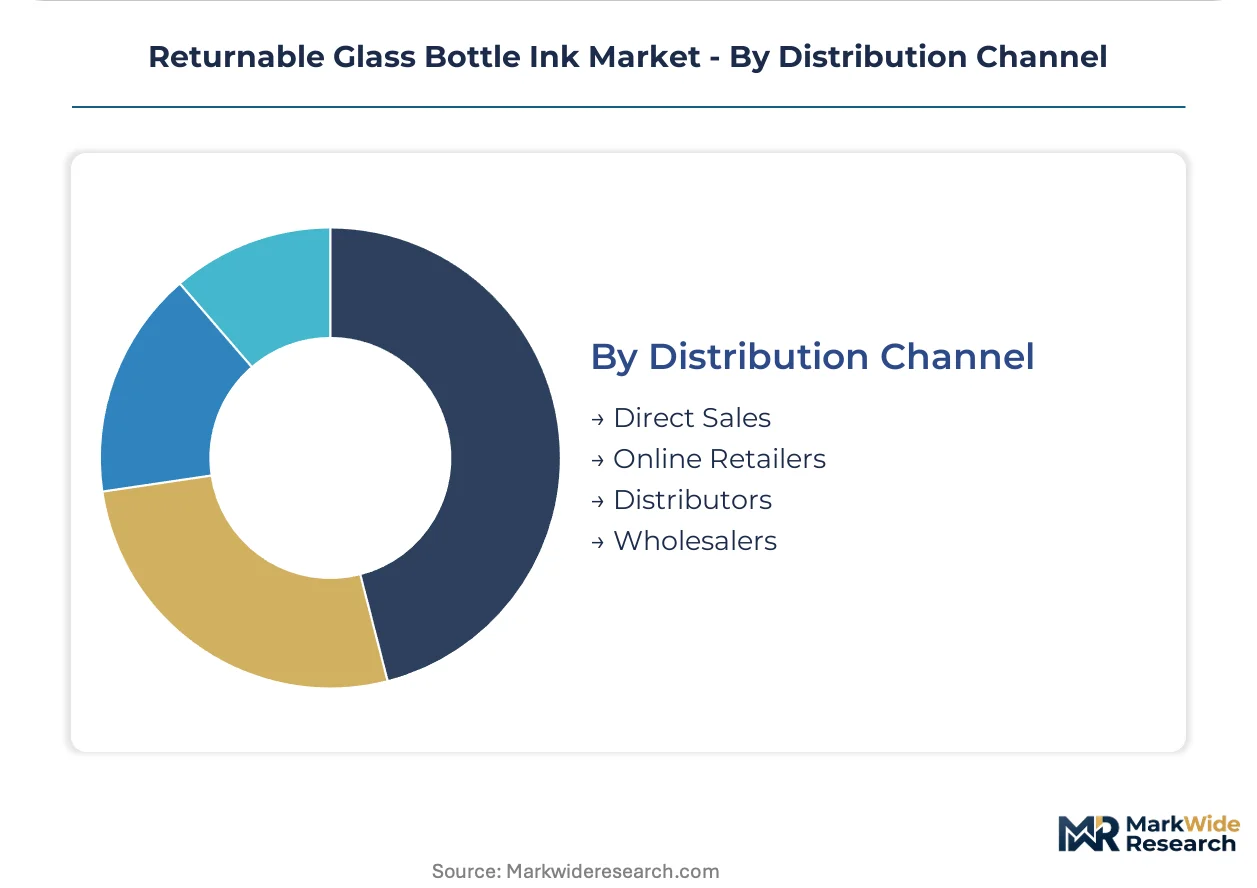
- Direct Sales:Flint Group and Siegwerk Druckfarben deploy technical service teams to major bottling cooperatives for specification development and line trials. These relationships lock in multi-year supply agreements with volume commitments.
- Distributors:Regional ink distributors capture residual volume from smaller bottlers and cosmetic companies requiring less intensive application engineering.
- Online Retailers:E-commerce platforms serve prototype and small-batch cosmetic producers with standardized SKU procurement.
- Wholesalers:General industrial chemical wholesalers move economy-tier solvent-based formulations to price-sensitive chemical container users.
Transaction value concentrates in direct sales channels; online retailers gain share fastest among emerging cosmetic entrants testing returnable formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's packaging ordinance incentives concentrate returnable glass bottle ink demand within designated circular economy zones, creating tax-advantaged procurement clusters for beverage bottlers operating refillable pool systems.
Germany
Bavarian and North Rhine-Westphalian bottling cooperatives drive procurement volume through centralized specification authority. REACH authorization deadlines from ECHA compress reformulation timelines for alkali-resistant resin chemistries. Technical service teams from major ink suppliers maintain permanent presence in Munich and Düsseldorf industrial corridors.
France
Paris-based cosmetic houses pilot returnable glass programs for premium skincare serums, generating niche ink demand outside beverage dominance. ANSM disclosure requirements for cosmetic packaging chemicals elevate batch-traceability documentation standards. Lyon and Provence-Alpes-Côte d'Azur clusters host specialized decorative ink trials for fragrance refillables.
United States
Craft beverage producers in Pacific Northwest and Colorado experiment with limited returnable bottle pools despite single-use packaging economics. FDA indirect food contact standards govern formulation deployment on beverage containers. Wisconsin and Michigan retain legacy refillable beer infrastructure with regional ink sourcing through distributor networks.
Japan
METI circular economy roadmaps encourage refillable packaging pilots among premium beverage brands. JIS standards for container reuse durability influence ink specification protocols. Osaka-Kobe industrial zone maintains specialized glass container washing equipment manufacturing that supports adjacent ink application system demand.
Netherlands
Amsterdam-Rotterdam corridor beverage distributors test hybrid returnable systems under EU Green Deal circularity mandates. EFSA compliance requirements align with German REACH frameworks for cross-border supply chains. Randstad logistics infrastructure enables efficient bottle pool rotation that sustains wash-cycle ink replacement schedules.
Returnable Glass Bottle Ink Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation expertise commanding premium positioning in high-wash-cycle beverage applications while economy-tier producers serve price-sensitive chemical container coding. Market structure tilts toward consolidated supply relationships at the beverage manufacturer tier, with distributor intermediaries capturing residual volume from smaller regional players. Three archetypes dominate: integrated ink-pigment compounders, specialized glass decoration formulators, and diversified industrial marking suppliers. Competitive dynamics center on direct technical service integration and pre-qualified alternative chemistry pipelines.
Among European-anchored specialists, Flint Group and Siegwerk Druckfarben exemplify the integrated formulator archetype through sustained supply relationships with major beverage bottlers. Sun Chemical occupies a position bridging pigment dispersion control with glass-specific application engineering. These three represent differentiated approaches to the alkaline durability challenge—through manufacturing footprint depth, wash-cycle specialization, and materials science integration respectively.
| Leading Market Players |
|---|
| Flint Group |
| Siegwerk Druckfarben |
| TOYO INK SC HOLDINGS CO. LTD. |
| Sakata INX Corporation |
| DIC Corporation |
| Sun Chemical |
| Markem-Imaje |
| Videojet Technologies |
| Linx Printing Technologies |
| Others |
Supply Flow & Price Mechanics
Beverage bottling cooperatives in Bavaria and North Rhine-Westphalia concentrate procurement authority at headquarters level, enabling contract-based long-term offtake agreements that lock in volume commitments and compress spot market liquidity for ink formulators.
Pricing Analysis
Short lead-time premiums apply to UV-curable ink orders from German bottlers retrofitting LED curing arrays on compressed timelines. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant alkali-resistant formulations from water-based alternatives and legacy solvent systems. Cost compression in water-based tiers is intensifying because mid-speed regional producers in France and Austria accept slower drying kinetics for air quality compliance. Chemical container coders show highest price sensitivity; beverage manufacturers with direct technical service relationships exhibit lowest.
Supply Chain Analysis
Direct-to-beverage-manufacturer channels handle hyperscale demand from German multi-brand conglomerates, while regional distributors capture residual volume from smaller cosmetic companies and food processors. Photoinitiator manufacturing clusters in China, alkali-resistant resin production in Germany, and specialty pigment dispersion operations in Japan anchor upstream supply. Raw material flows draw from photoinitiator chemistries, polyurethane acrylic dispersions, and inorganic pigment stabilizers. Single-source vulnerability concentrates in Chinese photoinitiator supply. Distribution runs through technical service-integrated direct sales for volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pigment dispersion expertise scarcity props pricing power for qualified formulators, as chemists capable of stabilizing inorganic pigments at pH levels exceeding 12 command premium compensation and constrain workforce scaling.
For Market Incumbents: Anchor market position through backward integration into alkali-resistant resin production and captive supply of specialized photoinitiator alternatives ahead of ECHA sunset dates. Pre-qualify bio-based photoinitiator chemistries through bilateral testing protocols with Bavarian bottling cooperatives to defend against formulation disruption. Deepen technical service presence in Munich and Düsseldorf industrial corridors to lock out distributor intermediaries.
For New Entrants and Emerging Players: Enter via personal care packaging pilots in France, where L'Oréal and Estée Lauder supply chains demand small-batch decorative inks with batch-traceability documentation and tolerate premium positioning. Target online retail channels serving prototype cosmetic producers testing returnable glass formats. Pursue hybrid UV-water formulation development for mid-speed bottlers seeking intermediate performance tiers.
For Investors and Strategic Acquirers: The window for entry favors pigment dispersion specialists with proven caustic wash cycle certification. Long-term viability hinges on formulation chemistry IP rather than manufacturing scale. Watch for ECHA authorization deadline acceleration as inflection indicator compressing reformulation timelines and elevating acquisition premiums for pre-qualified alternative chemistry pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive supply of REACH-compliant alkali-resistant chemistries insulates against ECHA authorization disruption. |
| UV-LED Curing System Partnership | Technical collaboration with German bottler retrofit programs locks in specification authority at headquarters level. |
| Hybrid Formulation Development | Converging low-VOC water-based carriers with UV-curable functional resins captures mid-speed bottler demand. |
| Cosmetic Supply Chain Qualification | Batch-traceability documentation for French skincare serums opens premium pricing outside beverage dominance. |
| Photoinitiator Substitution Pipeline | Pre-qualified bio-based alternatives ahead of ECHA sunset dates defend market position against regulatory displacement. |
Methodological Framework
Document review covered ECHA REACH registration databases, EU Green Deal circular economy action plan documentation, and beverage industry packaging ordinance filings, complemented by interviews with ink formulation chemists, technical service directors at major suppliers, procurement leads at Bavarian bottling cooperatives, and regulatory affairs specialists. Secondary validation drew from customs trade data, SEC filings of diversified chemical companies, and industry association reports from European printing ink manufacturers. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and end-user segments.
Segment-level projections across the analysis window incorporated UV-curable versus water-based formulation splits, beverage versus personal care application trajectories, and direct sales versus distributor channel evolution. CAGRs derived from wash-cycle intensity assumptions tied to returnable bottle pool expansion under national packaging ordinances and EU circularity mandates. Industry-specific inputs included caustic wash protocol pH standard divergence, photoinitiator authorization timelines, and LED curing adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated ECHA sunset scheduling or photoinitiator supply disruption from Chinese manufacturing clusters. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Global Printing Toners Market
Printing Inks
Global Digital Inks Market
Printing Inks
United States Printing Inks Market
Printing Inks
Thermochromic Ink Printing Market
Printing Inks
Printing Plate Market
Printing Inks
Global Digital Textile Printing Inks Market
Printing Inks
Continuous Inkjet Ink Market
Printing Inks
Inkjet Colorants Market
Printing Inks
Global UV (Ultraviolet) Curable Inks Market
Printing Inks
Global Ceramic Inks Market
Printing Inks
Textile Printing Ink Market
Printing Inks
Flexo-Ink Market
Printing Inks
Lithographic Printing Chemicals Market
Printing Inks
UV Fluorescing Ink Market
Printing Inks
Packaging Inks and Coatings Market
Printing Inks
Ink Additives Market