
 Thermochromic Ink Printing Market | 2026-2036
Thermochromic Ink Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Thermochromic Ink Printing Market Analytics
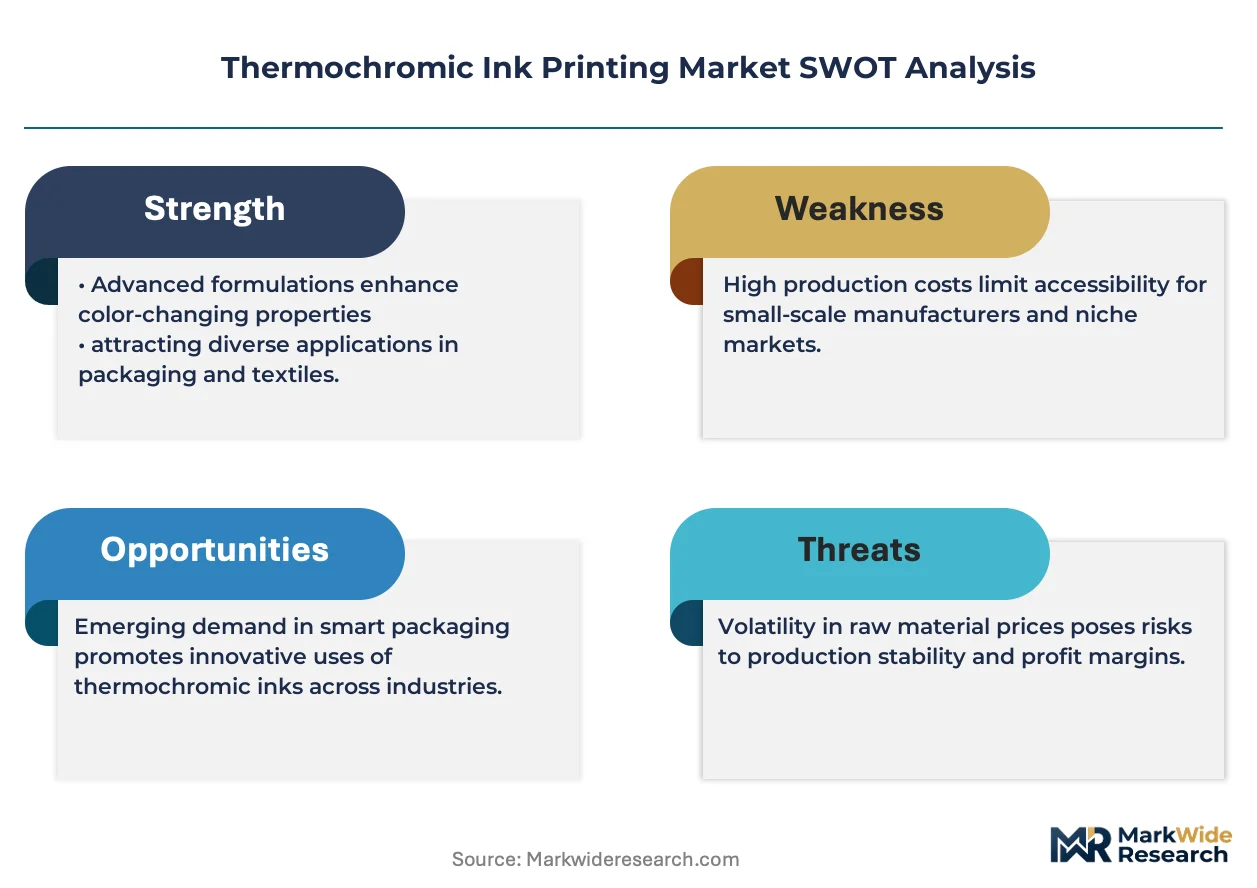
Asset-light leasing arrangements for digital printing equipment is fragmenting competitive entry barriers across the thermochromic ink value chain. Chromatic Technologies Inc. leverages captive R&D facilities to sustain formulation leadership in reversible color-change systems. LCR Hallcrest anchors North American supply through specialized temperature-indicating coatings for healthcare cold-chain monitoring. Matsui International dominates Asian textile applications with pigment stability across repeated washing cycles.
Thermochromic ink printing employs leuco dye-based or liquid crystal formulations that undergo reversible color transitions at defined temperature thresholds, typically engineered between negative twenty-nine and sixty-six degrees Celsius for industrial applications. The technology serves authentication, thermal warning, and interactive consumer engagement functions across printed substrates. Liquid ink formulations capture the dominant margin pool in packaging due to compatibility with high-speed flexo and offset lines, while digital printing represents the fastest-growing technology segment as short-run customization expands in premium gift and label markets. Powder ink maintains mature positioning in textile screen printing where batch consistency outweighs speed requirements.
REACH registration through ECHA governs leuco dye composition and migration limits across European consumer goods applications, while FDA 21 CFR indirect food additive rules constrain ink selection for U.S. packaging contacting edible contents. Japan's Ministry of Economy, Trade and Industry (METI) chemical substance classification system creates additional compliance layers for electronics-adjacent printing. Stakeholders must monitor evolving PFAS restrictions and state-level extended producer responsibility laws that could force reformulation of conventional thermochromic microencapsulation chemistries.
Market Dynamics
Leuco dye microencapsulation chemistry is undergoing forced reformulation as PFAS restrictions tighten across multiple jurisdictions, compressing supplier margins while elevating compliant formulation premiums.
Growth Catalysts
- Pharmaceutical serialization mandates:FDA 21 CFR track-and-trace requirements for prescription packaging are expanding demand for temperature-verification inks in cold-chain logistics.
- REACH registration completion:ECHA-compliant leuco dye portfolios now command preferential placement in European consumer goods applications.
- Digital retrofitting of flexo lines:High-speed inkjet integration is opening short-run customization pathways previously uneconomical for thermochromic work.
Market Restraints
- Specialty solvent cost volatility:Microencapsulation-grade aromatic solvents concentrate in German and Japanese chemical clusters, exposing formulators to input price spikes.
- Single-source leuco dye supply:Reversible dye precursors rely on concentrated Asian pigment manufacturing, creating geographic vulnerability.
- Liquid crystal thermal range limits:Narrow operational windows between negative twenty-nine and sixty-six degrees Celsius restrict deployment in extreme-climate logistics.
Strategic Opportunities
- Indian pharmaceutical export packaging:CDSCO-aligned cold-chain verification standards for temperature-sensitive biologics remain underpenetrated by specialty ink suppliers.
- EU Green Deal procurement incentives:Public sector purchasing preferences for recyclable printed materials favor water-based thermochromic formulations over solvent systems.
- Near-field communication convergence:Integration of printed electronics with color-change indicators enables smartphone-readable thermal history tracking.
Industry Challenges
- Color chemist talent scarcity:Formulation expertise spanning organic dye chemistry, polymer encapsulation, and print rheology concentrates in aging specialist workforces.
- Multi-jurisdiction certification timelines:Simultaneous FDA indirect food additive, REACH, and METI substance classification reviews extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermochromic Ink Printing Market |
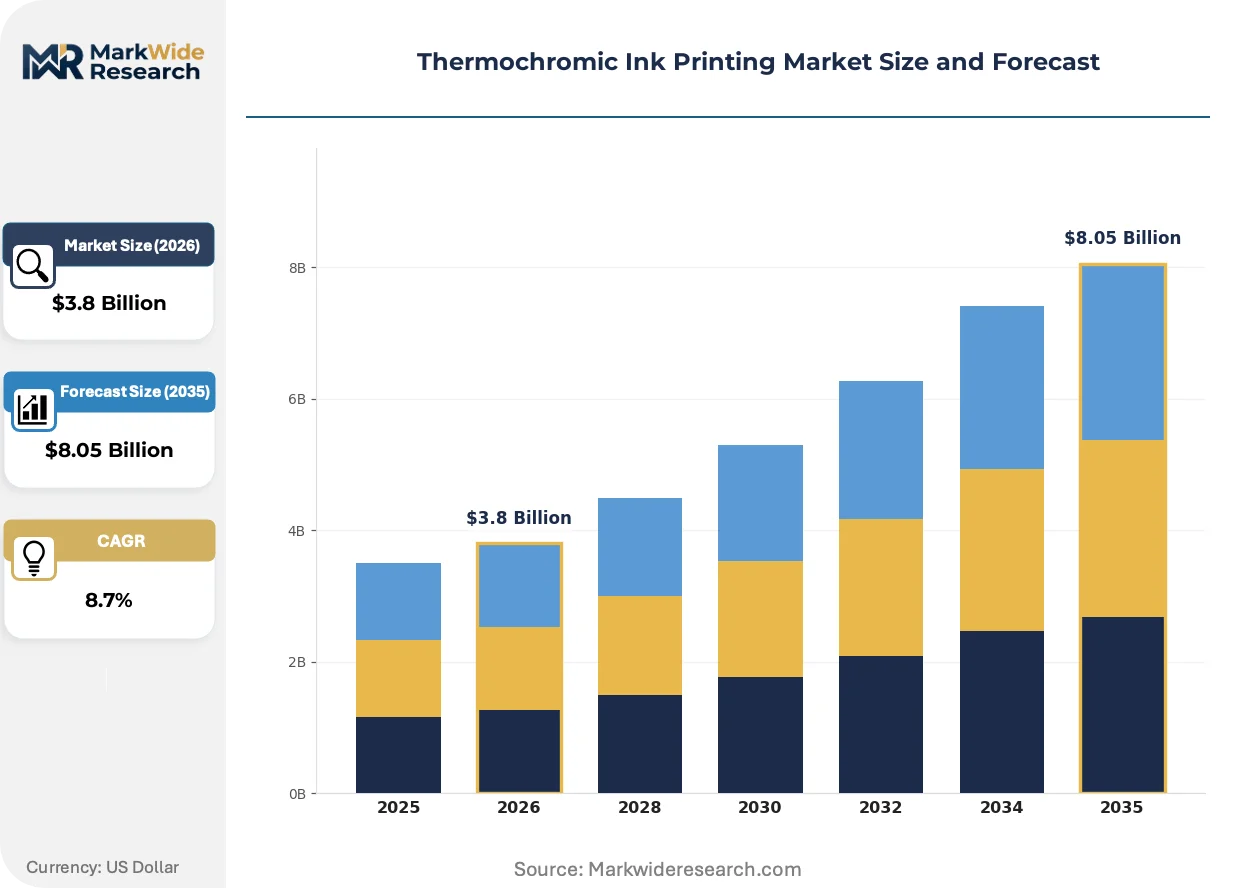
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Ink, Powder Ink, Paste Ink, Adhesive Ink Application: Packaging, Textiles, Labels, Gifts Technology: Offset Printing, Digital Printing, Screen Printing, Flexo Printing End User: Consumer Goods, Automotive, Healthcare, Electronics |
| Companies Covered | Chromatic Technologies Inc., LCR Hallcrest, OliKrom, Matsui International, Smarol Industry Co. Ltd., New Color Chemical, QCR Solutions Corp, SpotSee, Kolortek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermochromic Ink Printing Market Evolving Landscape
Formulation science and regulatory compliance are converging to redefine competitive advantage, with sustainability credentials and digital compatibility emerging as primary differentiation vectors.
Water-based leuco dye dispersions with bio-derived encapsulation polymers are rendering obsolete solvent-heavy conventional systems in European packaging. Premium cosmetic and food brands in Germany and France are specifying these formulations for primary retail packaging. The shift is compressing margins for legacy solvent-dependent suppliers while rewarding early movers with certified recyclable streams.
REACH Article 33 disclosure obligations for substances of very high concern are forcing reformulation of legacy microencapsulation chemistries across European consumer goods. Ink suppliers must now document full supply chain composition down to 0.1% concentration thresholds. Pharmaceutical and food-contact segments are responding fastest, with German and Swiss packaging converters leading qualification programs.
Brand procurement teams are consolidating supplier relationships around integrated color-change and digital authentication capabilities. Pharmaceutical cold-chain monitoring in the United States is shifting from discrete temperature strips toward printed indicators with embedded QR thermal history logs. This preference compression is most visible in California and Massachusetts biotech corridors, where serialization mandates intersect with sustainability reporting requirements.
Thermochromic Ink Printing Market Segmentation
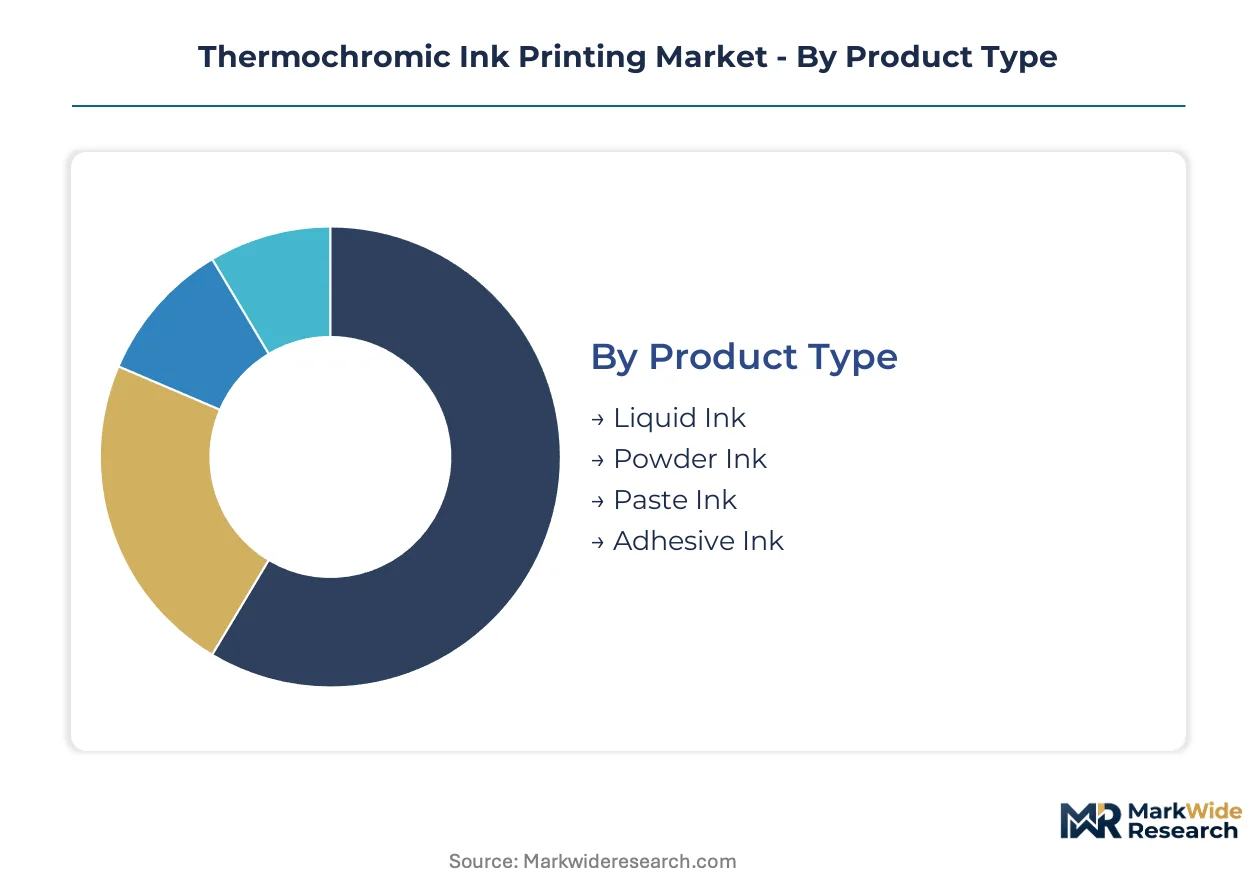
Thermochromic ink printing segments reveal stark divergences in formulation complexity, regulatory exposure, and equipment amortization cycles. Product type and technology choices determine whether converters capture premium authentication margins or compete on commodity textile decoration.
Product Type:
Liquid ink formulations turn inventory fastest in high-volume packaging lines, while paste and adhesive variants tie up working capital through extended curing and bonding validation cycles.
- Liquid Ink:Water-based and solvent-borne dispersions of leuco dye microcapsules dominate flexo and offset integration. Pharmaceutical cold-chain packaging in Germany and the United States absorbs the highest-specification lots, where FDA 21 CFR indirect food additive compliance and ECHA REACH registration create dual-certification premiums.
- Powder Ink:Dry thermochromic pigments require pre-mix activation with binders before screen deployment, extending batch preparation time. Japanese textile printers favor these systems for durability across repeated washing cycles in functional apparel, accepting slower throughput for color stability.
- Paste Ink:High-viscosity formulations serve specialty ceramic and glass decoration where thermal exposure during firing demands robust microencapsulation. Demand concentrates in Italian and Spanish decorative tile manufacturing.
- Adhesive Ink:Pressure-sensitive thermochromic coatings bond to irregular substrates for automotive interior and wearable electronics applications. South Korean electronics assemblers specify these for flexible display thermal warning indicators.
Liquid ink dominates installed base. Powder ink is where expansion concentrates for extreme-durability specifications.
Application:
Packaging applications command the steepest margin tiers through pharmaceutical serialization mandates, while textile and gift segments compete on design velocity and seasonal turnover.
- Packaging:Folding cartons, flexible films, and blister packs incorporate temperature-verification indicators for biologics and perishables. California and Massachusetts biotech corridors drive specification tightening, where printed QR-thermal history convergence commands supplier consolidation.
- Textiles:Screen-printed thermochromic graphics on activewear and promotional apparel require wash-fast leuco dye systems. Matsui International's pigment stabilization technology anchors Japanese and Taiwanese supply for premium sportswear brands.
- Labels:Self-adhesive temperature indicators serve logistics and healthcare cold-chain monitoring. German pharmaceutical exporters specify ECHA-compliant formulations for intra-EU distribution.
- Gifts:Short-run customization for promotional merchandise and novelty items favors digital printing compatibility. Seasonal demand spikes in North American and European retail calendars strain just-in-time ink supply.
Packaging captures value concentration. Digital-ready gift applications are climbing the fastest.
Technology:
Offset and flexo lines amortize equipment over decade-long cycles, while digital retrofit investments recover through job-mix flexibility within three to five years.
- Offset Printing:Sheet-fed and web offset systems handle high-volume pharmaceutical and cosmetic packaging with precise color registration. Chromatic Technologies Inc. formulates specifically for these lines in North American security printing.
- Digital Printing:Inkjet integration enables variable-data thermochromic elements with lot-specific thermal thresholds. Short-run label and gift producers in France and the United Kingdom adopt fastest where SKU proliferation outstocks analog changeover economics.
- Screen Printing:Thick-film deposition suits textile and industrial applications requiring heavy pigment loading. Batch consistency outweighs speed for Japanese functional apparel decorators.
- Flexo Printing:Central impression drum and inline stack configurations dominate food and beverage packaging. Water-based thermochromic formulations are displacing solvent systems under EU Green Deal procurement pressure.
Offset and flexo anchor production capacity. Digital printing is gaining share fastest through customization premiums.
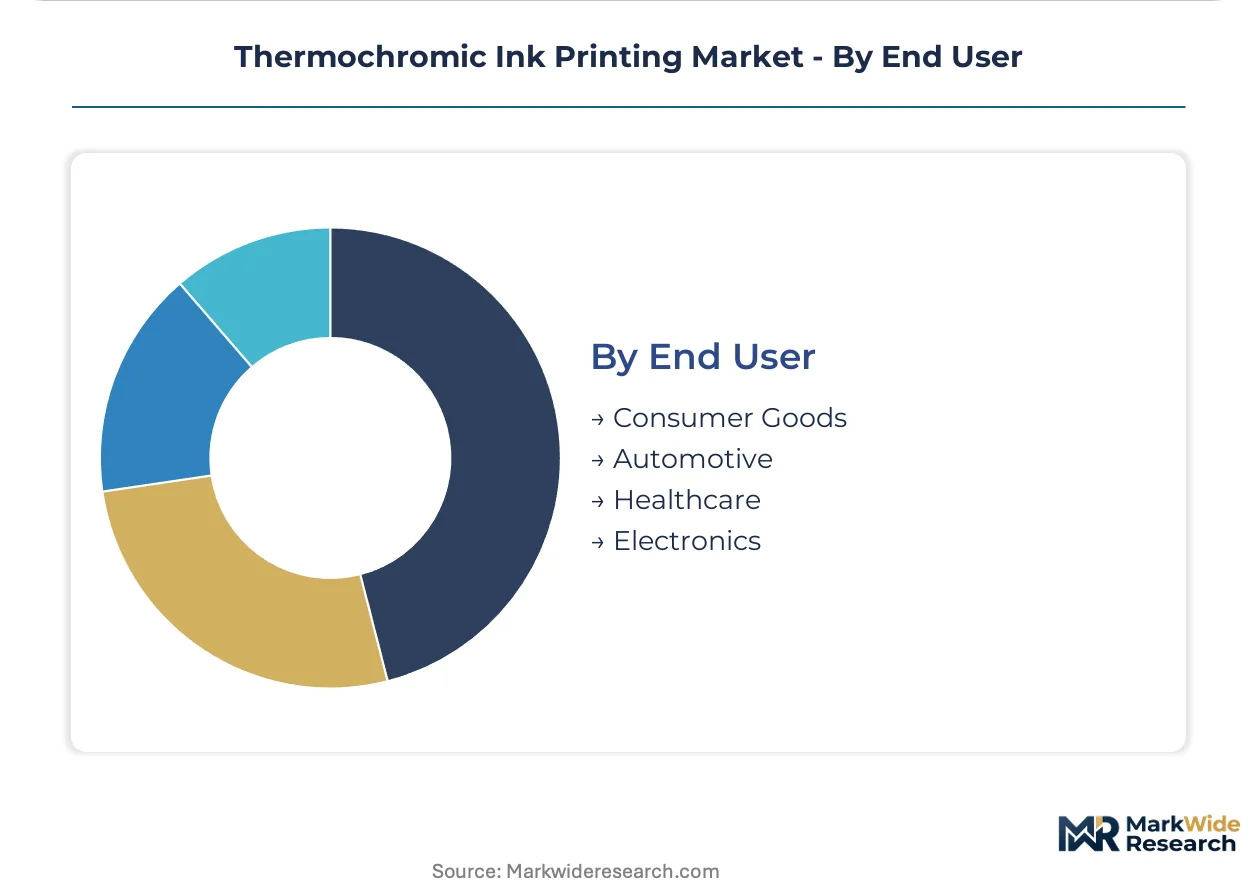
End User:
Healthcare and automotive procurement cycles stretch eighteen to thirty-six months for qualification, while consumer goods and electronics segments compress specification-to-production timelines below six months.
- Consumer Goods:Food, beverage, and personal care brands deploy thermochromic elements for interactive shelf engagement and temperature freshness indication. German and French premium cosmetic houses specify recyclable water-based systems.
- Automotive:Interior trim and battery thermal warning applications demand automotive-grade durability testing. LCR Hallcrest supplies North American OEMs through validated temperature-indicating coating programs.
- Healthcare:Pharmaceutical serialization and cold-chain verification represent the highest-compliance end-use. FDA track-and-trace mandates and CDSCO-aligned Indian export standards are expanding specification reach.
- Electronics:Flexible circuit thermal monitoring and wearable device indicators require thin-film deposition compatibility. South Korean and Japanese electronics manufacturers integrate printed thermochromics with near-field communication layers.
Healthcare dominates qualification-intensive value capture. Electronics integration with printed sensors is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal procurement incentives and FDA serialization mandates are redirecting investment toward compliant formulation hubs. Germany, Japan, and the United States concentrate advanced printing infrastructure. India and South Korea represent expansion frontiers for pharmaceutical and electronics integration.
United States
Pharmaceutical cold-chain verification absorbs high-specification thermochromic lots. FDA 21 CFR track-and-trace requirements for prescription packaging expand demand. California and Massachusetts biotech corridors drive QR-thermal history convergence in printed indicators.
Germany
Premium cosmetic and food brands specify recyclable water-based formulations for primary retail packaging. ECHA REACH registration governs leuco dye composition and migration limits. Packaging converters in Baden-Württemberg and Bavaria lead qualification programs for pharmaceutical exporters.
Japan
Functional apparel decorators favor powder ink systems for wash-fast pigment stability. METI chemical substance classification creates compliance layers for electronics-adjacent printing. Textile printers in Osaka and Nagoya accept slower throughput for color durability across repeated washing cycles.
India
Pharmaceutical export packaging for temperature-sensitive biologics remains underpenetrated by specialty ink suppliers. CDSCO-aligned cold-chain verification standards expand specification reach. Maharashtra and Gujarat packaging hubs are retrofitting lines for serialization-compliant thermochromic integration.
South Korea
Electronics manufacturers integrate printed thermochromics with near-field communication layers for thermal warning indicators. Flexible circuit and wearable device applications require thin-film deposition compatibility. Seoul and Busan assemblers specify pressure-sensitive coatings for automotive interior and display applications.
Thermochromic Ink Printing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation, equipment, and end-use verticals. The vendor base organizes around three strategic archetypes: captive R&D formulators, regional coating specialists, and digital-integrated solution providers. Consolidation pressure concentrates among solvent-dependent suppliers facing PFAS reformulation costs. Dominant competitive moves include backward integration into microencapsulation chemistry and geographic licensing partnerships for regulatory compliance.
Within the captive R&D tier, Chromatic Technologies Inc. and LCR Hallcrest exemplify formulation-led positioning. Chromatic Technologies occupies a position among North American security printers with reversible color-change systems. LCR Hallcrest anchors supply for healthcare cold-chain monitoring through temperature-indicating coating programs. Matsui International represents the Asian textile specialization vector, with pigment stabilization technology for functional apparel applications.
| Leading Market Players |
|---|
| Chromatic Technologies Inc. |
| LCR Hallcrest |
| OliKrom |
| Matsui International |
| Smarol Industry Co. Ltd. |
| New Color Chemical |
| QCR Solutions Corp |
| SpotSee |
| Kolortek |
| Others |
Value Network & Pricing Analysis
Shanghai-Rotterdam container freight corridors transmit cost volatility from concentrated leuco dye manufacturing clusters into European formulation premiums, compressing margins for solvent-dependent suppliers while elevating certified water-based alternatives. This logistics-cost pathway amplifies price differentiation between REACH-registered and legacy formulations across pharmaceutical packaging tiers.
Pricing Analysis
Certification level creates the primary spread, with FDA 21 CFR indirect food additive and ECHA REACH dual-compliant formulations commanding substantial premiums over single-certified alternatives. Three-tier pricing structure separates pharmaceutical-grade lots from standard industrial grades and economy textile pigments. Pricing pressure stems from PFAS reformulation mandates forcing chemistry transitions. Contract pharmaceutical packers exhibit lowest price sensitivity due to serialization compliance requirements, while promotional gift converters face acute cost compression.
Supply Chain Analysis
Export-control restrictions on microencapsulation-grade aromatic solvents limit German and Japanese chemical cluster flows to Asian formulators. Concentrated leuco dye precursor manufacturing in China and South Korea feeds global formulation, while specialty polymer encapsulation materials concentrate in Germany and the United States. Single-source vulnerability runs through reversible dye precursor supply. Distribution runs through authorized converter networks with direct technical service attachment for pharmaceutical qualification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical serialization mandates and PFAS regulatory inflections are compressing legacy supplier margins while opening premium capture for compliant formulators. This disruption rewards backward integration and digital-integrated positioning.
For Market Incumbents: Insulate formulation leadership through captive microencapsulation chemistry and ECHA REACH portfolio completion ahead of Article 33 disclosure tightening. Chromatic Technologies Inc. and LCR Hallcrest demonstrate defensive positioning via healthcare cold-chain certification depth. Priority investment targets water-based dispersion capacity in Baden-Württemberg to capture EU Green Deal procurement preference.
For New Entrants and Emerging Players: Build out digital-integrated authentication capabilities for California and Massachusetts biotech corridors, where QR-thermal history convergence remains undersupplied. Indian pharmaceutical export packaging for CDSCO-aligned biologics represents the most penetrable geography. Go-to-market leverage rests on asset-light digital printing equipment leasing with embedded ink supply contracts.
For Investors and Strategic Acquirers: Regional coating specialists with captive R&D facilities and pharmaceutical qualification track records offer the strongest acquisition profile. Long-term viability hinges on sustainability credential alignment and digital authentication integration. Monitor PFAS restriction enforcement timelines as the critical inflection signal for legacy supplier distress.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microencapsulation Chemistry | Captive leuco dye precursor supply insulates against Asian pigment concentration risk. |
| Water-Based Formulation Certification | ECHA REACH registration unlocks EU Green Deal procurement preference in German retail. |
| Digital Printing Equipment Partnership | Inkjet integration enables short-run customization for French and UK label producers. |
| Pharmaceutical Serialization Compliance Program | FDA 21 CFR track-and-trace alignment secures California biotech corridor placement. |
| Near-Field Communication Convergence | Printed electronics integration enables smartphone-readable thermal history tracking. |
Research Methodology
Operator-level perspectives from ink formulation chemists, pharmaceutical packaging converters, textile screen printers, and digital printing equipment distributors anchored the qualitative base. Secondary validation drew from ECHA registration databases, FDA 21 CFR indirect food additive filings, METI chemical substance classifications, and customs trade flows for leuco dye precursors. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling product type, application, technology, and end-use dimensions. CAGRs derived from segment-level growth rate aggregation with cross-validation against equipment installation data and formulation patent filings. Pharmaceutical serialization mandate timelines and PFAS restriction enforcement schedules served as industry-specific forecast inputs.
Stress conditions across leuco dye precursor supply disruption, REACH registration cost inflation, and digital printing adoption velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and pharmaceutical cold-chain expansion. Material shifts in EU PFAS restriction scope or FDA track-and-trace mandate acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Ink Resins Market
Printing Inks
Screen Printing Inks Market
Printing Inks
Molecular Ink Market
Printing Inks
North America Printing Inks Market
Printing Inks
Global Digital Fabrication Inkjet Inks Market
Printing Inks
Lithographic Printing Chemicals Market
Printing Inks
Packaging Inks and Coatings Market
Printing Inks
Food Grade Inks Market
Printing Inks
Radiation Curable Inks Market
Printing Inks
Plant Oil Based Printing Inks Market
Printing Inks
Ink-Cartridge Market
Printing Inks
Eco-Friendly Inks Market
Printing Inks
United States Printing Inks Market
Printing Inks
UV Fluorescing Ink Market
Printing Inks
Global Digital Inks Market
Printing Inks
Global UV (Ultraviolet) Curable Inks Market