

Water-Based Metal-Deco Beverage Can Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Water-Based Metal-Deco Beverage Can Inks Market Insights
Water-based resin chemistry is broadening the viable performance envelope for metal-deco graphics on aluminum and steel beverage cans. Sun Chemical leverages captive pigment technology to secure color consistency across high-speed deco lines. INX International Ink Co. sustains formulation leadership through dedicated water-based polymer research centers in North America. Siegwerk anchors European supply with specialized acrylic and polyurethane ink portfolios for two-piece can decorators.
Water-based metal-deco beverage can inks comprise pigment dispersions, acrylic or polyurethane binders, and water-dilutable additives engineered for adhesion, gloss, and chemical resistance on metal substrates at conveyor speeds exceeding 2,000 cans per minute; their primary purpose is to replace solvent-borne systems while maintaining graphic fidelity under pasteurization and refrigeration stress. Solvent-free ink formulations now lead volume as packagers confront volatile organic compound thresholds, while UV curable variants represent the fastest-growing technology tier where energy-cure infrastructure exists. Carbonated drinks and alcoholic beverages concentrate margin pools because these segments demand the highest decoration complexity and regulatory compliance.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-borne ink use in US can manufacturing, while REACH and the EU F-Gas Regulation shape product composition and market access across Europe. China's MEE enforces dual carbon goals that pressure domestic decorators toward water-based conversion. Stakeholders must monitor regulatory divergence between jurisdictions and decide whether to standardize formulations globally or maintain region-specific product lines.
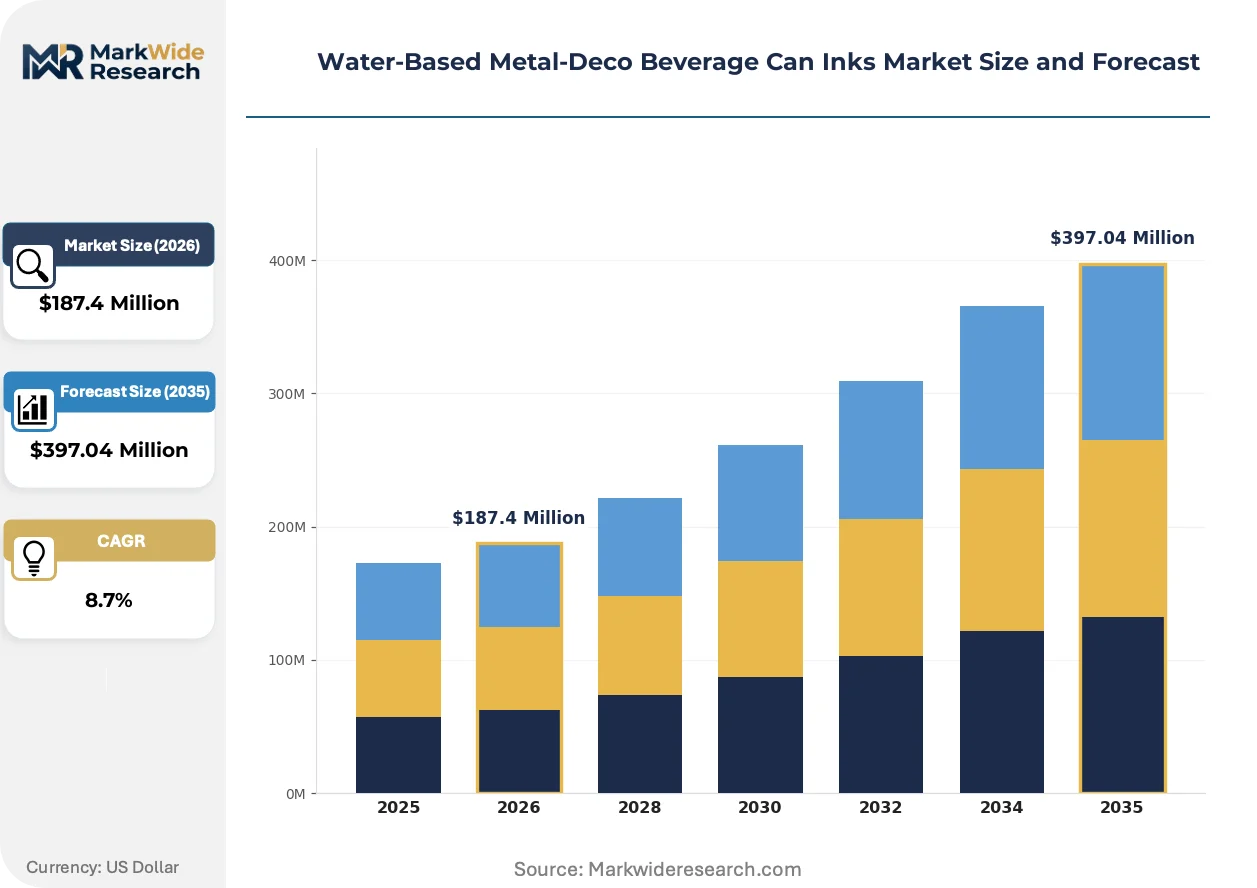
Market Dynamics
Carbonated beverage brands are converting metal-deco production lines to water-based ink systems under pressure from retailer sustainability scorecards and tightening volatile organic compound limits across multiple jurisdictions.
Growth Catalysts
- REACH Phase-Down Mandates:ECHA restrictions on solvent-borne formulations in European can manufacturing are forcing decorators toward compliant water-based alternatives. Germany's KBA enforces among the strictest VOC thresholds for beverage packaging.
- Aluminum Can Demand Surge:Craft beer and hard seltzer producers are expanding decorated can volumes, requiring high-speed deco lines compatible with water-based chemistries. These segments prioritize graphic complexity that water-based systems now deliver.
- Energy-Cure Infrastructure Expansion:UV LED curing systems are integrating with water-based metal-deco lines, enabling faster throughput without thermal drying. This hybrid approach reduces energy consumption and floor space requirements.
Market Restraints
- Acrylic Resin Price Volatility:Water-based polyurethane and acrylic binders face input cost pressure from petrochemical feedstock fluctuations. Formulators cannot fully pass these costs to price-sensitive beverage packagers.
- Asia-Pacific Supply Concentration:Specialty pigment dispersion production clusters in China, creating geographic risk for decorators dependent on just-in-time color matching. MEE environmental inspections periodically disrupt supply.
- Drying Speed Limitations:Water-based systems require longer evaporation periods than solvent-borne alternatives at equivalent line speeds, constraining throughput on legacy deco equipment without retrofit investment.
Strategic Opportunities
- India PLI Scheme Alignment:India's production-linked incentive scheme for advanced chemicals supports domestic water-based ink manufacturing. Local formulators can capture share from imported solvent-borne products.
- UV-Water Hybrid Convergence:Combining water-based vehicles with UV-curable acrylate oligomers enables single-pass decoration with instant cure. This dual-technology approach opens premium applications in retortable cans.
- Direct-to-Decorator Digital Channels:Ink suppliers are bypassing traditional distributor networks to sell formulated dispersions directly to regional can decorators. This channel compression improves technical service responsiveness and margin capture.
Industry Challenges
- Colorimetric Technician Scarcity:Water-based metal-deco requires specialized expertise in pigment wetting and substrate wetting dynamics. Qualified formulation chemists command premium compensation in tight labor markets.
- Deco Line Retrofit Capex Burden:Converting solvent-borne systems requires infrared dryer installation, corona treatment upgrades, and waste-handling system modifications. Smaller decorators face financing constraints for these capital outlays.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water-Based Metal-Deco Beverage Can Inks Market Trends and Innovations
Water-based ink chemistry is advancing through polymer architecture innovation, regulatory compliance engineering, and procurement model transformation that collectively reshape competitive requirements for metal-deco suppliers.
Polyurethane-acrylic hybrid binders are integrating silane coupling agents to improve adhesion on treated aluminum surfaces. Beverage can decorators in North America and Europe are adopting these formulations at accelerating rates for pasteurization-resistant applications. This materials convergence is integrating performance characteristics previously requiring solvent-borne systems, compressing the technical gap between regulatory-compliant and high-performance alternatives.
EPA National Emission Standards for Hazardous Air Pollutants are tightening permissible solvent emissions from can coating operations. US beverage can manufacturers must install add-on control devices or convert to water-based systems to maintain operating permits. Carbonated soft drink decorators face the most compressed compliance timelines, driving capital allocation toward water-based line conversions ahead of 2027 permit renewal cycles.
Long-term supply agreements are replacing spot purchasing for water-based ink volumes as decorators seek price stability amid raw material volatility. Tier-one beverage brands are consolidating supplier relationships to three-year framework contracts with technical service commitments. This procurement consolidation is most pronounced in Germany and the United States, where large can decorators leverage volume concentration to secure dedicated formulation support and inventory pooling arrangements.
Water-Based Metal-Deco Beverage Can Inks Market Segmentation
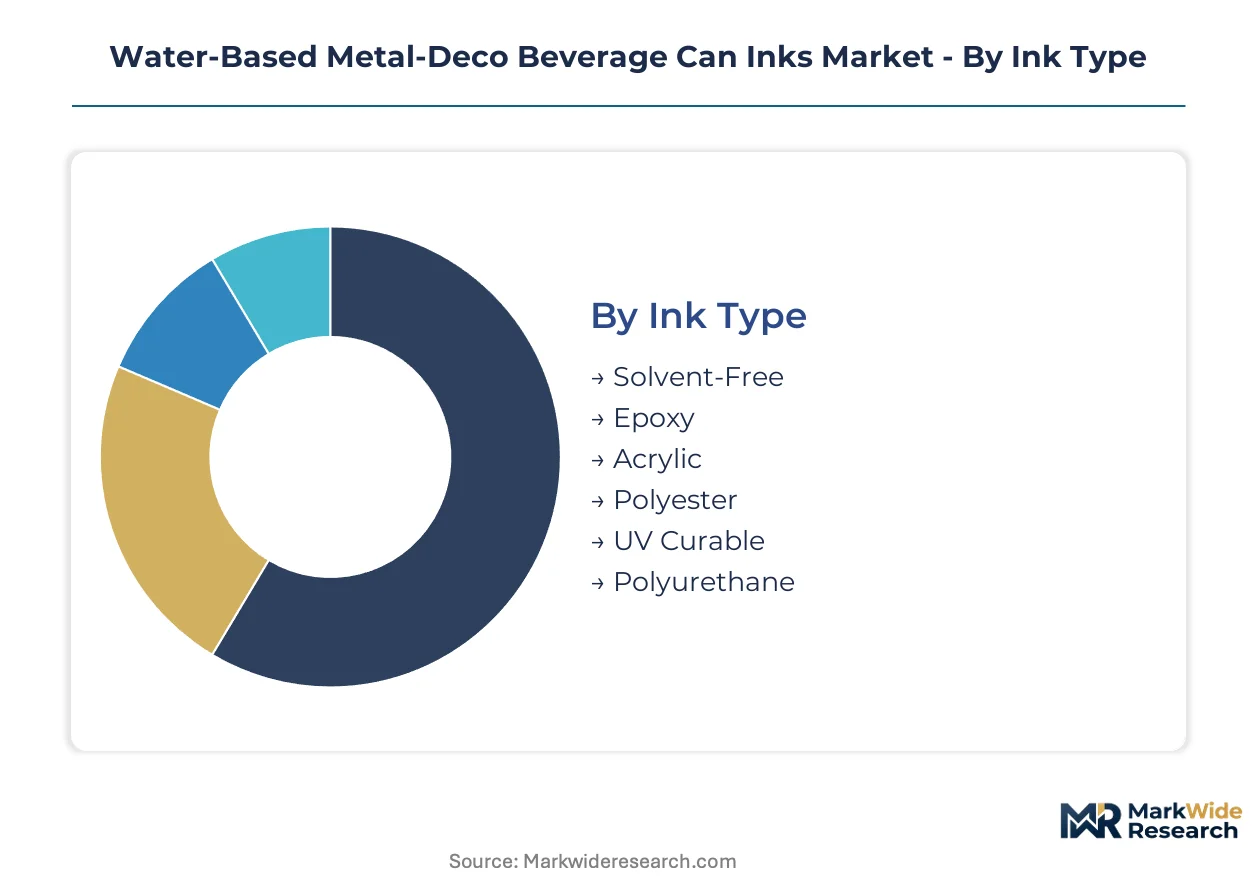
Water-based metal-deco beverage can inks serve distinct performance requirements across formulation chemistries, beverage categories, and supply chain roles. Segmentation reveals where formulation complexity concentrates and which customer types drive specification authority.
Ink Type:
Standalone water-based systems dominate new line installations, while hybrid and energy-cure formats embed into retrofitted solvent-borne infrastructure.
- Solvent-Free:Formulations rely entirely on water-dilutable acrylic or polyurethane binders with zero volatile organic compound contribution. Carbonated drink decorators in Germany specify these for KBA compliance deadlines.
- UV Curable:Water-based vehicles carry acrylate oligomers that polymerize under LED exposure. North American craft brewers adopt these for instant-cure throughput on compact deco lines.
- Acrylic:Cost-effective pigment binding with moderate chemical resistance for standard pasteurization cycles.
- Polyurethane:Superior flexibility and abrasion resistance for retortable can applications.
- Epoxy:Cross-linked systems for aggressive product-fill compatibility in nutritional supplements.
- Polyester:Gloss-optimized formulations for premium alcoholic beverage decoration.
Solvent-Free leads volumes today; UV Curable is gaining share fastest.
End Use Application:
Margin pools concentrate where pasteurization stress and graphic complexity intersect, separating commodity beverage decoration from technical specification markets.
- Carbonated Drinks:High-speed lines exceeding 2,000 cans per minute demand rapid-drying water-based systems with consistent color matching across billion-unit campaigns.
- Alcoholic Beverages:Craft beer and hard seltzer producers require complex multi-color graphics on aluminum cans. Water-based polyurethane hybrids now deliver solvent-borne equivalent adhesion for these pasteurization-resistant applications.
- Energy Drinks:Metallic effect inks and fluorescent pigments create visual differentiation on shelf.
- Bottled Water:Minimal decoration requirements favor standard acrylic formulations at volume pricing.
- Juices:Acidic product-fill compatibility drives epoxy-polyurethane hybrid specification.
- Nutritional Supplements:Retort processing demands maximum thermal and chemical resistance from ink systems.
Carbonated Drinks commands absolute volume; Alcoholic Beverages shows the steepest expansion trajectory.
Packaging Format:
Decoration scope varies from individual can identity to secondary packaging integration, with ink specification authority residing at different supply chain tiers.
- Single Can:Direct metal-deco graphics applied at beverage filling facilities. Brand owners specify ink systems for maximum shelf impact.
- Multi-Pack:Carrier graphics and promotional messaging on four- and six-pack configurations.
- Sleeve Label:Heat-shrinkable film decoration that reduces direct metal-deco coverage but requires compatible overprint varnishes.
- Shrink Wrap:Full-body secondary packaging with minimal primary can decoration requirements.
Single Can dominates specification value; Sleeve Label is climbing fastest as packagers seek material reduction.
Customer Type:
Technical decision-making authority fragments across outsourced decoration specialists and integrated beverage manufacturers with captive printing operations.
- Packagers:Integrated beverage manufacturers with in-house deco lines. These customers drive formulation standardization across multi-plant networks.
- Contract Manufacturers:Third-party decorators serving multiple beverage brands. They prioritize ink versatility across shifting customer portfolios.
- Brand Owners:Consumer goods companies specifying ink systems for toll-manufactured production. They enforce sustainability scorecard compliance through supplier selection.
- Labelers:Specialists in sleeve and shrink-wrap application with limited direct metal-deco exposure.
- Specialty Printers:Niche decorators for limited-edition and promotional can runs requiring rapid color change capability.
Packagers control the largest volume commitment; Brand Owners are expanding specification authority fastest through direct supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KBA-enforced VOC thresholds and beverage can manufacturing clusters anchor European water-based ink adoption. Conversion timelines concentrate in industrial centers where decorators face compressed compliance deadlines.
United States
Carbonated soft drink decorators drive water-based line conversions ahead of 2027 EPA permit renewal cycles. The National Emission Standards for Hazardous Air Pollutants constrain solvent-borne ink use across Midwestern can manufacturing corridors. Ohio and Illinois house concentrated deco line retrofit activity as packagers install infrared drying systems.
Germany
Strict KBA volatile organic compound limits force beverage can decorators toward solvent-free formulations faster than neighboring markets. REACH Phase-Down mandates from ECHA accelerate compliant ink adoption across Baden-Württemberg and Bavaria printing clusters. Stuttgart and Munich anchor specialized acrylic and polyurethane ink demand from premium alcoholic beverage producers.
China
Dual carbon goals from MEE pressure domestic decorators toward water-based conversion in Yangtze River Delta manufacturing zones. Environmental inspections periodically disrupt specialty pigment dispersion supply from concentrated production clusters. Shanghai and Suzhou beverage can facilities lead technical adoption of hybrid UV-water curing systems.
India
Production-linked incentive schemes for advanced chemicals support domestic water-based ink manufacturing expansion. FSSAI packaging safety requirements align with solvent-free formulation preferences among Mumbai and Ahmedabad beverage packagers. Maharashtra and Gujarat industrial corridors attract regional formulator investment to replace imported solvent-borne products.
Japan
Craft beer and hard seltzer volume expansion drives decorated aluminum can demand through Tokyo and Osaka deco facilities. METI industrial standards encourage low-emission printing technologies across Kanto and Kansai manufacturing belts. Yokohama-based decorators specify polyurethane-acrylic hybrid binders for pasteurization-resistant applications.
Water-Based Metal-Deco Beverage Can Inks Market Competitive Landscape
Global majors compete with regional champions across formulation technology and regulatory compliance capabilities. The vendor base organizes around three tiers: integrated chemical conglomerates with captive pigment operations, specialized ink formulators with dedicated polymer research infrastructure, and regional decorators with backward-integrated ink production. Consolidation pressures intensify as beverage brands consolidate supplier relationships to three-year framework contracts. Technology licensing and dedicated technical service partnerships represent dominant competitive moves for market access.
Among integrated chemical conglomerates, Sun Chemical and DIC Corporation exemplify archetypes combining pigment dispersion capabilities with formulation expertise. Specialized ink formulators include INX International Ink Co. and Siegwerk, occupying positions defined by dedicated water-based polymer research centers and regional compliance engineering. These named entities anchor competitive dynamics without exhausting the full participant set.
| Leading Market Players |
|---|
| Sun Chemical |
| INX International Ink Co. |
| Toyo Ink SC Holdings |
| Flint Group |
| Siegwerk |
| Hubergroup |
| DIC Corporation |
| Sakata INX |
| T&K Toka |
| Others |
Pricing and Supply Chain Analysis
UV LED curing infrastructure integration is compressing drying energy costs while concentrating supply leverage among decorators with capital for hybrid line retrofits. This technology transition simultaneously reshapes cost economics and supply concentration by favoring integrated packagers over fragmented contract decorators.
Pricing Analysis
Acrylic resin and polyurethane binder input costs pass through incompletely to beverage packagers due to contract manufacturer price sensitivity. Three-tier pricing structure across premium polyurethane, standard acrylic, and economy epoxy formulations reflects certification grade and volume scale differentiation. Pricing pressure stems from petrochemical feedstock volatility that formulators cannot fully recover. Contract manufacturers exhibit highest price sensitivity; integrated packagers with three-year framework contracts absorb premiums for dedicated technical service.
Supply Chain Analysis
Freight costs from concentrated specialty pigment dispersion production in China elevate landed costs for European and North American decorators. Supply draws from China, Germany, and India for pigment dispersions, acrylic resins, and polyurethane binders. Single-source vulnerability concentrates in Yangtze River Delta pigment clusters subject to MEE environmental inspection disruptions. Distribution runs through direct-to-decorator digital channels that bypass traditional distributor networks for regional can decorators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in solvent-free formulation tiers where REACH compliance premiums offset acrylic resin cost volatility. Water-based conversion capex requirements filter out price-competitive contract manufacturers, concentrating value capture among integrated packagers.
For Market Incumbents: Cement formulation standardization across multi-plant networks to lock in three-year framework contracts with tier-one beverage brands. Deepen backward integration into captive pigment dispersion production to insulate margins from China supply disruptions. Prioritize polyurethane-acrylic hybrid R&D investment to defend against emerging UV-curable specialists threatening pasteurization-resistant applications. For New Entrants and Emerging Players: Regional can decorators represent the most penetrable channel partner type for bypassing established distributor relationships. Target India's Maharashtra and Gujarat industrial corridors where PLI scheme subsidies reduce domestic manufacturing cost disadvantages. Pursue toll-manufacturing partnerships with beverage brands seeking direct supplier relationships to enforce sustainability scorecard compliance. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap specialized ink formulators with dedicated water-based polymer research infrastructure but limited geographic diversification. Long-term viability across the analysis window hinges on regulatory compliance engineering capabilities rather than commodity volume scale. Acquisition target archetypes include European polyurethane ink specialists facing KBA compliance-driven consolidation pressure. Monitor ECHA Phase-Down mandate enforcement velocity as the critical inflection indicator for accelerated water-based conversion capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Dispersion | Captive supply of colorants insulates Sun Chemical and DIC Corporation from China environmental inspection disruptions. |
| UV-Water Hybrid Curing System Deployment | Combining water-based vehicles with LED curing opens retortable can applications for North American craft brewers. |
| Direct-to-Decorator Digital Channel Launch | INX International Ink Co. and Siegwerk bypass distributors to improve technical service responsiveness and margin capture. |
| Long-term Framework Contract Consolidation | Three-year agreements with technical service commitments lock in volume concentration among German and US packagers. |
| Polyurethane-Acrylic Hybrid R&D Investment | Silane coupling agent integration delivers solvent-borne equivalent adhesion for pasteurization-resistant alcoholic beverage cans. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with plant managers at can manufacturing facilities, procurement leads at beverage brand headquarters, technical R&D directors at ink formulators, and distribution channel partners. Secondary validation draws from EPA NESHAP filings, ECHA REACH registration databases, SEC 10-K disclosures from listed chemical conglomerates, and customs trade data tracking acrylic resin and pigment dispersion flows. Bottom-up volume estimates triangulate against top-down addressable market calculations.
Rate-of-change decomposition separates volume growth from price-mix effects across the analysis window. The analytical framework models ink type, end-use application, packaging format, and customer type segmentation dimensions. CAGRs derive from fitted growth curves incorporating regulatory compliance deadline clustering, line retrofit capex cycles, and beverage category volume trajectories. Industry-specific forecast inputs include KBA VOC threshold enforcement schedules and MEE environmental inspection frequency patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical feedstock volatility and regulatory divergence between jurisdictions. Forecasts reflect assumptions about ECHA Phase-Down mandate adherence, EPA permit renewal compliance rates, and dual carbon goal enforcement intensity from China's MEE. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.