
 UV Fluorescing Ink Market | 2026-2036
UV Fluorescing Ink Market Size, Share, and Industry Trends Forecast 2026-2036
UV Fluorescing Ink Market Analytics
Water-based solvent systems are recalibrating cost structures across the UV fluorescing ink supply chain as converters seek lower-VOC alternatives. Sun Chemical leverages its pigment synthesis capabilities to control raw material quality from source to finished ink. SICPA Holding SA anchors its position through deep specialization in security printing applications for government documents. Gleitsmann Security Inks GmbH differentiates via precision manufacturing of high-performance formulations for authentication systems.
UV fluorescing ink comprises photoluminescent pigments suspended in carrier vehicles that emit visible light when exposed to ultraviolet radiation, typically formulated with europium-doped strontium aluminate or organic fluorescent dyes for optimal emission intensity and duration. The technology serves primarily as a covert authentication layer in security documents, packaging verification, and brand protection systems where machine-readable fluorescence provides non-destructive identification. Specialty ink formulations command premium positioning due to custom wavelength engineering for exclusive detector pairing, while security printing applications concentrate margin pools through multi-layer authentication requirements. Water-based delivery systems are gaining formulation share as environmental compliance tightens across European and North American converting operations.
FDA oversees indirect food contact migration limits for packaging inks in the United States, while REACH and RoHS frameworks in Europe restrict hazardous substance content in fluorescent pigment chemistries. ECHA substance evaluations are extending compliance timelines for reformulation of legacy photoinitiator packages. Security printing mandates from central banks and tax authorities across multiple jurisdictions are hardening demand specifications for machine-readable fluorescence characteristics. Stakeholders must monitor evolving chemical restriction lists and detector standardization protocols to sustain formulation relevance across regional compliance regimes.
Market Dynamics
Water-based solvent systems are compressing formulation economics as converters across security printing and packaging authentication confront tightening VOC emission ceilings. REACH substance evaluations are extending reformulation timelines for legacy photoinitiator packages.
Growth Catalysts
- REACH RoHS chemical restrictions:European hazardous substance frameworks are forcing pigment chemistry innovation, opening premium positioning for compliant reformulations.
- Central bank security mandates:Machine-readable fluorescence specifications for banknote authentication are hardening demand requirements across government document issuers.
- Germany security printing cluster:Concentration of anti-counterfeiting technology providers in Baden-Württemberg and Bavaria is amplifying specialized ink demand.
Market Restraints
- Europium supply concentration:Rare earth element dependency for strontium aluminate doping creates input cost volatility tied to Chinese export quotas.
- Photoinitiator regulatory friction:ECHA substance evaluations are delaying commercialization of reformulated UV-curable packages.
- Organic dye substitution threat:Lower-cost fluorescent dyes are pressuring inorganic pigment pricing in non-security packaging applications.
Strategic Opportunities
- India pharmaceutical serialization:Track-and-trace mandates for drug packaging are opening authentication ink demand in an underpenetrated geography.
- Tax stamp application expansion:Excise verification programs across beverage and tobacco sectors are creating emerging volume pools.
- NMPA medical device labeling:China's medical product authentication requirements are generating regulatory tailwind for covert marking technologies.
Industry Challenges
- Fluorescence spectroscopy skill scarcity:Formulation chemists with expertise in excitation-emission matrix optimization remain concentrated among legacy security ink specialists.
- Detector standardization delays:Absence of unified wavelength protocols across authentication equipment vendors complicates exclusive detector pairing strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Fluorescing Ink Market |
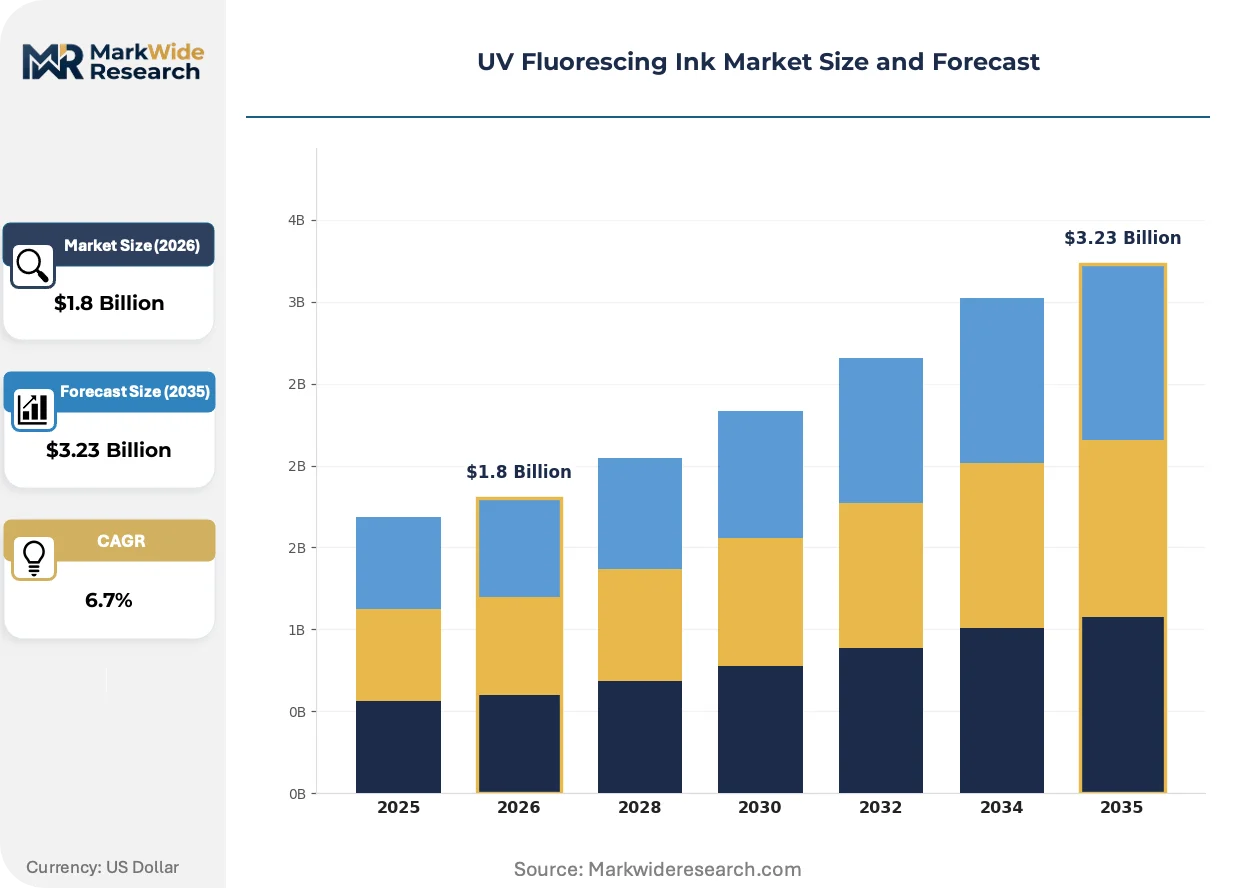
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glow-in-the-Dark Ink, High-Performance Ink, Specialty Ink, Water-Based Ink Application: Packaging, Labels, Security Printing, Promotional Materials Delivery Mode: Direct Supply, Online Retail, Distributor Network, Trade Shows End User: Manufacturers, Retailers, Promotional Companies, Educational Institutions |
| Companies Covered | Sun Chemical, SICPA Holding SA, DIC Corporation, Gleitsmann Security Inks GmbH, ANY Security Printing Company, Siegwerk Druckfarben AG & Co. KGaA, Flint Group, INX International Ink Co., Microtrace LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Fluorescing Ink Market Evolving Landscape
Formulation science is converging with environmental compliance engineering as water-based delivery systems displace solvent-borne alternatives across authentication and packaging segments.
Photoluminescent pigment synthesis is unifying emission intensity control with carrier vehicle compatibility. Security printing specialists are adopting these integrated systems at accelerated pace to meet central bank fluorescence specifications. The technology is unifying previously separate formulation and application engineering functions, compressing supplier qualification timelines for authentication system integrators.
REACH authorization procedures are extending compliance timelines for legacy photoinitiator chemistries. Ink manufacturers are accelerating reformulation investments to secure continuity of supply for European security printing customers. Water-based UV fluorescing formulations are capturing disproportionate development resources as converters anticipate ECHA substance restriction expansions.
Authentication system procurement is compressing vendor qualification cycles as central banks and tax authorities consolidate supplier panels. Brand protection managers are displacing spot-buying arrangements with multi-year formulation partnerships. This pattern is most visible across German and Swiss security printing clusters where detector-ink pairing requirements favor incumbent relationships.
UV Fluorescing Ink Market Segmentation
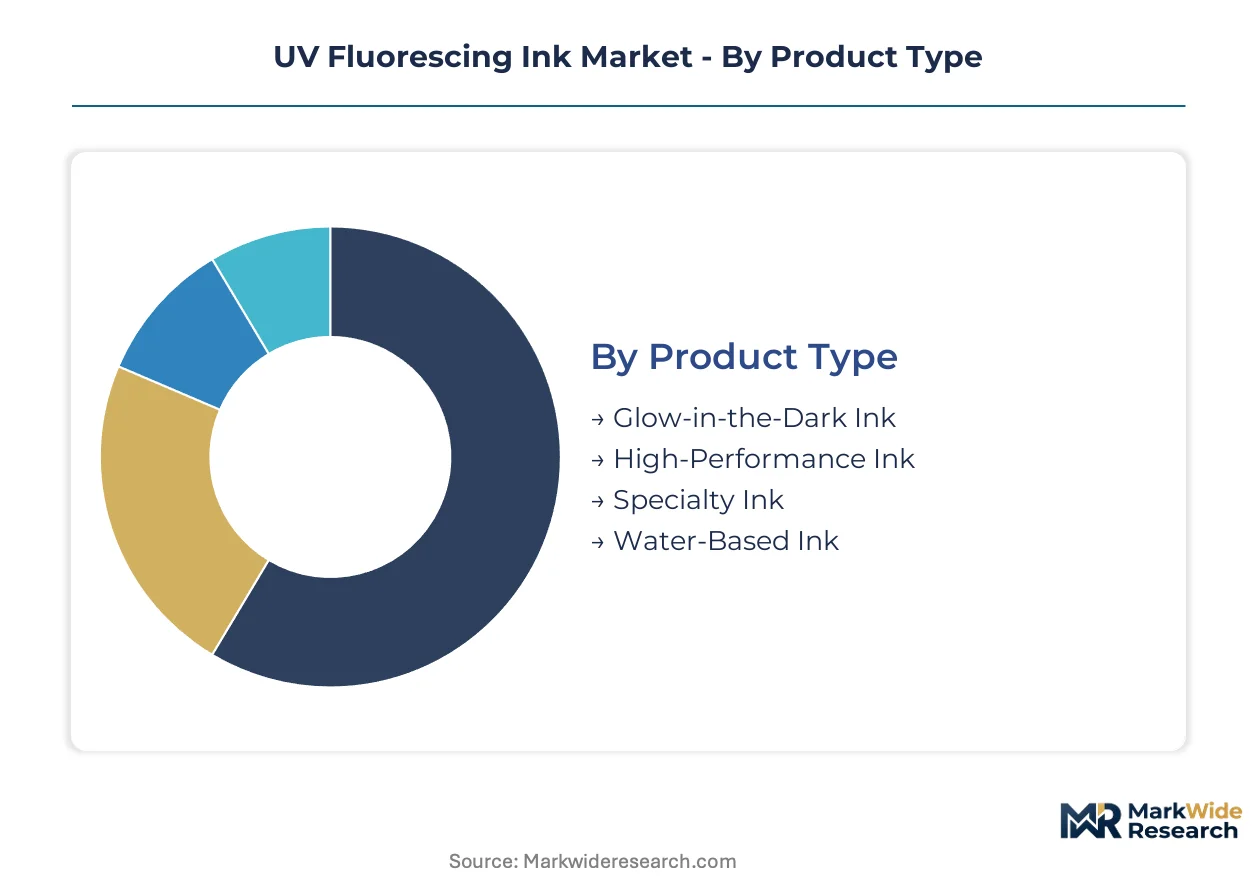
UV fluorescing ink segmentation reveals how formulation chemistry, application security requirements, and channel economics fragment procurement patterns. Buyers stratify across covert authentication systems, visible decorative effects, and regulatory-compliant packaging solutions with distinct technical specifications and price thresholds.
Product Type:
Customization intensity spans from commodity water-based formulations to engineered specialty systems with exclusive wavelength signatures.
- Specialty Ink:Engineered with precise excitation-emission profiles for detector-specific authentication systems. Central banks in Germany and Switzerland specify custom europium-doped formulations for banknote security threads, with procurement cycles extending 18-24 months for vendor qualification.
- Water-Based Ink:Carrier vehicles use aqueous resin systems to meet REACH VOC thresholds. German converters in Baden-Württemberg are displacing solvent-borne alternatives as ECHA substance evaluations tighten photoinitiator approvals.
- High-Performance Ink:Extended afterglow duration through optimized strontium aluminate particle size distribution.
- Glow-in-the-Dark Ink:Consumer-facing decorative applications with visible phosphorescence rather than covert UV response.
Leading the category by volume: Water-Based Ink. Expanding most quickly: Specialty Ink.
Application:
Security intensity determines margin structure, with covert authentication commanding premium positioning over visible decorative uses.
- Security Printing:Machine-readable fluorescence for government documents, tax stamps, and brand protection. India's pharmaceutical serialization mandates under CDSCO track-and-trace rules are opening new volume pools for authentication ink integration.
- Packaging:Covert verification layers for high-value consumer goods. China's NMPA medical device labeling requirements are generating demand for non-destructive authentication marking.
- Labels:Anti-counterfeiting features for pharmaceutical and luxury goods verification.
- Promotional Materials:Visible UV-reactive effects for event marketing and consumer engagement.
Dominant by revenue: Security Printing. Steepest expansion trajectory: Packaging.
Delivery Mode:
Channel selection tracks buyer sophistication, with security printing specialists favoring direct technical partnership over transactional procurement.
- Direct Supply:Formulation partnerships with dedicated technical service for authentication system integrators. Swiss and German security printing clusters consolidate procurement through multi-year supply agreements with embedded detector-ink pairing validation.
- Distributor Network:Regional inventory positioning for packaging converters with standardized specifications.
- Online Retail:Small-volume decorative and educational product segments.
- Trade Shows:Specification development channel for emerging authentication applications.
Highest volume flow: Distributor Network. Fastest channel growth: Direct Supply.
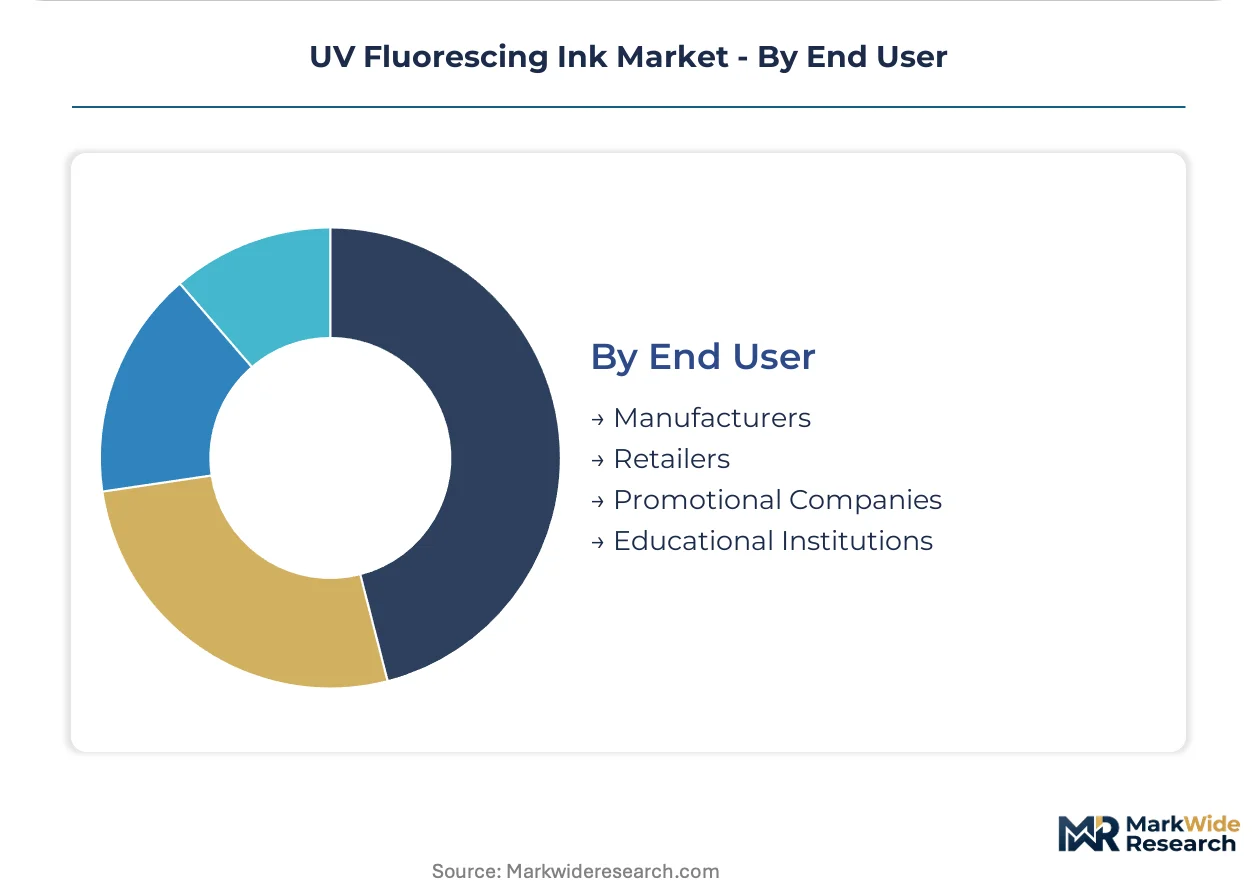
End User:
Technical capability divides buyers between self-integrating authentication engineers and outsourced security printing services.
- Manufacturers:Brand owners integrating covert verification into packaging lines. Beverage and tobacco excise programs across multiple jurisdictions are hardening demand specifications for machine-readable tax stamp authentication.
- Promotional Companies:Event marketing and consumer engagement applications with visible fluorescence effects.
- Retailers:Private label authentication and supply chain verification programs.
- Educational Institutions:Research and teaching applications for photoluminescent materials.
Largest procurement base: Manufacturers. Gaining share fastest: Promotional Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Security printing demand concentrates in Germany due to its dense cluster of anti-counterfeiting technology providers and central bank authentication requirements. Tax stamp programs across multiple jurisdictions are expanding machine-readable fluorescence specifications.
Germany
REACH and RoHS frameworks are tightening chemical composition requirements for fluorescent pigments used in banknote security threads. ECHA substance evaluations are extending reformulation timelines for legacy photoinitiator packages. Baden-Württemberg and Bavaria host concentrated security printing specialists serving European central banks.
United States
FDA oversees indirect food contact migration limits for packaging inks while brand protection managers expand covert verification layers. Pharmaceutical serialization mandates under DSCSA are hardening authentication specifications. The Midwest and Northeast corridors concentrate converter operations seeking lower-VOC alternatives.
India
CDSCO track-and-trace rules for pharmaceutical packaging are opening authentication ink demand in an underpenetrated geography. The country's national pharmaceutical regulator is expanding serialization requirements for drug exports. Maharashtra and Gujarat host expanding packaging converter capacity targeting compliance-driven brand owners.
China
NMPA medical device labeling requirements are generating regulatory tailwind for covert marking technologies in healthcare packaging. GB standards for product authentication are hardening across beverage and tobacco excise programs. The Yangtze River Delta concentrates security ink formulation capacity serving domestic and export markets.
Switzerland
Swissmedic oversight of pharmaceutical packaging is reinforcing demand for non-destructive authentication marking. The country's precision manufacturing heritage supports specialized ink formulation for high-value document security. The Zurich-Basel corridor anchors detector-ink pairing validation for European authentication system integrators.
UV Fluorescing Ink Market Competitive Landscape
Strategic partnerships dominate the current landscape as authentication system integrators consolidate supplier panels and compress vendor qualification cycles. The vendor base stratifies across three tiers: multinational chemical conglomerates with captive pigment synthesis, specialized security ink houses with deep government relationships, and regional converters with standardized formulation capabilities. Portfolio diversification and technology licensing represent the dominant competitive moves as players seek detector-specific wavelength engineering capabilities.
Within the specialized security ink tier, SICPA Holding SA and Gleitsmann Security Inks GmbH exemplify deep specialization in government document authentication. Sun Chemical occupies a position among multinational chemical groups leveraging upstream pigment synthesis capabilities. These three entities represent distinct archetypes: the Swiss-headquartered security specialist with entrenched central bank relationships, the German GmbH focused on precision manufacturing for authentication systems, and the American chemical conglomerate with integrated raw material control.
| Leading Market Players |
|---|
| Sun Chemical |
| SICPA Holding SA |
| DIC Corporation |
| Gleitsmann Security Inks GmbH |
| ANY Security Printing Company |
| Siegwerk Druckfarben AG & Co. KGaA |
| Flint Group |
| INX International Ink Co. |
| Microtrace LLC |
| Others |
Value Network & Pricing Analysis
REACH substance evaluations and ECHA authorization procedures gate qualified supply for European security printing customers, restricting premium-tier pricing access to reformulation-capable manufacturers with compliant photoluminescent pigment packages.
Pricing Analysis
Volume flows concentrate in standardized water-based formulations while margins pool in specialty ink tiers with exclusive wavelength engineering. Three-tier pricing structure across premium, standard, and economy levels separates detector-specific authentication systems from commodity packaging applications. Price differentiation hinges on certification grade for central bank security mandates and customization level for covert verification systems. Cost compression in water-based segments is intensifying because converters prioritize REACH-compliant alternatives, though brand owners in pharmaceutical serialization show limited price sensitivity for machine-readable fluorescence specifications.
Supply Chain Analysis
Dual-sourcing requirements from authentication system integrators mandate multi-supplier qualification for europium-doped strontium aluminate pigments, compressing vendor consolidation timelines. Raw material concentration centers on China for rare earth element refining, Germany for photoluminescent pigment synthesis, and Switzerland for detector-ink pairing validation. Supply chain risk rests on single-source vulnerability for europium feedstock tied to export quota volatility. Distribution runs through direct technical partnerships with security printing specialists and regional distributor networks for packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into photoluminescent pigment synthesis represents the decisive upstream lever as ink manufacturers race to secure raw material continuity and custom wavelength engineering capabilities.
For Market Incumbents: Anticipate photoinitiator regulatory friction by accelerating reformulation investments ahead of ECHA substance restriction expansions. Secure captive supply of europium-doped strontium aluminate through long-term offtake agreements with Chinese rare earth refiners to defend margin position against organic dye substitution threats in non-security packaging tiers.
For New Entrants and Emerging Players: Capture underpenetrated volume pools in India's pharmaceutical serialization market under CDSCO track-and-trace mandates, where authentication ink integration lags European benchmarks. Lead with water-based formulation capabilities to bypass incumbent solvent-borne supply relationships and qualify directly with Maharashtra and Gujarat packaging converters.
For Investors and Strategic Acquirers: ECHA authorization timeline announcements for legacy photoinitiator chemistries are the leading indicator that reformulation-capable specialists will command scarcity premiums. Target acquisition candidates with integrated pigment synthesis and established central bank vendor qualification status. Watch for detector standardization protocol convergence as the signal that exclusive wavelength engineering moats are narrowing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Synthesis | Sun Chemical's captive raw material control secures supply continuity for European security printing customers facing REACH compliance deadlines. |
| Water-Based Formulation Expansion | German converters in Baden-Württemberg displace solvent-borne alternatives as ECHA evaluations tighten photoinitiator approvals. |
| Detector-Ink Pairing Validation Partnerships | Swiss and German authentication system integrators consolidate supplier panels through multi-year technical service agreements. |
| Geographic Expansion into India Pharmaceutical Serialization | CDSCO track-and-trace mandates open authentication ink demand in packaging converter clusters across Maharashtra and Gujarat. |
| Long-Term Supply Agreement for Rare Earth Feedstock | Europium supply concentration creates input cost volatility that qualified suppliers must hedge through Chinese refinery relationships. |
Research Methodology
Document review covered trade association publications from European Printing Ink Association and National Association of Printing Ink Manufacturers, complemented by interviews with security printing specialists, formulation chemists at authentication ink manufacturers, procurement managers at central bank security printers, and regulatory affairs leads navigating ECHA substance evaluations. Secondary validation drew from customs data on photoluminescent pigment trade flows, SEC filings of chemical conglomerates with ink divisions, and REACH authorization status databases. Bottom-up volume modeling across formulation chemistry tiers and top-down value triangulation against security printing expenditure patterns anchored the analysis.
Cross-referencing historical authentication system procurement cycles against panel input from government document issuers shaped the projection framework. Segmentation dimensions modeled include product type chemistry tiers, application security intensity levels, delivery mode channel structures, and end-user technical capability clusters across the analysis window. CAGRs were derived from elasticity-adjusted demand curves incorporating central bank security mandate timelines and pharmaceutical serialization regulatory rollout schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to europium export quota volatility and detector wavelength standardization convergence. Deviation in ECHA authorization timelines for legacy photoinitiator packages would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Global Decorative Print Market
Printing Inks
Global Water-Based Inks Market
Printing Inks
Thermal Inkjet Inks Market
Printing Inks
United States Flexographic Printing Market
Printing Inks
Food Marking Inks Market
Printing Inks
Global Gravure Printing Inks Market
Printing Inks
Screen Printing Inks Market
Printing Inks
Water-Borne Inks and Paints Market
Printing Inks
Textile Printing Ink Market
Printing Inks
Lithography Inks Market
Printing Inks
Solvent-Based Inks Market
Printing Inks
Global Low Migration Inks Market
Printing Inks
Offset Ink Market
Printing Inks
Global Conductive Inks Market
Printing Inks
Security Printing Market
Printing Inks
Global Ceramic Inks Market