
 Global Digital Inks Market | 2026-2036
Global Digital Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Inks Market Foresight
REACH compliance is shifting the cost-of-entry calculus for European ink formulators, forcing reformulation investments that favor established producers with dedicated regulatory teams. Sun Chemical leverages its vertically integrated pigment operations to absorb raw-material volatility. Nazdar Company specializes in narrow-web UV inks for label converters seeking migration-compliant food packaging solutions. Fujifilm Holdings Corporation anchors the high-end segment with its proprietary UV LED curing chemistry.
Digital inks comprise pigment- or dye-based liquid formulations engineered for precise deposition through piezoelectric, thermal bubble, or continuous inkjet printheads, with viscosity typically controlled between 3 and 15 centipoise at jetting temperature to ensure droplet formation without satellite splatter. Their primary purpose is to enable on-demand, variable-data printing across substrates without analog plate or screen setup. UV-curable formulations now dominate packaging decoration applications where instant polymerization supports high-speed converting lines. Latex inks represent the fastest-growing category in large format printing as water-based chemistry satisfies indoor air-quality mandates without sacrificing outdoor durability. Solvent inks retain share in textile printing through sublimation transfer, though water-based dye alternatives are displacing them in European apparel hubs.
EMA migration limits, EPA Method 24 VOC testing, and China's GB standards collectively constrain formulation freedom while creating certification barriers for unqualified suppliers. The EU F-Gas Regulation further pressures solvent-based systems by restricting fluorinated propellants used in some aerosol-dispensed ink products. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance investments optimized for REACH may not satisfy China's evolving SAMR labeling requirements or upcoming US state-level extended producer responsibility frameworks for printed packaging.
Market Dynamics
UV LED curing chemistry is compressing drying times from minutes to seconds, forcing solvent ink producers to defend installed base through migration-compliant reformulation investments.
Growth Catalysts
- REACH VOC limits:German packaging converters are replacing solvent systems with UV-curable inks to meet ECHA-mandated emission ceilings, expanding addressable demand for compliant formulations.
- Dye-sublimation textile clusters:Guangdong province manufacturers operate dense printer networks for fast-fashion export production, sustaining concentrated ink consumption.
- UV LED hardware penetration:Narrow-web label presses across European converting facilities are standardizing on 395nm curing wavelengths, pulling compatible ink formulations through the installed base.
Market Restraints
- Pigment raw material concentration:Specialty photoinitiator supply concentrates among Chinese chemical producers, exposing formulators to intermediate price volatility and qualification delays.
- Technical viscosity ceiling:Piezoelectric printheads impose strict 3-15 centipoise operating windows, restricting formulation freedom for high-pigment-load applications.
- Substitution by aqueous latex:Large-format signage printers in indoor environments are migrating to water-based latex systems that satisfy air-quality mandates without UV hardware investment.
Strategic Opportunities
- India packaging conversion:Domestic label and flexible packaging growth is outpacing local UV ink production capacity, creating import substitution potential for qualified suppliers.
- Food-contact migration compliance:EFSA-positive list expansion for photoinitiators opens new substrate applications previously blocked by safety certification gaps.
- Water-based dye-sublimation convergence:European apparel hubs are piloting aqueous alternatives to solvent transfer inks, requiring reformulation partnerships with textile chemistry specialists.
Industry Challenges
- Regulatory divergence management:Formulators must maintain parallel certification tracks for REACH, EPA Method 24, and China's GB standards without unified testing protocols.
- Printhead-ink compatibility testing:OEM qualification cycles for new piezoelectric architectures extend 18-24 months, compressing product lifecycle returns.
- Fluorinated propellant phaseout:EU F-Gas Regulation restrictions are forcing aerosol-dispensed product lines into hardware redesign or chemistry substitution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Inks Market |
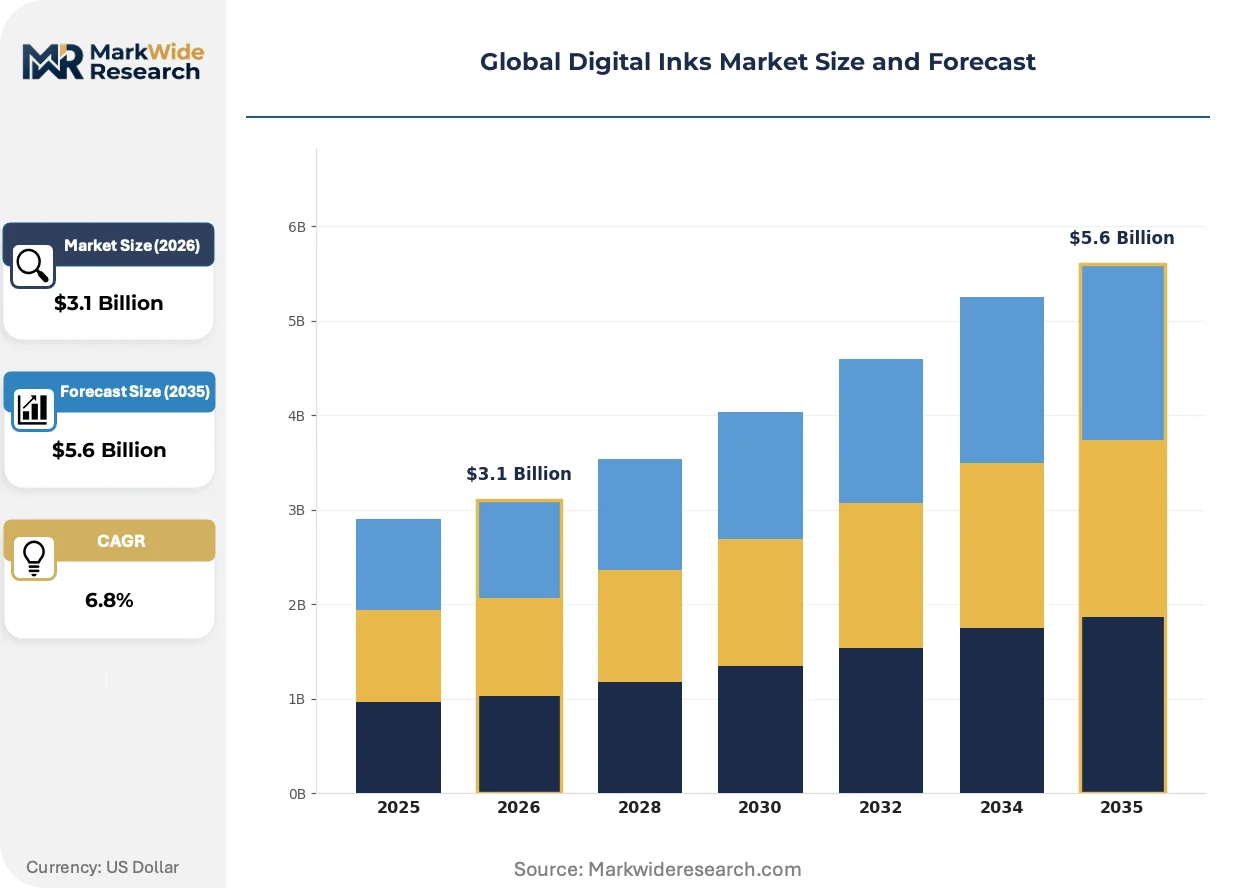
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ink Type: Solvent, UV, Dye, Latex, Sublimation, Thermal Technology: Piezoelectric, Thermal Bubble, Continuous Inkjet, Drop-on-Demand, Electrostatic Application: Textile Printing, Packaging Decoration, Labeling, Large Format Printing, Fine Art, Commercial Printing End User: Print Service Providers, Advertising Agencies, Textile Manufacturers, Packaging Companies, Publishing Houses |
| Companies Covered | Sun Chemical, INX International Ink Co, Toyo Ink SC Holdings Co., Nazdar Company, Fujifilm Holdings Corporation, Marabu, Siegwerk Druckfarben AG & Co. KGaA, JK Group, Flint Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Inks Market Shifts & Advancements
Formulation chemistry, hardware curing systems, and regulatory compliance frameworks are locking into interdependent development cycles that favor integrated suppliers over component specialists.
UV LED curing systems are converging with low-migration photoinitiator packages to enable direct food-contact printing on flexible packaging. Narrow-web converters in Germany and Italy are retrofitting existing flexo presses with 395nm arrays at accelerating pace. This hardware-chemistry pairing is compressing the addressable market for thermal drying ovens and their associated solvent ink volumes.
China's GB standards for printed packaging labeling are tightening disclosure requirements for ink constituents and migration test results. SAMR enforcement is expanding beyond food-contact applications into cosmetics and pharmaceutical secondary packaging. Domestic Chinese ink producers are building in-house analytical capabilities to preempt certification delays that currently favor established multinational suppliers.
Brand owners are consolidating specification authority at headquarters level, stripping individual plant procurement teams of formulation discretion. Centralized technical approval teams now mandate qualified supplier lists across converting networks in North America and Western Europe. This concentration is most visible in beverage and personal care packaging, where sustainability scorecards increasingly weight ink chemistry selection alongside substrate recyclability.
Global Digital Inks Market Segmentation
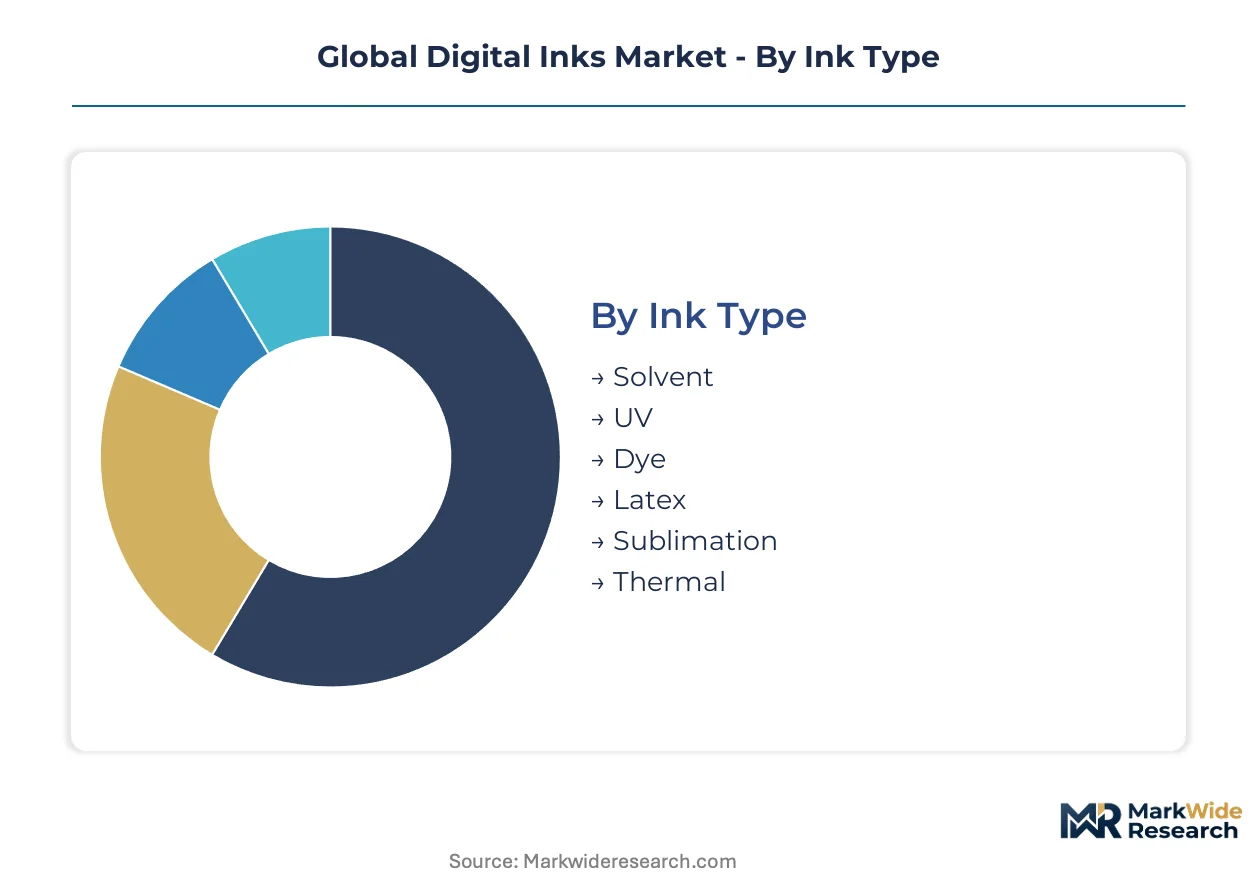
Digital ink formulation chemistry, printhead physics, and substrate compatibility requirements create distinct technical boundaries between segments. Each segmentation axis carries different margin profiles, regulatory exposure, and hardware dependency structures that reshape competitive positioning.
Ink Type:
Formulation chemistry determines curing mechanism, substrate adhesion, and regulatory compliance burden across installed printer bases.
- UV:Photoinitiator-loaded acrylate oligomers polymerize instantly under 395nm LED arrays, enabling high-speed flexible packaging lines in Germany and Japan where REACH and JIS VOC ceilings are tightening. Migration-compliant variants for direct food contact command specification authority from centralized brand technical teams.
- Latex:Water-based polymer dispersions with pigment loads optimized for thermal inkjet heads, expanding most quickly in North American and European large-format signage as indoor air-quality mandates displace solvent alternatives without requiring UV hardware capital.
- Solvent:Glycol ether and ketone-based carriers with dissolved dyes for aggressive substrate wetting on uncoated vinyl and banner materials, retaining share in outdoor graphics where weathering resistance trumps emission concerns.
- Dye:Low-viscosity aqueous formulations for absorbent substrates, concentrated in desktop document printing and fine art reproduction where color gamut breadth outweighs lightfastness limitations.
- Sublimation:Disperse dye suspensions engineered for transfer paper release and polyester fiber fixation, clustered in Guangdong province textile export manufacturing.
- Thermal:Wax- or resin-based solid inks melted on demand for specialized barcode and receipt printing applications with minimal maintenance requirements.
Mature deployment sits with solvent systems in legacy outdoor graphics. Newer deployment is concentrated in UV and latex formulations responding to regulatory compression.
Technology:
Drop generation physics constrains ink viscosity windows, droplet volume precision, and maximum operating frequency.
- Piezoelectric:Ceramic actuator deformation ejects variable droplet volumes across 3-15 centipoise viscosity range, dominating industrial textile and packaging applications where high pigment loads and precise dot placement justify hardware cost.
- Thermal Bubble:Resistive heating nucleates vapor bubbles for high-frequency ejection at lower hardware cost, standard in desktop document and photo printing where aqueous dye compatibility and disposable head economics dominate.
- Continuous Inkjet:Pressurized continuous streams with electrostatic deflection for high-speed coding and marking on production lines, concentrated in beverage and pharmaceutical secondary packaging where uptime reliability outweighs ink efficiency.
- Drop-on-Demand:Piezo or thermal actuation with binary ejection control for variable data personalization in direct mail and security printing applications.
- Electrostatic:Charged particle attraction to image drums for wide-format engineering and architectural reprographics with toner-like opacity on uncoated stocks.
Hardware refresh cycles favor piezoelectric architectures in industrial segments. Thermal bubble retains installed base dominance in consumer and office environments.
Application:
Substrate handling requirements and image permanence specifications segment demand by end-use value chain position.
- Packaging Decoration:UV-curable and water-based flexo-compatible inks for corrugated, folding carton, and flexible film converting, concentrated in European beverage and personal care supply chains where EFSA migration compliance gates market access.
- Textile Printing:Dye-sublimation and pigment dispersion formulations for polyester and cotton pretreatment, anchored in Chinese manufacturing clusters serving fast-fashion export demand with rapid design-to-garment turnaround.
- Labeling:Narrow-web UV and water-based pressure-sensitive adhesives for prime and logistics labels, standardizing on low-migration photoinitiator packages for food-contact compliance.
- Large Format Printing:Solvent, latex, and UV roll-to-roll formulations for retail signage, vehicle wraps, and exhibition graphics, with chemistry selection driven by indoor air-quality mandates and outdoor durability requirements.
- Fine Art:Pigment-based aqueous and solvent inks on cotton rag and alpha-cellulose substrates for archival giclée reproduction, concentrated in specialized print service providers serving museum and gallery markets.
- Commercial Printing:Sheet-fed and web inkjet for transactional documents, direct mail, and book manufacturing, displacing offset in short-run variable data applications.
Specification authority centralization is reshaping packaging decoration procurement. Textile printing retains distributed demand concentration in manufacturing clusters.
End User:
Technical capability depth and volume scale determine formulation service requirements and pricing leverage.
- Packaging Companies:Integrated converters with in-house prepress and regulatory compliance teams, driving qualified supplier list consolidation and sustainability scorecard weighting for ink chemistry selection.
- Textile Manufacturers:Guangdong province dye-sublimation clusters with dense printer networks and rapid design turnover, sustaining high-volume ink consumption with limited formulation switching costs.
- Print Service Providers:Independent wide-format and commercial operations with equipment lease dependencies, exposed to OEM ink pricing and printhead warranty conditions.
- Advertising Agencies:Creative specification influence without direct procurement authority, shaping brand owner substrate and finish preferences that cascade to converter ink selection.
- Publishing Houses:Book and periodical printers transitioning web offset to inkjet for short-run economics, requiring aqueous pigment formulations compatible with uncoated paper stocks.
Volume concentration sits with packaging companies and textile manufacturers. Technical influence without procurement control characterizes advertising agency relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province's dense textile manufacturing clusters concentrate dye-sublimation ink demand for fast-fashion export production. REACH and JIS VOC limits are compressing solvent ink volumes across German and Japanese packaging converters.
China
Guangdong province hosts dense networks of dye-sublimation printers serving fast-fashion export chains. SAMR's tightening GB standards for printed packaging labeling now extend into cosmetics and pharmaceutical secondary packaging. Domestic producers are building in-house analytical capabilities to preempt certification delays that currently favor multinational suppliers.
Germany
Narrow-web label presses across converting facilities are standardizing on 395nm UV LED curing wavelengths. ECHA-mandated REACH emission ceilings are forcing packaging converters to replace solvent systems with UV-curable formulations. The KBA maintains strict automotive interior material compliance protocols that filter ink specification authority.
Japan
JIS standards are tightening volatile organic compound limits for packaging applications. METI oversees industrial chemical registration frameworks that parallel REACH complexity. Osaka-based flexible packaging producers are expanding UV-curable ink installations to meet domestic emission protocols.
United States
EPA Method 24 VOC testing constrains formulation freedom for wide-format signage producers. State-level extended producer responsibility frameworks for printed packaging are emerging in California and New York. Brand owners are consolidating specification authority at headquarters level, stripping individual plant procurement teams of formulation discretion.
India
Domestic label and flexible packaging growth is outpacing local UV ink production capacity. BIS certification requirements create import substitution potential for qualified multinational suppliers. Maharashtra and Gujarat textile clusters are piloting water-based dye-sublimation alternatives to solvent transfer inks.
Global Digital Inks Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and hardware integration vectors. The vendor base spans vertically integrated pigment producers, narrow-web UV specialists, and proprietary curing chemistry developers. Three strategic archetypes dominate: conglomerates with captive raw material supply, mid-cap specialists with regulatory compliance depth, and technology licensors with proprietary curing platforms. M&A activity concentrates on photoinitiator supply security and regional formulation capacity expansion.
Among diversified chemical conglomerates, Sun Chemical leverages vertically integrated pigment operations to absorb raw-material volatility. Fujifilm Holdings Corporation anchors the high-end segment with proprietary UV LED curing chemistry. Nazdar Company occupies a specialist position within narrow-web UV formulations for label converters seeking migration-compliant food packaging solutions.
| Leading Market Players |
|---|
| Sun Chemical |
| INX International Ink Co |
| Toyo Ink SC Holdings Co. |
| Nazdar Company |
| Fujifilm Holdings Corporation |
| Marabu |
| Siegwerk Druckfarben AG & Co. KGaA |
| JK Group |
| Flint Group |
| Others |
Supply & Pricing Matrix
Formulation chemist concentrations in Germany's Rhineland and China's Jiangsu province create labor-cost differentials that spread pricing tiers across premium REACH-compliant formulations and economy-grade alternatives for price-sensitive textile clusters.
Pricing Analysis
Lead-time premiums compress margins for converters facing just-in-time delivery demands from fast-fashion exporters in Guangdong, while spot inventory discounts attract volume buyers with flexible scheduling. A three-tier pricing structure across premium, standard, and economy levels stratifies by migration certification grade and photoinitiator purity. Price differentiation hinges on EFSA-positive list compliance and OEM printhead warranty coverage. Pricing pressure stems from aqueous latex substitution in large-format signage, with indoor air-quality mandates eroding solvent ink premiums. Print service providers with equipment lease dependencies exhibit highest price sensitivity; centralized brand technical teams prioritize specification compliance over unit cost.
Supply Chain Analysis
Reverse-logistics flows for spent ink cartridges and expired formulations remain underdeveloped, creating disposal cost burdens for high-volume textile clusters in Guangdong and label converters in Germany. Specialty photoinitiator production concentrates in China, Germany, and Japan, with intermediate synthesis anchored in Chinese chemical parks. Raw material dependencies include acrylate oligomers, disperse dyes, and ceramic printhead components. Single-source vulnerability for narrow-spectrum photoinitiators exposes formulators to qualification delays when suppliers fail ECHA substance evaluation. Distribution runs through authorized OEM channels for piezoelectric head compatibility, parallel bulk supply for textile dye-sublimation, and direct technical service for packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH registration expenditures and EFSA migration testing create barrier-to-entry moats favoring established producers with dedicated regulatory infrastructure.
For Market Incumbents: To counter aqueous latex displacement in indoor signage, Sun Chemical and Fujifilm should deepen backward integration into photoinitiator supply and expand low-migration formulation capacity in Germany. Certification investment in SAMR-compliant analytical capabilities preempts domestic Chinese producer advancement. Channel control through printhead OEM partnerships locks in specification authority at brand headquarters level.
For New Entrants and Emerging Players: E-commerce platform sales of dye-sublimation consumables offer route-to-market access for qualified suppliers targeting Guangdong textile clusters with limited technical service requirements. India's domestic packaging conversion gap presents most penetrable geography, with BIS certification creating import substitution window. Specialty water-based sublimation partnerships with European apparel hubs enable premium positioning against solvent legacy.
For Investors and Strategic Acquirers: Re-rating potential sits with narrow-web UV specialists given UV LED hardware penetration acceleration across European label presses. Long-term viability favors formulators with captive pigment supply and multi-jurisdiction certification depth. Watch EFSA photoinitiator positive list expansion as signal for food-contact addressable market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Supply | Captive sourcing from Chinese chemical producers absorbs raw-material volatility and qualification delays. |
| Low-Migration Formulation Capacity Expansion | German and Italian narrow-web converters standardizing on 395nm LED arrays pull compatible ink volumes. |
| SAMR Analytical Capability Buildout | In-house testing preempts certification delays that currently favor multinational suppliers in China. |
| Water-Based Dye-Sublimation Partnership | European apparel hubs piloting aqueous alternatives require textile chemistry specialist collaboration. |
| Printhead OEM Qualification Investment | Eighteen-to-twenty-four month certification cycles compress product lifecycle returns without early positioning. |
Research Methodology
Document review covered customs/trade data, SEC filings, ECHA substance registrations, and SAMR GB standard disclosures, complemented by interviews with formulation chemists at multinational ink producers, procurement leads at German packaging converters, technical directors at Guangdong textile manufacturers, and regulatory affairs specialists navigating REACH and F-Gas compliance. Bottom-up volume estimates derived from printer installed base and ink consumption rates triangulated against top-down market sizing from industry association reports and chemical producer revenue disclosures.
Cross-referencing historical growth patterns with expert panel input on UV LED hardware penetration timelines and regulatory enforcement intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry, printhead physics, substrate application, and end-user technical capability depth. CAGRs were derived from elasticity-adjusted demand curves incorporating substitution effects from aqueous latex and water-based sublimation alternatives. Forecast inputs included photoinitiator supply lead times, OEM qualification cycle durations, and EFSA migration limit revision probabilities.
The model holds under stable REACH and JIS enforcement intensity; deviation in SAMR inspection frequency or EU F-Gas Regulation acceleration would shift volume trajectories between solvent and UV-curable categories. Practitioners should monitor EFSA photoinitiator list expansion announcements and UV LED hardware shipment data from narrow-web press manufacturers for early demand inflection signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Global Light Changing Packaging Inks Market
Printing Inks
Printing Plate Market
Printing Inks
Global Conductive Inks Market
Printing Inks
Zink Printing Market
Printing Inks
Screen Printing Mesh Market
Printing Inks
Europe Specialty Printing Consumables Market
Printing Inks
Global Printing Blanket Market
Printing Inks
Ink Resins Market
Printing Inks
Lithography Inks Market
Printing Inks
Specialty Ink Market
Printing Inks
Returnable Glass Bottle Ink Market
Printing Inks
Global Ceramic Inks Market
Printing Inks
Roll-To-Roll Type UV Imprinting Machines Market
Printing Inks
Global Flexographic Inks Market
Printing Inks
Lithographic Printing Chemicals Market
Printing Inks
Flexo-Ink Market