
 Food Industry Vacuum Cooling Equipment Market | 2026-2036
Food Industry Vacuum Cooling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Food Industry Vacuum Cooling Equipment Market Analysis
Consolidation among packaged food manufacturers is realigning procurement patterns toward larger-capacity continuous cooling systems. Dongguan COLDMAX Ltd. leverages its manufacturing scale to dominate domestic Chinese supply chains. Weber Cooling International BV anchors European demand through specialized bakery cooling installations. SHENZHEN ALLCOLD Co Ltd competes on thermoelectric system integration for mid-scale vegetable processors.
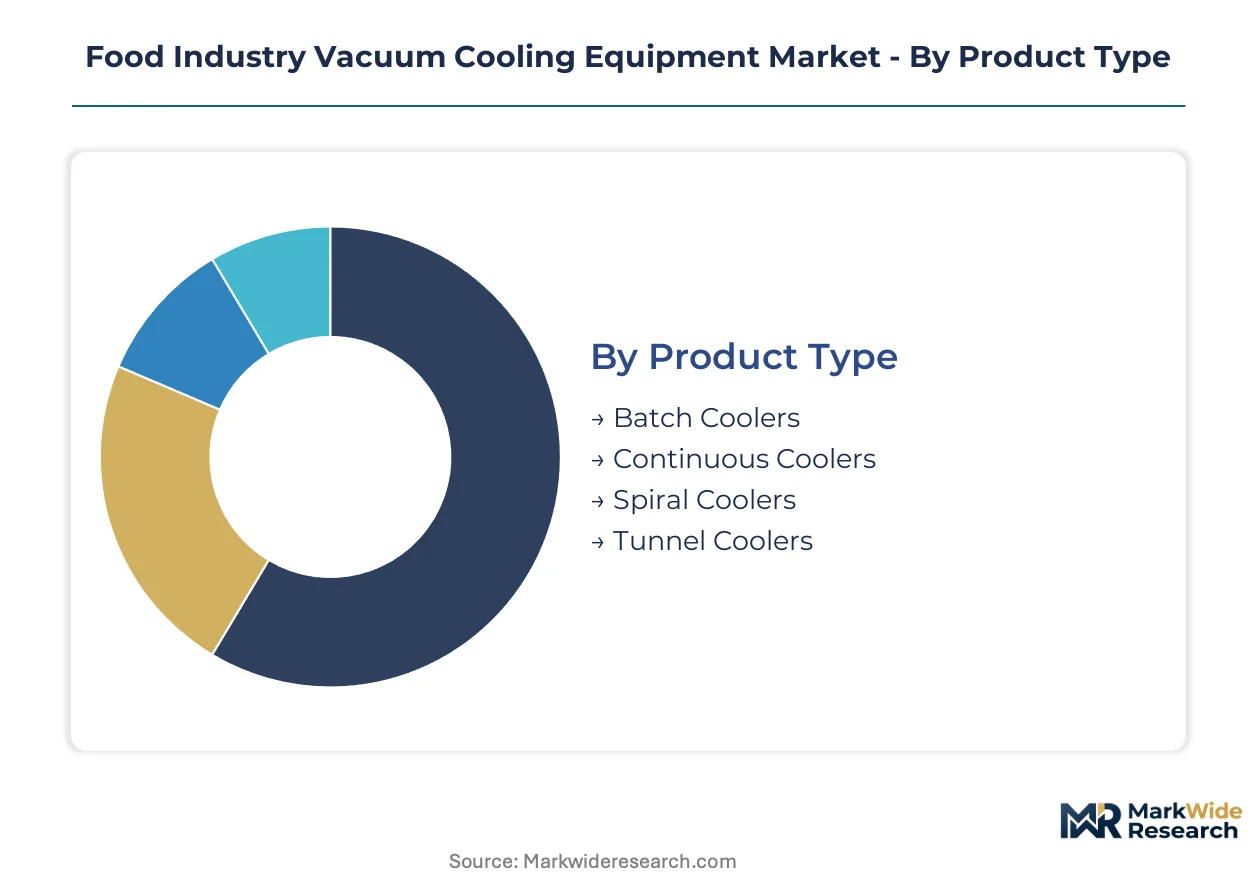
Food industry vacuum cooling equipment removes heat from prepared foods by reducing chamber pressure below the vaporization point of water, typically operating at pressures between 0.61 kPa and 2.3 kPa depending on target core temperatures. The technology flash-evaporates surface moisture to drop product temperatures from 90°C to 4°C within 20-30 minutes for bakery and vegetable applications. Batch coolers capture the largest installed base due to lower capital requirements and flexibility across product formats, while continuous coolers represent the fastest-growing category as high-volume processors automate post-bake and post-blanching lines. Mechanical compression systems lead technology adoption where infrastructure supports industrial refrigeration cycles, though hybrid systems are gaining traction among energy-conscious operators seeking to balance electricity loads.
The U.S. FDA Food Safety Modernization Act and EU MDR-aligned hygiene standards shape equipment design requirements, mandating clean-in-place capability and stainless-steel contact surfaces for cross-border market access. China's SAMR enforces GB standards for food machinery safety that domestic producers like Dongguan Huaxian Technology Co Ltd must satisfy before commercial deployment. Stakeholders must monitor how evolving energy efficiency regulations in major food processing jurisdictions reshape total cost of ownership calculations for vacuum cooling investments.
Market Dynamics
Consolidation among packaged food manufacturers is redirecting procurement toward continuous cooling systems capable of handling automated post-bake and post-blanching lines. This structural concentration is compressing vendor margins while elevating technical performance requirements.
Growth Catalysts
- FDA Food Safety Modernization Act:The U.S. mandate for rapid cooling to minimize bacterial growth windows is accelerating replacement of conventional cooling methods in domestic meat and bakery processing facilities.
- Hybrid thermoelectric-mechanical systems:Energy-conscious operators are deploying combined refrigeration cycles to balance electricity loads and reduce peak demand charges in high-volume vegetable processing.
- China's eastern manufacturing corridor:Dense clustering of domestic equipment makers and export-oriented bakery operations is creating localized supply-demand loops that shorten delivery cycles.
Market Restraints
- Stainless steel input volatility:Fluctuations in nickel and chromium prices directly impact fabrication costs for FDA and EU MDR-mandated contact surfaces.
- Mechanical compressor supply concentration:Dependence on specialized refrigeration component suppliers in Germany and Japan creates lead time vulnerability for system integrators.
- Water recovery technical limits:Flash evaporation rates in high-moisture vegetable applications constrain throughput scalability below continuous bakery cooling benchmarks.
Strategic Opportunities
- India's organized food retail expansion:FSSAI enforcement of cold chain standards in processed vegetables and ready-to-eat meals is opening first-mover positioning for vacuum cooling installations.
- Clean-in-place automation convergence:Integration of robotic CIP systems with vacuum chamber design addresses EU MDR hygiene mandates while reducing labor dependency.
- Carbon border adjustment mechanisms:EU CBAM phase-in is incentivizing energy-efficient cooling technology adoption among export-oriented processors in Southeast Asia.
Industry Challenges
- Vacuum pump specialist scarcity:Maintenance and optimization of sub-atmospheric systems requires technicians trained in both refrigeration and pressure vessel certification, creating hiring bottlenecks.
- Legacy PLC integration friction:Retrofitting continuous vacuum coolers into existing SCADA-controlled bakehouse lines demands custom protocol bridging that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Industry Vacuum Cooling Equipment Market |
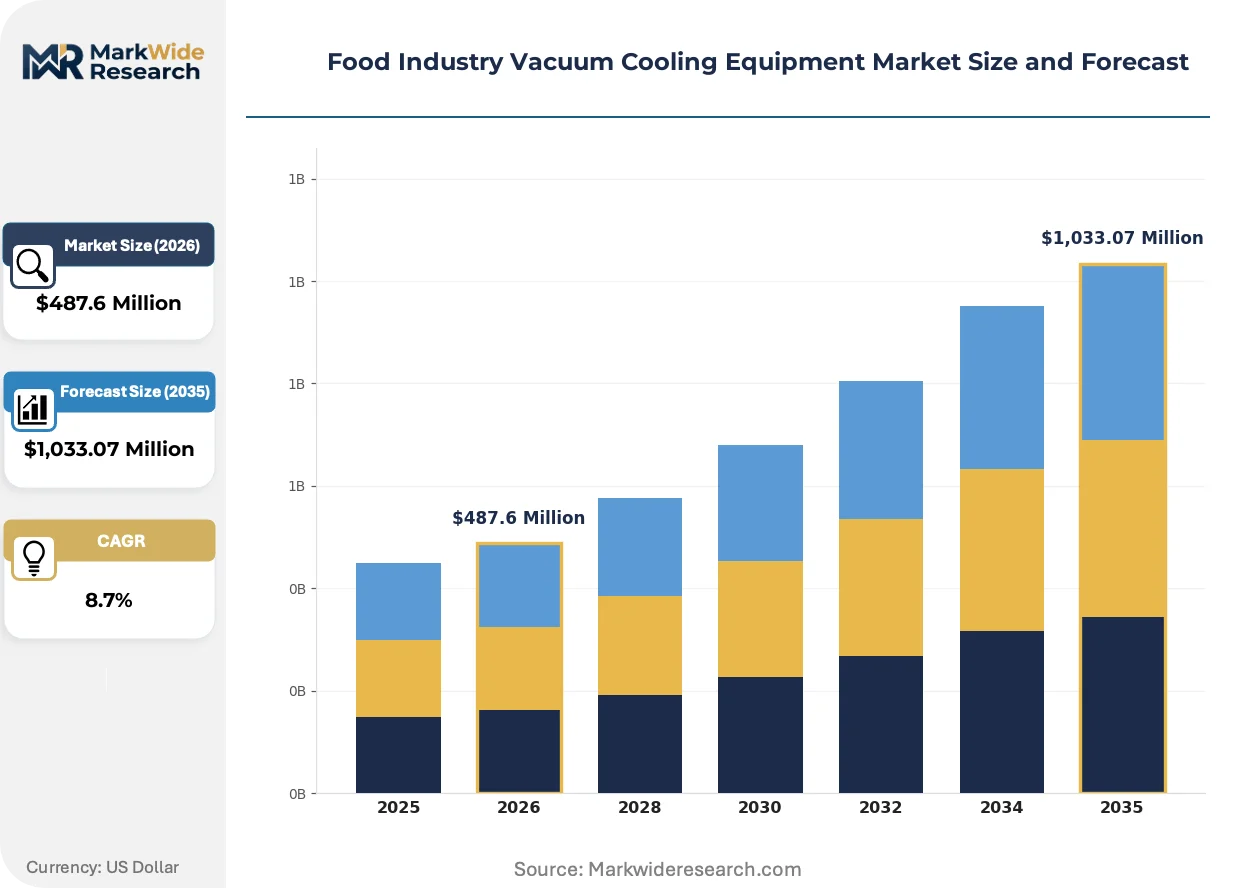
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Coolers, Continuous Coolers, Spiral Coolers, Tunnel Coolers Application: Vegetable Cooling, Fruit Cooling, Bakery Products, Meat Cooling End User: Food Processors, Packaged Food Manufacturers, Restaurants, Supermarkets Technology: Thermoelectric Systems, Mechanical Compression, Water-Liquid Systems, Hybrid Systems |
| Companies Covered | Agrimaint Inc., KoolJet, SHENZHEN ALLCOLD Co Ltd, Southern Vacuum Cooling Inc., Dongguan COLDMAX Ltd., Dongguan Huaxian Technology Co Ltd, Atlas Copco AB, Celtic Cooling, Weber Cooling International BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Industry Vacuum Cooling Equipment Market Emerging Trajectories
Active reshaping of this market centers on modular system architectures that reduce installation footprint and enable phased capacity expansion. Equipment designers are prioritizing interoperability with existing plant automation hierarchies.
Thermoelectric cooling modules are decentralizing temperature control authority within vacuum chambers. Mid-scale vegetable processors in China's Shandong province are adopting distributed thermoelectric arrays to replace centralized mechanical compression. This shift is compressing the minimum efficient scale for vacuum cooling deployment.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in mechanical compression systems. Industrial cooling equipment manufacturers are reformulating refrigeration cycles to accommodate lower-global-warming-potential alternatives. Bakery processors in Germany and the Netherlands are front-loading equipment replacement to avoid compliance deadlines.
Service unbundling is separating equipment supply from performance-based cooling contracts. Large packaged food manufacturers are negotiating temperature-guarantee agreements that shift operational risk to equipment vendors. This model is most visible in U.S. ready-to-eat meat processing, where processors prioritize uptime over capital ownership.
Food Industry Vacuum Cooling Equipment Market Segmentation
Equipment configuration and cooling methodology choices in the Food Industry Vacuum Cooling Equipment Market directly determine capital recovery timelines and operational flexibility. Processors balance throughput requirements against batch size variability when selecting system architectures. Each segmentation dimension carries distinct implications for energy consumption, maintenance protocols, and regulatory compliance pathways.
Product Type:
Volume-driven installations favor continuous configurations, while premium flexibility commands batch system premiums.
- Batch Coolers:Chamber-based units process discrete product loads through controlled pressure reduction cycles, accommodating multiple SKUs without format changeover. Packaged food manufacturers in China's Shandong province deploy these for seasonal vegetable campaigns where product mix shifts quarterly. Lower capital thresholds and format adaptability sustain dominance in mid-scale processor procurement.
- Continuous Coolers:Conveyor-integrated vacuum tunnels enable uninterrupted post-bake and post-blanching cooling for automated production lines. European bakery conglomerates in Germany and the Netherlands are retrofitting these into SCADA-controlled facilities to compress bacterial growth windows under EU MDR-aligned hygiene mandates. These configurations expand most quickly as consolidation redirects procurement toward integrated automation.
- Spiral Coolers:Vertical belt arrangements maximize floor-space efficiency for high-volume bakery applications. U.S. ready-to-eat meat processors favor these where FDA Food Safety Modernization Act compliance demands rapid temperature reduction within constrained plant footprints.
- Tunnel Coolers:Linear conveyor systems serve high-throughput fruit and vegetable operations with extended cooling profiles. Japanese food machinery standards shape design specifications for export-oriented installations.
Today's leader: Batch Coolers. Tomorrow's challenger: Continuous Coolers.
Application:
Moisture content and thermal mass differentiate cooling performance requirements across food categories.
- Vegetable Cooling:Leafy greens and blanched vegetables release substantial surface moisture during flash evaporation, demanding water recovery integration. China's eastern manufacturing corridor processors deploy hybrid thermoelectric-mechanical systems here to manage electricity load balancing under SAMR energy efficiency guidelines.
- Bakery Products:Bread, pastries, and baked goods require precise crust preservation during rapid core temperature reduction. Weber Cooling International BV anchors European demand through specialized installations serving automated post-bake lines in Germany and the Netherlands.
- Fruit Cooling:Delicate cellular structures limit pressure reduction rates to prevent texture degradation. California Central Valley stone fruit packers specify gentle-cycle batch configurations.
- Meat Cooling:Protein coagulation sensitivity and stringent pathogen control elevate stainless-steel surface requirements and CIP automation. U.S. processors negotiate performance-based cooling contracts prioritizing uptime guarantees over capital ownership.
Vegetable Cooling commands current installed base. Bakery Products show steepest expansion trajectory as European automation accelerates.
End User:
Scale concentration and risk tolerance separate enterprise procurement from distributed operator adoption.
- Food Processors:Dedicated vegetable and protein handling facilities prioritize throughput maximization and regulatory documentation. India's FSSAI cold chain enforcement is opening first-mover positioning among organized retail suppliers.
- Packaged Food Manufacturers:Multi-site operators standardize on vendor platforms to simplify maintenance training and spare parts logistics. Consolidation is compressing vendor margins while elevating technical performance requirements.
- Restaurants:Central kitchen and commissary operations deploy compact batch units for prepared meal cooling. Southeast Asian export-oriented processors are adopting energy-efficient configurations ahead of EU CBAM phase-in.
- Supermarkets:In-store bakery and prepared food departments require low-footprint solutions with simplified operator interfaces. Japanese retail chains specify JIS-compliant equipment for reliability assurance.
Packaged Food Manufacturers drive volume procurement. Food Processors offer deepest technology penetration potential.
Technology:
Refrigeration cycle selection determines energy intensity and maintenance specialization requirements.
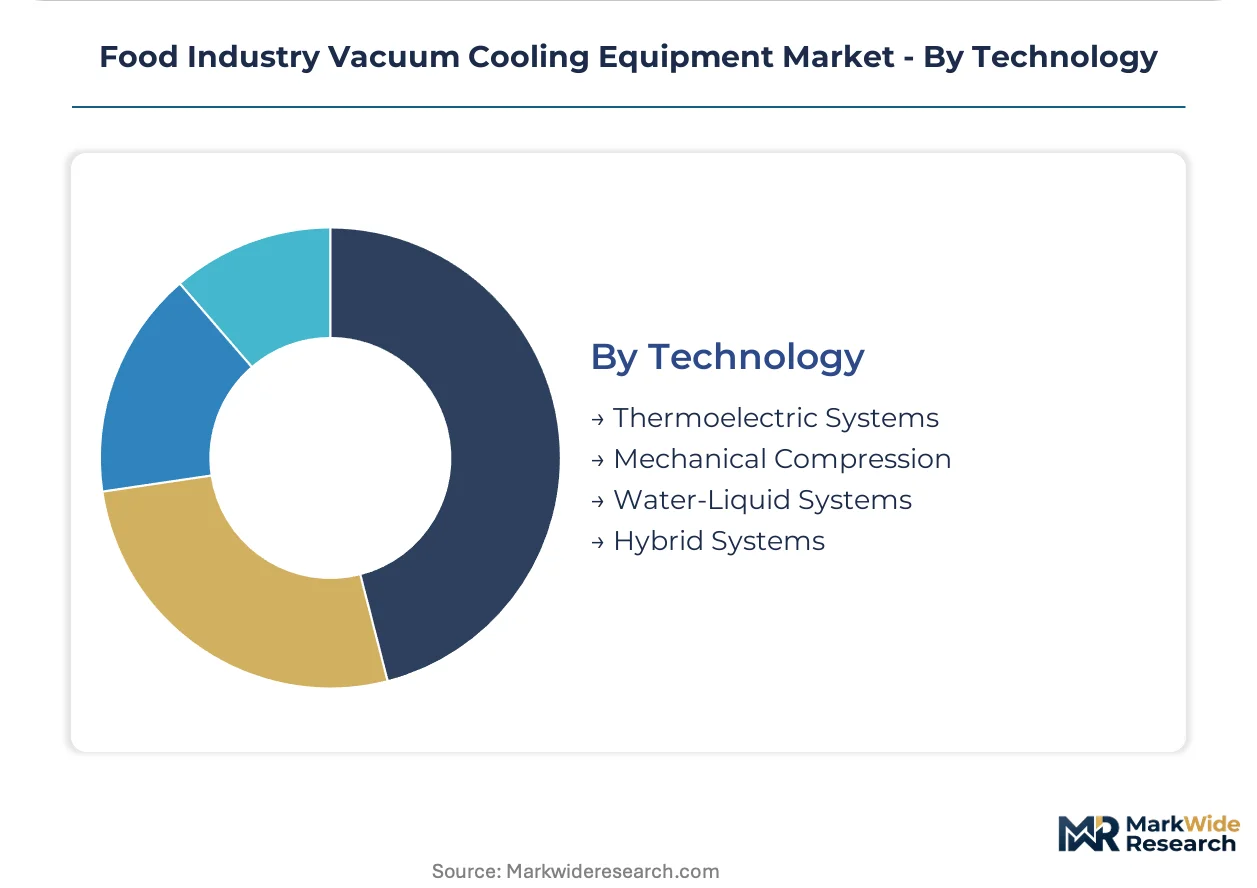
- Mechanical Compression:Traditional vapor-compression refrigeration dominates where industrial power infrastructure supports high electrical loads. EU F-Gas Regulation is forcing reformulation to lower-global-warming-potential alternatives ahead of compliance deadlines.
- Hybrid Systems:Combined thermoelectric and mechanical cycles balance electricity demand and enable load shifting. SHENZHEN ALLCOLD Co Ltd competes on integration expertise for mid-scale Chinese vegetable processors.
- Thermoelectric Systems:Solid-state cooling modules decentralize temperature control without moving parts. Shandong province vegetable processors adopt distributed arrays to compress minimum efficient scale thresholds.
- Water-Liquid Systems:Secondary heat transfer loops enable precise temperature staging for sensitive applications. German bakery equipment integrators specify these for crust quality preservation.
Mechanical Compression retains dominant share. Hybrid Systems gain preference among energy-conscious operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's bakery automation surge contrasts with China's vegetable processing dominance, revealing how regional food industry structures shape vacuum cooling deployment patterns. Equipment specifications diverge sharply between EU MDR-aligned hygiene mandates and China's SAMR energy efficiency frameworks. The analysis spans five countries where regulatory pressure and industrial concentration create distinct procurement environments.
United States
FDA Food Safety Modernization Act enforcement drives rapid cooling adoption in ready-to-eat meat and bakery segments. USDA-inspected facilities face compressed bacterial growth window requirements that favor continuous vacuum tunnel configurations. California Central Valley stone fruit packers specify gentle-cycle batch systems for delicate cellular preservation.
Germany
EU F-Gas Regulation phase-down accelerates mechanical compression system replacement ahead of hydrofluorocarbon deadlines. Bakery conglomerates in Bavaria and North Rhine-Westphalia retrofit SCADA-integrated continuous coolers into automated post-bake lines. Edeka and REWE supply chain standards elevate clean-in-place automation requirements for vendor qualification.
China
SAMR GB standards enforcement shapes domestic equipment certification pathways before commercial deployment authorization. Shandong province vegetable processors adopt distributed thermoelectric arrays to compress minimum efficient scale thresholds. Dongguan manufacturing clusters serve both local processors and export-oriented bakery operations with shortened delivery cycles.
India
FSSAI cold chain standard enforcement in processed vegetables and ready-to-eat meals opens first-mover positioning for vacuum cooling installations. Organized retail expansion by Reliance Retail and BigBasket creates demand concentration in Maharashtra and Karnataka processing corridors. National cold chain subsidies reduce capital recovery timelines for mid-scale vegetable handlers.
Netherlands
EU MDR-aligned hygiene mandates and carbon border adjustment anticipation drive energy-efficient technology preference among export-oriented processors. Rotterdam port logistics clusters integrate vacuum cooling into vegetable re-export handling for German and UK markets. Wageningen University research partnerships accelerate thermoelectric-mechanical hybrid system validation.
Food Industry Vacuum Cooling Equipment Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology integration and application depth dimensions. The vendor base organizes into three tiers: multinational industrial refrigeration groups with vacuum cooling divisions, regional equipment fabricators serving domestic food processing clusters, and thermoelectric technology specialists pursuing distributed cooling architectures. Consolidation among packaged food manufacturers compresses margins while elevating performance guarantees and uptime contracting requirements. Strategic moves center on clean-in-place automation convergence and service unbundling into performance-based temperature guarantee agreements.
Among Chinese equipment fabricators, Dongguan COLDMAX Ltd. and Dongguan Huaxian Technology Co Ltd occupy positions shaped by domestic SAMR certification requirements and eastern manufacturing corridor density. SHENZHEN ALLCOLD Co Ltd exemplifies thermoelectric integration specialization for mid-scale vegetable processors. Weber Cooling International BV represents European bakery cooling focus anchored in Netherlands-based automation integration expertise.
| Leading Market Players |
|---|
| Agrimaint Inc. |
| KoolJet |
| SHENZHEN ALLCOLD Co Ltd |
| Southern Vacuum Cooling Inc. |
| Dongguan COLDMAX Ltd. |
| Dongguan Huaxian Technology Co Ltd |
| Atlas Copco AB |
| Celtic Cooling |
| Weber Cooling International BV |
| Others |
Supply Flow & Price Mechanics
Hybrid thermoelectric-mechanical system adoption across China's Shandong province is compressing fabrication economics for mid-scale equipment while concentrating procurement leverage among domestic integrators who control distributed cooling module supply. This technology transition simultaneously erodes price premiums for traditional mechanical compression units and elevates stainless steel input volatility as a margin determinant across all vendor tiers.
Pricing Analysis
Capacity additions in China's eastern manufacturing corridor are reshaping price floors for batch cooler configurations as Dongguan fabricators expand thermoelectric integration lines. Three-tier pricing structure across premium continuous systems, standard batch units, and economy-grade compact coolers reflects certification tier differentiation under FDA and EU MDR hygiene mandates. Cost compression in economy segments is intensifying because nickel and chromium price volatility directly impacts stainless steel fabrication costs for contact surfaces. Packaged food manufacturers with multi-site standardization programs exhibit lowest price sensitivity, while independent vegetable processors in India's emerging corridors show highest elasticity to capital outlay.
Supply Chain Analysis
EU MDR-aligned clean-in-place certification requirements and FDA Food Safety Modernization Act compliance gating restrict vendor qualification to fabricators with documented pressure vessel and refrigeration cycle expertise. Component supply concentrates in Germany and Japan for specialized mechanical compressors, while stainless steel sheet and thermoelectric module production centers on China and South Korea. Raw material dependencies span nickel-chromium alloys for hygienic surfaces, rare-earth elements for thermoelectric arrays, and precision-machined vacuum pump assemblies. Single-source vulnerability in Japanese refrigeration component supply creates lead time exposure for European system integrators. Distribution runs through direct vendor relationships with large packaged food manufacturers and regional equipment distributors serving mid-scale processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where consolidation among packaged food manufacturers has shifted procurement toward premium continuous cooling systems with guaranteed uptime performance. The demand pivot toward EU MDR-aligned hygiene specifications and FDA-mandated rapid cooling compliance elevates technical performance over capital cost in vendor selection criteria.
For Market Incumbents: To counter margin compression from procurement consolidation, Weber Cooling International BV and Dongguan COLDMAX Ltd. should deepen backward integration into thermoelectric module assembly and stainless steel fabrication. Equipment vendors must also invest in clean-in-place automation certification to maintain qualification under evolving EU and U.S. hygiene mandates.
For New Entrants and Emerging Players: Regional bakery equipment distributors in Germany and the Netherlands represent the most accessible channel partnership for penetrating European automation retrofits. White-space opportunities concentrate in India's FSSAI-enforced cold chain expansion and Southeast Asian vegetable processing ahead of EU carbon border adjustment phase-in. A service-unbundled performance contract model targeting uptime guarantees rather than capital sales offers the strongest go-to-market differentiation against established vendors.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Chinese equipment fabricators with SAMR certification but limited export track record. Long-term viability hinges on regulatory compliance breadth across FDA, EU MDR, and emerging FSSAI frameworks. The acquisition target archetype combines thermoelectric integration capability with established clean-in-place automation. Watch for inflection signals in India's organized retail cold chain subsidy disbursement rates as a demand accelerator indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-in-Place Automation Integration | Robotic CIP systems address EU MDR hygiene mandates while reducing labor dependency in continuous cooling lines. |
| Backward Integration into Thermoelectric Modules | In-house production of distributed cooling arrays compresses cost structures for mid-scale vegetable processor targeting. |
| Performance-Based Cooling Contracts | Temperature-guarantee agreements shift operational risk to vendors and align pricing with uptime outcomes in U.S. meat processing. |
| Geographic Expansion into India | FSSAI cold chain enforcement creates first-mover positioning among organized retail suppliers in Maharashtra processing corridors. |
| Hybrid System Technology Licensing | Energy-conscious operators in China's Shandong province seek combined refrigeration cycles for electricity load balancing. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers at packaged food manufacturers, procurement leads at bakery conglomerates, maintenance directors at vegetable processing facilities, and aftermarket service heads at equipment distributors with secondary validation against SEC filings of diversified industrial refrigeration groups, SAMR equipment certification databases, FDA Food Safety Modernization Act guidance documents, and EU F-Gas Regulation compliance disclosures. Bottom-up equipment shipment tallies and top-down food processing capacity expansion estimates were cross-referenced for triangulation.
Segment-weighting approaches applied differential growth assumptions across batch versus continuous cooler configurations, mechanical compression versus hybrid thermoelectric-mechanical technology adoption curves, and vegetable versus bakery versus meat application penetration rates. CAGRs were derived from installed base evolution modeling and replacement cycle analysis across the projection horizon. Industry-specific forecast inputs incorporated EU F-Gas Regulation phase-down timelines for hydrofluorocarbon refrigerants and China's SAMR energy efficiency guideline enforcement trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to stainless steel input price volatility, vacuum pump specialist technician availability, and regulatory harmonization friction between FDA, EU MDR, and SAMR certification requirements. A model refresh is warranted upon material change in India's FSSAI subsidy disbursement rates or EU carbon border adjustment mechanism implementation scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Tortilla Machine Market
Food Processing Equipment
Food Processor Market
Food Processing Equipment
Ice Cream Processing Equipment Market
Food Processing Equipment
Food Waste Disposers Market
Food Processing Equipment
Seafood Processing Equipment Market
Food Processing Equipment
Global Food and Beverage Coding and Marking Equipment Market
Food Processing Equipment
Global Snack Pellet Equipment Market
Food Processing Equipment
Brewing Thermometer Market
Food Processing Equipment
Ice Cream Freezer Market
Food Processing Equipment
Continuous Fryer Machine Market
Food Processing Equipment
Ice Flaking Machine Market
Food Processing Equipment
Tube Ice Machine Market
Food Processing Equipment
High Speed Oven Market
Food Processing Equipment
Global Wine Tanks Market
Food Processing Equipment
North America Food and Beverage Filling and Capping Machines Market
Food Processing Equipment
Automatic Canning Machine Market