
 Ice Cream Processing Equipment Market | 2026-2036
Ice Cream Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Ice Cream Processing Equipment Market Analysis
Buyer concentration among food service chains is expanding as multinational quick-service restaurants centralize procurement through approved vendor programs. Alfa Laval leverages its heat exchanger portfolio to dominate pasteurizer supply for large-scale dairy cooperatives. Tetra Pak sustains integrated processing line contracts through end-to-end automation capabilities. GEA Group anchors European demand with specialized continuous freezer systems engineered for high-overrun production.
Ice cream processing equipment encompasses machinery designed to transform liquid dairy mixes into finished frozen desserts through controlled thermal treatment, homogenization, aging, and aeration processes operating at temperatures between -6°C and -10°C with overrun targets of 80-120%. Freezers represent the highest-margin segment due to precision refrigeration engineering requirements and extended replacement cycles. Pasteurizers constitute the most mature equipment category with standardized regulatory compliance protocols across jurisdictions. Homogenizers are gaining structural importance as plant-based formulations require finer particle size distribution to achieve equivalent mouthfeel.
The US FDA enforces Grade A Pasteurized Milk Ordinance standards that dictate sanitary design specifications for all dairy-contact processing surfaces. The EU F-Gas Regulation and REACH framework mandate refrigerant transition timelines and material safety documentation for equipment sold across member states. Equipment manufacturers must monitor evolving ESG disclosure requirements under CSRD as institutional buyers embed supply chain emissions criteria into procurement decisions.
Market Dynamics
The EU F-Gas Regulation is compressing equipment replacement cycles across the installed base, forcing capital allocation toward low-global-warming-potential refrigeration architectures while artisanal dairy processors simultaneously pursue automated batch freezer upgrades.
Growth Catalysts
- Regulatory Phase-Out Mandates:The EU F-Gas Regulation mandates refrigerant transition timelines that accelerate equipment turnover toward compliant systems, expanding addressable market volume for replacement sales.
- Artisanal Automation Demand:Boutique frozen dessert brands in Italy's Emilia-Romagna cluster are deploying capital into automated batch freezers to scale output without sacrificing product differentiation.
- Plant-Based Formulation Engineering:Homogenizer demand is intensifying as dairy-alternative processors require finer particle size distribution to replicate conventional mouthfeel in oat and almond bases.
Market Restraints
- Refrigerant Input Cost Volatility:Low-global-warming-potential refrigerant supply concentrates among limited chemical producers, exposing equipment margins to feedstock price swings.
- Precision Engineering Concentration:Continuous freezer manufacturing expertise clusters in Northern Italy and Southern Germany, creating geographic supply risk for high-overrun production systems.
- Sanitary Design Compliance Friction:The US FDA Grade A Pasteurized Milk Ordinance imposes divergent surface finish specifications that fragment product platform standardization.
Strategic Opportunities
- Underpenetrated Southeast Asian Processing:Vietnam and Indonesia dairy cooperatives lack continuous freezer infrastructure, creating first-mover advantage for equipment vendors offering financing-linked installation.
- CSRD-Driven ESG Procurement:The EU Corporate Sustainability Reporting Directive embeds supply chain emissions criteria into institutional buyer vendor qualification, advantaging manufacturers with verified lifecycle data.
- Retrofit Digitalization Convergence:IoT-enabled predictive maintenance modules are penetrating legacy installed bases, opening recurring revenue streams independent of new equipment sales.
Industry Challenges
- Refrigeration Technician Scarcity:Low-global-warming-potential system servicing requires specialized certification that outpaces vocational training pipeline output in multiple jurisdictions.
- Legacy Control Architecture Integration:Automated batch freezer deployments face protocol incompatibility with existing plant SCADA infrastructure, extending commissioning timelines.
- Multi-Jurisdiction Certification Stacking:Equipment qualifying for EU CE marking, US FDA compliance, and China GB standards simultaneously faces extended documentation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ice Cream Processing Equipment Market |
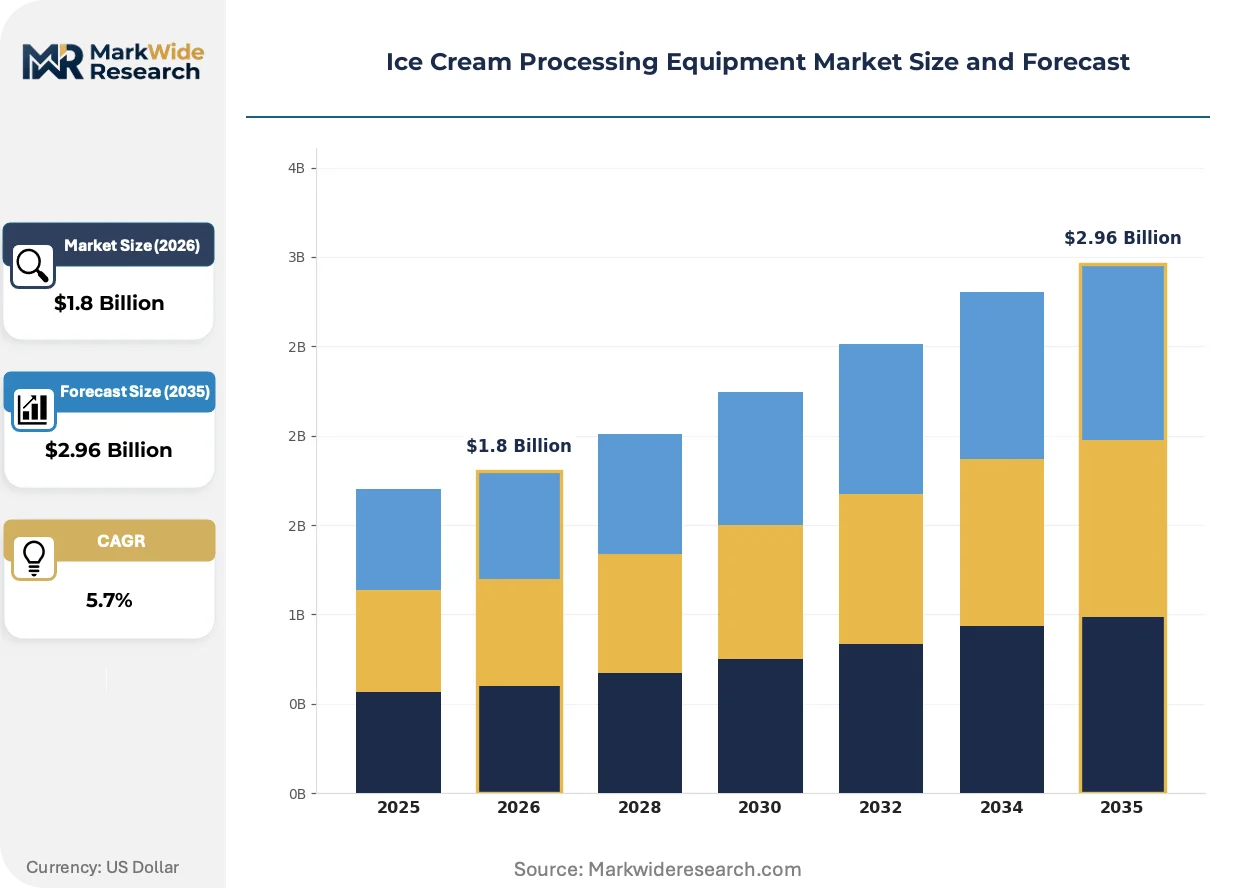
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Freezers, Mixers, Pasteurizers, Homogenizers Application: Soft Serve, Hard Ice Cream, Novelty Ice Cream, Dairy-Free Options End User: Commercial Vendors, Retail Outlets, Food Service Chains, Private Label Manufacturers Distribution Channel: Direct Sales, Online Retail, Distributor Partnerships, Wholesale |
| Companies Covered | Alfa Laval, SPX FLOW, Tetra Pak, ROKK Processing, Technogel, GEA Group, Gram Equipment, Snowball Machinery, Carpigiani Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ice Cream Processing Equipment Market Emerging Trajectories
Equipment architecture is fragmenting into configurable subsystems that accommodate rapid product changeovers, while regulatory pressure and buyer procurement evolution simultaneously reshape competitive requirements.
Continuous freezer engineering is modularizing into standardized refrigeration skids, homogenization units, and aeration modules that permit independent upgrade paths. Mid-scale dairy cooperatives in the Netherlands and Denmark are adopting this architecture to defer full-system replacement. The structural consequence is compressing capital commitment thresholds while extending vendor service attachment rates.
The EU F-Gas Regulation mandates complete phase-out of hydrofluorocarbon refrigerants above specific global-warming-potential thresholds by fixed deadlines. Equipment manufacturers must redesign heat exchanger and compressor specifications to accommodate hydrofluoroolefin and natural refrigerant alternatives. Large-scale dairy cooperatives in Germany and France are front-loading replacement investments to avoid stranded asset risk.
Consolidated procurement through approved vendor programs is displacing decentralized equipment purchasing across multinational quick-service restaurant chains. Regional equipment distributors in Spain and Poland are losing direct customer relationships as procurement authority centralizes at headquarters level. This concentration is most visible in Southern European markets where franchise density supports dedicated supply agreements.
Ice Cream Processing Equipment Market Segmentation
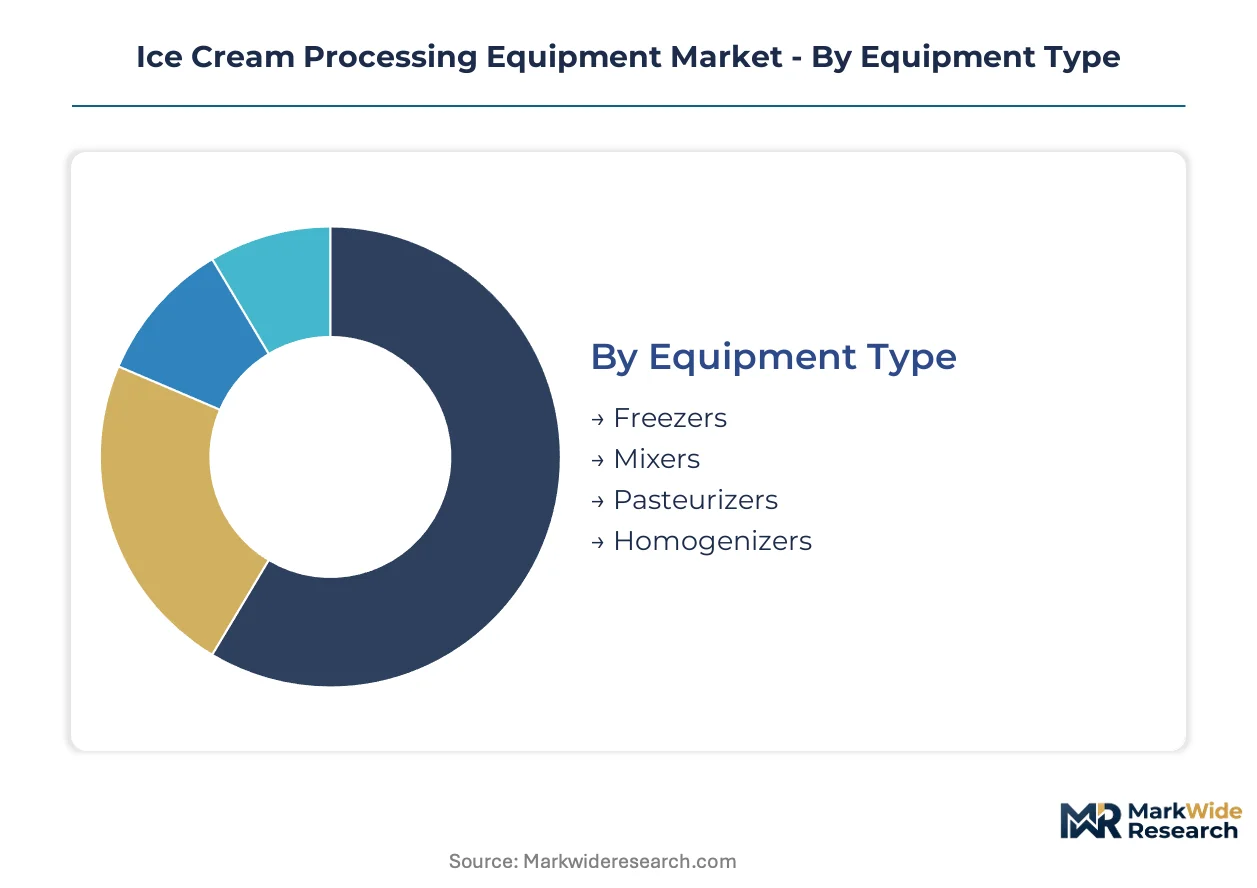
Equipment differentiation in ice cream processing reflects divergent thermal engineering requirements, regulatory compliance burdens, and end-user scale economics. Segmentation reveals where capital expenditure concentrates and which technology platforms command premium positioning.
Equipment Type:
Supply concentration clusters around precision refrigeration engineering, with component sourcing dictating competitive positioning across thermal treatment categories.
- Freezers:Continuous and batch freezer systems operate at -6°C to -10°C with overrun targets of 80-120%, requiring precision compressor and heat exchanger integration. Demand concentrates among large-scale dairy cooperatives in Germany and France front-loading replacement investments to avoid EU F-Gas Regulation stranded asset risk. These systems carry the highest margins due to extended replacement cycles and proprietary refrigeration architectures.
- Homogenizers:High-pressure valve systems achieve particle size distribution below 2 microns for mouthfeel consistency. Plant-based formulation engineering in oat and almond base production is intensifying demand from dairy-alternative processors seeking equivalent sensory profiles. This segment is gaining structural importance as formulation complexity escalates.
- Pasteurizers:Heat exchanger-based thermal treatment systems comply with FDA Grade A Pasteurized Milk Ordinance sanitary surface specifications. Alfa Laval dominates supply for large-scale cooperatives through integrated heat exchanger portfolios.
- Mixers:Aging tank and blending systems prepare liquid dairy bases for downstream freezing. Artisanal processors in Italy's Emilia-Romagna cluster deploy automated batch freezer-integrated mixer configurations.
Today's leader: Freezers. Tomorrow's challenger: Homogenizers.
Application:
End-product viscosity and aeration requirements fragment equipment specifications across frozen dessert categories, with overrun targets and serving temperature dictating machinery selection.
- Hard Ice Cream:High-overrun production systems achieve 100-120% air incorporation through continuous freezer architectures. GEA Group anchors European demand with specialized continuous systems engineered for this application in high-volume dairy cooperatives.
- Soft Serve:Lower overrun targets of 30-60% require gravity or pump-fed freezer configurations with rapid heat transfer. Food service chains centralize procurement through approved vendor programs, consolidating demand around standardized equipment platforms.
- Novelty Ice Cream:Molded and extruded product formats require specialized filling and forming attachments. Equipment modularity permits rapid changeover between stick, cone, and sandwich configurations.
- Dairy-Free Options:Oat, almond, and coconut base processing demands modified homogenization and aging protocols. Finer particle size distribution requirements are intensifying capital allocation toward upgraded homogenizer specifications.
Hard ice cream commands installed base dominance; dairy-free processing climbs the fastest as formulation portfolios diversify.
End User:
Procurement authority concentration versus fragmentation determines vendor relationship structures and service attachment economics.
- Food Service Chains:Multinational quick-service restaurants centralize procurement through approved vendor programs, displacing decentralized purchasing. Regional distributors in Spain and Poland lose direct relationships as headquarters-level authority consolidates.
- Commercial Vendors:Independent gelato shops and artisanal producers in Italy's Emilia-Romagna cluster prioritize automated batch freezers for scaled output without product differentiation sacrifice.
- Private Label Manufacturers:Contract processors serving retail brands require flexible equipment platforms accommodating rapid SKU rotation. Modular freezer architectures permit independent subsystem upgrades.
- Retail Outlets:Supermarket and convenience store in-house production demands compact footprint equipment with simplified sanitation protocols. Volume scale limits justify lower capital intensity configurations.
Food service chains dominate contract value; private label manufacturers present the steepest expansion trajectory as retailer vertical integration accelerates.
Distribution Channel:
Customer scale and technical complexity requirements stratify channel economics, with direct relationships commanding premium positioning.
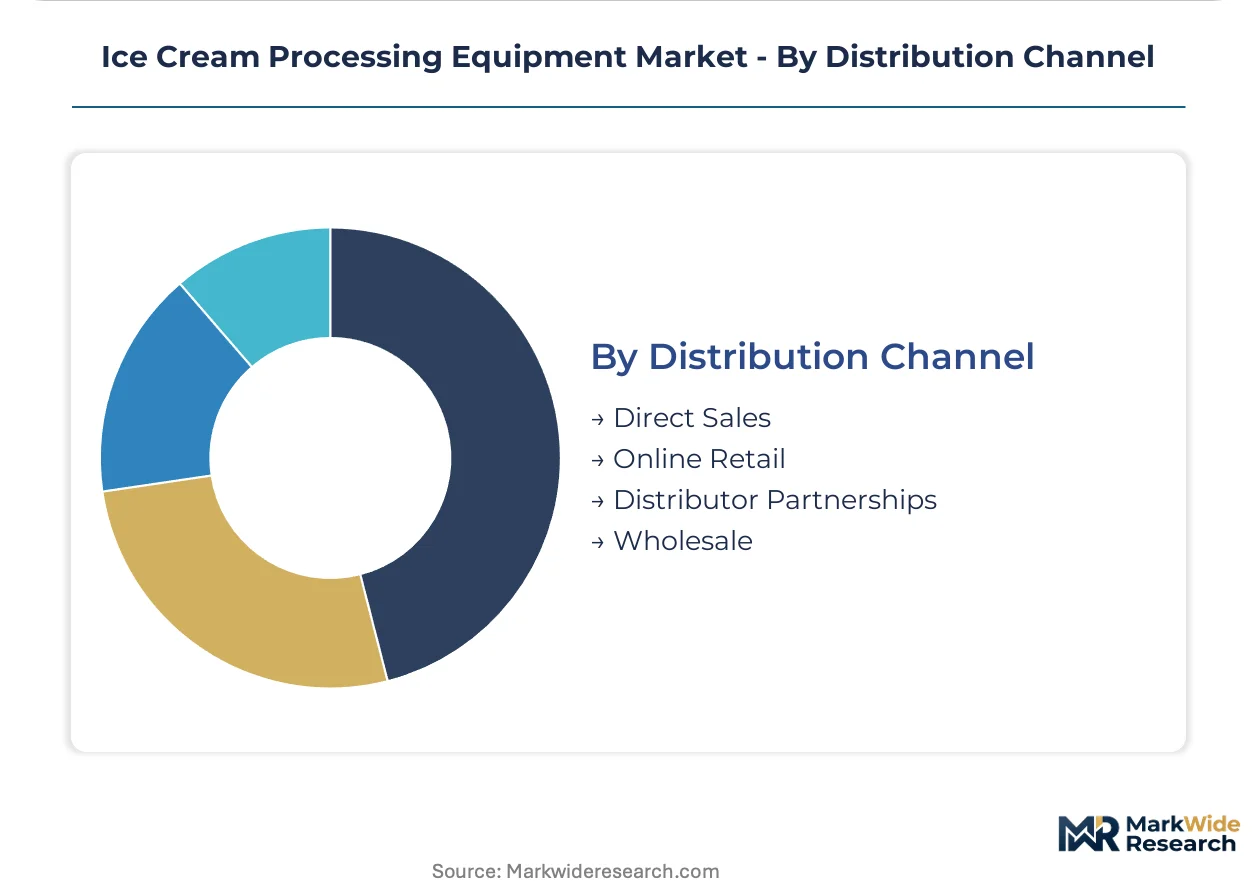
- Direct Sales:Large-scale dairy cooperatives and multinational chains negotiate integrated processing line contracts with manufacturers. Tetra Pak sustains these relationships through end-to-end automation capabilities and lifecycle service bundling.
- Distributor Partnerships:Regional equipment distributors serve mid-scale processors with localized installation and maintenance support. Southern European markets retain this structure where franchise density supports dedicated supply agreements.
- Online Retail:Standardized spare parts and consumables migrate to digital procurement platforms. Predictive maintenance module retrofits penetrate legacy installed bases through this channel.
- Wholesale:Volume equipment transactions for emerging market dairy cooperatives in Vietnam and Indonesia flow through financing-linked wholesale arrangements.
Direct sales capture premium margin concentration; distributor partnerships face procurement centralization pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's dairy cooperatives front-load freezer replacement investments while Vietnam's emerging cooperatives lack continuous processing infrastructure entirely, revealing a bifurcated capital deployment landscape across developed and developing markets.
United States
Multinational quick-service restaurant chains centralize procurement through approved vendor programs, consolidating equipment demand at headquarters level. The FDA enforces Grade A Pasteurized Milk Ordinance sanitary surface specifications that fragment product platform standardization. Dairy processing clusters in Wisconsin and California drive pasteurizer and homogenizer demand from large-scale cooperatives.
Germany
Large-scale dairy cooperatives accelerate capital allocation toward low-global-warming-potential refrigeration systems to avoid EU F-Gas Regulation stranded asset risk. The REACH framework mandates material safety documentation for equipment sold across member states. Southern Germany hosts continuous freezer manufacturing expertise that supplies high-overrun production systems across Europe.
Italy
Artisanal dairy processors and boutique frozen dessert brands in Emilia-Romagna deploy capital into automated batch freezers to scale output without sacrificing product differentiation. The EU F-Gas Regulation compresses equipment replacement cycles across the installed base. Bologna and surrounding provinces anchor specialized gelato equipment manufacturing serving premium producers worldwide.
Netherlands
Mid-scale dairy cooperatives adopt modular freezer architectures with standardized refrigeration skids and independent upgrade paths to defer full-system replacement. CSRD disclosure requirements embed supply chain emissions criteria into institutional procurement decisions. Dairy processing clusters in Friesland and Gelderland drive demand for configurable subsystems accommodating rapid product changeovers.
Vietnam
Emerging dairy cooperatives lack continuous freezer infrastructure, creating first-mover advantage for equipment vendors offering financing-linked installation. The country's national dairy regulator imposes evolving sanitary standards as processing capacity expands. Ho Chi Minh City and Hanoi concentrate demand for entry-level batch processing equipment as domestic ice cream consumption rises.
Ice Cream Processing Equipment Market Vendor Landscape
Italian producers anchor one tier of precision freezer engineering; German specialists hold continuous system expertise. The vendor base stratifies between integrated processing line contractors and modular subsystem fabricators. Two strategic archetypes dominate: heat exchanger-anchored thermal treatment providers and refrigeration-centric precision engineering houses. Competitive moves concentrate on M&A for geographic footprint expansion and strategic partnerships for retrofit digitalization capabilities.
Within the integrated processing tier, Tetra Pak and GEA Group occupy positions exemplifying end-to-end automation capabilities and specialized continuous freezer engineering respectively. Alfa Laval anchors the heat exchanger-anchored archetype through pasteurizer supply relationships with large-scale dairy cooperatives. These three entities represent distinct competitive positioning vectors: integrated line contracting, precision refrigeration manufacturing, and thermal treatment component supply.
| Leading Market Players |
|---|
| Alfa Laval |
| SPX FLOW |
| Tetra Pak |
| ROKK Processing |
| Technogel |
| GEA Group |
| Gram Equipment |
| Snowball Machinery |
| Carpigiani Group |
| Others |
Supply Flow & Price Mechanics
Low-global-warming-potential refrigerant feedstock costs cascade through equipment pricing tiers, compressing margins on economy-grade continuous freezers while premium batch freezer configurations absorb input volatility through extended service bundling.
Pricing Analysis
Capacity additions in Southern Germany and Northern Italy are reshaping price floors for high-overrun continuous freezer systems. Three-tier pricing structure across premium, standard, and economy levels separates GEA Group's specialized architectures from modular subsystem fabricators and entry-level batch equipment. Price differentiation hinges on CE marking tier and after-sales service attachment depth. Pricing pressure stems from refrigerant input cost volatility concentrated among limited chemical producers. Food service chains exhibit lowest price sensitivity due to centralized procurement authority, while emerging Vietnamese cooperatives face acute budget constraints.
Supply Chain Analysis
Dual-sourcing requirements from large-scale dairy cooperatives mandate multi-supplier qualification for compressor and heat exchanger components. Manufacturing gravity centers on Italy, Germany, and Denmark for precision refrigeration engineering. Component sourcing draws from specialized valve suppliers in Northern Italy and control system fabricators in Southern Germany. Single-source vulnerability concentrates in proprietary refrigeration architectures. Distribution runs through direct manufacturer relationships for integrated processing lines and regional distributor partnerships for mid-scale installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in retrofit digitalization modules and premium-tier homogenizer specifications as formulation complexity escalates across plant-based processing.
For Market Incumbents: To counter procurement centralization at multinational quick-service restaurant headquarters, anchor direct relationships through lifecycle service bundling and predictive maintenance module integration. Deepen backward integration into heat exchanger manufacturing to defend margin position against refrigerant cost volatility. Prioritize certification investment for simultaneous EU CE marking, US FDA compliance, and China GB standards to compress documentation cycles. For New Entrants and Emerging Players: The price-point gap between premium Italian batch freezers and economy Chinese equipment creates white-space opportunity in Southeast Asian financing-linked installations. Target Vietnam and Indonesia dairy cooperatives lacking continuous freezer infrastructure through equipment-as-a-service models. Penetrate private label manufacturer segments with modular subsystem architectures that permit independent upgrade paths without full-system replacement. For Investors and Strategic Acquirers: Consolidation pressure builds where precision refrigeration engineering expertise clusters geographically in Northern Italy and Southern Germany. Long-term viability favors vendors with verified lifecycle emissions data under CSRD disclosure frameworks. Target acquisition archetype: mid-scale modular subsystem fabricators with IoT-enabled predictive maintenance capabilities. Watch refrigerant transition timeline adherence as inflection indicator for stranded asset risk exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Retrofit Digitalization Convergence | IoT-enabled predictive maintenance modules penetrate legacy installed bases, opening recurring revenue streams. |
| Refrigerant Architecture Redesign | Heat exchanger and compressor specifications must accommodate hydrofluoroolefin and natural refrigerant alternatives. |
| Modular Subsystem Standardization | Configurable refrigeration skids and independent upgrade paths compress capital commitment thresholds for mid-scale cooperatives. |
| CSRD-Aligned Lifecycle Data Investment | Verified emissions documentation advantages manufacturers in institutional procurement under EU Corporate Sustainability Reporting Directive. |
| Financing-Linked Installation Partnerships | Equipment vendors capture first-mover advantage in Vietnam and Indonesia through wholesale arrangements with emerging cooperatives. |
Methodological Framework
Multiple input streams — equipment manufacturer technical specifications, dairy cooperative procurement records, and regulatory filing databases — were reconciled through bottom-up and top-down triangulation. Primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors at dairy processing facilities across Germany, Italy, Netherlands, and Vietnam were cross-validated against secondary sources including EU F-Gas Regulation compliance filings, FDA Grade A Pasteurized Milk Ordinance documentation, customs trade records, and SEC equipment manufacturer disclosures.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include equipment type, application viscosity requirements, end-user procurement authority concentration, and distribution channel technical complexity. CAGRs were derived from installed base replacement cycle analysis and emerging market penetration assumptions. Industry-specific forecast inputs incorporated EU refrigerant phase-out timelines and artisanal automation capital deployment patterns in Italy's Emilia-Romagna cluster.
The model assumes a particular technology adoption path; alternative pathways for natural refrigerant system deployment would alter the outlook if hydrofluoroolefin supply constraints accelerate. Forecasts reflect assumptions on regulatory enforcement consistency and vocational training pipeline output for low-global-warming-potential technician certification. Deviation in EU F-Gas Regulation deadline adherence or Southeast Asian dairy cooperative financing availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Loss-In-Weight Feeder Market
Food Processing Equipment
Brewing Thermometer Market
Food Processing Equipment
Walk-In Refrigerator Market
Food Processing Equipment
Hydrostatic Steam Blancher Market
Food Processing Equipment
Shrimp Peeling Machine Market
Food Processing Equipment
Spray Dried Food Market
Food Processing Equipment
Tangyuan Machine Market
Food Processing Equipment
Industrial Planetary Mixers Market
Food Processing Equipment
Food Slicer and Dicer Market
Food Processing Equipment
Food Processing Equipment Market
Food Processing Equipment
Fish Processing Equipment Market
Food Processing Equipment
Commercial Beverage Blender Market
Food Processing Equipment
Vee Bee Consistometer Market
Food Processing Equipment
Freshwater Flake Ice Machine Market
Food Processing Equipment
High-Pressure Processing Equipment Market
Food Processing Equipment
Food Industry Pulsed Electric Field (PEF) Systems Market