
 Prepared Food Equipment Market | 2026-2036
Prepared Food Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Prepared Food Equipment Market Analysis
Cloud kitchen operators are reorganizing the buyer landscape for prepared food equipment, displacing traditional full-service restaurants as the primary volume purchasers. Middleby Corporation dominates this shift through its extensive portfolio of automated cooking platforms designed for minimal footprint and maximum output. Heat and Control, Inc. anchors its position in thermal processing equipment for ready-to-eat protein applications. Bühler Group differentiates through integrated solutions spanning mixing, thermal treatment, and packaging for plant-based prepared foods.
Prepared food equipment encompasses commercial-grade machinery engineered for cooking, mixing, frying, and thermal processing of partially or fully prepared food products, typically constructed from stainless steel with temperature tolerances exceeding 300°C and designed for continuous washdown sanitation cycles. Ovens and fryers command the largest installed base due to their ubiquity across restaurant and catering operations, though induction-based technologies are gaining fastest among urban operators seeking energy efficiency and precise thermal control. Mixers occupy a mature, replacement-driven segment where margin pools concentrate in planetary and spiral configurations for high-viscosity dough and batter applications.
The FDA food code and NSF/ANSI standards govern equipment sanitation and material safety in the United States, while the EU Machinery Directive and CE marking regulate mechanical safety and electromagnetic compatibility across European installations. These frameworks compel manufacturers to engineer seamless clean-in-place systems and traceable material certifications as baseline market access requirements. Stakeholders must monitor how evolving energy efficiency mandates and carbon disclosure rules reshape equipment specification criteria across major procurement accounts.
Market Dynamics
Cloud kitchen proliferation is compressing equipment footprint requirements while simultaneously demanding throughput parity with traditional restaurant installations, forcing manufacturers to reengineer thermal systems for vertical density rather than floor-area expansion.
Growth Catalysts
- NSF/ANSI Sanitation Standards:Updated washdown certification requirements are accelerating replacement cycles in United States foodservice operations as operators face inspection compliance deadlines.
- Induction Technology Maturation:Precise thermal control and energy efficiency gains are pulling urban operators away from gas-fired equipment in dense metropolitan clusters.
- Plant-Based Protein Processing:Extrusion and thermal treatment equipment demand is concentrating in Germany and China as alternative protein production scales.
Market Restraints
- Stainless Steel Input Volatility:Grade 304 and 316 alloy price swings compress margin visibility for equipment fabricators locked into fixed-price municipal contracts.
- Electronics Supply Concentration:Induction control modules and IoT sensors concentrate in East Asian semiconductor foundries, exposing lead time vulnerability.
- Clean-in-Place Technical Ceiling:Current spray-ball and turbulent-flow designs face hard limits accessing complex heat exchanger geometries without disassembly.
Strategic Opportunities
- India Cloud Kitchen Infrastructure:Underpenetrated automated cooking platform deployment offers first-mover positioning as Swiggy and Zomato expand dark kitchen networks.
- EU Energy Efficiency Mandates:Ecodesign Directive updates and national carbon disclosure rules create specification tailwinds for heat-recovery oven systems.
- Predictive Maintenance Convergence:IoT sensor integration with thermal imaging is opening subscription revenue streams separate from equipment sale economics.
Industry Challenges
- Mechatronics Talent Scarcity:Cross-functional engineers capable of integrating thermal, mechanical, and software systems command premium compensation in competitive labor pools.
- Multi-Certification Timelines:Simultaneous FDA food code, NSF/ANSI, and CE marking processes extend product launch windows by 8-14 months.
- Legacy Control Integration:Proprietary communication protocols in installed base equipment obstruct seamless retrofit of smart monitoring modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prepared Food Equipment Market |
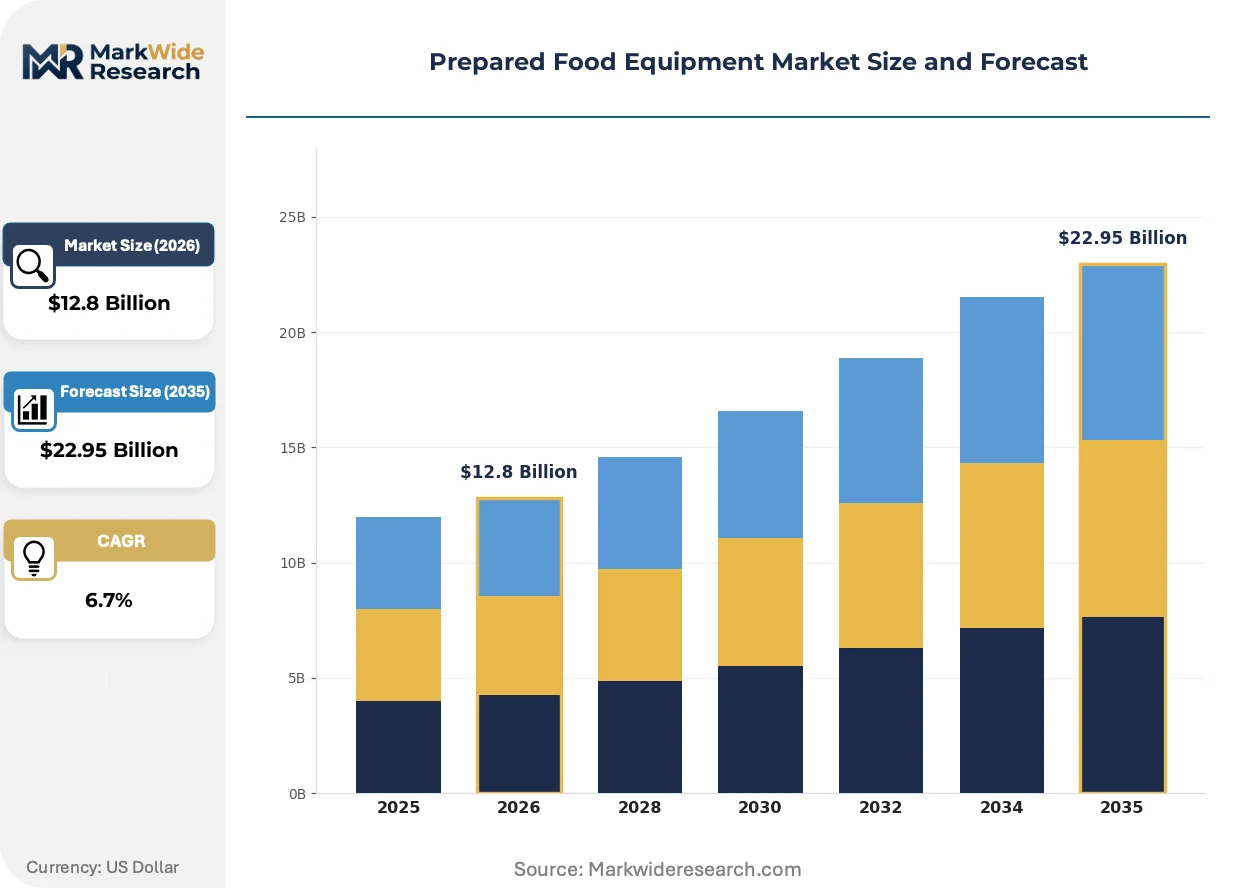
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ovens, Griddles, Fryers, Mixers Technology: Convection, Steam, Induction, Radiant End User: Restaurants, Catering Services, Food Trucks, Bakeries Installation: Countertop, Standalone, Integrated, Mobile |
| Companies Covered | Middleby Corporation, Heat and Control, Inc., Bühler Group, GEA Group Aktiengesellschaft, Marel, JBT Corporation, Tetra Laval S.A., Ali Group, Multivac Sepp Haggenmüller SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prepared Food Equipment Market Emerging Trajectories
Equipment intelligence and thermal efficiency are converging to redefine competitive differentiation, with connectivity and precision control now table stakes rather than premium features.
Induction heating technology is fragmenting traditional gas equipment dominance across high-throughput frying and sauté applications. Cloud kitchen operators in Singapore and Dubai are specifying all-electric kitchens to sidestep ventilation complexity and accelerate permitting. This shift is fragmenting the historical gas-electric equipment mix and compressing aftermarket parts revenue tied to combustion systems.
REACH substance restrictions and F-Gas Regulation phase-down schedules are forcing refrigerant and insulation material substitutions in European thermal equipment. Manufacturers are engineering vacuum-insulated panels and natural refrigerant loops to maintain performance envelopes. Ready-to-eat protein processors in Germany and the Netherlands face the steepest compliance curves given their installed base of legacy ammonia and HFC systems.
Equipment-as-a-service contracting is displacing capital purchase models among mid-scale catering operators and institutional foodservice buyers. Monthly fee structures bundle maintenance, sanitation validation, and technology refresh cycles into predictable operating expenditures. This pattern is most visible in United States healthcare and education verticals where budget cycle constraints favor opex flexibility over balance sheet impact.
Prepared Food Equipment Market Segmentation
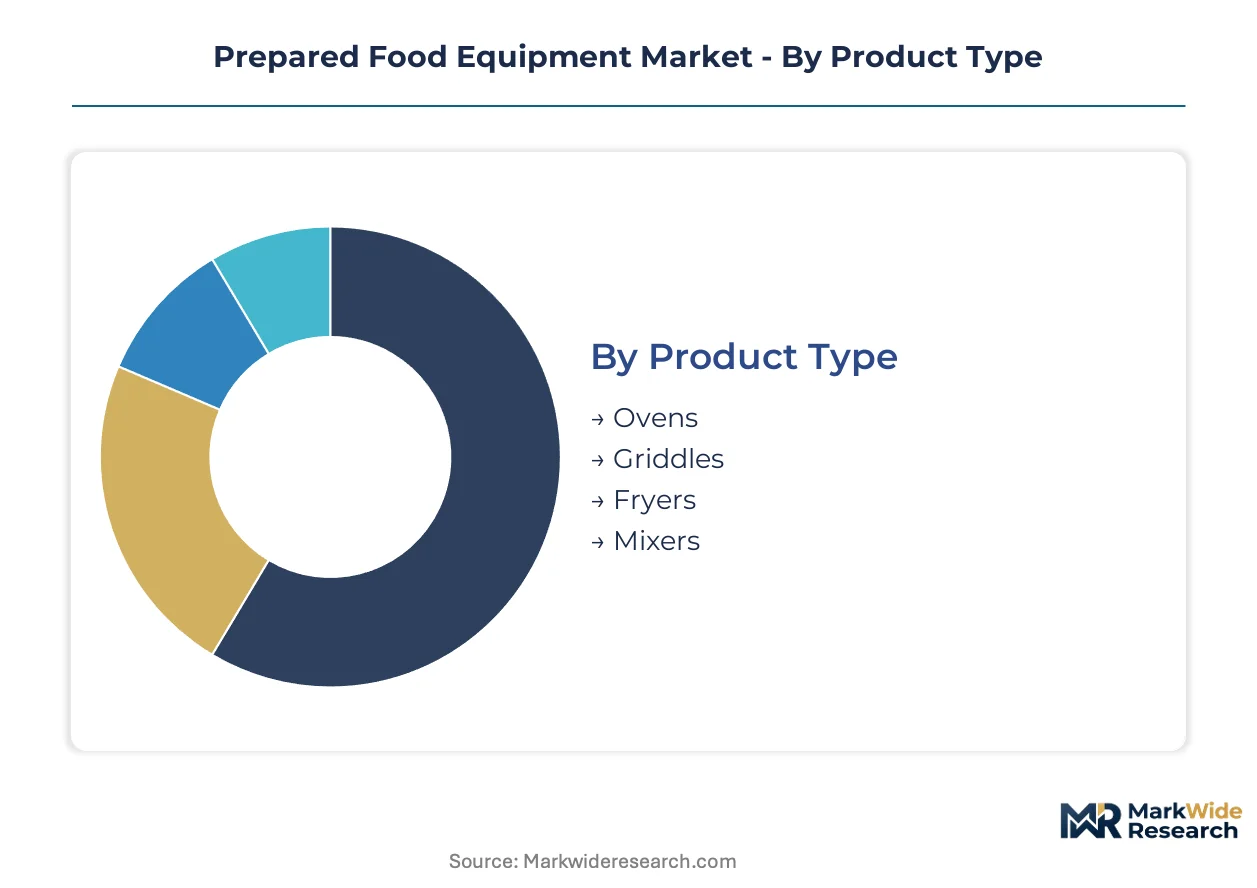
Equipment specification patterns diverge sharply between domestic foodservice operators and export-oriented manufacturers targeting cloud kitchen rollouts. Procurement priorities across each segment reflect this geographic split in deployment models.
Product Type:
Domestic demand concentrates in fryers and ovens for full-service restaurant retrofits, while export-led growth flows through compact griddles and mixers for cloud kitchen containerized builds.
- Ovens:Thermal processing chambers engineered for convection, steam, or radiant heat distribution, typically constructed with 304-grade stainless steel interiors rated for continuous 300°C operation. Cloud kitchen operators in Singapore and Dubai specify these for vertical stacking configurations to maximize throughput per square meter in dense urban cores.
- Fryers:Oil-immersion cooking vessels with automated filtration and temperature recovery systems designed for high-volume protein and starch processing. United States fast-casual chains drive replacement cycles here as NSF/ANSI washdown certification deadlines approach for installed gas-fired units.
- Griddles:Flat-surface conductive heating platforms for protein and breakfast item preparation, increasingly specified with induction elements to bypass ventilation infrastructure.
- Mixers:Planetary and spiral configurations for dough and batter applications, with planetary designs dominating bakery end-use for high-viscosity formulations.
Ovens command the established base. The steepest expansion runs through fryers as cloud kitchen operators prioritize high-throughput protein processing.
Technology:
Cost tiering separates premium induction systems from standard convection and economy radiant configurations, with steam technology occupying a mid-tier niche for health-focused operators.
- Induction:Electromagnetic field generation through copper coil assemblies enables precise wattage modulation and instantaneous thermal response. Urban operators in Germany and the Netherlands specify these to satisfy EU Ecodesign Directive efficiency mandates and eliminate combustion ventilation costs.
- Convection:Forced-air circulation through turbine-driven heat distribution achieves uniform product finish across batch loads. United States institutional foodservice buyers favor these for volume baking and roasting applications where consistency outweighs energy premium.
- Steam:Saturated vapor injection systems for moisture-retentive cooking of vegetables, seafood, and rethermalization applications.
- Radiant:Infrared emitter arrays for direct surface browning, predominant in legacy installed base equipment across price-sensitive markets.
Convection retains the broadest installed footprint. Induction gains share fastest as metropolitan permitting constraints tighten.
End User:
Application intensity varies by operational scale, with catering services and food trucks demanding portable configurations while restaurants and bakeries anchor stationary high-volume procurement.
- Restaurants:Full-service and fast-casual operators with fixed-location kitchens requiring NSF/ANSI-certified equipment for inspection compliance. United States chains are consolidating vendor relationships to secure sanitation validation documentation ahead of FDA food code enforcement waves.
- Catering Services:Event-based and contract foodservice operators with mobile deployment requirements and seasonal demand fluctuation. These buyers in India and the UAE are piloting equipment-as-a-service contracts to convert capital expenditure into operating budgets.
- Food Trucks:Constrained-footprint mobile operators prioritizing all-electric specifications to simplify power generation and ventilation design.
- Bakeries:Specialized operators requiring precise humidity control and consistent thermal profiles for fermentation and crust development.
Restaurants anchor procurement volume. Food trucks represent the steepest climb as mobile foodservice licensing expands across Indian and Southeast Asian metropolitan zones.
Installation:
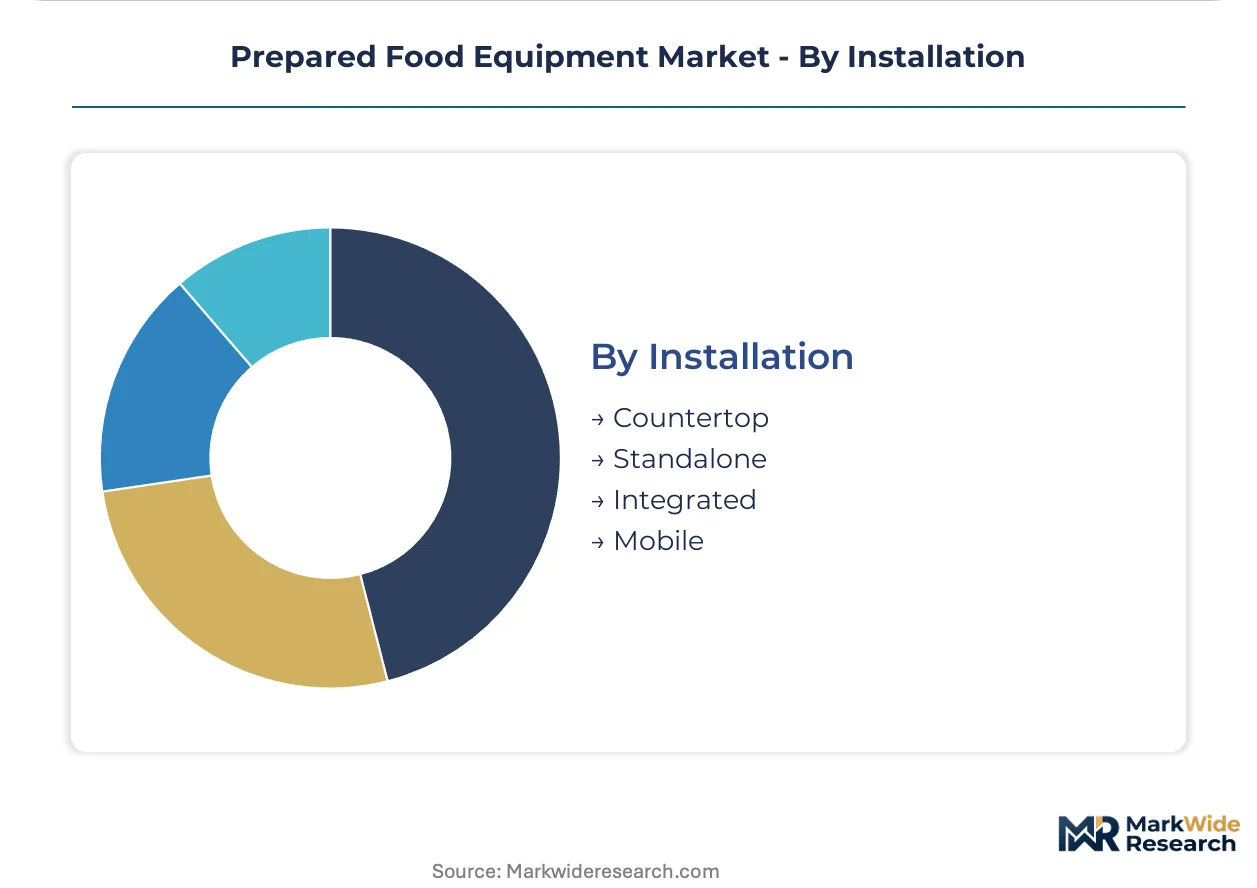
Customer type stratification separates enterprise buyers specifying integrated systems from independent operators selecting countertop or standalone units.
- Countertop:Compact plug-and-operate units designed for front-of-house display cooking and back-of-house supplementary capacity. Cloud kitchen operators in London and New York deploy these for rapid menu testing without infrastructure modification.
- Standalone:Floor-mounted equipment with independent utility connections and castor mobility for flexible kitchen layouts. Germany's ready-to-eat protein processors favor these for clean-in-place accessibility and modular line reconfiguration.
- Integrated:Custom-engineered equipment suites built into production line sequences with centralized control architecture.
- Mobile:Ruggedized units with suspension mounting and quick-disconnect utilities for food truck and field catering deployment.
Standalone configurations dominate current deployment. Integrated systems are climbing fastest as automated production lines scale in China and Germany.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment fabricators dominate export flows to cloud kitchen operators across Singapore and Dubai, while United States manufacturers serve domestic fast-casual replacement cycles and Chinese producers scale automated lines for plant-based protein processing.
United States
Fast-casual chains and institutional foodservice buyers drive replacement demand as NSF/ANSI washdown certification deadlines approach for installed gas-fired fryers and ovens. FDA food code enforcement waves compel operators to consolidate vendor relationships for sanitation validation documentation. Equipment procurement concentrates in Texas and the Southeast where cloud kitchen operators pilot containerized builds.
Germany
Ready-to-eat protein processors and plant-based alternative manufacturers anchor thermal processing equipment demand as extrusion capacity scales. EU Ecodesign Directive efficiency mandates and F-Gas Regulation phase-down schedules force refrigerant and insulation material substitutions. Industrial clusters in Bavaria and North Rhine-Westphalia engineer vacuum-insulated panels and natural refrigerant loops for compliance.
China
Automated production line deployment for alternative protein manufacturing concentrates equipment procurement in Yangtze River Delta and Pearl River Delta manufacturing zones. MIIT industrial upgrading programs and dual carbon goals accelerate induction-based thermal system adoption over legacy gas infrastructure. Shanghai and Shenzhen-based operators specify compact high-throughput platforms for vertical density.
India
Swiggy and Zomato cloud kitchen network expansion drives underpenetrated automated cooking platform deployment across Maharashtra and Karnataka. FSSAI food safety compliance requirements and state-level municipal permitting create specification hurdles for imported equipment. Mumbai and Bengaluru operators pilot equipment-as-a-service contracts to convert capital expenditure into operating budgets.
Singapore
Delivery-focused restaurant chains and dark kitchen operators specify all-electric kitchen configurations to bypass ventilation complexity and accelerate municipal permitting. NEA environmental regulations and carbon disclosure frameworks favor heat-recovery oven systems and induction griddles. Central Business District and Jurong food production zones concentrate containerized kitchen deployments.
Prepared Food Equipment Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with thermal processing heritage, creating a tiered structure where scale-driven manufacturers compete against specialized automation integrators. Strategic archetypes include full-line system integrators bundling mixing through packaging, component specialists dominating single-equipment categories, and regional fabricators serving price-sensitive replacement cycles. Competitive moves center on portfolio diversification into adjacent thermal technologies and strategic partnerships with cloud kitchen operators for specification lock-in.
Among diversified system integrators, Middleby Corporation and Bühler Group occupy positions exemplifying the full-line archetype spanning cooking through packaging workflows. Heat and Control, Inc. represents the component specialist tier with concentrated positioning in thermal processing equipment. These three anchors illustrate how competitive positioning fragments between breadth-driven conglomerates and depth-focused specialists, with each archetype commanding distinct margin pools based on specification complexity and integration scope.
| Leading Market Players |
|---|
| Middleby Corporation |
| Heat and Control, Inc. |
| Bühler Group |
| GEA Group Aktiengesellschaft |
| Marel |
| JBT Corporation |
| Tetra Laval S.A. |
| Ali Group |
| Multivac Sepp Haggenmüller SE & Co. KG |
| Others |
Supply Flow & Price Mechanics
Fourteen-to-eighteen-week lead times for induction control modules from East Asian semiconductor foundries compress margin visibility for equipment fabricators while simultaneously anchoring pricing power with component suppliers who command premium terms for expedited delivery.
Pricing Analysis
Current-generation induction systems command 40-60% premiums over prior-generation gas-fired equivalents, while next-generation IoT-integrated platforms layer additional subscription fees atop hardware costs. Pricing stratifies across NSF/ANSI-certified premium tiers, CE-marked standard configurations, and economy radiant systems for price-sensitive replacement cycles. Cost compression in economy tiers is intensifying because municipal contract bidders face fixed-price commitments amid stainless steel alloy volatility. Cloud kitchen operators exhibit lowest price sensitivity due to throughput-per-square-meter prioritization, while independent food truck vendors drive hardest bargain negotiations.
Supply Chain Analysis
China and Germany anchor stainless steel fabrication capacity for Grade 304 and 316 alloy components, while Taiwan and South Korea concentrate induction coil and semiconductor control module production. Equipment assembly draws from copper coil assemblies, 304-grade stainless steel sheet, and IoT sensor arrays as core inputs. Single-source vulnerability concentrates in East Asian semiconductor foundries where geopolitical friction threatens control module availability. Distribution runs through manufacturer-direct sales for integrated systems and specialized foodservice equipment distributors for standalone and countertop configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment specification fragmentation across cloud kitchen, plant-based protein, and traditional foodservice archetypes creates multiple niche entry points for specialized competitors.
For Market Incumbents: Shield installed base relationships through captive aftermarket service contracts and backward integration into IoT sensor modules to reduce semiconductor supply exposure. Prioritize NSF/ANSI certification investment ahead of FDA food code enforcement waves to lock out non-compliant imports. Vertical control over thermal imaging predictive maintenance software preserves recurring revenue streams against pure-hardware competitors. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Germany opens specification access to EU Ecodesign Directive-mandated efficiency upgrades. Target India's underpenetrated cloud kitchen infrastructure where Swiggy and Zomato network expansion outpaces domestic fabrication capacity. Lead with equipment-as-a-service contracting to bypass capital expenditure barriers among mid-scale catering operators. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core thermal processing divisions with stranded plant-based protein expertise. Five-to-ten-year viability hinges on software-enabled service revenue attachment rates exceeding hardware margin erosion. Monitor F-Gas Regulation compliance cost curves as inflection signal for European equipment replacement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Contracting | Converts capital expenditure to operating budgets for healthcare and education verticals. |
| Backward Integration into IoT Modules | Reduces semiconductor supply vulnerability and captures predictive maintenance subscription revenue. |
| NSF/ANSI Certification Fast-Track | Accelerates market access ahead of FDA food code enforcement deadlines in United States. |
| Heat-Recovery Oven System Development | Aligns product portfolios with EU Ecodesign Directive efficiency mandates in Germany. |
| Cloud Kitchen Operator Partnership | Locks in specification preference for compact high-throughput platforms in Singapore and Dubai. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cloud kitchen procurement directors, equipment fabrication plant managers, NSF/ANSI certification auditors, and aftermarket service technicians. Secondary validation incorporated FDA food code documentation, EU Machinery Directive technical files, SEC 10-K filings from diversified equipment manufacturers, and customs trade data for stainless steel alloy imports. Bottom-up equipment shipment tallies triangulated against top-down foodservice capital expenditure estimates.
Across the analysis window, forecasts segment by product type, technology generation, end-user operational scale, and installation configuration complexity. CAGRs derive from equipment replacement cycle modeling, cloud kitchen rollout trajectories, and regulatory compliance deadline clustering. Key inputs include stainless steel price indices, municipal permitting velocity in dense metropolitan clusters, and induction technology adoption curves.
Underlying assumptions cover sustained cloud kitchen network expansion, stable NSF/ANSI certification timelines, and intact East Asian semiconductor supply chains, with deviation risk concentrated in trade policy shifts and alloy price volatility. Recalibration cycles align with material shifts in FDA enforcement waves, F-Gas Regulation phase-down schedules, and MIIT industrial upgrading program announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Ice Maker Market
Food Service Equipment
Multi-Deck Refrigerated Display Cases Market
Food Service Equipment
Global Roti Maker Market
Food Service Equipment
Popcorn Machine Market
Food Service Equipment
North America Countertop Ice Makers Market
Food Service Equipment
Autonomous One-Pot Cooking System Market
Food Service Equipment
Combi Cooler Market
Food Service Equipment
Commercial Ventless Cooking Equipment Market
Food Service Equipment
Commercial Stainless Steel Cooking Equipment Market
Food Service Equipment
Global Commercial Cooking Equipment Market
Food Service Equipment
Restaurant Fryers Market
Food Service Equipment
Industrial Dishwasher Market
Food Service Equipment
Hospital Foodservice Equipment Market
Food Service Equipment
Global Glass Door Cooler Market
Food Service Equipment
North America Fountain Dispenser Equipment Market
Food Service Equipment
Cooking Hood Market