
 Mexico Fruits & Vegetables Market | 2026-2036
Mexico Fruits & Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Fruits & Vegetables Market Insights
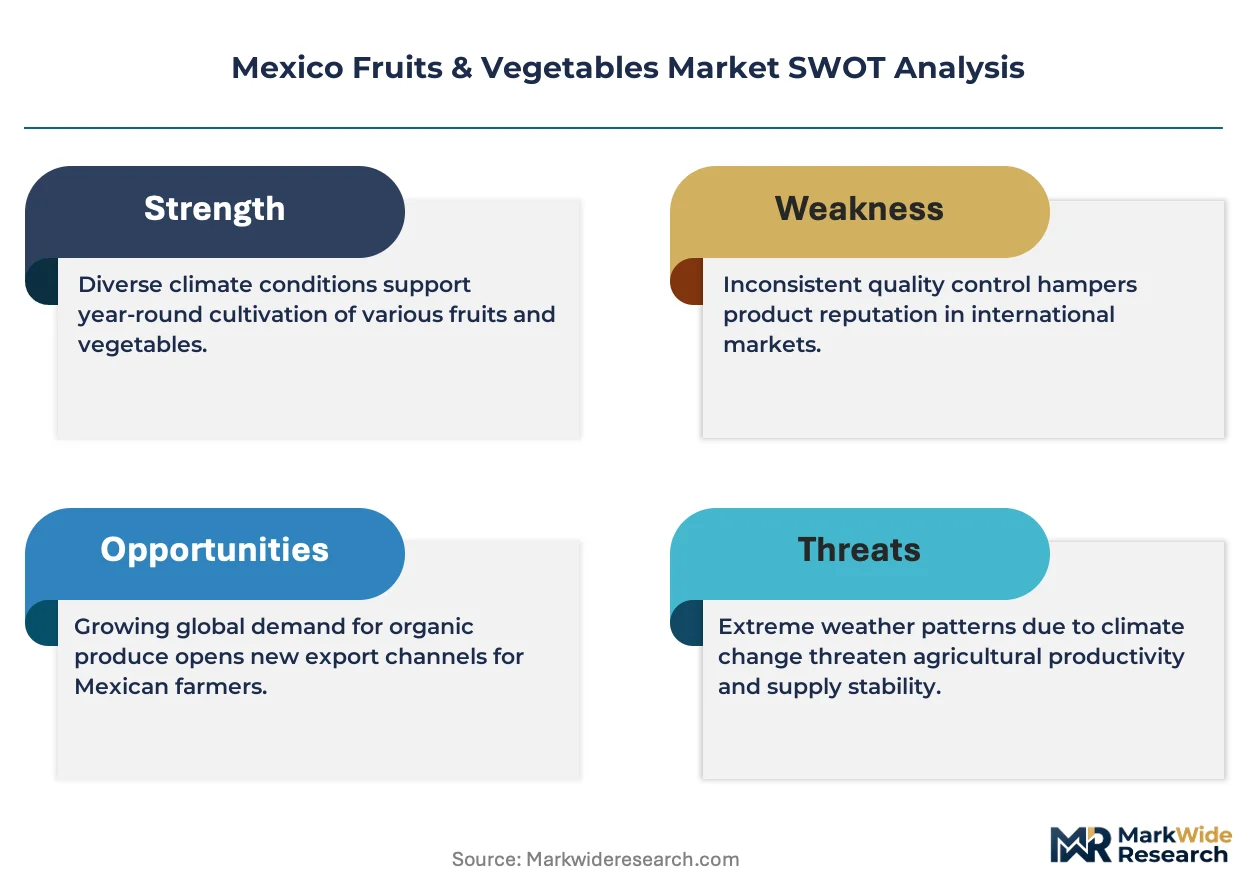
Sinaloa's controlled-environment greenhouse capacity is decoupling from traditional open-field cycles, extending tomato and bell pepper harvest windows by four to six months annually. Grupo Driscoll's de México leverages its proprietary berry genetics program to dominate the high-value raspberry and blackberry segments. Wonderful Citrus sustains integrated orchard-to-port operations across Sonora and Tamaulipas, controlling cold-chain integrity for export-grade grapefruit and mandarin shipments.
Mexico fruits and vegetables encompass fresh, minimally processed, and value-added horticultural products cultivated across diverse agro-climatic zones, with shelf-life parameters ranging from three days for leafy greens to eight weeks for refrigerated citrus under optimal post-harvest handling. The primary commercial purpose centers on supplying domestic retail and foodservice channels while fulfilling North American export contracts governed by phytosanitary compliance protocols. Citrus and berries command disproportionate margin pools due to per-unit value density and established export infrastructure, while root vegetables anchor volume throughput through stable institutional procurement. The organic quality grade segment attracts premium positioning as retailers consolidate certified sourcing programs, though conventional production retains scale dominance through established distributor relationships.
Secretaría de Agricultura y Desarrollo Rural (SADER) sets federal phytosanitary benchmarks that determine export eligibility to US and Canadian markets, while COFEPRIS enforces maximum residue limits for domestic retail distribution. These regulatory frameworks compel growers to maintain dual-certification protocols, elevating compliance costs for smaller operators. Stakeholders must monitor evolving SADER inspection frequency and COFEPRIS label disclosure mandates to anticipate margin compression points and redirect investment toward traceability infrastructure.
Market Dynamics
COFEPRIS residue limit enforcement and SADER export certification protocols are compressing margins for non-compliant operators while accelerating consolidation toward integrated packers with captive cold-chain infrastructure.
Growth Catalysts
- Quick-service restaurant expansion:Chains across Mexico City and Monterrey are expanding fresh produce procurement as consumer menus pivot toward healthier options, pulling volume through contracted distributor networks.
- Controlled-environment agriculture:Sinaloa greenhouse operators are extending tomato and bell pepper harvest windows by four to six months, decoupling from traditional open-field seasonality constraints.
- Organic certification demand:Retailer consolidation of certified sourcing programs is creating premium positioning channels for growers meeting SADER organic benchmarks.
Market Restraints
- Input cost volatility:Fertilizer and agricultural chemical prices fluctuate with global commodity markets, squeezing margin predictability for open-field operators in Michoacán and Jalisco.
- Phytosanitary compliance friction:Dual-certification requirements under SADER export protocols and COFEPRIS domestic standards elevate fixed costs for sub-scale growers below fifty hectares.
- Water access concentration:Irrigated farmland expansion concentrates in the Bajío corridor, leaving rain-dependent regions in Oaxaca and Chiapas structurally disadvantaged for year-round output.
Strategic Opportunities
- Value-added processing:Minimally processed and fresh-cut segments remain underdeveloped relative to US penetration rates, creating whitespace for Guanajuato packers with HACCP infrastructure.
- Berry genetics premiumization:Proprietary cultivar programs in Baja California and Jalisco command disproportionate margin pools in raspberry and blackberry segments through extended shelf-life traits.
- Direct-to-retail traceability:Blockchain-enabled lot tracking is opening procurement relationships with Walmart México and Soriana that bypass traditional wholesale intermediaries.
Industry Challenges
- Post-harvest handling skill gaps:Cold-chain management expertise remains concentrated among large integrated operators, limiting smallholder participation in export-grade segments.
- Certification timeline compression:SADER inspection frequency increases are shortening compliance windows, forcing accelerated investment in traceability infrastructure ahead of revenue realization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Fruits & Vegetables Market |
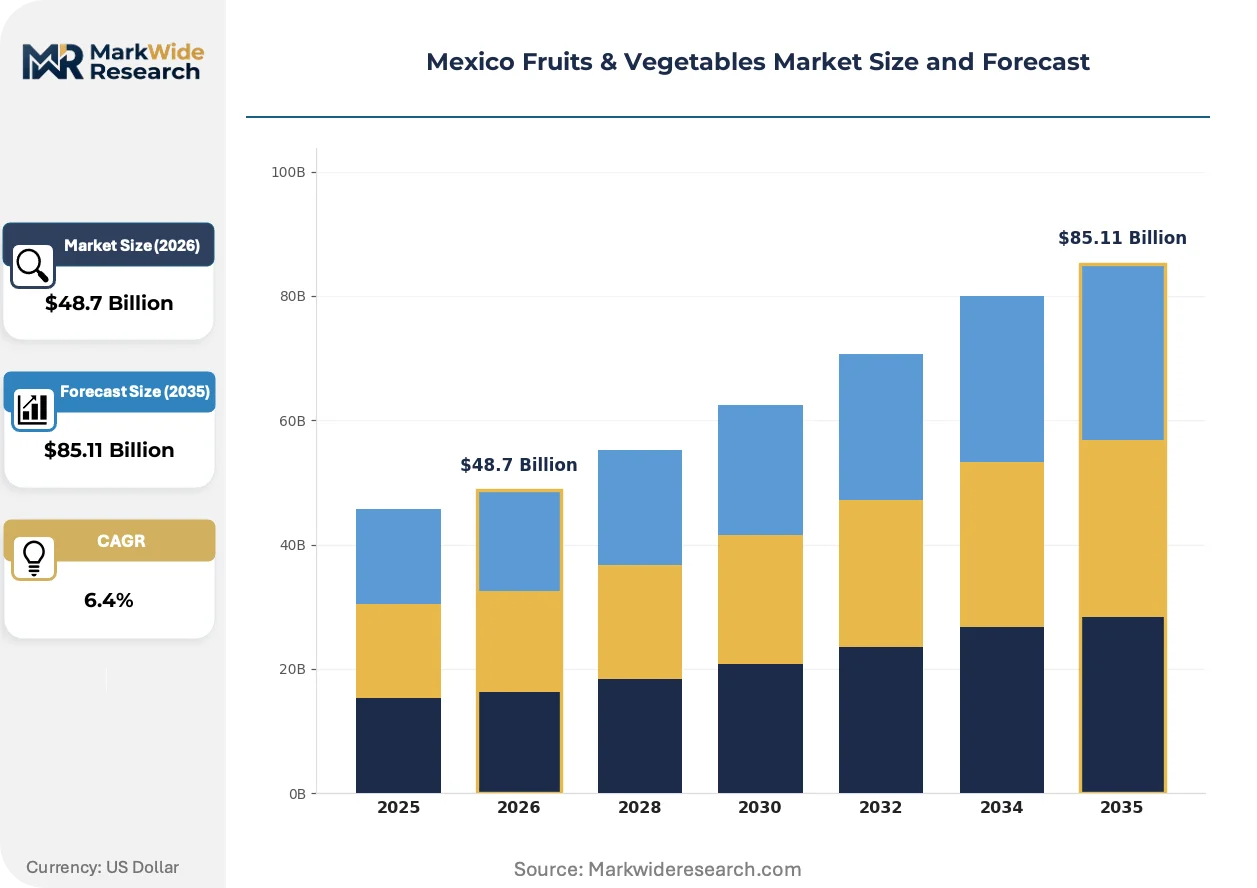
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citrus, Berries, Leafy Greens, Root Vegetables Distribution Channel: Wholesale, Retail, Direct to Consumer, Online Quality Grade: Organic, Conventional, Premium, Standard Packaging Type: Bags, Boxes, Loose, Carts |
| Companies Covered | Grupo Driscoll’s de México, Wonderful Citrus, Hortifrut México, Lineage Logistics, Grupo Alta, Dole PLC, Fresh Del Monte Produce Inc, Chiquita Brands International, Grimmway Farms, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Fruits & Vegetables Market Trends and Innovations
Digital agriculture platforms and precision irrigation systems are reshaping how Mexican growers manage water stress and labor scarcity across fragmented landholdings.
Precision fertigation technology is modularizing input application across greenhouse complexes in Culiacán and Los Mochis. Mid-scale operators with fifty to two hundred hectares are adopting sensor-driven nutrient dosing at accelerated rates. This technology is modularizing capital requirements, enabling phased infrastructure rollout without full-system commitment.
COFEPRIS updated maximum residue limit schedules are tightening enforcement timelines for domestic retail distribution. Growers face accelerated testing frequency and expanded pesticide disclosure requirements. The berry and leafy greens segments are responding fastest, redirecting procurement toward integrated packers with in-house laboratory capabilities.
Foodservice buyers are consolidating procurement relationships toward fewer, larger distributors with multi-category capabilities and documented cold-chain integrity. Traditional open-market purchasing through central de abasto networks is losing share to contracted volume agreements with traceability documentation. This concentration is most visible in Mexico City and Monterrey, where hotel and restaurant chains prioritize supply security over spot-price flexibility.
Mexico Fruits & Vegetables Market Segmentation
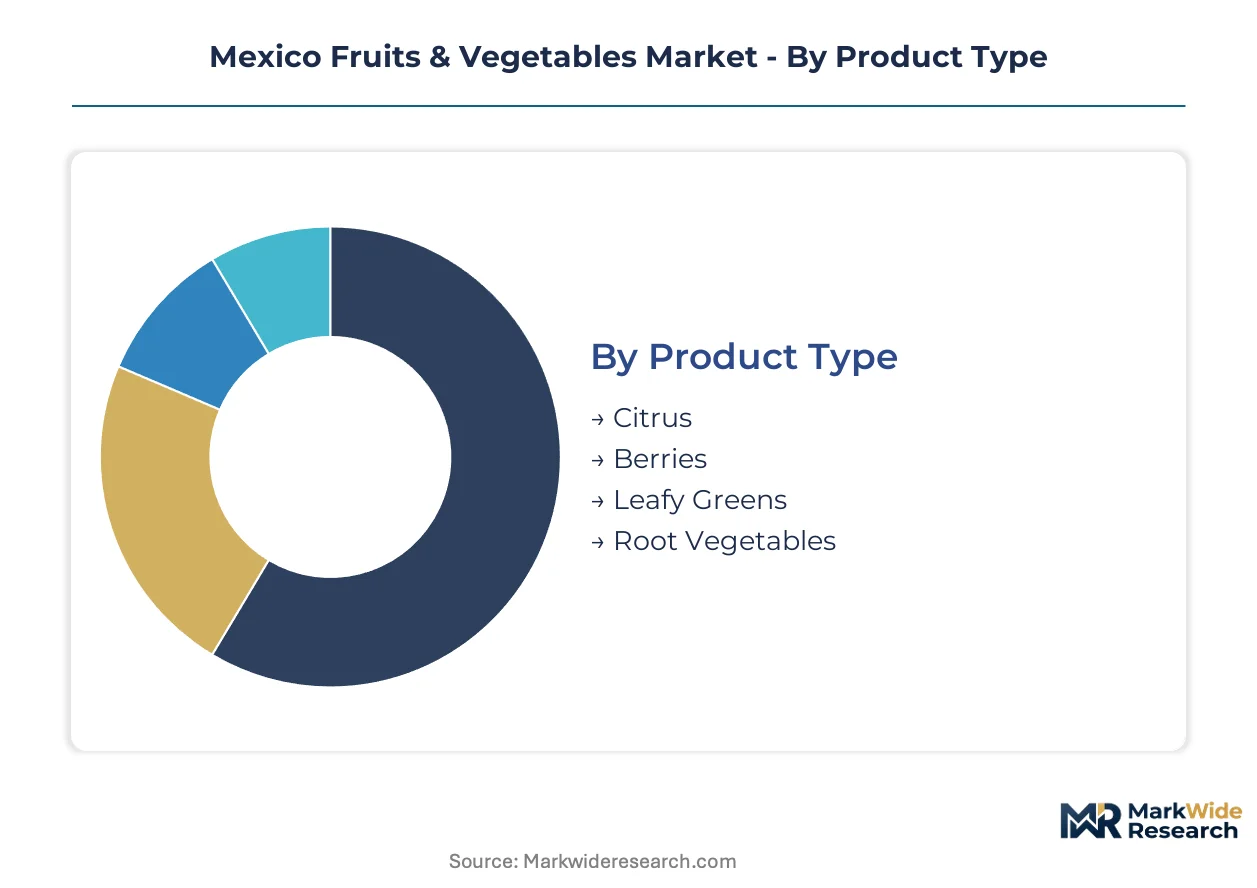
Segmentation reveals how certification burdens, channel economics, and quality premiums stratify Mexico's horticultural supply base. Understanding these divisions exposes where compliance costs concentrate and which segments attract investment in cold-chain infrastructure.
Product Type:
Citrus and berries carry the heaviest dual-certification obligations under SADER export protocols and COFEPRIS domestic residue limits, while root vegetables face lighter phytosanitary scrutiny but thinner margins.
- Citrus:Grapefruit and mandarin varieties dominate Sonora and Tamaulipas orchard belts with eight-week refrigerated shelf life. Wonderful Citrus controls integrated orchard-to-port operations, securing cold-chain integrity for US-bound shipments through captive infrastructure.
- Berries:Raspberry and blackberry production concentrates in Baja California and Jalisco under proprietary genetics programs. Grupo Driscoll's de México leverages cultivar exclusivity to command premium positioning in North American retail channels.
- Leafy Greens:Three-day shelf life demands rapid field-to-cooler logistics concentrated in Guanajuato's Bajío corridor.
- Root Vegetables:Institutional procurement anchors volume throughput for carrots and beets from Michoacán open-field operations.
Leading the category by volume: Root Vegetables. Growing fastest: Berries.
Distribution Channel:
Channel selection determines traceability infrastructure requirements and margin capture potential, with foodservice consolidation favoring integrated packers over fragmented wholesale networks.
- Wholesale:Central de abasto networks in Mexico City and Monterrey still handle substantial volume but lose share to contracted alternatives as buyers prioritize supply security documentation.
- Retail:Walmart México and Soriana procurement relationships increasingly bypass traditional intermediaries through blockchain-enabled lot tracking requirements.
- Direct to Consumer:Farm-level sales concentrate in Oaxaca and Chiapas rain-dependent regions with limited cold-chain reach.
- Online:Last-mile delivery platforms expand fastest in Mexico City metropolitan zone, though perishability constraints limit penetration for leafy categories.
Wholesale retains volume dominance. Online channels climb fastest.
Quality Grade:
Grade stratification reflects input cost differentials and certification timeline compression, with organic segments requiring SADER benchmark compliance and conventional production leveraging established distributor relationships.
- Organic:SADER-certified operations attract retailer consolidation of sourcing programs, commanding premium positioning through documented input prohibition protocols.
- Conventional:Scale dominance persists through established wholesaler relationships and lower fixed compliance burdens for sub-fifty-hectare operators.
- Premium:Proprietary cultivar programs and extended shelf-life traits define this tier in berry and citrus segments.
- Standard:Institutional procurement and price-sensitive retail segments anchor volume here.
Conventional production leads by volume. Organic certification expands most quickly.
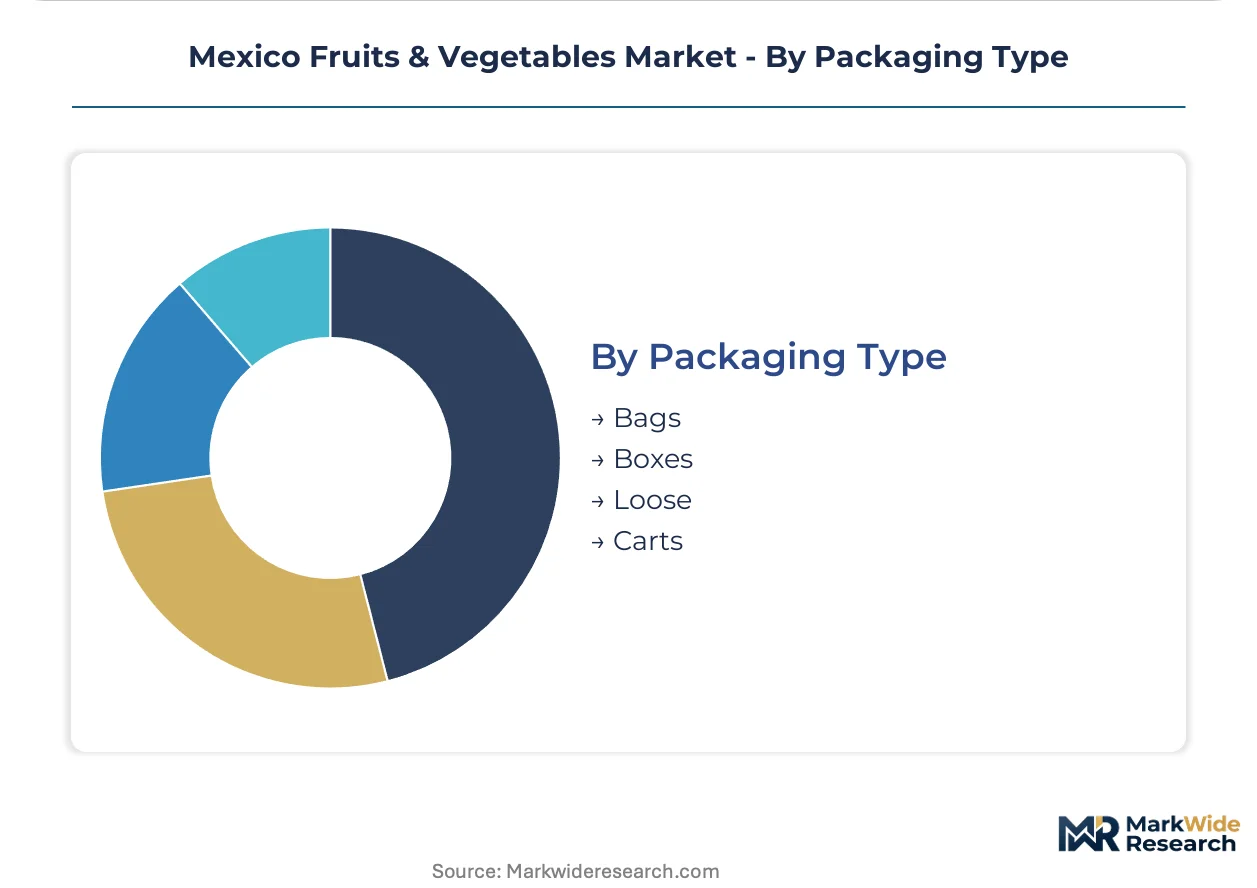
Packaging Type:
Packaging selection intersects with cold-chain capability and retail format requirements, with export-grade segments demanding rigid infrastructure that smallholders struggle to provision.
- Boxes:Corrugated containers dominate export channels for citrus and berries, with specifications set by US retail buyers requiring palletization compatibility.
- Bags:Polyethylene and mesh formats serve domestic retail and wholesale segments with lower unit value density.
- Loose:Bulk handling persists in traditional central de abasto transactions and direct farm sales.
- Carts:Reusable plastic containers gain traction in closed-loop foodservice procurement with documented sanitization protocols.
Boxes lead by volume. Carts gain share fastest in foodservice channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bajío corridor's irrigated farmland anchors Mexico's horticultural output, with Sinaloa's greenhouse infrastructure extending harvest windows beyond traditional open-field cycles.
Bajío Region
Quick-service restaurant chains in Guanajuato and Michoacán pull volume through contracted distributor networks as consumer menus pivot toward healthier options. SADER enforces federal phytosanitary benchmarks that determine export eligibility to US markets. León and Irapuato concentrate tomato and bell pepper packing operations with year-round irrigation infrastructure.
Sinaloa
Controlled-environment greenhouse operators extend tomato and bell pepper harvest windows by four to six months annually. COFEPRIS maximum residue limit schedules tighten enforcement timelines for domestic retail distribution. Culiacán and Los Mochis anchor precision fertigation technology adoption among mid-scale greenhouse complexes.
Baja California
Proprietary berry genetics programs command premium positioning in raspberry and blackberry segments through extended shelf-life traits. SADER organic certification benchmarks attract retailer consolidation of certified sourcing programs. Ensenada and Mexicali concentrate Grupo Driscoll's proprietary cultivar operations for North American export channels.
Nuevo León
Foodservice buyers in Monterrey consolidate procurement toward distributors with multi-category capabilities and documented cold-chain integrity. The state's national food safety regulator enforces phytosanitary protocols under updated federal standards. San Pedro Garza García anchors hotel and restaurant chain procurement relationships prioritizing supply security over spot-price flexibility.
Sonora
Wonderful Citrus sustains integrated orchard-to-port operations controlling cold-chain integrity for export-grade grapefruit and mandarin shipments. SADER inspection frequency increases shorten compliance windows for sub-scale growers. Hermosillo and Navojoa concentrate citrus orchard belts with eight-week refrigerated shelf-life parameters.
Mexico Fruits & Vegetables Market Competitive Landscape
Global majors compete with regional champions across genetics programs and cold-chain infrastructure, creating a tiered structure where scale advantages concentrate among integrated packers. The vendor base stratifies between proprietary cultivar holders, captive logistics operators, and conventional volume players. Three archetypes dominate: genetics-driven premium specialists, vertically integrated logistics controllers, and scale-oriented commodity suppliers. Capacity expansion and strategic partnerships represent the dominant competitive moves as operators seek SADER dual-certification compliance.
Among genetics-driven specialists, Grupo Driscoll's de México and Hortifrut México exemplify the proprietary cultivar tier, occupying positions defined by berry exclusivity and shelf-life trait control. Wonderful Citrus anchors the integrated logistics archetype, representing orchard-to-port cold-chain consolidation. Dole PLC sits within the scale-oriented multinational tier, exemplifying commodity volume throughput across multiple horticultural categories.
| Leading Market Players |
|---|
| Grupo Driscoll's de México |
| Wonderful Citrus |
| Hortifrut México |
| Lineage Logistics |
| Grupo Alta |
| Dole PLC |
| Fresh Del Monte Produce Inc |
| Chiquita Brands International |
| Grimmway Farms |
| Others |
Pricing and Supply Chain Analysis
SADER organic certification benchmarks gate qualified supply access and premium-tier pricing power, compressing margins for conventional operators while rewarding integrated packers with dual-certification infrastructure. COFEPRIS residue limit enforcement tightens further, accelerating price stratification between compliant and non-compliant supply pools.
Pricing Analysis
Cold-chain warranty bundling separates premium export-grade shipments from unbundled domestic wholesale transactions, with integrated operators capturing service-inclusive pricing. Three-tier pricing structure across premium, standard, and economy levels reflects SADER certification grade and volume scale. Pricing pressure stems from fertilizer cost volatility squeezing open-field margins in Michoacán. Quick-service restaurant chains show lowest price sensitivity, prioritizing supply security documentation over spot-rate flexibility.
Supply Chain Analysis
Dual-certification under SADER export protocols and COFEPRIS domestic standards gates supplier eligibility, concentrating qualified volume among integrated packers with captive laboratory infrastructure. Production draws from Sinaloa greenhouse complexes, Baja California berry belts, and Sonora citrus orchards. Supply chain risk centers on water access concentration in the Bajío corridor leaving rain-dependent regions structurally disadvantaged. Distribution runs through contracted distributor networks with documented traceability, displacing traditional central de abasto spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: irrigated farmland expansion limits in the Bajío corridor prop pricing power for qualified operators with year-round output capability.
For Market Incumbents: Anticipate COFEPRIS inspection frequency increases by accelerating traceability infrastructure investment ahead of compliance windows. Defend margin position through backward integration into captive cold-chain logistics, neutralizing post-harvest handling skill gaps that exclude smaller competitors from export-grade segments. For New Entrants and Emerging Players: Mid-scale foodservice buyers in Monterrey and Mexico City represent an underserved archetype consolidating procurement toward multi-category distributors with documented cold-chain integrity. Target minimally processed fresh-cut segments where Guanajuato packers with HACCP infrastructure capture whitespace against underdeveloped US-comparable penetration. Pursue direct-to-retail traceability partnerships bypassing wholesale intermediaries. For Investors and Strategic Acquirers: SADER inspection frequency increases are the leading indicator that consolidation toward integrated packers will accelerate, compressing sub-fifty-hectare operator viability. Position acquisition strategy around mid-scale greenhouse operators with precision fertigation adoption and dual-certification compliance capability. Monitor blockchain-enabled lot tracking adoption rates as the inflection signal for procurement relationship restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Infrastructure Investment | SADER and COFEPRIS compliance capability secures export eligibility and domestic retail access simultaneously. |
| Precision Fertigation Technology Adoption | Sensor-driven nutrient dosing modularizes capital requirements for mid-scale Sinaloa greenhouse operators. |
| Cold-Chain Logistics Integration | Captive orchard-to-port infrastructure controls eight-week refrigerated shelf-life parameters for citrus export. |
| Proprietary Genetics Program Development | Grupo Driscoll's cultivar exclusivity commands premium positioning in North American raspberry and blackberry retail. |
| Blockchain-Enabled Traceability Implementation | Walmart México and Soriana procurement relationships increasingly require documented lot tracking bypassing wholesalers. |
Research Methodology
Document review covered SADER phytosanitary protocol filings, COFEPRIS maximum residue limit schedules, and agricultural trade statistics, complemented by interviews with greenhouse operation managers, cold-chain logistics directors, retail produce buyers, and foodservice procurement leads. Secondary validation drew from customs export records, irrigation infrastructure development reports, and federal agricultural census data. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Market size and growth projections across the analysis window reflect segmented modeling by product type, distribution channel, quality grade, and regional production cluster. CAGRs derive from historical volume trajectories adjusted for irrigation expansion rates, greenhouse capacity buildout, and certification adoption curves. Forecast inputs incorporate SADER inspection frequency trends, COFEPRIS enforcement timeline compression, and quick-service restaurant procurement expansion patterns.
Revisions become necessary when federal phytosanitary protocol amendments, water access policy shifts, or fertilizer commodity price dislocations materialize outside modeled parameters. Forecasts reflect documented assumptions about certification timeline stability and cold-chain infrastructure investment continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Japan Frozen Fruit Puree Market
Fruits and Vegetables
Lemon Juice Concentrate Market
Fruits and Vegetables
United Kingdom Berries Market
Fruits and Vegetables
Europe Canned Fruits Market
Fruits and Vegetables
Button Mushroom Products Market
Fruits and Vegetables
US Vegetable Puree Market
Fruits and Vegetables
Fresh Fruits Market
Fruits and Vegetables
Boysenberry Market
Fruits and Vegetables
North America Fruits & Vegetables Market
Fruits and Vegetables
Mulberry Market
Fruits and Vegetables
Freeze Dried Fruits and Vegetables Market
Fruits and Vegetables
Global Shiitake Mushroom Market
Fruits and Vegetables
Argentina Lime Market
Fruits and Vegetables
US Fruit Puree Market
Fruits and Vegetables
Uruguay Fruits and Vegetables Market
Fruits and Vegetables
Processed Fruits and Vegetables Market