
 Tortilla Machine Market | 2026-2036
Tortilla Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Tortilla Machine Market Analytics
Remote diagnostics and predictive maintenance subscriptions is realigning how tortilla machine vendors capture lifetime value from commercial clients. Gruma Machinery leverages its vertically integrated masa expertise to bundle proprietary software with hardware deployments. Heat and Control anchors North American market presence through extensive field service networks. Alfa Laval competes on thermal engineering specialization, offering precision heat exchangers that reduce energy waste in high-volume tortilla lines.
A tortilla machine is an automated or semi-automated food processing system designed to mix, press, bake, and cool flatbread products from corn or wheat masa, typically operating at temperatures between 150°C and 220°C with throughput rates from 500 to 50,000 units per hour for commercial and industrial bakeries. Automatic systems dominate capital expenditure among large-scale processors seeking labor reduction, while semi-automatic configurations retain strong positions in mid-tier bakeries balancing throughput flexibility with operator oversight. Electric technology leads new installations in urban food manufacturing zones with strict emissions codes, though hybrid gas-electric systems capture growing interest from operators seeking to hedge volatile utility tariffs across multiple geographies.
The US FDA governs food-contact materials and sanitary design standards that dictate stainless steel specifications and clean-in-place requirements for tortilla machines sold into American commercial kitchens. Mexico's national standards body sets complementary mechanical safety and electrical codes that manufacturers must satisfy for cross-border equipment certification. Buyers should monitor how evolving energy efficiency mandates in both jurisdictions reshape total cost-of-ownership calculations and retrofit timing decisions.
Market Dynamics
Automated tortilla production lines are displacing artisanal methods across North American commercial baking, driven by labor scarcity and FDA sanitary design mandates that favor stainless steel continuous-process systems over batch equipment.
Growth Catalysts
- Hybrid gas-electric heating systems:Food manufacturers in Texas and California adopt dual-fuel configurations to hedge volatile utility tariffs while maintaining throughput during grid instability.
- Clean-in-place (CIP) mandates:The US FDA's food-contact surface regulations compel bakery retrofits, accelerating replacement cycles for non-compliant cast-iron and carbon steel equipment.
- Remote diagnostics subscriptions:Predictive maintenance software bundled with hardware deployments captures recurring revenue from Gruma Machinery's vertically integrated masa expertise.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 price swings compress margins for machine fabricators locked into fixed-price municipal contracts.
- Concentrated component supply:Precision heat exchanger manufacturing clusters in northern Italy create lead time vulnerability for North American OEMs.
- Skilled technician scarcity:Mechatronics expertise for automated masa handling systems remains concentrated in Mexico's industrial baking corridors, limiting rapid scaling.
Strategic Opportunities
- US Southwest food manufacturing belt:Arizona and New Mexico industrial parks offer tax incentives for tortilla equipment suppliers establishing regional service hubs.
- Induction baking convergence:Integration of electromagnetic heating with IoT temperature controls enables real-time energy optimization for high-volume lines.
- US Inflation Reduction Act efficiency credits:Commercial bakeries retrofitting to electric or hybrid systems qualify for accelerated depreciation, shortening payback periods.
Industry Challenges
- Legacy PLC integration complexity:Retrofitting predictive maintenance sensors onto 1990s-era Allen-Bradley control architectures demands custom middleware development.
- Sanitary welding certification timelines:AWS D18.1 qualification for food-grade stainless steel joints extends production schedules by eight to twelve weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tortilla Machine Market |
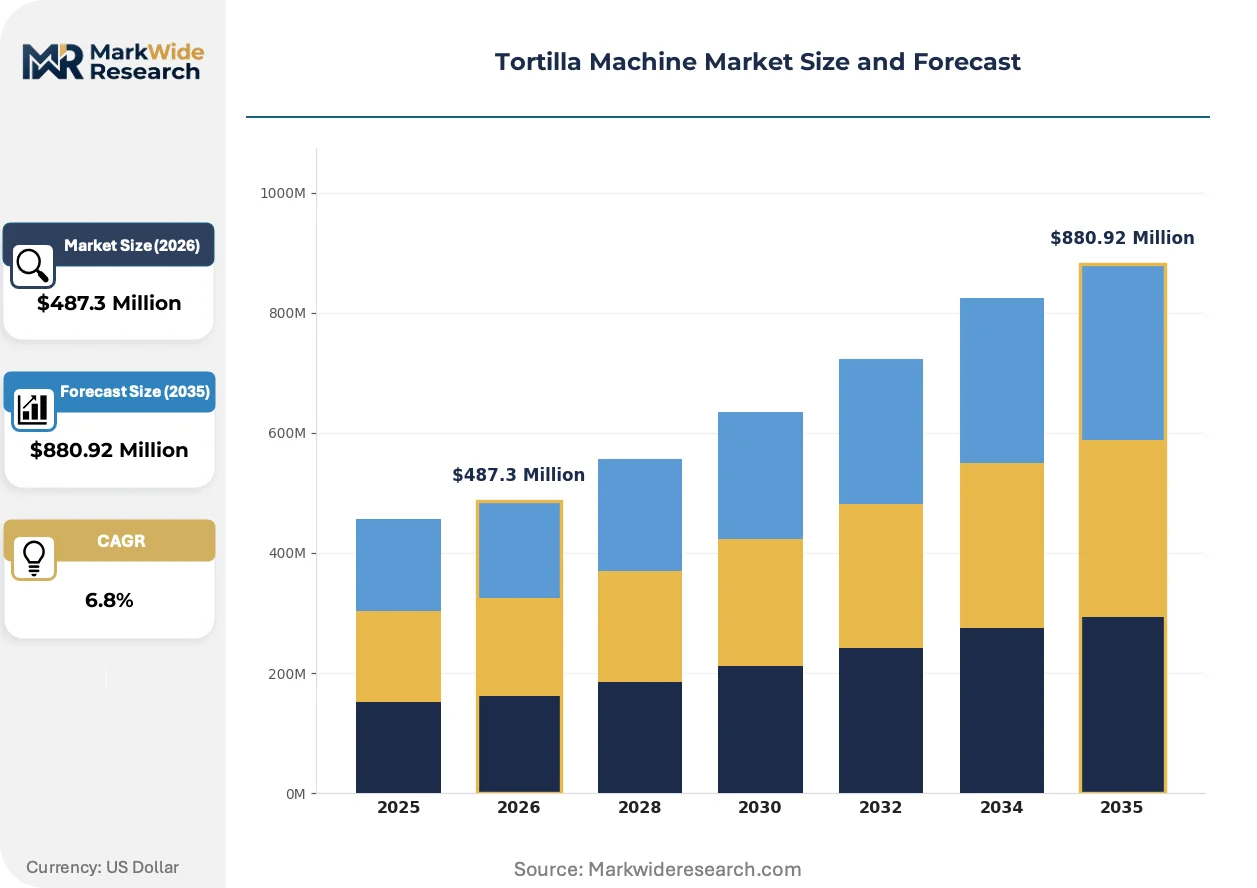
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
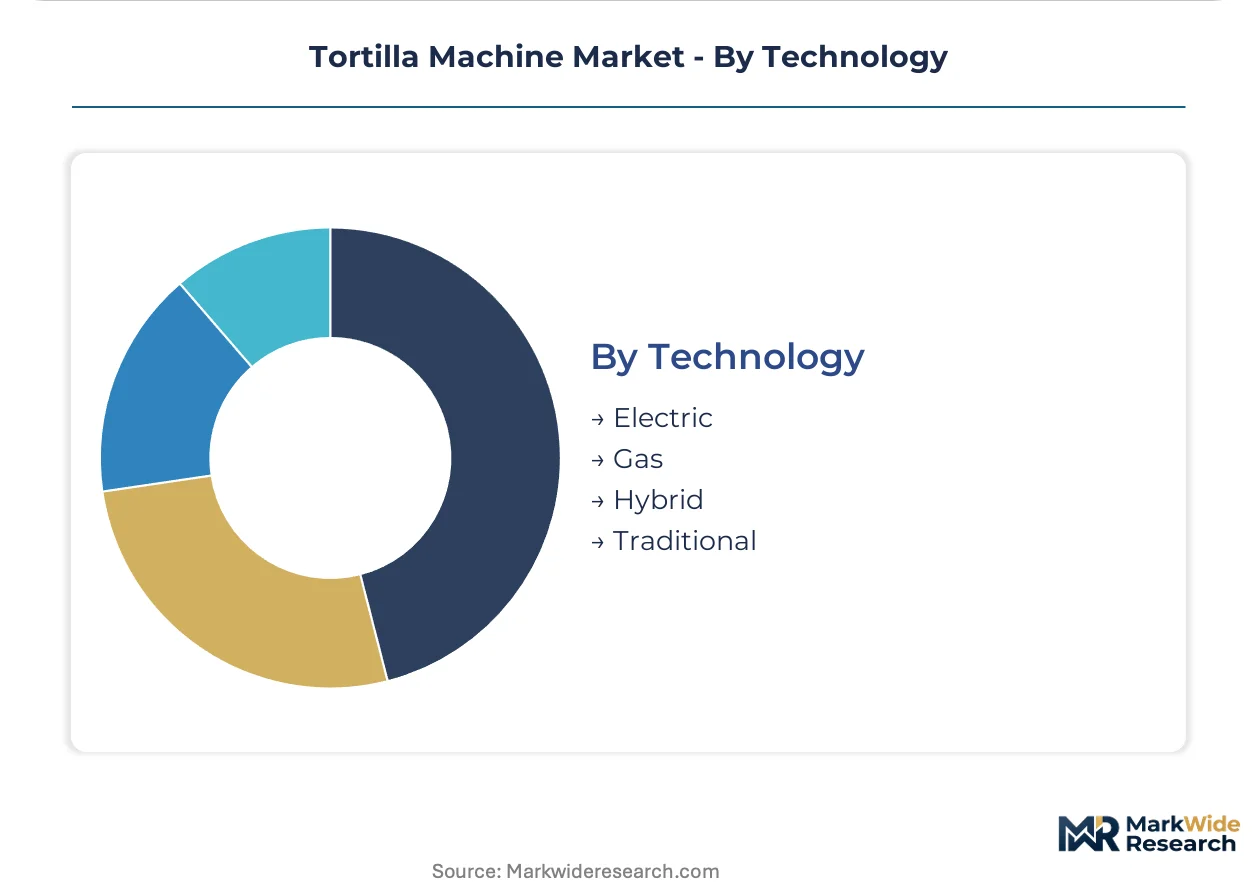
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Industrial End User: Restaurants, Food Trucks, Catering Services, Bakeries Capacity: Small Scale, Medium Scale, Large Scale, Custom Technology: Electric, Gas, Hybrid, Traditional |
| Companies Covered | CHENPIN FOOD MACHINE CO., LTD, Revent, Alfa Laval, Heat and Control, Reading Bakery Systems, Gruma Machinery, Tortilla Masters, Axis Machine Company, Perfectech Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tortilla Machine Market Evolving Landscape
Digitalization of thermal management and predictive analytics is compressing equipment lifecycle economics, while regulatory pressure on food-contact materials accelerates materials science investment across the supplier base.
Electromagnetic induction heating modules are overtaking conventional gas-fired tunnel ovens in new installations. Large-scale processors in California's Central Valley adopt these systems to satisfy regional air quality management district emissions caps. The technology is overtaking radiant heat methods by eliminating thermal lag, enabling 40-second product changeovers that gas systems cannot match.
The US FDA's updated Food Code provisions on allergen cross-contact now mandate dedicated production lines for gluten-free corn tortillas. Commercial bakeries serving institutional buyers must segregate wheat and corn processing equipment or face liability exposure. Mexico's national standards body has harmonized mechanical safety requirements with ANSI B155.1, easing cross-border certification for OEMs serving both markets.
Subscription-based uptime guarantees are displacing traditional break-fix service contracts among multi-plant operators. Heat and Control anchors North American market presence through field service networks that bundle labor, parts, and remote monitoring into per-unit-hour fees. This model concentrates most visibly in Texas and Illinois, where bakery consolidation has created buyers with sufficient fleet scale to justify outcome-based arrangements.
Tortilla Machine Market Segmentation
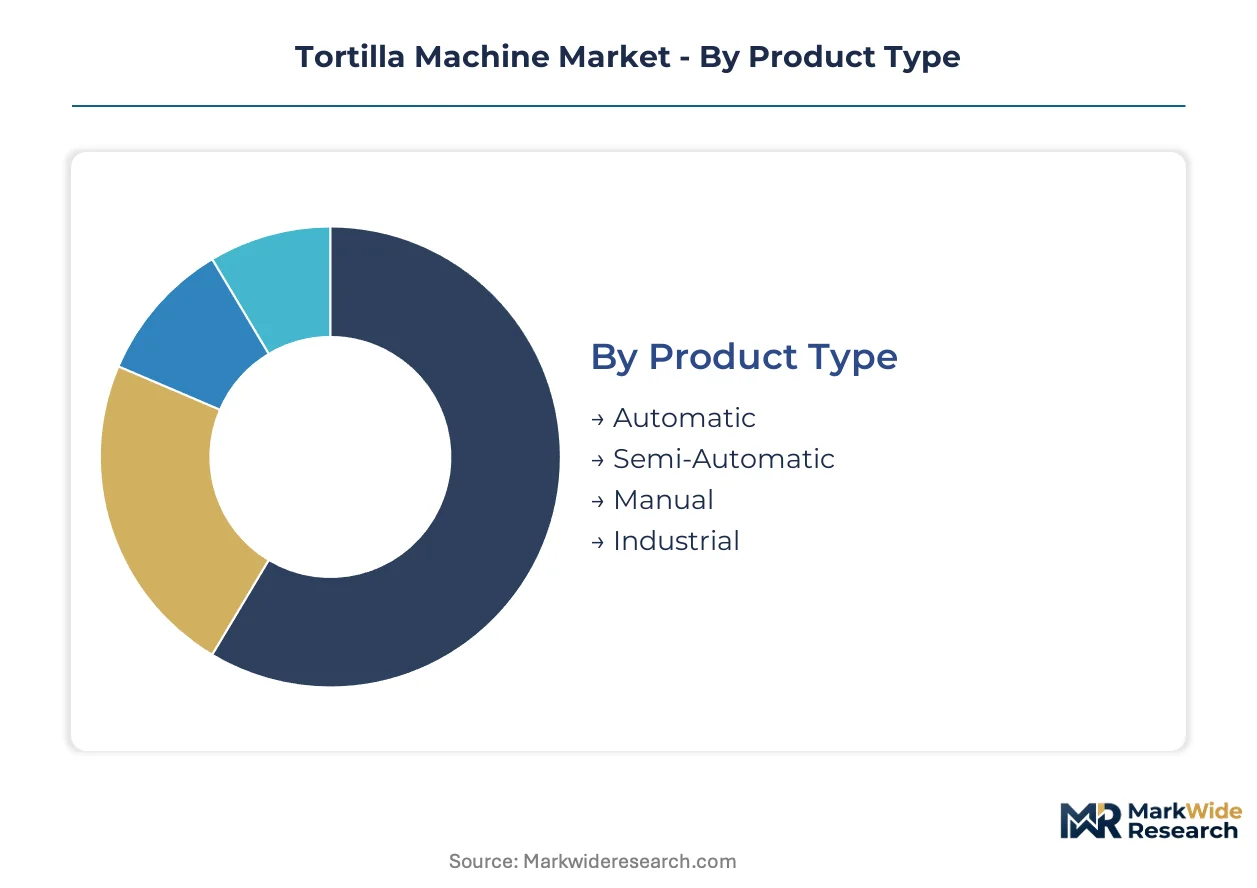
Tortilla machine segmentation reveals how capital deployment varies sharply by operational scale and regulatory exposure. Equipment buyers sort across automation levels, energy systems, and throughput tiers that directly determine compliance costs and labor economics.
Product Type:
Volume lines dominate capital flows while premium configurations capture margin in specialized applications.
- Automatic:Continuous-process systems integrate masa mixing, pressing, baking, and cooling at throughputs exceeding 10,000 units per hour. Large processors in California's Central Valley deploy these lines to satisfy regional air quality emissions caps while minimizing labor headcount.
- Semi-Automatic:Modular configurations balance throughput flexibility with operator oversight at mid-tier bakeries. Operators in Texas and Arizona favor these systems for product changeover agility when serving mixed institutional and retail accounts.
- Manual:Hand-operated presses serve artisanal producers and training facilities with minimal capital requirements.
- Industrial:Integrated production lines combine multiple process stages for dedicated high-volume facilities.
Today's leader: Automatic. Tomorrow's challenger: Semi-Automatic.
End User:
Customer type determines equipment specification priority, from mobility constraints to sanitary certification depth.
- Restaurants:Front-of-house visibility demands compact footprints with rapid heat-up cycles. Chains in the US Southwest specify clean-in-place designs to satisfy FDA food-contact surface mandates without kitchen disassembly.
- Bakeries:Dedicated production facilities prioritize throughput consistency and allergen segregation capabilities. Commercial operators serving institutional buyers must segregate wheat and corn processing equipment per updated Food Code provisions.
- Food Trucks:Mobile operations require propane compatibility and vibration-resistant construction.
- Catering Services:Event-based demand patterns favor rapid deployment and minimal setup complexity.
Restaurants anchor current procurement volumes. Bakeries are climbing the fastest as consolidation creates multi-unit fleet buyers.
Capacity:
Scale tier selection locks buyers into specific supply chain and service network dependencies.
- Large Scale:Systems exceeding 50,000 units per hour require dedicated utility infrastructure and preventive maintenance contracts. Processors in Mexico's industrial baking corridors concentrate procurement here to serve export markets.
- Medium Scale:Flexible throughput ranges from 5,000 to 20,000 units per hour suit regional distributors balancing multiple SKUs.
- Small Scale:Entry-level equipment serves startup operations and geographic market testing.
- Custom:Engineered-to-order configurations address unique product specifications or facility constraints.
Large Scale commands the installed base. Custom is expanding most quickly as product differentiation intensifies.
Technology:
Energy system choice increasingly reflects regulatory pressure and tariff volatility hedging rather than pure operating economics.
- Hybrid:Dual-fuel gas-electric configurations enable operators to switch energy sources during grid instability or price spikes. Texas and California food manufacturers adopt these systems to hedge volatile utility tariffs while maintaining production continuity.
- Electric:Resistance and induction heating modules satisfy urban emissions codes and qualify for accelerated depreciation under efficiency credit programs. New installations in California's Central Valley favor electromagnetic induction for 40-second product changeovers.
- Gas:Conventional tunnel ovens retain cost advantages in regions with stable natural gas pricing.
- Traditional:Comal-based methods persist in heritage product positioning and demonstration applications.
Hybrid leads new capital commitments. Electric shows the steepest expansion trajectory as emissions mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's industrial baking corridors concentrate masa-handling expertise, while the United States Southwest hosts the densest deployment of automated tortilla lines outside Mexican territory.
United States
California's Central Valley processors deploy electromagnetic induction systems to satisfy regional air quality emissions caps. The US FDA's updated Food Code provisions on allergen cross-contact mandate dedicated production lines for gluten-free corn tortillas. Texas industrial parks attract equipment suppliers establishing regional service hubs to hedge volatile utility tariffs through hybrid gas-electric configurations.
Mexico
Export-oriented processors in Nuevo León and Jalisco drive demand for large-scale systems exceeding 50,000 units per hour. The national standards body harmonized mechanical safety requirements with ANSI B155.1, easing cross-border certification for OEMs. Mexico City's metro area concentrates skilled mechatronics technicians for automated masa handling systems, limiting rapid scaling elsewhere.
Canada
Ethnic food manufacturing clusters in Ontario and British Columbia sustain mid-tier bakery equipment procurement. Health Canada's food-contact material regulations align with FDA stainless steel specifications, reducing compliance friction for US-sourced machinery. Toronto-area distributors balance multiple SKUs through flexible 5,000 to 20,000 unit-per-hour configurations.
Italy
Precision heat exchanger manufacturing clusters in northern Italy create lead time vulnerability for North American OEMs. REACH compliance for food-contact materials shapes stainless steel sourcing decisions across European supply chains. Milan-based thermal engineering specialists supply energy recovery components to high-volume tortilla lines in multiple continents.
Tortilla Machine Market Competitive Landscape
Top-tier vendors anchor the premium equipment segment, while mid-tier fabricators compete on regional service density and retrofit flexibility. The vendor base stratifies across three tiers: integrated masa-to-package system providers, specialized thermal engineering houses, and regional fabrication shops serving single-country markets. Two strategic archetypes dominate: vertically integrated food conglomerates leveraging captive machinery expertise, and independent equipment specialists competing on thermal efficiency innovation. Competitive moves concentrate on predictive maintenance software bundling and field service network expansion.
Within the integrated-system tier, Gruma Machinery occupies a position exemplifying backward integration into equipment manufacturing from core food production. Heat and Control represents the independent specialist archetype, anchoring North American presence through extensive service infrastructure. Alfa Laval sits within the thermal engineering specialist category, supplying precision heat exchange components to multiple OEMs rather than complete systems. These three patterns illustrate how competitive positioning diverges between captive supply strategies and component-level specialization.
| Leading Market Players |
|---|
| CHENPIN FOOD MACHINE CO., LTD |
| Revent |
| Alfa Laval |
| Heat and Control |
| Reading Bakery Systems |
| Gruma Machinery |
| Tortilla Masters |
| Axis Machine Company |
| Perfectech Machinery |
| Others |
Value Network & Pricing Analysis
Electromagnetic induction heating adoption across California's Central Valley simultaneously compresses energy operating costs and concentrates procurement leverage among thermal engineering specialists capable of precision heat exchanger integration. This technology transition reshapes how equipment fabricators negotiate stainless steel input contracts and how buyers evaluate total cost-of-ownership across hybrid versus electric configurations.
Pricing Analysis
Capacity additions in Mexico's industrial baking corridors are reshaping price floors for mid-tier automatic systems as domestic fabricators expand throughput. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified clean-in-place configurations from basic cast-iron retrofits. Cost compression in standard-tier equipment is intensifying because Grade 304 stainless steel price volatility squeezes fixed-price municipal contract margins. Small-scale artisanal buyers exhibit highest price sensitivity, while large-scale processors prioritize energy efficiency payback over capital expenditure.
Supply Chain Analysis
Single-source vulnerability sits with precision heat exchanger manufacturing clusters in northern Italy that feed North American OEM assembly lines. Component sourcing draws from Mexico for mechatronics expertise, the United States for control systems integration, and Italy for thermal engineering subassemblies. Raw material dependencies center on Grade 304 and 316 stainless steel, precision-machined aluminum heat spreaders, and Allen-Bradley-compatible PLC modules. Tariff exposure on European-sourced thermal components creates lead time vulnerability during trade policy shifts. Distribution runs through regional service hubs in Texas and Arizona that bundle installation, training, and predictive maintenance subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where consolidation favors vendors with integrated masa-to-software capabilities as commercial bakeries demand allergen-segregated production lines and real-time energy optimization.
For Market Incumbents: Lock in field service network density across the US Southwest food manufacturing belt before regional tax incentive windows close. Invest in AWS D18.1 sanitary welding certification capacity to compress production schedules threatened by eight-to-twelve-week qualification timelines. Defend against emerging thermal engineering specialists by bundling predictive maintenance software with hardware deployments to capture recurring revenue streams. For New Entrants and Emerging Players: The premium-to-economy price-point gap in mid-scale semi-automatic systems offers white-space entry for modular configurations targeting Texas and Arizona bakeries balancing throughput flexibility with operator oversight. Target mobile food truck operators with propane-compatible, vibration-resistant constructions currently underserved by tunnel-oven specialists. Establish beachhead through aftermarket retrofit services for 1990s-era PLC architectures rather than competing head-to-head on new line installations. For Investors and Strategic Acquirers: Roll-up economics work for regional fabrication shops with established municipal contracts because FDA clean-in-place mandates accelerate replacement cycles for non-compliant legacy equipment. Long-term viability rests on exposure to efficiency credit programs and hybrid system adoption curves. Monitor induction baking convergence with IoT temperature controls as the inflection indicator for technology obsolescence risk in conventional gas-fired tunnel ovens.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Software Bundling | Gruma Machinery leverages vertically integrated masa expertise to capture recurring revenue from commercial bakery fleets. |
| Regional Service Hub Expansion | Arizona and New Mexico industrial parks offer tax incentives for suppliers establishing proximity to Texas utility hedging demand. |
| Sanitary Welding Certification Investment | AWS D18.1 qualification for food-grade stainless steel joints differentiates vendors competing on production schedule reliability. |
| Hybrid Gas-Electric System Development | Dual-fuel configurations address California air quality emissions caps while enabling Texas operators to switch during grid instability. |
| Backward Integration into Heat Exchanger Manufacturing | In-house thermal component production mitigates lead time vulnerability from northern Italian supply concentration. |
Research Methodology
Bottom-up bakery equipment procurement modeling reconciled against top-down OEM shipment tracking forms the analytical core of this study. Primary interviews with maintenance directors at commercial tortilla processors, plant engineers at industrial baking facilities, OEM procurement teams, and aftermarket service heads were cross-validated against secondary sources including FDA food-contact material regulations, SEC equipment manufacturer filings, US customs import records for thermal components, and California Air Resources Board emissions compliance databases. Triangulation between demand-side capital expenditure patterns and supply-side production capacity announcements ensures statistical integrity.
Historical trendline analysis of automatic versus semi-automatic system deployment rates established baseline growth trajectories across the projection horizon. The quantitative framework segments volume and value outputs by automation level, energy system technology, throughput capacity tier, and end-user archetype. CAGRs were derived from regression analysis of replacement cycle timing, regulatory retrofit mandates, and efficiency credit program eligibility. Industry-specific forecast inputs include stainless steel price volatility indices and regional air quality management district emissions cap trajectories.
Caveats apply where FDA food-contact surface regulation updates, Grade 304 stainless steel commodity price spikes, or northern Italian heat exchanger supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions about utility tariff volatility hedging behavior and commercial bakery consolidation rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Food Ultrasound Market
Food Processing Equipment
Spray Drying Market
Food Processing Equipment
Commercial Oven Market
Food Processing Equipment
Magnetic Grill Market
Food Processing Equipment
Bread Maker Market
Food Processing Equipment
Fish Processing Equipment Market
Food Processing Equipment
Pizza Preparation Refrigerator Market
Food Processing Equipment
High Speed Oven Market
Food Processing Equipment
Craft Brewery Equipment Market
Food Processing Equipment
Global Commercial Refrigeration Market
Food Processing Equipment
Portable Clean-In-Place Market
Food Processing Equipment
Craft Beer Saccharification Equipment Market
Food Processing Equipment
Loss-In-Weight Feeder Market
Food Processing Equipment
Commercial Food Refrigeration Equipment Market
Food Processing Equipment
Hydrostatic Steam Blancher Market
Food Processing Equipment
Food Processing Machinery Market