
 Food Processor Market | 2026-2036
Food Processor Market Size, Share, and Industry Trends Forecast 2026-2036
Food Processor Market Analysis
Asian contract manufacturers is shifting capacity toward brushless motor assemblies and stainless-steel bowl fabrication for Western brands. Bühler leverages its Swiss engineering heritage to dominate industrial-scale milling and mixing integrations. GEA Group anchors European food service channels with hygienic-design processors certified for dairy and meat applications. Ninja competes in the North American premium household tier through direct-to-consumer marketing and blade-system specialization.
A food processor is a motorized kitchen appliance employing interchangeable blades, discs, and bowls to mechanically chop, slice, puree, or emulsify ingredients at rotational speeds typically ranging from 1,500 to 15,000 RPM. Multi-functional food processors command the widest household penetration by consolidating blender, mixer, and chopper functions into single footprint units. Smart processors represent the fastest-expanding technology segment as WiFi-enabled recipe guidance and automated speed adjustment migrate from luxury to mid-tier price bands. Heavy-duty food processors sustain margin pools in industrial settings where NSF-certified construction and continuous-duty motors justify premium positioning over standard residential models.
FDA food contact substance regulations and EU MDR-adjacent machinery safety directives shape electrical and materials compliance for exporters targeting both jurisdictions. Ecodesign requirements under the EU Green Deal are pressuring motor efficiency upgrades and recyclable plastic substitution in European-bound product lines. Stakeholders must monitor evolving right-to-repair legislation across multiple geographies and decide whether modular component architectures warrant upfront engineering investment against downstream service revenue capture.
Market Dynamics
Automated food prep equipment procurement in commercial kitchens is compressing replacement cycles as FDA and EFSA safety protocols harden certification requirements for electrical contact surfaces and motor assemblies.
Growth Catalysts
- EFSA Machinery Safety Directives:European food service operators face mandatory upgrades to hygienic-design processors, accelerating equipment turnover in Germany and France.
- Industrial Bakery Automation:High-throughput mixing and milling integrations in ready-meal production lines drive demand for continuous-duty motor systems.
- Brushless Motor Migration:Asian contract manufacturers redirect capacity toward precision motor assemblies, lowering input costs for Western brand procurement.
Market Restraints
- Copper and Rare Earth Volatility:Permanent magnet motor supply chains concentrate in Chinese processing facilities, exposing cost structures to export quota fluctuations.
- NSF Certification Timelines:Third-party laboratory testing for commercial kitchen equipment extends lead times by 8-14 weeks for North American market entry.
- Blender-Chopper Convergence:Multi-functional countertop appliances substitute discrete food processor purchases in household segments below $150 price points.
Strategic Opportunities
- EU Green Deal Ecodesign:Motor efficiency mandates and recyclable plastic substitution requirements create first-mover advantage for redesign-ready manufacturers.
- Smart Kitchen Convergence:WiFi-enabled recipe guidance and automated speed adjustment migrate from luxury to mid-tier price bands, opening volume expansion.
- Cloud Kitchen Infrastructure:Ghost kitchen and delivery-only restaurant formats in urban India and Southeast Asia demand compact, high-output prep equipment.
Industry Challenges
- Embedded Software Talent Scarcity:Smart processor development requires firmware engineers with food safety domain knowledge, a skill combination concentrated in Swiss and German industrial clusters.
- Right-to-Repair Compliance:Modular component architectures demand upfront engineering investment against uncertain service revenue capture across multiple geographies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Processor Market |
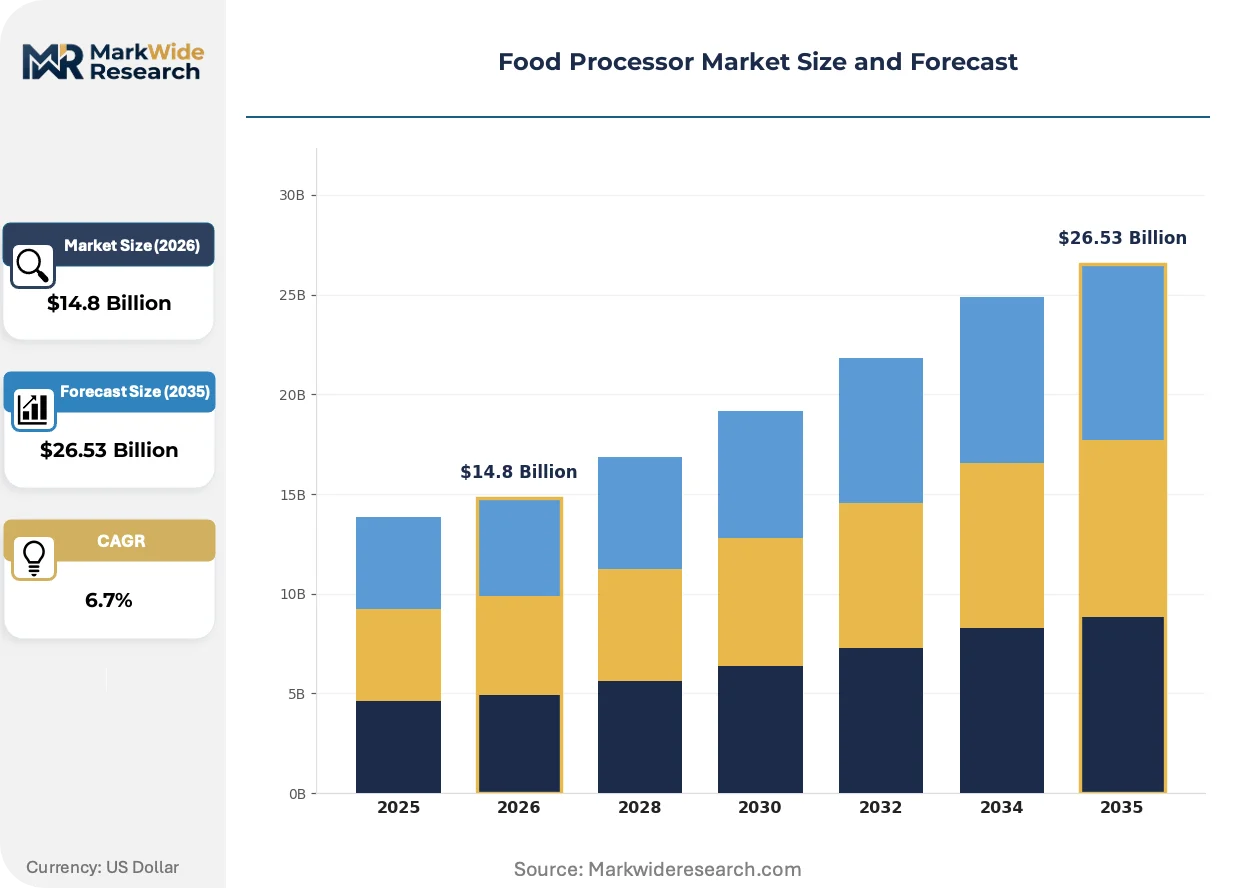
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Food Processors, Standard Food Processors, Heavy-Duty Food Processors, Multi-Functional Food Processors Application: Household, Commercial, Industrial, Food Service Technology: Smart Processors, Multi-Speed Processors, Multi-Blade Processors, Variable Speed Processors Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Magimix, Ninja, Breville, GEA Group, Bühler, Cuisinart, Braun, Tetra Laval, KitchenAid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Processor Market Emerging Trajectories
Electrification of food prep workflows and connected appliance architectures are redrawing competitive boundaries between industrial equipment suppliers and consumer electronics platforms.
Brushless DC motor technology is absorbing mechanical transmission complexity in next-generation food processors, replacing brushed universal motors with electronically commutated drives that deliver higher torque density at reduced thermal load. Industrial bakery operators in Germany and Japan are specifying these systems for continuous-duty mixing applications exceeding 12-hour run cycles. The technology is absorbing margin pressure from copper price volatility by reducing winding mass 30-40% versus conventional designs.
EU Green Deal ecodesign requirements are forcing motor efficiency upgrades and recyclable plastic substitution in European-bound product lines, with CE marking now contingent on documented end-of-life disassembly protocols. Manufacturers serving EFSA-regulated channels must redesign housing assemblies to eliminate polypropylene-ABS bonding that complicates mechanical recycling. Dairy and meat processing equipment faces the tightest compliance windows, with certified suppliers capturing procurement preference from sustainability-mandated food service chains.
Direct-to-consumer channel expansion is fragmenting traditional retail concentration for premium household tiers, with specialized blade-system marketing displacing big-box merchandising as the primary customer acquisition mode. Ninja and similar brands bypass distributor markups through owned e-commerce platforms and social media conversion funnels. North American urban markets exhibit the steepest channel shift, though European adoption trails by 18-24 months due to stronger kitchen specialty retailer relationships.
Food Processor Market Segmentation
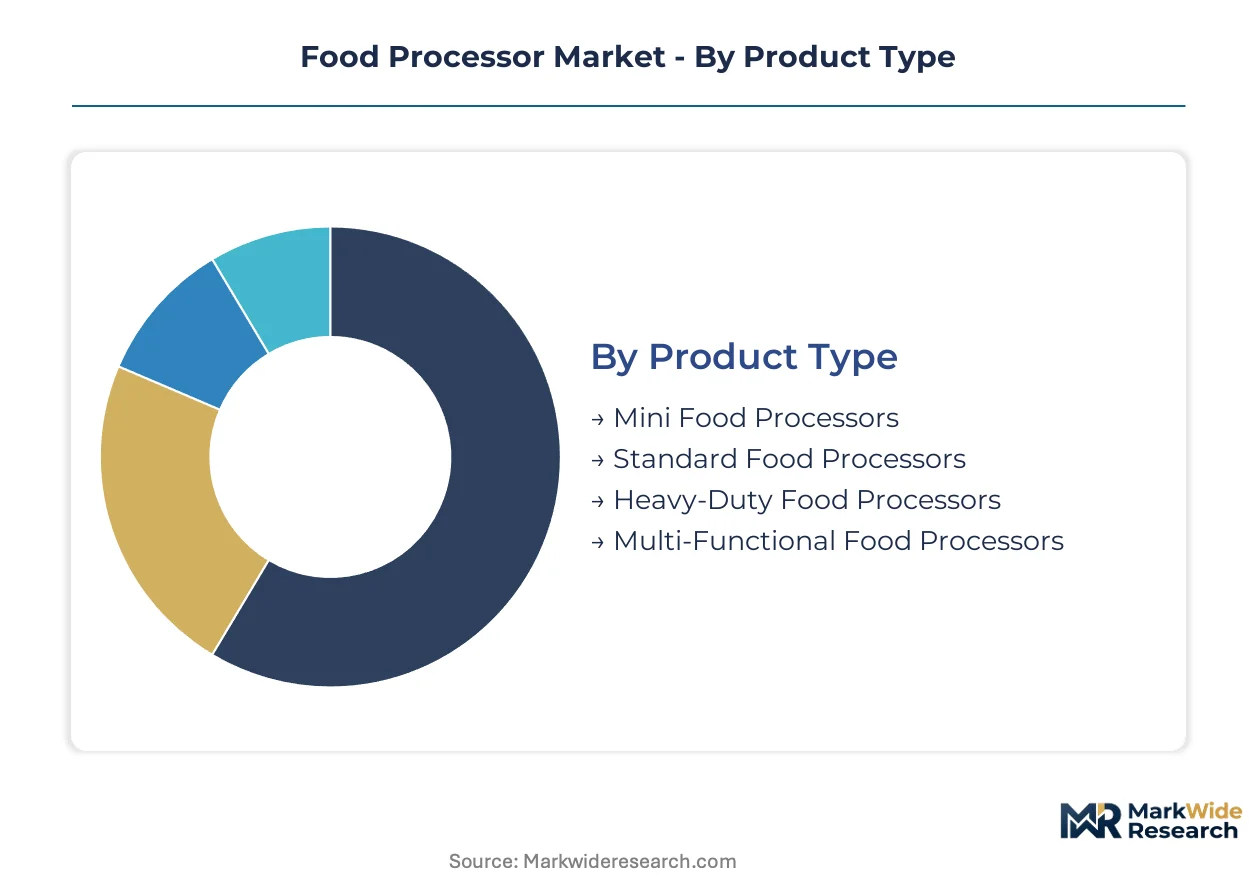
Food processor segmentation reveals divergent engineering priorities across power ratings, duty cycles, and connectivity architectures. Manufacturers must align motor specifications, blade geometries, and control systems with distinct end-use environments rather than pursuing universal platform strategies.
Product Type:
Supply concentration in brushless motor assemblies and stainless-steel fabrication capacity tilts procurement leverage toward heavy-duty and multi-functional platforms.
- Heavy-Duty Food Processors:Continuous-duty motor systems rated for 12-hour run cycles anchor industrial bakery and ready-meal production lines in Germany and Japan. NSF-certified construction and thermal management justify premium positioning over residential alternatives.
- Multi-Functional Food Processors:These units consolidate blender, mixer, and chopper functions into single-footprint designs. North American households above $150 price points drive volume, though blender-chopper convergence below this threshold erodes discrete processor demand.
- Mini Food Processors:Compact motor assemblies target urban apartments and secondary prep stations with sub-500-watt power draws.
- Standard Food Processors:Mid-tier motor platforms serve replacement cycles in established Western markets without smart connectivity premiums.
Today's leader: Heavy-Duty Food Processors. Tomorrow's challenger: Multi-Functional Food Processors.
Application:
End-use environments impose distinct certification burdens and replacement cadences that fragment go-to-market approaches.
- Industrial:High-throughput milling and mixing integrations require EFSA-compliant hygienic design and documented end-of-life disassembly protocols under EU Green Deal ecodesign.
- Commercial:Ghost kitchen and delivery-only restaurant formats in urban India and Southeast Asia demand compact, high-output prep equipment with rapid cycle times.
- Household:Direct-to-consumer channel expansion fragments traditional retail concentration for premium tiers in North American urban markets.
- Food Service:Mandatory FDA and EFSA safety protocol upgrades accelerate equipment turnover in dairy and meat processing applications.
Industrial applications command the steepest margin pools. Food Service represents the fastest volume expansion trajectory.
Technology:
Embedded software development costs and firmware talent scarcity concentrate smart processor innovation in Swiss and German industrial clusters.
- Smart Processors:WiFi-enabled recipe guidance and automated speed adjustment migrate from luxury to mid-tier price bands. Firmware engineers with food safety domain knowledge remain scarce outside Central European technical centers.
- Variable Speed Processors:Electronically commutated drives deliver torque density across 1,500-15,000 RPM ranges while reducing thermal load versus brushed universal motors.
- Multi-Speed Processors:Mechanical transmission systems persist in cost-sensitive segments where brushless DC migration remains incomplete.
- Multi-Blade Processors:Specialized blade-system marketing displaces big-box merchandising as primary customer acquisition mode for premium household tiers.
Smart Processors absorb the fastest R&D investment. Variable Speed Processors deliver the most immediate cost-structure relief.
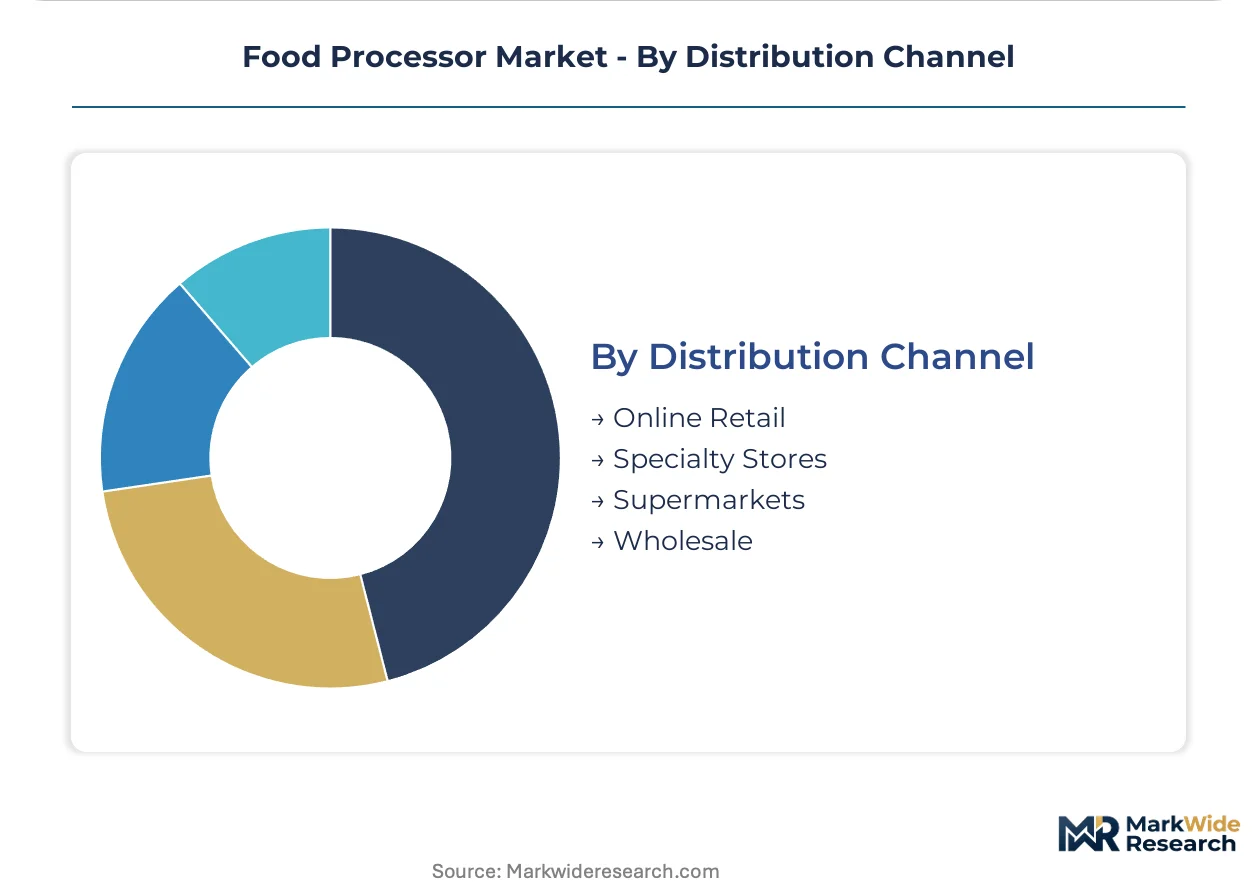
Distribution Channel:
Channel economics diverge sharply between owned e-commerce conversion funnels and traditional wholesale markups.
- Online Retail:Owned platforms bypass distributor markups and enable specialized blade-system marketing with social media conversion optimization.
- Specialty Stores:European kitchen specialty retailer relationships retain stronger consumer trust than in North America, delaying direct-to-consumer adoption by 18-24 months.
- Supermarkets:Mass merchandising concentrates below-$150 household segments where multi-functional convergence pressures discrete processor placement.
- Wholesale:Commercial and industrial procurement runs through food service equipment distributors with NSF certification documentation and installation service bundling.
Online Retail captures the steepest growth slope. Wholesale retains the deepest commercial lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing procurement geography as FDA certification timelines push North American brands toward Asian contract manufacturers, while EU Green Deal ecodesign rules trap value in European industrial clusters.
Germany
Industrial bakery automation and ready-meal production lines drive continuous-duty processor demand. EFSA machinery safety directives mandate hygienic-design upgrades, compressing replacement cycles. Stuttgart and Munich anchor precision motor engineering clusters where brushless DC development concentrates.
United States
Commercial kitchen procurement and ghost kitchen expansion accelerate automated prep equipment adoption. FDA food contact substance regulations extend third-party laboratory testing lead times. Chicago and Dallas-Fort Worth host food service equipment distribution hubs bundling NSF certification documentation.
Japan
High-throughput milling integrations for industrial bakery operators specify 12-hour run cycle motors. METI efficiency standards pressure motor winding redesigns. Osaka-Kobe industrial corridors concentrate stainless-steel fabrication capacity for Western brand procurement.
China
Contract manufacturers redirect capacity toward brushless motor assemblies and precision bowl fabrication. GB standards and dual carbon goals shape export-bound product specifications. Yangtze River Delta production zones capture Western OEM sourcing shifts from cost-of-compliance gaps.
India
Cloud kitchen infrastructure in urban centers demands compact, high-output prep equipment. FSSAI safety protocols and PLI scheme incentives attract component manufacturing investment. Mumbai and Bangalore emerge as assembly points for Southeast Asian ghost kitchen supply chains.
Food Processor Market Vendor Landscape
Swiss and German producers anchor the industrial tier; Chinese and Southeast Asian fabricators hold contract manufacturing. The vendor base stratifies across three layers: integrated industrial equipment suppliers, premium household brands with direct-to-consumer channels, and component-specialist contract manufacturers. Two competitive moves dominate: capacity redirection toward brushless motor supply chains, and owned e-commerce platform development to bypass distributor markups.
Within the industrial integration tier, Bühler and GEA Group represent archetypal European engineering-heavy suppliers. Ninja occupies a position exemplifying direct-to-consumer household premium positioning. These three anchors illustrate the geographic and channel bifurcation shaping procurement leverage.
| Leading Market Players |
|---|
| Magimix |
| Ninja |
| Breville |
| GEA Group |
| Bühler |
| Cuisinart |
| Braun |
| Tetra Laval |
| KitchenAid |
| Others |
Supply Flow & Price Mechanics
Industrial bakery operators in Germany and Japan anchor procurement volumes for continuous-duty motor systems, locking in contract-based long-term offtake pricing with tiered performance guarantees rather than spot-market transactions. This buyer concentration compresses margin negotiation windows for component suppliers while elevating certification-grade premiums over standard residential alternatives.
Pricing Analysis
Distributor markups in North American food service channels absorb 18-25 points before end-user pricing, while direct-to-consumer platforms bypass these layers entirely. Three-tier pricing structure across premium, standard, and economy levels segments by motor duty cycle and NSF certification status, with thermal management specifications commanding the widest spreads. Cost compression in brushless motor tiers is intensifying because Asian contract manufacturers redirect capacity toward precision assemblies, eroding legacy supplier margin pools. Household segments below $150 price points exhibit acute price sensitivity, whereas industrial buyers prioritize 12-hour run cycle reliability over unit cost.
Supply Chain Analysis
Workforce availability for precision motor winding in China's Yangtze River Delta and stainless-steel fabrication in Japan's Osaka-Kobe corridors shapes output scalability for Western OEM procurement. Supply draws from Chinese rare earth processing facilities, Vietnamese component assembly zones, and German engineering clusters for firmware development. Single-source vulnerability concentrates in permanent magnet supply chains tethered to Chinese export quota administration. Distribution runs through food service equipment distributors bundling NSF certification documentation with installation service in North America, while owned e-commerce platforms capture premium household tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EFSA machinery safety directives and FDA food contact substance rules generate replacement-driven demand independent of macroeconomic cycles. Compliance windows for hygienic-design upgrades create predictable procurement spikes across European and North American commercial kitchen networks.
For Market Incumbents: Extend certification coverage into dairy and meat processing applications where EFSA compliance windows are tightest, capturing procurement preference from sustainability-mandated food service chains. Deepen backward integration into brushless motor supply chains to offset copper price volatility exposure. Anchor channel control through distributor relationships bundling NSF documentation and installation service, defending against direct-to-consumer erosion in premium household tiers. For New Entrants and Emerging Players: Capture cloud kitchen infrastructure deployment in urban India and Southeast Asia where compact, high-output prep equipment demand outpaces established supplier presence. Target ghost kitchen operators with rapid-cycle thermal management systems priced below industrial-tier premiums. Pursue go-to-market alignment with regional food delivery platforms operating captive kitchen networks, bypassing traditional food service distribution entirely. For Investors and Strategic Acquirers: Food service equipment conglomerates are the most active acquirers in this space, consolidating hygienic-design specialists to fill EFSA compliance portfolio gaps. Long-term viability hinges on regulatory arbitrage durability as right-to-repair legislation matures across multiple geographies. Monitor embedded software talent scarcity in Swiss and German industrial clusters as inflection indicator for smart processor development cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Brushless Motor Supply Agreement | Secures torque density advantages for continuous-duty bakery applications in Germany and Japan. |
| EFSA Hygienic-Design Certification | Unlocks procurement preference from dairy and meat processing operators facing mandatory upgrades. |
| Direct-to-Consumer Platform Launch | Bypasses distributor markups in North American urban markets where retail concentration fragments. |
| Cloud Kitchen Equipment Partnership | Captures volume expansion in Mumbai and Bangalore ghost kitchen infrastructure buildouts. |
| Modular Component Architecture Investment | Positions for right-to-repair compliance while preserving aftermarket service revenue capture. |
Methodological Framework
Bottom-up commercial kitchen procurement modeling reconciled against top-down contract manufacturing capacity tracking forms the analytical core. Primary interviews with food service equipment procurement directors, industrial bakery maintenance engineers, NSF certification laboratory managers, and Asian contract manufacturing executives combined with secondary validation from FDA food contact substance filings, EFSA machinery safety directive documentation, customs import records for brushless motor assemblies, and food service distributor financial disclosures. Top-down and bottom-up estimates triangulate through cross-referencing OEM sourcing shifts with end-user replacement cycle surveys.
Input-output matrices map motor specification tiers against end-use duty cycle requirements across the projection horizon. Segmentation dimensions modeled include product type, application environment, technology architecture, and distribution channel, with additional granularity on regulatory compliance tier. CAGRs derive from equipment replacement cadence analysis under hardening safety protocols, with motor efficiency upgrade trajectories and recyclable material substitution timelines as food processor-specific forecast inputs.
Underlying measurement precision varies by segment; industrial and food service applications carry tighter precision than household tiers where channel shift velocity complicates demand forecasting. Forecasts reflect assumptions on regulatory implementation timelines and rare earth supply quota administration. Material deviation in EFSA enforcement intensity or Chinese export restriction scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Frozen Food Processing Machinery Market
Food Processing Equipment
Food Irradiation Equipment Market
Food Processing Equipment
Brewing Thermometer Market
Food Processing Equipment
Bakery Processing Equipment Market
Food Processing Equipment
Asia-Pacific Commercial Sous Vide Machine Market
Food Processing Equipment
Cereal Rolling Machine Market
Food Processing Equipment
Aseptic Processing Equipment Market
Food Processing Equipment
Tunnel Oven Market
Food Processing Equipment
Global Meat Mixer Market
Food Processing Equipment
Cook Processor Market
Food Processing Equipment
Global Food Dehydrators Market
Food Processing Equipment
Potato Processing Market
Food Processing Equipment
Flake Ice Machines Market
Food Processing Equipment
Freezers Market
Food Processing Equipment
Portioning Machines Market
Food Processing Equipment
Fluidized Bed Dryer Market