
 Brewing Thermometer Market | 2026-2036
Brewing Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Brewing Thermometer Market Outlook
Multi-source component procurement is recalibrating how brewing thermometer manufacturers balance cost and precision. ThermoWorks Inc. leverages its vertically integrated calibration laboratories to guarantee NIST-traceable accuracy across professional-grade probes. ETI Ltd. anchors its competitive stance through British-made thermistor assemblies that serve European craft brewery specifications. Inkbird Tech. competes aggressively on wireless data-logging connectivity, capturing price-sensitive home brewer segments in North America and Asia.
A brewing thermometer measures wort, mash, and fermentation temperatures with specified accuracy, typically employing stainless-steel probe sheaths, thermistor or thermocouple sensing elements, and digital or analog readout displays to ensure enzymatic conversion efficiency and yeast viability during beer production. Digital thermometers now dominate commercial installations where Bluetooth-enabled data logging supports process repeatability, while infrared thermometers occupy a niche for non-contact surface checks on kettle exteriors and piping. Probe thermometers sustain the deepest penetration across microbreweries and commercial breweries alike, as immersion-style measurements remain indispensable for mash tun and fermenter monitoring.
The U.S. Food and Drug Administration enforces sanitary equipment standards that influence thermometer material specifications and clean-in-place compatibility for breweries selling across state lines. The National Institute of Standards and Technology calibration traceability requirements shape procurement criteria for commercial operations seeking insurance and quality certifications. Stakeholders must monitor how evolving state-level craft beverage regulations and emerging wireless connectivity standards reshape equipment replacement timelines and supplier qualification protocols.
Market Dynamics
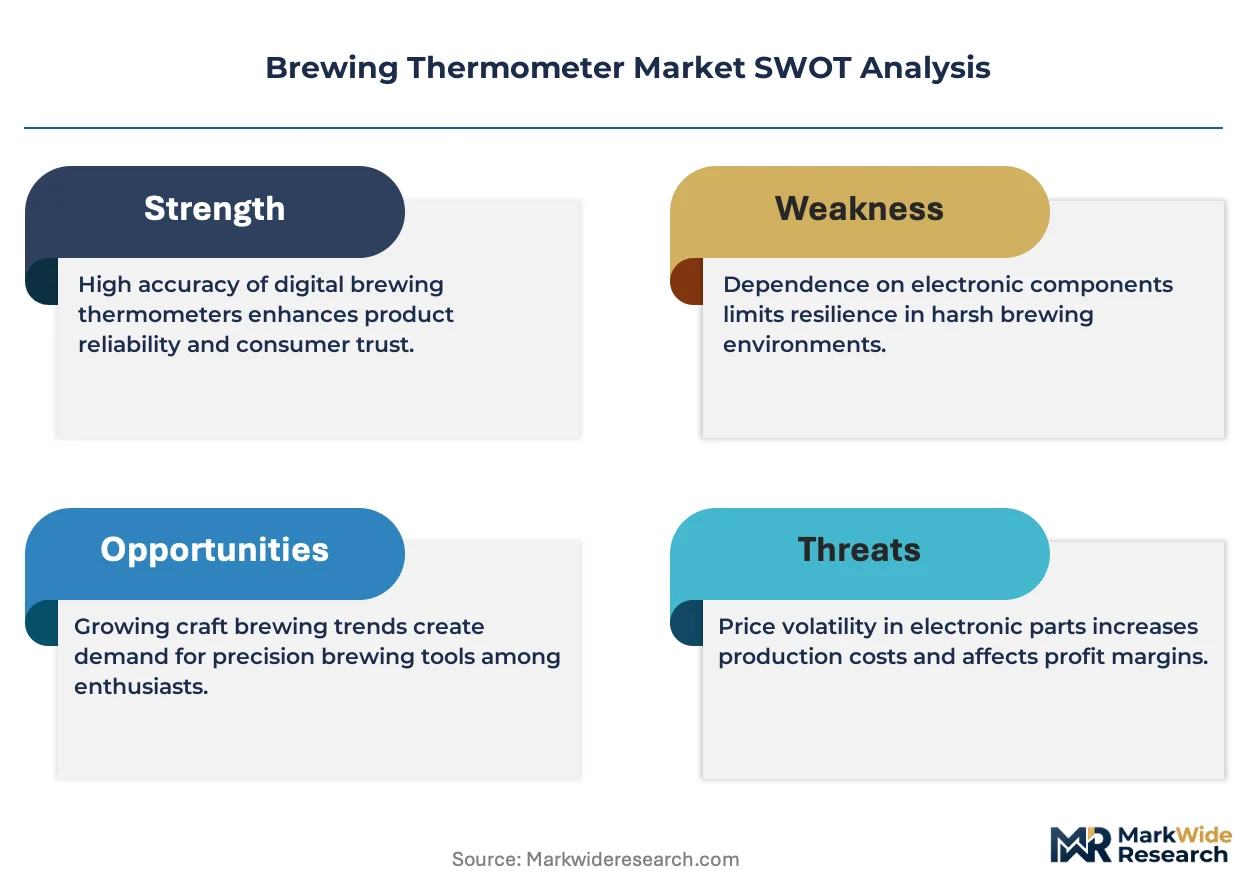
NIST calibration mandates are compressing procurement cycles across commercial brewing operations, forcing equipment upgrades ahead of natural replacement timelines as insurance underwriters and quality auditors tighten traceability requirements.
Growth Catalysts
- Craft Quality Standards:Microbreweries in the Pacific Northwest and Colorado are expanding temperature monitoring protocols as enzymatic conversion precision becomes a competitive differentiator in saturated regional markets.
- FDA Sanitary Equipment Standards:Cross-state distribution requirements for craft beverage producers are mandating stainless-steel probe sheaths and clean-in-place compatibility, accelerating digital instrument adoption.
- Wireless Data-Logging:Bluetooth-enabled process repeatability tools are capturing price-sensitive home brewer segments in North America and Asia, expanding the addressable base beyond commercial installations.
Market Restraints
- Thermistor Component Concentration:British-made thermistor assemblies anchor European supply chains, creating geographic vulnerability for manufacturers dependent on single-source sensing elements.
- Calibration Infrastructure Costs:Vertically integrated calibration laboratories require substantial capital commitment, disadvantaging smaller entrants against established NIST-traceable competitors.
- Infrared Niche Limitation:Non-contact surface measurement technology cannot displace immersion-style probes for mash tun monitoring, capping substitution threat in core brewing applications.
Strategic Opportunities
- Brazilian Modernization Programs:Brewery equipment replacement cycles are accelerating in Brazil's concentrated demand zone, creating white space for certified digital instrument penetration.
- EU Green Deal Alignment:Energy-efficient temperature monitoring systems qualify for sustainability-linked financing instruments, opening procurement budgets previously reserved for capital equipment.
- Home Brewer Channel Expansion:Direct-to-consumer wireless connectivity platforms bypass traditional industrial distribution, capturing margin previously allocated to channel intermediaries.
Industry Challenges
- Metrology Talent Scarcity:NIST-traceable calibration expertise remains concentrated among legacy suppliers, constraining quality assurance scaling for emerging manufacturers.
- Legacy Analog Integration:Fermentation facilities with installed analog gauge infrastructure face data logging incompatibility when upgrading to digital probe systems.
- Multi-Jurisdiction Certification:Breweries selling across state lines must reconcile FDA sanitary standards with emerging state-level craft beverage regulations, extending compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brewing Thermometer Market |
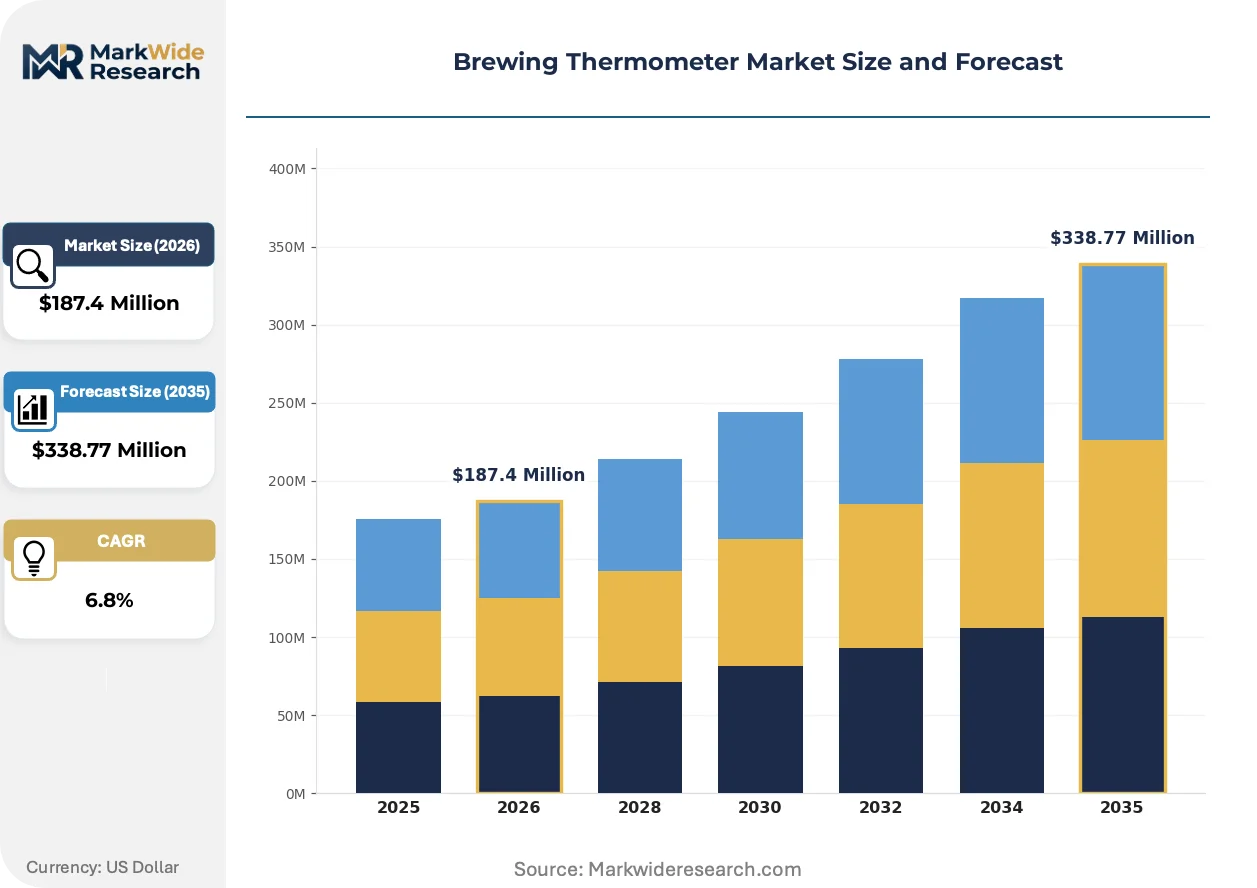
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Thermometers, Analog Thermometers, Infrared Thermometers, Probe Thermometers End User: Home Brewers, Microbreweries, Commercial Breweries, Beverage Manufacturers Technology: Thermocouple, Thermistor, Infrared, Bimetallic Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | ThermoWorks Inc., ETI Ltd., Inkbird Tech., Hanna Instruments, Blichmann Engineering, Reotemp Instruments, Tel-Tru, Northern Brewer, Taylor Precision Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brewing Thermometer Market Strategic Shifts
Sensor miniaturization and connectivity protocols are redefining how brewing operations capture and act on thermal data, shifting competitive advantage from hardware precision toward real-time analytics integration.
Silicon-based thermistor arrays with embedded Bluetooth Low Energy transmitters are absorbing market share from traditional thermocouple installations. Mid-sized craft breweries in Germany and Australia are adopting these systems at twice the pace of smaller microbreweries. The technology is absorbing calibration labor costs by enabling automated drift detection and remote recertification scheduling.
REACH substance restrictions on mercury-containing thermometers are accelerating phase-out timelines for analog glass instruments across European brewing operations. Industrial consequence includes mandatory replacement of legacy equipment ahead of functional end-of-life. German commercial breweries are responding fastest, with modernization programs now bundling digital probe procurement with fermentation tank upgrades.
Certification-driven procurement is compressing vendor qualification cycles as quality auditors demand documented NIST traceability chains. Industrial distributors are losing ground to manufacturer-direct channels that bundle calibration certificates with initial purchase. This pattern is most visible across Australian brewery cooperatives, where group purchasing agreements now specify certified-digital-only supplier pools.
Brewing Thermometer Market Segmentation
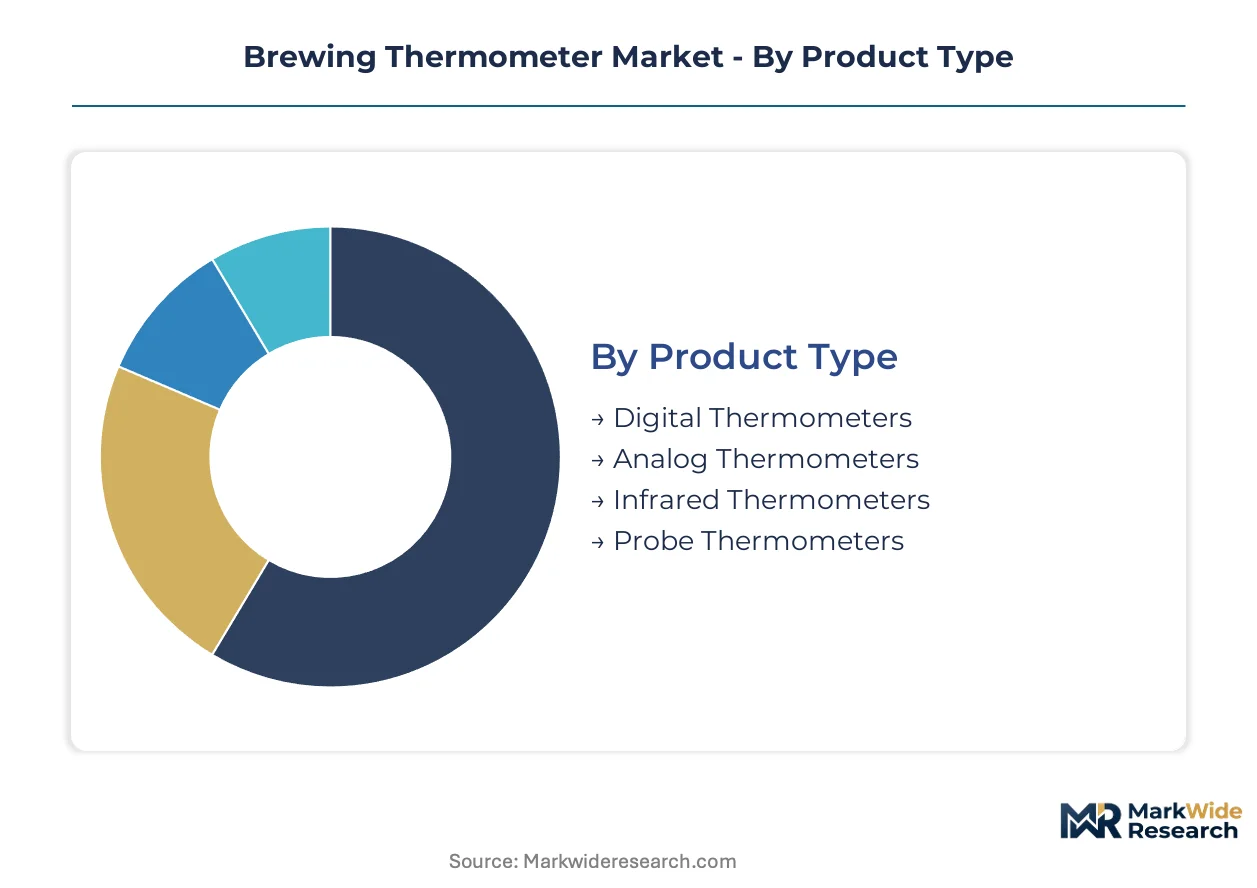
Temperature measurement requirements diverge sharply across brewing scales, from hobbyist precision needs to industrial NIST traceability mandates. Equipment selection hinges on calibration infrastructure, connectivity demands, and regulatory exposure rather than price alone.
Product Type:
Commercial buyers prioritize certification grade and data-logging capability over upfront cost, while home segments trade absolute precision for wireless convenience.
- Digital Thermometers:Stainless-steel probe sheaths paired with thermistor or thermocouple sensing elements deliver NIST-traceable accuracy for mash tun and fermenter monitoring. Demand concentrates among U.S. microbreweries facing FDA cross-state distribution requirements and insurance auditor traceability mandates.
- Probe Thermometers:Immersion-style instruments with fixed or detachable probes remain indispensable for enzymatic conversion efficiency in commercial settings. German and Australian brewery modernization programs are accelerating replacement cycles as REACH mercury restrictions force analog phase-outs.
- Analog Thermometers:Glass-stem mercury or alcohol-based instruments face regulatory extinction across European operations.
- Infrared Thermometers:Non-contact surface measurement occupies niche applications for kettle exterior and piping checks where immersion is impractical.
Volume sits with probe thermometers; growth tilts toward digital instruments with embedded Bluetooth connectivity.
End User:
Scale of operation dictates calibration burden, with larger facilities absorbing metrology infrastructure costs that exclude smaller competitors.
- Commercial Breweries:Facilities with interstate distribution networks require NIST-traceable calibration chains and clean-in-place compatible stainless-steel construction. Brazil's concentrated demand zone is driving certified digital instrument penetration as modernization programs accelerate.
- Microbreweries:Pacific Northwest and Colorado operations are expanding temperature monitoring protocols as enzymatic precision becomes a competitive differentiator in saturated regional markets. These buyers balance certification requirements against capital constraints.
- Home Brewers:Price-sensitive segments in North America and Asia are capturing wireless data-logging tools for process repeatability.
- Beverage Manufacturers:Diversified fermentation operations spanning kombucha, cider, and spirits require multi-application temperature monitoring flexibility.
Revenue concentrates among commercial breweries; expansion is climbing the fastest in microbrewery digitization.
Technology:
Sensing element selection determines response speed, accuracy range, and long-term drift characteristics that shape total cost of ownership.
- Thermistor:Semiconductor-based temperature sensors offer superior sensitivity and stability for brewing's narrow enzymatic windows. British-made thermistor assemblies anchor European supply chains, creating geographic sourcing concentration for manufacturers.
- Thermocouple:Junction-based sensors withstand extreme temperature cycling in kettle and whirlpool applications where durability outweighs absolute precision.
- Infrared:Non-contact thermal radiation detection serves surface measurement needs without probe immersion.
- Bimetallic:Mechanical deflection sensors persist in legacy analog gauges facing replacement pressure from digital alternatives.
Installed base favors thermocouples; thermistor arrays with embedded Bluetooth transmitters are gaining share fastest.
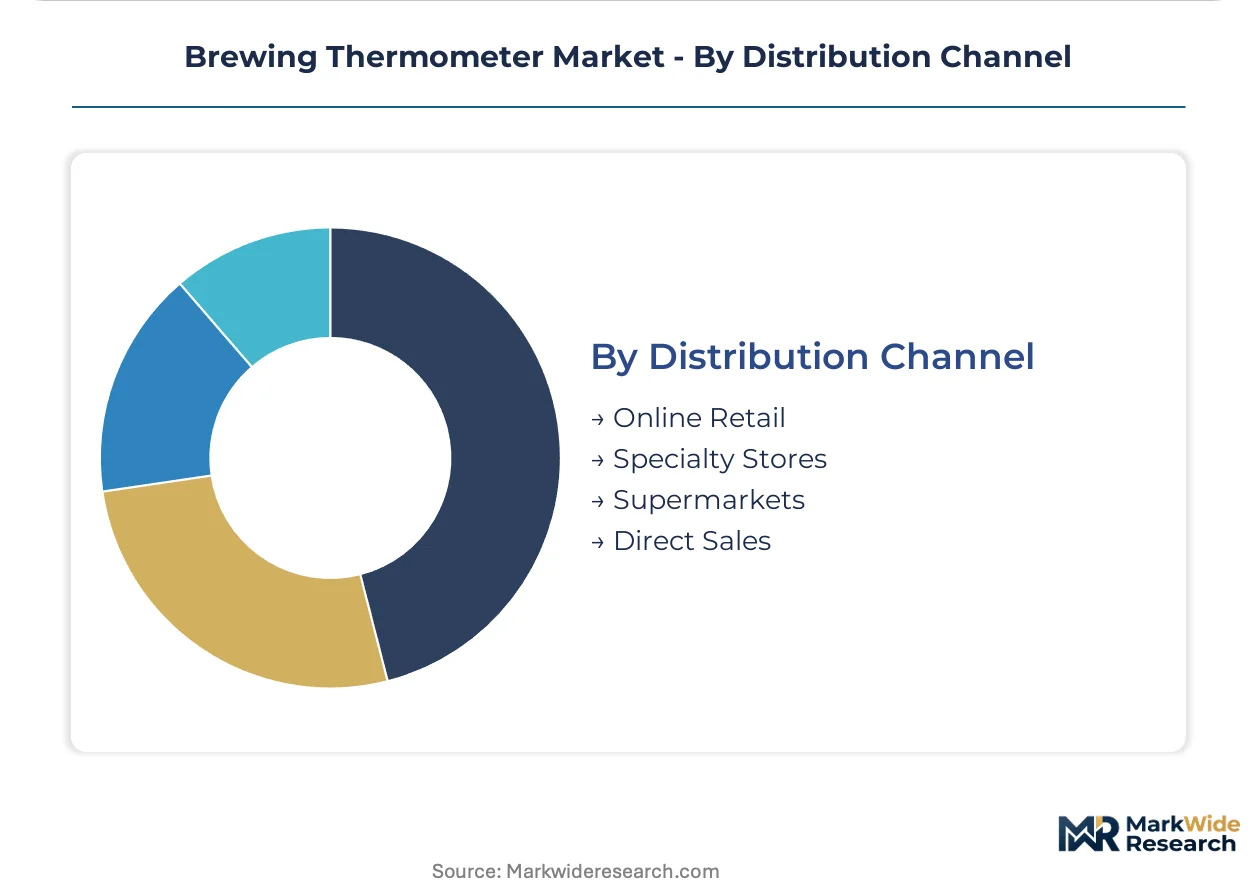
Distribution Channel:
Certification bundling and calibration certificate integration are restructuring channel economics away from traditional industrial distribution.
- Direct Sales:Manufacturer-direct channels bundle NIST-traceable calibration certificates with initial purchase, compressing vendor qualification cycles. Australian brewery cooperatives specify certified-digital-only supplier pools through group purchasing agreements.
- Online Retail:Direct-to-consumer wireless connectivity platforms bypass traditional intermediaries, capturing margin previously allocated to channel partners in home brewer segments.
- Specialty Stores:Local brewing equipment retailers serve immediate replacement needs with limited certification documentation.
- Supermarkets:Mass retail channels stock entry-level instruments for hobbyist segments with minimal technical support.
Transaction volume flows through online retail; value capture is expanding most quickly in direct sales with bundled calibration services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless-steel thermistor component manufacturing concentrates in British industrial zones, anchoring European supply chains for precision sensing elements while Pacific Northwest malt barley cultivation drives North American instrument demand.
United States
FDA cross-state distribution mandates and NIST calibration requirements compress procurement cycles for commercial breweries. Insurance underwriters in Colorado and Washington demand documented traceability chains. Denver and Seattle microbrewery clusters are digitizing temperature monitoring protocols ahead of quality audits.
Germany
REACH mercury restrictions force analog glass thermometer phase-outs across commercial fermentation operations. The country's national equipment safety regulator accelerates modernization timelines. Bavarian brewery cooperatives are bundling digital probe procurement with tank upgrades to satisfy clean-in-place compatibility standards.
Brazil
Federal brewery modernization programs concentrate equipment replacement demand in São Paulo and Minas Gerais states. ANVISA sanitary equipment standards reshape import qualification protocols for certified digital instruments. Southern craft brewery clusters are adopting NIST-traceable probes as quality differentiation intensifies.
Australia
Group purchasing agreements among brewery cooperatives specify certified-digital-only supplier pools with bundled calibration certificates. TGA-aligned quality frameworks influence procurement criteria for interstate beverage distribution. Victorian and New South Wales craft operations are consolidating vendor relationships around direct manufacturer channels.
Japan
METI industrial standards and JIS certification requirements elevate precision specifications for thermistor-based instruments. Compact sensor miniaturization aligns with space-constrained urban brewery layouts. Osaka and Tokyo metropolitan brewing facilities are integrating Bluetooth-enabled data-logging systems for process repeatability.
Brewing Thermometer Market Competitive Environment
Global majors compete with regional champions across calibration infrastructure and certification bundling capabilities. The vendor base stratifies into three tiers: vertically integrated metrology laboratories, specialized thermistor fabricators, and wireless connectivity platforms. Consolidation pressure concentrates among legacy analog gauge suppliers facing regulatory extinction. Dominant competitive moves include backward integration into captive calibration services and direct-to-consumer channel bypass of industrial distributors.
Among North American precision instrument specialists, ThermoWorks Inc. exemplifies the vertically integrated archetype with in-house NIST-traceable laboratory control. ETI Ltd. represents British-made thermistor assembly concentration anchoring European supply chains. Inkbird Tech. occupies the wireless connectivity platform position capturing price-sensitive segments through direct online retail channels.
| Leading Market Players |
|---|
| ThermoWorks Inc. |
| ETI Ltd. |
| Inkbird Tech. |
| Hanna Instruments |
| Blichmann Engineering |
| Reotemp Instruments |
| Tel-Tru |
| Northern Brewer |
| Taylor Precision Products |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal sustainability-linked financing instruments gate qualified supply access and premium-tier pricing power for certified digital brewing thermometer manufacturers. Smaller entrants lacking NIST-traceable calibration infrastructure face exclusion from procurement budgets that bundle energy-efficient equipment with green certification requirements.
Pricing Analysis
Calibration certificate bundling separates premium-tier from standard-tier from economy-tier offerings across manufacturer-direct channels. Warranty and remote recertification services anchor price differentiation between vertically integrated metrology laboratories and unbundled competitors. Pricing pressure stems from wireless connectivity platforms capturing home brewer segments through direct online retail, compressing margins for traditional industrial distributors. Commercial breweries exhibit lowest price sensitivity due to insurance auditor mandates, while hobbyist segments prioritize wireless convenience over absolute precision.
Supply Chain Analysis
Workforce availability constraints in British industrial zones and German precision manufacturing regions concentrate thermistor assembly production. Component sourcing draws from British-made thermistor arrays, Japanese silicon-based sensor miniaturization facilities, and Chinese Bluetooth transmitter module producers. Single-source vulnerability in European thermistor supply chains creates geographic concentration risk for manufacturers dependent on British sensing elements. Distribution runs through manufacturer-direct channels bundling calibration certificates, bypassing traditional industrial distributors in Australian and North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where REACH mercury restrictions and NIST calibration mandates force analog gauge suppliers and uncertified digital entrants toward exit or acquisition.
For Market Incumbents: Acquire captive calibration laboratory assets to secure NIST-traceable expertise concentrated among legacy suppliers. Backward integration into thermistor fabrication mitigates British supply chain concentration risk. Wireless connectivity platforms threaten probe thermometer incumbents; defend through embedded Bluetooth Low Energy transmitter integration in professional-grade instruments. For New Entrants and Emerging Players: Launch via direct-to-consumer online retail channels targeting price-sensitive home brewer segments in North America and Asia. Brazilian brewery modernization programs represent the most penetrable white-space geography for certified digital instrument penetration. White-label thermistor array sourcing from Japanese miniaturization specialists enables rapid product qualification without captive fabrication investment. For Investors and Strategic Acquirers: Bavarian brewery cooperative bundling announcements are the leading indicator that modernization program acceleration is compressing vendor qualification cycles. Five-to-ten year viability favors vertically integrated metrology laboratories with in-house calibration infrastructure over component assemblers lacking certification authority. Target acquisition archetype: regional digital instrument manufacturers with FDA clean-in-place compatible probe designs but lacking NIST-traceable laboratory control.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Acquisition | Captive NIST-traceable expertise secures insurance auditor qualification requirements. |
| Bluetooth Low Energy Integration | Silicon-based thermistor arrays with embedded transmitters absorb thermocouple market share. |
| Brazilian Distribution Partnership | ANVISA sanitary equipment alignment accelerates certified digital instrument penetration. |
| Green Certification Bundling | EU Green Deal alignment unlocks sustainability-linked financing for brewery procurement. |
| Direct-to-Consumer Platform Launch | Online retail bypass captures home brewer margin previously allocated to channel intermediaries. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this brewing thermometer market analysis. Primary interviews with brewery operations managers, quality assurance directors, equipment procurement leads, and metrology laboratory supervisors combined with FDA enforcement records, NIST calibration registry data, and EU REACH substance restriction filings. Bottom-up instrumentation shipment tracking and top-down brewery capital expenditure analysis enabled triangulation across data streams.
Reconciliation of shipment volumes, import-export flows, and end-user procurement surveys shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user scale, sensing element technology, and distribution channel structure. CAGRs derived from fitted growth curves incorporating craft brewery formation rates, regulatory phase-out timelines for mercury-containing instruments, and wireless connectivity adoption patterns in process monitoring equipment.
Regulatory enforcement delays, thermistor component supply disruptions, and craft brewery consolidation failures are the dominant revision risks to forecast assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Pizza Scissors Market
Food Processing Equipment
Food Waste Composting Machine Market
Food Processing Equipment
Industrial Planetary Mixers Market
Food Processing Equipment
Global Snack Pellet Equipment Market
Food Processing Equipment
Industrial Steam Peeler Market
Food Processing Equipment
Electric Meat Saw Market
Food Processing Equipment
Global Food Processing Market
Food Processing Equipment
Conveyor Ovens and Impinger Ovens Market
Food Processing Equipment
Pulp Washing Equipment Market
Food Processing Equipment
Blast Chillers Market
Food Processing Equipment
Cake Cutting Machines Market
Food Processing Equipment
Commercial Wood Fired Pizza Oven Market
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market
Food Processing Equipment
Water Pod Soluble Machines Market
Food Processing Equipment
Air Cooled Cube Ice Machines Market
Food Processing Equipment
Global Commercial Food Dehydrators Market